
 Biliary Tract Cancers (Btcs) Treatment Market | 2026-2036
Biliary Tract Cancers (Btcs) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Biliary Tract Cancers (Btcs) Treatment Market Outlook
The divergence between premium targeted therapy and commodity chemotherapy tiers is broadening as biomarker-driven patient selection reshapes reimbursement thresholds. Incyte leverages its IDH inhibitor portfolio to anchor the precision medicine segment in hepatobiliary malignancies. AstraZeneca competes through durvalumab combinations in perioperative settings, while Roche/Genentech sustains dominance in HER2-directed approaches for biliary tract subsets.
Biliary Tract Cancers Treatment encompasses therapeutic interventions for malignancies arising from the bile ducts, gallbladder, and ampulla of Vater, including surgical resection, systemic cytotoxic agents, external beam radiation, and molecularly targeted small molecules or monoclonal antibodies designed to interrupt oncogenic signaling pathways in cholangiocarcinoma and gallbladder carcinoma. The primary purpose spans curative intent in localized disease, palliation in advanced stages, and increasingly neoadjuvant or adjuvant strategies to improve resection rates and durable remission. Targeted therapy represents the fastest-expanding product category as FGFR, IDH1, and BRAF alterations yield addressable patient subsets, while intravenous delivery mode retains the largest volume share though oral kinase inhibitors are capturing disproportionate value growth in the homecare and clinic channels.
FDA oncology center of excellence and EMA committee for medicinal products for human use shape trial design requirements and label expansions for biliary tract indications, with both agencies tightening evidentiary standards for accelerated approvals in rare tumor types. The country's national pharmaceutical regulator in Japan and Health Canada/PMMA in Canada add parallel review complexity for sponsors pursuing multinational registration strategies. Stakeholders must monitor how post-marketing confirmatory trial failures reshape payer tolerance for provisional coverage and whether biomarker testing infrastructure keeps pace with label expansions.
Market Dynamics
Biomarker-guided patient stratification is fragmenting the biliary tract cancer treatment landscape into addressable molecular subsets, forcing payers to recalibrate coverage thresholds and manufacturers to justify premium pricing through companion diagnostic linkages.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The FDA oncology center of excellence accelerates regulatory timelines for novel agents addressing FGFR2 fusions and IDH1 mutations, compressing development cycles and expanding provisional reimbursement windows.
- Academic Medical Center Adoption:Specialized cancer hospitals in the United States, Germany, and Japan are building molecular tumor boards that standardize next-generation sequencing for cholangiocarcinoma subtypes, creating institutional demand for targeted therapy portfolios.
- EMA Priority Medicine Pathways:The European Medicines Agency's PRIME designation offers enhanced regulatory support for therapies addressing unmet needs in gallbladder carcinoma, attracting sponsor investment into European trial infrastructure.
Market Restraints
- Companion Diagnostic Infrastructure Gaps:Testing capacity for FGFR, IDH1, and HER2 alterations concentrates in tertiary referral centers, leaving community oncology practices dependent on send-out laboratories with prolonged turnaround times.
- Reimbursement Compression for Cytotoxic Backbones:Payers in Germany and Japan are tightening prior authorization requirements for gemcitabine-cisplatin combinations as biosimilar competition erodes branded pricing power.
- Small Patient Cohorts per Alteration:Ultra-rare molecular subsets fragment addressable populations below thresholds that support standalone commercial infrastructure, forcing dependence on cross-tumor basket trials.
Strategic Opportunities
- Perioperative Immunotherapy Integration:Durvalumab-based neoadjuvant protocols in resectable disease represent an expansion opportunity ahead of established adjuvant standards, with trial readouts poised to reshape surgical oncology practice patterns.
- Homecare Oral Kinase Inhibitors:FGFR and IDH inhibitors with oral bioavailability enable clinic-to-home transitions that reduce infusion center burden and capture value through adherence monitoring technologies.
- Japanese Regulatory Parallel Review:PMDA's participation in Project Orbis creates synchronized approval pathways with FDA and Health Canada, reducing regulatory duplication costs for sponsors targeting East Asian markets.
Industry Challenges
- Molecular Pathology Workforce Scarcity:Interpretation of complex fusion signatures and variant of uncertain significance reporting requires specialized gastrointestinal pathologists, with training pipelines failing to match testing volume growth.
- Post-Marketing Confirmatory Trial Execution:Accelerated approvals mandate randomized controlled trials that struggle to enroll against evolving standard-of-care comparators, risking regulatory withdrawal and payer recoupment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biliary Tract Cancers (Btcs) Treatment Market |
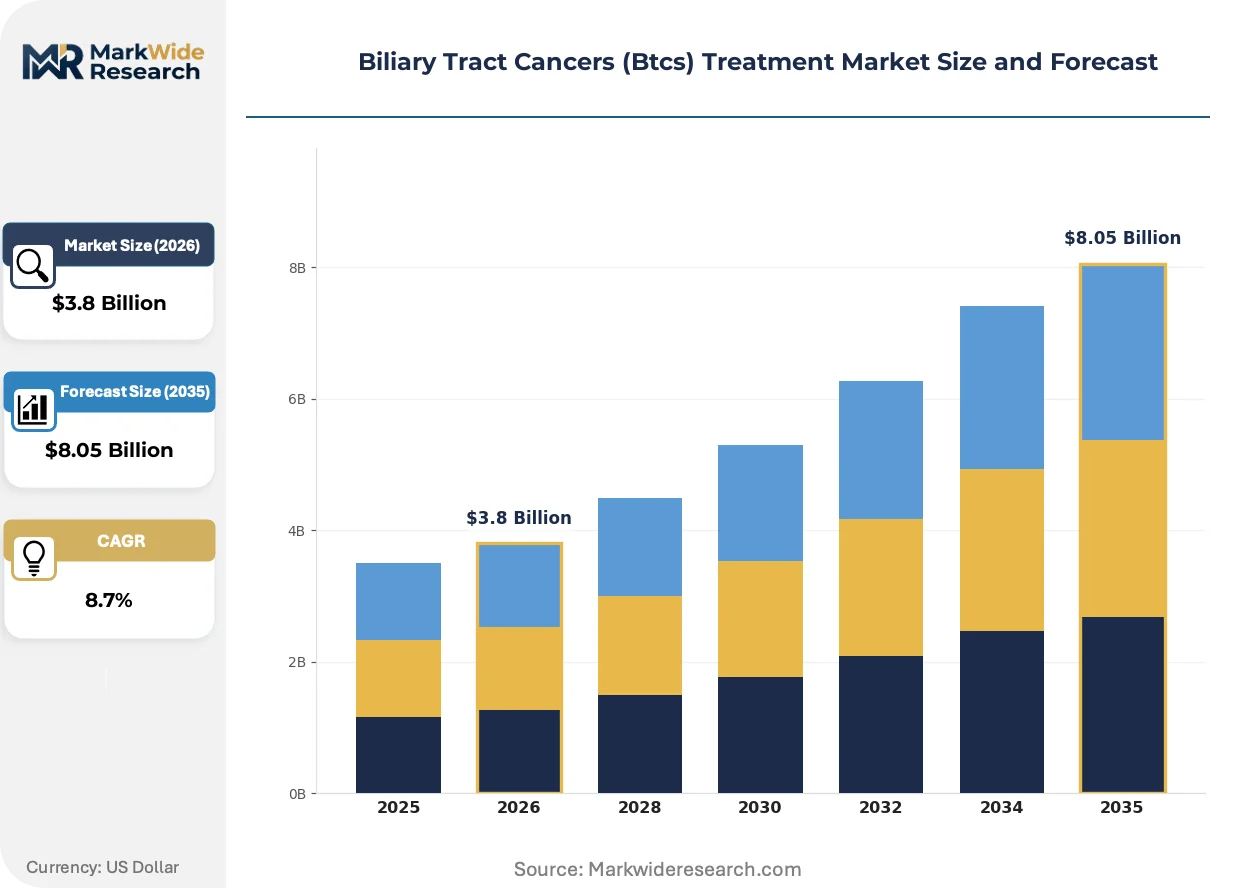
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Chemotherapy, Radiotherapy, Targeted Therapy Delivery Mode: Intravenous, Oral, Intratumoral, Subcutaneous End User: Hospitals, Clinics, Research Institutes, Homecare Therapy Area: Oncology, Palliative Care, Immunotherapy, Genetic Therapy |
| Companies Covered | Incyte, AstraZeneca, Roche/Genentech, Bayer/Loxo Oncology, Agios Pharmaceuticals/Servier, Taiho, Merck, Eli Lilly, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biliary Tract Cancers (Btcs) Treatment Market Strategic Shifts
Liquid biopsy platforms are displacing tissue-dependent molecular profiling, enabling serial monitoring of clonal evolution and resistance mechanisms without repeat invasive procedures in advanced biliary tract malignancies.
Next-generation sequencing panels with circulating tumor DNA capability are decentralizing biomarker testing from centralized academic laboratories into community oncology networks. Regional cancer centers in Texas and Florida are adopting CLIA-validated platforms that return actionable results within seven days. This shift is compressing referral delays and expanding clinical trial access for patients outside major metropolitan corridors.
REACH regulatory frameworks in Europe are tightening evidentiary requirements for accelerated approvals in rare tumor indications, with EMA now mandating interim overall survival data before granting conditional marketing authorization. Sponsors are responding by embedding survival endpoints earlier in phase II protocols, extending trial duration and inflating development costs for biliary tract programs.
Site-of-care migration is redirecting systemic therapy administration from hospital outpatient departments into independent oncology clinics and home infusion settings. Payer pressure in the United States, particularly from Medicare Advantage plans, favors lower-cost ambulatory environments for stable patients on oral regimens. This displacement is fragmenting revenue capture across hospital systems and community practices.
Biliary Tract Cancers (Btcs) Treatment Market Segmentation
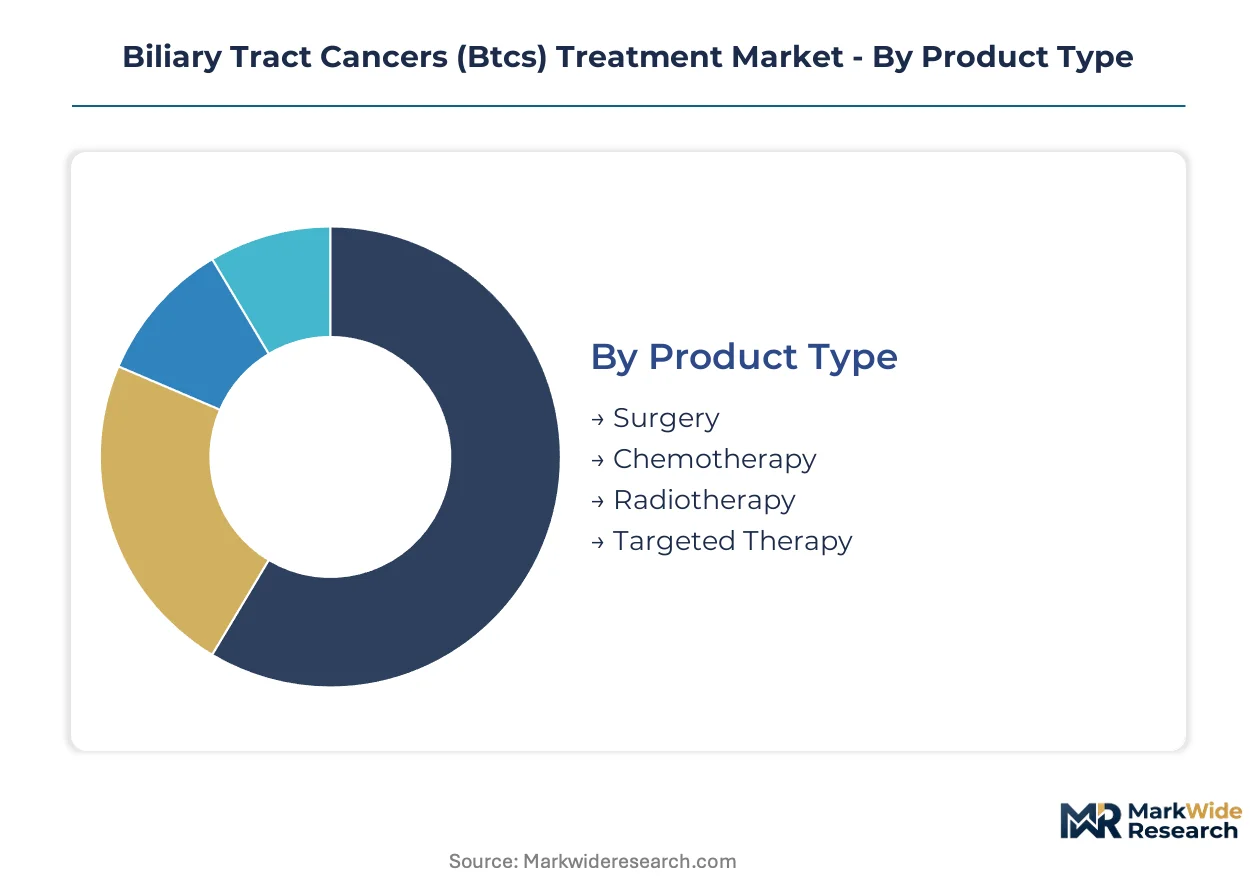
Patient stratification by molecular alteration and care setting is reshaping how manufacturers configure clinical trial programs and commercial infrastructure. Segmentation clarity determines whether therapies achieve provisional reimbursement through accelerated pathways or face prolonged access negotiations.
Product Type:
FDA oncology center of excellence and EMA committee for medicinal products for human use impose distinct evidentiary burdens on each modality, with device-drug combinations triggering additional premarket review cycles.
- Surgery:Curative-intent resection with negative margins remains the foundation for localized cholangiocarcinoma and gallbladder carcinoma. Demand concentrates in tertiary referral centers across the United States, Germany, and Japan where hepatobiliary surgical volumes support multidisciplinary tumor boards and neoadjuvant protocol enrollment.
- Chemotherapy:Gemcitabine-cisplatin backbone regimens dominate first-line advanced disease despite biosimilar erosion of branded pricing. Community oncology practices in the United States and regional hospitals in Germany administer the majority of cycles, constrained by prior authorization tightening and infusion center capacity limits.
- Radiotherapy:External beam and stereotactic body radiation therapy address locally advanced unresectable presentations. Academic medical centers integrate radiotherapy into trimodality protocols, with proton therapy availability limited to specialized centers in Texas, Florida, and selected Japanese metropolitan areas.
- Targeted Therapy:FGFR, IDH1, and BRAF inhibitors require companion diagnostic linkages for label-aligned prescribing. Oral kinase inhibitors in this category enable homecare transitions and capture disproportionate value growth through adherence monitoring platforms.
Surgery sits at the top of the volume ranking, with targeted therapy climbing the fastest.
Delivery Mode:
Reimbursement differentials between hospital outpatient departments and ambulatory infusion centers are redirecting administration patterns for stable patients on established regimens.
- Intravenous:Cytotoxic agents and monoclonal antibodies require supervised infusion with hypersensitivity monitoring. Hospital systems in the United States retain the largest volume share, though Medicare Advantage pressure is migrating stable patients to independent oncology clinics.
- Oral:Kinase inhibitors with bioavailability enable clinic-to-home transitions that reduce infusion center burden. Patient assistance programs and specialty pharmacy networks in Germany and Japan manage adherence monitoring and resistance surveillance.
- Intratumoral:Direct injection approaches remain investigational, with early-phase trials concentrated at academic medical centers in the United States exploring oncolytic virus and immunotherapy combinations for unresectable disease.
- Subcutaneous:Alternative administration for selected supportive care agents and emerging immunotherapy formulations. Home health nursing infrastructure in Japan supports subcutaneous delivery, expanding access outside metropolitan hospital catchments.
Intravenous administration maintains volume leadership, while oral delivery gains share fastest through patient preference and payer cost avoidance.
End User:
Site-of-care economics and molecular testing capability determine where patients initiate therapy and whether they remain within referral networks for subsequent lines.
- Hospitals:Tertiary centers manage complex surgical cases, clinical trial enrollment, and molecular tumor board coordination. Academic medical centers in the United States, Germany, and Japan concentrate next-generation sequencing capacity and FGFR fusion expertise.
- Clinics:Community oncology practices administer cytotoxic backbones and oral targeted therapy with remote specialist consultation. Independent clinics in Texas and Florida are adopting CLIA-validated liquid biopsy platforms to reduce referral delays.
- Research Institutes:Phase I-II trial units and translational research programs explore novel combinations. Sponsors prioritize institutes with established cholangiocarcinoma registries and rapid activation timelines.
- Homecare:Oral regimen administration with remote monitoring and adverse event triage. Specialty pharmacies in Germany and patient support programs in Japan manage logistics and compliance tracking.
Hospitals dominate patient volume, with homecare expanding most quickly through oral kinase inhibitor adoption.
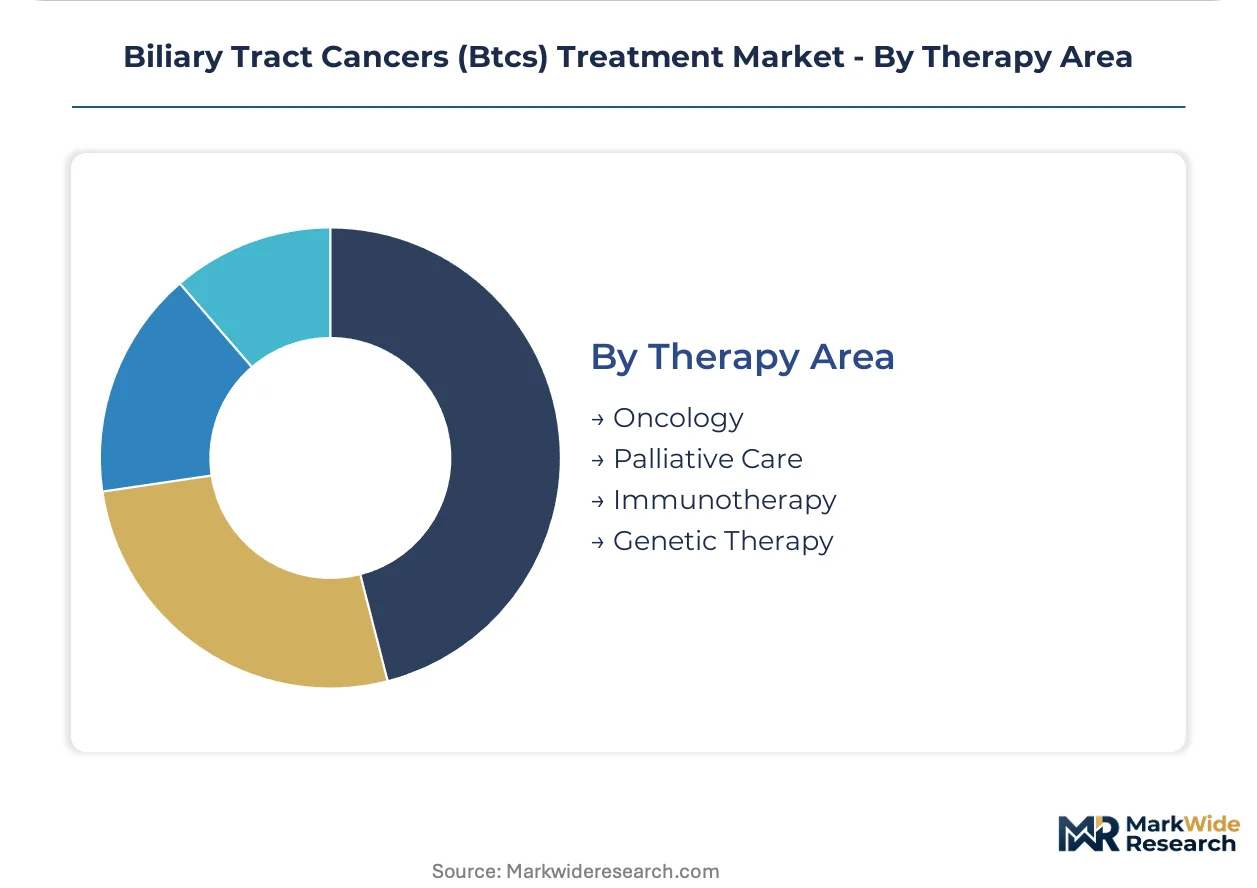
Therapy Area:
Regulatory pathway selection—oncology drug approval versus device designation versus biologics license—varies substantially across therapeutic intent categories.
- Oncology:Cytotoxic and targeted systemic therapy with curative or life-prolonging intent. FDA breakthrough therapy designation and EMA PRIME accelerate development for FGFR and IDH inhibitor programs.
- Palliative Care:Symptom management and quality-of-life interventions for advanced disease. Hospice and palliative medicine services in the United States integrate with oncology practices for seamless care transitions.
- Immunotherapy:Checkpoint inhibitors and neoadjuvant durvalumab combinations in resectable disease. Perioperative protocols are reshaping surgical oncology practice patterns ahead of established adjuvant standards.
- Genetic Therapy:Investigational approaches addressing underlying driver alterations. Early-phase programs concentrate at academic centers with gene therapy manufacturing partnerships and rare tumor trial expertise.
Oncology commands the largest patient volume, with immunotherapy demonstrating the steepest expansion trajectory through perioperative protocol development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized gastrointestinal pathologists and hepatobiliary surgeons concentrate in tertiary referral networks across the United States, Germany, and Japan, anchoring molecular tumor board capacity and clinical trial enrollment infrastructure for cholangiocarcinoma subtypes.
United States
Academic medical centers in Texas and Florida deploy CLIA-validated liquid biopsy platforms with seven-day turnaround, compressing referral delays for FGFR fusion testing. FDA breakthrough therapy designation accelerates provisional reimbursement for IDH inhibitors. The MD Anderson Cancer Center in Houston anchors a regional trial network exploring perioperative durvalumab protocols.
Germany
Community oncology practices administer gemcitabine-cisplatin backbones while university hospitals in Munich and Heidelberg coordinate molecular tumor boards for rare alterations. EMA PRIME designation attracts sponsor investment into European trial infrastructure. The German Cancer Research Center in Heidelberg maintains a cholangiocarcinoma registry supporting translational studies.
Japan
PMDA participation in Project Orbis synchronizes approval pathways with FDA and Health Canada, reducing regulatory duplication for East Asian market entry. Home health nursing infrastructure supports subcutaneous delivery outside metropolitan hospital catchments. The National Cancer Center Hospital in Tokyo concentrates next-generation sequencing expertise for biliary tract malignancies.
United Kingdom
NHS England's specialized commissioning framework routes complex hepatobiliary cases to designated surgical centers in London and Manchester, consolidating molecular testing demand. The MHRA operates parallel review with EMA for oncology indications. The Royal Marsden NHS Foundation Trust maintains early-phase trial capacity for FGFR inhibitor programs.
Canada
Health Canada/PMRA aligns with FDA through Project Orbis for synchronized approval timelines. Provincial health technology assessment bodies in Ontario and British Columbia evaluate companion diagnostic linkages for targeted therapy reimbursement. The Princess Margaret Cancer Centre in Toronto anchors a national referral network for cholangiocarcinoma molecular profiling.
Biliary Tract Cancers (Btcs) Treatment Market Competitive Environment
Top-tier vendors anchor precision oncology portfolios, while mid-cap specialists concentrate on single-agent kinase inhibitors and biosimilar cytotoxic alternatives. The competitive structure stratifies across three archetypes: large-cap diversified pharmaceutics with immuno-oncology breadth, targeted therapy specialists with companion diagnostic partnerships, and regional generics manufacturers absorbing chemotherapy volume. Consolidation pressure operates through M&A for molecular platform access and strategic alliances for biomarker co-development.
Within the targeted therapy specialist tier, Incyte and Agios Pharmaceuticals/Servier exemplify portfolio concentration on IDH inhibition for hepatobiliary malignancies. Among large-cap diversified players, AstraZeneca and Roche/Genentech occupy positions spanning checkpoint inhibitor combinations and HER2-directed approaches respectively. These archetypes represent competitive positioning through molecular patient stratification rather than undifferentiated cytotoxic market share capture.
| Leading Market Players |
|---|
| Incyte |
| AstraZeneca |
| Roche/Genentech |
| Bayer/Loxo Oncology |
| Agios Pharmaceuticals/Servier |
| Taiho |
| Merck |
| Eli Lilly |
| Novartis |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialty pharmacy networks in the United States and Germany are consolidating oral kinase inhibitor distribution, tightening margin capture on FGFR and IDH inhibitors while redirecting procurement leverage toward manufacturers with direct-to-patient adherence platforms.
Pricing Analysis
Bundled drug-diagnostic-reimbursement packages dominate targeted therapy pricing, while unbundled chemotherapy cycles face commodity compression. Three-tier pricing structure across premium, standard, and economy levels separates companion-diagnostic-linked FGFR inhibitors from branded gemcitabine-cisplatin from biosimilar cytotoxic backbones. Pricing pressure stems from Medicare Advantage prior authorization tightening in the United States. Community oncology practices exhibit highest price sensitivity; academic medical centers with molecular tumor boards show lowest.
Supply Chain Analysis
Domestic-content mandates for pharmaceutical manufacturing in the United States and Japan are reshaping active pharmaceutical ingredient sourcing toward North American and Japanese contract manufacturers. Supply concentrates in Switzerland for high-potency oncology APIs, India for intermediate chemical synthesis, and the United States for finished oral dosage forms. Cold-chain logistics for monoclonal antibodies hinge on single-source vulnerability at major international airports. Distribution runs through specialty pharmacy networks with hub-and-spoke models into patient home settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between United States reimbursement rates and European EMA PRIME pathway speed offers cost-efficient clinical trial execution, with Germany and the United Kingdom providing faster enrollment against lower per-patient operational costs than domestic FDA-track studies.
For Market Incumbents: Anchor precision oncology portfolios through companion diagnostic co-development partnerships that lock in biomarker-exclusive prescribing. Defend against biosimilar erosion by embedding cytotoxic backbones into neoadjuvant immunotherapy protocols with durvalumab. Prioritize vertical integration into liquid biopsy platform access to capture serial monitoring revenue streams. For New Entrants and Emerging Players: Community oncology practices in Texas and Florida represent an underserved buyer archetype with unmet liquid biopsy capability and clinical trial access gaps. Capture this segment through CLIA-validated platform partnerships and remote molecular tumor board consultation services. Lead with oral kinase inhibitor homecare logistics as the go-to-market wedge against hospital-centric incumbents. For Investors and Strategic Acquirers: Large-cap diversified pharmaceutics with immuno-oncology breadth are the most active acquirer in this space, seeking targeted therapy specialists with FDA breakthrough therapy designation momentum. Five-to-ten year viability favors platforms with perioperative protocol positioning ahead of adjuvant standard establishment. Watch for post-marketing confirmatory trial readouts as the decisive inflection signal for accelerated approval durability.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA breakthrough therapy designation requires linked biomarker validation, accelerating label-aligned prescribing. |
| Perioperative Immunotherapy Integration | Durvalumab-based neoadjuvant protocols reshape surgical oncology practice ahead of adjuvant standards. |
| Liquid Biopsy Platform Adoption | CLIA-validated circulating tumor DNA testing decentralizes molecular profiling from academic centers to community clinics. |
| Homecare Oral Kinase Inhibitor Logistics | Specialty pharmacy networks in Germany and Japan manage adherence monitoring and resistance surveillance remotely. |
| Project Orbis Regulatory Synchronization | PMDA parallel review with FDA and Health Canada reduces duplication costs for East Asian market entry. |
Study Parameters
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists; secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases; plus bottom-up patient flow modeling and top-down epidemiological triangulation — were reconciled to construct market estimates across the analysis window.
Data-stream reconciliation anchored volume and value outputs to segmentation dimensions spanning product type, delivery mode, end user, and therapy area, with regional regulatory clusters modeled separately. CAGRs were derived from fitted growth curves against historical adoption patterns. Forecast inputs incorporated clinical trial pipeline progression probabilities and companion diagnostic penetration assumptions by geography.
Underlying measurement precision varies by segment; targeted therapy with companion diagnostic linkages carries tighter precision than commodity chemotherapy due to clearer patient identification. Forecasts reflect assumptions about regulatory approval timelines, biomarker testing infrastructure buildout, and payer coverage policy evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Gastric Cancer Market
Gastroenterology
Hirschsprung Disease Treatment Market
Gastroenterology
Pouchitis Treatment Market
Gastroenterology
Polyps Market
Gastroenterology
Crohns Disease Therapeutics Market
Gastroenterology
Intestinal Pseudo-Obstruction Treatment Market
Gastroenterology
Inflammatory Bowel Disease Treatment Market
Gastroenterology
Disposable Intestinal Wash Bags Market
Gastroenterology
Inflammatory Bowel Disease Market
Gastroenterology
Digestive Health Products Market
Gastroenterology
US Gastroenterology Ambulatory Surgery Center Market
Gastroenterology
Stomach Cancer Market
Gastroenterology
Gallstone Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
Intestinal Fistula Treatment Market
Gastroenterology
Duodenal Ulcer Treatment Market