
 Gluten Intolerance Treatment Market | 2026-2036
Gluten Intolerance Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten Intolerance Treatment Market Foresight
North America is fragmenting as new manufacturing capacity for gluten-free therapeutics expands across the United States and Canada. Takeda Pharmaceutical Company Limited leverages its gastrointestinal drug pipeline to sustain competitive positioning in prescription-grade treatments. Enzymedica differentiates through enzyme-based digestive aids targeting symptom management. NOW Foods anchors the supplements segment with broad retail distribution across health stores and pharmacies.
Gluten intolerance treatment encompasses pharmaceutical interventions, nutritional supplements, and specially formulated foods designed to manage celiac disease and non-celiac gluten sensitivity through enzymatic breakdown, immune modulation, or strict dietary exclusion. Formulations typically require sub-20 parts per million gluten thresholds to achieve clinical efficacy and patient safety standards. Pharmaceuticals and supplements capture the dominant margin pools due to recurring consumption patterns and clinician endorsement. Adult Patients represent the largest addressable base, while Online Retail channels are expanding fastest as direct-to-consumer diagnostic testing normalizes gluten-free lifestyle adoption.
The FDA enforces gluten-free labeling standards that mandate verified ingredient sourcing and manufacturing segregation protocols. EFSA and national regulators across Europe enforce comparable thresholds through EC regulation on food information to consumers. Stakeholders must monitor evolving enzyme therapy approvals and reimbursement policy shifts that could reshape access economics for prescription versus over-the-counter modalities.
Market Dynamics
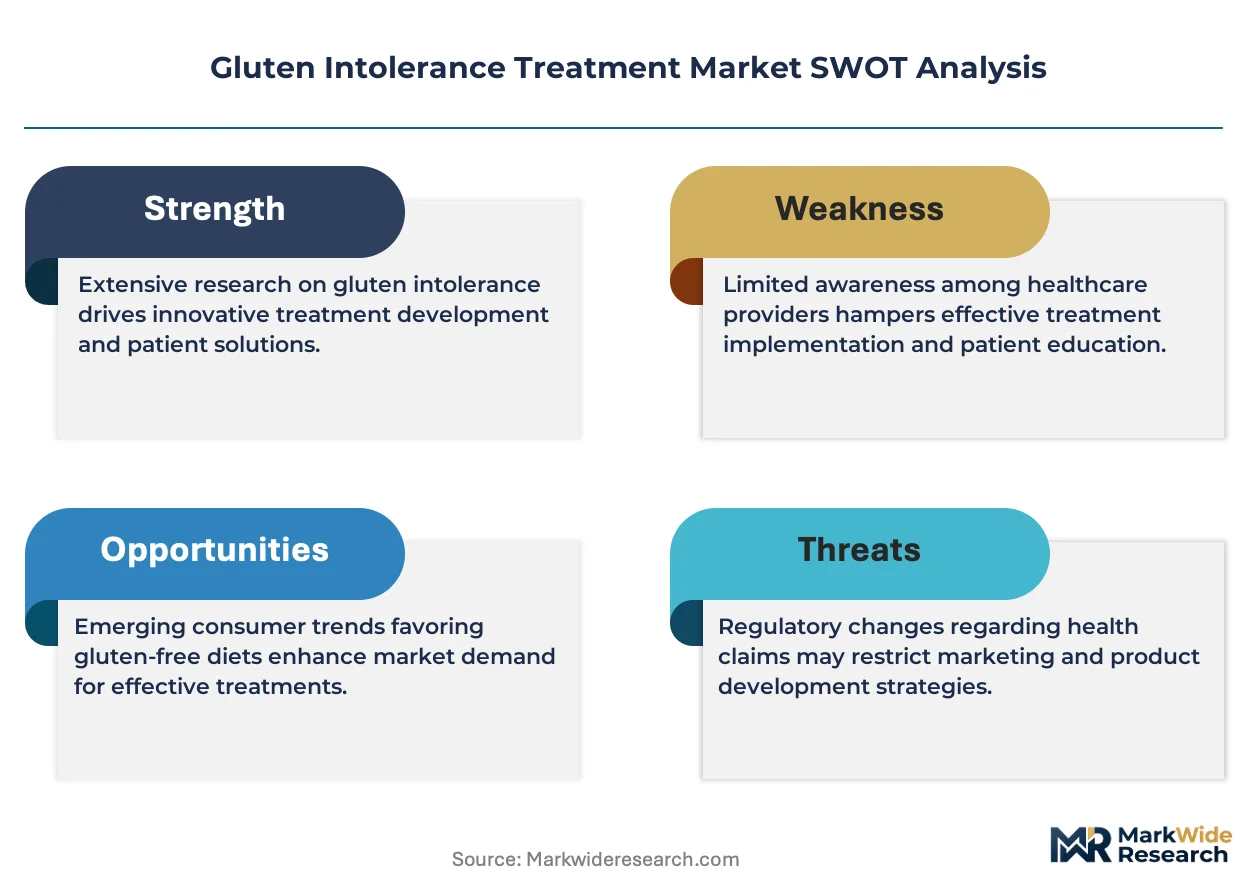
Prescription-grade enzyme therapies are displacing over-the-counter digestive aids as gastroenterologists prioritize clinically validated interventions for celiac disease management.
Growth Catalysts
- FDA Gluten-Free Labeling Standard:The regulation mandates sub-20 parts per million thresholds, forcing manufacturers to invest in verified ingredient sourcing and manufacturing segregation protocols that elevate clinical credibility.
- Direct-to-Consumer Diagnostic Testing:At-home celiac and gluten sensitivity panels normalize disease identification, expanding the addressable patient base seeking pharmaceutical and nutritional interventions.
- Enzymatic Breakthrough Formulations:Novel glutenases demonstrate prolyl endopeptidase activity sufficient to degrade immunogenic peptides in vivo, opening prescription pathways previously limited to dietary exclusion.
Market Restraints
- Input Cost Volatility:Pharmaceutical-grade enzyme production depends on fermentation-derived biocatalysts whose supply concentrates in contract manufacturing organizations across Switzerland and Denmark.
- Substitution Threat from Plant-Based Alternatives:Grain-free flour formulations using cassava, almond, and coconut displace demand for gluten-targeting therapeutics in the non-celiac sensitivity segment.
- Reimbursement Friction:Private insurers and Medicare maintain inconsistent coverage policies for prescription enzyme therapies, creating out-of-pocket cost barriers that suppress adoption velocity.
Strategic Opportunities
- Pediatric Formulation Gap:Palatable, age-appropriate dosing formats for children with celiac disease remain underdeveloped, representing white space for taste-masked or chewable delivery systems.
- EU Green Deal Alignment:Sustainable manufacturing incentives under the European Commission's pharmaceutical strategy reward enzymatic processes with reduced solvent use and lower carbon intensity.
- Telehealth Integration:Virtual gastroenterology platforms enable remote prescription workflows for maintenance therapies, bypassing traditional clinic-based access constraints in rural and underserved counties.
Industry Challenges
- Cross-Contamination Control:Manufacturing facilities must maintain dedicated production lines and airborne particle monitoring systems to prevent gluten cross-contact, requiring substantial facility capital expenditure.
- Biomarker Standardization Delays:Discordance between tissue transglutaminase IgA assays and intestinal biopsy confirmation prolongs diagnostic timelines, delaying treatment initiation and frustrating patient retention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten Intolerance Treatment Market |
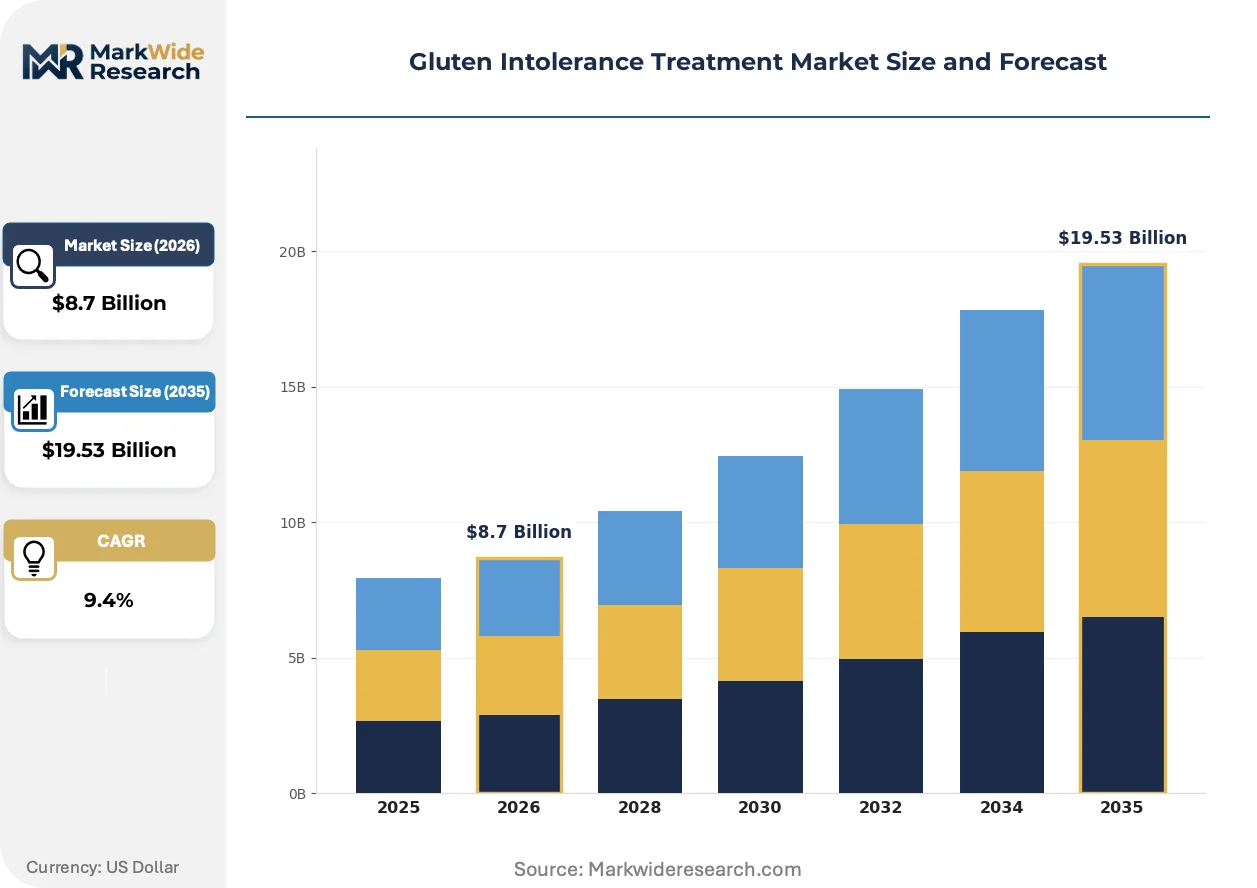
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Supplements, Foods, Beverages End User: Adult Patients, Pediatric Patients, Clinics, Home Care Distribution Channel: Online Retail, Supermarkets, Pharmacies, Health Stores Application: Preventive Care, Treatment, Diagnostics, Patient Education |
| Companies Covered | Precigen, Genetic Nutrition, Takeda Pharmaceutical Company Limited, KLAIRE LABS, AMYRA Biotech AG, DSM-Firmenich, NOW Foods, Sun Pharmaceutical Industries Ltd., Enzymedica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten Intolerance Treatment Market Shifts & Advancements
Biotechnology convergence with personalized nutrition is redefining how clinicians match therapeutic intensity to individual disease phenotypes and dietary compliance patterns.
Engineered glutenases is hybridizing recombinant DNA technology with oral delivery science to create acid-stable enzymes that survive gastric transit. Gastroenterology practices in academic medical centers are piloting these formulations for patients with refractory celiac symptoms. The technology is compressing the boundary between dietary management and pharmaceutical intervention, forcing reclassification discussions among pharmacy benefit managers.
REACH authorization requirements for novel enzyme catalysts are tightening toxicological data submission standards across the European Economic Area. Manufacturers must now demonstrate absence of immunogenic off-target effects through extended lymphocyte proliferation assays. Small-molecule supplement producers without dedicated regulatory affairs functions are exiting the region, consolidating shelf presence among pharmaceutical-grade suppliers.
Subscription-based replenishment models are displacing episodic pharmacy purchases for chronic gluten sensitivity patients. Direct-to-consumer platforms bundle diagnostic monitoring with automated supplement delivery, capturing recurring revenue streams that retail pharmacies struggle to match. This behavioral pivot concentrates in metropolitan counties with above-median digital health literacy and established telemedicine infrastructure.
Gluten Intolerance Treatment Market Segmentation
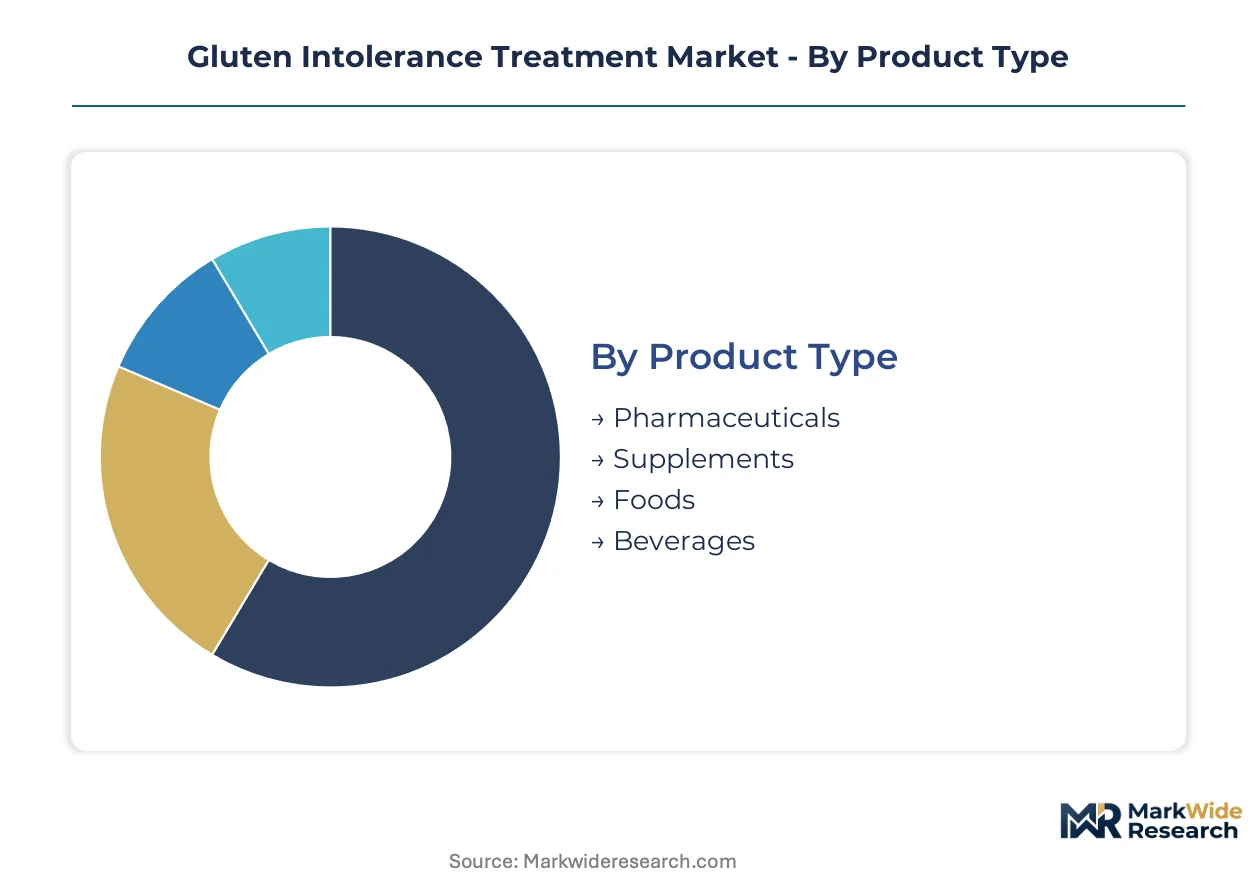
Gluten intolerance treatment segments reflect divergent margin structures and regulatory burdens. Pharmaceutical-grade formulations command recurring revenue streams through prescription workflows, while food and beverage categories compete on shelf placement and certification credibility.
Product Type:
Mature categories anchor revenue stability; emerging formats target enzymatic breakthroughs and delivery innovation.
- Pharmaceuticals:Prescription enzyme therapies and immune modulators require FDA or EMA approval pathways. Gastroenterologists in the United States and Germany drive adoption for refractory celiac patients where dietary exclusion fails. Reimbursement friction and clinical validation timelines constrain launch velocity.
- Supplements:Over-the-counter digestive aids and probiotic formulations dominate retail pharmacy and health store channels. NOW Foods and Enzymedica compete on enzyme specificity and third-party certification. Direct-to-consumer platforms accelerate replenishment cycles through subscription bundling.
- Foods:Certified gluten-free baked goods, pastas, and prepared meals must achieve sub-20 parts per million thresholds under FDA and EFSA protocols. Manufacturing segregation requirements elevate production costs.
- Beverages:Fermented drinks and meal replacements target non-celiac gluten sensitivity consumers seeking convenience over strict therapeutic efficacy.
Pharmaceuticals handle the majority of throughput; Supplements is expanding most quickly as self-diagnosis normalizes.
End User:
Volume concentrates where diagnostic access intersects with purchasing autonomy and reimbursement coverage.
- Adult Patients:Self-directed consumers with established celiac diagnoses or gluten sensitivity drive pharmaceutical and supplement demand. Telehealth platforms in the United States enable remote prescription renewal for maintenance therapies.
- Pediatric Patients:Palatability challenges and dosing precision requirements create formulation white space. Caregivers prioritize taste-masked delivery systems and school-compliant packaging.
- Clinics:Gastroenterology practices and celiac disease centers coordinate diagnostic confirmation with treatment initiation. Academic medical centers pilot engineered glutenase therapies.
- Home Care:Family-managed dietary compliance and symptom monitoring rely on subscription replenishment models and at-home testing integration.
Adult Patients capture the dominant addressable base; Pediatric Patients show the steepest unmet need trajectory.
Distribution Channel:
Channel economics diverge between high-touch clinical endorsement and algorithmic consumer targeting.
- Online Retail:Direct-to-consumer platforms bundle diagnostic testing with automated supplement delivery. Amazon and specialized health portals capture recurring revenue through subscription lock-in.
- Supermarkets:Mass-market gluten-free foods compete on shelf positioning and certification visibility. Retail buyers prioritize suppliers with verified supply chain segregation.
- Pharmacies:Pharmacist counseling supports over-the-counter enzyme selection and prescription fulfillment. CVS and Walgreens allocate premium shelf space to clinically endorsed brands.
- Health Stores:Whole Foods and regional cooperatives cater to wellness-oriented consumers seeking premium positioning and clean-label credentials.
Pharmacies handle the majority of prescription throughput; Online Retail is gaining share fastest through diagnostic-commerce integration.
Application:
Use case segmentation tracks patient journey stages from suspicion through chronic management.
- Preventive Care:Prophylactic enzyme use before dining out or travel addresses anxiety-driven demand among diagnosed celiac patients. Takeda and emerging biotechs target this contingency-use indication.
- Treatment:Daily pharmaceutical and nutritional interventions manage confirmed celiac disease and non-celiac gluten sensitivity. Gastroenterologists prioritize clinically validated options with biomarker endpoints.
- Diagnostics:At-home celiac panels and tissue transglutaminase IgA testing normalize disease identification. Direct-to-consumer laboratories expand the treated population.
- Patient Education:Digital platforms and dietitian services improve dietary compliance and cross-contamination awareness. Telehealth integration scales access beyond urban academic centers.
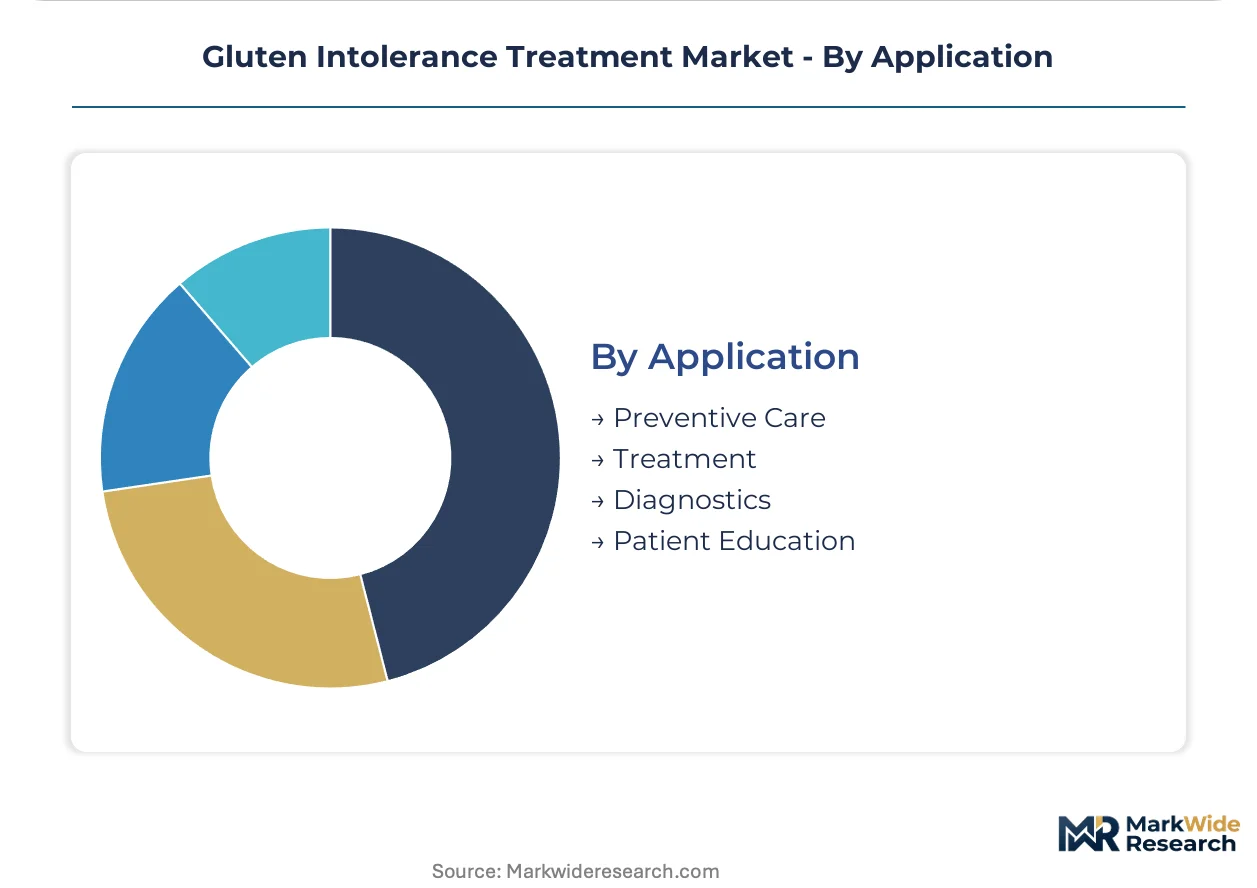
Treatment handles the majority of commercial activity; Diagnostics is climbing the fastest as testing decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA gluten-free labeling standards anchor the United States as the dominant geography, while EFSA protocols and national regulators across Europe and Asia-Pacific shape parallel compliance frameworks. Diagnostic access and reimbursement policies concentrate demand in specific metropolitan clusters and industrial corridors.
United States
Celiac disease diagnosis rates climb fastest in the Northeast and Pacific Coast metropolitan corridors where gastroenterology density supports screening protocols. The FDA enforces sub-20 parts per million gluten thresholds through verified ingredient sourcing mandates. Boston and San Francisco anchor engineered glutenase clinical trials at academic medical centers.
Germany
Gastroenterology practices in Bavaria and North Rhine-Westphalia drive prescription enzyme adoption for refractory celiac patients. EMA approval pathways and REACH authorization requirements tighten toxicological data standards for novel biocatalysts. The Munich biotech corridor concentrates fermentation-derived enzyme contract manufacturing capacity.
United Kingdom
NHS diagnostic backlogs delay treatment initiation despite rising celiac seroprevalence in England and Scotland. MHRA post-Brexit regulatory autonomy maintains alignment with EMA standards while streamlining national assessment timelines. London's digital health cluster incubates telehealth platforms bundling diagnostic testing with supplement subscriptions.
Canada
Health Canada gluten-free labeling regulations mirror FDA thresholds with additional bilingual packaging requirements. Celiac disease prevalence in Ontario and Quebec exceeds national averages, concentrating specialist gastroenterology capacity in Toronto and Montreal. Vancouver's natural products sector anchors supplement manufacturing for cross-border export.
Australia
TGA approval processes for prescription enzyme therapies lag FDA and EMA timelines, delaying market entry for novel formulations. Celiac disease diagnosis rates in Victoria and New South Wales rise with expanded serological screening in primary care. Sydney's medical research institutes pilot biomarker standardization protocols to reduce biopsy confirmation delays.
Gluten Intolerance Treatment Market Competitive Landscape
Pharmaceutical-grade developers and nutritional supplement specialists split the market along regulatory burden and margin structure lines. The vendor base concentrates among mid-cap specialists with dedicated regulatory affairs functions and established gastroenterology channel relationships. Three archetypes dominate: prescription enzyme innovators, retail supplement incumbents, and hybrid diagnostic-commerce platforms. Competitive moves center on clinical validation investments and direct-to-consumer channel capture.
Within the pharmaceutical archetype, Takeda Pharmaceutical Company Limited and Sun Pharmaceutical Industries Ltd. occupy positions shaped by gastrointestinal drug pipeline depth and emerging market manufacturing scale. Enzymedica exemplifies the enzyme-specific supplement tier, while NOW Foods anchors broad retail distribution across health stores and pharmacy channels. These three represent divergent strategic postures: prescription clinical validation, enzymatic specialization, and mass-market shelf presence.
| Leading Market Players |
|---|
| Precigen |
| Genetic Nutrition |
| Takeda Pharmaceutical Company Limited |
| KLAIRE LABS |
| AMYRA Biotech AG |
| DSM-Firmenich |
| NOW Foods |
| Sun Pharmaceutical Industries Ltd. |
| Enzymedica |
| Others |
Supply & Pricing Matrix
Munich's biotech corridor concentrates fermentation-derived enzyme contract manufacturing, concentrating pricing power among pharmaceutical-grade suppliers who pass through fermentation substrate volatility to downstream buyers. This geographic concentration forces supplement producers without captive capacity into price-taker positions while prescription-grade developers extract premium through clinical validation tiers.
Pricing Analysis
Geographic price spreads separate North American prescription enzyme therapies from European over-the-counter supplements by certification grade and reimbursement eligibility. Three-tier pricing structure across premium, standard, and economy levels tracks FDA clinical validation status, with EMA-approved formulations commanding highest tiers. Cost compression in the standard tier is intensifying because grain-free flour alternatives displace enzyme demand among non-celiac sensitivity consumers. Pediatric formulations show least price sensitivity due to caregiver willingness-to-pay for palatability, while adult maintenance therapies face highest elasticity.
Supply Chain Analysis
Lonza and Boehringer Ingelheim hold dominant contract manufacturing capacity for pharmaceutical-grade glutenases across Switzerland, Denmark, and Germany. Production draws from fermentation-derived biocatalysts, purified active pharmaceutical ingredients, and acid-stable delivery excipients. Single-source vulnerability concentrates in Swiss fermentation facilities where REACH authorization timelines create regulatory chokepoints. Distribution runs through specialty pharmacy networks for prescription tiers and direct-to-consumer platforms for supplement replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from plant-based grain alternatives that bypass enzymatic intervention entirely, requiring differentiation through clinical outcome validation that commodity flours cannot replicate.
For Market Incumbents: Harden regulatory moats by pursuing FDA breakthrough therapy designation for engineered glutenases, insulating prescription tiers from supplement price erosion. Deepen backward integration into fermentation capacity through acquisition of Danish or Swiss contract manufacturing assets, reducing input cost volatility exposure. Secure exclusive formulary placement with major gastroenterology practices before biosimilar enzyme competition emerges. For New Entrants and Emerging Players: Establish a beachhead in pediatric formulation white space where taste-masked delivery systems remain underdeveloped and caregiver willingness-to-pay supports premium positioning. Target telehealth-integrated diagnostic-commerce bundles in metropolitan counties with established digital health infrastructure, bypassing traditional pharmacy channel gatekeepers. Lead with subscription-based replenishment models that capture recurring revenue through automated supplement delivery. For Investors and Strategic Acquirers: Long-term, this sits as a chronic disease management play because celiac disease requires lifetime dietary compliance and maintenance therapy consumption. Acquisition targets should display hybrid diagnostic-commerce capabilities with direct-to-consumer testing integration and automated fulfillment infrastructure. Watch FDA enzyme therapy approval velocity as the signal for prescription tier margin expansion versus supplement commoditization.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Engineered glutenase trials at Boston and San Francisco academic centers validate prescription pathways beyond dietary exclusion. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation accelerates review timelines for novel prolyl endopeptidase formulations. |
| Manufacturing Scale-Up | Fermentation capacity expansion in Munich biotech corridor secures pharmaceutical-grade enzyme supply for refractory celiac indications. |
| Direct-to-Consumer Launch | Diagnostic-commerce bundles integrate at-home celiac testing with automated supplement replenishment subscriptions. |
| Strategic Partnership | Telehealth platform alliances enable remote prescription workflows for maintenance therapies in underserved counties. |
Research Methodology
Operator-level perspectives from gastroenterology practice administrators, celiac disease center clinical directors, pharmacy benefit managers, and direct-to-consumer diagnostic platform executives anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FDA gluten-free labeling guidance documents, EMA centralized procedure assessment reports, ClinicalTrials.gov enzyme therapy protocol registrations, and formulary coverage policy databases. Bottom-up patient population sizing triangulated against top-down pharmaceutical revenue estimates across the analysis window.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated enzyme therapy adoption pathways. Segmentation dimensions modeled included product type tier, end user age cohort, distribution channel format, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to diagnosed celiac prevalence trajectories and treatment penetration assumptions, with sensitivity testing around reimbursement policy shifts and diagnostic testing expansion rates.
Sensitivities concentrate around FDA enzyme therapy approval timelines, Medicare coverage determination outcomes, and grain-free alternative flour cost curves that could accelerate substitution. Forecasts reflect documented assumptions regarding clinician prescribing behavior and patient compliance persistence. Quarterly review of FDA advisory committee calendars, CMS national coverage determinations, and telehealth platform funding rounds is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Chile Gastric Cancer Treatment Market
Gastroenterology
Gastric Cancer Market
Gastroenterology
Colon Hydrotherapy Market
Gastroenterology
Stomach Cancer Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
Gastroesophageal Junction Adenocarcinoma Therapeutics Market
Gastroenterology
High Definition Ultrasound Gastroscope Market
Gastroenterology
Acute Pancreatitis Market
Gastroenterology
Fecal Incontinence Market
Gastroenterology
Gastroretentive Drug Delivery Systems Outsourcing Market
Gastroenterology
Necrotic Enteritis Treatment Market
Gastroenterology
Hirschsprung Disease Treatment Market
Gastroenterology
Intestinal Pseudo-Obstruction Treatment Market
Gastroenterology
Biliary Tract Cancers (Btcs) Treatment Market
Gastroenterology
Digestive Health Products Market
Gastroenterology
Gastrointestinal Drugs Market