
 Polyps Market | 2026-2036
Polyps Market Size, Share, and Industry Trends Forecast 2026-2036
Polyps Market Outlook
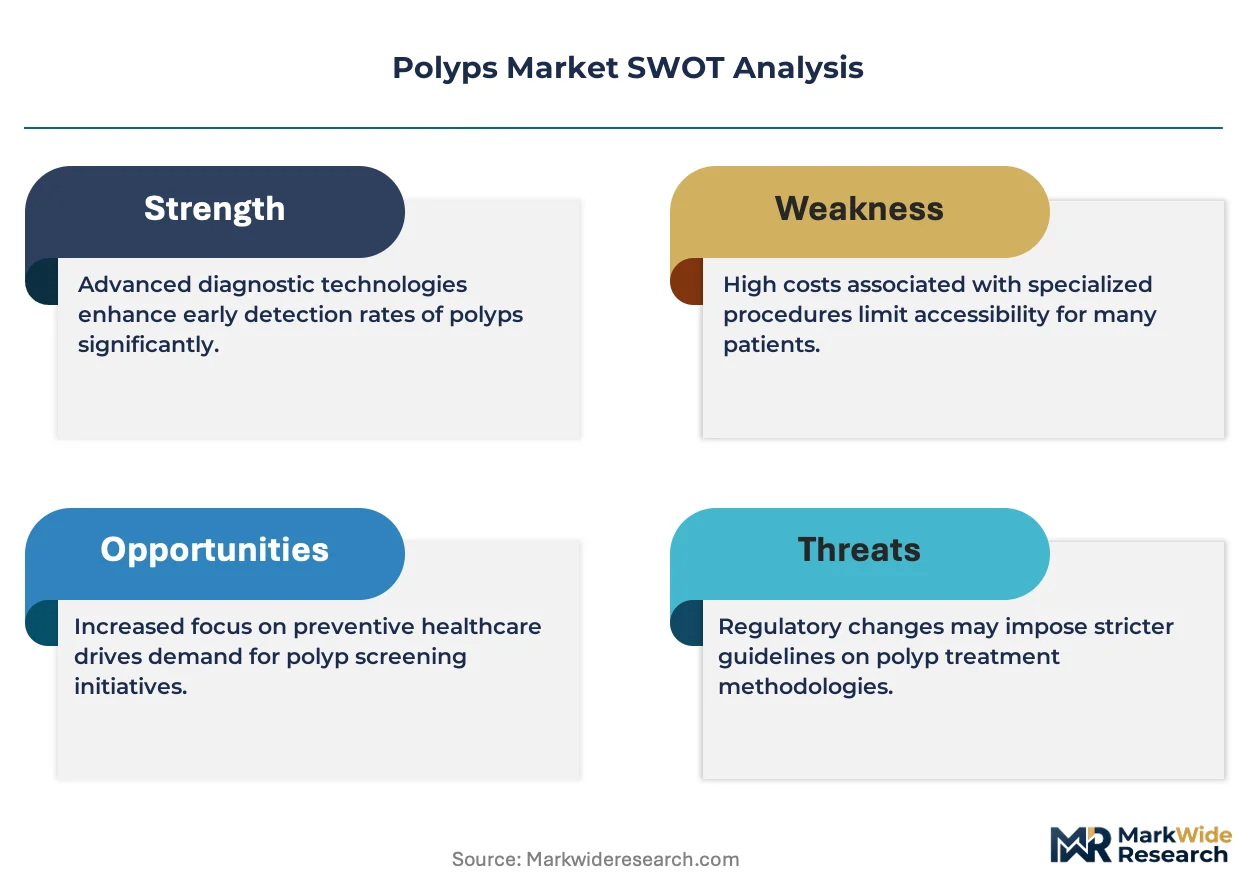
Gastroenterologist workforce shortages across the United States and Western Europe is unwinding access to routine colonoscopy services. Medtronic leverages its integrated endoscopy platform to sustain device placements in hospital systems facing staffing gaps. Boston Scientific anchors its competitive position through specialized polypectomy tools that dominate outpatient settings. Olympus Corporation controls the imaging pipeline with optical technologies that extend its reach into diagnostic laboratories.
Polyps are abnormal tissue growths protruding from mucosal surfaces, typically ranging from millimeters to several centimeters in diameter, with histological classification distinguishing adenomatous, hyperplastic, and serrated subtypes based on malignant potential. These lesions require endoscopic visualization and histopathological examination to determine surveillance intervals and therapeutic intervention. Colonoscopy Devices occupy the largest product category, with Snare Polypectomy Devices representing the fastest-growing segment as outpatient facilities shift toward same-session resection. AI-Assisted Detection technology captures expanding margin pools as reimbursement frameworks in the United States and Japan begin recognizing computer-aided diagnosis codes.
FDA premarket notification pathways shape device commercialization timelines for polypectomy tools entering the United States market. The European Union's MDR and FDA's unique device identification requirements are forcing manufacturers to restructure quality management systems and post-market surveillance protocols. Stakeholders must monitor evolving reimbursement decisions for AI-assisted colonoscopy across Medicare, Japan's Ministry of Health, and Germany's Institute for Quality and Efficiency in Health Care to anticipate capital deployment cycles in diagnostic infrastructure.
Market Dynamics
AI-assisted polyp detection is fragmenting diagnostic workflows across hospital systems, forcing endoscopy manufacturers to restructure software-hardware integration strategies while gastroenterology departments retrain clinical staff on algorithm-augmented interpretation protocols.
Growth Catalysts
- Preventive Coverage Mandates:The Affordable Care Act's colorectal screening provisions in the United States eliminated cost barriers for eligible populations, expanding addressable patient volumes for endoscopy service lines.
- Computer-Aided Diagnosis Reimbursement:Japan's Ministry of Health recognition of AI-assisted colonoscopy codes creates sustainable revenue models for capital-intensive imaging platform deployments.
- Same-Session Resection Protocols:Outpatient facilities are adopting snare polypectomy workflows that compress diagnostic and therapeutic encounters into single encounters, driving device utilization intensity.
Market Restraints
- Specialist Workforce Contraction:Fellowship-trained gastroenterologist shortages in the United States and Germany limit procedural capacity expansion regardless of equipment availability.
- MDR Compliance Burden:The European Union's Medical Device Regulation imposes extended clinical evaluation timelines and post-market surveillance obligations that compress margin structures for polypectomy tool manufacturers.
- Optical Component Supply Concentration:High-precision lens assemblies and image sensors concentrate in East Asian manufacturing clusters, exposing device OEMs to single-source disruption risks.
Strategic Opportunities
- Rural Screening Access Gaps:Underpenetrated regions in the United States present white space for mobile endoscopy units and telepathology-linked community health center deployments.
- Convergence of Optical and Computational Imaging:Integration of real-time hyperspectral tissue analysis with deep learning classification enables histology-predictive resection margins without laboratory latency.
- Germany's IQWIG Evidence Framework:Positive technology assessment pathways for AI-assisted detection create preferential reimbursement positioning for validated algorithm platforms.
Industry Challenges
- Algorithm Validation Bottlenecks:FDA premarket notification requirements for software-as-a-medical-device impose substantial clinical trial costs and timeline uncertainty on detection algorithm developers.
- Legacy System Interoperability:Hospital information system fragmentation forces endoscopy platform vendors to maintain multiple data exchange protocols, inflating integration engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyps Market |
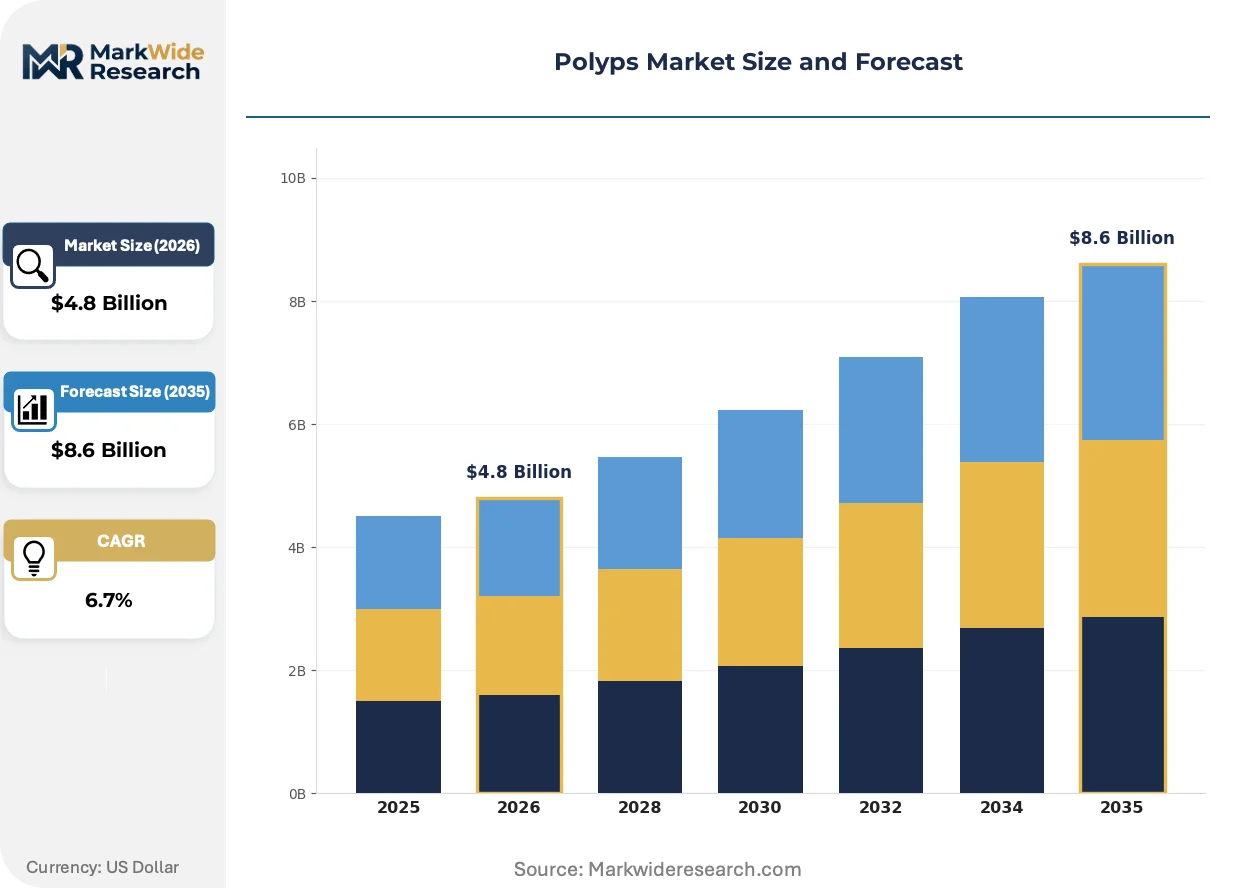
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colonoscopy Devices, Endoscopic Biopsy Forceps, Snare Polypectomy Devices, Polyp Detection Software Application: Screening, Diagnosis, Treatment, Follow-up End User: Hospitals, Clinics, Diagnostic Laboratories, Outpatient Facilities Technology: Conventional Endoscopy, Virtual Colonoscopy, Imaging Techniques, AI-Assisted Detection |
| Companies Covered | Medtronic, Boston Scientific, Johnson & Johnson, Stryker, Olympus Corporation, Cook Medical, Conmed Corporation, B. Braun Melsungen AG, Hologic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyps Market Strategic Shifts
Computational pathology is displacing visual inspection heuristics in mucosal lesion assessment, while reimbursement frameworks scramble to codify algorithm-augmented procedures into established billing structures.
Deep learning-based polyp characterization is fragmenting the diagnostic pipeline between endoscopists and pathologists. Community hospital systems in the United States are piloting real-time margin assessment tools that reduce histology laboratory referral volumes. This compression of the diagnostic chain is forcing pathology groups to reposition around complex neoplasia cases while ceding routine adenoma classification to algorithm-mediated bedside workflows.
The European Union's Medical Device Regulation is tightening clinical evidence requirements for software-driven detection systems. Manufacturers must now submit prospective validation data from European patient populations rather than extrapolating from United States or Japanese trials. German notified bodies are processing MDR certification applications for AI-assisted colonoscopy modules at extended timelines, delaying commercial availability relative to FDA-cleared equivalents.
Hospital procurement departments are consolidating endoscopy device contracts under single-source framework agreements. Integrated delivery networks in the United States are negotiating multi-year supply arrangements that bundle colonoscopes, polypectomy tools, and software subscriptions, displacing the historical pattern of specialty-specific purchasing committees. This concentration of buying authority is most visible in the southeastern United States, where regional health systems have consolidated gastroenterology service lines under centralized capital planning functions.
Polyps Market Segmentation
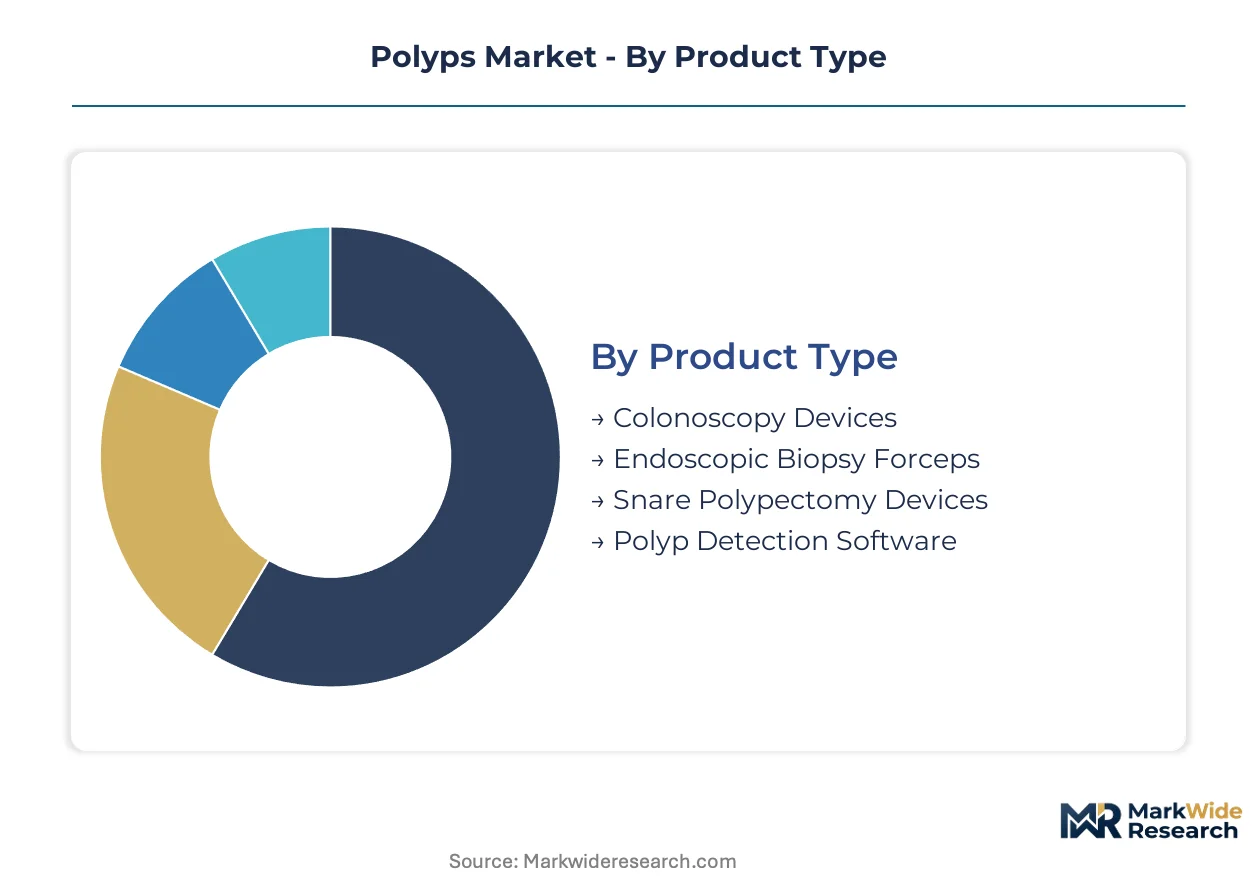
Polyp management workflows fragment across distinct procurement channels and clinical settings. Device manufacturers must align product configurations with the divergent capital cycles of hospital systems, outpatient surgery centers, and diagnostic laboratories.
Product Type:
Channel distribution varies sharply: capital-intensive colonoscopy platforms flow through hospital procurement committees, while disposable polypectomy tools route through outpatient supply chains.
- Colonoscopy Devices:Flexible endoscopic systems with high-definition imaging capabilities dominate hospital capital budgets. Demand concentrates in integrated delivery networks across the United States where centralized purchasing committees negotiate multi-year equipment leases.
- Snare Polypectomy Devices:Electrosurgical loops and cold snare configurations enable same-session resection protocols. Outpatient facilities in Germany and Japan are driving utilization intensity as ambulatory reimbursement frameworks favor complete diagnostic-therapeutic encounters.
- Endoscopic Biopsy Forceps:Single-use grasping instruments for tissue sampling prior to definitive resection.
- Polyp Detection Software:FDA-cleared and PMDA-registered algorithm modules that overlay real-time detection markers on endoscopic video feeds.
By volume, Colonoscopy Devices leads. By growth pace, Snare Polypectomy Devices is ahead.
Application:
Cost tier stratification separates screening programs with mass throughput requirements from treatment applications demanding precision instrumentation.
- Screening:Population-scale colorectal cancer prevention programs operate on compressed per-procedure economics. The Affordable Care Act's preventive coverage mandates in the United States eliminated patient cost-sharing for eligible populations, expanding addressable volumes for service line operators.
- Treatment:Therapeutic polypectomy commands premium reimbursement relative to diagnostic colonoscopy alone. Japanese Ministry of Health recognition of complete resection procedures supports sustainable revenue models for high-complexity interventions.
- Diagnosis:Histopathological characterization workflows requiring forceps biopsy and laboratory referral.
- Follow-up:Surveillance colonoscopy intervals dictated by adenoma detection rates and pathology findings from index procedures.
Screening captures the highest procedure volumes. Treatment applications generate the steepest expansion trajectory as same-session protocols proliferate.
End User:
Customer type determines contract structure: hospitals negotiate capital equipment frameworks while outpatient facilities purchase disposable instruments through distribution intermediaries.
- Hospitals:Academic medical centers and community hospital systems anchor demand for integrated endoscopy platforms. Gastroenterologist workforce shortages across the United States are forcing these institutions to prioritize throughput-optimized equipment configurations.
- Outpatient Facilities:Ambulatory surgery centers and independent endoscopy suites specialize in efficient polypectomy workflows. Germany's outpatient reimbursement framework supports rapid site-of-service migration for low-complexity procedures.
- Clinics:Physician office laboratories with limited procedural capacity.
- Diagnostic Laboratories:Pathology groups processing resected specimens for histological classification and malignancy staging.
Hospitals lead by installed base. Outpatient Facilities are gaining share fastest as site-of-service economics shift.
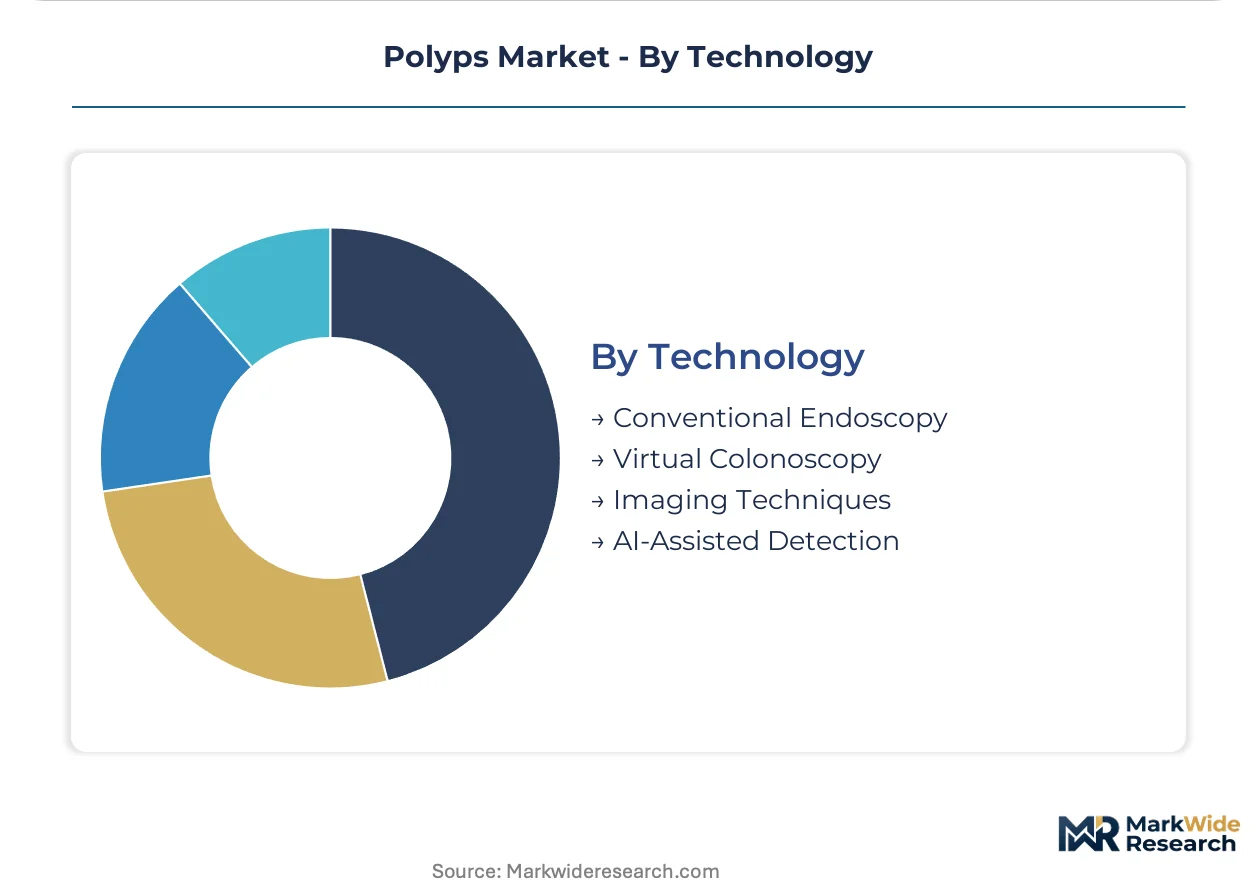
Technology:
Technology maturity curves separate established optical platforms from emerging computational modalities requiring regulatory validation and reimbursement establishment.
- AI-Assisted Detection:Deep learning algorithms for real-time polyp identification and characterization are displacing unassisted visual inspection. Japan's Ministry of Health reimbursement recognition creates sustainable revenue models for capital-intensive platform deployments.
- Conventional Endoscopy:White-light and narrow-band imaging systems remain the procedural standard. Olympus Corporation and Medtronic maintain installed base dominance through optical technology pipelines and service network coverage.
- Virtual Colonoscopy:CT-based colorectal imaging for patients with incomplete optical colonoscopy or procedural contraindications.
- Imaging Techniques:Chromoendoscopy, confocal laser endomicroscopy, and other optical enhancement modalities for lesion characterization.
Conventional Endoscopy leads by procedure volume. AI-Assisted Detection is climbing the fastest as regulatory pathways mature and reimbursement frameworks codify computer-aided diagnosis codes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket pathways and Japan's PMDA reimbursement frameworks anchor the dominant geographies for polyp detection technology commercialization. Screening mandates and AI-assisted diagnosis codes are reshaping procurement patterns across hospital systems. Device OEMs prioritize regulatory clearance sequencing to capture early-mover positioning in high-reimbursement markets.
United States
Academic medical centers in the Southeast and Midwest are consolidating gastroenterology service lines under centralized capital planning functions. The Affordable Care Act's preventive coverage mandates eliminated patient cost-sharing for eligible populations, expanding addressable procedure volumes. The Cleveland Clinic and Mayo Clinic anchor AI-assisted colonoscopy pilot programs that compress diagnostic-therapeutic encounters into single sessions.
Japan
Japan's Ministry of Health recognition of computer-aided diagnosis reimbursement codes creates sustainable revenue models for capital-intensive imaging platforms. Tokyo and Osaka metropolitan hospital systems are deploying algorithm-augmented detection modules at scale. The PMDA's streamlined software-as-a-medical-device pathway accelerates commercial availability relative to FDA timelines.
Germany
Germany's Institute for Quality and Efficiency in Health Care (IQWIG) evidence framework creates preferential reimbursement positioning for validated AI detection platforms. Outpatient facilities in Bavaria and North Rhine-Westphalia are migrating low-complexity polypectomy procedures from hospital settings. The EU MDR imposes extended clinical evaluation timelines that compress margin structures for device manufacturers.
United Kingdom
NHS England's bowel cancer screening programme drives demand for throughput-optimized endoscopy configurations across London and the Midlands. The National Institute for Health and Care Excellence (NICE) technology appraisal pathways determine algorithm adoption in public hospital systems. Manchester and Birmingham health systems are piloting mobile endoscopy units to address rural access gaps in Northern England.
South Korea
The Ministry of Food and Drug Safety (MFDS) is aligning software-medical-device pathways with FDA and PMDA precedents to attract algorithm developers. Seoul National University Hospital and Asan Medical Center anchor clinical validation networks for hyperspectral tissue analysis integration. Busan-Ulsan manufacturing clusters supply high-precision optical components to global endoscopy OEMs.
Polyps Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the polyp management device market. Olympus Corporation and Medtronic control installed base dominance through optical technology pipelines and service network coverage. Boston Scientific anchors outpatient positioning through specialized polypectomy tool portfolios. Competitive moves concentrate on software-hardware integration restructuring and multi-year supply contract consolidation under single-source framework agreements.
Among the integrated platform vendors, Medtronic and Olympus Corporation exemplify the full-stack archetype spanning imaging hardware, detection algorithms, and disposable instruments. Boston Scientific occupies a position within the specialized intervention tier, with its forceps and snare portfolios dominating ambulatory surgery center procurement channels. Johnson & Johnson and Stryker represent diversified medical technology conglomerates where endoscopy constitutes one vertical among broader surgical and interventional portfolios. These five entities collectively anchor competitive dynamics across hospital capital committees and outpatient supply chains.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific |
| Johnson & Johnson |
| Stryker |
| Olympus Corporation |
| Cook Medical |
| Conmed Corporation |
| B. Braun Melsungen AG |
| Hologic |
| Others |
Value Chain & Pricing Dynamics
Multi-year framework agreements with integrated delivery networks lock in colonoscope placements and polypectomy tool supply while capping annual price escalations. These contracts bundle capital equipment, disposable instruments, and AI software subscriptions into single-source arrangements that stabilize procurement costs for hospital systems facing gastroenterologist workforce shortages.
Pricing Analysis
Price spreads between Japan and Germany exceed those between Germany and the United States due to divergent reimbursement frameworks. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated platforms from conventional imaging systems and refurbished equipment. Pricing pressure stems from EU MDR compliance costs compressing manufacturer margins. Outpatient surgery centers exhibit highest price sensitivity; academic medical centers prioritize throughput optimization over unit cost.
Supply Chain Analysis
Japan and South Korea anchor high-precision optical component fabrication for endoscope lens assemblies and image sensors. Manufacturing draws from specialized glass substrates, CMOS sensors, and electrosurgical wire alloys. Single-source vulnerability concentrates in East Asian precision optics clusters. Distribution runs through regional distribution intermediaries serving hospital procurement committees and ambulatory surgery center supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across AI-assisted detection algorithms, disposable polypectomy tools, and legacy imaging platforms creates entry points for specialists. Same-session resection protocols are fragmenting procurement authority between hospital capital committees and outpatient facility managers.
For Market Incumbents: Consolidate software-hardware integration capabilities to defend against modular AI entrants unbundling detection algorithms from colonoscope platforms. Secure multi-year exclusive supply agreements with southeastern United States integrated delivery networks before centralized procurement functions mature. Prioritize backward integration into optical sensor production to reduce East Asian supply exposure.
For New Entrants and Emerging Players: FDA's streamlined software-as-a-medical-device premarket notification pathway enables rapid commercial entry for validated detection algorithms. Target rural United States community health centers lacking capital for full platform replacement with AI overlay modules compatible with installed Olympus and Medtronic systems. Pursue telepathology-linked mobile endoscopy unit partnerships as channel strategy.
For Investors and Strategic Acquirers: Specialized polypectomy tool manufacturers with outpatient facility channel control represent prime acquisition targets. Long-term viability hinges on reimbursement framework durability for computer-aided diagnosis across Japan's Ministry of Health and Germany's IQWIG. Monitor CMS recognition of AI-assisted colonoscopy billing codes as inflection signal for United States capital deployment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm FDA Submission | Premarket notification pathway accelerates commercial availability relative to EU MDR timelines. |
| Hospital System Partnership | Multi-year framework agreements with Cleveland Clinic and Mayo Clinic anchor platform adoption. |
| Software Companion Development | Real-time margin assessment tools reduce histology laboratory referral volumes for pathology groups. |
| Reimbursement Strategy | Japan's Ministry of Health computer-aided diagnosis codes create sustainable revenue models. |
| CE Marking Pathway | EU MDR clinical evidence requirements demand prospective European validation data. |
Study Parameters
Initial hypotheses were tested against primary input from gastroenterology department heads, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, PMDA registration databases, CMS Medicare reimbursement schedules, and hospital procurement contract disclosures. Bottom-up procedure volume estimates triangulated with top-down capital equipment shipment data.
Variance decomposition across product type, application, end user, and technology dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level procedure growth rates and per-procedure device utilization intensity. Forecast inputs incorporated AI reimbursement recognition timelines and gastroenterologist workforce projection models.
Underlying assumptions cover stable regulatory pathways for software-as-a-medical-device, with deviation risk concentrated in FDA algorithm validation bottlenecks and EU MDR certification delays. Forecasts reflect these assumptions with sensitivity to reimbursement policy shifts. Recalibration cycles align with material shifts in CMS coverage determinations and IQWIG technology assessments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Inflammatory Bowel Disease Treatment Market
Gastroenterology
Acute Pancreatitis Market
Gastroenterology
Gastroretentive Drug Delivery Systems Outsourcing Market
Gastroenterology
Anal Fissure Treatment Market
Gastroenterology
Gluten Intolerance Treatment Market
Gastroenterology
Chile Gastric Cancer Treatment Market
Gastroenterology
Peptic Ulcer Market
Gastroenterology
Global Gastrointestinal Stent Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
Stomach Cancer Market
Gastroenterology
Hirschsprung Disease Treatment Market
Gastroenterology
Colon Hydrotherapy Market
Gastroenterology
Global Gastrointestinal Bleeding Treatment Market
Gastroenterology
Hyperemesis Gravidarum Treatment Market
Gastroenterology
Inflammatory Bowel Disease Market
Gastroenterology
Fecal Incontinence Market