
 Faecal Calprotectin Testing Market | 2026-2036
Faecal Calprotectin Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Faecal Calprotectin Testing Market Foresight
European diagnostic reagent manufacturing is shifting toward automated platform compatibility. BÜHLMANN Laboratories AG anchors its position through deep specialization in gastrointestinal biomarker assay development. Thermo Fisher Scientific Inc. leverages its clinical chemistry installed base to distribute complementary immunoassay content. Diazyme Laboratories Inc. competes on cost-engineered ELISA formulations for mid-volume laboratories.
Faecal calprotectin testing quantifies the calcium-binding protein S100A8/A9 complex in stool specimens, with clinical cutoffs typically set at 50-100 micrograms per gram for distinguishing inflammatory from functional bowel conditions. The primary purpose is non-invasive differentiation of inflammatory bowel disease from irritable bowel syndrome and monitoring of mucosal healing during therapy. ELISA Kits retain the largest share of routine laboratory throughput due to established reimbursement codes and batch-processing economics, while Point-of-Care Devices represent the fastest-expanding segment as gastroenterology practices seek same-visit clinical decisions. Lateral Flow technology dominates near-patient settings where laboratory infrastructure remains limited, though Fluorescent Microscopy methods sustain premium positioning in academic medical centers requiring quantitative precision.
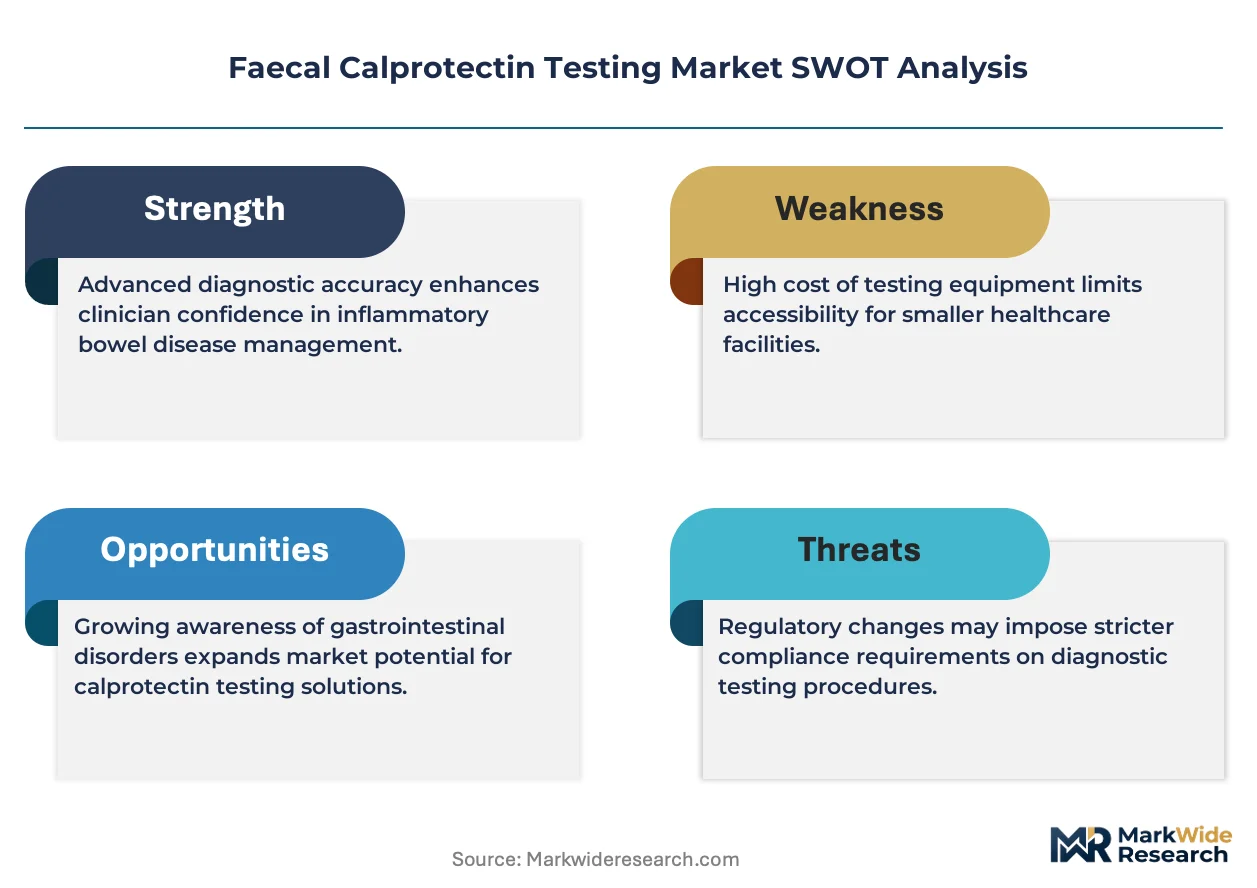
The FDA regulates faecal calprotectin assays as Class II IVD devices requiring 510(k) clearance, while the EU MDR transition is extending conformity assessment timelines for gastrointestinal biomarker manufacturers seeking CE marking renewal. ISO 13485 certification remains mandatory for supply chain access across both jurisdictions, with notified bodies scrutinizing stability validation for stool matrix controls. Stakeholders must monitor how decentralized IBD care models reshape volume allocation between hospital laboratories and outpatient clinic point-of-care deployments.
Market Dynamics
Hospital laboratories across Germany, the United Kingdom, and the United States are consolidating faecal calprotectin testing onto automated immunoassay platforms, compressing demand for manual ELISA workflows and reshaping vendor competitive positioning around installed-base compatibility.
Growth Catalysts
- Germany's statutory health insurance reimbursement:The country's statutory health insurance system reimburses faecal calprotectin screening for inflammatory bowel disease monitoring, creating predictable volume demand that anchors manufacturer investment in assay development.
- Quantitative immunoassay automation:Automated clinical chemistry analyzers are integrating faecal calprotectin reagents, enabling mid-volume hospital laboratories to process higher specimen throughput without proportional staffing expansion.
- Point-of-care lateral flow adoption:Gastroenterology practices in outpatient settings are deploying near-patient testing devices to deliver same-visit clinical decisions, bypassing centralized laboratory turnaround constraints.
Market Restraints
- EU MDR conformity assessment bottlenecks:The European Union Medical Device Regulation transition has extended notified body review timelines for gastrointestinal biomarker manufacturers seeking CE marking renewal, delaying product launches.
- Stool matrix control instability:Calprotectin degradation in faecal specimens requires stringent cold-chain logistics and rapid processing protocols, elevating operational costs for laboratories without same-day collection infrastructure.
- Serum biomarker substitution pressure:C-reactive protein and faecal lactoferrin assays compete for differential diagnostic positioning in inflammatory bowel disease workups, particularly where calprotectin reimbursement remains unsettled.
Strategic Opportunities
- Underpenetrated Asia-Pacific outpatient networks:Japan's community gastroenterology clinics and South Korea's health screening centers represent untapped deployment sites for quantitative point-of-care calprotectin devices.
- Fluorescent microscopy-poised academic centers:Research hospitals requiring high-precision mucosal healing quantification are adopting fluorescence-based quantitative immunoassays, sustaining premium pricing tiers.
- Home collection kit regulatory pathways:The FDA's refinement of 510(k) clearance frameworks for patient-collected stool specimens opens direct-to-consumer channels for IBD monitoring outside traditional laboratory networks.
Industry Challenges
- ISO 13485 stability validation complexity:Notified bodies are scrutinizing extended shelf-life claims for calprotectin controls in stool matrix, requiring costly real-time aging studies that compress development budgets.
- Legacy analyzer integration friction:Mid-volume laboratories face technical barriers when retrofitting automated immunoassay modules onto existing clinical chemistry platforms, necessitating vendor-specific engineering support.
- Cross-platform standardization gaps:Variability in calprotectin quantification between ELISA, quantitative immunoassay, and lateral flow methods complicates longitudinal patient monitoring across care transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Faecal Calprotectin Testing Market |
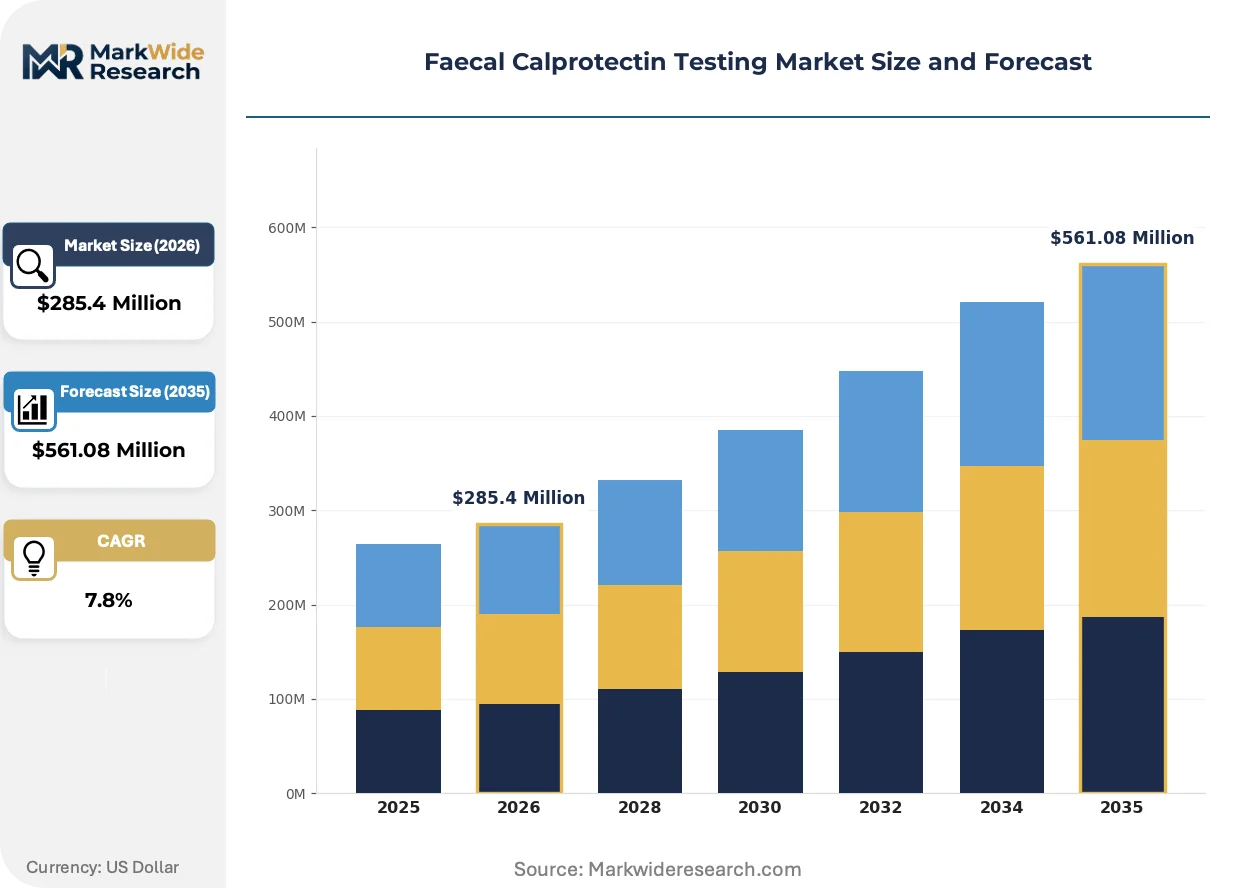
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $561.08 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA Kits, Rapid Test Kits, Point-of-Care Devices, Laboratory Analyzers Technology: Immunoassay, Lateral Flow, Fluorescent Microscopy, PCR End User: Hospitals, Diagnostic Laboratories, Academic Research Institutes, Outpatient Clinics Application: Inflammatory Bowel Disease, Gastrointestinal Disorders, Colorectal Cancer Screening, Routine Screening |
| Companies Covered | Diazyme Laboratories Inc., Hycult Biotech, BÜHLMANN Laboratories AG, Eagle Biosciences Inc., ALPCO, Epitope Diagnostics Inc., Svar Life Science, Operon S.A., Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Faecal Calprotectin Testing Market Shifts & Advancements
Faecal calprotectin testing is bifurcating between high-throughput automated platforms for hospital laboratories and rapid near-patient devices for outpatient gastroenterology, with technology choices increasingly dictated by reimbursement geography rather than clinical performance alone.
Fluorescent quantitative immunoassay technology is overtaking conventional ELISA workflows in academic medical centers requiring precise mucosal healing quantification. Large university hospitals in the United States and Germany are adopting these platforms to support biologic therapy monitoring protocols. The shift is compressing demand for manual batch-processing ELISA kits in tier-one institutions while sustaining premium pricing for quantitative precision.
The EU Medical Device Regulation's extended conformity assessment timelines are forcing gastrointestinal biomarker manufacturers to prioritize notified body relationships and stability documentation. Manufacturers are responding by consolidating product portfolios to focus on highest-volume assays with established clinical utility evidence. This regulatory friction most acutely affects mid-size reagent producers seeking CE marking renewal for specialized calprotectin formulations.
Hospital procurement committees are unbundelling after-sales service contracts from reagent supply agreements, pressuring vendors to compete on standalone technical support pricing. Gastroenterology department administrators in the United Kingdom and the Netherlands are leading this shift, separating analyzer maintenance from per-test reagent purchasing. This behavioral change is most visible in National Health Service trusts where centralized procurement frameworks mandate transparent service cost disclosure.
Faecal Calprotectin Testing Market Segmentation
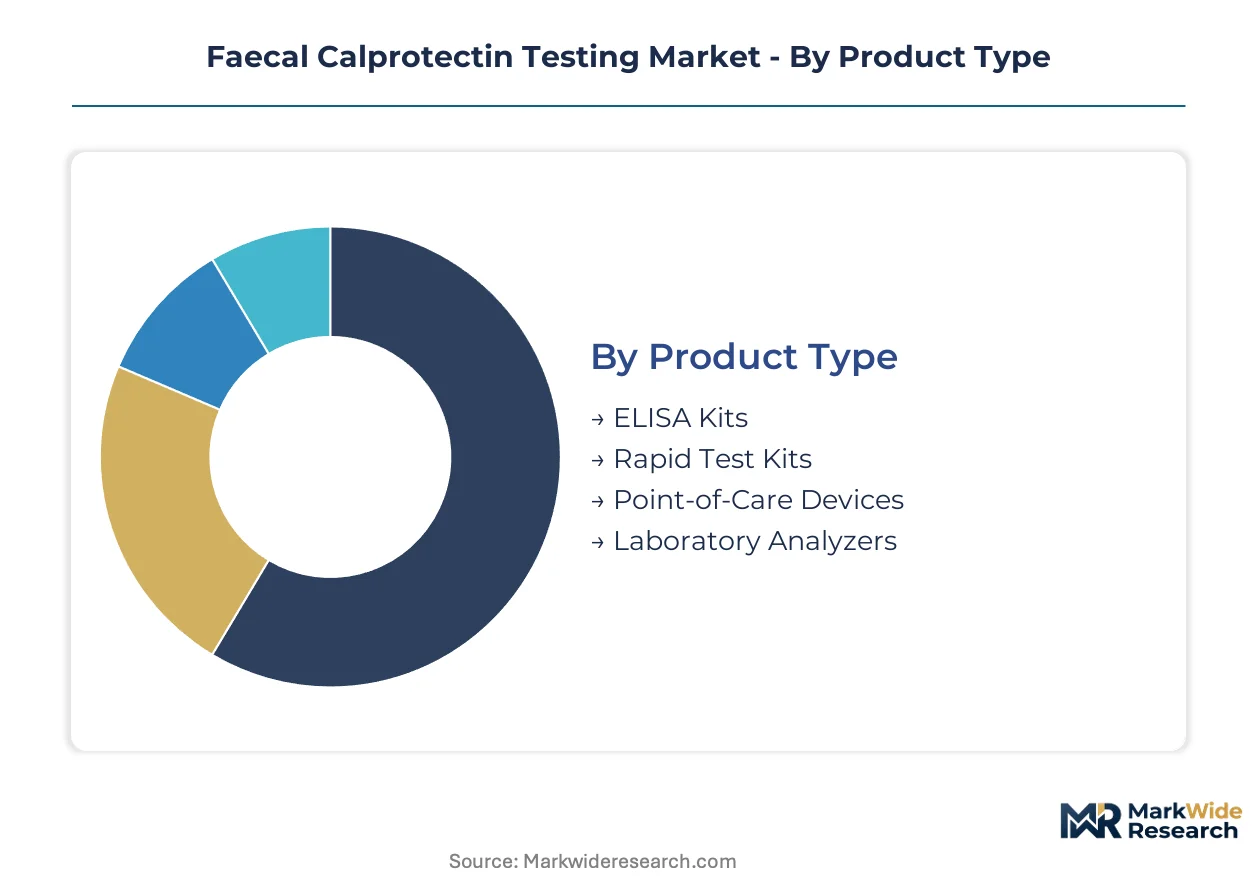
Faecal calprotectin testing spans multiple workflow configurations, from manual batch processing to fully automated platforms. Segmentation reveals how reimbursement geography and laboratory infrastructure dictate technology choices across care settings.
Product Type:
Upgrade cycles from manual ELISA to automated analyzers are compressing replacement timelines as hospital laboratories consolidate gastrointestinal biomarker workflows onto integrated chemistry platforms.
- ELISA Kits:Enzyme-linked immunosorbent assays remain the workhorse format for mid-volume laboratories processing 50-200 specimens daily. Demand concentrates in German hospital laboratories where statutory reimbursement codes sustain batch-processing economics despite automation pressure.
- Point-of-Care Devices:Portable quantitative and semi-quantitative analyzers enable same-visit clinical decisions in gastroenterology practices. Outpatient clinics across the United Kingdom are adopting these devices to bypass centralized laboratory turnaround constraints and capture IBD monitoring revenue directly.
- Rapid Test Kits:Single-use lateral flow cassettes serve resource-limited settings without cold-chain infrastructure.
- Laboratory Analyzers:Random-access clinical chemistry platforms with dedicated calprotectin reagent packs.
Volume placements concentrate in ELISA Kits; the faster expansion belongs to Point-of-Care Devices.
Technology:
Cost tiers separate premium quantitative precision from economy near-patient screening, with reimbursement differentials widening the technology gap between academic and community settings.
- Immunoassay:Automated chemiluminescent and turbidimetric methods deliver high-throughput quantification on clinical chemistry analyzers. Hospital laboratories in the United States are migrating toward these platforms to reduce manual handling and integrate calprotectin into routine inflammation panels.
- Lateral Flow:Immunochromatographic strips provide qualitative or semi-quantitative results within 15 minutes. Community gastroenterology clinics in Germany deploy these devices where same-day therapeutic adjustments justify higher per-test costs against laboratory referral fees.
- Fluorescent Microscopy:Quantitative fluorescence immunoassays achieve the lowest detection limits for mucosal healing protocols.
- PCR:Molecular amplification methods remain investigational for calprotectin quantification.
Immunoassay captures the highest absolute volumes; Fluorescent Microscopy is gaining share fastest in academic medical centers.
End User:
Customer type determines workflow complexity, with hospital procurement committees demanding analyzer compatibility while outpatient practices prioritize result speed over integration.
- Hospitals:Integrated health systems process calprotectin alongside C-reactive protein and erythrocyte sedimentation rate as part of standardized IBD workup protocols. Diagnostic laboratories within German university hospitals anchor the highest specimen volumes through centralized regional referrals.
- Diagnostic Laboratories:Independent reference laboratories compete on turnaround time and specialized gastrointestinal reporting. Commercial laboratories across the United Kingdom are consolidating faecal calprotectin with faecal immunochemical testing onto common automation tracks.
- Academic Research Institutes:University hospitals driving mucosal healing biomarker protocols.
- Outpatient Clinics:Community gastroenterology practices seeking point-of-care autonomy.
Hospitals retain the dominant placement base; Outpatient Clinics are expanding most quickly as decentralized IBD care models mature.
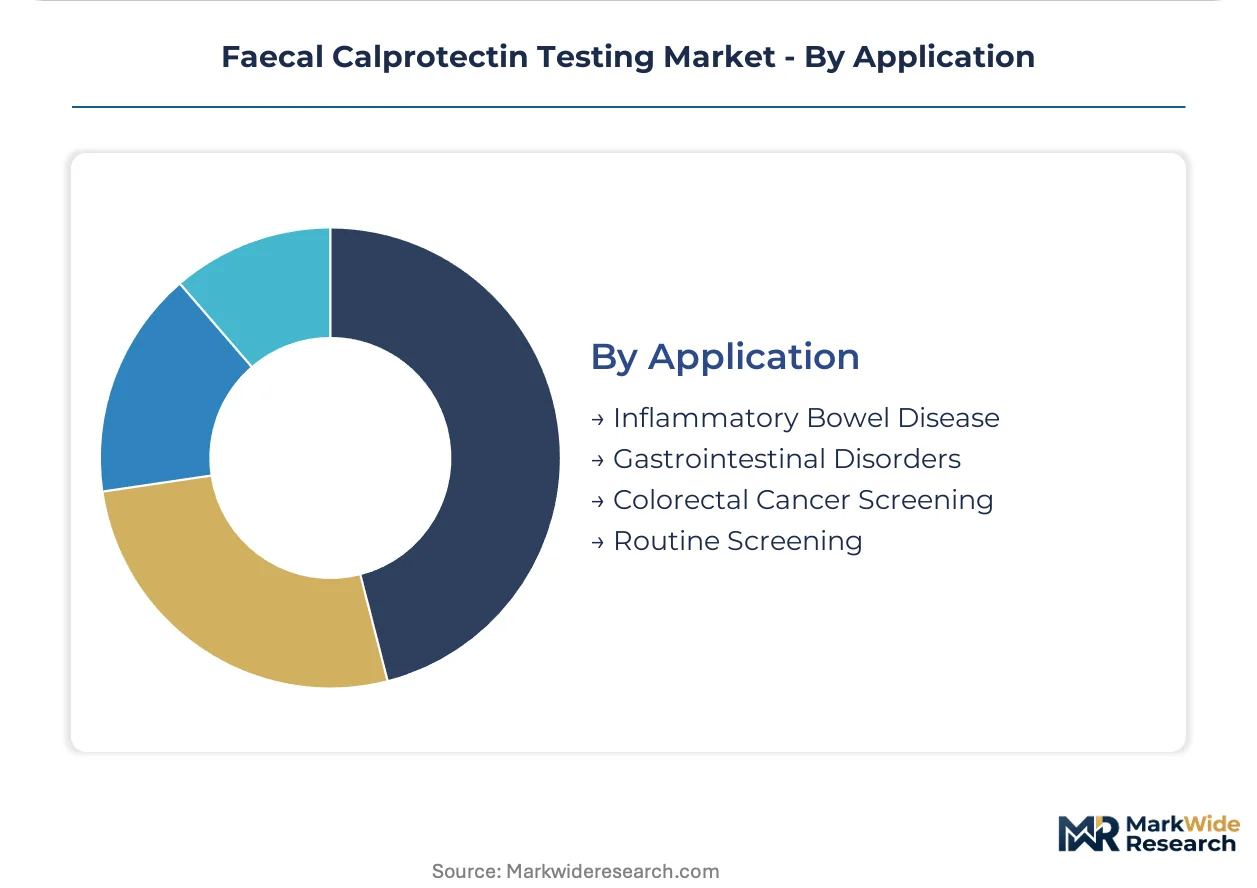
Application:
Maturity curves diverge sharply, with established IBD monitoring protocols contrasting against emerging screening applications where clinical utility evidence remains under development.
- Inflammatory Bowel Disease:Differentiation of Crohn's disease and ulcerative colitis from irritable bowel syndrome, plus therapy response monitoring. Gastroenterology departments in Germany rely on serial calprotectin measurement to guide biologic dose escalation or de-escalation decisions.
- Gastrointestinal Disorders:Functional bowel condition exclusion and microscopic colitis investigation. Diagnostic laboratories across the United States are expanding calprotectin ordering for unexplained diarrhoea workups where endoscopy access faces scheduling constraints.
- Colorectal Cancer Screening:Adjunctive inflammation marker to faecal immunochemical testing.
- Routine Screening:Asymptomatic population surveillance remains investigational.
Inflammatory Bowel Disease commands the deepest volume penetration; Gastrointestinal Disorders represents the steepest expansion trajectory as diagnostic criteria broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stool specimen collection logistics concentrate demand in countries with dense laboratory networks and established inflammatory bowel disease management protocols. Reimbursement stability and regulatory clarity determine where manufacturers prioritize assay platform launches.
Germany
Statutory health insurance reimbursement for faecal calprotectin screening anchors predictable volume demand for IBD monitoring. The EU MDR transition extends notified body review timelines for gastrointestinal biomarker CE marking renewals. Bavarian university hospitals in Munich and Erlangen anchor centralized regional referrals for mucosal healing quantification protocols.
United States
Hospital laboratories consolidate gastrointestinal biomarker workflows onto automated clinical chemistry analyzers to reduce manual handling. The FDA's 510(k) clearance framework for Class II IVD devices governs market entry for novel assay formats. Academic medical centers in Boston and the Research Triangle Park adopt fluorescent quantitative immunoassays for biologic therapy monitoring.
United Kingdom
National Health Service trusts unbundle after-sales service contracts from reagent supply agreements, mandating transparent technical support cost disclosure. The Medicines and Healthcare products Regulatory Agency oversees IVD conformity assessment alongside EU MDR alignment pressures. London and Manchester diagnostic laboratories consolidate faecal calprotectin with faecal immunochemical testing onto common automation tracks.
Japan
Community gastroenterology clinics represent untapped deployment sites for quantitative point-of-care calprotectin devices. The Pharmaceuticals and Medical Devices Agency regulates IVD market entry through pre-market approval pathways. Tokyo and Osaka metropolitan clusters concentrate demand for high-throughput automated platforms in university-affiliated hospitals.
South Korea
Health screening centers drive volume expansion for non-invasive gastrointestinal inflammation assessment. The Ministry of Food and Drug Safety oversees IVD classification and quality management system certification. Seoul Capital Area diagnostic networks prioritize rapid turnaround capabilities for outpatient IBD monitoring workflows.
Faecal Calprotectin Testing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue point-of-care miniaturization and home collection kit regulatory pathways. The vendor base stratifies across multinational life science conglomerates, specialized European diagnostics firms, and cost-engineered reagent suppliers. Three archetypes dominate: platform-integrated system providers, gastrointestinal biomarker specialists, and mid-volume ELISA formulators. Competitive moves center on analyzer installed-base conversion and notified body relationship consolidation for EU MDR compliance.
Among specialized European diagnostics firms, BÜHLMANN Laboratories AG and Svar Life Science exemplify deep gastrointestinal biomarker assay development expertise. Thermo Fisher Scientific Inc. anchors the platform-integrated tier through clinical chemistry analyzer distribution networks. Diazyme Laboratories Inc. occupies the cost-engineered reagent segment for mid-volume laboratory price sensitivity.
| Leading Market Players |
|---|
| Diazyme Laboratories Inc. |
| Hycult Biotech |
| BÜHLMANN Laboratories AG |
| Eagle Biosciences Inc. |
| ALPCO |
| Epitope Diagnostics Inc. |
| Svar Life Science |
| Operon S.A. |
| Thermo Fisher Scientific Inc. |
| Others |
Supply & Pricing Matrix
National Health Service procurement unbundling in the United Kingdom strips after-sales service from reagent contracts, compelling manufacturers to restructure pricing around standalone technical support and compressing margins on analyzer placements. This buyer-driven separation of hardware and service economics reshapes how vendors recover costs across automated platform and point-of-care segments.
Pricing Analysis
Service-bundling unbundling dominates contract negotiations, with NHS trusts and German statutory insurers now mandating transparent separation of analyzer maintenance from per-test reagent purchasing. Pricing stratifies across premium fluorescent microscopy systems for academic medical centers, standard automated immunoassay platforms for hospital laboratories, and economy lateral flow cassettes for resource-limited settings. Cost compression in the ELISA tier intensifies because mid-volume laboratories face automation retrofit expenses without proportional reimbursement expansion. Community gastroenterology clinics exhibit highest price sensitivity due to direct per-test cost exposure, while university hospitals prioritize quantitative precision over unit economics.
Supply Chain Analysis
Specialized diagnostic reagent manufacturing workforce availability concentrates in Switzerland, Germany, and the northeastern United States, where ISO 13485-certified facilities anchor gastrointestinal biomarker production. Antibody production for S100A8/A9 detection draws from Chinese biologics contractors and domestic European fermentation capacity. Single-source vulnerability runs through stool matrix control suppliers, where extended stability validation requirements tether manufacturers to qualified vendors. Distribution runs through regional diagnostic distributors serving hospital procurement committees and direct-to-clinic channels for point-of-care devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The faecal calprotectin testing market operates as a vertical-integration race, with incumbents pursuing backward control over antibody supply chains and emerging players capturing downstream patient-collected specimen channels.
For Market Incumbents: Anticipate serum biomarker substitution pressure from C-reactive protein and faecal lactoferrin assays by deepening in-house production of S100A8/A9 antibody pairs and securing exclusive distribution through GPO contracts. Consolidate notified body relationships for EU MDR compliance acceleration, as CE marking renewal timelines now determine competitive shelf presence. For New Entrants and Emerging Players: FDA refinement of 510(k) clearance frameworks for patient-collected stool specimens in the United States opens a window for home collection kit market entry, bypassing established laboratory networks. Target Japan's community gastroenterology clinics and South Korean health screening centers with quantitative point-of-care devices, deploying direct sales teams to circumvent distributor margin stacking. For Investors and Strategic Acquirers: The window for entry favors specialized European diagnostics firms with deep gastrointestinal biomarker assay development expertise and existing notified body relationships. Watch EU MDR conformity assessment timeline resolution as the inflection indicator for portfolio consolidation activity; accelerated clearance pathways would trigger incumbent acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment acceleration secures market access for automated platform launches. |
| Hospital System Partnership | Installed-base conversion agreements with German university hospitals anchor predictable reagent volume. |
| Reimbursement Strategy | Statutory health insurance code expansion in Germany stabilizes per-test economics for IBD monitoring. |
| Software Companion Development | Quantitative result interpretation algorithms differentiate fluorescent microscopy platforms in academic centers. |
| Backward Integration into Antibody Supply | Captive S100A8/A9 antibody production insulates margin from biologics contractor pricing volatility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital laboratory directors, gastroenterology practice administrators, diagnostic reagent procurement managers, and notified body technical assessors. FDA 510(k) clearance databases, EU MDR technical documentation, and German statutory health insurance reimbursement schedules provided validation anchors. Bottom-up specimen volume modeling triangulated against top-down market sizing from automated analyzer placement data.
Granularity-level modeling operated at the intersection of product type, technology platform, end-user facility category, and geographic reimbursement cluster. CAGRs derived from weighted average of historic volume trajectories and projected automation adoption curves across the analysis window. Assay format migration rates from ELISA to quantitative immunoassay, point-of-care penetration ceilings by clinic type, and regulatory approval timeline distributions informed scenario boundaries.
The model assumes a particular technology adoption path; alternative pathways for fluorescent quantitative immunoassay would alter the outlook if lateral flow sensitivity improvements accelerate. Forecasts reflect assumptions around EU MDR transition completion pacing and FDA home collection kit pathway finalization. Material deviation in reimbursement code stability or notified body capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Tablet Hardness Testers Market
Testing Services
Global Mycoplasma Testing Market
Testing Services
Irradiation Sterilization Services Market
Testing Services
US C-Reactive Protein Testing Market
Testing Services
Viral Vector Integrity and Potency Analytics Test Instruments Market
Testing Services
Global ADME Toxicology Testing Market
Testing Services
Global Virology Testing Market
Testing Services
Human Papilloma Virus Testing Market
Testing Services
United States Testing, Inspection, and Certification (TIC) Market
Testing Services
Sterilization Monitoring Technologies Market
Testing Services
Host Cell Protein Testing Market
Testing Services
Global Cholesterol Testing Products and Services Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
Sports Drug Testing Market
Testing Services
US at-Home Testing Kits Market
Testing Services
US & Europe Extractable and Leachable Testing Services Market