
 Armored Vehicle Procurement and Upgrade Market | 2026-2036
Armored Vehicle Procurement and Upgrade Market Size, Share, and Industry Trends Forecast 2026-2036
Armored Vehicle Procurement and Upgrade Market Outlook
Poland's defense industrial expansion is reshaping European armored vehicle supply chains, with Rheinmetall AG leveraging its new Lynx production facility in Swietoszow to anchor regional manufacturing capacity. BAE Systems plc sustains transatlantic relevance through its Bradley Fighting Vehicle upgrade programs, while Hanwha Defense competes aggressively by extending its K21 and Redback platforms into European tender processes. General Dynamics Corporation dominates US ground combat vehicle modernization through its Stryker and Abrams upgrade pipelines.
Armored vehicle procurement and upgrade encompasses the acquisition, retrofit, and life-extension of ballistic-protected platforms rated against kinetic threats, blast overpressure, and electromagnetic interference, typically incorporating composite armor arrays, active protection systems, and modular turret architectures to preserve crew survivability across multi-domain battlefields. Heavy armored vehicles occupy the largest value pool due to platform longevity and subsystem complexity, while surveillance systems within upgrade features represent the fastest-growing margin segment as sensor fusion and unmanned turret architectures displace legacy optics. Military end users control the dominant procurement channel, though law enforcement demand for mine-resistant ambush-protected vehicles has created a secondary volume tier through direct purchase mechanisms.
The US Army's Ground Vehicle Systems Center, NATO's Standardization Office, and Germany's Federal Office of Bundeswehr Equipment operate as the triad shaping technical requirements, with STANAG 4569 ballistic protection levels and electromagnetic compatibility mandates directly determining platform eligibility for allied procurement. The EU's Permanent Structured Cooperation framework on defense and emerging US Congressional restrictions on foreign component sourcing are tightening supply chain qualification thresholds. Stakeholders must monitor how NATO's next-generation armor requirements and Indo-Pacific militaries' amphibious platform specifications will bifurcate R&D investment priorities between European and Asian design philosophies.
Market Dynamics
The STANAG 4569 protection standard revision is compressing procurement cycles as NATO members accelerate mechanized infantry modernization ahead of interoperability deadlines. This regulatory pressure is redistributing contract awards toward platforms with certified active protection systems and modular armor architectures.
Growth Catalysts
- EU Permanent Structured Cooperation:This framework pools member state R&D funding for cross-border armored vehicle development, creating economies of scale for medium-sized defense contractors.
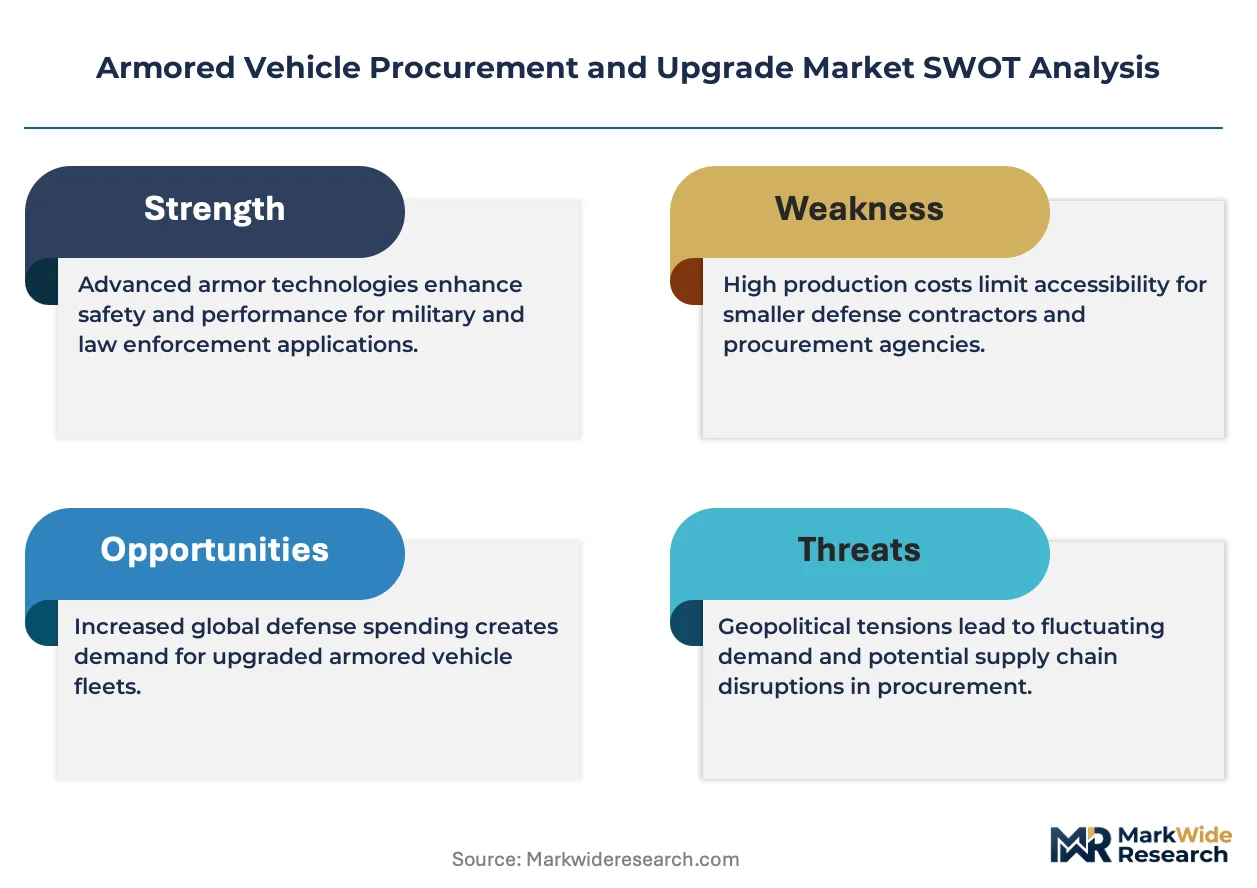
- Active Protection Systems:Hard-kill and soft-kill countermeasures against anti-tank guided missiles are becoming mandatory in Polish and German tender specifications, expanding subsystem addressable value.
- Indo-Pacific amphibious requirements:Japan's Ground Self-Defense Force and the Australian Army are specifying corrosion-resistant hull treatments and swim capability, diverting R&D investment toward maritime mobility packages.
Market Restraints
- Titanium and high-hardness steel volatility:Armor-grade alloy prices fluctuate with aerospace sector demand, squeezing fixed-price contract margins for hull fabricators.
- Single-source turret ring suppliers:European production of precision-machined bearing assemblies concentrates in southwestern Germany, creating geographic chokepoints for NATO-wide programs.
- Electromagnetic spectrum congestion:Active protection radars interfere with friendly force communications, limiting simultaneous deployment density on congested battlefields.
Strategic Opportunities
- Unmanned turret architectures:Crew capsule decoupling from weapon stations permits lighter hull designs and opens retrofit markets for legacy infantry fighting vehicles.
- US Congressional domestic sourcing mandates:Buy American provisions in National Defense Authorization Acts incentivize reshoring of armor ceramic production to qualified US facilities.
- Urban warfare retrofit packages:Brazilian and Colombian security forces require 360-degree camera suites and underbody blast protection for law enforcement armored vehicles.
Industry Challenges
- Systems integration engineering talent:Shortages of military-qualified software architects delay sensor fusion timelines for next-generation battle management systems.
- STANAG 4569 Level 6 certification timelines:Live-fire testing protocols for mine blast protection require 18-24 month validation cycles, compressing platform delivery windows.
- Legacy fleet interoperability:Digital backbone upgrades for Cold War-era chassis demand custom mechanical-electrical interface solutions that fragment supplier margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Armored Vehicle Procurement and Upgrade Market |
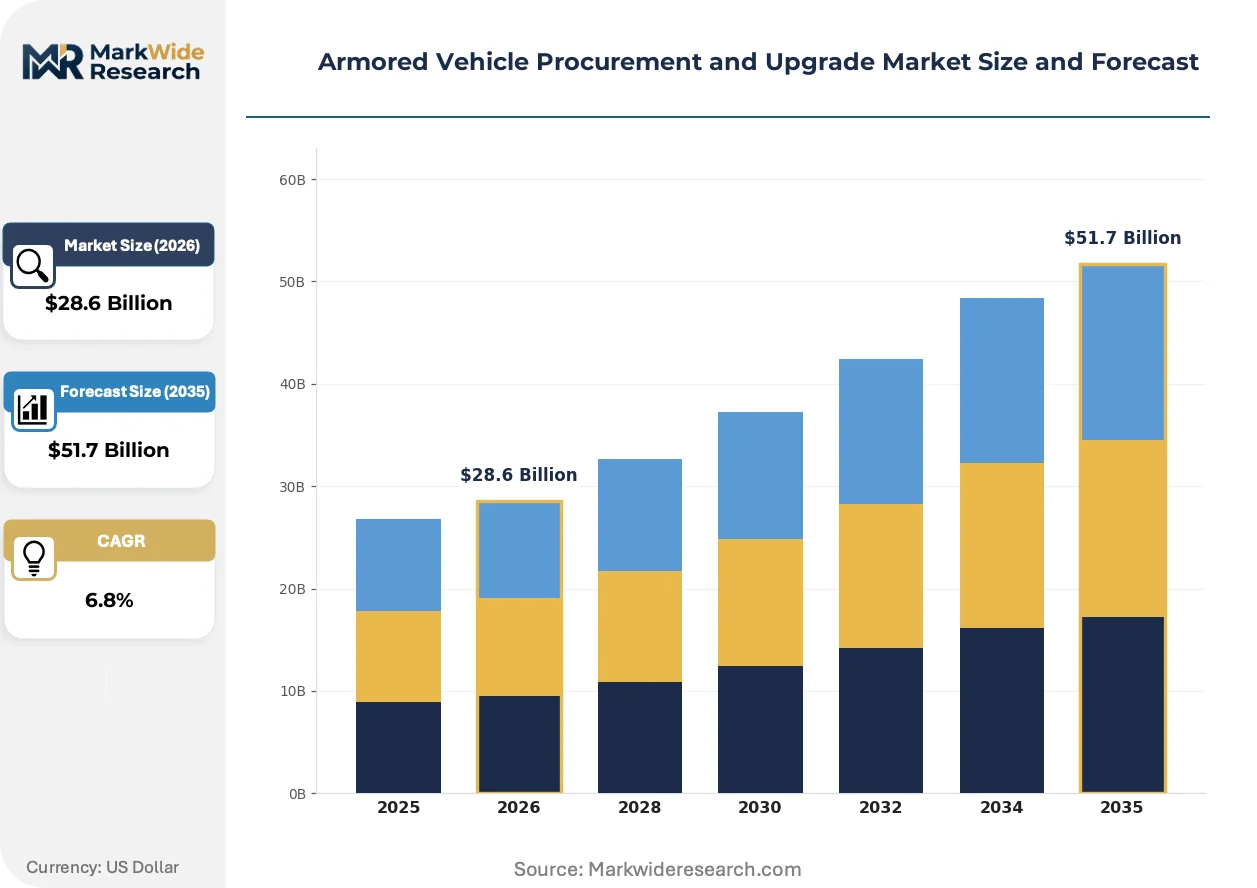
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Armored Vehicles, Medium Armored Vehicles, Heavy Armored Vehicles, Tactical Vehicles Upgrade Feature: Armor Enhancement, Weapons Systems, Surveillance Systems, Communication Systems End User: Military, Law Enforcement, Private Security, Government Agencies Procurement Method: Direct Purchase, Lease, Auction, Government Contracts |
| Companies Covered | General Dynamics Corporation, BAE Systems plc, Rheinmetall AG, Textron Inc., Oshkosh Corporation, Lockheed Martin Corporation, Leonardo S.p.A., Hanwha Defense, Nexter Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Armored Vehicle Procurement and Upgrade Market Strategic Shifts
Electrified powertrains and autonomous mobility kits are bifurcating platform development roadmaps, forcing prime contractors to maintain parallel engineering teams for manned and optionally manned variants.
Composite armor arrays integrating ceramic tiles with polymer matrix backings are rendering obsolete traditional rolled homogeneous steel hulls. The US Army's Ground Vehicle Systems Center has mandated weight reduction targets that exclude legacy metallurgy. This shift compresses supplier qualification timelines as foundries retool for laminate fabrication.
REACH chemical restrictions in Europe and EPA perfluorinated substance regulations in the US are banning legacy fire suppression and corrosion coating chemistries. Armor system integrators must reformulate internal hull treatments and recertify fire safety protocols. German and French procurement offices now require substance compliance documentation at technical proposal stage.
Life-cycle availability contracts are displacing transactional platform purchases in NATO member tenders. Danish and Dutch defense ministries now contract for guaranteed operational readiness percentages rather than hull delivery milestones. This transfers subsystem obsolescence risk to original equipment manufacturers and concentrates aftermarket revenue with platform primes.
Armored Vehicle Procurement and Upgrade Market Segmentation
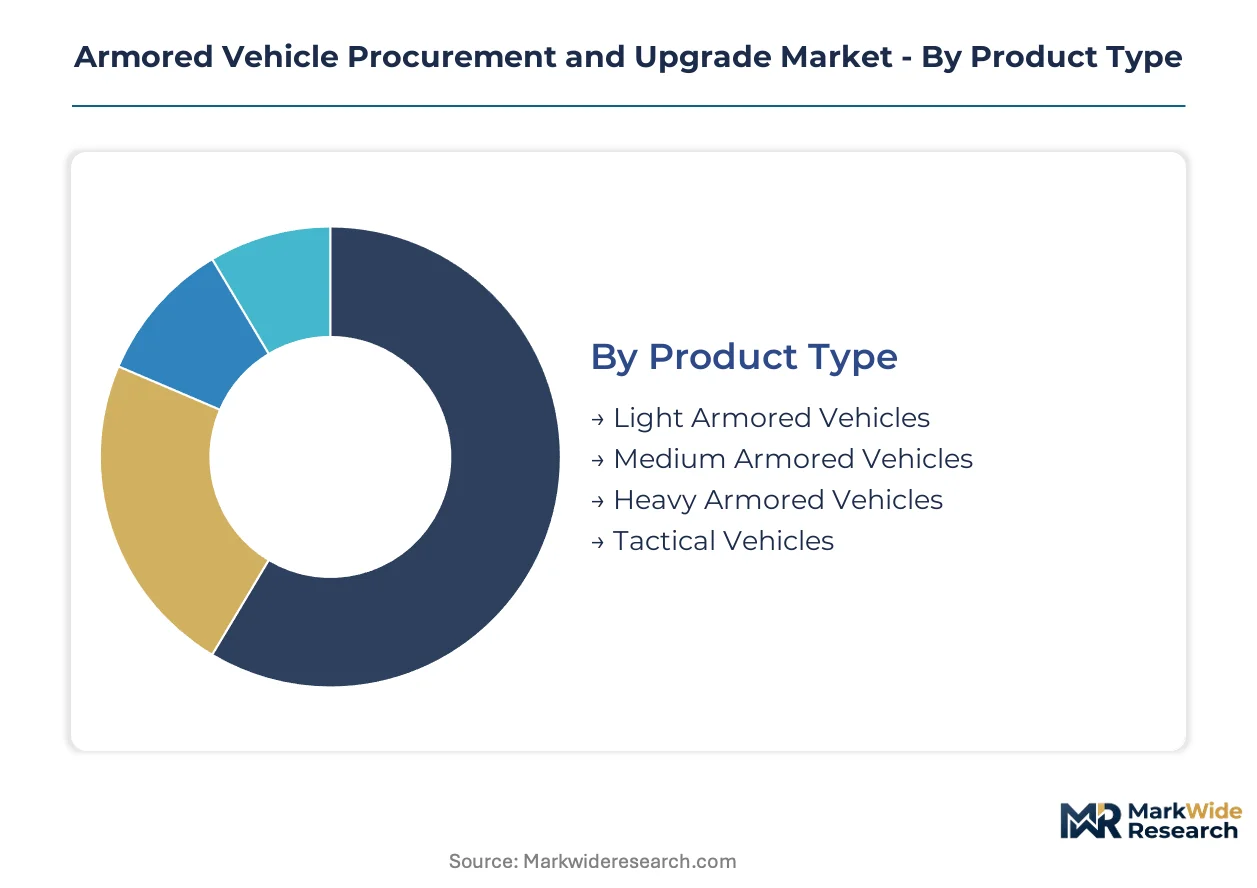
Platform weight classes and subsystem upgrade priorities determine procurement budget allocation and supplier qualification pathways across NATO and allied defense ministries. Procurement method selection reflects fiscal constraints, operational tempo requirements, and sovereign industrial policy preferences.
Product Type:
Mature heavy platforms anchor fleet modernization budgets while emerging tactical configurations reshape expeditionary deployment concepts.
- Heavy Armored Vehicles:Main battle tanks and infantry fighting vehicles integrate composite armor arrays, active protection systems, and modular turret architectures rated against kinetic energy penetrators and blast overpressure. Poland's K2 acquisition program and Germany's Panther KF51 development concentrate regional demand for 50+ tonne platforms with certified STANAG 4569 Level 6 protection.
- Medium Armored Vehicles:Wheeled and tracked platforms in the 15-35 tonne range balance strategic mobility against crew survivability, with the US Army's Stryker family and European 8x8 programs driving standardization around modular mission equipment packages. NATO's push for mechanized interoperability elevates procurement priority for platforms with common digital backbone architectures.
- Light Armored Vehicles:Protected mobility vehicles below 15 tonnes emphasize air-transportability and urban maneuverability for special operations and reconnaissance formations.
- Tactical Vehicles:Unarmored or lightly upfitted trucks and utility platforms support logistics and command functions in permissive threat environments.
Heavy Armored Vehicles handles the majority of throughput; Medium Armored Vehicles is the fastest mover on share.
Upgrade Feature:
Margin concentration shifts toward sensor and electronic warfare subsystems as platform hull lifespans extend through incremental retrofit cycles.
- Surveillance Systems:Unmanned turret architectures, 360-degree situational awareness cameras, and sensor fusion battle management systems displace legacy thermal optics and periscopes. Australian and Japanese amphibious specifications accelerate corrosion-resistant electro-optical package development.
- Armor Enhancement:Ceramic-polymer composite arrays, reactive armor tiles, and underbody blast deflectors retrofit legacy hulls to current protection standards. REACH chemical restrictions and EPA perfluorinated substance regulations force reformulation of fire suppression and corrosion coating chemistries across European and US upgrade programs.
- Weapons Systems:Remote weapon stations, medium-caliber autocannons, and anti-tank guided missile launchers integrate through standardized turret ring interfaces.
- Communication Systems:Software-defined radios, satellite uplink modules, and encrypted data networks enable network-centric warfare interoperability.
Armor Enhancement absorbs the largest retrofit expenditure; Surveillance Systems delivers the steepest expansion trajectory.
End User:
Volume concentration reflects sovereign defense commitments while secondary channels create aftermarket service opportunities.
- Military:Army, marine corps, and special operations forces control platform procurement through national defense ministries and NATO collaborative frameworks. Life-cycle availability contracts in Denmark and the Netherlands transfer subsystem obsolescence risk to original equipment manufacturers.
- Law Enforcement:Federal and municipal police agencies acquire mine-resistant ambush-protected vehicles and armored personnel carriers for counter-terrorism and high-risk warrant service. Brazilian and Colombian security forces drive demand for urban warfare retrofit packages with 360-degree camera suites and underbody blast protection.
- Government Agencies:Border patrol, customs, and critical infrastructure protection services procure lightly armored mobility platforms.
- Private Security:Corporate and diplomatic protection services lease or purchase retired military platforms through secondary markets.
Military commands the dominant procurement channel; Law Enforcement generates the fastest-growing secondary volume tier.
Procurement Method:
Contract structure selection determines supplier cash flow timing and long-term revenue concentration.
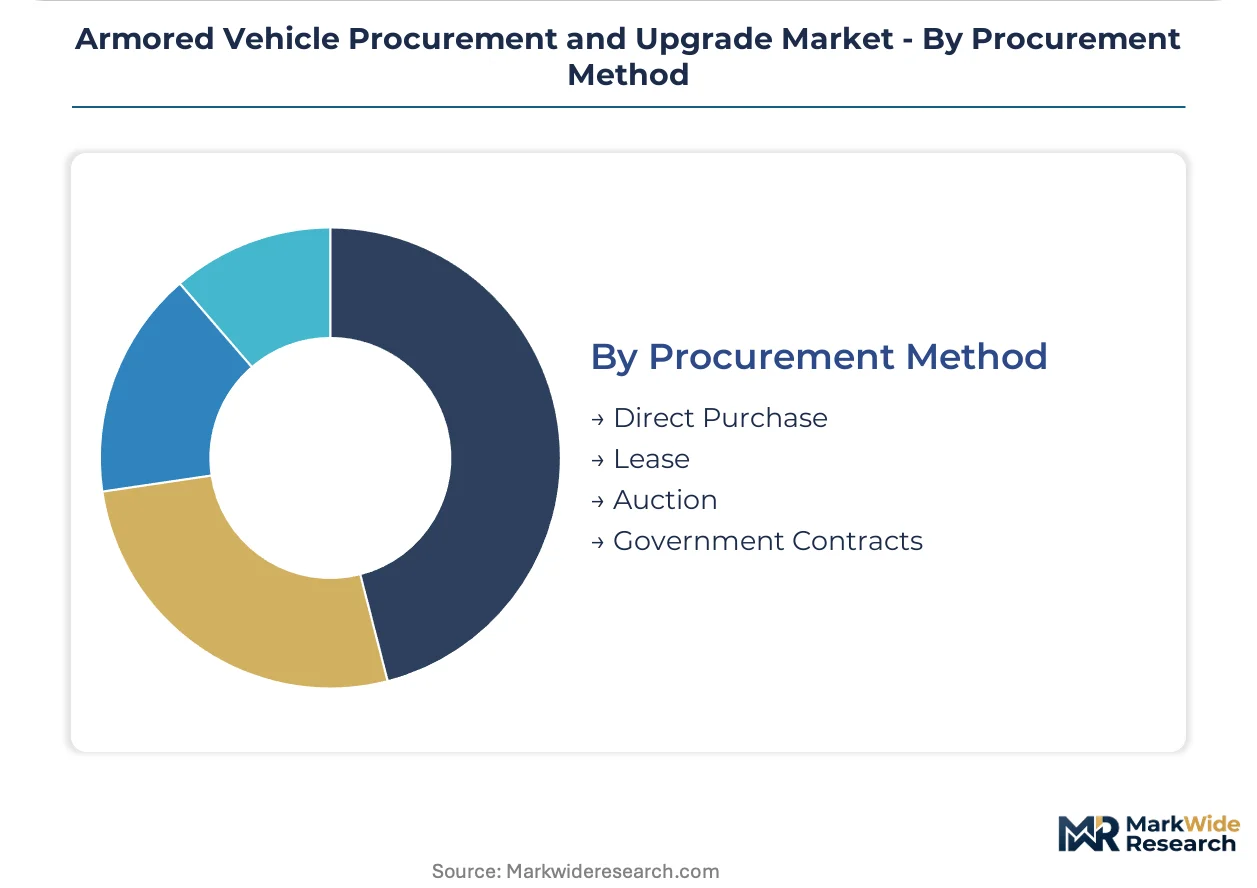
- Government Contracts:Multi-year framework agreements and competitive tenders dominate NATO member state acquisition, with EU Permanent Structured Cooperation pooling R&D funding for cross-border development programs. US Congressional domestic sourcing mandates in National Defense Authorization Acts restrict foreign component eligibility.
- Direct Purchase:Off-the-shelf acquisition of proven platforms accelerates fielding timelines for frontline states facing immediate threat elevation.
- Lease:Operational leasing arrangements preserve capital budgets for platforms with rapid technology obsolescence cycles.
- Auction:Surplus platform disposal and secondary market redistribution channels supply law enforcement and private security demand segments.
Government Contracts structures the preponderance of value flow; Direct Purchase climbs fastest as frontline NATO members accelerate mechanized modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Army's Ground Vehicle Systems Center anchors procurement volume through multi-year modernization frameworks. NATO's Standardization Office harmonizes STANAG 4569 certification requirements across allied defense ministries. Procurement demand concentrates in frontline states facing elevated threat environments.
United States
The Optionally Manned Fighting Vehicle program and Stryker family upgrades drive Army ground combat vehicle investment. Congressional domestic sourcing mandates in National Defense Authorization Acts restrict foreign component eligibility for prime contracts. Michigan and Ohio industrial corridors host hull fabrication and turret integration facilities serving Pentagon acquisition channels.
Germany
The Panther KF51 development and Lynx infantry fighting vehicle production anchor European heavy platform supply. The Federal Office of Bundeswehr Equipment mandates STANAG 4569 Level 6 certification for mine blast protection in all new procurements. The Swietoszow facility in southwestern Poland extends German manufacturing capacity into NATO's eastern flank.
Poland
Accelerated K2 tank and IFV acquisitions from South Korean suppliers address immediate mechanized modernization gaps. EU Permanent Structured Cooperation frameworks pool R&D funding for cross-border armored vehicle development programs. The southeastern industrial zone around Dęblin hosts final assembly operations for foreign-sourced platforms.
South Korea
Hanwha Defense extends K21 and Redback platforms into European tender processes through offset agreements. The country's national defense procurement agency coordinates technology transfer provisions with NATO member states. The Changwon cluster in South Gyeongsang Province concentrates tracked vehicle production and active protection system integration.
Australia
The Australian Army specifies corrosion-resistant hull treatments and amphibious swim capability for Indo-Pacific expeditionary requirements. The Department of Defence mandates interoperability with US Marine Corps platform specifications through AUKUS security arrangements. Victoria-based facilities handle integration of surveillance and communication subsystems for regional deployment.
Armored Vehicle Procurement and Upgrade Market Competitive Environment
Transatlantic primes and Asian challengers split the market between legacy platform sustainment and new entrant disruption. Consolidation around national champions persists despite EU cross-border cooperation frameworks. Two archetypes dominate: integrated system houses controlling full platform lifecycles, and subsystem specialists capturing upgrade retrofit margins. Prime contractors pursue capacity expansion through foreign direct investment in frontline NATO states, while component suppliers license active protection technologies across multiple hull integrators.
Within the integrated system house tier, General Dynamics Corporation and BAE Systems plc anchor transatlantic procurement channels through long-term sustainment contracts. Rheinmetall AG exemplifies the European challenger archetype by establishing captive production capacity in Poland. Hanwha Defense represents the Asian export-oriented model, leveraging offset agreements to penetrate NATO tender processes previously closed to non-allied suppliers.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| BAE Systems plc |
| Rheinmetall AG |
| Textron Inc. |
| Oshkosh Corporation |
| Lockheed Martin Corporation |
| Leonardo S.p.A. |
| Hanwha Defense |
| Nexter Systems |
| Others |
Value Chain & Pricing Dynamics
The Changwon cluster in South Gyeongsang Province anchors tracked vehicle production capacity for Hanwha Defense's K21 and Redback exports, translating concentrated manufacturing scale into pricing leverage for NATO tender processes. Hull fabricators in southwestern Germany and Michigan's industrial corridors face divergent cost pressures from alloy input volatility and Congressional domestic sourcing mandates.
Pricing Analysis
Geographic price spreads between European and Asian platform suppliers reflect divergent labor cost structures and offset agreement frameworks. Three-tier pricing structure across premium, standard, and economy levels segments by STANAG 4569 certification grade and active protection system integration depth. Pricing pressure stems from titanium and high-hardness steel volatility squeezing fixed-price contract margins. Law enforcement buyers exhibit highest price sensitivity due to capital budget constraints, while military end users prioritize life-cycle availability over unit acquisition cost.
Supply Chain Analysis
Armor-grade alloy feedstock draws from German, South Korean, and US specialty steel foundries with aerospace sector demand competing for capacity. Ceramic-polymer composite arrays, precision-machined turret ring bearings, and active protection system radars constitute critical component dependencies. Single-source turret ring suppliers in southwestern Germany create geographic chokepoints for NATO-wide programs. Distribution runs through government contract frameworks and direct purchase mechanisms with minimal spot market activity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards firms controlling scarce systems integration engineering talent and certified STANAG 4569 testing infrastructure. The gap between platform prime capabilities and subsystem specialist margins is widening as life-cycle availability contracts transfer obsolescence risk.
For Market Incumbents: Insulate core platform positions through captive production capacity in frontline NATO states like Poland's Swietoszow facility, while deepening software architecture capabilities to capture sensor fusion upgrade cycles. Threats from Asian export-oriented challengers with offset agreements demand accelerated certification investment for active protection systems. Backward integration into armor ceramic production addresses US Congressional domestic sourcing mandates. For New Entrants and Emerging Players: Establish a beachhead in urban warfare retrofit packages for Brazilian and Colombian law enforcement agencies, where 360-degree camera suites and underbody blast protection specifications outpace incumbent response timelines. White-space concentration in amphibious mobility packages for Australian and Japanese Indo-Pacific requirements offers lower certification barriers than European heavy platform tenders. Go-to-market leverage rests on corrosion-resistant hull treatment specialization. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors subsystem specialists with unmanned turret architectures and sensor fusion software stacks over legacy hull integrators. Long-term viability hinges on electrified powertrain and autonomous mobility kit development pipelines. Acquisition targets should demonstrate certified STANAG 4569 Level 6 testing infrastructure and established relationships with the US Army's Ground Vehicle Systems Center. Watch for Indo-Pacific amphibious specification divergence as an inflection indicator for R&D investment reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Active Protection System Certification | Hard-kill and soft-kill countermeasures are becoming mandatory in Polish and German tender specifications. |
| Captive Production in Frontline States | Rheinmetall's Swietoszow facility anchors regional manufacturing capacity for NATO's eastern flank demand. |
| Unmanned Turret Architecture Development | Crew capsule decoupling permits lighter hull designs and opens retrofit markets for legacy IFVs. |
| Corrosion-Resistant Hull Treatment Specialization | Australian and Japanese amphibious specifications accelerate maritime mobility package R&D investment. |
| Life-Cycle Availability Contract Structuring | Danish and Dutch defense ministries now contract for guaranteed operational readiness percentages. |
Study Parameters
A standing panel of program managers at the US Army's Ground Vehicle Systems Center, NATO Standardization Office technical leads, defense procurement officers at Germany's Federal Office of Bundeswehr Equipment, and active protection system engineering directors provided ongoing calibration. Primary interviews with hull fabricators, turret integrators, and subsystem suppliers combined with secondary validation from STANAG 4569 certification records, EU Permanent Structured Cooperation framework documents, and National Defense Authorization Act procurement disclosures. Bottom-up platform delivery forecasts and top-down defense budget allocation analysis triangulated market sizing.
Scenario-bracketing around STANAG 4569 revision timelines and Indo-Pacific amphibious specification divergence framed projection uncertainty. Segmentation modeling spanned platform weight class, upgrade feature priority, end-user channel, and procurement method dimensions across the analysis window. CAGRs derived from defense ministry capital expenditure trajectories and platform replacement cycle analysis. Forecast inputs incorporated alloy price volatility indices and electromagnetic spectrum allocation regulatory developments.
Macroeconomic conditions sit as an overlay; deviation in defense budget prioritization, aerospace sector alloy demand, or NATO threat perception calibration would shift the trajectory. Forecasts reflect documented assumptions regarding interoperability deadline adherence and technology transfer agreement execution. Cross-checking against national defense procurement agency disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Armored Vehicles
Middle-East and Africa Armored Vehicles Market
Armored Vehicles
Armoured Personnel Carrier (APC) Market
Armored Vehicles
Europe Armored Fighting Vehicles Market
Armored Vehicles
Armored Personnel Carrier Market
Armored Vehicles
Military Armored Car Market
Armored Vehicles
Armored Fighting Vehicles Market
Armored Vehicles
North America Armored Fighting Vehicles Market
Armored Vehicles
Asia-Pacific Armored Fighting Vehicles Market
Armored Vehicles
Armored Vehicles Market
Armored Vehicles
Armored Vehicle Navigation Systems Market
Armored Vehicles
Armored Vehicles Upgrade and Retrofit Market
Armored Vehicles
Armor Protection Systems Market
Armored Vehicles
US Armored Vehicle Market
Armored Vehicles
Global Ceramic Armor Market
Armored Vehicles
Armored Vehicle Fire Suppression Systems Market
Armored Vehicles
Boom Arms Market