
 Global Commercial Satellite Imagery Market | 2026-2036
Global Commercial Satellite Imagery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Satellite Imagery Market Foresight
Modular tasking packages is realigning how defense and intelligence buyers contract for satellite capacity. Maxar Technologies leverages its geostationary and polar orbit assets to sustain long-term government relationships. Planet Labs anchors daily coverage capabilities through its Dove and SkySat constellations. BlackSky differentiates via rapid-revisit analytics that compress decision cycles for military and commercial monitoring clients.
Commercial satellite imagery denotes Earth observation data captured by privately operated spacecraft and distributed under license for non-governmental applications, typically spanning spatial resolutions from 30 centimeters to 30 meters depending on sensor modality and orbital altitude. Synthetic aperture radar and hyperspectral instruments penetrate cloud cover and atmospheric interference, enabling all-weather surveillance for maritime route monitoring and mineral exploration. The imagery type dimension shows optical products occupying the largest revenue share while radar segments attract the fastest growth from defense and insurance underwriting demand. Within deployment mode, cloud-based architectures dominate new contract flow as hyperscale providers integrate satellite feeds into enterprise GIS platforms, though edge computing deployments are gaining traction for latency-sensitive disaster response coordination.
The US National Oceanic and Atmospheric Administration administers commercial remote sensing licensing under the Land Remote Sensing Policy Act, while the EU Space Programme and its Copernicus data policy shape European market access terms for proprietary imagery providers. Japan's Cabinet Office space policy and METI guidelines influence domestic operator certification and foreign data resale permissions. Stakeholders must monitor evolving national security export controls and data sovereignty mandates that increasingly restrict cross-border imagery transfer for sensitive geographies.
Market Dynamics
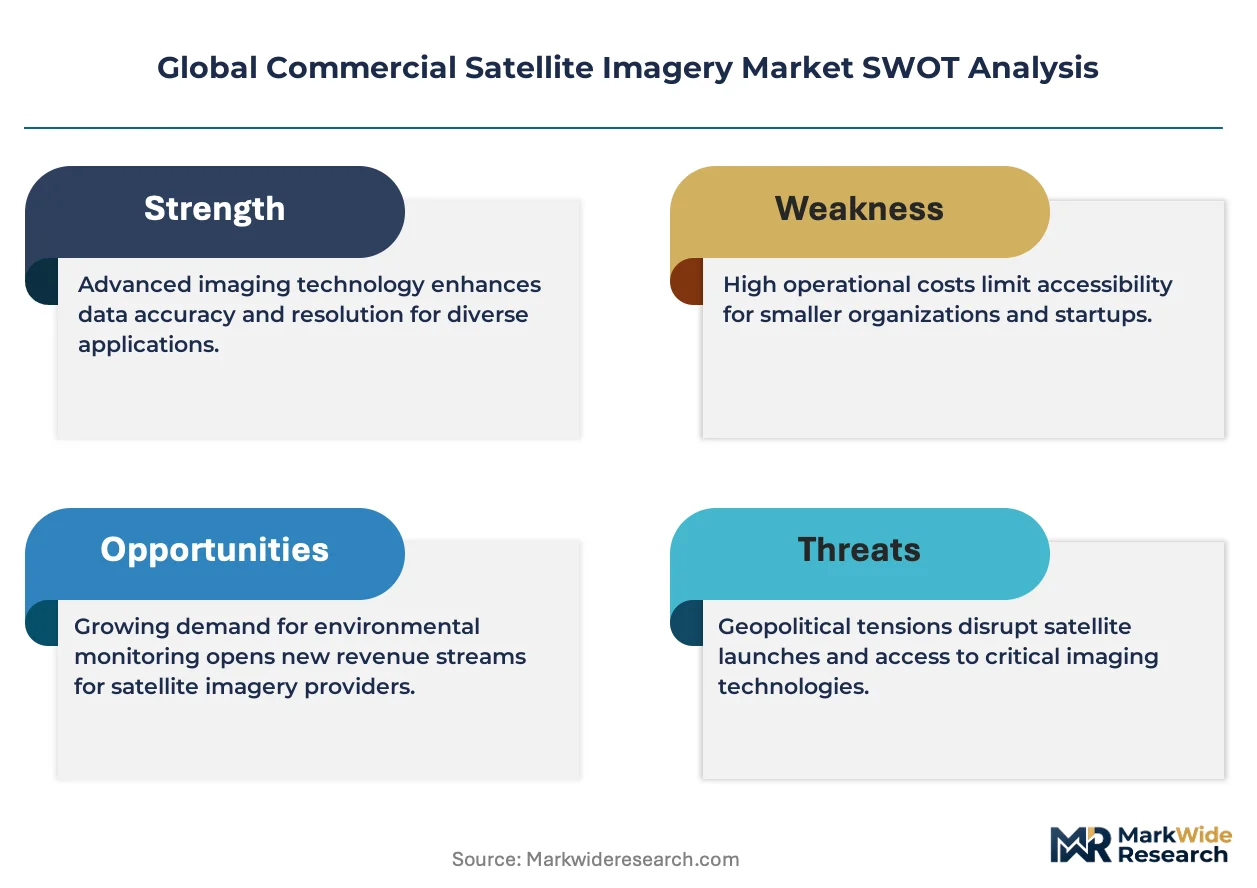
Modular tasking packages are compressing procurement cycles for defense and intelligence buyers, forcing satellite operators to restructure service delivery around mission-specific duration and resolution tiers rather than traditional annual subscriptions.
Growth Catalysts
- EU Space Programme acceleration:Copernicus data policy reforms are expanding procurement pathways for proprietary imagery providers serving agricultural monitoring and climate analytics.
- Cloud-native analytics convergence:Hyperscale providers are embedding satellite feeds directly into enterprise GIS platforms, reducing integration friction for insurance and logistics clients.
- Japan's sovereign capability expansion:METI guidelines and Cabinet Office space policy are stimulating domestic operator certification and foreign data resale permissions.
Market Restraints
- Launch capacity bottlenecks:Reliance on limited heavy-lift providers concentrates deployment schedules and inflates constellation refresh costs.
- NOAA licensing friction:US Land Remote Sensing Policy Act compliance timelines extend market entry by 18-24 months for foreign operators.
- Synthetic aperture radar skill scarcity:Interpretation of SAR data requires specialized geospatial analysts, constraining adoption outside defense and maritime surveillance.
Strategic Opportunities
- India's downstream analytics gap:ISRO's satellite data democratization policies create entry points for foreign analytics firms serving precision agriculture and urban planning.
- Hyperspectral-mineral exploration convergence:Unmapped spectral signatures for rare earth deposits offer first-mover positioning in resource extraction verticals.
- Edge computing for disaster response:Onboard processing architectures enable latency-sensitive coordination for emergency management agencies.
Industry Challenges
- ITAR-controlled component sourcing:US export restrictions on focal plane arrays and encryption modules complicate supply chain diversification.
- Cross-border data sovereignty mandates:National security classifications increasingly restrict imagery transfer for sensitive geographies, fragmenting global service architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Satellite Imagery Market |
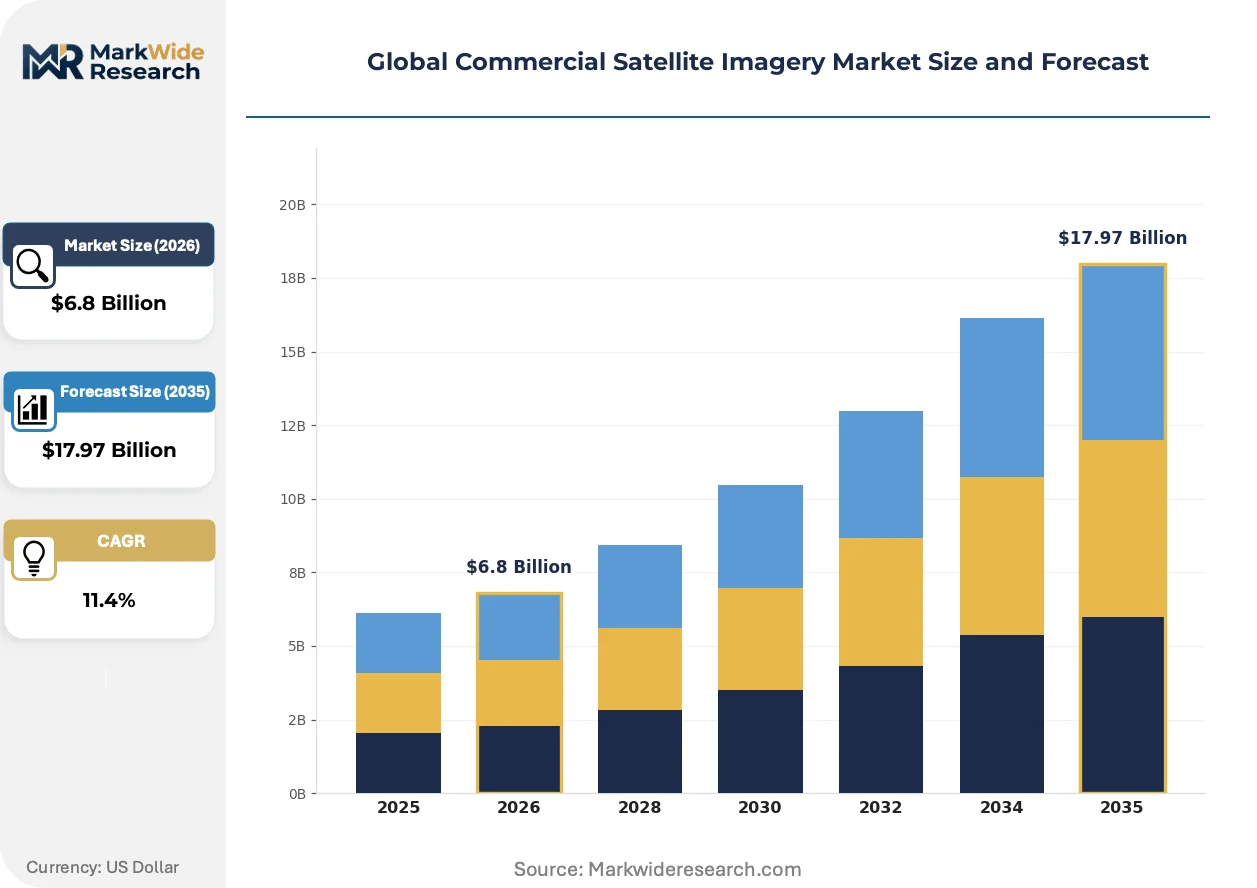
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Imagery Type: Optical, Radar, Hyperspectral, Multispectral, Thermal End Use Industry: Agriculture, Urban Planning, Environmental Monitoring, Maritime Surveillance, Disaster Management Deployment Mode: Cloud-based, On-premise, Hybrid, Edge Computing Service Offering: Data Analytics, Image Processing, Real-time Monitoring, Historical Data Access, Custom Mapping |
| Companies Covered | 21AT, Capella Space, Maxar Technologies, Umbra, Satellogic, Planet Labs, BlackSky, ICEYE, Airbus Defence and Space, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Satellite Imagery Market Shifts & Advancements
Artificial intelligence inference at the sensor edge is collapsing the latency between image capture and actionable intelligence, reshaping competitive positioning around real-time delivery rather than archival access.
Synthetic aperture radar processors are integrating onboard machine learning classification to filter cloud-obscured frames before downlink. Maritime surveillance agencies and agricultural insurers are adopting these capabilities fastest, compressing decision cycles from hours to minutes for route optimization and crop stress detection.
NOAA's streamlined commercial remote sensing licensing pathways under the Land Remote Sensing Policy Act are reducing approval timelines for new sensor modalities. This regulatory recalibration is accelerating polarimetric and interferometric SAR deployments, with defense contractors and climate research consortia capturing first-mover advantages in all-weather monitoring.
Defense procurement officers are unbundling satellite tasking from analytics services, creating spot-market liquidity for raw imagery. This purchasing pattern shift is displacing long-term exclusive access contracts, with Germany's BSI and Japan's Cabinet Office piloting usage-based frameworks that reward revisit frequency over archive depth.
Global Commercial Satellite Imagery Market Segmentation
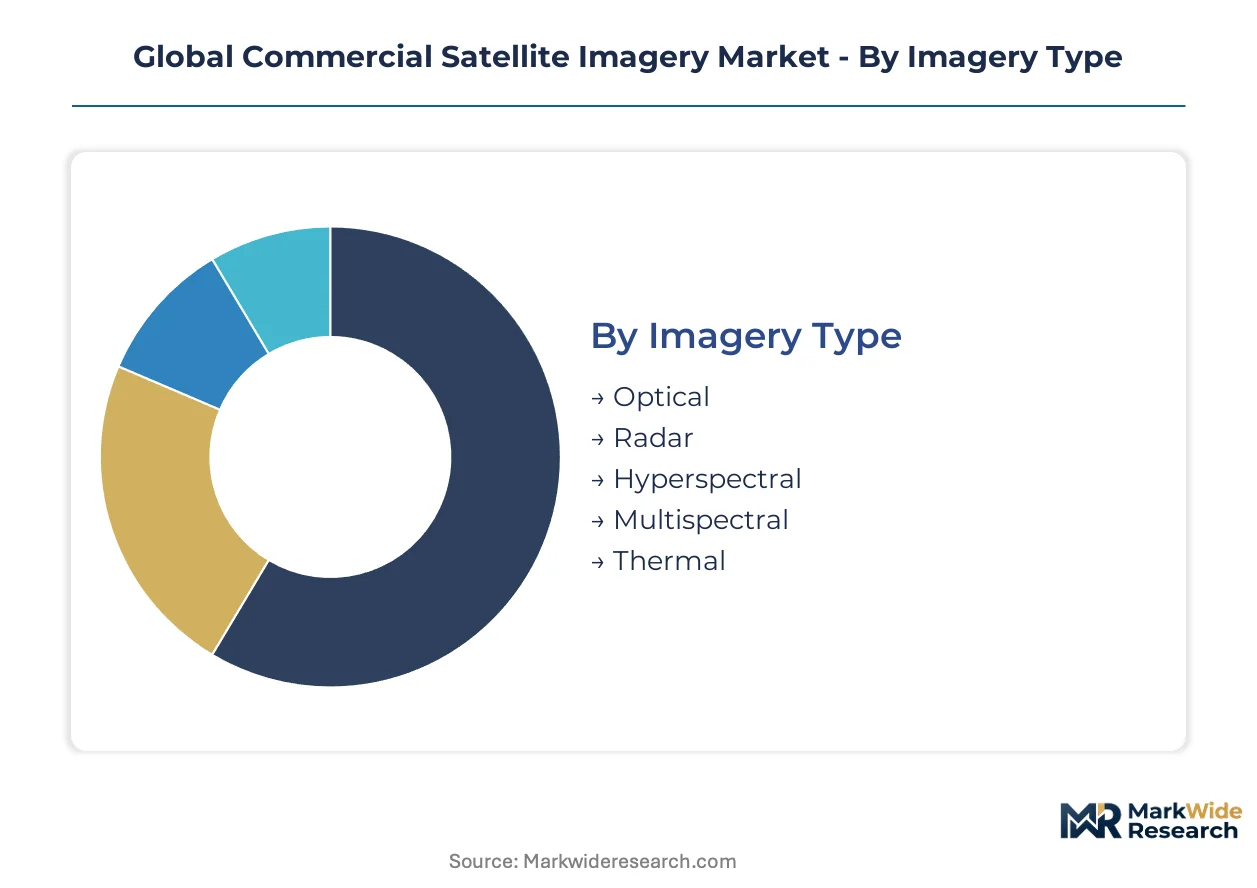
Segmentation in commercial satellite imagery determines procurement pathways, pricing tiers, and regulatory compliance burdens. Resolution specifications and sensor modalities dictate whether buyers qualify for standard commercial licenses or restricted national security frameworks.
Imagery Type:
NOAA licensing under the Land Remote Sensing Policy Act imposes tiered restrictions based on spatial resolution and sensor technology, with sub-meter optical and advanced radar modalities facing extended approval timelines.
- Optical:Electro-optical sensors capture reflected visible and near-infrared light at resolutions reaching 30 centimeters. Defense agencies in the United States and agricultural technology firms in Germany concentrate procurement here, driven by intuitive interpretation and established analytics pipelines.
- Radar:Synthetic aperture radar penetrates cloud cover and operates independent of solar illumination, enabling all-weather surveillance. Maritime route monitoring agencies and insurance underwriters in Japan prioritize this modality for its reliability in high-latitude and tropical environments.
- Hyperspectral:Hundreds of narrow spectral bands enable material identification and mineral exploration. Rare earth deposit mapping in uncharted territories drives specialized demand.
- Multispectral:Broader spectral bands than hyperspectral support vegetation health monitoring and land cover classification. Agricultural cooperatives leverage this for crop yield forecasting.
- Thermal:Infrared sensors detect heat signatures for industrial facility monitoring and wildfire detection. Energy infrastructure operators deploy this for pipeline surveillance.
Optical sits at the top of the volume ranking, with Radar climbing the fastest.
End Use Industry:
Customer sophistication and budget scale vary dramatically across verticals, with defense and intelligence buyers commanding premium tasking priority while municipal governments negotiate usage-based frameworks.
- Agriculture:Precision farming operations subscribe to seasonal coverage packages for crop health monitoring and yield optimization. German agricultural technology firms and Indian farming cooperatives represent expanding demand centers.
- Urban Planning:Municipal governments and real estate developers require cadastral mapping and infrastructure change detection. Japanese metropolitan authorities lead adoption of high-frequency revisit services.
- Environmental Monitoring:Climate research consortia and carbon credit verification bodies track deforestation, glacial retreat, and wetland degradation. EU Space Programme funding accelerates procurement in this vertical.
- Maritime Surveillance:Coast guards and fisheries enforcement agencies monitor exclusive economic zones for illegal fishing and smuggling. All-weather radar capability is non-negotiable here.
- Disaster Management:Emergency response agencies require rapid tasking activation for flood, earthquake, and wildfire damage assessment. Edge computing deployments are gaining traction for latency-sensitive coordination.
Agriculture commands the largest contract value, with Disaster Management expanding most quickly.
Deployment Mode:
Architecture choices determine integration complexity, data sovereignty compliance, and latency performance for time-critical applications.
- Cloud-based:Hyperscale providers embed satellite feeds directly into enterprise GIS platforms, reducing integration friction. Insurance and logistics clients in the United States and Germany dominate this segment.
- On-premise:Sensitive government installations and classified defense programs mandate air-gapped infrastructure for imagery processing and storage. Compliance with national security export controls drives this preference.
- Hybrid:Organizations partition workloads between cloud analytics and local archival, balancing computational flexibility with data residency requirements. Japanese operators favor this for Cabinet Office policy alignment.
- Edge Computing:Onboard processing architectures enable latency-sensitive coordination for emergency management agencies. Disaster response teams in disaster-prone geographies pilot these deployments.
Cloud-based captures the dominant share, with Edge Computing gaining share fastest.
Service Offering:
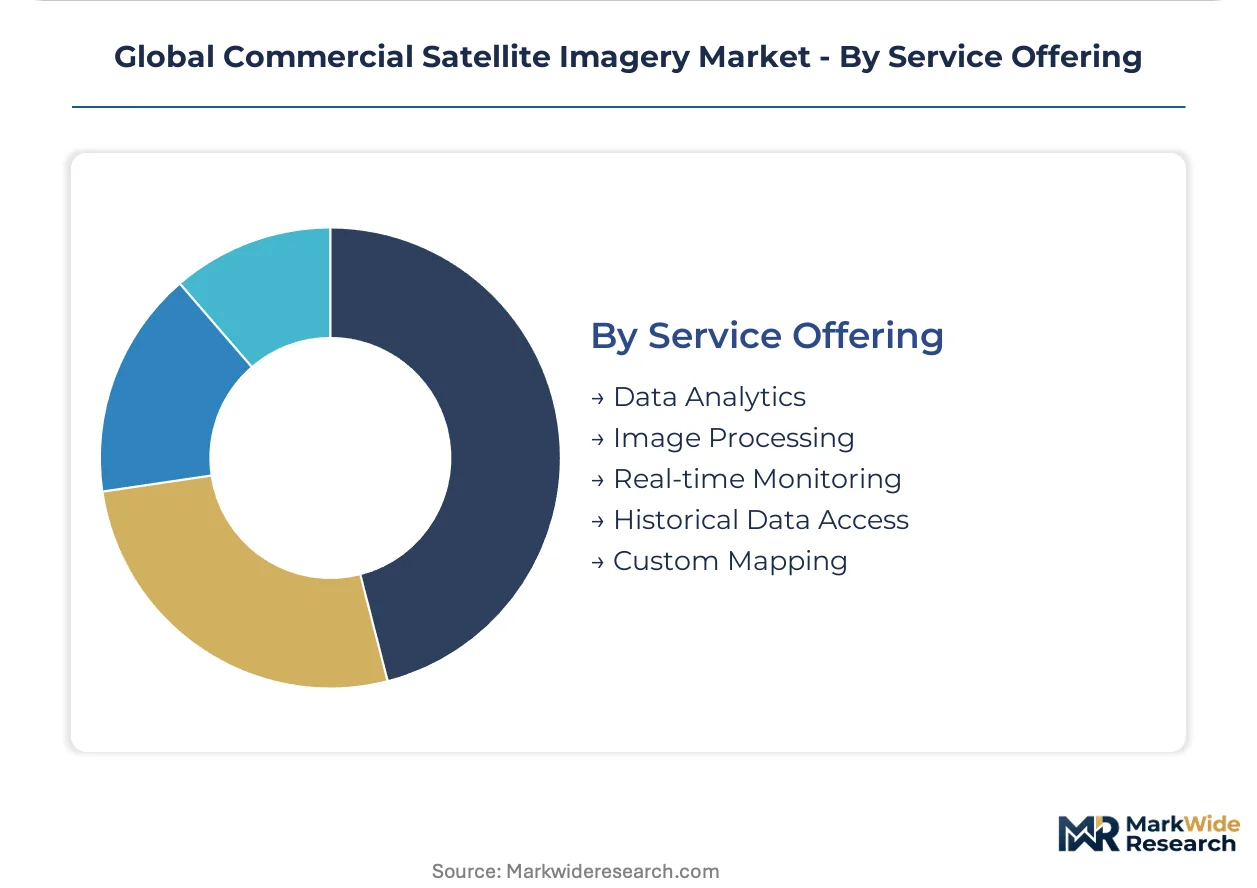
Service unbundling is reshaping vendor-client relationships, with defense procurement officers separating raw imagery acquisition from value-added analytics.
- Data Analytics:Machine learning classification and change detection algorithms transform raw pixels into actionable intelligence. Agricultural insurers and commodity traders drive subscription growth.
- Image Processing:Orthorectification, atmospheric correction, and pan-sharpening prepare imagery for downstream integration. GIS professionals and mapping agencies require these services.
- Real-time Monitoring:Rapid-revisit tasking with sub-hourly delivery compresses decision cycles for military and commercial monitoring clients. Border security and critical infrastructure protection programs prioritize this capability.
- Historical Data Access:Archive depth enables temporal analysis and baseline establishment for environmental and urban studies. Climate researchers and legal dispute resolution teams access decades of accumulated imagery.
- Custom Mapping:Bespoke cartographic products and specialized feature extraction serve unique project requirements. Engineering consultancies and legal surveyors commission these services.
Data Analytics leads contract value, with Real-time Monitoring showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial satellite imagery traces its commercial lineage to United States defense contracting origins, with early private sector scaling emerging from NASA technology transfer programs and NOAA licensing frameworks established under the Land Remote Sensing Policy Act.
United States
Defense procurement officers and agricultural technology firms drive sustained demand for sub-meter optical and radar products. NOAA administers commercial remote sensing licensing under the Land Remote Sensing Policy Act, with recent reforms compressing approval timelines for new sensor modalities. The Washington D.C.-Northern Virginia corridor hosts concentrated federal contracting activity, while California's aerospace clusters anchor commercial constellation operations.
Germany
Agricultural technology firms and municipal governments expand procurement of high-resolution Earth observation data for precision farming and urban planning applications. The EU Space Programme and Copernicus data policy shape market access terms, expanding procurement pathways for proprietary imagery providers. Bavaria and Baden-Württemberg host dense clusters of geospatial analytics firms serving European agricultural cooperatives.
Japan
Maritime surveillance agencies and disaster management authorities prioritize all-weather radar capabilities for exclusive economic zone monitoring and emergency response coordination. METI guidelines and Cabinet Office space policy stimulate domestic operator certification and foreign data resale permissions. Tokyo and Osaka metropolitan authorities lead adoption of high-frequency revisit services for infrastructure change detection.
India
Precision agriculture cooperatives and urban planning authorities access satellite data through ISRO's democratization policies, creating entry points for foreign analytics firms. The country's national space regulator oversees commercial remote sensing data distribution permissions. Karnataka's Bangalore cluster and Maharashtra's Mumbai-Pune corridor concentrate downstream analytics and GIS service providers.
United Kingdom
Climate research consortia and insurance underwriters drive demand for historical archive depth and real-time monitoring capabilities. Post-Brexit regulatory frameworks continue aligning with EU Space Programme data policies while establishing independent licensing pathways. London's financial services sector integrates satellite-derived risk analytics into commodity trading and agricultural insurance underwriting.
Global Commercial Satellite Imagery Market Competitive Landscape
The competitive structure tilts toward constellation-scale operators with established government relationships. Market concentration reflects substantial capital requirements for orbital deployment and regulatory compliance timelines that extend 18-24 months for new entrants. Two strategic archetypes dominate: legacy operators with geostationary and polar orbit assets sustaining long-term defense contracts, and agile newcomers deploying rapid-revisit small satellite constellations. Competitive moves center on unbundling raw imagery from analytics services and forming cloud-native partnerships with hyperscale providers.
Within the established operator tier, Maxar Technologies and Airbus Defence and Space exemplify legacy infrastructure advantages, while Planet Labs and BlackSky represent rapid-revisit constellation strategies. Maxar Technologies occupies a position anchored in geostationary and polar orbit assets, Planet Labs exemplifies daily coverage capabilities through distributed small satellite architectures, and BlackSky sits within the rapid-revisit analytics segment compressing decision cycles for defense and commercial monitoring clients.
| Leading Market Players |
|---|
| 21AT |
| Capella Space |
| Maxar Technologies |
| Umbra |
| Satellogic |
| Planet Labs |
| BlackSky |
| ICEYE |
| Airbus Defence and Space |
| Others |
Supply & Pricing Matrix
Defense procurement officers and agricultural technology firms dominate contract flow, anchoring pricing power around mission-specific duration tiers rather than traditional annual subscriptions. This buyer concentration compresses margins for small satellite operators while rewarding constellation-scale incumbents with tasking priority premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by resolution grade and revisit frequency. Premium tiers command priority tasking for sub-meter optical and advanced radar modalities, while standard tiers serve agricultural monitoring with 1-5 meter products. Price differentiation hinges on NOAA licensing compliance timelines and cloud-native analytics bundling. Cost compression in economy tiers is intensifying because ISRO's data democratization policies flood India with subsidized alternatives. Municipal governments and precision farming cooperatives exhibit highest price sensitivity; defense intelligence buyers show least.
Supply Chain Analysis
NOAA licensing under the Land Remote Sensing Policy Act and EU Space Programme certification requirements gate market entry, extending qualification timelines 18-24 months for foreign operators. Manufacturing concentrates in the United States, Germany, and Japan for focal plane arrays, synthetic aperture radar processors, and encryption modules. Supply chains draw from gallium arsenide substrates, radiation-hardened electronics, and heavy-lift launch capacity. Single-source vulnerability runs through limited qualified launch providers. Distribution runs through direct government contracting, hyperscale cloud partnerships, and specialized geospatial analytics firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where NOAA licensing friction in the United States creates 18-24 month entry delays that Indian and European operators exploit through faster domestic certification pathways.
For Market Incumbents: To counter rapid-revisit constellation entrants like Planet Labs and BlackSky, Maxar Technologies and Airbus Defence and Space should deepen exclusive government relationships through polar orbit asset expansion and accelerate cloud-native analytics partnerships with hyperscale providers. Backward integration into focal plane array production reduces ITAR-controlled component exposure. For New Entrants and Emerging Players: The premium-to-economy price-point gap in real-time monitoring services creates entry space for mid-tier operators. India's downstream analytics gap offers the most penetrable geography, where ISRO data policies enable foreign analytics firms to serve precision agriculture without sovereign satellite investment. A channel partnership strategy with German agricultural technology clusters accelerates credential building. For Investors and Strategic Acquirers: Defense contractors are the most active acquirer in this space, seeking rapid-revisit capabilities and AI-at-the-edge processing. Long-term viability centers on constellation refresh economics and government relationship durability rather than pure technology differentiation. Acquisition targets should display established NOAA licensing pathways and recurring defense revenue. The signal to watch is modular tasking package adoption rates by Germany's BSI and Japan's Cabinet Office.| Strategic Initiative | Industry Significance |
|---|---|
| Constellation Refresh Acceleration | Shortens revisit cycles for defense buyers competing with BlackSky's rapid-revisit analytics. |
| Cloud-Native Platform Integration | Embeds satellite feeds into AWS and Azure GIS stacks for insurance and logistics clients. |
| Edge Computing Architecture Deployment | Enables latency-sensitive disaster response coordination for Japanese emergency management agencies. |
| Hyperspectral Sensor Modality Expansion | Captures first-mover positioning in rare earth mineral exploration verticals. |
| Regulatory Licensing Pathway Streamlining | Compresses NOAA approval timelines under Land Remote Sensing Policy Act reforms. |
Research Methodology
Direct dialogue with satellite operators, defense procurement officers, agricultural technology firm executives, and geospatial analytics specialists grounded the qualitative assessment. Secondary validation drew from NOAA commercial remote sensing license filings, EU Space Programme procurement disclosures, METI policy guidelines, and ISRO data distribution records. Bottom-up and top-down triangulation reconciled constellation deployment schedules with downstream demand segmentation.
Bottom-up modeling built forecasts from individual operator capacity, licensing timelines, and end-use vertical penetration rates across the analysis window. Segmentation dimensions included imagery type, deployment mode, service offering, and end-use industry. CAGRs derived from orbital asset deployment trajectories and defense budget allocation patterns. Industry-specific inputs incorporated heavy-lift launch capacity constraints and synthetic aperture radar skill scarcity.
Caveats apply where launch capacity bottlenecks, ITAR export control expansion, or cross-border data sovereignty mandates could materially shift the outlook. Forecasts reflect assumptions around NOAA licensing reform continuity and EU Copernicus data policy stability. A model refresh is warranted upon material change in defense procurement unbundling velocity or edge computing adoption for disaster response.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Germany Satellite-Based Earth Observation Market
Satellite
North America Satellite Manufacturing Market
Satellite
Global Satellite Based Earth Observation Market
Satellite
Satellite Communications Service Market
Satellite
Sudan Satellite Transponder Market
Satellite
Italy Satellite Imagery Services Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
Spain Satellite-Based Earth Observation Market
Satellite
Europe Satellite Bus Market
Satellite
India Satellite Connectivity Market
Satellite
Fixed Satellite Services (FSS) Market
Satellite
Earth Observation Satellite Market
Satellite
Satellite Payload Market
Satellite
Optical Satellite Communication Market
Satellite
Aviation Satellite Antenna Systems Market
Satellite
Satellite Imaging Market