
 Aircraft Engine Market | 2026-2036
Aircraft Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Engine Market Intelligence
The performance gap between next-generation high-bypass turbofan engines and legacy turbojet systems is restructuring the competitive landscape. General Electric Company leverages its extensive research in ceramic matrix composites to gain an efficiency advantage in its platforms. Pratt & Whitney specializes in geared turbofan (GTF) technology, particularly for single-aisle aircraft. Safran SA competes through its joint venture, CFM International, which occupies a dominant position in the narrow-body segment.
An aircraft engine is a propulsion system that generates mechanical power and thrust by combusting fuel and air to propel an aircraft. Key performance metrics include bypass ratio and specific fuel consumption, which directly determine operational efficiency and flight range. The turbofan engine type commands the market, driven by its widespread adoption in commercial aviation for its fuel economy. In contrast, piston engines continue to serve a foundational role in the general aviation training and personal aircraft segment.
Regulatory oversight from bodies like the FAA in the United States and adherence to directives under the EU Green Deal are non-negotiable for market access. These regulations enforce strict limits on noise pollution and emissions such as NOx and CO2, compelling manufacturers to invest in cleaner combustion technologies. The central strategic decision for incumbents is how to allocate capital between optimizing current jet fuel-based architectures and developing disruptive hydrogen or hybrid-electric propulsion systems.
Market Dynamics
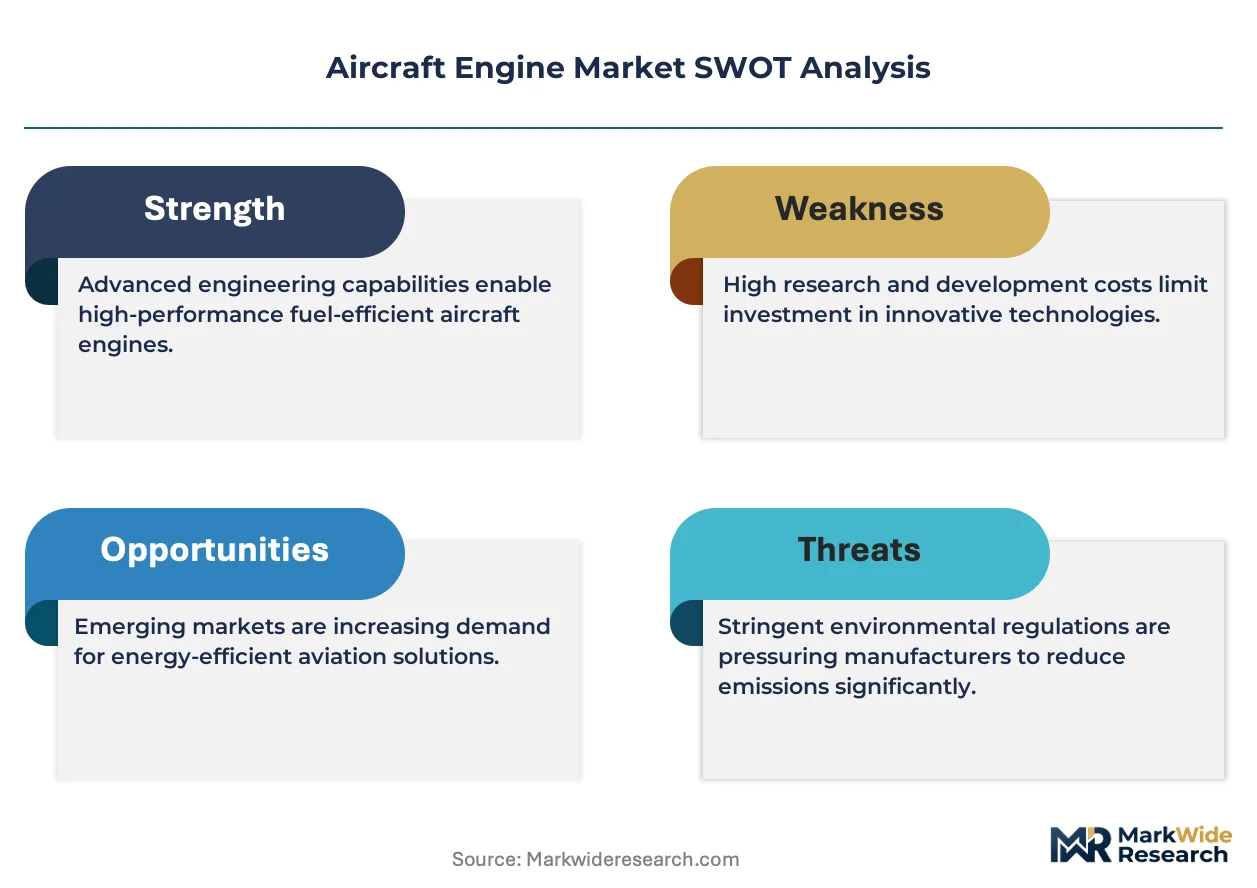
The central dynamic is the capital allocation conflict between optimizing mature turbofan architectures and investing in disruptive hydrogen or hybrid-electric propulsion. This decision is driven by intense pressure to meet future decarbonization mandates from regulators like the EASA and FAA.
Growth Catalysts
- Sustainable Aviation Fuels (SAF):Mandates under frameworks like the EU Green Deal are compelling the development and certification of engines fully compatible with SAF, creating a distinct technological pathway for next-generation turbofans.
- Fleet Renewal Cycles:Commercial airline demand in the United States and Asia for new narrow-body aircraft accelerates the replacement of older engines with modern high-bypass turbofans to improve fuel economy.
- Stringent Emissions Standards:Regulations limiting NOx and noise pollution, enforced by bodies such as the FAA, push manufacturers to innovate in combustor design and acoustic liner technology, stimulating R&D investment.
Market Restraints
- Material Supply Concentration:The supply chain for inputs like titanium and nickel superalloys is highly concentrated in a few regions, creating vulnerability to trade disruptions and price volatility for all major manufacturers.
- Extreme R&D Costs:The immense capital investment and multi-year timelines required to develop, test, and certify a new engine platform under bodies like EASA represent a formidable barrier to entry and slow the pace of radical innovation.
- Thermal Efficiency Limits:Current-generation nickel-based superalloys are approaching their theoretical performance limits, restricting further significant improvements in thermodynamic efficiency without a shift to new material sciences like CMCs.
Strategic Opportunities
- Hybrid-Electric Propulsion:Developing hybrid-electric powertrains for regional and short-haul aircraft presents a significant opportunity to address a segment where battery technology limitations are less prohibitive than in long-haul aviation.
- Urban Air Mobility (UAM):The emerging UAM sector requires novel, lightweight, and efficient propulsion systems, creating a new market segment for smaller-scale electric motors and compact turbine-based generators.
- Predictive Maintenance Services:Expanding data-driven services using onboard sensor analytics offers new revenue. This optimizes MRO scheduling and improves asset utilization for airlines globally.
Industry Challenges
- Specialized Talent Scarcity:A shortage of aerospace engineers and technicians with expertise in advanced materials, such as ceramic matrix composites, and in digital twin modeling, constrains development and production capacity.
- Certification of Novel Systems:Securing airworthiness certification for disruptive technologies like hydrogen combustion is a major hurdle, as existing regulatory frameworks were not designed for these architectures.
- Manufacturing Retooling:The high capital expenditure needed to reconfigure production lines and supply chains for new engine architectures and advanced materials poses a significant financial challenge for incumbents and suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Engine Market |
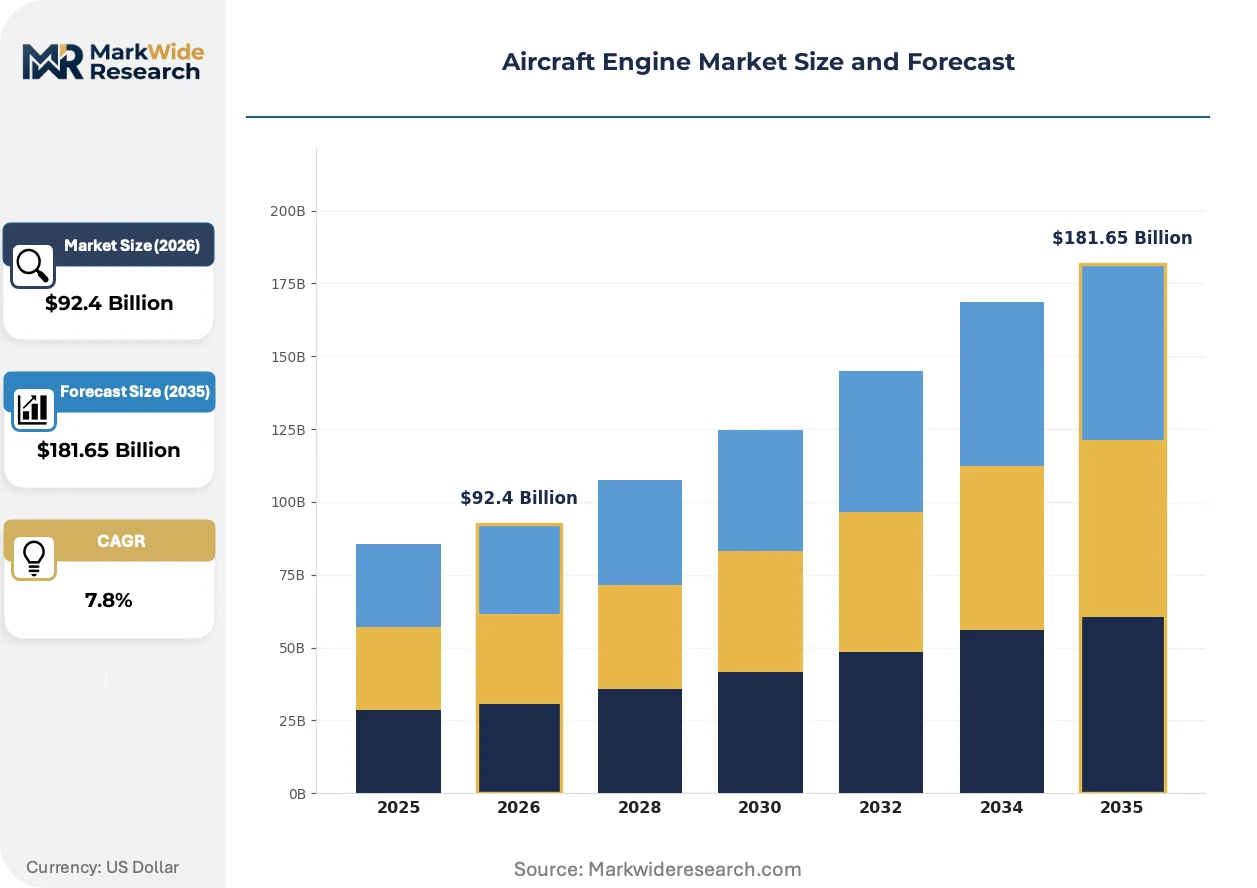
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $181.65 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Engine Type: Turbofan, Turboprop, Turbojet, Piston Application: Commercial Aviation, Military Aviation, General Aviation, Unmanned Aerial Vehicles Fuel Type: Jet A, Avgas, Biofuel, Synthetic Fuel End User: Airlines, Aircraft Manufacturers, Maintenance Providers, Military |
| Companies Covered | General Electric Company, Pratt & Whitney, Rolls-Royce Holdings, Safran SA, CFM International, Honeywell International, MTU Aero Engines, GE Aerospace, Textron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Engine Market Strategic Shifts & Innovations
Dual pressures from decarbonization mandates and the pursuit of operational efficiency are reshaping the aircraft engine market. This fosters both incremental improvements to existing turbofans and development of radical new propulsion concepts.
Digital twin technology creates a high-fidelity virtual replica of a physical engine in operation. MRO providers and major airlines are adopting this technology to monitor engine health and performance in real-time. The virtual model is converging with live sensor data to enable predictive maintenance, reducing unplanned downtime.
The European Union's ReFuelEU Aviation initiative mandates escalating shares of Sustainable Aviation Fuels (SAF) for flights departing from EU airports. This policy forces manufacturers to accelerate certification of engines to run on higher SAF blends. The commercial aviation segment is most affected, with SAF-readiness now a key marketing feature.
Airlines are increasingly shifting from outright engine purchases to comprehensive 'power-by-the-hour' service agreements. This model transfers operational and maintenance risk from the airline to the engine original equipment manufacturer. This trend is most prominent in the global narrow-body and wide-body commercial aircraft segments.
Aircraft Engine Market Segmentation
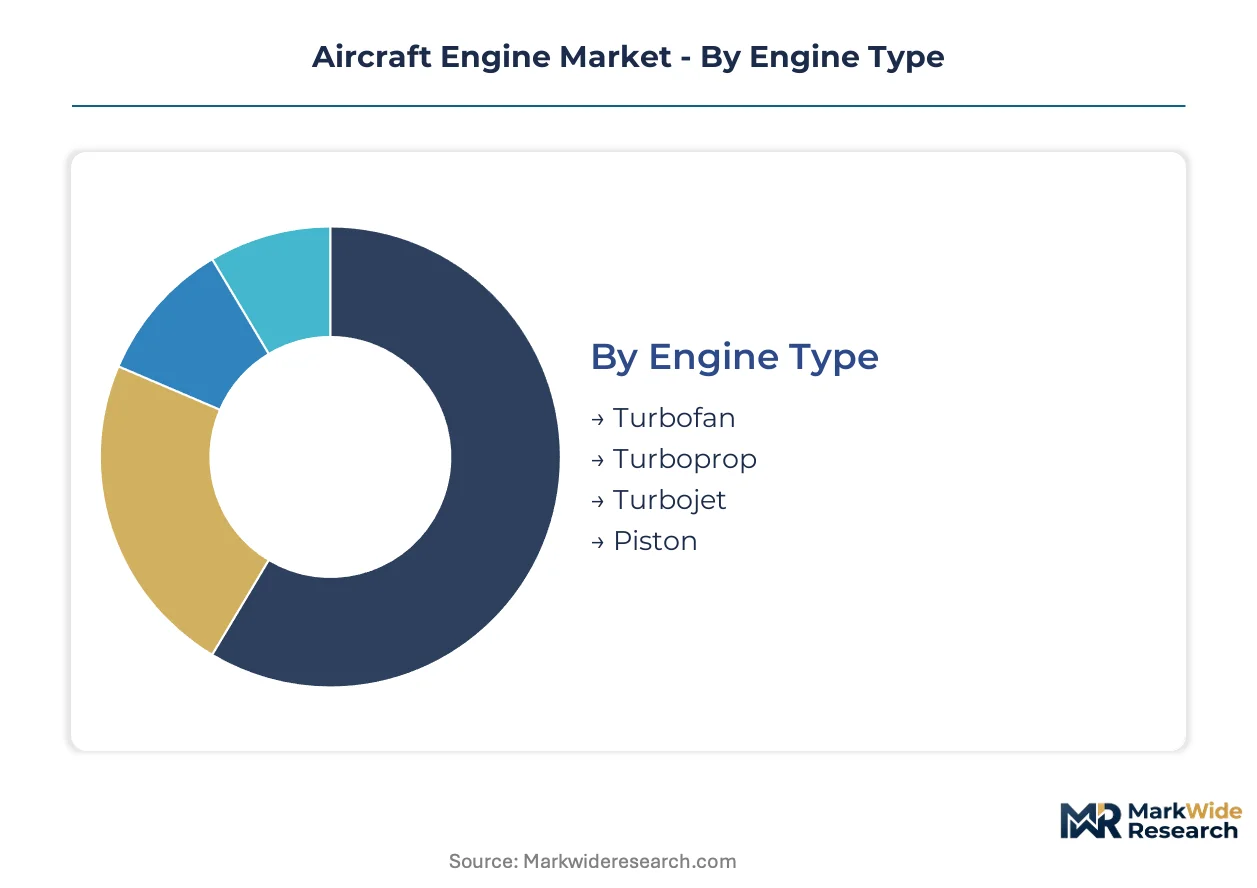
Understanding the distinct segments within the aircraft engine market is crucial for assessing technological shifts and investment priorities. Each category presents unique demand drivers, regulatory influences, and competitive dynamics shaping the industry's trajectory.
Engine Type:
The ongoing fleet renewal cycles across commercial aviation directly influence the demand for specific engine types, driving upgrades to more efficient propulsion systems.
- Turbofan:This engine type features a large fan at the front, bypassing a significant portion of air around the core for thrust, resulting in high bypass ratios and superior fuel efficiency. Commercial aviation's demand for new narrow-body aircraft largely drives the segment, emphasizing operational cost reduction.
- Turboprop:Turboprop engines use a gas turbine to drive a propeller, providing efficient thrust at lower speeds and altitudes, making them suitable for regional and utility aircraft. Demand concentrates in regional airline fleets and cargo operations, where their short-field performance is advantageous.
- Turbojet:Turbojet engines produce thrust solely from the exhaust gases, offering high speed capability but lower fuel efficiency compared to turbofans, primarily serving older military aircraft.
- Piston:Piston engines convert reciprocating motion into rotational power to drive a propeller, remaining foundational for general aviation training and personal aircraft due to their simplicity and cost-effectiveness.
Turbofan engines sit at the top of the volume ranking, with turboprop systems climbing the fastest in regional and utility aircraft applications.
Application:
The diverse operational requirements across various aviation applications dictate the specific engine performance characteristics and certification pathways.
- Commercial Aviation:This segment covers engines for passenger and cargo aircraft operated by airlines, focusing on fuel efficiency, reliability, and reduced emissions to meet strict operational and regulatory standards. Fleet renewal cycles in the United States and Asia are a primary driver for new engine demand.
- Military Aviation:Engines in this application power combat, transport, and surveillance aircraft for defense forces, prioritizing thrust-to-weight ratio, durability in harsh conditions, and stealth capabilities. Government defense budgets and geopolitical considerations heavily influence procurement decisions.
- General Aviation:General aviation includes engines for private planes, business jets, and training aircraft, emphasizing reliability, lower operational costs, and ease of maintenance for individual owners and flight schools.
- Unmanned Aerial Vehicles:This application requires lightweight, compact, and often electric or hybrid propulsion systems for drones and remotely piloted aircraft, driven by surveillance, logistics, and emerging urban air mobility needs.
Commercial aviation applications represent the largest segment by installed base, while Unmanned Aerial Vehicles demand specialized lightweight propulsion solutions.
Fuel Type:
The maturity level of various fuel technologies directly impacts their commercial viability and regulatory acceptance within the propulsion market.
- Biofuel:Biofuels are derived from biomass, such as agricultural waste or algae, and offer a pathway to reduce carbon emissions when blended with conventional jet fuel. Regulatory mandates like the EU Green Deal are compelling manufacturers to certify engines for higher biofuel blends.
- Synthetic Fuel:Synthetic fuels are produced through chemical processes, including Power-to-Liquid (PtL) methods, offering a scalable, low-carbon alternative to traditional jet fuel. Investment in this segment is driven by the long-term decarbonization goals of major airlines and aerospace companies.
- Jet A:Jet A is the standard aviation turbine fuel globally, a kerosene-based product that currently powers the vast majority of commercial and military jet aircraft.
- Avgas:Avgas (aviation gasoline) is a leaded fuel primarily used by piston-engine aircraft in general aviation, where its high octane rating is crucial for engine performance.
Jet A remains the dominant fuel type, though Biofuel and Synthetic Fuel are gaining share as decarbonization mandates intensify.
End User:
Different end-user segments exhibit distinct procurement strategies and maintenance requirements for their aircraft engine fleets.
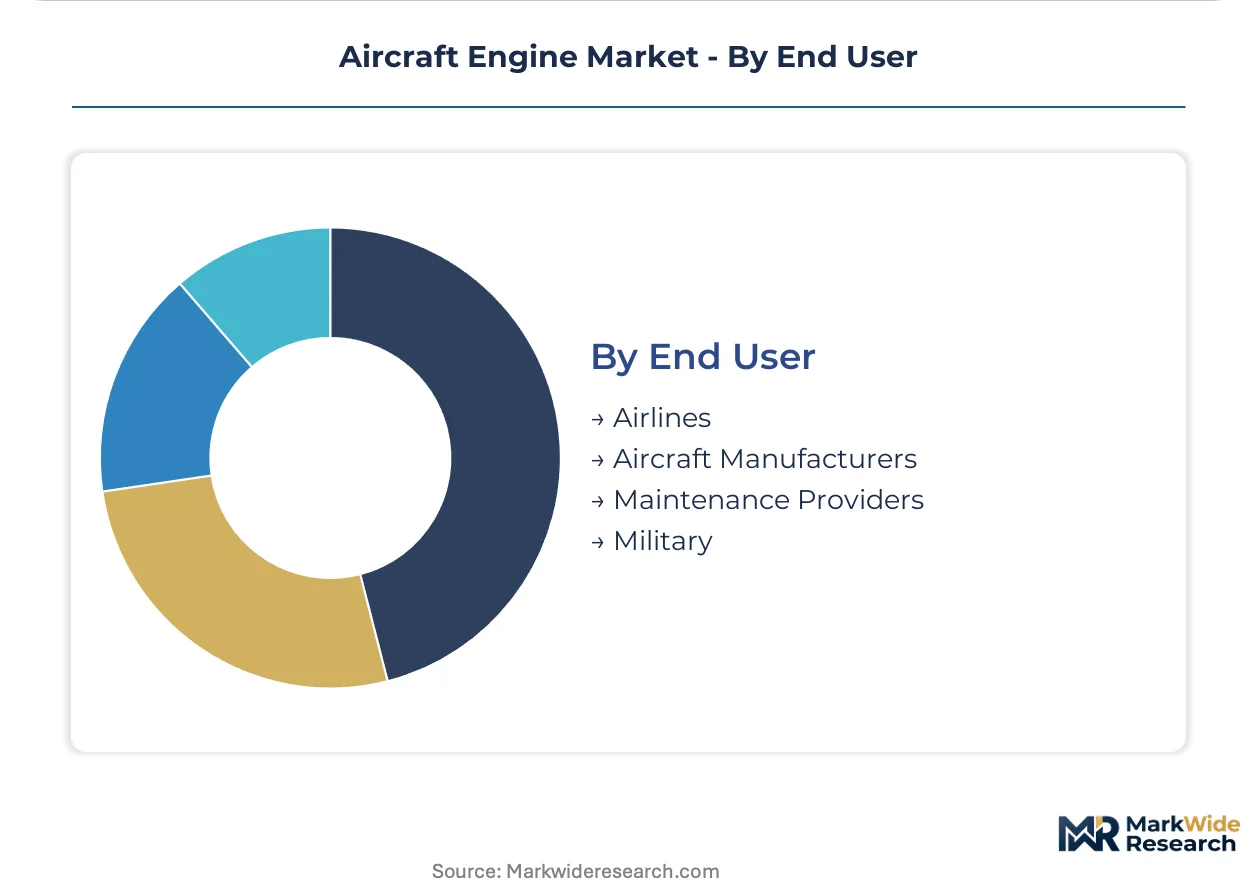
- Airlines:Airlines represent a major end-user segment, procuring engines for their commercial fleets and often entering into long-term maintenance contracts with engine original equipment manufacturers. The focus for airlines is on operational efficiency, reliability, and total cost of ownership.
- Aircraft Manufacturers:These companies integrate engines into new aircraft designs, collaborating closely with engine manufacturers during the development and certification phases. Their demand is tied directly to new aircraft orders and production rates for models like the Airbus A320 and Boeing 737.
- Maintenance Providers:Maintenance providers specialize in the repair, overhaul, and servicing of aircraft engines, offering critical support to airlines and military operators to ensure operational readiness and extend asset life.
- Military:Military end-users acquire engines for defense aircraft through government procurement processes, prioritizing mission-specific performance, durability, and secure supply chains for national security objectives.
Airlines drive significant engine demand through new aircraft orders and MRO contracts, while aircraft manufacturers integrate propulsion systems during initial production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A deep concentration of aerospace engineering talent anchors the aircraft engine market across several key geographies. These regions foster innovation and advanced manufacturing capabilities. Regulatory frameworks also shape market dynamics, driving investment into specific technological pathways.
United States
Demand for new, fuel-efficient engines drives activity in the United States, particularly for commercial aviation fleet renewals. The FAA mandates stringent noise and emissions standards, compelling continuous technological advancement. Major aerospace clusters in Seattle and Wichita house significant engine manufacturing and MRO facilities.
France
Europe's commercial aviation sector fuels strong demand for turbofan engines in France. The EU Green Deal mandates accelerate the development of Sustainable Aviation Fuels compatible propulsion systems. Toulouse, a major aerospace hub, hosts significant design and production operations for engine manufacturers.
Germany
Specialized engineering expertise in Germany supports advanced material research for aircraft engines. EASA certification processes guide the development of new engine platforms and components. Major industrial centers like Munich contribute to the manufacturing of high-precision engine parts.
Japan
Japan's focus on technological precision drives innovation in aircraft engine component manufacturing. METI initiatives support research into next-generation propulsion systems, including hybrid-electric technologies. Nagoya, a central aerospace manufacturing region, integrates advanced materials into engine production.
China
Commercial aviation expansion and defense modernization efforts underpin engine demand in China. The country's dual carbon goals promote investment in cleaner aviation propulsion technologies. Xi'an serves as a significant aerospace industrial base, with extensive engine assembly and testing facilities.
Aircraft Engine Market Key Industry Players
Top-tier vendors anchor the global aircraft engine market, while specialized component suppliers and MRO providers form a critical lower tier. The market structure is highly consolidated, dominated by a few integrated propulsion system manufacturers. Strategic archetypes include full-system integrators, technology specialists, and service-focused entities. Dominant competitive moves involve strategic partnerships for new engine programs and continuous R&D investment in advanced materials.
Full-system integrators such as General Electric Company exemplify the market's consolidated nature, offering comprehensive engine solutions across diverse aircraft platforms and leveraging extensive research in ceramic matrix composites. Pratt & Whitney, an American aerospace manufacturer, occupies a position as a leading innovator in geared turbofan technology, particularly for single-aisle aircraft applications, focusing on improved fuel economy. Safran SA, a French multinational, represents a key player through its joint ventures, anchoring a significant share of the global narrow-body commercial aircraft segment. These firms collectively drive advancements in fuel efficiency, emissions reduction, and the development of Sustainable Aviation Fuels compatibility.
| Leading Market Players |
|---|
| General Electric Company |
| Pratt & Whitney |
| Rolls-Royce Holdings |
| Safran SA |
| CFM International |
| Honeywell International |
| MTU Aero Engines |
| GE Aerospace |
| Textron |
| Others |
Cost & Logistics Intelligence
The EU Green Deal and similar decarbonization mandates gate access to qualified supply and premium-tier pricing for advanced aircraft engines. These regulations compel manufacturers to invest in Sustainable Aviation Fuels (SAF) compatibility and cleaner combustion technologies, influencing material choices and production processes.
Pricing Analysis
Bundled service agreements, particularly 'power-by-the-hour' models, dominate aircraft engine pricing, shifting operational and maintenance risk to engine original equipment manufacturers. Price differentiation stems from superior fuel efficiency and certified SAF compatibility, offering airlines lower operating costs. Regulatory pressure to reduce emissions and noise limits intensifies pricing pressure across the commercial aviation segment. Commercial airlines exhibit the highest price sensitivity, balancing initial acquisition costs with long-term operational expenditures.
Supply Chain Analysis
Logistics and freight costs represent a significant component of the aircraft engine supply chain, influencing the global distribution of specialized components. Supply of critical raw materials like titanium and nickel superalloys concentrates in a few regions, including parts of Russia and China, creating vulnerability. This material concentration poses a structural risk of price volatility and potential trade disruptions for engine manufacturers. Downstream distribution primarily runs through direct sales channels to aircraft manufacturers and airlines, supported by a global network of MRO facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft engine market functions as a stable compounder, driven by continuous commercial aviation fleet renewal cycles globally.
For Market Incumbents: Anticipate continued pressure from decarbonization mandates by accelerating investment in hybrid-electric and hydrogen propulsion research. Secure long-term supply agreements for advanced materials like ceramic matrix composites to mitigate material supply concentration risks. This strategy defends against emerging disruptive technologies and ensures a competitive edge in fuel efficiency.
For New Entrants and Emerging Players: Enter via niche applications such as Urban Air Mobility (UAM) or regional hybrid-electric aircraft, where existing turbofan architectures are less dominant. The most penetrable segment for new propulsion technologies lies in short-haul and regional aviation, where battery weight limitations are less prohibitive. A go-to-market angle focusing on lightweight, compact, and efficient electric or hybrid powertrains will differentiate offerings.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized component suppliers and MRO technology providers, offering attractive entry points into this essential industry. The long-term viability of the aircraft engine market remains robust, anchored by essential air travel and defense needs. Watch for significant breakthroughs and certification milestones in hydrogen or hybrid-electric propulsion systems as key inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| SAF Engine Certification | Accelerates adoption of sustainable fuels, meeting EU Green Deal mandates for airlines. |
| Hybrid-Electric Powertrain Development | Opens new market segments for regional and Urban Air Mobility applications. |
| Advanced Materials R&D | Enhances engine efficiency and durability, particularly with ceramic matrix composites. |
| Predictive Maintenance Platform | Optimizes MRO scheduling and improves asset utilization for global airlines. |
| Global MRO Network Expansion | Strengthens after-sales service and long-term customer relationships worldwide. |
Research Approach
Direct dialogue with engine design engineers, airline procurement managers, MRO specialists, and regulatory compliance officers informed the qualitative grounding of this analysis. This primary research was rigorously validated through secondary sources including FAA and EASA regulatory documents, aerospace industry association reports, company annual reports, and academic research on propulsion systems. The study employed both bottom-up and top-down triangulation to ensure data consistency and accuracy.
The analytical model produced comprehensive volume and value projections across the analysis window. Segmentation dimensions modeled included engine type, application, fuel type, end user, and regional market maturity. Compound annual growth rates were derived from historical trend analysis and future demand drivers, incorporating key industry-specific forecast inputs such as commercial aircraft order backlogs and Sustainable Aviation Fuel production roadmaps.
Inputs from industry reports, regulatory filings, and expert interviews were available through the study window; gaps in emerging technology adoption rates introduce uncertainty bands. Forecasts reflect assumptions concerning technological advancements and regulatory enforcement. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Global Aircraft Engine Testbed Market
Aircraft Engine Systems and Services
Aircraft Lubricant Market
Aircraft Engine Systems and Services
Asia-Pacific Aircraft Engine Market
Aircraft Engine Systems and Services
Commercial Aircraft Engines Market
Aircraft Engine Systems and Services
Gas Turbine Service Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
Gas Turbine Upgrade for Performance Enhancement Market
Aircraft Engine Systems and Services
Commercial Aircraft Gas Turbine Engine Market
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market
Aircraft Engine Systems and Services
Rocket Propulsion Systems Market
Aircraft Engine Systems and Services
Turboprop Engine Market
Aircraft Engine Systems and Services
Aircraft Turbine Engine Market
Aircraft Engine Systems and Services
Piston Engine Aircraft Market
Aircraft Engine Systems and Services
Aircraft Engine Blade Market
Aircraft Engine Systems and Services
Aeroengine Accessory Drive Train Market
Aircraft Engine Systems and Services
Aviation Gas Turbine Market