
 Boiler System Market | 2026-2036
Boiler System Market Size, Share, and Industry Trends Forecast 2026-2036
Boiler System Market Outlook
The gap between premium condensing systems and commodity fire-tube units is repositioning procurement strategies across end-use sectors. Mitsubishi Heavy Industries Ltd leverages its integrated turbine-boiler technology to anchor high-efficiency power generation contracts in Asia. Bosch Industriekessel GmbH competes on modular system architecture that sustains margin pools in European commercial heating. Babcock & Wilcox Enterprises differentiates through supercritical water-tube designs that dominate utility-scale installations in North America.
A boiler system converts fuel or electrical energy into steam or hot water through controlled combustion or resistance heating, operating at pressures ranging from low-pressure residential settings to supercritical conditions exceeding 22 MPa in power generation. Its primary purpose is to deliver reliable thermal energy for space heating, industrial processes, or electricity generation across residential, commercial, and institutional facilities. Water-tube configurations command structural preference in high-capacity industrial and power applications where pressure and output demands exceed fire-tube limits. Condensing technology is expanding fastest among product categories as efficiency mandates tighten operational economics. Combined heat and power systems concentrate margin capture where facilities can monetize both thermal and electrical outputs from single fuel inputs.
The EPA enforces emissions limits under the National Emission Standards for Hazardous Air Pollutants that compel industrial boiler operators to install pollution controls or retire aging units. The EU Green Deal and F-Gas Regulation shape European demand by penalizing carbon-intensive heating and restricting fluorinated greenhouse gases in system components. China's MEE implements dual carbon goals that redirect industrial procurement toward biomass and electric boiler technologies. Stakeholders must monitor how divergent national efficiency timelines reshape equipment replacement cycles and aftermarket service opportunities.
Market Dynamics
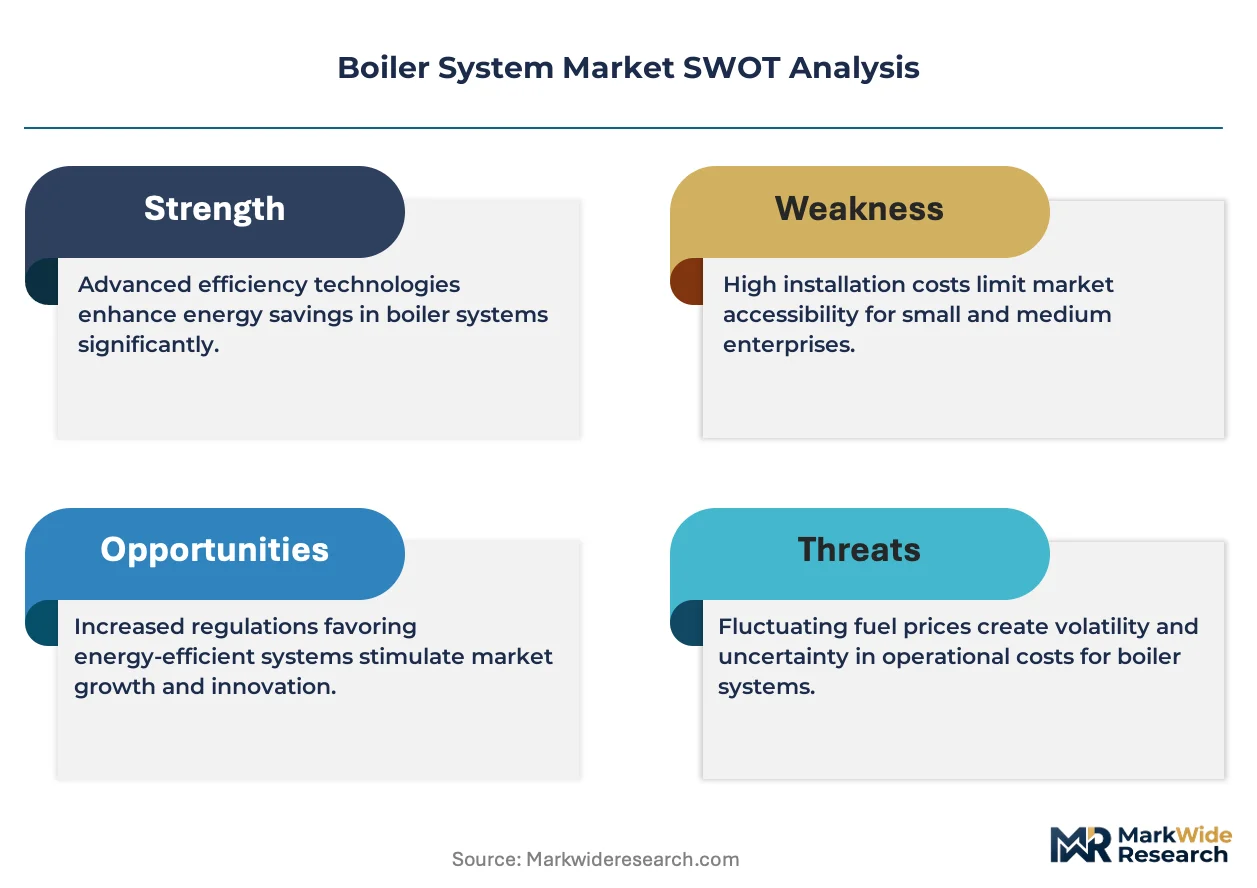
Stringent emissions mandates under the EU Green Deal and EPA National Emission Standards are compressing replacement cycles for aging industrial boiler fleets. Operators face binary decisions between costly retrofit investments and full system replacement with condensing or biomass-fired alternatives.
Growth Catalysts
- Industrial Food Processing:Thermal energy demand from sterilization and pasteurization lines is expanding boiler installations across protein processing and dairy facilities. Steam reliability requirements prevent downtime losses.
- REACH and F-Gas Regulation:European restrictions on fluorinated greenhouse gases in system components are redirecting procurement toward low-GWP refrigerant architectures and electric boiler alternatives.
- Biomass Combustion:Agricultural residue and wood pellet feedstock availability is improving operational economics for carbon-neutral steam generation in Nordic and Baltic district heating networks.
Market Restraints
- Steel and Alloy Input Volatility:Pressure vessel-grade carbon steel and Inconel superalloy price swings compress fabrication margins for water-tube boiler manufacturers.
- Specialized Welding Labor Concentration:Certified ASME Section IX welders cluster in Germany, Japan, and the United States, creating geographic bottlenecks for high-pressure system production.
- Natural Gas Infrastructure Lock-in:Existing pipeline distribution networks in North American commercial buildings delay electric boiler adoption despite efficiency advantages.
Strategic Opportunities
- India Industrial Corridor Expansion:PLI scheme incentives for food processing and textiles are creating greenfield boiler demand in Gujarat and Maharashtra manufacturing zones.
- Heat Pump-Boiler Hybrid Systems:Convergence of vapor compression heat pumps with conventional steam generators enables sub-boiling temperature applications to decarbonize first.
- China Dual Carbon Goals:MEE enforcement of provincial emissions intensity targets is redirecting state-owned enterprise procurement toward biomass cofiring and electric resistance technologies.
Industry Challenges
- ASME BPVC Certification Timelines:Pressure vessel code compliance review periods extend 14-18 months, delaying project commissioning and straining working capital.
- Legacy Control System Integration:Digital twin and predictive maintenance platforms require protocol translation layers to interface with pneumatic and early DCS architectures common in 1980s-era installations.
- Skilled Commissioning Engineer Scarcity:Combustion tuning and safety interlock verification expertise concentrates with retiring technician cohorts, constraining deployment velocity for advanced low-NOx burners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boiler System Market |
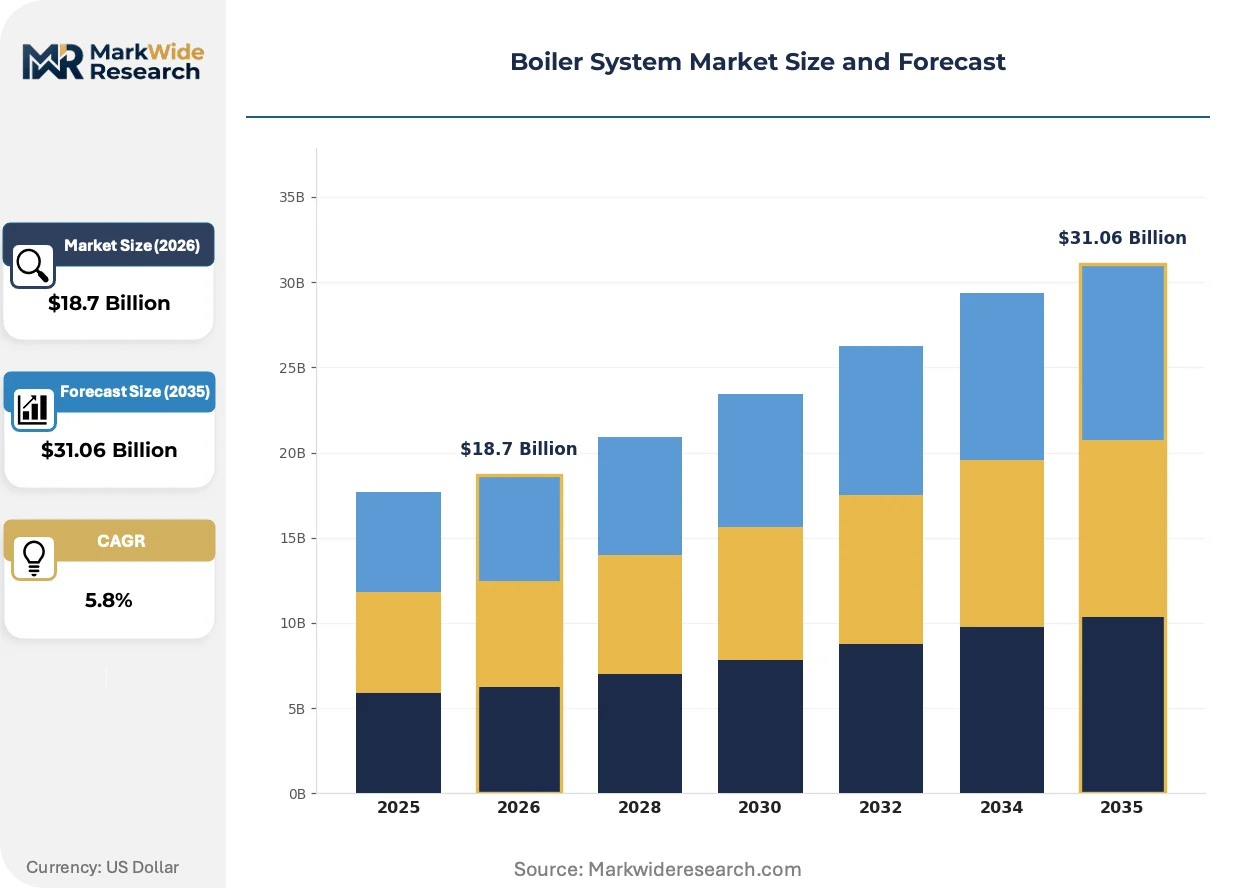
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Tube, Water-Tube, Electric, Condensing Technology: Steam Generation, Hot Water Generation, Combined Heat and Power, Biomass End User: Residential, Commercial, Industrial, Institutional Application: Heating, Power Generation, Food Processing, Chemical Production |
| Companies Covered | Mitsubishi Heavy Industries Ltd, Siemens AG, Babcock & Wilcox Enterprises, Bosch Industriekessel GmbH, Cleaver-Brooks, Thermax Limited, Viessmann Group, IHI Corporation, Hurst Boiler & Welding Company Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boiler System Market Strategic Shifts
Boiler system evolution centers on efficiency architecture redesign, emissions compliance automation, and thermal output flexibility to serve variable renewable electricity grids. These shifts are compressing traditional equipment lifecycles and rewiring vendor-customer relationships.
Condensing heat exchanger technology is overtaking conventional non-condensing designs in commercial and light industrial segments. Stainless steel and aluminum alloy economizers extract latent heat from flue gases, pushing thermal efficiency past 95 percent in natural gas applications. Facility operators in Germany and the Netherlands are specifying these systems to meet building performance certificate thresholds, forcing commodity fire-tube suppliers to retool product lines or exit mid-market segments entirely.
The EPA National Emission Standards for Hazardous Air Pollutants for industrial, commercial, and institutional boilers is tightening particulate matter and mercury limits. Compliance deadlines are compelling operators to install fabric filters, activated carbon injection, or retire sub-75 MMBtu/hour units. Food processing plants in the Midwest and Southeast United States are consolidating steam loads into fewer, larger supercritical water-tube systems to spread abatement capital across higher output.
Energy-as-a-service contracting is displacing traditional equipment purchase and ownership models in European district heating. Municipal utilities in Denmark and Sweden are signing 15-20 year heat supply agreements that transfer operational risk to specialized thermal service providers. This arrangement accelerates deployment of biomass and waste-to-energy boilers that would fail standalone project finance tests, while locking in long-term maintenance revenue streams for system integrators.
Boiler System Market Segmentation
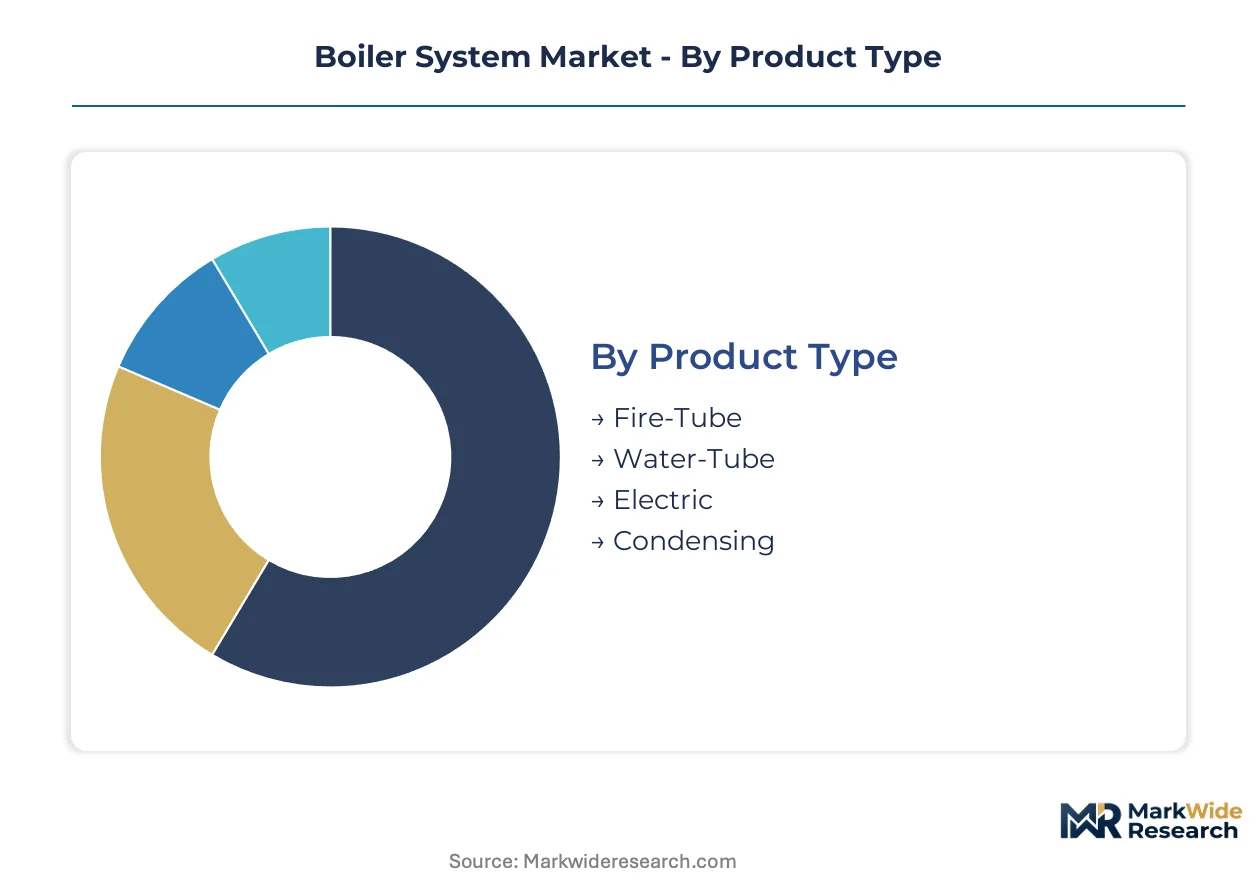
Boiler system procurement diverges sharply across thermal output requirements, pressure specifications, and emissions compliance burdens. Segmentation reveals which configurations command premium pricing versus commodity positioning.
Product Type:
ASME BPVC Section I certification governs high-pressure steam applications, while Section IV covers low-pressure heating boilers, creating divergent compliance timelines and engineering costs across these four architectures.
- Fire-Tube:Hot combustion gases pass through tubes immersed in a water shell, limiting pressure ratings to approximately 25 bar. Demand concentrates in North American commercial buildings where retrofit compatibility with existing gas infrastructure delays electric alternatives.
- Water-Tube:Water circulates through tubes exposed to combustion heat, enabling supercritical pressures exceeding 22 MPa for utility-scale power generation. German and Japanese fabricators dominate high-capacity orders where ASME Section IX welding certification creates supply bottlenecks.
- Electric:Resistance or electrode heating eliminates flue gas emissions entirely. Nordic district heating networks specify these units to meet EU Green Deal carbon intensity targets.
- Condensing:Stainless steel economizers extract latent heat from exhaust streams, pushing thermal efficiency past 95 percent. Netherlands building performance certificates mandate these systems for new commercial construction.
Leading the category by volume: Fire-Tube. Growing fastest: Condensing.
Technology:
Cost tiers separate mature combustion platforms from emerging low-carbon thermal architectures requiring specialized feedstock handling or grid integration capabilities.
- Steam Generation:Saturated or superheated steam output for industrial process heat. Chemical production facilities in the US Gulf Coast and Germany's Ruhr Valley sustain demand for high-pressure systems with precise temperature control.
- Hot Water Generation:Lower-temperature output for space heating and domestic hot water. European residential and commercial replacement cycles favor condensing variants with modulating burners.
- Combined Heat and Power:Simultaneous electricity and thermal output from single fuel input. Danish and Swedish municipal utilities sign long-term energy-as-a-service contracts that transfer operational risk to specialized thermal providers.
- Biomass:Agricultural residue and wood pellet combustion for carbon-neutral steam generation. Baltic states and Finland leverage local feedstock availability to decarbonize district heating networks.
Volume leadership: Steam Generation. Steepest expansion trajectory: Biomass.
End User:
Customer type determines specification complexity, maintenance contract structures, and financing mechanisms from residential point-of-sale to industrial project finance.
- Residential:Single-family and multi-family dwelling heating systems. German building energy efficiency regulations accelerate condensing boiler replacements in aging housing stock.
- Commercial:Office buildings, retail, and hospitality facilities. Netherlands and France specify high-efficiency systems to meet building performance certificate thresholds.
- Industrial:Manufacturing and process heat applications. Food processing and chemical production in Gujarat and Maharashtra manufacturing zones drive greenfield demand under India's PLI scheme incentives.
- Institutional:Hospitals, universities, and government facilities. Long capital planning cycles favor durable water-tube configurations with 30-year service life expectations.
Industrial segment leads by installed base. Residential replacement activity is climbing fastest.
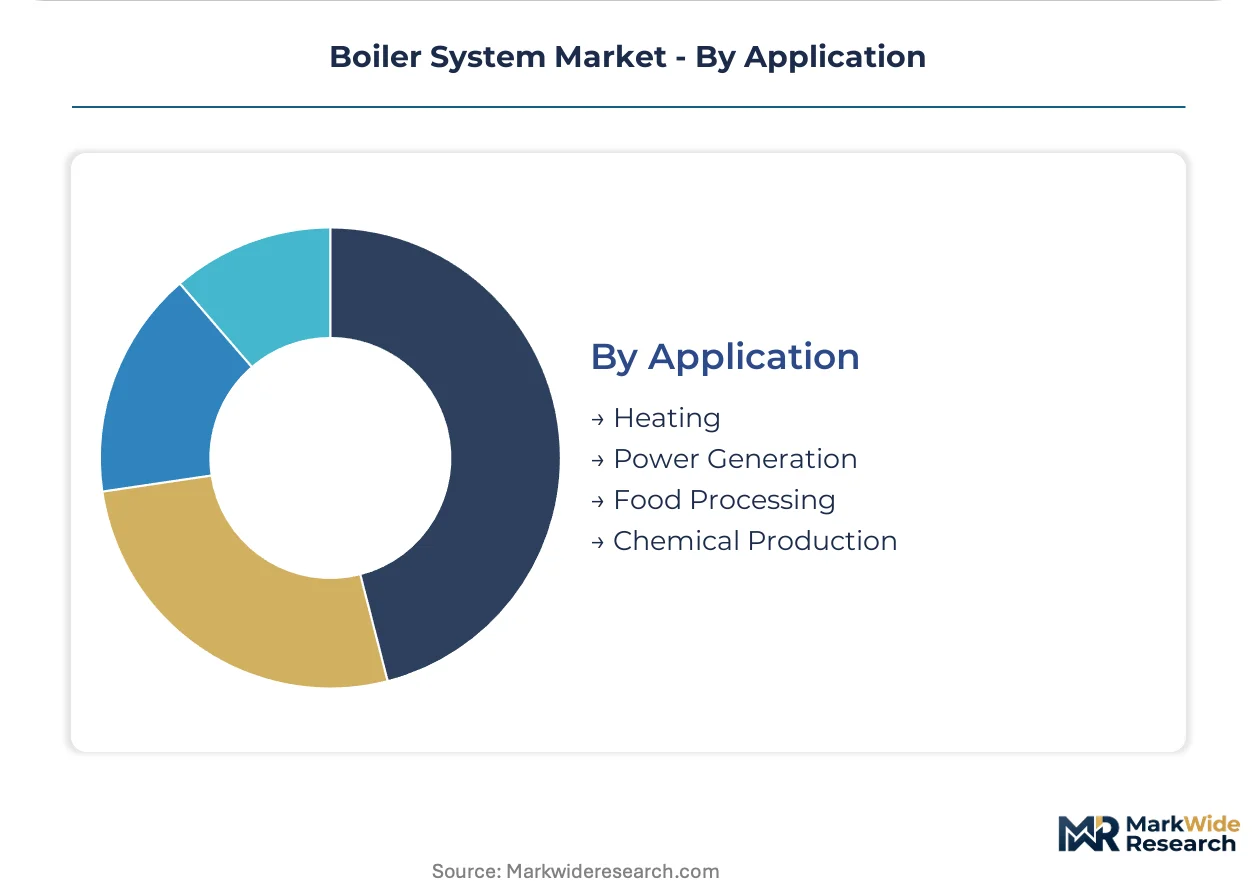
Application:
Application scope dictates pressure ratings, steam purity requirements, and redundancy architectures from comfort heating to critical process steam.
- Heating:Space heating and domestic hot water for buildings. European commercial retrofits favor condensing natural gas units where heat pump-boiler hybrid systems decarbonize sub-boiling temperature loads first.
- Power Generation:Utility-scale electricity production from steam turbine drives. Supercritical water-tube designs dominate US and Chinese utility procurement where capacity factors justify high capital intensity.
- Food Processing:Sterilization, pasteurization, and cooking steam. Protein processing and dairy facilities require 99.9 percent steam reliability to prevent batch spoilage losses.
- Chemical Production:Process heat for reactions and distillation. US EPA National Emission Standards for Hazardous Air Pollutants compel Midwest plants to consolidate steam loads into fewer, larger supercritical systems.
Heating commands greatest installed volume. Food Processing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr Valley industrial corridor anchors European boiler demand as chemical manufacturers retrofit aging steam infrastructure to meet tightening emissions standards.
United States
Gulf Coast petrochemical complexes and Midwest food processing plants drive industrial boiler procurement. EPA National Emission Standards for Hazardous Air Pollutants compel operators to install pollution controls or consolidate steam loads into fewer, larger supercritical water-tube systems. Houston and Baton Rouge chemical clusters are retiring sub-75 MMBtu/hour units ahead of compliance deadlines.
Germany
District heating network expansion in North Rhine-Westphalia and Bavaria sustains demand for high-efficiency condensing systems. Building Energy Act regulations mandate minimum efficiency thresholds for new commercial installations. Munich and Hamburg utilities are signing 15-20 year energy-as-a-service contracts that transfer operational risk to specialized thermal providers.
China
Provincial emissions intensity targets under MEE dual carbon goals redirect state-owned enterprise procurement toward biomass cofiring and electric resistance technologies. Yangtze River Delta manufacturing zones in Jiangsu and Zhejiang are retrofitting coal-fired boilers for natural gas and agricultural residue combustion.
India
PLI scheme incentives for food processing and textiles create greenfield boiler demand in Gujarat and Maharashtra manufacturing zones. Central Electricity Authority regulations mandate efficiency audits for industrial thermal systems. Surat and Ahmedabad textile clusters are installing biomass-fired steam generators to reduce grid electricity dependence.
Netherlands
Building performance certificate thresholds accelerate condensing boiler specification in new commercial construction. F-Gas Regulation restrictions on fluorinated greenhouse gases redirect procurement toward low-GWP refrigerant architectures. Rotterdam and Amsterdam district heating operators are integrating heat pump-boiler hybrid systems to decarbonize sub-boiling temperature loads.
Boiler System Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the boiler system market. Integrated turbine-boiler specialists anchor utility-scale contracts through captive power generation capabilities. Modular system fabricators sustain margin pools in European commercial heating through standardized component architectures. Supercritical water-tube manufacturers dominate high-pressure industrial applications where ASME Section IX welding certification creates supply bottlenecks. Strategic moves concentrate on vertical integration into pressure vessel fabrication and geographic expansion through localized assembly partnerships.
Among Japanese industrial conglomerates, Mitsubishi Heavy Industries Ltd and IHI Corporation exemplify the integrated turbine-boiler archetype. German fabricators Bosch Industriekessel GmbH and Viessmann Group occupy positions within the modular commercial heating tier. North American specialists Babcock & Wilcox Enterprises and Cleaver-Brooks represent divergent scale vectors in industrial steam generation.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries Ltd |
| Siemens AG |
| Babcock & Wilcox Enterprises |
| Bosch Industriekessel GmbH |
| Cleaver-Brooks |
| Thermax Limited |
| Viessmann Group |
| IHI Corporation |
| Hurst Boiler & Welding Company Inc. |
| Others |
Value Chain & Pricing Dynamics
Condensing economizer technology is redrawing cost curves across boiler manufacturing while concentrating fabrication expertise in Germany, Japan, and the United States. Stainless steel alloy specifications for latent heat recovery systems simultaneously inflate material costs and disqualify commodity fabricators lacking ASME Section IX welding certifications.
Pricing Analysis
Uptime guarantees anchor value-based pricing for industrial steam contracts, with chemical processors and food manufacturers paying premiums for 99.9 percent availability commitments. Three-tier pricing structure across premium, standard, and economy levels separates ASME-certified supercritical systems from modular commercial units and imported fire-tube alternatives. Cost compression in mid-market segments is intensifying because European fabricators are absorbing alloy price volatility to defend market share. Municipal utilities and district heating operators exhibit lowest price sensitivity due to energy-as-a-service contracting structures, while independent commercial building owners drive hard bargaining on replacement cycles.
Supply Chain Analysis
Single-source vulnerability sits with certified ASME Section IX welders clustering in Germany, Japan, and the United States, creating geographic bottlenecks for high-pressure system production. Pressure vessel-grade carbon steel and Inconel superalloy feedstock draws from integrated mills in China, South Korea, and the United States. Tariff exposure on alloy imports threatens margin stability for European and North American fabricators. Distribution runs through authorized service networks and OEM-direct channels for large industrial projects, with aftermarket parts flowing through specialized combustion equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with fabrication capabilities and captive alloy supply emerging as the decisive levers for margin defense. Players are pursuing backward integration into pressure vessel manufacturing to escape welding certification bottlenecks.
For Market Incumbents: Lock in long-term service contracts with municipal utilities and district heating operators before energy-as-a-service models mature. Secure captive supply agreements for Inconel and stainless steel alloys to insulate fabrication margins from commodity volatility. Invest in automated welding systems to reduce dependence on scarce ASME-certified labor pools. For New Entrants and Emerging Players: Launch via heat pump-boiler hybrid system architectures targeting Netherlands and German commercial retrofits where building performance certificates mandate efficiency thresholds. Target India's Gujarat and Maharashtra manufacturing corridors where PLI scheme incentives for food processing create greenfield demand without entrenched incumbent relationships. Emphasize biomass cofiring capabilities to align with China's MEE dual carbon enforcement. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated turbine-boiler specialists seeking modular commercial heating capabilities. Five-to-ten year viability hinges on positioning within district heating energy-as-a-service value chains rather than equipment-only models. Watch for MEE enforcement intensity in China's Yangtze River Delta as the inflection signal for biomass and electric technology adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pressure Vessel Fabrication | Captive ASME-certified welding capacity eliminates production bottlenecks and protects margins from alloy price swings. |
| Energy-as-a-Service Contracting | Danish and Swedish municipal utilities transfer operational risk to thermal providers while locking 15-20 year revenue streams. |
| Biomass Cofiring Technology Licensing | Finnish and Baltic district heating operators monetize agricultural residue feedstock availability for carbon-neutral steam generation. |
| Heat Pump-Boiler Hybrid System Launch | Netherlands building performance certificates mandate sub-boiling temperature decarbonization before full electrification. |
| Long-term Alloy Supply Agreement | European fabricators secure Inconel and stainless steel pricing stability against tariff exposure and commodity volatility. |
Study Parameters
Document review covered ASME BPVC certification databases, EPA National Emission Standards compliance filings, and EU Green Deal implementation reports, complemented by interviews with plant engineers at US Gulf Coast petrochemical complexes, procurement leads at German district heating utilities, and aftermarket service heads at Nordic biomass boiler operators. Secondary validation drew from customs trade data, MEE provincial emissions disclosures, and India CEA efficiency audit records. Bottom-up installation data triangulated against top-down fuel consumption projections across the analysis window.
Cross-referencing historical replacement cycle patterns with expert panel input on regulatory timeline acceleration shaped the projection framework. Segmentation modeling captured product type, technology architecture, end-user category, and application pressure requirements throughout the forecast period. CAGRs were derived from elasticity-adjusted demand curves incorporating EU F-Gas Regulation phase-out schedules and China's dual carbon goal enforcement intensity.
Steel and alloy input volatility, ASME certification timeline extensions, and divergent national efficiency mandate calendars are the dominant revision risks for forecast trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
US Industrial Boiler Market
Boilers
Field Erected Boiler Market
Boilers
Hydrogen Boilers Market
Boilers
Industrial and Residential Heating Market
Boilers
Asia-Pacific Combined Heat and Power Market
Boilers
Boiler Control Solutions Market
Boilers
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market
Boilers
Germany Combined Heat and Power Market
Boilers
Global Fuel Flexible Boiler Market
Boilers
Waste Heat Boiler Market
Boilers
Europe Power Plant Boiler Market
Boilers
Power Boiler Market
Boilers
Micro Combined Heat and Power (CHP) Market
Boilers
North America Commercial Boiler Market
Boilers
Space Heating Boilers Market
Boilers
US Combined Heat and Power (CHP) Market