
 Watertube Boilers Market | 2026-2036
Watertube Boilers Market Size, Share, and Industry Trends Forecast 2026-2036
Watertube Boilers Market Insights
Supercritical steam cycle integration is tilting engineering priorities toward higher-pressure designs. Babcock & Wilcox leverages its heritage in utility-scale installations to anchor large power contracts. Cleaver-Brooks specializes in modular packaged configurations that reduce field assembly time. Thermax Limited dominates Asian industrial markets through localized manufacturing and aftermarket service networks.
Watertube boilers contain water-filled tubes heated externally by combustion gases, with operating pressures typically exceeding 150 psi and steam capacities reaching thousands of pounds per hour for central power and process heat applications. Forced circulation systems lead in utility-scale deployments where precise thermal control matters, while natural circulation designs retain share in established industrial facilities with stable baseload profiles. Packaged installations capture margin pools by compressing project timelines, whereas skid-mounted units serve remote oil and gas extraction sites where modular logistics reduce capital risk.
ASME Boiler and Pressure Vessel Code governs construction standards across North American jurisdictions, while EPA Clean Air Act rules force fuel-switching investments that reshape boiler specifications. China's MEE enforces emissions intensity targets that accelerate biomass and natural gas retrofits in industrial zones. Stakeholders must track how carbon border adjustments and evolving efficiency mandates recalibrate total cost of ownership calculations against upfront equipment spend.
Market Dynamics
Supercritical steam cycle integration is compressing engineering timelines and forcing recalibration of pressure vessel specifications across utility procurement offices. This thermal efficiency imperative now governs capital allocation decisions more than fuel flexibility.
Growth Catalysts
- EPA Clean Air Act enforcement:Stringent emissions ceilings are accelerating coal-to-gas retrofits in US power generation fleets, triggering replacement orders for high-efficiency watertube units.
- China's MEE dual carbon targets:Provincial industrial clusters face binding emissions intensity reductions that mandate boiler upgrades in steel and chemical processing facilities.
- Modular packaged configurations:Field-assembly time compression is winning EPC contracts where project schedule risk dominates total cost evaluation.
Market Restraints
- Alloy steel price volatility:Chromium and molybdenum input cost swings compress fabrication margins and destabilize long-term contract pricing.
- Fabrication concentration in East Asian shipyards:Limited qualified pressure vessel construction capacity creates order backlogs extending delivery timelines.
- Heat recovery steam generator substitution:Combined-cycle gas turbine integration reduces standalone watertube boiler demand in new-build power projects.
Strategic Opportunities
- India's CEA thermal efficiency mandates:Aging subcritical coal units face compulsory retirement schedules that open replacement windows for supercritical watertube systems.
- Hydrogen-ready burner retrofits:Dual-fuel combustion technology convergence positions existing installed base for fuel-switching without full replacement.
- Digital twin integration:Predictive maintenance platforms create recurring revenue streams from aftermarket service contracts tied to operational uptime guarantees.
Industry Challenges
- ASME Section I welder certification scarcity:Qualified pressure vessel fabrication labor pools are thinning across North American construction sites.
- Legacy DCS integration complexity:Modern watertube control systems require protocol translation layers to interface with decades-old distributed control architectures in industrial facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Watertube Boilers Market |
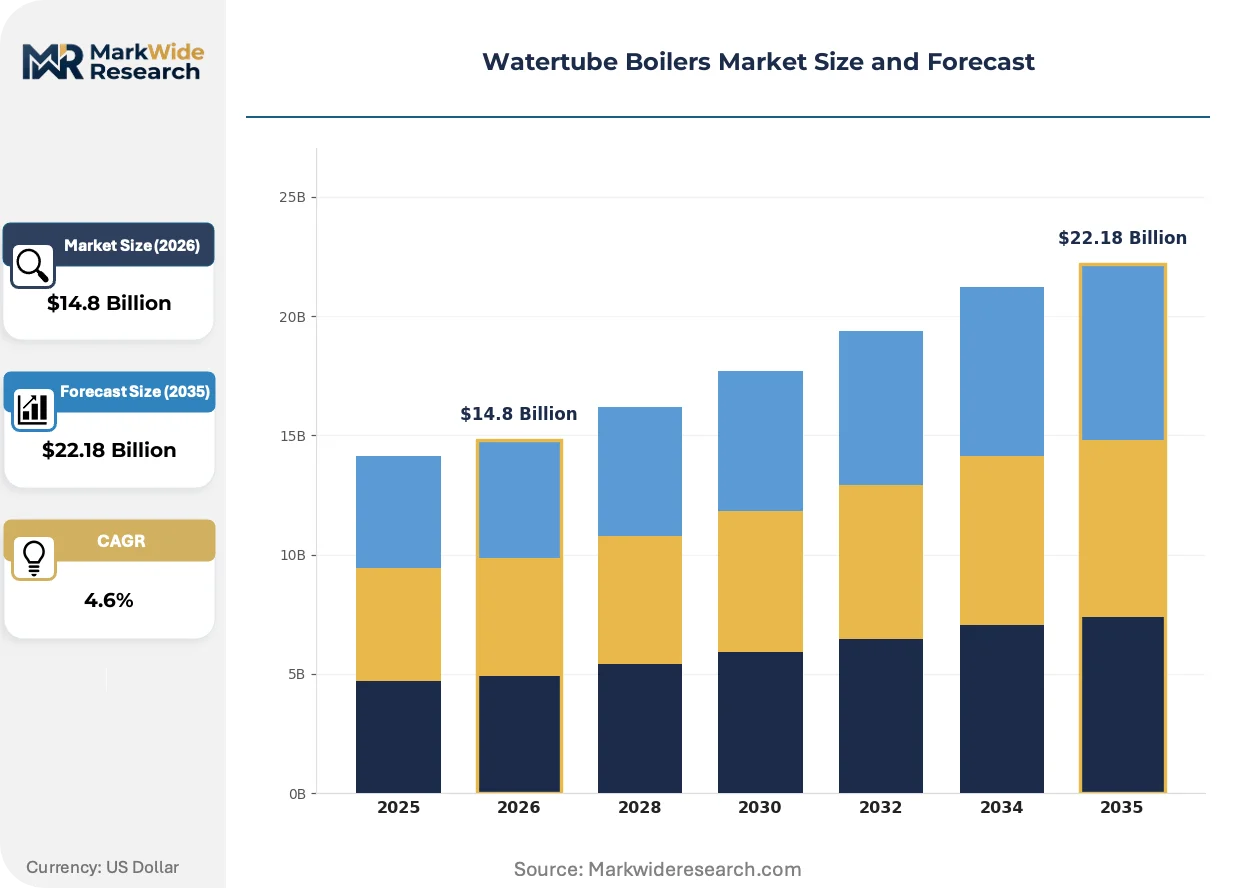
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Circulation, Forced Circulation, High-Pressure, Low-Pressure End User: Power Generation, Oil & Gas, Food Processing, Textile Manufacturing Installation: Onsite, Offsite, Skid-Mounted, Packaged Fuel Type: Natural Gas, Biomass, Coal, Diesel |
| Companies Covered | Cleaver-Brooks, Babcock & Wilcox, Thermax Limited, Hurst Boiler & Welding, Clayton Industries, Alfa Laval, Bharat Heavy Electricals Limited, Fulton Companies, Rentech Boilers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Watertube Boilers Market Trends and Innovations
Digital instrumentation and advanced metallurgy are converging to redefine operational envelopes and maintenance economics across watertube boiler deployments. These shifts are compressing the viable lifecycle of established designs.
Advanced nickel superalloy tubing is enabling steam temperatures exceeding 600°C in ultra-supercritical configurations. Korean and Chinese utility operators are specifying these materials for new coal-fired units despite higher capital cost. Conventional carbon-steel tubing is rendering obsolete for high-pressure applications above 250 bar.
EU F-Gas Regulation phase-down schedules are forcing refrigerant-based heat recovery system redesigns in cogeneration configurations. Industrial boiler manufacturers must now certify alternative working fluids for combined heat and power integration. German chemical processing clusters are most affected, with facility engineers evaluating ammonia and CO2-based thermal loops.
Performance-based service agreements are displacing traditional spare parts and maintenance contracts in European and North American utility fleets. Boiler OEMs now contract for guaranteed availability percentages rather than equipment-only supply. This model concentrates most visibly in UK and Netherlands district heating networks where municipal operators lack in-house technical depth.
Watertube Boilers Market Segmentation
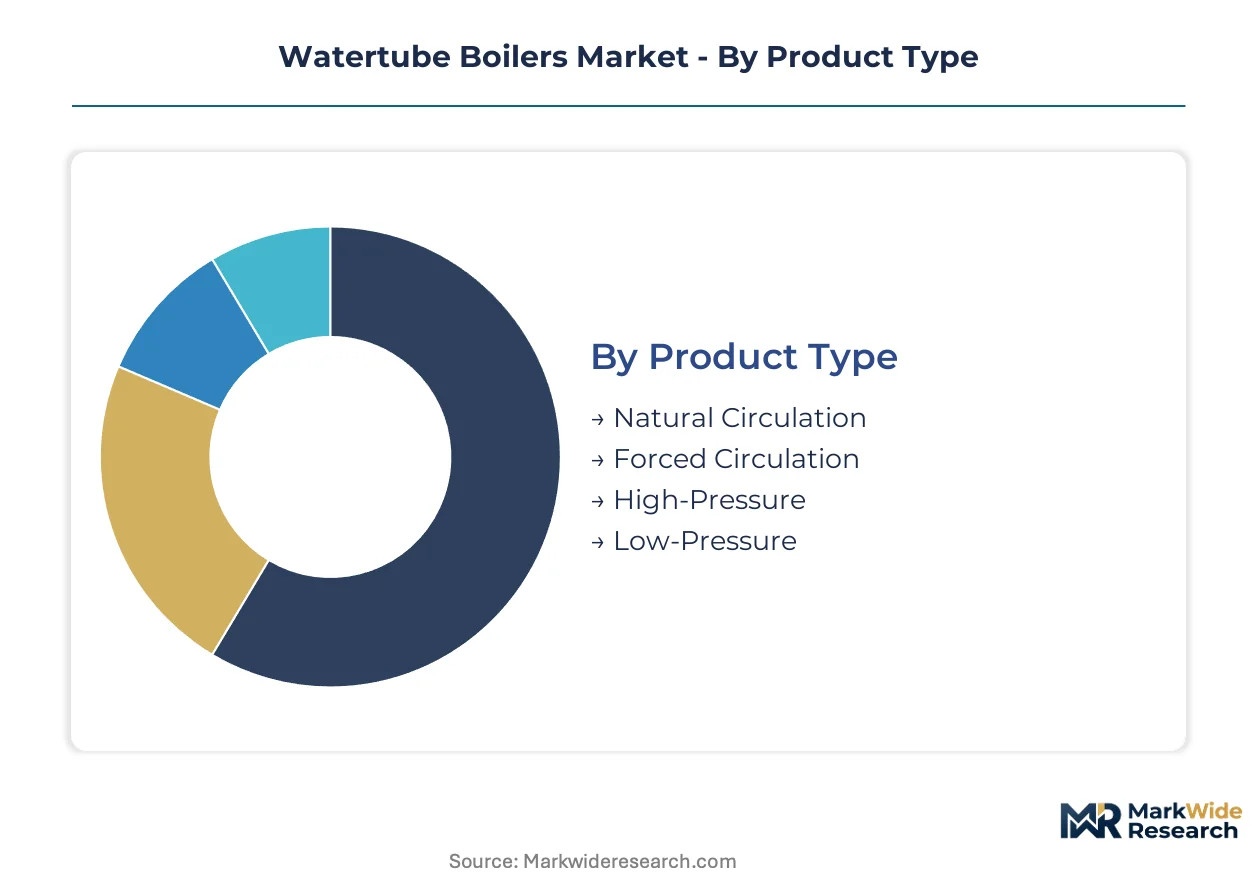
Watertube boiler procurement patterns diverge sharply across pressure ratings, fuel pathways, and installation logistics. Specification choices cascade through engineering timelines, regulatory compliance burdens, and lifecycle cost structures.
Product Type:
Pressure thresholds and circulation mechanics define the engineering trade-offs between thermal efficiency, capital outlay, and operational flexibility.
- Natural Circulation:Relies on density differentials between heated and cooled water columns to drive flow without mechanical pumps. Baseload coal plants in China's Shandong and Henan provinces specify these designs for their mechanical simplicity and tolerance of variable feedwater quality.
- Forced Circulation:Employs pump-driven flow control enabling precise heat distribution across tube bundles. Supercritical units in India's Ultra Mega Power Projects mandate forced circulation to manage the narrow operational margins of ultra-high-pressure steam conditions.
- High-Pressure:Operating envelopes exceed 150 bar with alloy-reinforced tube walls. Chemical processing clusters in Germany's Ruhr region require these specifications for integrated cogeneration.
- Low-Pressure:Simpler fabrication standards reduce capital costs for saturated steam applications. District heating networks in Denmark deploy these for space heating loads where superheat is unnecessary.
Established volume favors natural circulation; emerging adoption favors forced circulation.
End User:
Process intensity and thermal load profiles reshape boiler specifications from fuel flexibility to turndown ratios.
- Power Generation:Central station utilities demand the highest pressure ratings and largest steam capacities. State-backed procurement in China sustains order volumes for supercritical coal units despite carbon intensity scrutiny.
- Oil & Gas:Remote extraction sites prioritize modular logistics and rapid commissioning. North Sea platform operators specify compact watertube configurations with dual-fuel burners for fuel-switching flexibility during supply disruptions.
- Food Processing:Sanitary steam requirements drive stainless steel construction and clean-in-place compatibility. Dairy processing cooperatives in the Netherlands specify these for pasteurization lines.
- Textile Manufacturing:Batch-dyeing operations require rapid steam pressure ramping. Industrial zones in Bangladesh's Dhaka region source low-pressure units for sizing and finishing operations.
Power generation commands the largest unit sizes; oil and gas procurement is climbing the fastest on modular deployment trends.
Installation:
Project timeline risk and site accessibility constraints determine the optimal assembly strategy.
- Onsite:Field-erected configurations accommodate the largest pressure vessels and custom geometries. Greenfield coal plants in Indonesia's Java region require extended construction schedules for welded tube panel installation.
- Offsite:Factory fabrication under controlled conditions improves weld quality and reduces weather delays. European EPC contractors favor this approach for North African power export projects.
- Skid-Mounted:Pre-piped and pre-wired modules minimize field labor. Permian Basin oilfield operators in Texas deploy these for rapid steam flood deployment in enhanced recovery operations.
- Packaged:Compressed delivery schedules win contracts where commercial operation dates carry penalty clauses. Data center developers in Northern Virginia specify packaged watertube units for combined heat and power integration.
Onsite construction retains dominance for utility scale; packaged configurations are gaining share fastest among industrial and commercial buyers.
Fuel Type:
Emissions compliance trajectories and feedstock availability reshape burner specifications and combustion chamber geometries.
- Natural Gas:Lowest carbon intensity among fossil options simplifies EPA Clean Air Act compliance. US utility coal-to-gas retrofits concentrate procurement in the Ohio River Valley and Texas ERCOT zones.
- Biomass:Agricultural residue and energy crop combustion requires specialized grate designs and flue gas treatment. Swedish district heating utilities specify these for carbon-neutral heat supply mandates.
- Coal:Persistent cost advantage sustains demand in markets with domestic mining capacity. India's CEA retirement schedules for subcritical units are compressing the viable window for new coal-fired installations.
- Diesel:Liquid fuel storage and handling systems add capital cost but enable off-grid deployment. Remote mining camps in Western Australia's Pilbara region specify these for operational independence from pipeline infrastructure.
Natural gas dominates new-build specifications; biomass is expanding most quickly on European decarbonization policy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-backed utilities and industrial processors drive procurement concentration across five major markets. Each geography imposes distinct regulatory frameworks that reshape boiler specifications and fuel pathways. Cluster-level demand patterns reveal where upgrade cycles concentrate.
China
Provincial power authorities in Shandong and Henan sustain orders for supercritical coal units despite carbon intensity scrutiny. MEE dual carbon targets bind industrial clusters to emissions intensity reductions that mandate boiler replacements. Steel processing facilities in Tangshan face compulsory upgrade schedules for high-pressure steam systems.
United States
Utility coal-to-gas retrofits concentrate procurement in the Ohio River Valley and Texas ERCOT zones. EPA Clean Air Act enforcement accelerates replacement orders for high-efficiency natural gas units. Chemical processors along the Gulf Coast specify dual-fuel configurations to manage feedstock price volatility.
India
CEA thermal efficiency mandates force retirement schedules for aging subcritical coal installations. Ultra Mega Power Projects specify forced-circulation supercritical designs for narrow operational margins. Gujarat's industrial corridors source modular units for rapid commissioning in pharmaceutical and textile clusters.
Germany
Ruhr region chemical processors require high-pressure specifications for integrated cogeneration applications. EU F-Gas Regulation phase-down schedules force refrigerant-based heat recovery system redesigns. District heating utilities in Hamburg and Berlin specify biomass-compatible units for carbon-neutral heat supply mandates.
Indonesia
State electricity utility PLN expands coal-fired capacity additions across Java and Sumatra islands. Greenfield power projects in Java require extended construction schedules for field-erected configurations. Nickel processing smelters in Sulawesi source high-pressure units for hydrometallurgical operations.
Watertube Boilers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement channels. Utility-scale contracts concentrate among heritage manufacturers with ASME certification depth, while packaged configurations attract modular specialists with compressed delivery capabilities. Three archetypes dominate: integrated boiler-house providers, pressure vessel fabricators with captive metallurgy expertise, and aftermarket service platforms. Consolidation pressure operates through strategic partnerships for geographic coverage and technology licensing for fuel-flexible burner systems.
Within the heritage utility tier, Babcock & Wilcox occupies a position anchored to large power contracts. Among packaged configuration specialists, Cleaver-Brooks exemplifies the field-assembly compression model. Thermax Limited represents the localized manufacturing archetype across Asian industrial markets.
| Leading Market Players |
|---|
| Cleaver-Brooks |
| Babcock & Wilcox |
| Thermax Limited |
| Hurst Boiler & Welding |
| Clayton Industries |
| Alfa Laval |
| Bharat Heavy Electricals Limited |
| Fulton Companies |
| Rentech Boilers |
| Others |
Pricing and Supply Chain Analysis
East Asian alloy steel mills anchor fabrication economics, concentrating chromium and molybdenum sourcing leverage among Korean and Chinese pressure vessel constructors. This upstream density funnels margin capture toward integrated metallurgy players while forcing downstream boiler OEMs into long-term offtake negotiations.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate utility-scale procurement, insulating fabricators from nickel superalloy volatility while compressing margins on fixed-price packaged configurations. Price differentiation hinges on ASME Section I certification tier and aftermarket service bundling. Cost compression in standard-pressure carbon-steel segments intensifies as Chinese modular specialists expand export capacity. Industrial processors in Southeast Asian chemical clusters exhibit highest price sensitivity; supercritical utility buyers prioritize thermal efficiency over capital outlay.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts seamless tube sourcing for North American pressure vessel fabricators. Manufacturing gravity centers on China, South Korea, and Germany for specialized alloy forming. Raw material feeds draw from Indonesian nickel laterite, South African chromium, and Kazakh molybdenum. Single-source vulnerability concentrates in superalloy vacuum induction melting capacity. Distribution runs through EPC contractor-specified channels with captive logistics for oversized pressure vessel modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin platforms are reconfiguring this market toward recurring-revenue ecosystems, with predictive maintenance interoperability creating winner-take-most dynamics among boiler OEMs with installed base density.
For Market Incumbents: Entrench through backward integration into nickel superalloy casting capacity and captive ASME welder certification academies. Heat recovery steam generator substitution in combined-cycle projects threatens standalone watertube demand; defend through hydrogen-ready burner retrofit programs that extend existing asset lifecycles without full replacement. For New Entrants and Emerging Players: India's CEA-mandated subcritical retirement schedules create replacement windows for forced-circulation supercritical specialists. Modular packaged configurations for Permian Basin oilfield steam flood operations offer lowest barriers to initial contract penetration. Partner with European EPC contractors on North African power export projects to bypass heritage utility procurement relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed aftermarket service platforms lacking digital twin capabilities. Long-term viability favors operators with recurring revenue from availability-guarantee contracts over equipment-only suppliers. Watch for hydrogen combustion certification milestones as inflection signals for dual-fuel retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Casting | Captive nickel-chromium supply secures margin pools for ultra-supercritical pressure vessel production. |
| Digital Twin Platform Deployment | Predictive maintenance contracts with UK district heating utilities convert equipment sales into recurring revenue streams. |
| Hydrogen-Ready Burner Certification | Dual-fuel retrofit positioning captures EU carbon border adjustment compliance spending without full boiler replacement. |
| ASME Welder Academy Investment | Certified labor scarcity in North American construction sites creates captive capability moats for qualified fabricators. |
| Modular Packaged Configuration Expansion | Compressed delivery schedules win data center CHP contracts in Northern Virginia where commercial operation penalties apply. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across utility procurement offices, EPC contractor engineering teams, pressure vessel fabrication managers, and aftermarket service directors. Secondary validation drew from EPA enforcement databases, ASME certification registries, EIA power plant inventories, and customs trade records for alloy steel imports. Bottom-up unit economics triangulated against top-down sector expenditure patterns.
Calibration against historical capacity additions and retirement schedules anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include circulation mechanism, pressure rating tier, fuel pathway, installation logistics, and regional regulatory cluster. CAGRs derived from elasticity-adjusted replacement demand curves and greenfield project development pipelines. Inputs incorporated MEE dual carbon target enforcement timelines and CEA thermal efficiency mandate compliance schedules.
Practitioners should monitor alloy steel price volatility, ASME welder certification pipeline constraints, and hydrogen combustion regulatory milestones for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Boiler System Market
Boilers
Superheater Tubes Market
Boilers
US Commercial Boiler Market
Boilers
Circulating Fluid Bed Boilers Market
Boilers
Global Package Boilers Market
Boilers
District Heating Market
Boilers
Fuel Operated Heaters Market
Boilers
Residential Boiler Market
Boilers
Water Tube Industrial Boiler Market
Boilers
US Industrial Boiler Market
Boilers
Europe Power Plant Boiler Market
Boilers
Advanced Utility Boilers Market
Boilers
Global Boiler Market
Boilers
Boiler Control Market
Boilers
Industrial Boiler MRO Market
Boilers
Brazil Combined Heat and Power Market