
 US Boiler Market | 2026-2036
US Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
US Boiler Market Analysis
Industrial facility managers is reorganizing procurement priorities toward high-efficiency natural gas systems as energy costs pressure operating budgets. Cleaver-Brooks leverages its modular steam generator platform to serve food processing and pharmaceutical clients with rapid-start capabilities. Miura America differentiates through compact once-through designs that reduce footprint and water treatment costs for urban commercial installations. Fulton Boiler Works anchors the mid-capacity segment with vertical tubeless configurations favored by regional hospitals and universities.
Boilers are pressure vessels designed to heat water or generate steam through combustion, electric resistance, or solid fuel conversion, operating at temperatures exceeding 212°F and pressures ranging from 15 to over 1,500 psi for process heating, power generation, and building climate control. Fire-tube configurations dominate residential and light commercial applications due to lower capital outlay and simpler maintenance protocols, while water-tube systems command industrial and institutional share where higher pressure thresholds and rapid load response prove critical. Natural gas-fired units lead fuel-type demand across the US, though biomass adoption is accelerating in pulp and paper corridors seeking carbon-neutral steam supply.
The Department of Energy enforces minimum efficiency standards under federal appliance regulations, while EPA emissions rules under the Clean Air Act constrain NOx and CO output from commercial and industrial combustion sources. OSHA boiler inspection mandates and ASME Boiler and Pressure Vessel Code compliance requirements shape maintenance cycles and replacement timelines for facility operators. Stakeholders must weigh retrofit economics against full replacement pathways as state-level decarbonization roadmaps tighten fossil-fuel allowances in building codes.
Market Dynamics
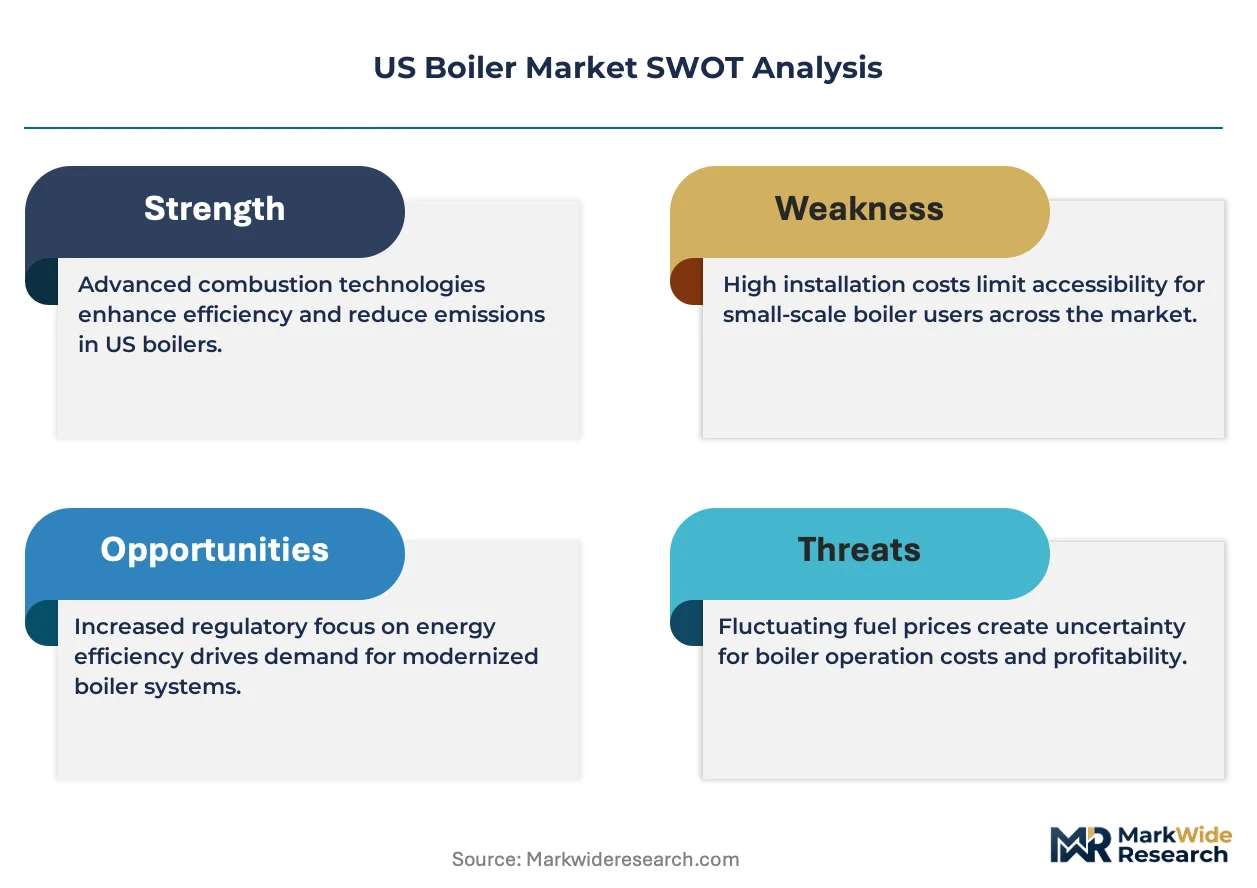
The US Boiler Market is undergoing a fundamental reconfiguration as the Department of Energy's efficiency standards and EPA emissions rules force facility managers toward condensing boiler replacements, compressing replacement cycles and redirecting capital flows across industrial, commercial, and institutional segments.
Growth Catalysts
- EPA Clean Air Act enforcement:Stricter NOx and CO output limits are compelling healthcare facilities and petrochemical plants to accelerate fleet modernization ahead of compliance deadlines.
- Texas industrial cluster expansion:Petrochemical plant buildouts and hospital construction in the Gulf Coast corridor are concentrating large-capacity boiler orders from single-source procurement teams.
- Condensing technology maturation:Natural gas-fired condensing systems now achieve thermal efficiency thresholds that satisfy both federal mandates and operating budget pressures for facility managers.
Market Restraints
- Stainless steel alloy cost volatility:Heat exchanger fabrication depends on nickel and chromium supply chains concentrated in specific mining jurisdictions, creating input cost unpredictability for domestic manufacturers.
- Skilled boiler technician scarcity:ASME-certified welders and pressure vessel inspectors face generational workforce gaps, extending installation timelines and inflating labor premiums in urban markets.
- Electrification substitution threat:Heat pump systems for low-temperature process heating are capturing share in food processing and light commercial applications where thermal loads permit.
Strategic Opportunities
- Rural healthcare boiler retrofit backlog:Critical access hospitals in Appalachia and the Mountain West operate aging steam systems with deferred maintenance, creating concentrated demand pockets for turnkey replacement providers.
- Biomass fuel supply chain development:Pulp and paper corridors in the Pacific Northwest and Southeast are piloting carbon-neutral steam supply through woody residue combustion, opening alternative fuel boiler deployments.
- Remote monitoring service unbundling:IoT-enabled predictive maintenance platforms are creating recurring revenue streams independent of equipment sales, with early adoption concentrated in university district heating networks.
Industry Challenges
- ASME Section I certification bottlenecks:Third-party inspection backlogs and documentation complexity are extending project commissioning timelines, straining contractor cash flow and owner occupancy schedules.
- Legacy control system integration:Facility automation teams face protocol mismatches when retrofitting modern modulating burners onto existing Building Management Systems, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Boiler Market |
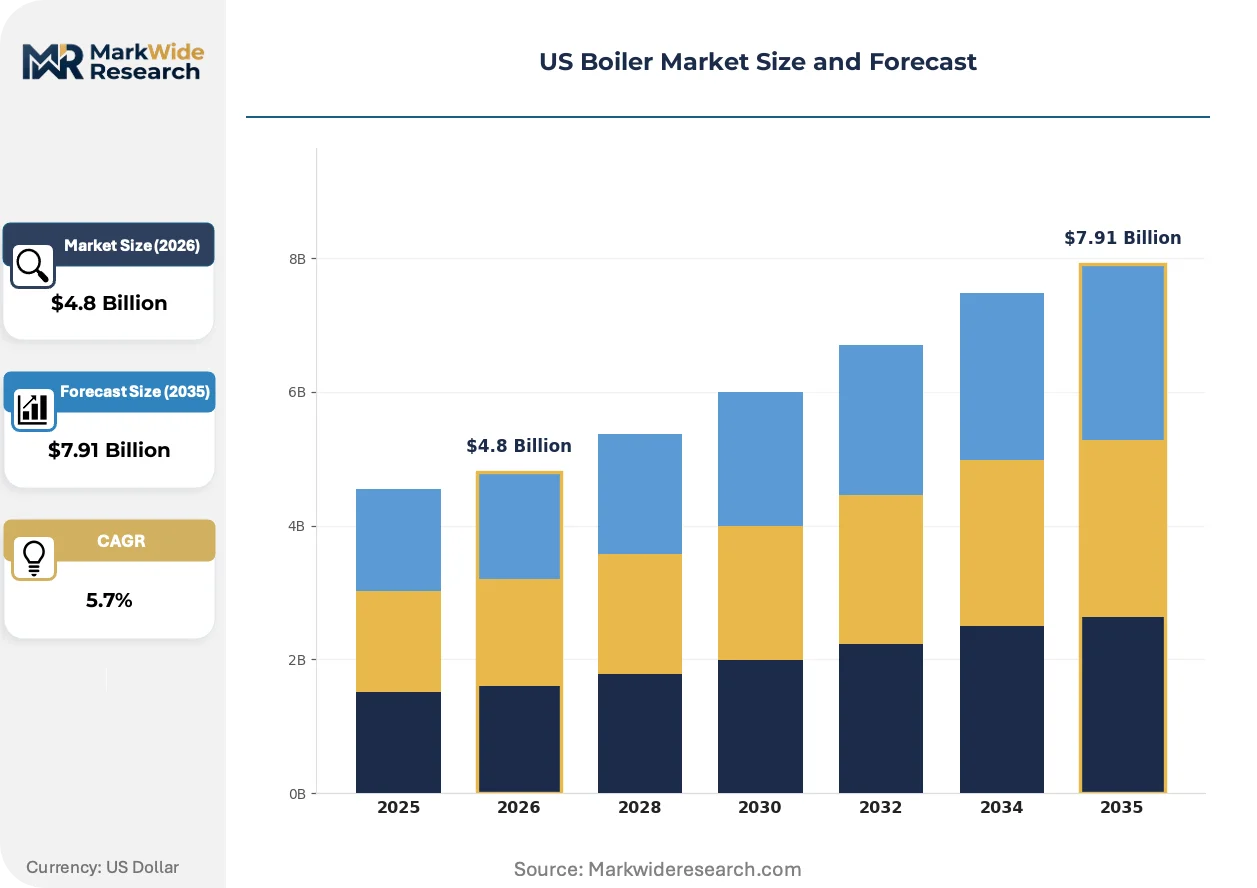
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Tube, Water-Tube, Electric, Solid Fuel End User: Residential, Commercial, Industrial, Institutional Fuel Type: Natural Gas, Oil, Coal, Biomass Size: Small, Medium, Large, XL |
| Companies Covered | Cleaver-Brooks, Fulton Boiler Works, Miura America, Hurst Boiler and Welding Co., Columbia Boiler Company, Clayton Industries, P. M. Lattner Manufacturing, Babcock & Wilcox Enterprises, Weil-McLain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Boiler Market Emerging Trajectories
Digital combustion optimization and modular steam architectures are compressing equipment footprints while expanding operational flexibility, forcing incumbent manufacturers to reconfigure product portfolios around rapid-start and low-NOx performance benchmarks rather than thermal efficiency alone.
Modular once-through steam generator designs are fragmenting traditional fire-tube and water-tube category boundaries. These compact systems eliminate thermal mass lag, enabling pharmaceutical and food processing clients to match steam output precisely to batch process demand. The technology is compressing market share for conventional horizontal pressure vessels in sub-300 horsepower applications.
OSHA boiler inspection mandates and EPA Maximum Achievable Control Technology standards are tightening compliance documentation requirements. Facility operators must now maintain continuous emissions monitoring records and preventive maintenance logs for audit readiness. Industrial users in Texas and Louisiana are responding by consolidating boiler house operations under dedicated compliance officers.
Hospital and university procurement teams are unbundling lifecycle service contracts from initial equipment purchases. Buyers now negotiate separate agreements for combustion tuning, water treatment, and tube inspection, shifting vendor relationships from transactional sales toward long-term performance partnerships. This pattern is most visible in Northeast and Midwest institutional clusters with mature district heating infrastructure.
US Boiler Market Segmentation
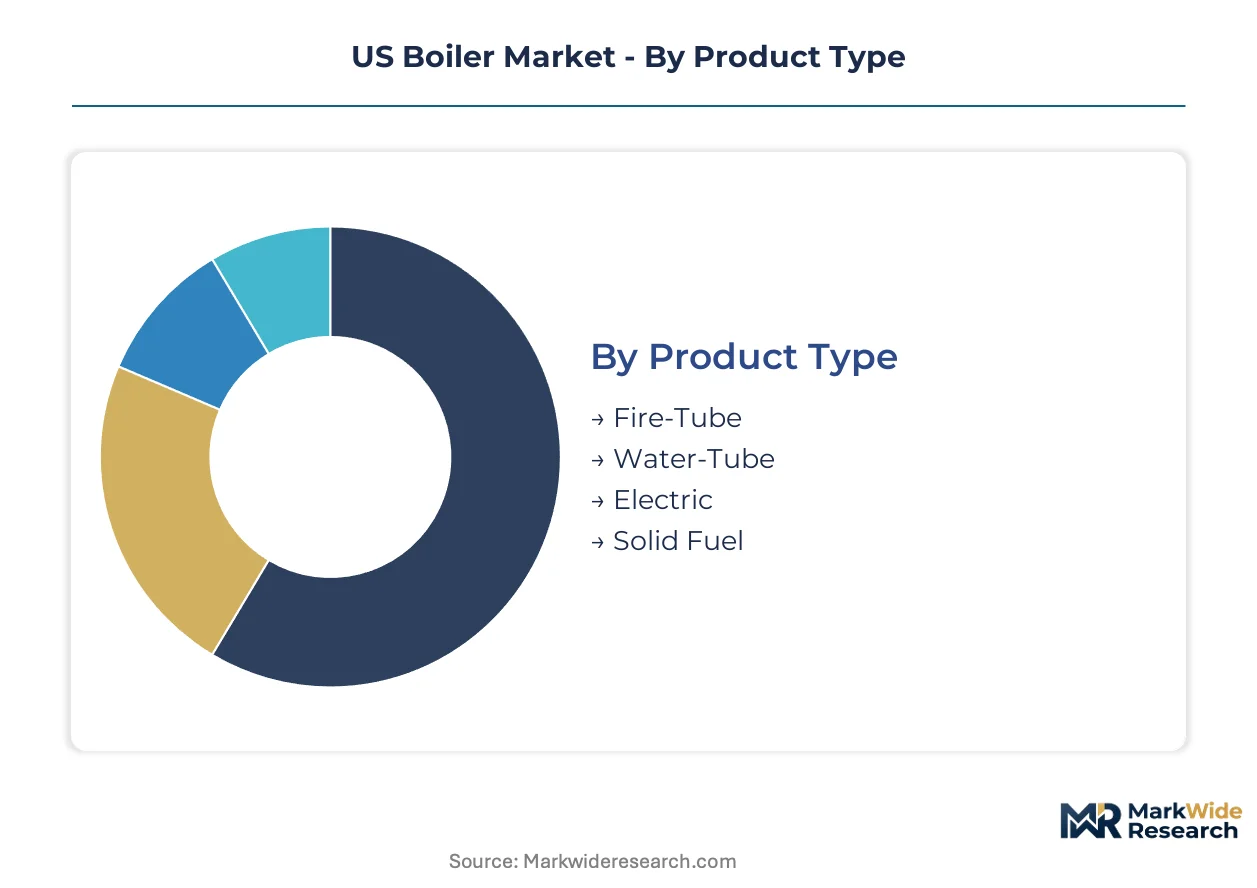
US boiler procurement patterns fragment sharply across pressure thresholds, fuel infrastructure, and compliance burdens. Facility managers weight capital efficiency against operating cost exposure differently in each segment, creating distinct margin architectures for equipment suppliers and service providers.
Product Type:
Margin pools concentrate in water-tube configurations where engineering complexity sustains premium pricing, while fire-tube systems compete on installed cost in high-volume replacement cycles.
- Fire-Tube:Hot combustion gases pass through tubes submerged in water, generating steam at pressures below 350 psi. Demand clusters in Texas hospital construction and light commercial retrofits where ASME Section IV compliance costs dominate specification decisions. Facility managers favor these units for their simpler maintenance protocols and lower technician certification requirements.
- Water-Tube:Water circulates through tubes exposed to combustion heat, achieving pressures exceeding 1,500 psi with rapid load response. Petrochemical plant expansions along the Gulf Coast drive large-capacity orders as process steam reliability becomes critical to continuous operations. The segment commands the highest engineering margins due to custom fabrication requirements.
- Electric:Resistance heating elements eliminate combustion emissions entirely, serving California and Northeast facilities facing fossil fuel restrictions in building codes.
- Solid Fuel:Biomass and coal-fired systems retain share in pulp and paper corridors where captive fuel supply chains reduce operating cost volatility.
Fire-tube systems hold installed capacity across the commercial base. Water-tube configurations are rotating up the share rankings in industrial greenfield projects.
End User:
Volume concentration tilts toward industrial process heating, though institutional procurement cycles generate the most predictable replacement revenue streams.
- Industrial:Continuous steam demand for chemical processing, food manufacturing, and refining operations requires 24/7 reliability with redundancy built into fleet design. Texas petrochemical complexes and Louisiana refineries represent the densest demand geography, with procurement teams negotiating multi-unit contracts tied to plant expansion timelines.
- Institutional:Universities and healthcare facilities operate district heating networks with seasonal load variation, creating complexity in right-sizing replacement equipment. Critical access hospitals in Appalachia and the Mountain West face compressed upgrade timelines as deferred maintenance collides with EPA emissions enforcement.
- Commercial:Office buildings and retail centers prioritize rapid-start capabilities and footprint minimization in urban mechanical rooms.
- Residential:Single-family and multifamily installations concentrate in cold-climate states where heating degree-days justify condensing boiler premiums.
Industrial users command the largest average transaction values. Institutional buyers are expanding their share of vendor attention as compliance documentation requirements intensify.
Fuel Type:
Natural gas infrastructure density determines regional competitive dynamics, while biomass adoption tracks forestry industry geography.
- Natural Gas:Pipeline distribution networks enable the lowest operating costs for facilities with consistent thermal demand. The fuel dominates new installations across the Midwest and Southeast where utility infrastructure is mature, though Northeast states are tightening fossil fuel allowances in decarbonization roadmaps.
- Biomass:Woody residue combustion serves Pacific Northwest and Southeast pulp mills seeking carbon-neutral steam supply chains. The segment requires significant upfront investment in fuel handling and emissions control systems that complicate project economics outside integrated forestry operations.
- Oil:Retained share concentrates in rural Northeast markets lacking pipeline access, with deliveries tracking heating season demand spikes.
- Coal:Limited to legacy industrial installations in Appalachia and the Mountain West where existing fuel contracts and emissions grandfathering delay conversion timelines.
Natural gas retains dominant installed base. Biomass is climbing the fastest as carbon accounting pressures reshape fuel procurement in forest products.
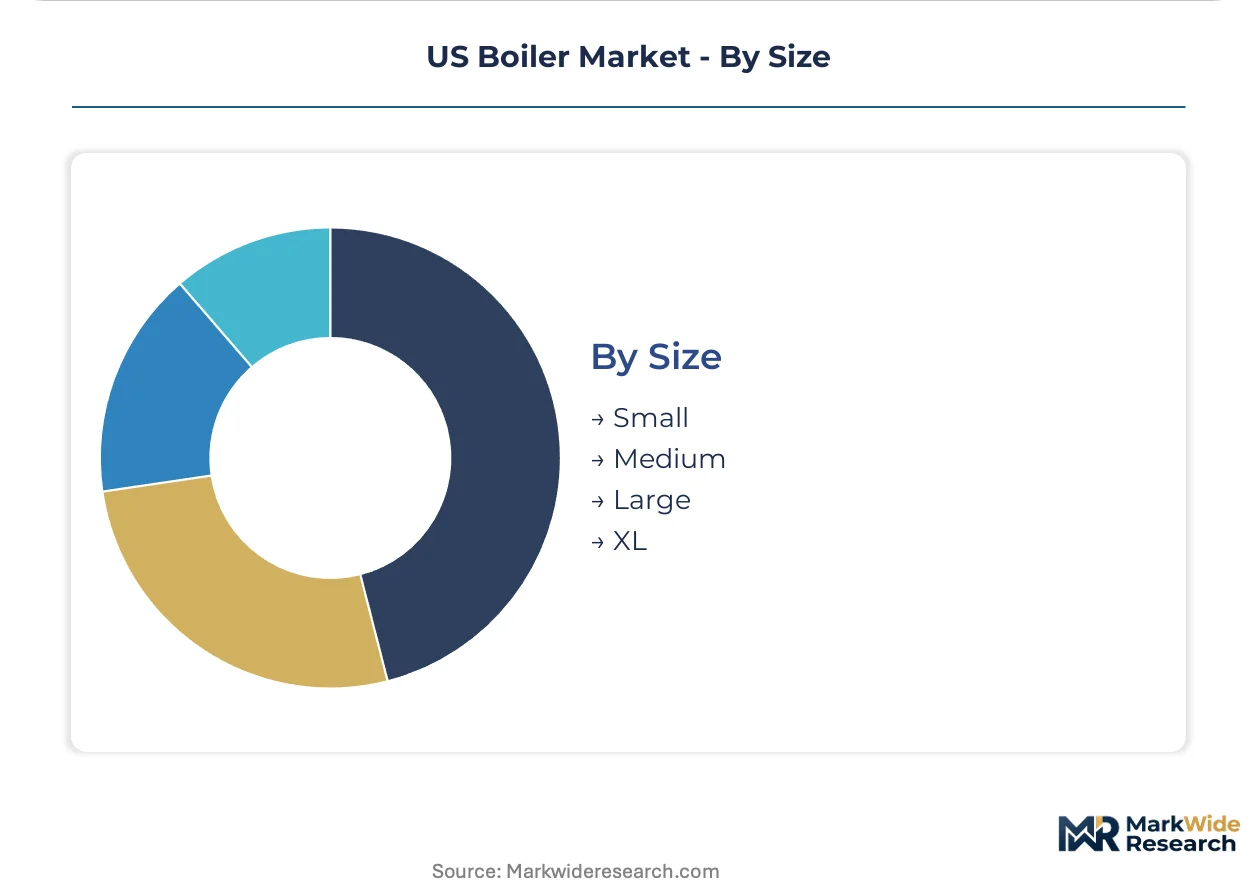
Size:
Mid-capacity equipment generates the most contested pricing environment as standardized designs compress differentiation opportunities.
- Large:Systems exceeding 250 horsepower serve central plant operations in major hospitals, universities, and industrial facilities where redundancy requirements demand multiple units. Texas medical center expansions and Gulf Coast chemical plant buildouts concentrate procurement activity, with buyers negotiating performance guarantees tied to thermal efficiency and emissions compliance.
- Medium:50-250 horsepower configurations anchor regional hospital and university markets where vertical tubeless designs reduce mechanical room footprint. The segment faces the most intense price competition as manufacturers standardize burner and control packages.
- Small:Sub-50 horsepower units dominate residential and light commercial replacement cycles with shorter decision timelines.
- XL:Custom-engineered systems above 500 horsepower serve utility-scale district heating and major industrial process loads with extended fabrication lead times.
Medium-capacity units hold the broadest installed footprint. Large systems are expanding most quickly as institutional central plants consolidate distributed boiler houses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication concentrates in the industrial Midwest and Southeast, while procurement demand clusters along the Gulf Coast and in Texas medical corridors where petrochemical and healthcare construction cycles overlap.
Texas
Petrochemical plant expansions and hospital construction in Houston and the Gulf Coast corridor drive large-capacity boiler orders from single-source procurement teams. EPA Clean Air Act enforcement compels facility managers to accelerate fleet modernization ahead of compliance deadlines. The Texas Medical Center and Port Arthur refining complexes represent the densest demand geography.
Louisiana
Refinery operations and chemical processing facilities require 24/7 steam reliability with built-in redundancy. OSHA boiler inspection mandates and EPA Maximum Achievable Control Technology standards tighten compliance documentation requirements. Industrial users in Baton Rouge and Lake Charles are consolidating boiler house operations under dedicated compliance officers.
Appalachia
Critical access hospitals operate aging steam systems with deferred maintenance, creating concentrated demand pockets for turnkey replacement providers. State-level decarbonization roadmaps tighten fossil-fuel allowances in building codes. Rural healthcare facilities in West Virginia and Kentucky face compressed upgrade timelines as emissions enforcement intensifies.
Pacific Northwest
Pulp and paper corridors pilot carbon-neutral steam supply through woody residue combustion, opening alternative fuel boiler deployments. Biomass fuel supply chain development requires significant upfront investment in fuel handling systems. Washington and Oregon forestry operations integrate captive fuel supply chains to reduce operating cost volatility.
California
Resistance heating elements eliminate combustion emissions entirely, serving facilities facing fossil fuel restrictions in building codes. The state's decarbonization roadmap accelerates electrification substitution for low-temperature process heating. Urban commercial installations in Los Angeles and San Francisco prioritize footprint minimization in constrained mechanical rooms.
US Boiler Market Vendor Landscape
Concentration sits with diversified industrial equipment manufacturers and specialized boiler fabricators serving distinct capacity segments. The vendor base spans consolidated multinational entities and regional specialists competing on engineering customization versus installed cost. Three archetypes dominate: full-line steam system providers, compact once-through specialists, and vertical tubeless mid-capacity anchor manufacturers. Competitive moves center on modular platform development and unbundled service contract expansion.
Among US-based fabricators, Cleaver-Brooks, Fulton Boiler Works, and Miura America exemplify the strategic archetype segmentation. Cleaver-Brooks occupies a position within the full-line provider tier with modular steam generator platforms. Fulton Boiler Works anchors the mid-capacity segment with configurations favored by regional hospitals and universities. Miura America sits within the compact system specialist category, serving urban commercial installations where footprint constraints dominate specification decisions.
| Leading Market Players |
|---|
| Cleaver-Brooks |
| Fulton Boiler Works |
| Miura America |
| Hurst Boiler and Welding Co. |
| Columbia Boiler Company |
| Clayton Industries |
| P. M. Lattner Manufacturing |
| Babcock & Wilcox Enterprises |
| Weil-McLain |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Gulf Coast petrochemical operators and domestic fabricators lock in heat exchanger alloy supply while capping price volatility exposure across multi-year replacement cycles. These contractual structures concentrate procurement leverage among large-volume buyers in Texas and Louisiana, compressing margins for mid-tier manufacturers serving fragmented institutional demand.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment transactions, with premium tiers commanding spreads based on ASME Section I certification status and bundled lifecycle service contracts. Price differentiation hinges on thermal efficiency ratings and EPA NOx compliance guarantees, with economy tiers facing the steepest compression as stainless steel input costs transmit through fabrication quotes. Hospital procurement teams in the Northeast exhibit the highest price sensitivity due to constrained capital budgets, while Texas petrochemical buyers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Extended lead times for nickel-chromium alloy heat exchangers now stretch 18-24 weeks, forcing fabricators to carry elevated raw material inventory against order volatility. Supply concentrates in domestic Midwest foundries and specialty metal processors in Pennsylvania and Ohio, with secondary sourcing from Canadian and Mexican fabricators for standard pressure vessel components. Single-source vulnerability concentrates in Indonesian nickel ore supply chains that feed domestic stainless production. Distribution runs through manufacturer-direct sales teams for large industrial contracts, while regional distributors handle commercial and institutional replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Boiler Market is recovering from a cyclical trough as EPA compliance deadlines force deferred replacement demand into active procurement pipelines. Healthcare facility managers face compressed upgrade timelines that override traditional budget cycle constraints.
For Market Incumbents: Shield installed base relationships by embedding IoT-enabled predictive maintenance platforms that create switching costs against modular once-through competitors. Deepen backward integration into heat exchanger fabrication to capture margin pools currently flowing to specialty metal processors. Prioritize ASME certification investment to accelerate project commissioning timelines and differentiate against regional fabricators facing inspection backlogs. For New Entrants and Emerging Players: Differentiate on rapid-start steam architectures targeting food processing batch operations where thermal mass lag penalties exceed equipment cost premiums. Concentrate geographic entry on Appalachia critical access hospitals with deferred maintenance backlogs and limited incumbent service coverage. Deploy turnkey replacement bundling that consolidates demolition, installation, and compliance documentation into single-contract procurement. For Investors and Strategic Acquirers: Compact once-through specialists with established pharmaceutical and urban commercial customer bases represent the most defensible acquisition targets as footprint constraints intensify across dense mechanical room retrofits. Long-term viability rests on fuel flexibility engineering that accommodates prospective hydrogen blending in natural gas distribution networks. Monitor state-level decarbonization roadmap revisions as the primary inflection signal for electrification substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Expansion | Enables Cleaver-Brooks and Miura America to serve pharmaceutical batch processing with rapid-start configurations. |
| Backward Integration into Alloy Fabrication | Reduces heat exchanger cost volatility exposure from Indonesian nickel supply chains for domestic manufacturers. |
| IoT Predictive Maintenance Unbundling | Creates recurring revenue streams independent of equipment sales through university district heating network contracts. |
| Biomass Fuel Supply Chain Development | Opens alternative fuel deployments in Pacific Northwest pulp corridors seeking carbon-neutral steam supply chains. |
| ASME Certification Acceleration | Compresses project commissioning timelines for Gulf Coast petrochemical buyers facing EPA compliance deadlines. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA enforcement records, ASME certification databases, and hospital procurement disclosures to establish baseline market sizing. Primary interviews with plant engineers at Texas petrochemical complexes, maintenance directors at Appalachian critical access hospitals, and procurement leads at Midwest universities informed demand segmentation and replacement cycle timing. Secondary validation drew from Department of Energy efficiency standard filings, OSHA inspection mandate documentation, and state-level decarbonization roadmap publications. Bottom-up equipment shipment analysis triangulates against top-down facility count and replacement rate modeling.
Segmentation dimensions modeled include pressure vessel configuration, fuel type infrastructure, end-user industry, and capacity tier across the projection horizon. The analytical framework incorporates thermal efficiency mandate compliance trajectories, regional emissions enforcement intensity variations, and fuel price differential assumptions throughout the forecast period. CAGRs derive from installed base aging profiles, regulatory deadline clustering, and capital expenditure cycle normalization inputs specific to healthcare and petrochemical end-markets.
The analysis sits within stated boundaries; outcomes outside sustained natural gas price stability or accelerated electrification substitution timelines would require recalibration. Forecasts reflect assumptions regarding EPA enforcement continuity and ASME inspector workforce availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
Micro Combined Heat and Power (CHP) Market
Boilers
Watertube Boilers Market
Boilers
North America and Europe Electric Boilers Market
Boilers
Germany Combined Heat and Power Market
Boilers
Feed Water Heater for Power Plants Market
Boilers
US Combined Heat and Power (CHP) Market
Boilers
Boiler Control Market
Boilers
Coal-Saving Combustion-Supporting Agent Market
Boilers
Power Boiler Market
Boilers
Water Tube Industrial Boiler Market
Boilers
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market
Boilers
Waste Heat Boiler Market
Boilers
GCC Electric Water Heater Market
Boilers
Industrial Biomass Boiler Market
Boilers
Advanced Utility Boilers Market