
 Egypt Oil and Gas Downstream Market | 2026-2036
Egypt Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Oil and Gas Downstream Market Foresight
Digital refinery automation is fragmenting traditional process control architectures across Egyptian downstream operations. Egyptian General Petroleum Corporation leverages integrated digital twin platforms to optimize crude distillation yields. TotalEnergies sustains competitive positioning through advanced hydrocracking technology deployment at its Egyptian facilities. Shell anchors its downstream presence via strategic storage terminal networks along the Mediterranean coast.
Egypt oil and gas downstream encompasses crude refining, product distribution, retail marketing, and bulk storage of refined petroleum derivatives including petrol, diesel, liquefied petroleum gas, and lubricant formulations with sulfur content specifications typically below 50 ppm for transportation fuels. The sector primarily converts raw hydrocarbon feedstocks into finished energy products for commercial and industrial consumption. Refining infrastructure dominates capital deployment, while distribution networks capture recurring margin pools through throughput fees. Petrol and diesel product types lead volume throughput, though LPG segments expand fastest amid residential energy transition programs. Storage capacity represents a structurally constrained bottleneck, creating premium returns for operators with coastal terminal access.
Egypt's petroleum sector regulator and the Ministry of Petroleum and Mineral Resources enforce product quality standards and environmental compliance protocols for refinery emissions and fuel specifications. The General Authority for Investment and Free Zones coordinates downstream licensing with customs and tax frameworks governing import-export operations. Stakeholders must monitor regulatory shifts around subsidy rationalization and carbon intensity benchmarks that will reshape investment prioritization across the value chain.
Market Dynamics
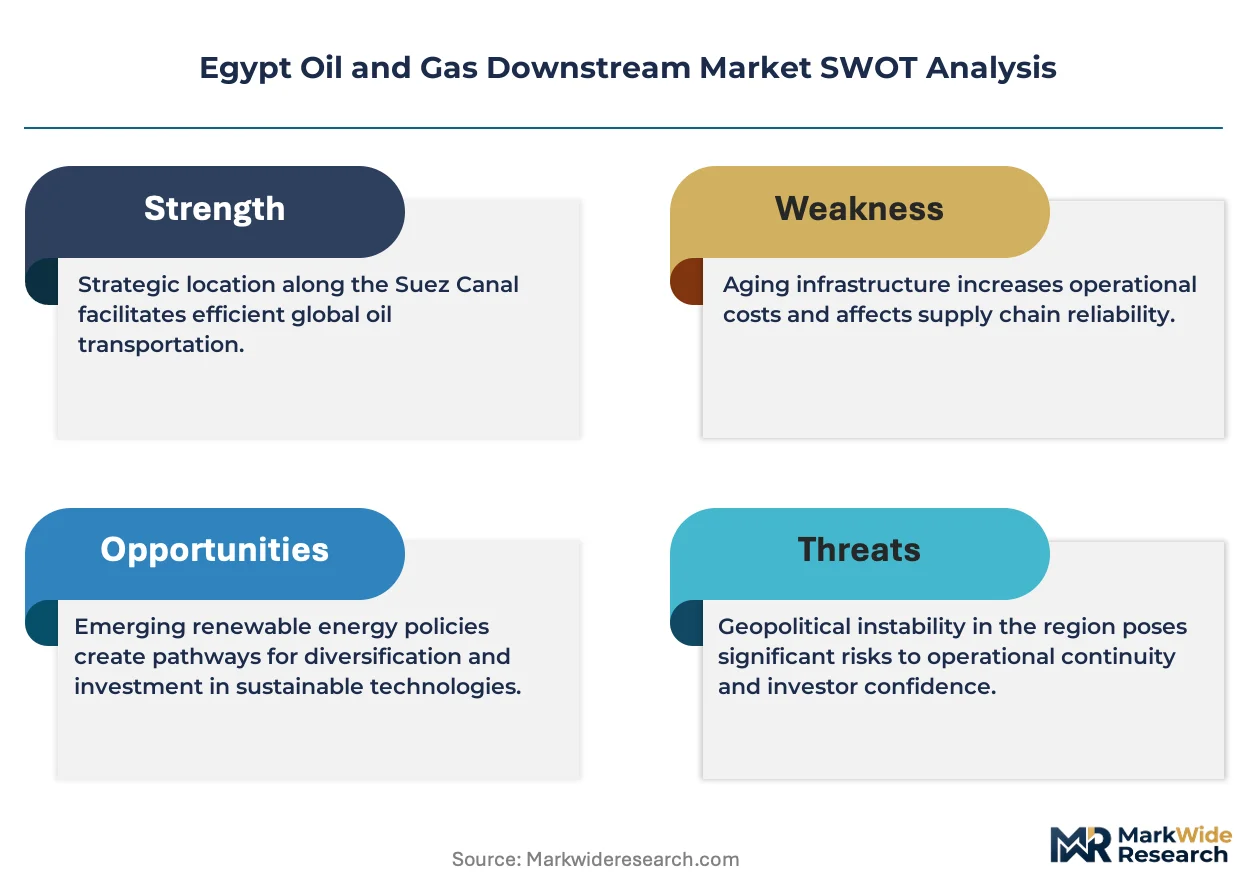
Refining capacity bottlenecks at Mediterranean coastal terminals are forcing Egyptian downstream operators to prioritize storage infrastructure over incremental distillation investment, reshaping capital allocation across the value chain.
Growth Catalysts
- Suez Canal Economic Zone clustering:Petrochemical integration projects near existing refining complexes concentrate demand for specialized storage and blending services.
- Subsidy rationalization frameworks:The Ministry of Petroleum and Mineral Resources is streamlining pricing mechanisms to attract private capital into distribution networks.
- Digital twin deployment:Integrated simulation platforms optimize crude distillation yields at Egyptian General Petroleum Corporation facilities.
Market Restraints
- Storage capacity scarcity:Coastal terminal access remains structurally constrained, creating throughput bottlenecks for imported crude and refined product movements.
- Feedstock cost volatility:Egyptian refiners face exposure to international crude price swings without full pass-through mechanisms to domestic retail markets.
- Sulfur specification compliance:Transportation fuel standards below 50 ppm require hydrocracking upgrades that strain mid-scale refinery economics.
Strategic Opportunities
- LPG residential expansion:Government energy transition programs target rural household fuel switching from biomass and kerosene.
- Mediterranean bunkering hub development:The Suez Canal corridor positions Egyptian terminals to capture marine fuel demand from international shipping lanes.
- Private terminal licensing:New regulatory frameworks enable independent storage operators to access previously restricted coastal sites.
Industry Challenges
- Process control talent scarcity:Digital refinery automation requires instrumentation specialists with hybrid mechanical-digital competencies that outpace local training pipeline output.
- Legacy system integration friction:Brownfield refineries face retrofit complexity when connecting analog distillation controls to modern distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Oil and Gas Downstream Market |
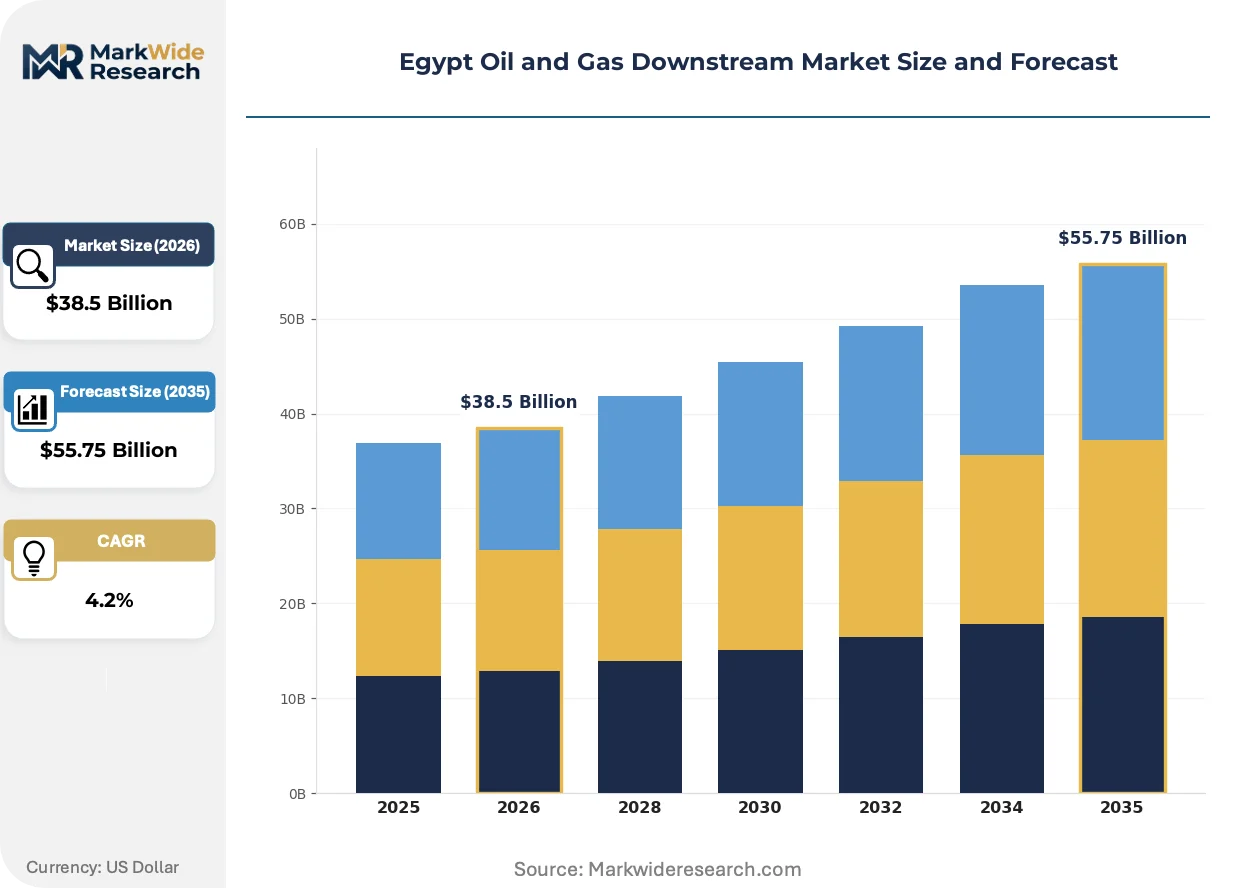
| Market Size in 2026 | $38.5 Billion |
| Market Size in 2035 | $55.75 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Refining, Distribution, Retailing, Storage Product Type: Petrol, Diesel, LPG, Lubricants Application: Transportation, Industrial Fuel, Heating, Power Generation End User: Automotive, Manufacturing, Residential, Aerospace |
| Companies Covered | Egyptian General Petroleum Corporation, Egyptian Natural Gas Holding Company, TotalEnergies, Shell, ExxonMobil Corporation, Chevron Corporation, BP, Egyptian Refining Company, Petrojet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Oil and Gas Downstream Market Shifts & Advancements
Digital instrumentation architectures are compressing traditional process control hierarchies across Egyptian refining operations. Three distinct shifts are reconfiguring competitive positioning.
Advanced hydrocracking catalyst formulations are collapsing the yield gap between high-sulfur heavy crude processing and light sweet crude economics. Mid-scale Egyptian refiners are adopting these systems to process discounted regional feedstocks. The technology is collapsing the traditional premium for complex refining configuration, enabling simpler distillation trains to compete on marginal barrel economics.
Egypt's petroleum regulator is tightening emissions monitoring protocols for refinery flaring and fugitive releases. The General Authority for Investment and Free Zones now coordinates environmental compliance with customs frameworks for imported catalysts and additives. Coastal refining complexes face the steepest compliance timelines, accelerating capital deployment into vapor recovery and continuous emissions monitoring systems.
Industrial off-takers are consolidating procurement through long-term offtake agreements with integrated storage-terminal operators. Bulk fuel distributors that previously relied on spot market purchases are locking in throughput commitments at Mediterranean coastal facilities. The shift concentrates volume through preferred terminal networks, marginalizing smaller distributors without dedicated storage access in Alexandria and Suez corridor markets.
Egypt Oil and Gas Downstream Market Segmentation
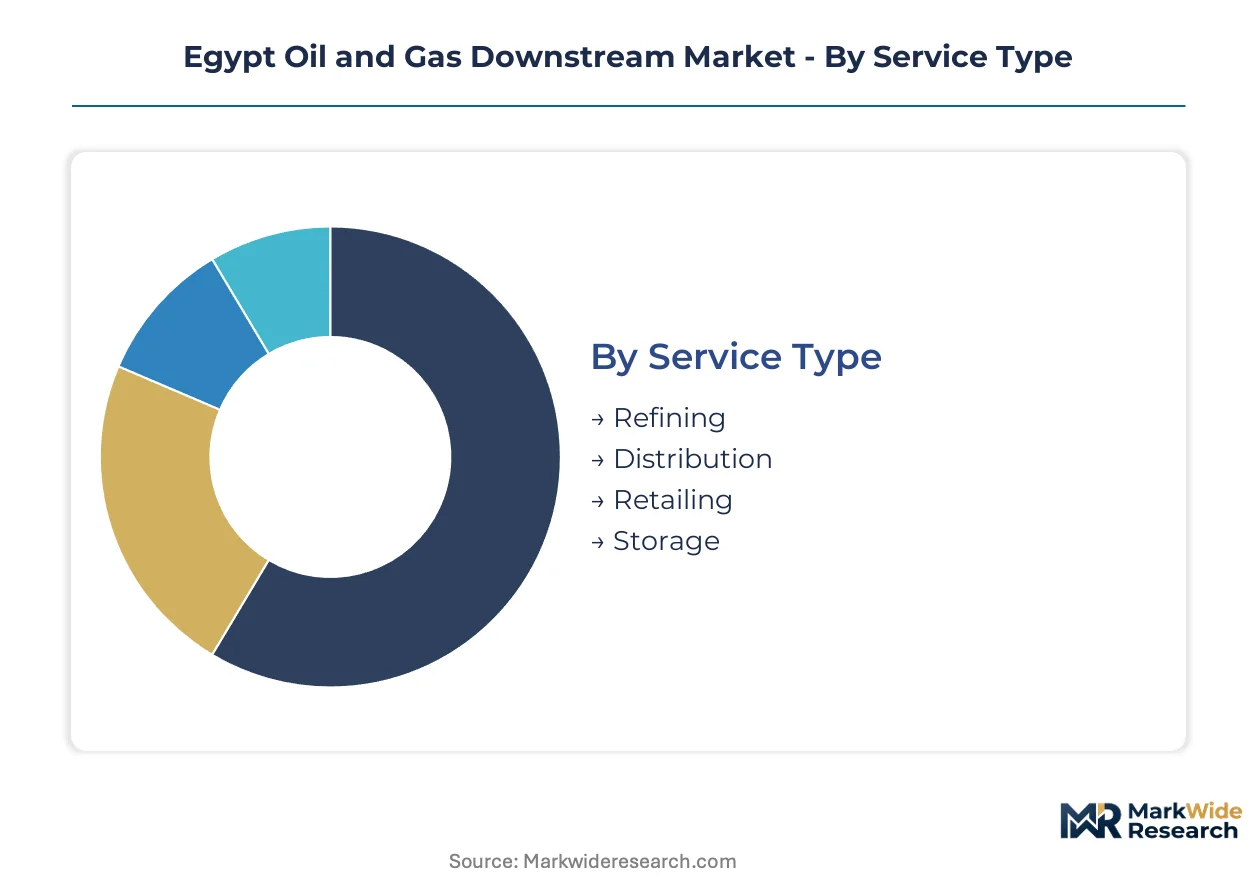
Segmentation in Egypt's downstream oil and gas market reveals how capital allocation, regulatory exposure, and margin capture vary across distinct operational layers. Each dimension—service type, product slate, application, and end-user category—exhibits divergent competitive intensity and infrastructure requirements that shape investment prioritization.
Service Type:
Mature infrastructure segments dominate throughput volumes while emerging service models capture margin expansion from regulatory liberalization.
- Refining:Crude distillation and conversion operations process feedstock into transportation fuels and petrochemical precursors. Egyptian General Petroleum Corporation facilities concentrate capacity around the Mediterranean coast, where hydrocracking upgrades address sulfur specification compliance below 50 ppm.
- Distribution:Bulk product movement through pipeline networks, rail, and trucking systems connects refining centers to consumption zones. The Suez Canal Economic Zone anchors the highest throughput corridors, with private terminal licensing reforms enabling independent operator entry previously restricted to state-controlled entities.
- Retailing:Fuel station networks and direct commercial sales deliver finished products to end consumers. Subsidy rationalization frameworks are compressing margins at price-controlled gasoline pumps while lubricant and premium product sales offer unregulated pricing flexibility.
- Storage:Terminal infrastructure for crude and refined product holding provides throughput fees and blending services. Coastal access scarcity at Alexandria and Suez corridor sites generates premium returns for operators with existing tankage positions.
Refining handles the majority of throughput; Storage is the fastest mover on share as capacity bottlenecks force capital reallocation.
Product Type:
Volume concentration and margin structure diverge sharply across fuel grades, with transportation fuels capturing scale and specialty products retaining pricing power.
- Petrol:Gasoline formulations for spark-ignition engines constitute the largest single product volume through Egyptian refineries. Demand concentrates in Greater Cairo and Alexandria metropolitan zones where automotive density exceeds national averages.
- Diesel:Compression-ignition fuel serves commercial trucking, rail, and marine applications with higher energy density per liter. Industrial off-takers in manufacturing zones are consolidating procurement through long-term offtake agreements with integrated terminal operators.
- LPG:Liquefied petroleum gas for residential cooking and heating applications expands fastest amid government energy transition programs targeting rural household fuel switching from biomass and kerosene.
- Lubricants:Engine oil and industrial fluid formulations command premium pricing based on additive packages and viscosity specifications. Blending operations cluster near Alexandria port facilities to minimize import logistics for base oil feedstocks.
Petrol and Diesel together dominate volume throughput; LPG is expanding most quickly as residential conversion programs accelerate.
Application:
End-use concentration patterns reflect Egypt's economic structure, with mobility and industrial activity driving fuel consumption while power sector demand competes with natural gas alternatives.
- Transportation:Road, rail, aviation, and marine fuel consumption absorbs the majority of refined product output. The Suez Canal corridor positions Egyptian terminals to capture marine bunkering demand from international shipping lanes.
- Industrial Fuel:Manufacturing process heat, boiler fuel, and feedstock applications in cement, steel, and chemicals production. Energy-intensive facilities in the Suez Canal Economic Zone cluster near refining complexes to minimize logistics costs.
- Heating:Residential and commercial space heating demand concentrates in Nile Delta governorates during winter months. LPG displaces kerosene in rural areas while natural gas infrastructure expansion competes in urban centers.
- Power Generation:Fuel oil and diesel for electricity production, primarily in remote areas or peak demand periods. Grid-connected generation is shifting toward natural gas and renewables, compressing this segment's growth trajectory.
Transportation handles the majority of throughput; Power Generation faces the steepest competitive pressure from fuel substitution.
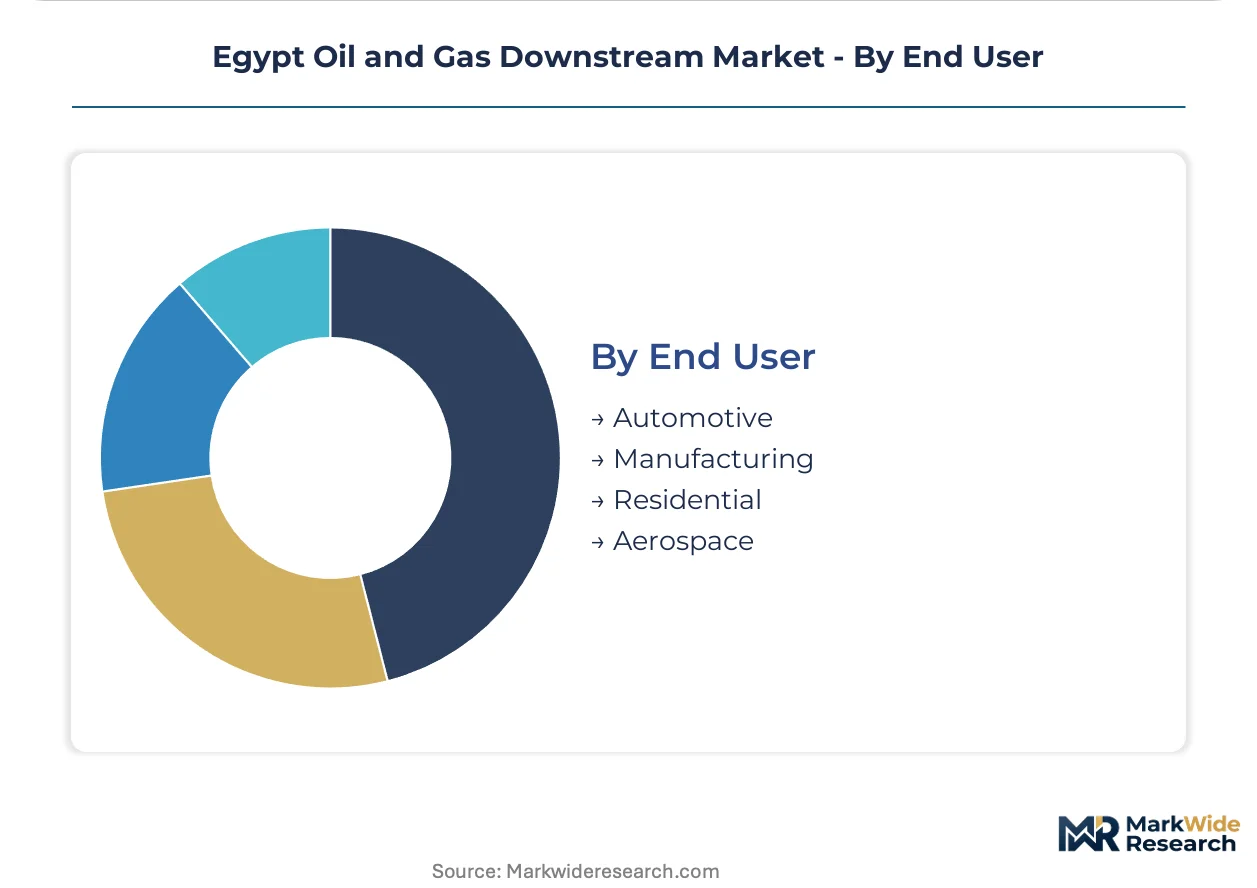
End User:
Customer concentration and procurement sophistication vary across consumer, industrial, and institutional segments with divergent price sensitivity and contract structures.
- Automotive:Private vehicle owners and commercial fleet operators purchasing through retail stations or direct commercial contracts. Cairo and Alexandria vehicle registration density drives geographic demand concentration.
- Manufacturing:Industrial facilities procuring bulk fuel through term contracts or spot market purchases. Cement and steel producers in the Suez corridor anchor the largest single-industry offtake volumes.
- Residential:Household consumers purchasing LPG cylinders or kerosene for cooking and heating applications. Government subsidy programs and energy transition initiatives reshape affordability and fuel choice in this segment.
- Aerospace:Commercial aviation fuel demand concentrated at Cairo International Airport and coastal resort destinations. Jet fuel specifications and international supply chain integration requirements limit domestic refinery participation.
Automotive handles the majority of throughput; Residential LPG conversion is climbing the fastest on policy-driven demand expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's downstream infrastructure channels refined products across North Africa and Mediterranean shipping lanes, with the Suez Canal Economic Zone serving as the primary transit hub for regional energy trade.
Greater Cairo Metropolitan Area
Automotive fuel demand concentrates in Egypt's capital region where vehicle density exceeds national averages by a factor of three. The Ministry of Petroleum and Mineral Resources enforces sulfur specifications below 50 ppm for transportation fuels sold through retail networks. Refinery product pipelines terminate at bulk terminals in Cairo's eastern industrial zones where cement and steel manufacturers consolidate procurement through long-term offtake agreements.
Alexandria Coastal Corridor
Mediterranean marine bunkering demand anchors storage infrastructure investment along Egypt's northern coastline. The General Authority for Investment and Free Zones coordinates environmental compliance protocols with customs frameworks for imported catalysts and additives. Shell maintains terminal networks at Alexandria port facilities that capture throughput fees from international shipping lanes transiting the Suez Canal.
Suez Canal Economic Zone
Petrochemical integration projects cluster near existing refining complexes to minimize logistics costs for industrial off-takers. Egypt's petroleum regulator streamlines licensing frameworks to attract private capital into specialized storage and blending services. TotalEnergies deploys hydrocracking technology at facilities positioned to process discounted regional heavy crude feedstocks.
Red Sea Governorate
LPG residential expansion programs target rural household fuel switching from biomass and kerosene in Egypt's eastern desert regions. Government energy transition initiatives subsidize cylinder distribution networks that extend beyond natural gas pipeline coverage. Coastal terminal access at Safaga and Hurghada ports enables product imports that bypass Mediterranean storage bottlenecks.
Nile Delta Industrial Belt
Manufacturing process heat demand in textiles and food processing drives diesel consumption across Egypt's northern agricultural heartland. Egyptian General Petroleum Corporation leverages digital twin platforms to optimize crude distillation yields for regional product allocation. Mid-scale refineries in the Delta corridor face retrofit complexity when connecting analog distillation controls to modern distributed control architectures.
Egypt Oil and Gas Downstream Market Competitive Landscape
On the supply side, the industry is structured around state-controlled refining capacity with selective international operator participation through joint ventures and technology licensing arrangements. Egyptian General Petroleum Corporation dominates crude processing infrastructure while specialized storage terminals attract private capital under liberalized licensing reforms. Strategic archetypes include integrated national oil companies, international majors with technology transfer agreements, and independent terminal operators exploiting coastal access scarcity. Dominant competitive moves encompass hydrocracking upgrades for sulfur compliance and long-term offtake contracting that locks in industrial volume.
Within the state-controlled tier, Egyptian General Petroleum Corporation and Egyptian Natural Gas Holding Company anchor downstream infrastructure ownership. Among international operators with Egyptian presence, TotalEnergies and Shell exemplify technology-led positioning through advanced conversion capabilities and Mediterranean terminal networks. Egyptian Refining Company occupies a position between these archetypes as a joint venture vehicle that channels private capital into domestic capacity expansion.
| Leading Market Players |
|---|
| Egyptian General Petroleum Corporation |
| Egyptian Natural Gas Holding Company |
| TotalEnergies |
| Shell |
| ExxonMobil Corporation |
| Chevron Corporation |
| BP |
| Egyptian Refining Company |
| Petrojet |
| Others |
Supply & Pricing Matrix
Regional heavy crude feedstock concentration in Iraq and Saudi Arabia directly determines where hydrocracking upgrade premiums accumulate across Egyptian refining complexes. Coastal terminal access scarcity at Alexandria and Suez corridor sites concentrates margin capture among operators with existing storage positions, forcing price differentiation between integrated and non-integrated market participants.
Pricing Analysis
Technology-generation pricing gaps separate legacy hydroskimming configurations from advanced hydrocracking installations and next-generation digital twin-integrated facilities. Three-tier pricing structure across premium low-sulfur fuels, standard transportation grades, and economy residual products dominates contract structures, with sulfur specification compliance below 50 ppm and coastal terminal access as primary price differentiation drivers. Cost compression in standard-grade diesel is intensifying because industrial off-takers are consolidating procurement through long-term offtake agreements. Manufacturing buyers in the Suez Canal Economic Zone exhibit the highest price sensitivity due to feedstock pass-through limitations, while Mediterranean bunkering customers show the least sensitivity given voyage cost minimization priorities.
Supply Chain Analysis
Contract-refining concentration at Egyptian General Petroleum Corporation facilities and Egyptian Refining Company joint ventures anchors domestic capacity deployment. Geographic supply concentration centers on Iraq, Saudi Arabia, and Libya for crude feedstocks, with specialty catalysts and hydrocracking additives drawing from Germany, the Netherlands, and the United States. Raw material dependencies rest on regional heavy crude availability, imported catalyst formulations, and LPG feedstock for residential expansion programs. Single-source vulnerability around coastal terminal access at Alexandria port generates structural risk for non-integrated distributors. Distribution runs through Mediterranean coastal storage terminals, pipeline networks to Greater Cairo, and cylinder distribution systems for rural LPG penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's downstream oil and gas market functions as a regulatory-entrenchment defensive moat, where coastal terminal licensing restrictions and state-controlled refining capacity create structural barriers that protect incumbent returns while constraining new entrant pathways.
For Market Incumbents: Entrench market position through backward integration into specialized storage and blending services at Suez Canal Economic Zone sites, while accelerating hydrocracking catalyst certification investments to maintain sulfur specification compliance below 50 ppm. Digital twin deployment at Egyptian General Petroleum Corporation facilities offers a defensive lever against emerging independent terminal operators exploiting private licensing reforms. Capacity addition in Red Sea Governorate LPG distribution networks counters biomass-to-gas switching program capture by non-integrated competitors. For New Entrants and Emerging Players: Pursue private terminal licensing opportunities at previously restricted Mediterranean coastal sites, particularly Safaga and Hurghada ports that bypass Alexandria storage bottlenecks. The most penetrable segment sits in independent LPG cylinder distribution for rural household energy transition programs, where government subsidy frameworks reduce customer acquisition friction. A go-to-market angle anchored in digital inventory management and route optimization software differentiates against state-controlled legacy distributors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed mid-scale terminal operators holding coastal access positions at Suez corridor sites. Long-term viability over the five-to-ten-year window hinges on regulatory stability around subsidy rationalization and carbon intensity benchmarking enforcement. Acquisition targets with integrated storage-terminal-offtake contract structures offer the most defensive cash flow profiles. The signal to watch is Ministry of Petroleum and Mineral Resources licensing velocity for independent coastal terminal approvals.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocracking Technology Licensing | TotalEnergies deployment at Suez facilities collapses yield gaps for discounted regional heavy crude processing. |
| Coastal Terminal Capacity Expansion | Private licensing reforms enable independent operators to capture premium throughput fees at Alexandria port. |
| Digital Twin Platform Integration | Egyptian General Petroleum Corporation optimization of crude distillation yields improves marginal barrel economics. |
| Long-term Supply Agreement Structuring | Industrial off-taker consolidation in Suez Canal Economic Zone locks in volume for integrated terminal operators. |
| LPG Distribution Network Buildout | Government energy transition programs in Red Sea Governorate accelerate rural household fuel switching from biomass. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing refinery operations directors at Egyptian General Petroleum Corporation facilities, terminal logistics managers at Mediterranean coastal sites, industrial procurement leads in Suez Canal Economic Zone manufacturing complexes, and Ministry of Petroleum and Mineral Resources regulatory affairs specialists. Secondary validation drew from Egyptian customs and trade data, General Authority for Investment and Free Zones licensing disclosures, petroleum sector environmental compliance filings, and international energy agency supply reports. Bottom-up capacity and throughput modeling triangulated against top-down macroeconomic demand projections.
Calibration approaches anchored volume and value outputs across the projection horizon through multi-scenario stress testing against crude price volatility and subsidy reform timelines. Segmentation dimensions modeled encompass service type hierarchy, product slate sulfur specifications, application concentration patterns, and end-user procurement sophistication tiers. CAGRs were derived from iterative convergence between demand elasticity estimates and supply-side capacity expansion schedules. Industry-specific forecast inputs included hydrocracking upgrade deployment timelines and private terminal licensing approval velocities.
Sensitivities concentrate around international crude price volatility, subsidy rationalization policy shifts, and coastal terminal access regulatory changes that could accelerate or delay independent operator market entry. Forecasts reflect documented assumptions regarding industrial demand growth trajectories and residential LPG conversion program penetration rates. Quarterly review of Ministry of Petroleum and Mineral Resources licensing announcements and Suez Canal Economic Zone investment commitment disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Gabon Oil and Gas Downstream Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Remote Monitoring Solutions Market
Offshore Oil and Gas
Asia-Pacific Offshore Energy Market
Offshore Oil and Gas
Brazil Oil and Gas Upstream Market
Offshore Oil and Gas
Floating Liquefied Natural Gas (FLNG) Market
Offshore Oil and Gas
Subsea Equipment Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Oil Rig Market
Offshore Oil and Gas
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market
Offshore Oil and Gas
East Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Oil and Gas Downstream Market
Offshore Oil and Gas
LNG Satellite Station Market
Offshore Oil and Gas
United Kingdom LNG Bunkering Market
Offshore Oil and Gas
Enhanced Oil Recovery Market