
 North America Industrial Boiler Market | 2026-2036
North America Industrial Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Boiler Market Intelligence
The ASME Boiler and Pressure Vessel Code (BPVC) is reorganizing market participation by setting stringent design and safety benchmarks for all manufacturers. Established incumbents like Babcock & Wilcox Enterprises, Inc. leverage their extensive engineering expertise to meet these complex certification requirements. Cleaver-Brooks, Inc. differentiates with integrated boiler room solutions, while Clayton Industries focuses on rapid-start steam generators for specific industrial applications.
An industrial boiler is a closed pressure vessel designed to produce steam or hot water at pressures typically exceeding 15 psig for process heating. These systems are fundamental for transferring heat energy in facilities like chemical processing plants and paper mills. Natural gas dominates the fuel type segment due to widespread availability, though biomass is gaining share for sustainability mandates. Among boiler types, water-tube designs serve high-pressure power generation, while fire-tube units are common in food processing.
The U.S. Environmental Protection Agency (EPA), through regulations under the Clean Air Act, imposes strict limits on emissions like NOx and SOx. Concurrently, standards from the Occupational Safety and Health Administration (OSHA) and Canada's provincial safety authorities mandate operational safety protocols. Future procurement decisions for operators will balance initial capital costs against long-term fuel efficiency and evolving environmental mandates.
Market Dynamics
The North America industrial boiler market is defined by the dual pressures of stringent environmental regulations and the operational demand for higher thermal efficiency. Compliance with EPA standards in the United States and parallel provincial rules in Canada is forcing fleet modernization.
Growth Catalysts
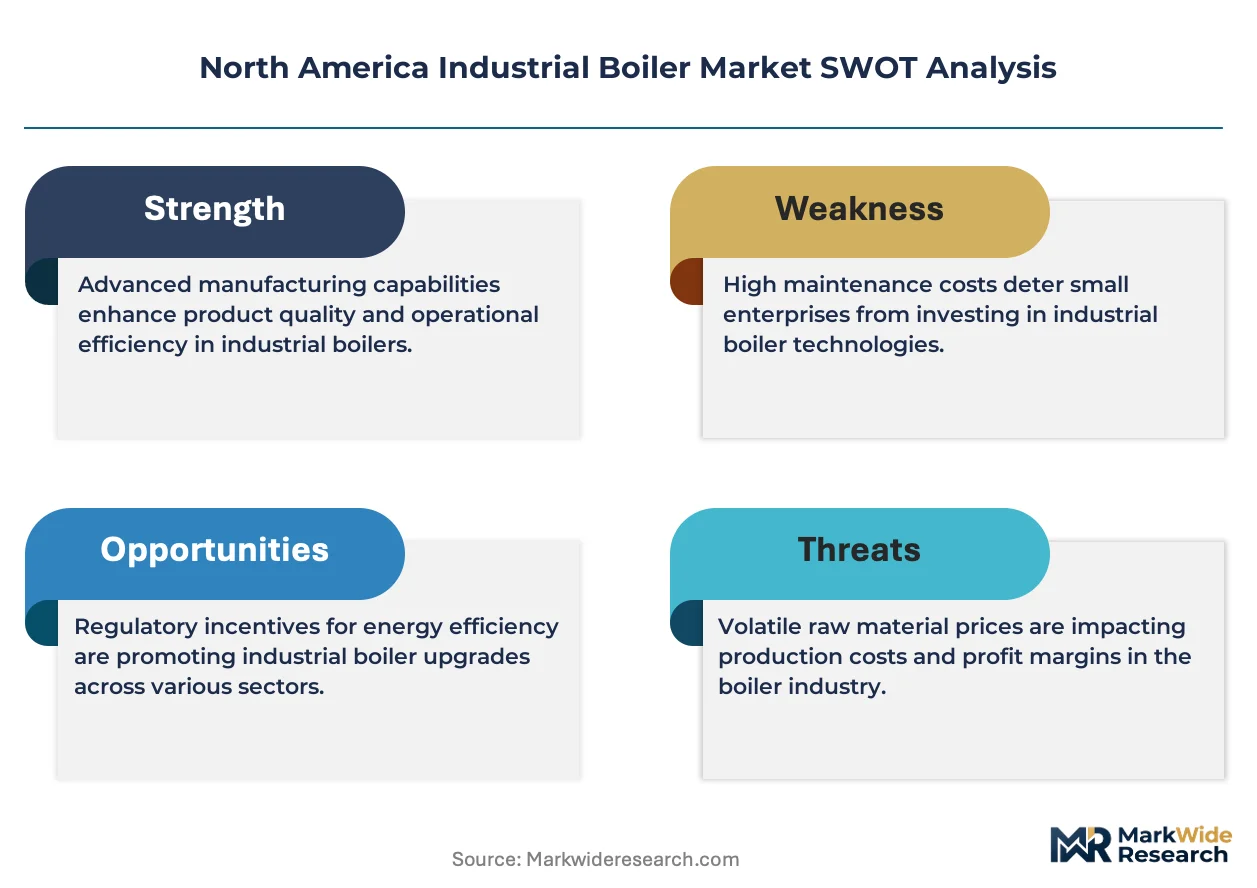
- Regulatory Mandates:The EPA's Industrial Boiler MACT rules in the U.S. compel operators to upgrade or replace older, non-compliant units, directly stimulating demand for modern, low-emission systems, particularly in the chemical and refining sectors.
- Food Processing Expansion:Growth in the food and beverage industry requires significant investment in new and upgraded steam generation capacity for processes like sterilization and cooking, favoring efficient fire-tube and packaged boiler designs.
- Fuel Diversification:Sustainability initiatives and corporate ESG goals are encouraging a shift toward biomass and waste-to-energy boiler systems, creating a distinct growth segment supported by demand for carbon-neutral heat sources.
Market Restraints
- High Capital Investment:The significant upfront cost of new industrial boiler systems, including installation and compliance with ASME BPVC standards, presents a substantial barrier for small and medium-sized enterprises, often delaying replacement cycles.
- Natural Gas Price Volatility:Dependence on natural gas as the primary fuel source exposes operators to price fluctuations, impacting long-term operational budgets and making total cost of ownership calculations less predictable for new investments.
- Customization Lead Times:Large-scale, high-pressure water-tube boilers required for power generation and heavy industrial applications involve long engineering and manufacturing lead times, slowing project execution and creating supply-side bottlenecks.
Strategic Opportunities
- Boiler Control Retrofits:A substantial opportunity exists in upgrading existing boiler fleets with advanced digital controls, IoT sensors, and automated combustion management systems to improve efficiency and meet emissions targets without full system replacement.
- District Energy Systems:The expansion of district heating and cooling networks in dense urban centers and university campuses across Canada and the northern U.S. creates new demand for large, centralized hot water and steam boiler plants.
- Electrification and Hybridization:The development of hybrid boilers that can operate on both natural gas and electricity, or fully electric boilers, offers a path for industrial decarbonization, aligning with policies like the U.S. Inflation Reduction Act.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of ASME-certified welders, boiler operators, and specialized service technicians across North America creates installation delays, increases maintenance costs, and constrains the capacity of service providers.
- Legacy System Integration:Integrating modern, digitally-native boiler control systems with older, analog plant-wide infrastructure presents significant technical challenges, often requiring complex and costly custom interface solutions.
- Compliance Burden:The administrative complexity and continuous monitoring required to document and maintain compliance with evolving EPA and OSHA regulations adds significant operational overhead for plant operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Boiler Market |
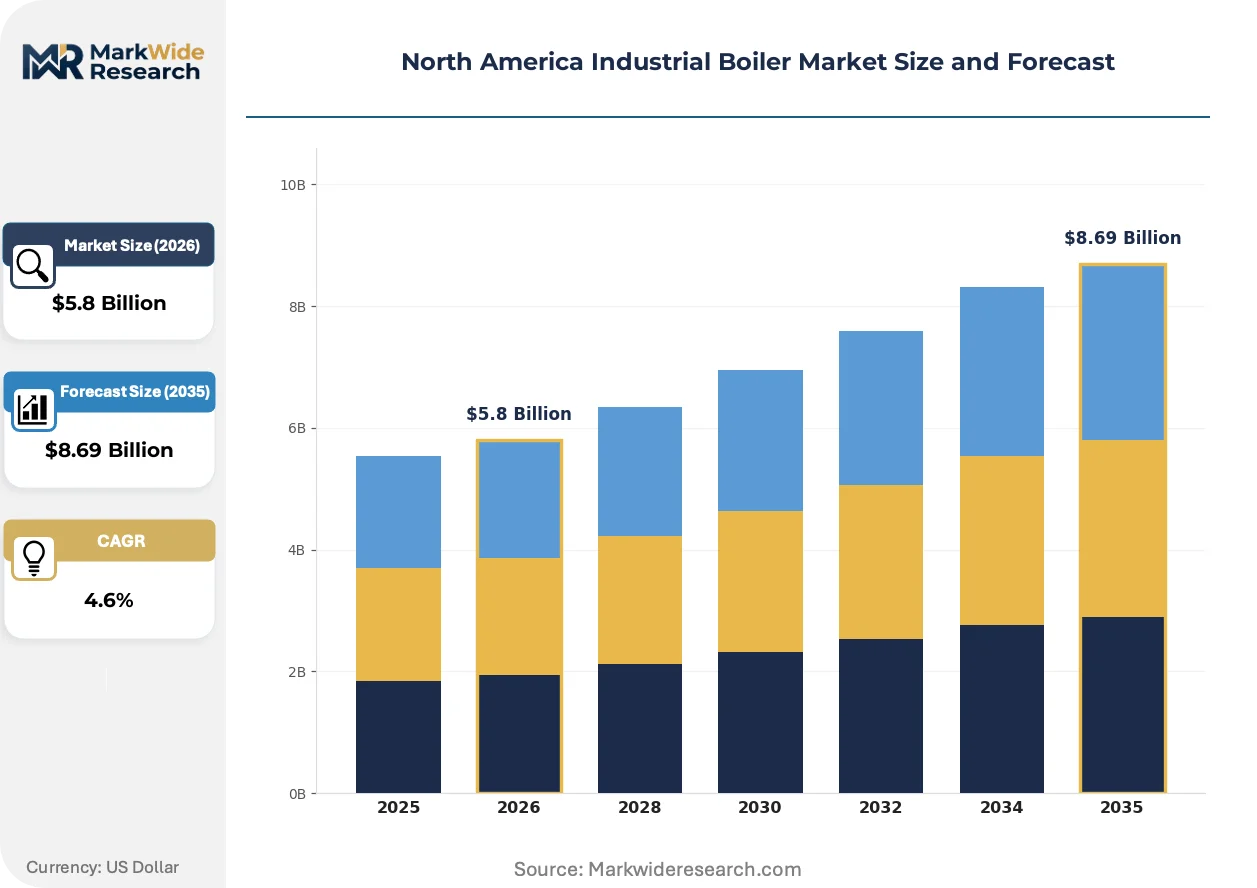
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Boiler Type: Fire Tube, Water Tube, Electric, Waste Heat, Steam Boiler Fuel Type: Natural Gas, Coal, Oil, Biomass, Propane Application: Power Generation, Chemical Processing, Food & Beverage, Paper & Pulp, Textile End User Industry: Manufacturing Plants, Oil Refineries, Pulp Mills, Food Processing Units, Textile Mills |
| Companies Covered | Clayton Industries, GE Gas Power, Babcock & Wilcox Enterprises, Inc., Sigma Thermal, Hurst Boiler & Welding Company, Miura America, The Fulton Companies, ECR International, Inc., Cleaver-Brooks, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Boiler Market Strategic Shifts & Innovations
Digitalization and sustainability are fundamentally altering industrial boiler design and operation. The focus is shifting from standalone hardware to integrated, data-driven systems that optimize energy consumption, ensure regulatory compliance, and minimize environmental impact across the asset lifecycle.
Integrated IoT sensors and predictive analytics software provide real-time monitoring of boiler performance, combustion efficiency, and component health. Chemical processing plants and refineries are the primary adopters, seeking to maximize asset uptime and prevent costly failures. This data-driven approach is displacing traditional, schedule-based maintenance with condition-based interventions that reduce unplanned outages and extend equipment life.
Implementation of the EPA's Boiler MACT standards imposes strict limits on hazardous air pollutants, including mercury and acid gases. This regulation forces operators of older coal- and oil-fired units to either invest in expensive emission control retrofits or replace the boilers entirely. The refining sector along the U.S. Gulf Coast is most affected, accelerating a transition toward cleaner-burning natural gas and advanced combustion technologies.
Facility operators are increasingly favoring modular boiler systems over traditional, large-scale, site-built installations. This approach allows for phased capacity expansion, reduces initial capital outlay, and simplifies transportation and installation, disrupting the conventional single-purchase model for large facilities. This trend is most visible in food processing and light manufacturing across the U.S. Midwest, where operational flexibility is highly valued.
North America Industrial Boiler Market Segmentation
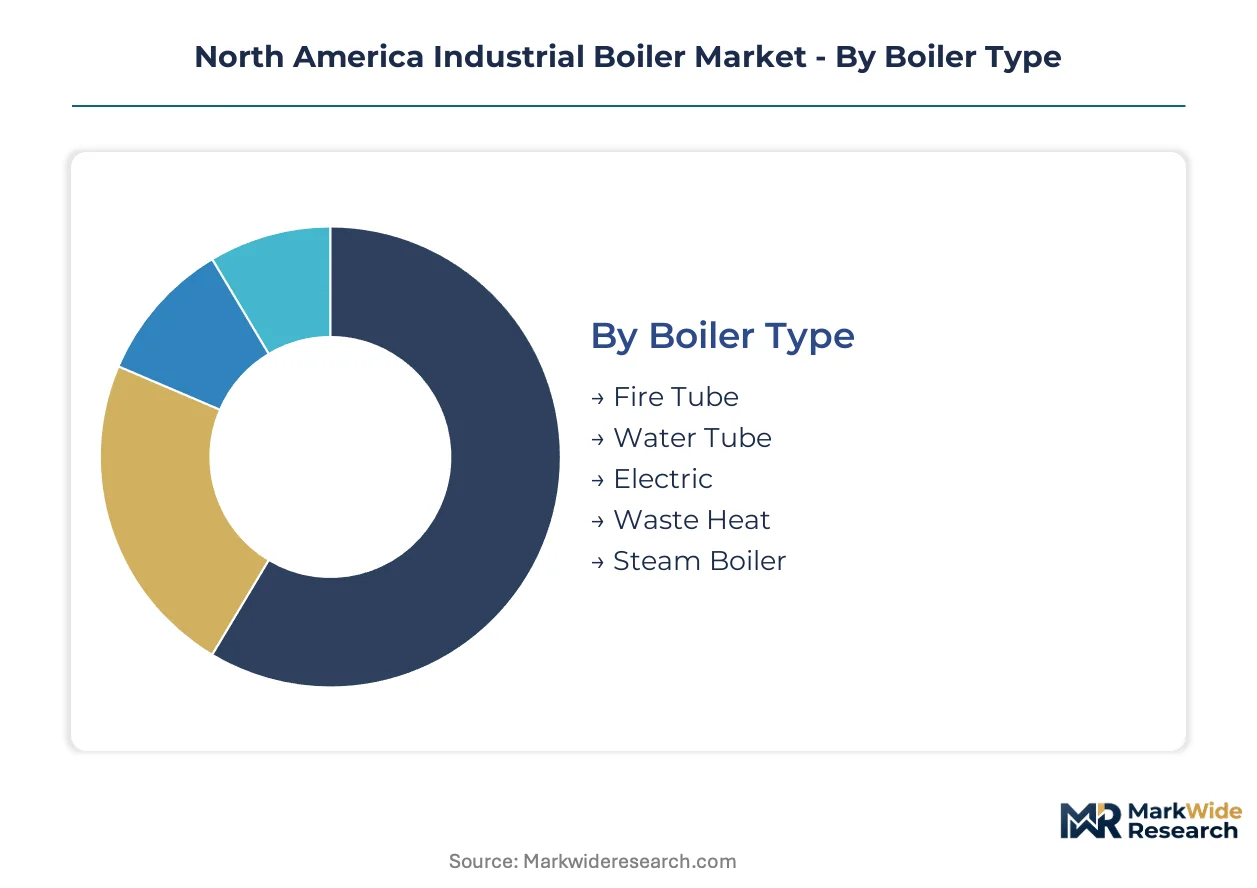
Understanding the North America industrial boiler market through segmentation reveals critical demand patterns and technological preferences across diverse industrial landscapes. This granular view allows stakeholders to identify specific growth pockets and operational challenges within distinct product types, fuel sources, applications, and end-user industries.
Boiler Type:
The distribution of boiler types across North America reflects varied operational scales and regulatory compliance needs, with some designs suited for localized commercial use and others for extensive industrial complexes.
- Water Tube:These boilers feature water circulating inside tubes heated externally by hot gases, enabling high-pressure steam generation for large-scale power plants and heavy industrial processes. Demand concentrates in the U.S. Gulf Coast region due to extensive chemical processing and refining operations requiring substantial high-pressure steam.
- Fire Tube:In these units, hot gases pass through tubes surrounded by water, producing steam or hot water at lower pressures, suitable for commercial and light industrial applications. Food processing units across the U.S. Midwest and Canada heavily utilize fire-tube boilers for sterilization and cooking processes, valuing their reliability and compact design.
- Electric:Electric boilers use resistance heating elements to generate steam or hot water, offering zero direct emissions at the point of use. These systems are gaining traction in regions with abundant renewable electricity, aligning with decarbonization goals for smaller facilities.
- Waste Heat:Waste heat boilers recover energy from hot exhaust gases or other industrial processes, converting it into usable steam or hot water. Industries like steel manufacturing and glass production integrate these systems to improve energy efficiency.
- Steam Boiler:This broad category encompasses systems specifically designed to produce steam for various industrial processes, often tailored to specific pressure and temperature requirements. Many manufacturing plants depend on steam boilers for process heating and equipment sterilization.
Fire Tube designs command the established base in diverse sectors. The steepest expansion runs through Water Tube designs, particularly for high-pressure industrial needs.
Fuel Type:
Fuel choices in North America are driven by availability, cost, and evolving environmental mandates, shaping the operational footprint of industrial boiler systems.
- Natural Gas:Natural gas boilers combust natural gas to produce heat, steam, or hot water, offering a cleaner-burning and widely available fuel source. Its widespread pipeline infrastructure across the United States and Canada makes natural gas the dominant fuel type for industrial boilers, favored for its efficiency and lower emissions compared to other fossil fuels.
- Biomass:Biomass boilers burn organic materials such as wood chips, agricultural waste, or dedicated energy crops to generate heat, contributing to renewable energy targets. Sustainability initiatives and corporate ESG goals are driving the adoption of biomass boilers, particularly in the pulp and paper industry and other sectors seeking carbon-neutral heat sources.
- Coal:Coal-fired boilers utilize pulverized coal to generate high-temperature steam, historically common in heavy industry and power generation. Strict EPA regulations in the U.S. and provincial rules in Canada are steadily phasing out coal, leading to significant fleet modernization or replacement.
- Oil:Oil-fired boilers combust fuel oil to produce steam or hot water, often used as a backup fuel or in remote locations without natural gas access. Price volatility and environmental concerns limit new installations, but existing systems remain operational in some industrial facilities.
- Propane:Propane boilers use liquid petroleum gas for heating, serving as an alternative where natural gas infrastructure is unavailable or for smaller-scale industrial operations. Its portability and cleaner combustion compared to oil make it a viable option for specific applications.
Demand for Natural Gas remains consistent across the region, while Biomass is gaining momentum as a sustainable alternative.
Application:
Industrial boiler applications are diverse, ranging from large-scale energy production to specialized process heating, each with distinct requirements for pressure, temperature, and steam quality.
- Chemical Processing:Boilers in chemical processing facilities provide high-pressure steam for reaction heating, distillation, and drying processes, demanding precise control and robust construction. The U.S. Gulf Coast, with its concentration of petrochemical plants, represents a significant demand hub for these specialized boiler systems, driven by continuous operational requirements.
- Food & Beverage:Industrial boilers in the food and beverage sector supply steam for sterilization, cooking, pasteurization, and cleaning, requiring high purity and consistent steam delivery. The expansion of food processing units across North America, particularly in the U.S. Midwest, directly fuels investment in efficient fire-tube and packaged boiler designs to meet stringent hygiene standards.
- Power Generation:Large water-tube boilers are central to thermal power plants, producing high-pressure, superheated steam to drive turbines for electricity generation. Compliance with emission standards under the Clean Air Act is forcing upgrades and replacements in existing power generation facilities across the United States.
- Paper & Pulp:Boilers in paper and pulp mills generate steam for pulping, drying, and chemical recovery processes, often utilizing biomass fuels from wood waste. These energy-intensive operations demand high thermal efficiency and continuous uptime to maintain production schedules.
- Textile:Textile manufacturing uses steam for dyeing, drying, and fabric finishing processes, requiring consistent temperatures and pressures. Smaller-scale fire-tube boilers are common in these facilities, providing reliable steam for various stages of textile production.
Industrial operations heavily rely on Chemical Processing applications, with Food & Beverage showing significant uptake in new capacity.
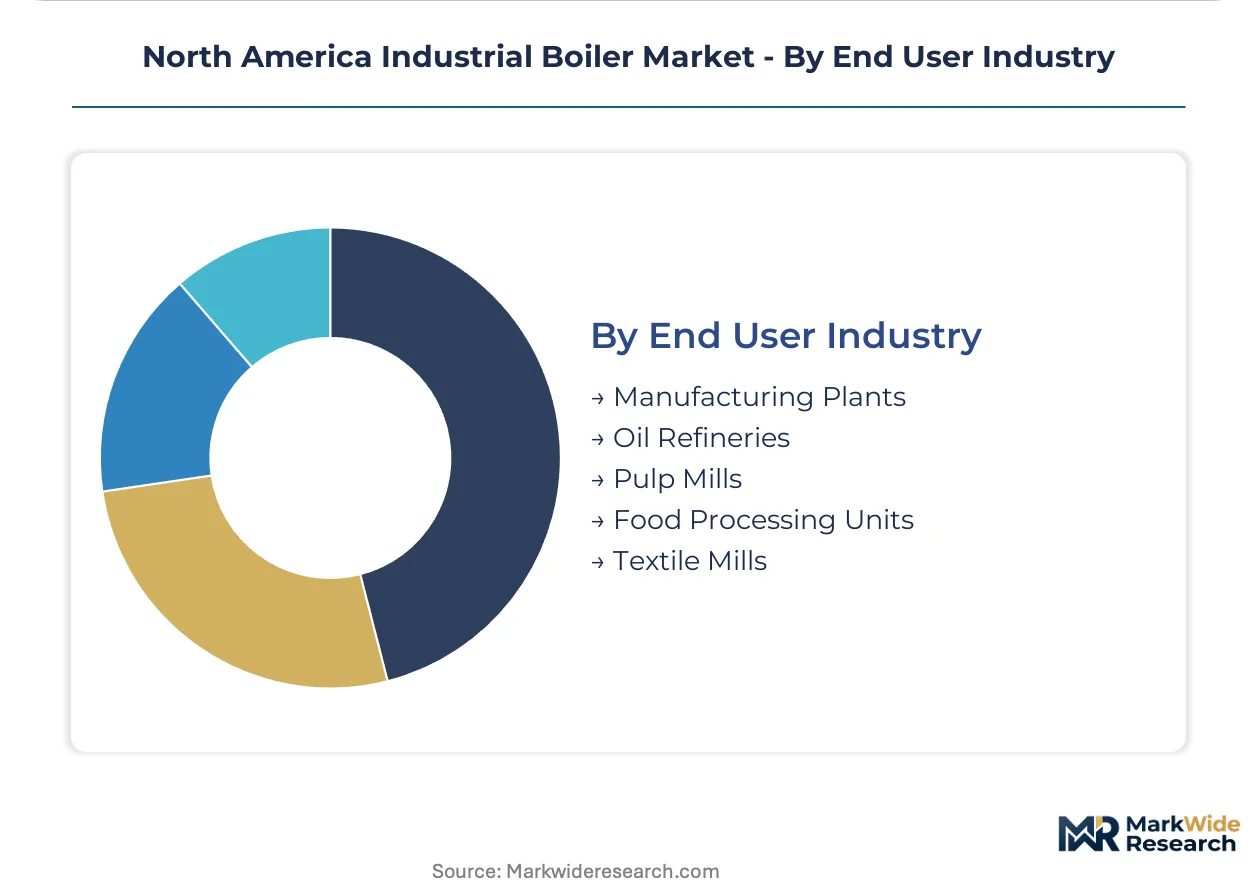
End User Industry:
The end-user industries for industrial boilers span a wide economic spectrum, each presenting unique operational demands and investment cycles for steam generation equipment.
- Oil Refineries:Oil refineries utilize industrial boilers for various processes, including crude oil distillation, catalytic cracking, and hydrogen production, requiring large volumes of high-pressure steam. Demand for new and upgraded boilers in oil refineries is concentrated along the U.S. Gulf Coast, driven by the need for continuous operation and compliance with EPA emission limits.
- Food Processing Units:These units require boilers for cooking, sterilization, drying, and sanitation, emphasizing hygienic design and reliable steam supply. Growth in the food and beverage industry directly translates into investment in new and upgraded boiler systems for food processing units across North America, particularly for efficient fire-tube designs.
- Manufacturing Plants:Diverse manufacturing plants employ boilers for process heating, humidification, and power generation, adapting to specific production needs. The widespread presence of manufacturing facilities across the U.S. and Canada ensures a consistent demand for various boiler types, from small packaged units to larger industrial systems.
- Pulp Mills:Pulp mills use industrial boilers to generate steam for wood pulping, paper drying, and chemical recovery, often integrated with biomass fuel sources. These mills represent a significant market for high-capacity boilers, driven by the energy-intensive nature of paper production.
- Textile Mills:Textile mills rely on boilers for steam in dyeing, finishing, and drying processes, requiring precise temperature control for fabric treatment. These mills typically utilize smaller to medium-sized boilers to support their manufacturing operations.
Oil Refineries drive substantial volume in the market, as Food Processing Units expand their installed base for steam generation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Policies like the U.S. Inflation Reduction Act and Canada's carbon pricing initiatives are accelerating the shift towards more energy-efficient and lower-emission industrial boiler systems across North America. These governmental efforts provide financial incentives and regulatory pressure for fleet modernization. Operators are evaluating long-term fuel efficiency against initial capital costs.
United States
The U.S. market is driven by EPA's Industrial Boiler MACT rules, which mandate significant emission reductions for existing units. The Inflation Reduction Act provides tax credits for clean energy technologies, including electric boilers. Manufacturing clusters in the U.S. Midwest are actively upgrading to comply with environmental standards.
U.S. Gulf Coast
Demand for high-pressure steam in chemical processing and refining operations defines the U.S. Gulf Coast industrial boiler market. OSHA regulations ensure operational safety in these complex facilities. Extensive petrochemical plants around Houston, Texas, continuously invest in robust water-tube boiler systems.
Canada
Canadian provincial safety authorities and carbon pricing policies are compelling industrial operators to adopt more efficient boiler solutions. Health Canada mandates specific safety protocols for industrial equipment. The oil sands region in Alberta presents a significant market for heavy-duty steam generation.
Mexico
Mexico's industrial growth, particularly in manufacturing, drives demand for reliable steam generation. The country's energy efficiency regulations encourage investment in modern boiler technologies. Industrial corridors in Nuevo León and Jalisco are experiencing increased installations of fire-tube boilers.
U.S. Midwest
Food processing expansion in the U.S. Midwest fuels substantial investment in new and upgraded steam generation capacity. State-level environmental initiatives often complement federal EPA guidelines. Large food and beverage production facilities in Illinois and Ohio are favoring efficient packaged boiler designs.
North America Industrial Boiler Market Key Industry Players
Listed leaders compete with private specialists across the full spectrum of industrial boiler solutions. The market exhibits a tiered structure, with established global manufacturers alongside niche regional providers. Strategic archetypes include integrated system providers, specialized component manufacturers, and rapid-response service firms. Companies are primarily engaging in strategic partnerships and portfolio diversification to enhance their market reach.
Among established players, Babcock & Wilcox Enterprises, Inc. represents a long-standing presence in high-capacity, engineered boiler systems for heavy industry. This company typifies the archetype of a large-scale, custom solution provider, leveraging extensive engineering expertise for complex projects. Cleaver-Brooks, Inc. exemplifies an integrated approach, offering comprehensive boiler room solutions that combine equipment with controls and services. This firm sits within the segment focused on optimizing overall system performance and efficiency for various industrial applications. Clayton Industries occupies a position as a specialist in compact, rapid-start steam generators, catering to specific industrial applications requiring quick steam availability and flexibility. These entities collectively highlight the diverse operational models within the North American industrial boiler landscape.
| Leading Market Players |
|---|
| Clayton Industries |
| GE Gas Power |
| Babcock & Wilcox Enterprises, Inc. |
| Sigma Thermal |
| Hurst Boiler & Welding Company |
| Miura America |
| The Fulton Companies |
| ECR International, Inc. |
| Cleaver-Brooks, Inc. |
| Others |
Cost & Logistics Intelligence
Electrification and biomass substitution dynamics reshape North America's industrial boiler market, simultaneously altering fuel supply geographies and influencing system pricing economics. This shift impacts investment priorities for both boiler manufacturers and industrial operators.
Pricing Analysis
ASME BPVC certification level creates the primary spread in industrial boiler pricing, reflecting stringent design and safety requirements. The dominant pricing structure is project-based, heavily influenced by customization for specific industrial applications. Pricing pressure stems from rising material costs, particularly for steel and specialized alloys, and the need to integrate advanced emission control technologies for EPA compliance. Small and medium-sized enterprises (SMEs) exhibit the highest price sensitivity, often delaying replacement cycles due to significant upfront capital investment.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized components and large boiler modules, often involve complex cross-border movements within North America. Geographic supply concentration for industrial boiler manufacturing centers in the United States and Canada, with Mexico emerging for certain components. Raw material dependencies include high-grade steel, specialized heat exchange tubes, and sophisticated control systems. Skilled labor scarcity, especially ASME-certified welders, presents a structural supply chain risk. Distribution runs through direct sales channels for large, custom projects and specialized distributor networks for packaged and modular boiler units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a substitution defense, as incumbents must navigate the growing threat of electrification and hybrid boiler systems in industrial decarbonization strategies.
For Market Incumbents: Shield core market share by deepening engineering expertise in advanced combustion technologies and integrated digital controls. Invest in modular system design to counter new entrants and address demand for flexible capacity expansion. Focus on comprehensive aftermarket service contracts and compliance support to maintain customer loyalty amidst evolving EPA and OSHA regulations.
For New Entrants and Emerging Players: Lead with differentiated, low-emission solutions targeting specific industrial applications. Penetrate the food processing and light manufacturing sectors with modular, rapid-start boiler designs that offer operational flexibility. Leverage electrification and hybrid boiler technologies, aligning with U.S. Inflation Reduction Act incentives, to create a distinct value proposition for decarbonization-focused buyers.
For Investors and Strategic Acquirers: The market sits at a modernization phase that favors technology-agnostic providers with strong regulatory compliance capabilities. Long-term viability is strong, driven by continuous industrial demand and non-negotiable environmental mandates. Target specialized firms offering advanced boiler controls, predictive analytics, or electric/hybrid boiler solutions. The signal to watch is the rate of adoption for district energy systems and industrial electrification projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Digital Controls | Enhances operational efficiency and ensures continuous compliance with stringent EPA emission standards. |
| Expand Modular Boiler System Offerings | Addresses demand for flexible, scalable steam generation, particularly in food processing units. |
| Develop Hybrid Electric-Gas Boilers | Aligns with industrial decarbonization goals, leveraging incentives from the U.S. Inflation Reduction Act. |
| Strengthen Aftermarket Service Networks | Ensures uptime and extends the lifespan of complex industrial boiler systems across North America. |
| Acquire Specialized Component Manufacturers | Secures critical supply chains for high-performance materials and advanced control system integration. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EPA reports, ASME BPVC codes, OSHA guidelines, and industry association publications. Primary interviews involved plant managers, boiler operators, and procurement leads at chemical processing plants, food processing units, and manufacturing facilities across North America. This approach ensured bottom-up and top-down triangulation for market sizing and forecasting.
The analytical framework modeled segmentation dimensions including boiler type, fuel type, application, end-user industry, and regional regulatory environment over the projection horizon. Compound annual growth rates were derived through regression analysis and validated against expert consensus. Key forecast inputs included industrial production indices, natural gas price forecasts, and regulatory compliance timelines in the United States and Canada.
The analysis sits within stated boundaries; outcomes outside unforeseen shifts in energy policy, sudden changes in commodity prices, or rapid technological disruptions would require recalibration. Forecasts reflect assumptions regarding economic stability and consistent regulatory enforcement. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Field Erected Boiler Market
Boilers
North America and Europe Electric Boilers Market
Boilers
Hydrogen Boilers Market
Boilers
Global Domestic Boilers Market
Boilers
Global Marine Boilers Market
Boilers
Boiler Control Market
Boilers
Waste Heat Boiler Market
Boilers
Biomass Boiler Market
Boilers
Utility Boiler Market
Boilers
GCC Electric Water Heater Market
Boilers
Micro Combined Heat and Power (CHP) Market
Boilers
Fuel Operated Heaters Market
Boilers
Power Boiler Market
Boilers
Fossil Fuel Fired Water Heaters Market
Boilers
Europe Combined Heat and Power Market
Boilers
North America Commercial Boiler Market