
 United Kingdom Electric Vehicle Battery Anode Market | 2026-2036
United Kingdom Electric Vehicle Battery Anode Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Electric Vehicle Battery Anode Market Insights
CE marking under the EU Battery Directive is redrawing supplier qualification requirements for anode material producers serving UK-based cell manufacturers. Nexeon leverages its silicon-composite anode technology to differentiate from conventional graphite suppliers. Umicore SA sustains its position through integrated cathode and anode material R&D operations across European research centers. SGL Carbon anchors graphite anode supply through its carbon fiber and specialty graphite manufacturing expertise.
United Kingdom Electric Vehicle Battery Anode refers to the negative electrode material in lithium-ion cells, typically comprising carbonaceous compounds such as synthetic or natural graphite with specific surface areas of 1.5–4.0 m²/g and particle sizes engineered for intercalation efficiency, whose primary function is to receive lithium ions during charging and release them during discharge to enable reversible electrochemical energy storage. Graphite retains dominant share among material types due to established supply chains and cost structures, while silicon composites represent the fastest-expanding segment as manufacturers pursue energy densities above 300 Wh/kg. Among end users, OEMs command the largest procurement volumes, though fleet operators are emerging as a concentrated demand channel as commercial vehicle electrification timelines compress.
The UK's Office for Product Safety and Standards enforces battery safety regulations aligned with UN 38.3 transport testing protocols, while the Environment Agency governs hazardous substance handling in anode manufacturing facilities under REACH-derived domestic chemical control frameworks. These regulatory layers elevate compliance costs for imported materials while creating preferential conditions for domestic production scale-up. Stakeholders must monitor how post-Brexit alignment with EU Battery Regulation carbon footprint rules reshapes material sourcing decisions and qualification timelines for UK cell factories.
Market Dynamics
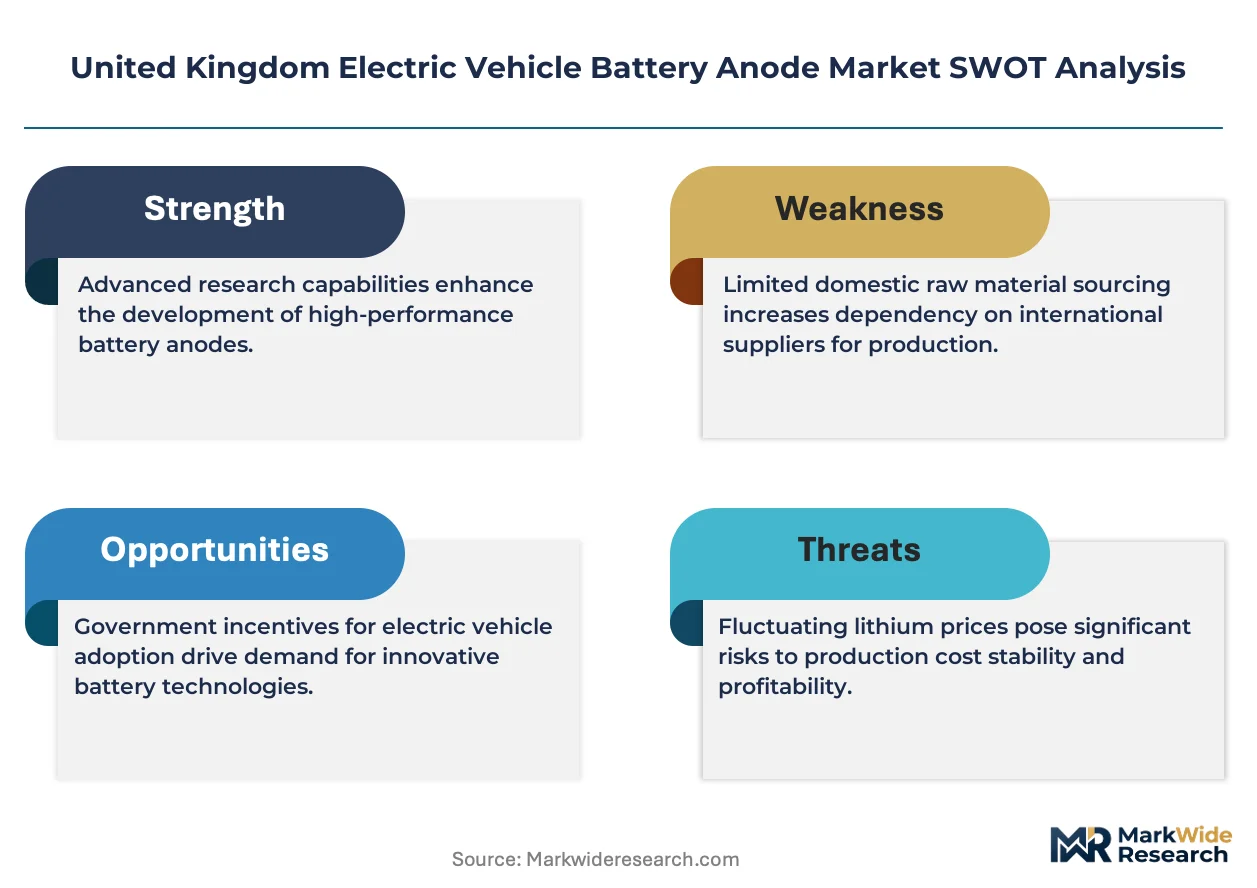
The UK Electric Vehicle Battery Anode Market is experiencing structural pressure from the 2030 internal combustion engine sales ban, which is compressing qualification timelines for domestic cell manufacturing and redirecting automotive supply chain investment toward Midlands-based production clusters.
Growth Catalysts
- Cell Gigafactory Buildout:Britishvolt's planned facility in Northumberland and AESC's Sunderland expansion are creating captive demand for anode qualification programs, pulling material suppliers into domestic co-development partnerships.
- EU Battery Regulation Carbon Footprint Rules:Post-Brexit alignment pressures are forcing UK cell manufacturers to prioritize locally sourced anode materials to minimize Scope 3 emissions in product passports.
- Silicon-Composite Material Performance:Energy density targets above 300 Wh/kg are accelerating silicon doping adoption in anode formulations, opening premium pricing tiers for advanced material producers.
Market Restraints
- Graphite Feedstock Concentration:Spherical graphite processing capacity concentrates in China, exposing UK anode manufacturers to supply disruption risks and tariff volatility under evolving trade frameworks.
- Capital Intensity of Synthetic Graphite Production:Graphitization furnaces require sustained electricity loads exceeding 3,000 kWh per tonne, compressing margins against UK industrial power pricing.
- PET Coke Environmental Scrutiny:REACH-derived domestic chemical controls are restricting needle coke availability for high-performance synthetic graphite, forcing reformulation toward lower-purity feedstocks.
Strategic Opportunities
- Scottish Renewable-Powered Production:Highlands wind and hydro resources offer sub-grid-parity electricity for energy-intensive graphitization, creating locational arbitrage for anode manufacturing.
- Second-Life Battery Material Recovery:End-of-life EV volumes from early Nissan Leaf and BMW i3 fleets are enabling pilot hydrometallurgical recovery of graphite anode material for recirculation.
- UK Battery Industrialisation Centre Partnerships:The Coventry-based UKBIC facility offers shared pilot lines for anode material validation, reducing barrier-to-entry for specialty material developers.
Industry Challenges
- Electrochemical Engineer Scarcity:UK universities produce fewer than 200 battery-specialist graduates annually, forcing cell manufacturers to recruit from European competitor pools and inflate compensation.
- UN 38.3 Certification Bottlenecks:Transport testing protocols for lithium-ion cells containing novel anode chemistries extend qualification timelines by 6-12 months, delaying revenue recognition.
- Silicon Expansion Cycling Degradation:Volume expansion exceeding 300% during lithiation causes particle pulverization, requiring binder and electrolyte co-optimization that fragments R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Electric Vehicle Battery Anode Market |
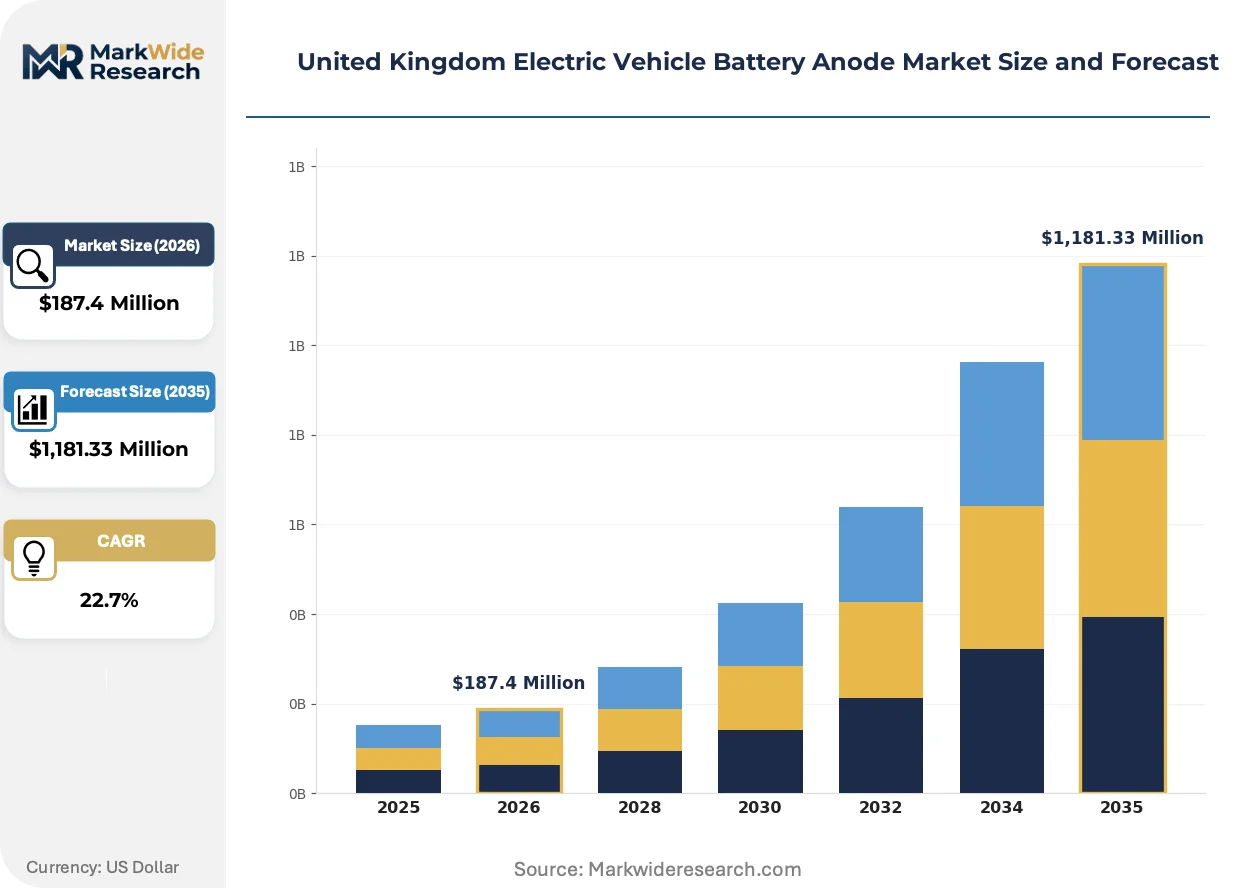
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Graphite, Silicon, Lithium Titanate, Composite Production Method: Coating, Mixing, Spherical, Strip End User: OEMs, Aftermarket Providers, Fleet Operators, Research Labs Configuration: Prismatic, Cylindrical, Pouch, Others |
| Companies Covered | Nexeon, Umicore SA, Solvay SA, BASF SE, Sumitomo Chemical Co., Ltd, Arkema SA, SGL Carbon, Resonac Holdings Corporation, POSCO FUTURE M, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Electric Vehicle Battery Anode Market Trends and Innovations
Material science advances and regulatory stringency are fragmenting the UK anode supply base into performance-tier specialists, with silicon-doped formulations and domestically qualified graphite grades diverging into separate procurement channels.
Silicon-composite anode technology is bifurcating the UK material supply landscape. Silicon nanoparticles embedded in porous carbon matrices enable energy densities approaching 400 Wh/kg, attracting premium EV platform development at Jaguar Land Rover and Lotus. Cell manufacturers are running parallel qualification tracks for 5-10% silicon loadings against conventional graphite benchmarks, compressing pricing power for undifferentiated carbon suppliers.
REACH-derived domestic chemical controls administered by the Environment Agency are tightening hazardous substance handling permits for anode manufacturing facilities. These frameworks elevate compliance costs for imported synthetic graphite precursors while creating preferential conditions for UK-based production scale-up. Midlands automotive clusters are responding by consolidating material qualification activities around UKBIC shared pilot infrastructure.
Fleet operators are displacing individual OEM procurement teams as concentrated demand channels for high-capacity anode cells. Arrival and electrified van platforms at Royal Mail are specifying silicon-enhanced anode chemistries for route-optimized energy density. This buyer concentration is compressing supplier negotiation cycles and forcing material producers to reconfigure technical service models toward fleet-specific cycle life guarantees.
United Kingdom Electric Vehicle Battery Anode Market Segmentation
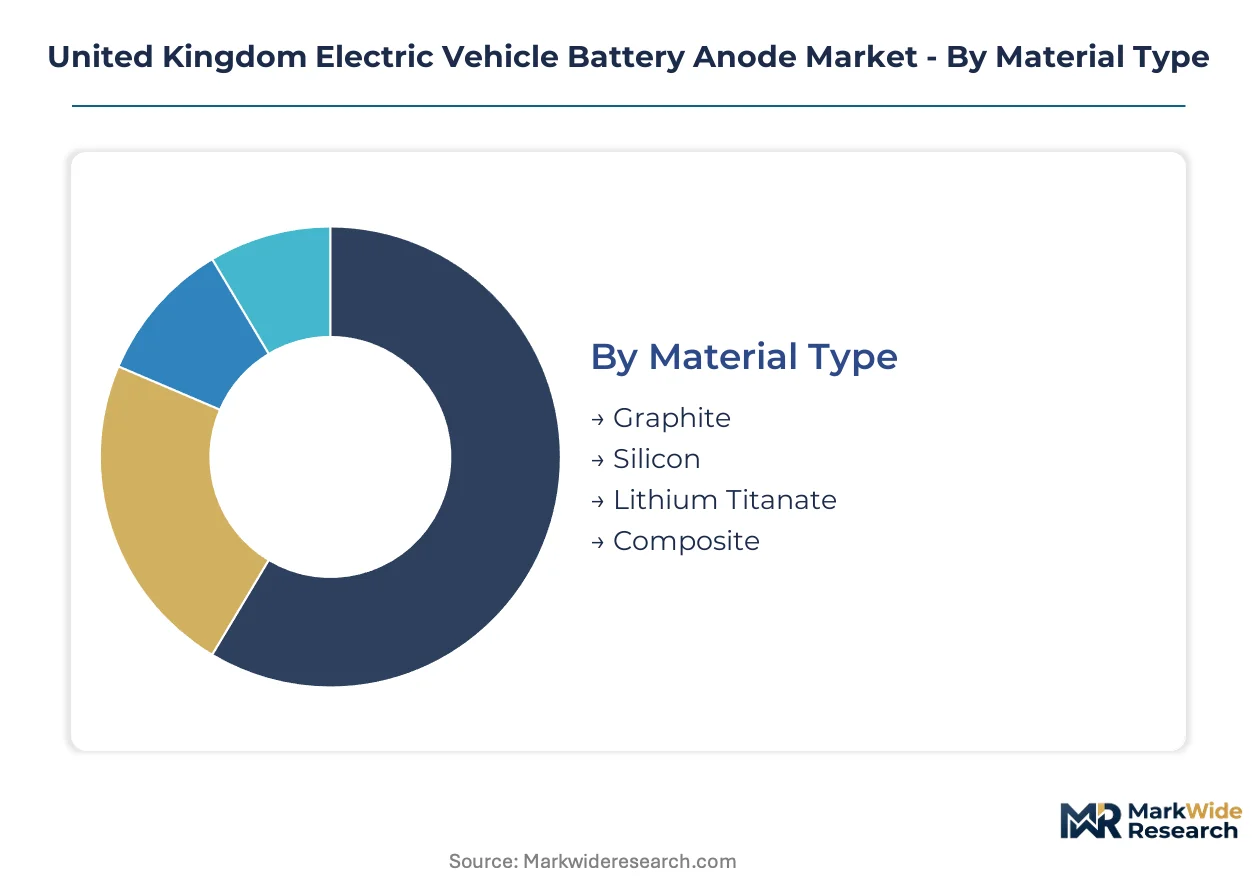
Material chemistry and cell geometry are fragmenting procurement channels across UK battery manufacturing. Suppliers must qualify against divergent performance specifications and regulatory footprints that reshape margin structures by segment.
Material Type:
Silicon-composite formulations are exerting substitution pressure on carbonaceous anodes as OEMs pursue energy density thresholds above 300 Wh/kg.
- Graphite:Synthetic and natural graphite variants dominate current cell formulations with established intercalation efficiency and cycle stability. Procurement concentrates at Britishvolt and AESC Sunderland facilities seeking qualified domestic supply chains under EU Battery Regulation carbon footprint rules.
- Silicon:Nanoparticle-embedded porous carbon matrices enable energy densities approaching 400 Wh/kg. Jaguar Land Rover and Lotus development programs are accelerating qualification timelines for 5-10% silicon loadings in premium EV platforms.
- Lithium Titanate:High-rate capability anodes serve niche applications requiring extreme fast-charging tolerance.
- Composite:Hybrid formulations blend graphite base structures with silicon or titanate additives for intermediate performance tiers.
Graphite retains volume leadership; Silicon holds the steepest expansion curve.
Production Method:
Cost tier differentiation separates capital-intensive spherical processing from lower-barrier coating operations.
- Spherical:High-temperature spheroidization of flake graphite yields optimal packing density and electrolyte wetting for automotive-grade cells. Midlands material suppliers are investing in mechanofusion capacity to serve UKBIC qualification pipelines.
- Coating:Carbon and ceramic surface modifications protect active material from electrolyte degradation. Fleet operator specifications for extended cycle life are pulling coating capacity toward commercial vehicle cell lines.
- Mixing:Slurry preparation and dry powder blending operations constitute lower-value-add processing stages with thinner margin profiles.
- Strip:Continuous roll-to-roll electrode manufacturing integrates anode material into finished cell components.
Spherical processing commands premium pricing; Coating is gaining share fastest among mid-tier suppliers.
End User:
Customer type concentration is compressing supplier negotiation leverage and forcing technical service reconfiguration.
- OEMs:Original equipment manufacturers specify anode chemistries at platform design stage with multi-year qualification horizons. Volume procurement from Jaguar Land Rover, Nissan, and emerging British EV startups anchors Midlands supply chain investment.
- Fleet Operators:Royal Mail electrification programs and Arrival van platforms are consolidating demand for route-optimized energy density. Cycle life guarantees and total cost of ownership modeling now dominate supplier selection criteria.
- Aftermarket Providers:Replacement cell and pack refurbishment services generate secondary demand for matched anode materials.
- Research Labs:UKBIC and university battery research facilities procure specialty anode formulations for next-generation chemistry development.
OEMs retain volume leadership; Fleet operators are climbing the fastest as procurement channels consolidate.
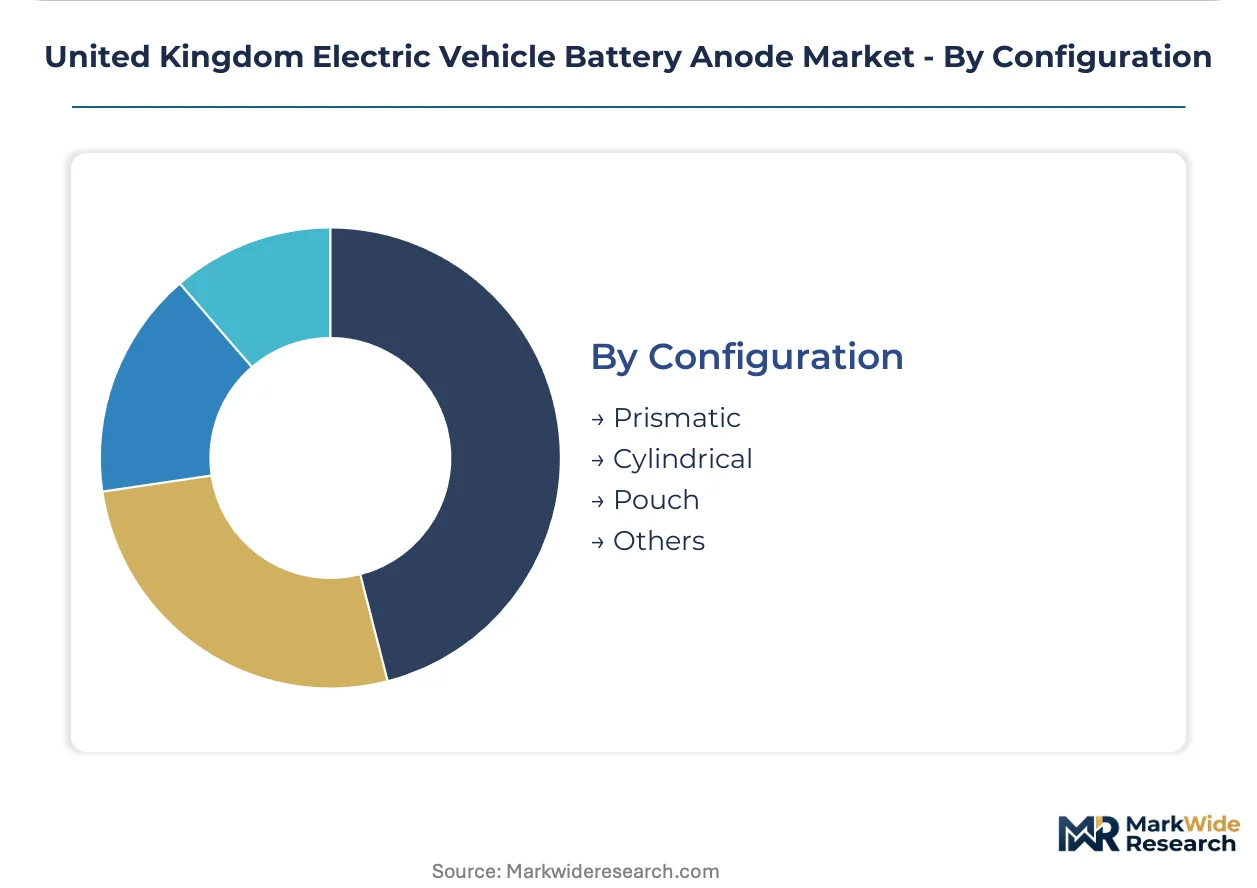
Configuration:
Cell geometry dictates electrode manufacturing equipment and anode material form factor requirements.
- Prismatic:Stacked-layer cells with aluminum housings dominate European automotive platforms. Britishvolt's planned Northumberland facility targets prismatic formats for SUV and commercial vehicle applications.
- Cylindrical:Rolled electrode configurations in steel cans offer mature manufacturing economics. AESC Sunderland expansion maintains cylindrical capacity for Nissan Leaf successor platforms.
- Pouch:Flexible polymer-foil enclosures enable packaging efficiency in space-constrained vehicle architectures.
- Others:Emerging cell formats including tabless electrode designs and solid-state configurations.
Prismatic retains volume leadership; Pouch is expanding most quickly among next-generation platform designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and OEM procurement teams concentrate demand across England's industrial corridors, with Midlands automotive clusters anchoring material qualification activity and Scottish renewable zones emerging as production cost arbitrage opportunities.
Midlands
Britishvolt's planned Northumberland facility and AESC's Sunderland expansion pull anode suppliers into co-development partnerships around Coventry and Birmingham. The UK Battery Industrialisation Centre operates shared pilot lines for material validation under UN 38.3 transport testing protocols enforced by the Office for Product Safety and Standards. Birmingham's automotive engineering base hosts silicon-composite qualification programs for Jaguar Land Rover platforms.
North England
AESC's Sunderland gigafactory expansion maintains cylindrical cell capacity for Nissan successor platforms while generating captive demand for domestic anode sourcing. The Environment Agency administers REACH-derived chemical controls for graphite processing facilities along the Tyne and Wear industrial corridor. Newcastle material suppliers invest in mechanofusion capacity to serve UKBIC qualification pipelines.
Scotland
Highlands wind and hydro resources offer sub-grid-parity electricity for energy-intensive graphitization operations, attracting anode manufacturing investment outside England's industrial power pricing zone. Scottish Enterprise coordinates battery supply chain development under UK-wide carbon footprint alignment pressures. Aberdeen's energy transition infrastructure repurposes offshore engineering capabilities toward battery material processing equipment.
South East
Lotus development programs in Hethel accelerate silicon-enhanced anode qualification for premium EV platforms targeting energy densities above 300 Wh/kg. The UK's post-Brexit alignment with EU Battery Regulation carbon footprint rules forces cell manufacturers to prioritize locally sourced materials across Thames Valley distribution networks. Oxfordshire research facilities pilot solid-state cell configurations requiring novel anode formulations.
Wales
Second-life battery material recovery operations target early Nissan Leaf and BMW i3 fleet volumes for hydrometallurgical graphite anode recirculation. The Welsh Government's battery strategy funds pilot recycling infrastructure under Environment Agency hazardous substance permits. Deeside industrial zones host downstream electrode coating operations serving Midlands cell manufacturers.
United Kingdom Electric Vehicle Battery Anode Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates and carbon-specialist manufacturers, with limited pure-play anode developers. Tiered competitive positioning separates silicon-composite technology leaders from established graphite suppliers. Strategic moves concentrate on UKBIC partnership formation and Scottish renewable-powered production siting.
Among UK-based technology developers, Nexeon occupies a position representing silicon-composite innovation archetypes, while SGL Carbon anchors carbon-specialist manufacturing expertise. Umicore SA exemplifies integrated cathode-anode R&D operations across European research centers. These three entities represent divergent competitive vectors: advanced material performance, specialty graphite supply security, and integrated battery chemistry development.
| Leading Market Players |
|---|
| Nexeon |
| Umicore SA |
| Solvay SA |
| BASF SE |
| Sumitomo Chemical Co., Ltd |
| Arkema SA |
| SGL Carbon |
| Resonac Holdings Corporation |
| POSCO FUTURE M |
| Others |
Pricing and Supply Chain Analysis
CE marking under the EU Battery Directive gates both supplier qualification timelines and price differentiation tiers for anode materials entering UK cell manufacturing. The regulatory threshold simultaneously elevates compliance costs for imported feedstocks while enabling domestic producers to command premium positioning against uncertified alternatives.
Pricing Analysis
Cost-plus contracts with needle coke and spherical graphite indexation dominate procurement between UK cell manufacturers and anode suppliers. Three-tier pricing structure across premium, standard, and economy levels separates silicon-composite formulations from high-purity synthetic graphite and lower-grade natural graphite alternatives. Cost compression in economy-tier natural graphite is intensifying because Chinese spherical processing capacity expansions are outstripping UK demand growth. Fleet operators exhibit the highest price sensitivity due to total cost of ownership modeling, while premium OEM platforms at Jaguar Land Rover and Lotus tolerate elevated silicon-anode pricing for energy density gains.
Supply Chain Analysis
China controls spherical graphite processing and needle coke refining, while South Korea and Japan anchor specialty carbon fiber precursor supply. UK anode manufacturing draws from Chinese flake graphite feedstock, Japanese carbon coating equipment, and German graphitization furnace technology. Single-source vulnerability concentrates in spherical graphite spheroidization capacity, where three Chinese producers supply over eighty percent of UK-qualified material. Distribution runs through Midlands consolidation hubs serving Britishvolt and AESC Sunderland with just-in-time electrode coating operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Material qualification services and cycle-life guarantee contracts are expanding faster than hardware margins as fleet operators and OEMs outsource electrochemical validation risk.
For Market Incumbents: Consolidate UKBIC partnership positions to lock in shared pilot line access before capacity constraints materialize. Secure backward integration into Scottish renewable-powered graphitization to escape England's industrial electricity pricing zone. Silicon-composite specialists threaten premium positioning; synthetic graphite incumbents must accelerate mechanofusion capacity additions in North East England to defend standard-tier volume. For New Entrants and Emerging Players: Lead with hydrometallurgical graphite recovery services targeting Welsh second-life battery operations, where early Nissan Leaf and BMW i3 fleet volumes create feedstock scarcity. The aftermarket refurbishment segment remains penetrable because OEMs have ceded material matching expertise to independent cell rebuilders. Partner with UKBIC for accelerated UN 38.3 certification rather than building captive testing infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silicon-composite anode development as binder and electrolyte co-optimization fragments R&D resource allocation. Five-to-ten-year viability favors acquisition targets with UKBIC validation relationships and Scottish production siting options rather than pure technology licenses. Watch for Britishvolt commissioning milestones as inflection indicators for domestic demand materialization.| Strategic Initiative | Industry Significance |
|---|---|
| UKBIC Partnership Formation | Shared pilot line access at Coventry accelerates UN 38.3 certification timelines for novel silicon-composite formulations. |
| Scottish Renewable-Powered Production | Highlands wind and hydro resources enable sub-grid-parity electricity for energy-intensive graphitization operations. |
| Silicon-Composite Qualification Programs | Jaguar Land Rover and Lotus development tracks create premium pricing tiers above 300 Wh/kg energy density thresholds. |
| Second-Life Material Recovery Infrastructure | Welsh hydrometallurgical operations target early Nissan Leaf and BMW i3 fleets for graphite anode recirculation. |
| Mechanofusion Capacity Expansion | North East England spherical processing investments serve Midlands cell manufacturers under EU Battery Regulation carbon footprint alignment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the UK battery value chain, including cell manufacturing procurement leads at Britishvolt and AESC Sunderland, anode material R&D directors at Midlands carbon specialists, fleet operator technical specification teams at Royal Mail and Arrival, and UKBIC facility engineers. Secondary validation drew from Environment Agency hazardous substance permit filings, Office for Product Safety and Standards UN 38.3 certification records, EU Battery Regulation carbon footprint draft methodologies, and UK trade customs data for graphite and needle coke imports. Bottom-up cell production forecasts and top-down automotive electrification mandates were triangulated against material intensity assumptions.
Across the analysis window, projections integrate material chemistry segmentation with end-user procurement channel dynamics and regional production cluster development. Modeled dimensions span graphite versus silicon-composite formulations, spherical versus coating production methods, OEM versus fleet operator demand archetypes, and prismatic versus cylindrical cell configurations. CAGRs were derived from installed cell manufacturing capacity ramp schedules and material yield assumptions. Key forecast inputs include Britishvolt and AESC Sunderland commissioning timelines, REACH-derived domestic chemical control evolution, and EU Battery Regulation carbon footprint rule implementation.
The analysis sits within stated boundaries; outcomes outside sustained UK automotive production volumes, stable industrial electricity pricing, or continued EU regulatory alignment would require recalibration. Forecasts reflect assumptions regarding silicon-composite cycling degradation solutions, spherical graphite supply continuity from Chinese processors, and Midlands engineering talent pipeline expansion. Recalibration cycles align with material shifts in gigafactory commissioning schedules, EU Battery Regulation final carbon footprint thresholds, and Scottish renewable capacity allocation for industrial consumers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium-Ion Stationary Battery Market
Lithium-ion Battery
Solid Electrolyte for Lithium Ion Battery Market
Lithium-ion Battery
Industrial Lithium-Ion Batteries Market
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market
Lithium-ion Battery
Lithium Battery Cells for Passenger Car Market
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Lithium Ion Capacitor Market
Lithium-ion Battery
Li Air Battery Market
Lithium-ion Battery
Lithium-Ion Battery Materials Market
Lithium-ion Battery
Next-Generation Lithium Batteries Market
Lithium-ion Battery
Lithium and Lithium Ion Battery Electrolytes Market
Lithium-ion Battery
Large Capacity Lithium Battery Packs Sales Market
Lithium-ion Battery
Automotive Lithium-Ion Battery Cell Market
Lithium-ion Battery
United States Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Lithium Polymer Battery Market
Lithium-ion Battery
Lithium-Sulfur Battery Market