
 Fuel Operated Heaters Market | 2026-2036
Fuel Operated Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Operated Heaters Market Foresight
The EU Green Deal's transport decarbonization framework is shifting demand toward higher-efficiency diesel and gasoline heater systems that minimize cold-start emissions and idle fuel burn. Webasto SE leverages its integrated thermal management portfolio to dominate OEM supply contracts across European truck manufacturers. Eberspächer Group anchors its position through deep R&D investment in compact burner architectures for hybrid-electric commercial vehicles. Espar Products Inc specializes in North American aftermarket distribution, controlling service networks that sustain replacement part revenue streams.
Fuel operated heaters are self-contained combustion appliances that draw hydrocarbon fuel from a vehicle's main tank or dedicated reservoir to generate thermal energy via flame-type or catalytic burners, typically achieving thermal outputs between 1 kW and 30 kW for cabin or equipment warming. These units serve critical functions in commercial trucking, marine vessels, and off-highway machinery where engine-dependent heating wastes fuel, accelerates wear, or fails during shutdown periods. Diesel heaters lead product type demand due to fuel availability parity with commercial vehicle fleets and established service infrastructure, while infrared configurations capture premium positioning in construction equipment where rapid spot-heating of operator zones reduces total energy draw. Marine applications represent the fastest-growing segment as ship operators face tightening port emissions rules that penalize main-engine idling for thermal loads.
The EPA's heavy-duty vehicle emissions standards and the EU F-Gas Regulation shape product development trajectories by limiting allowable combustion byproducts and refrigerant-based alternatives, respectively. Germany's KBA enforces type-approval protocols that govern heater safety certification for road-legal installation, while ISO 13766 sets electromagnetic compatibility baselines for marine-deployed units. Stakeholders must monitor evolving zero-emission zone declarations in major freight corridors, as these spatial restrictions will force decisions between advanced combustion efficiency investments and accelerated transitions to electric auxiliary heating architectures.
Market Dynamics
Idling reduction mandates across freight corridors are compressing payback periods for diesel-fired auxiliary heaters, while hybrid-electric powertrain proliferation forces burner architecture miniaturization that challenges established thermal output benchmarks.
Growth Catalysts
- EU Green Deal transport decarbonization:The framework mandates cold-start emission reductions that diesel-fired pre-heaters directly address, accelerating OEM specification for Euro VI-compliant commercial vehicles.
- Port emissions enforcement:Marine operators face penalties for main-engine idling that fuel-operated heaters circumvent, driving specification of ISO 13766-certified units in coastal shipping lanes.
- Catalytic burner advancement:Platinum-palladium catalyst architectures now achieve sub-60-second ignition sequences that construction equipment operators demand for rapid cabin warming cycles.
Market Restraints
- Platinum group metal cost volatility:Catalytic burner substrates depend on palladium and rhodium inputs whose price spikes compress manufacturer margins and destabilize long-term supply contracts.
- Electric auxiliary heating substitution:Battery-electric commercial vehicle platforms eliminate combustion-based thermal management entirely, eroding addressable market scope in zero-emission freight corridors.
- German KBA type-approval duration:Safety certification protocols for road-legal heater installation extend development timelines by 8-14 months, delaying product launches.
Strategic Opportunities
- India commercial vehicle fleet expansion:The PLI scheme for automotive component manufacturing creates localized production incentives for compact diesel heaters serving domestic truck assembly.
- Hybrid-electric compatible architectures:Burners drawing 12V/48V electrical systems for ignition and control integration capture specification in mild-hybrid commercial platforms.
- Telematics-enabled predictive maintenance:Connected heater diagnostics bundled with fleet management software create recurring revenue streams through service network subscriptions.
Industry Challenges
- Combustion engineering talent scarcity:Specialized expertise in compact flame-type burner design concentrates among aging technical workforces in Germany and Japan, constraining R&D expansion.
- Electromagnetic compatibility certification:ISO 13766 testing for marine-deployed units requires capital-intensive anechoic chamber investments that smaller manufacturers cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Operated Heaters Market |
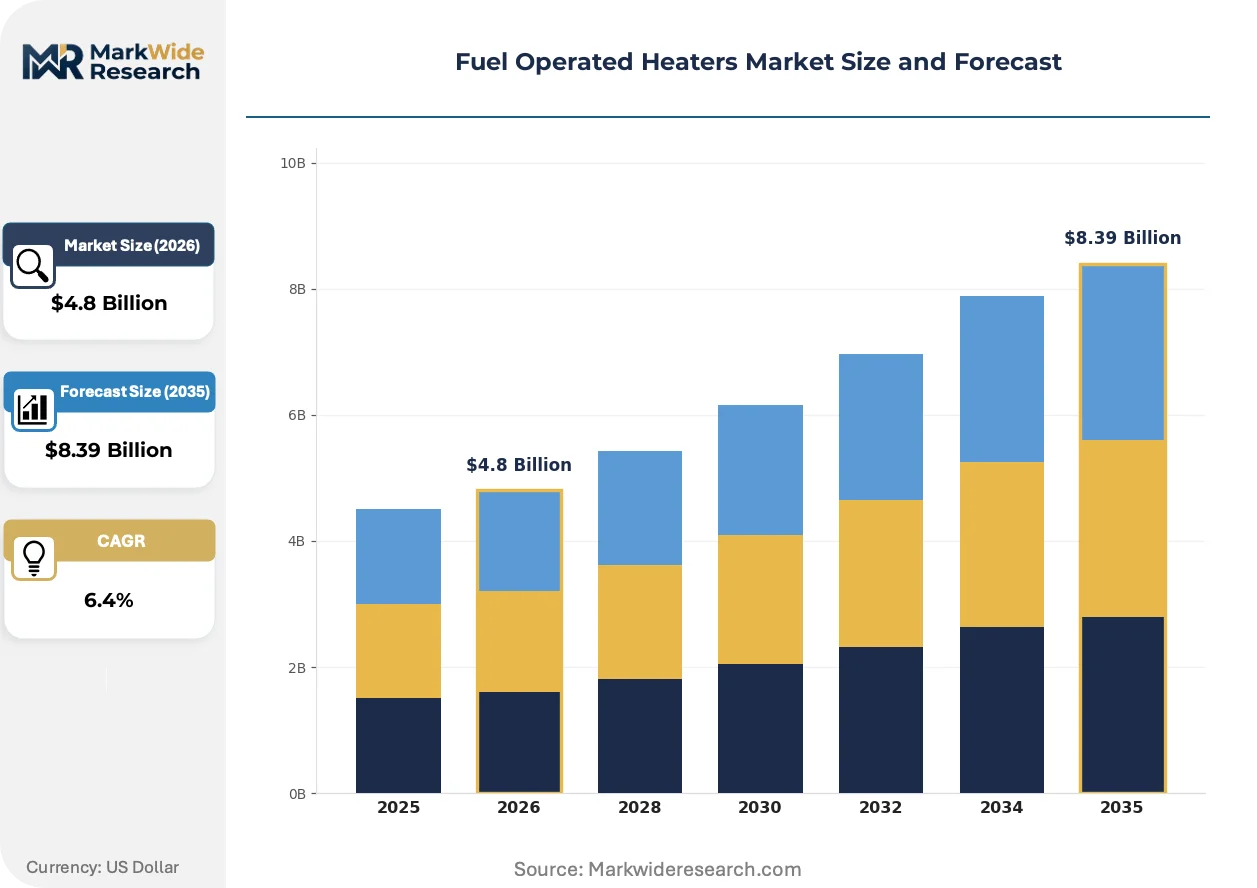
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Heaters, Diesel Heaters, Gas Heaters, Paraffin Heaters, Catalytic Heaters Fuel Type: Diesel, Gasoline, Propane, Kerosene, Natural Gas Application: Commercial Vehicles, Marine Vessels, Construction Equipment, Agricultural Machinery, Emergency Shelters End User: Vehicle Manufacturers, Marine Operators, Construction Companies, Agricultural Enterprises, Disaster Relief Agencies |
| Companies Covered | Webasto SE, Eberspächer Group, Espar Products Inc, Proheat Products Inc, Thermo King Corporation, Truma Gerätetechnik GmbH & Co. KG, Planar Marine & Truck Air Heaters Ltd, Autoterm LLC, VVKB Technology Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Operated Heaters Market Shifts & Advancements
Digital thermal management integration is compressing the traditional separation between cabin heating and powertrain temperature control, forcing component suppliers to reposition around system-level architecture rather than standalone appliance sales.
Compact catalytic diesel burners with integrated particulate filters are unifying emission control and thermal generation within single housings. European truck manufacturers specify these units for Euro VI Step E compliance. The convergence is unifying supplier tiers as exhaust after-treatment specialists acquire heater engineering capabilities.
The EPA's heavy-duty vehicle emissions standards now incorporate cold-start CO2 measurement windows that penalize engine-dependent heating. Manufacturers respond with fuel-operated pre-heaters that eliminate main-engine warm-up cycles. Long-haul freight operators in the United States face the steepest compliance penalties and show the fastest specification rates.
Fleet procurement departments now bundle heater specification with telematics platform selection, compressing the traditional equipment distributor channel. Direct OEM-to-fleet contracts displace aftermarket installation networks. This pattern concentrates in Germany's Stuttgart-Munich automotive supplier corridor where integrated thermal management portfolios dominate competitive positioning.
Fuel Operated Heaters Market Segmentation
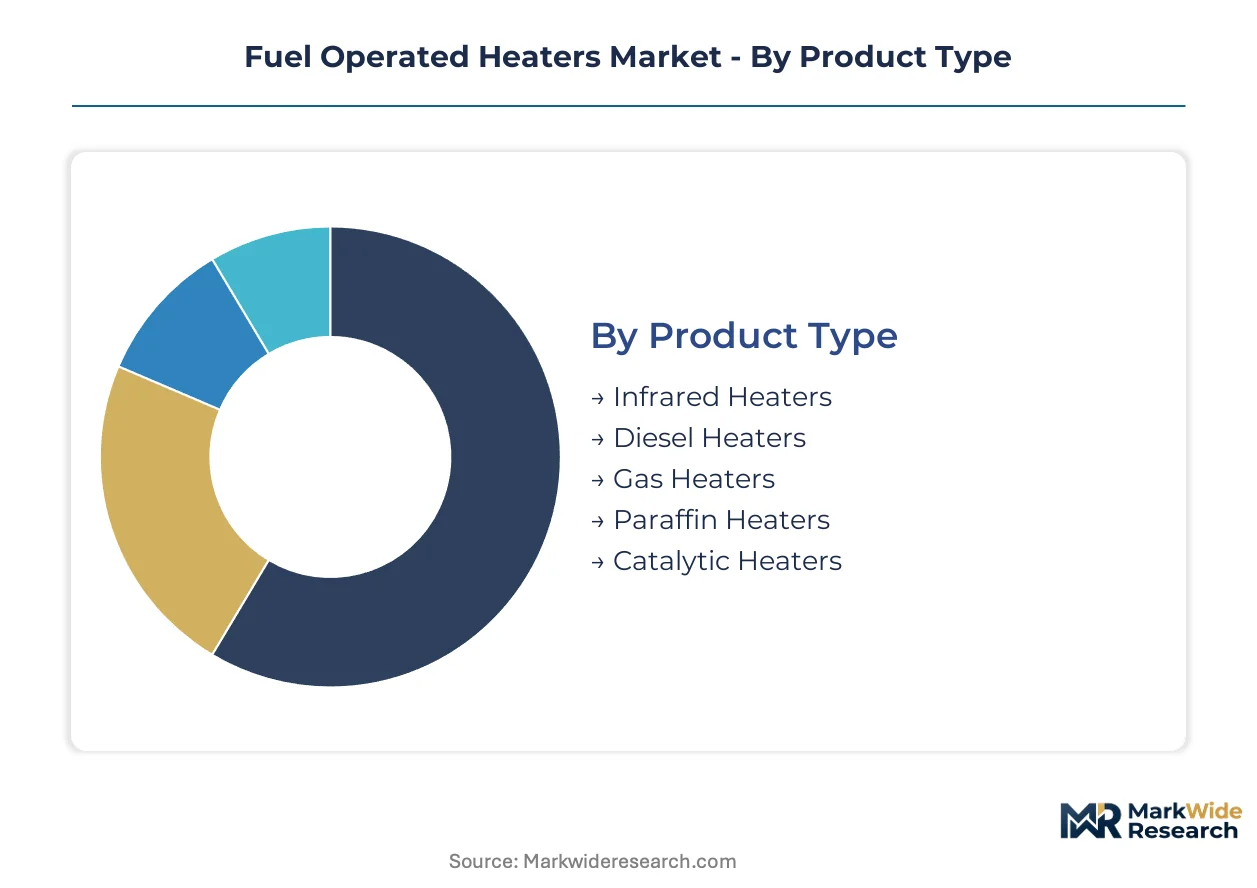
Segmentation in fuel operated heaters reveals how thermal output specifications, fuel availability, and regulatory constraints fragment demand across incompatible use cases. Suppliers must configure burner architectures, emission controls, and service networks to match the operational intensity and duty cycles of each vertical.
Product Type:
Supply concentration clusters around diesel-fired units due to fuel infrastructure parity with commercial fleets, while catalytic architectures attract R&D investment for emission-sensitive applications.
- Diesel Heaters:Flame-type burners achieving 1-30 kW thermal output draw fuel directly from vehicle main tanks. Demand concentrates in Germany's Stuttgart-Munich corridor where Webasto and Eberspächer anchor OEM supply contracts for Euro VI-compliant commercial vehicles.
- Catalytic Heaters:Platinum-palladium substrates enable sub-60-second ignition without open flames. Marine operators along coastal shipping lanes specify these units to circumvent port emissions penalties for main-engine idling.
- Infrared Heaters:Radiant heat configurations serve construction equipment where rapid spot-warming of operator zones reduces total energy draw.
- Gas Heaters:Propane and natural gas variants target stationary applications with dedicated fuel infrastructure.
- Paraffin Heaters:Compact units address emergency shelter deployment where fuel logistics prioritize shelf stability over energy density.
Today's leader: Diesel Heaters. Tomorrow's challenger: Catalytic Heaters.
Fuel Type:
Cost tier differentiation separates premium low-sulfur diesel formulations from economy kerosene alternatives, with infrastructure availability determining viable options in remote deployments.
- Diesel:Low-sulfur formulations dominate commercial vehicle integration due to tank-sharing compatibility and established service networks.
- Gasoline:Spark-ignition burners serve light-duty applications where fuel system modifications remain minimal.
- Propane:Liquefied petroleum gas configurations target stationary heating in construction site offices and temporary facilities.
- Kerosene:High-energy-density fuel powers compact units for disaster relief agencies operating beyond established fuel infrastructure.
- Natural Gas:Pipeline-connected systems serve fixed installations with continuous thermal demand and utility access.
Diesel maintains installed base dominance. Natural Gas climbs fastest where pipeline infrastructure expands.
Application:
Volume concentration in commercial vehicles reflects fleet procurement scale, while marine applications show steepest expansion trajectory under port emissions enforcement.
- Commercial Vehicles:Long-haul trucking fleets specify auxiliary heaters to comply with idling reduction mandates across freight corridors. The EPA's heavy-duty emissions standards accelerate specification rates in the United States.
- Marine Vessels:Coastal shipping operators face tightening port emissions rules that penalize main-engine idling for thermal loads. ISO 13766 certification requirements filter supplier participation.
- Construction Equipment:Off-highway machinery demands rapid cabin warming cycles to minimize operator downtime in cold-weather operations.
- Agricultural Machinery:Seasonal duty cycles favor durable burner architectures with extended maintenance intervals.
- Emergency Shelters:Disaster relief deployment requires portable units with simplified fuel logistics and rapid field setup.
Commercial Vehicles anchor current revenue. Marine Vessels gain share fastest under regulatory pressure.
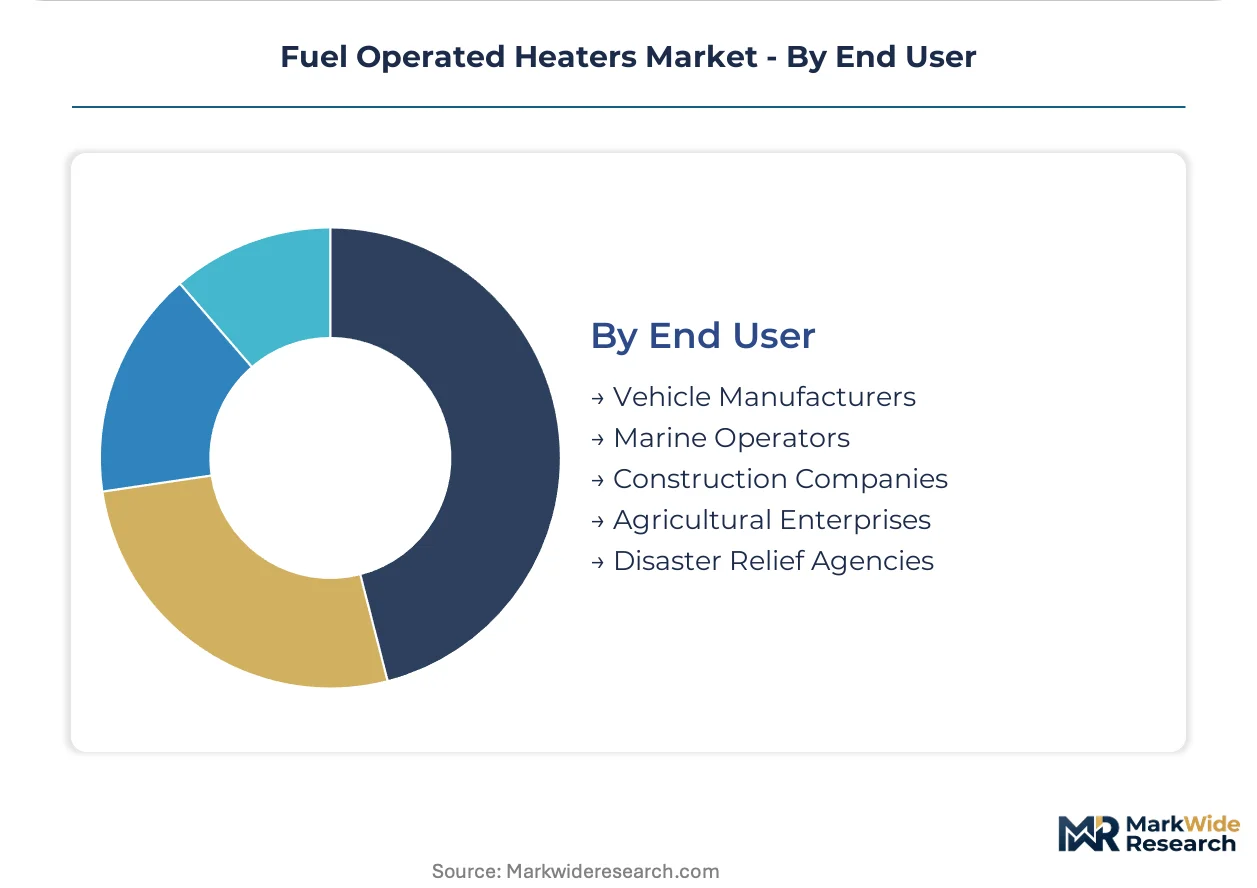
End User:
Customer type determines procurement channel structure, with vehicle manufacturers integrating at OEM tier and marine operators sourcing through specialized distributors.
- Vehicle Manufacturers:OEM specification decisions concentrate thermal management procurement within Germany's automotive supplier corridor. Direct contracts displace traditional equipment distributor channels.
- Marine Operators:Ship owners and coastal freight companies demand ISO 13766-certified units with electromagnetic compatibility validation for onboard electronics.
- Construction Companies:Project-based procurement favors rental and leasing models over capital equipment purchase.
- Agricultural Enterprises:Seasonal cash flow patterns drive financing structures aligned with harvest cycles.
- Disaster Relief Agencies:Government and NGO procurement prioritizes interoperability standards and multi-fuel compatibility.
Vehicle Manufacturers dominate specification authority. Marine Operators expand procurement autonomy fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering heritage established the fuel operated heater industry during post-war commercial vehicle expansion, with Stuttgart and Munich emerging as the original design centers for auxiliary thermal systems. This technical foundation diffused across North American trucking corridors and Asian manufacturing hubs, creating distinct regional specialization patterns.
Germany
Commercial vehicle OEMs along the Stuttgart-Munich corridor specify integrated thermal management systems for Euro VI-compliant truck platforms. The KBA enforces type-approval protocols that extend development timelines by 8-14 months, filtering supplier participation to established engineering houses. Eberspächer Group anchors R&D investment in compact burner architectures for hybrid-electric platforms from its Esslingen headquarters.
United States
Long-haul freight operators face EPA heavy-duty emissions standards incorporating cold-start CO2 measurement windows that penalize engine-dependent heating. The idling reduction mandates across interstate freight corridors compress payback periods for diesel-fired auxiliary heaters. Espar Products Inc controls aftermarket distribution networks sustaining replacement part revenue streams from its Minnesota base.
China
Domestic truck assembly expansion drives specification of cost-optimized diesel heaters for fleet operators serving inland logistics corridors. The MIIT enforces GB standards for vehicle auxiliary systems that align with dual carbon goals for transport decarbonization. Zhengzhou and Chongqing manufacturing clusters concentrate burner component fabrication for both domestic consumption and export assembly.
India
Commercial vehicle fleet expansion under the PLI scheme for automotive component manufacturing creates localized production incentives for compact diesel heaters. The BIS certification framework governs thermal appliance safety for road-legal installation across state transport authority jurisdictions. Tamil Nadu and Maharashtra assembly plants integrate auxiliary heating for export-oriented truck platforms serving Middle Eastern and African markets.
Japan
Specialized combustion engineering expertise concentrates among aging technical workforces in Nagoya and Tokyo metropolitan areas, constraining R&D expansion for next-generation burner architectures. METI industrial policy supports precision manufacturing capabilities for compact flame-type systems serving construction equipment OEMs. Yokohama-based marine suppliers navigate ISO 13766 electromagnetic compatibility requirements for coastal shipping specifications.
Fuel Operated Heaters Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and thermal output precision, with OEM supply contracts commanding 40-60% price premiums over aftermarket equivalents. The vendor base organizes into three strategic archetypes: integrated thermal management portfolios serving vehicle manufacturers, specialized marine distributors controlling ISO-certified service networks, and regional fabricators capturing price-sensitive fleet replacement cycles. Dominant competitive moves include backward integration into burner component manufacturing and telematics platform bundling to displace traditional equipment distributor channels.
Among German engineering houses, Webasto SE and Eberspächer Group occupy positions exemplifying the integrated portfolio archetype, with GmbH and SE structures reflecting long-standing corporate forms serving European OEM specification channels. Espar Products Inc represents the North American aftermarket specialization model, with its Inc. suffix indicating US corporate organization focused on service network density rather than manufacturing scale. Chinese private limited structures including VVKB Technology Co., Ltd and Autoterm LLC anchor the cost-optimized fabrication tier, with geographic identifiers in corporate names pointing to Zhengzhou and regional manufacturing clusters respectively.
| Leading Market Players |
|---|
| Webasto SE |
| Eberspächer Group |
| Espar Products Inc |
| Proheat Products Inc |
| Thermo King Corporation |
| Truma Gerätetechnik GmbH & Co. KG |
| Planar Marine & Truck Air Heaters Ltd |
| Autoterm LLC |
| VVKB Technology Co., Ltd |
| Others |
Supply & Pricing Matrix
Backward integration into platinum-palladium catalyst substrate manufacturing anchors premium-tier pricing power for German engineering houses serving Euro VI-compliant OEM contracts, while outsourced burner component fabrication in Chinese manufacturing clusters compresses margins for cost-optimized fleet replacement suppliers. This structural divergence in supply control directly determines which competitors command 40-60% price premiums over aftermarket equivalents.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the competitive landscape by certification complexity and thermal output precision. OEM supply contracts with KBA type-approval command substantial premiums over uncertified aftermarket installation, while volume-scale fleet procurement in North American trucking corridors extracts concessions through telematics bundling. Cost compression in the economy tier intensifies because Chinese fabricators absorb palladium price volatility through thin-margin component exports. Construction equipment operators show least price sensitivity due to rapid spot-heating productivity gains, whereas disaster relief agencies prioritize multi-fuel interoperability over unit cost.
Supply Chain Analysis
Specialized combustion engineering talent scarcity in Nagoya and Tokyo metropolitan areas constrains R&D expansion for Japanese manufacturers serving construction equipment OEMs. Manufacturing gravity centers on Germany's Stuttgart-Munich corridor for precision burner architectures, China's Zhengzhou and Chongqing clusters for cost-optimized diesel heater fabrication, and Minnesota-based distribution for North American aftermarket service networks. Platinum group metal supply draws from South African and Russian mining operations, creating single-source vulnerability for catalytic burner substrates. Distribution runs through direct OEM-to-fleet contracts that displace traditional equipment distributor channels in European commercial vehicle specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in telematics-enabled service subscriptions and hybrid-electric compatible burner architectures, justified by fleet procurement departments bundling heater specification with predictive maintenance platforms.
For Market Incumbents: Cement specification authority through captive supply of platinum-palladium catalyst substrates and ISO 13766 electromagnetic compatibility certification investments. Electric auxiliary heating substitution in zero-emission freight corridors threatens addressable market scope, requiring accelerated development of 12V/48V ignition-integrated burner architectures for mild-hybrid commercial platforms. For New Entrants and Emerging Players: Capture procurement autonomy expansion among marine operators facing port emissions enforcement along coastal shipping lanes. India's PLI scheme for automotive component manufacturing creates localized production incentives for compact diesel heaters serving domestic truck assembly, with BIS certification providing regulatory entry. Target ISO 13766-certified service network partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for specialized marine distributors controlling ISO-certified service networks because electromagnetic compatibility testing requirements filter supplier participation to capital-intensive engineering houses. Long-term viability hinges on combustion efficiency investments versus accelerated transitions to electric auxiliary heating architectures in declared zero-emission zones. Watch for zero-emission corridor declarations in major freight lanes as the inflection indicator warranting portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Connected heater diagnostics bundled with fleet management software create recurring revenue streams through service subscriptions. |
| Catalytic Burner Miniaturization | Compact platinum-palladium architectures capture specification in mild-hybrid commercial vehicle platforms requiring 12V/48V integration. |
| ISO 13766 Certification Investment | Electromagnetic compatibility validation filters supplier participation in marine-deployed units serving coastal shipping operators. |
| Backward Integration into Catalyst Substrates | In-house production of platinum-palladium components insulates margins from raw material price volatility. |
| Hybrid-Electric Compatible Architecture Development | Burners drawing low-voltage electrical systems for ignition control capture OEM specification in Euro VI Step E compliance. |
Research Methodology
Bottom-up commercial vehicle and marine vessel modeling reconciled against top-down burner component manufacturing tracking forms the analytical core of this study. Primary interviews with fleet procurement managers, marine operations directors, OEM thermal platform engineers, and aftermarket service network heads combined with secondary validation from EPA heavy-duty emissions filings, EU Green Deal transport decarbonization protocols, KBA type-approval registries, and ISO 13766 certification databases. Triangulation across these sources ensures supply-side shipment data aligns with demand-side specification patterns.
Historical trendline analysis of thermal output specifications and fuel type adoption across commercial trucking, marine shipping, and off-highway machinery established baseline penetration rates. Segmentation modeling incorporated product type, fuel configuration, application vertical, and end-user procurement channel dimensions across the projection horizon. CAGRs derived from regression analysis of idling reduction mandate implementation timelines and hybrid-electric powertrain proliferation curves, with platinum group metal price volatility and zero-emission zone declarations serving as scenario-weighting inputs.
Platinum group metal cost spikes, accelerated electric vehicle platform deployment, and German KBA type-approval timeline extensions are the dominant revision risks that could compress or extend forecast outputs. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and fleet replacement cycle timing. Material deviation in palladium supply stability or zero-emission corridor declaration pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Europe Combined Heat and Power Market
Boilers
Coal-Saving Combustion-Supporting Agent Market
Boilers
Boiler Combustion Chamber Market
Boilers
Gas Fired Boilers Market
Boilers
Steam Boiler Market
Boilers
Micro Combined Heat and Power (CHP) Market
Boilers
Industrial Boiler MRO Market
Boilers
Gas Condensing Boiler Market
Boilers
Advanced Utility Boilers Market
Boilers
Europe Residential Boiler Market
Boilers
North America Commercial Boiler Market
Boilers
Fire Tube Industrial Boiler Market
Boilers
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market
Boilers
US Commercial Boiler Market
Boilers
GCC Electric Water Heater Market
Boilers
Industrial and Residential Heating Market