
 Netherlands Combined Heat and Power Market | 2026-2036
Netherlands Combined Heat and Power Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Combined Heat and Power Market Analytics
Greenhouse operators and district heating cooperatives are redrawing the buyer landscape for Dutch CHP systems. Siemens AG leverages its gas turbine portfolio to anchor large-scale utility projects across the Randstad. Eneco competes through integrated energy service models that bundle heat supply with grid balancing services. BDR Thermea Group BV specializes in compact boiler-turbine packages tailored to commercial building retrofits in Amsterdam and Utrecht.
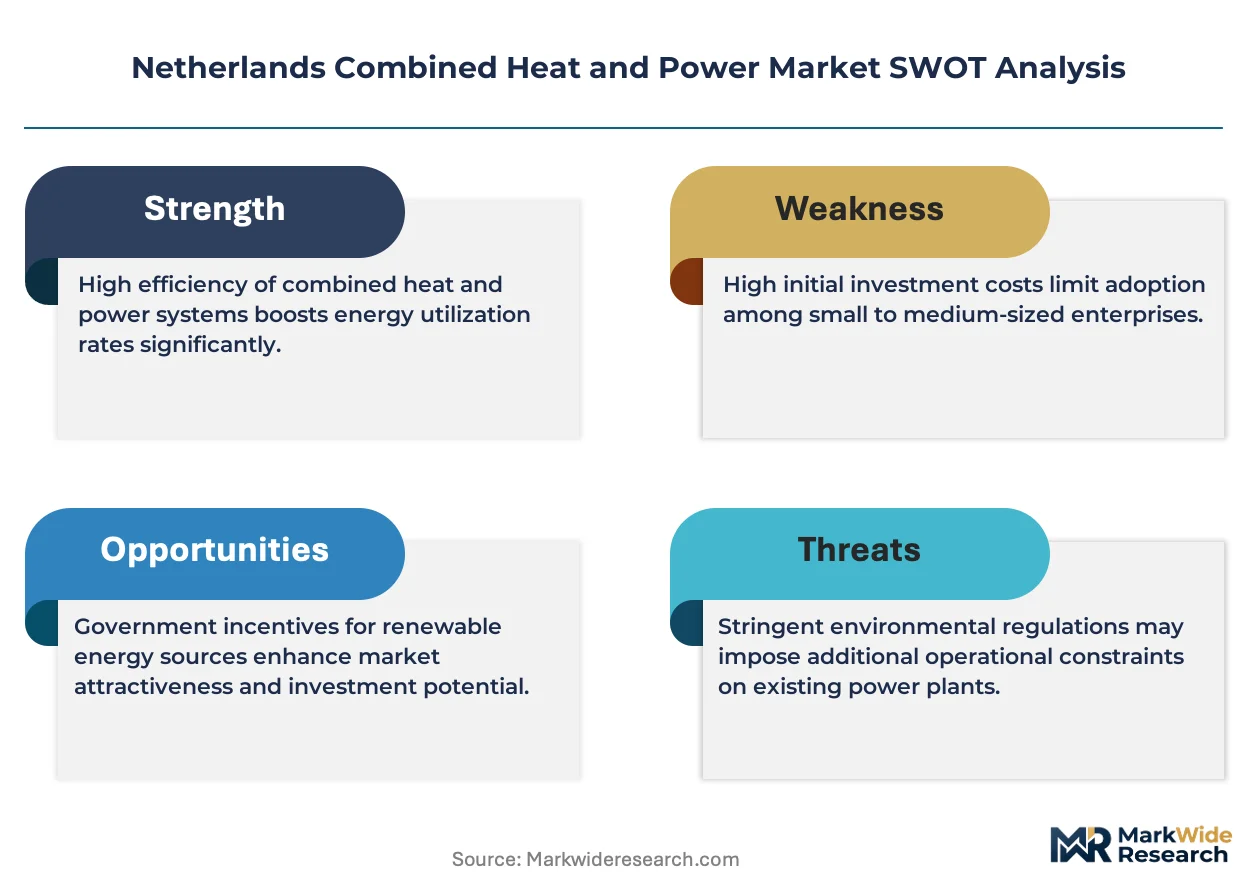
Combined heat and power denotes the simultaneous generation of usable thermal energy and electrical power from a single fuel source, typically achieving total system efficiencies of 75-90% through recovery of exhaust heat for space heating, process steam, or absorption cooling. The technology serves industrial decarbonization targets and grid stability needs by displacing separate boiler and power plant operations. Gas turbine systems dominate utility-scale installations given their hydrogen blending readiness, while micro-CHP units gain traction in residential buildings as net-zero retrofit requirements tighten. Reciprocating engines sustain margin pools in industrial process heat applications where load-following flexibility commands premium pricing.
The Netherlands Enterprise Agency (RVO) administers the SDE++ subsidy scheme that tilts project economics toward renewable and low-carbon CHP configurations. The Dutch Emissions Authority (NEa) enforces CO2 performance standards under the EU Emissions Trading System that penalize standalone fossil heat generation. The EU F-Gas Regulation restricts refrigerant choices in absorption cooling trigeneration systems, pushing equipment redesign toward natural working fluids. Stakeholders must track hydrogen infrastructure rollout timelines and carbon border adjustment mechanisms to time capital commitments on next-generation CHP assets.
Market Dynamics
The Netherlands Combined Heat and Power Market is being fundamentally restructured by the government's accelerated phase-out of natural gas extraction from the Groningen field, which forces industrial and commercial thermal users toward hydrogen-ready cogeneration assets before pipeline infrastructure fully matures.
Growth Catalysts
- SDE++ subsidy scheme:The Netherlands Enterprise Agency channels capital toward renewable and low-carbon CHP configurations, improving project IRRs for greenhouse operators and district heating cooperatives.
- Greenhouse horticulture clusters:Westland and Aalsmeer growers deploy gas engine CHP systems to secure baseload heat and power while monetizing grid balancing services.
- Hydrogen blending readiness:Gas turbine manufacturers are engineering fuel-flexible systems that accept 30% hydrogen injection, future-proofing assets against the Dutch natural gas transition timeline.
Market Restraints
- Natural gas price volatility:Input fuel costs for CHP operators fluctuate with TTF hub pricing, compressing operating margins for heat-only business models.
- Grid interconnection queues:Utility-scale CHP projects face 18-24 month delays for grid synchronization approvals from regional transmission operators.
- Heat pump substitution:Electric compression heat pumps achieve comparable efficiency for low-temperature applications, threatening micro-CHP residential penetration.
Strategic Opportunities
- Port of Rotterdam hydrogen hub:Industrial CHP operators can secure offtake contracts with emerging electrolyzer clusters for 100% hydrogen fuel switching by 2030.
- Data center thermal loads:Hyperscale facilities around Amsterdam seek dedicated CHP supply for both electricity and absorption cooling, creating premium pricing pools.
- Warmtenet 2.0 framework:Municipal heat network concessions mandate renewable heat quotas, opening procurement channels for biomass and biogas CHP developers.
Industry Challenges
- Electrical engineering talent scarcity:Grid synchronization specialists and power electronics technicians command premium wages, extending commissioning timelines.
- Legacy building integration:Amsterdam and Utrecht commercial retrofits require bespoke heat exchanger configurations to interface with 1970s-era hydronic distribution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Combined Heat and Power Market |
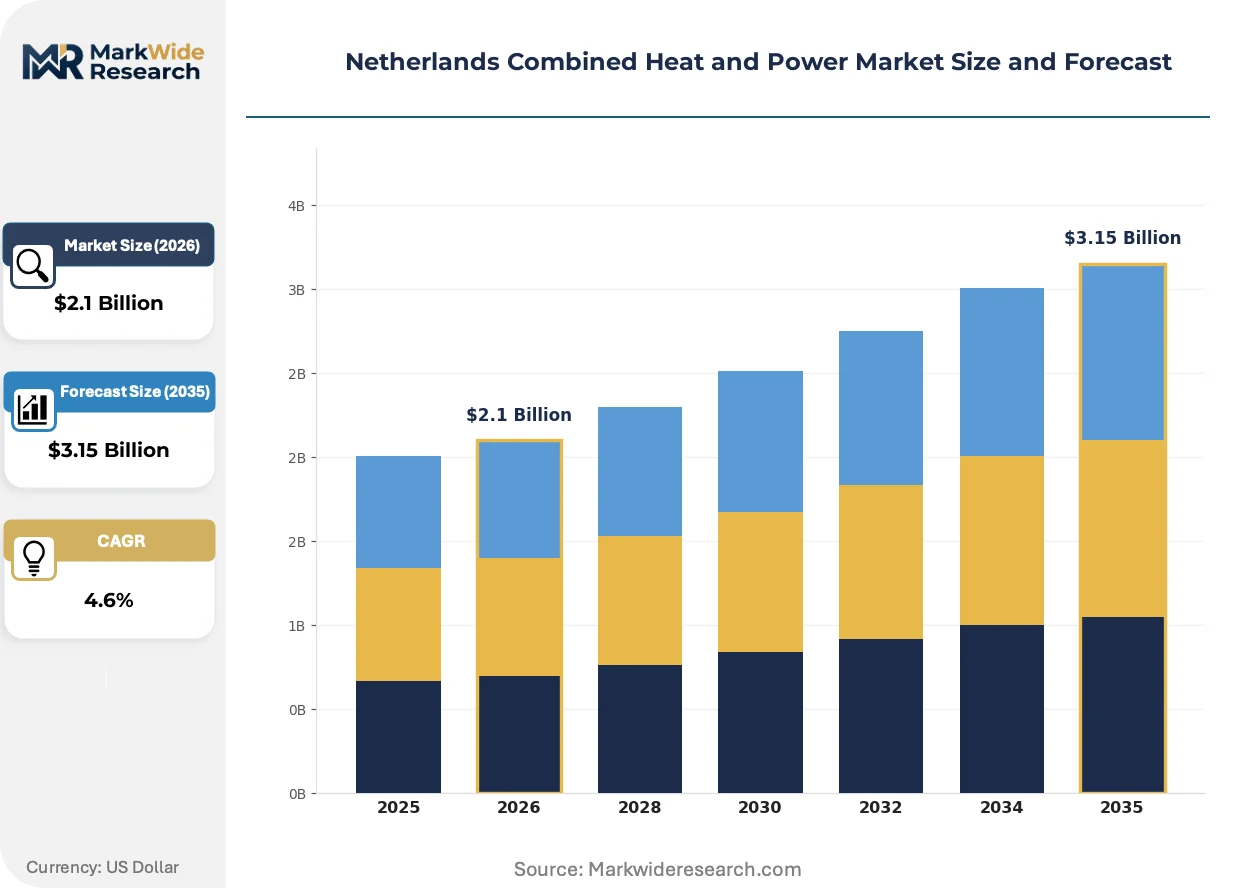
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gas Turbine, Steam Turbine, Reciprocating Engine, Micro-CHP End User: Industrial Sector, Residential Buildings, Commercial Buildings, Utilities Application: District Heating, Process Heat, Power Generation, Cogeneration Fuel Type: Natural Gas, Biomass, Coal, Others |
| Companies Covered | BDR Thermea Group BV, Siemens AG, ABB Ltd., Caterpillar Inc., Capstone Turbine Corporation, Viessmann Werke GmbH & Co. KG, Microgen Engine Corporation Holding B.V., Senertec Kraft-Warme-Energiesysteme GmbH, Eneco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Combined Heat and Power Market Evolving Landscape
Technology trajectories in Dutch CHP are converging on fuel flexibility and thermal storage integration, while regulatory pressure accelerates equipment replacement cycles beyond historical norms.
High-pressure alkaline electrolyzers paired with hydrogen-ready gas turbines are displacing conventional natural gas CHP in Rotterdam industrial zones. Chemical process operators at the port complex are piloting 10 MW-class systems with 30% hydrogen co-firing capability. This configuration is displacing standalone boiler investments as the baseline thermal infrastructure for new manufacturing capacity.
The EU F-Gas Regulation restricts synthetic refrigerants in absorption cooling trigeneration systems, forcing equipment redesign toward ammonia and water-lithium bromide working fluids. Dutch CHP manufacturers must re-engineer chiller packages to maintain cooling output with natural refrigerants. Greenhouse operators in Westland face accelerated equipment replacement timelines as R-134a and R-410A phase-down schedules tighten.
Heat-as-a-service contracting is restructuring procurement relationships between equipment vendors and district heating cooperatives. Eneco and regional utilities now bundle CHP asset ownership with 15-year thermal supply agreements, transferring operational risk from municipal buyers to energy service companies. This model concentrates most visibly in new-build residential developments around Utrecht where developers prefer opex-based heating solutions over capital-intensive plant ownership.
Netherlands Combined Heat and Power Market Segmentation
Technology choices in Dutch CHP determine hydrogen readiness and subsidy eligibility. End user concentration shapes equipment sizing and service contracting models across the value chain.
Technology:
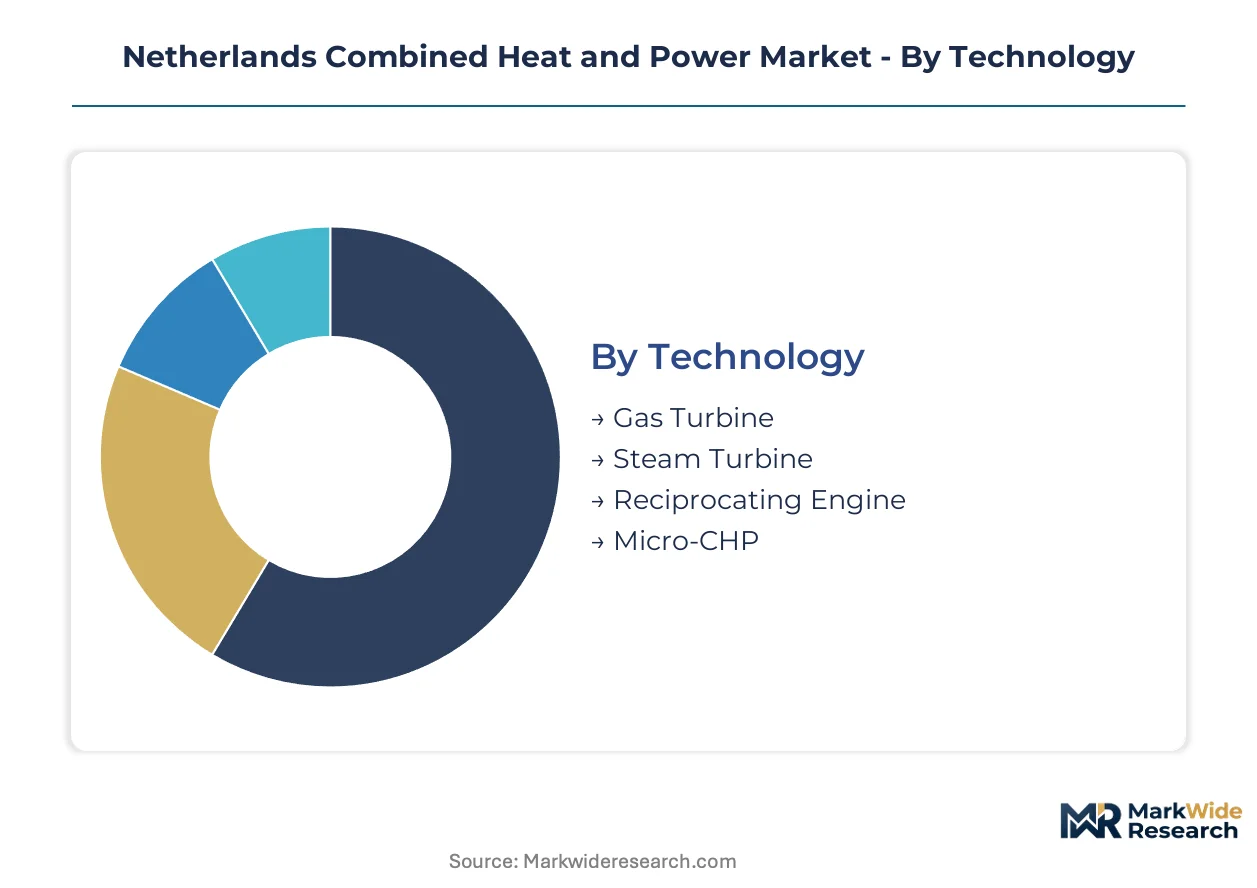
Margin pools concentrate in large-scale turbine systems where fuel flexibility commands engineering premiums and long-term service agreements.
- Gas Turbine:These systems achieve 30% hydrogen co-firing capability through dry low-NOx combustor redesigns. Rotterdam industrial operators at the Port of Rotterdam hydrogen hub prioritize these units for future fuel switching. SDE++ subsidy qualification hinges on demonstrated blending readiness.
- Reciprocating Engine:Fast-ramping gas engines dominate greenhouse horticulture installations around Westland and Aalsmeer. Load-following flexibility enables growers to capture peak power pricing and provide grid balancing services to TenneT.
- Steam Turbine:Legacy industrial sites with existing boiler infrastructure deploy backpressure configurations for process steam.
- Micro-CHP:Residential units face heat pump competition in Amsterdam net-zero retrofits.
Gas turbine holds installed capacity. Reciprocating engine is rotating up the share rankings.
End User:
Customer type determines whether projects self-execute or procure through energy service companies.
- Industrial Sector:Chemical processors and food manufacturers at Rotterdam and Eindhoven sites deploy 10-50 MW systems. These operators negotiate directly with Siemens AG and MAN Energy Solutions for fuel-flexible configurations.
- Greenhouse Horticulture:Westland and Aalsmeer growers cluster CHP adoption for combined heat, power, and CO2 fertilization. District heating cooperatives aggregate thermal demand across multiple glasshouse operations.
- Commercial Buildings:Amsterdam and Utrecht office retrofits source compact boiler-turbine packages.
- Utilities:Regional heat network operators procure under Warmtenet 2.0 concession frameworks.
Industrial sector anchors current deployment. Greenhouse horticulture is expanding most quickly.
Application:
Application mix tracks the Dutch heat network buildout and industrial decarbonization timelines.
- District Heating:Municipal concessions under Warmtenet 2.0 mandate renewable heat quotas. Biogas and biomass CHP developers secure 15-year offtake contracts with cooperative utilities.
- Process Heat:Chemical and refining operations at Rotterdam require high-temperature thermal inputs. Hydrogen-ready gas turbines displace standalone boilers as baseline infrastructure.
- Power Generation:Grid balancing revenue streams supplement thermal economics.
- Cogeneration:Combined output configurations dominate new installations.
District heating captures policy tailwinds. Process heat maintains margin density.
Fuel Type:
Fuel sourcing strategy determines carbon intensity and SDE++ subsidy tier eligibility.
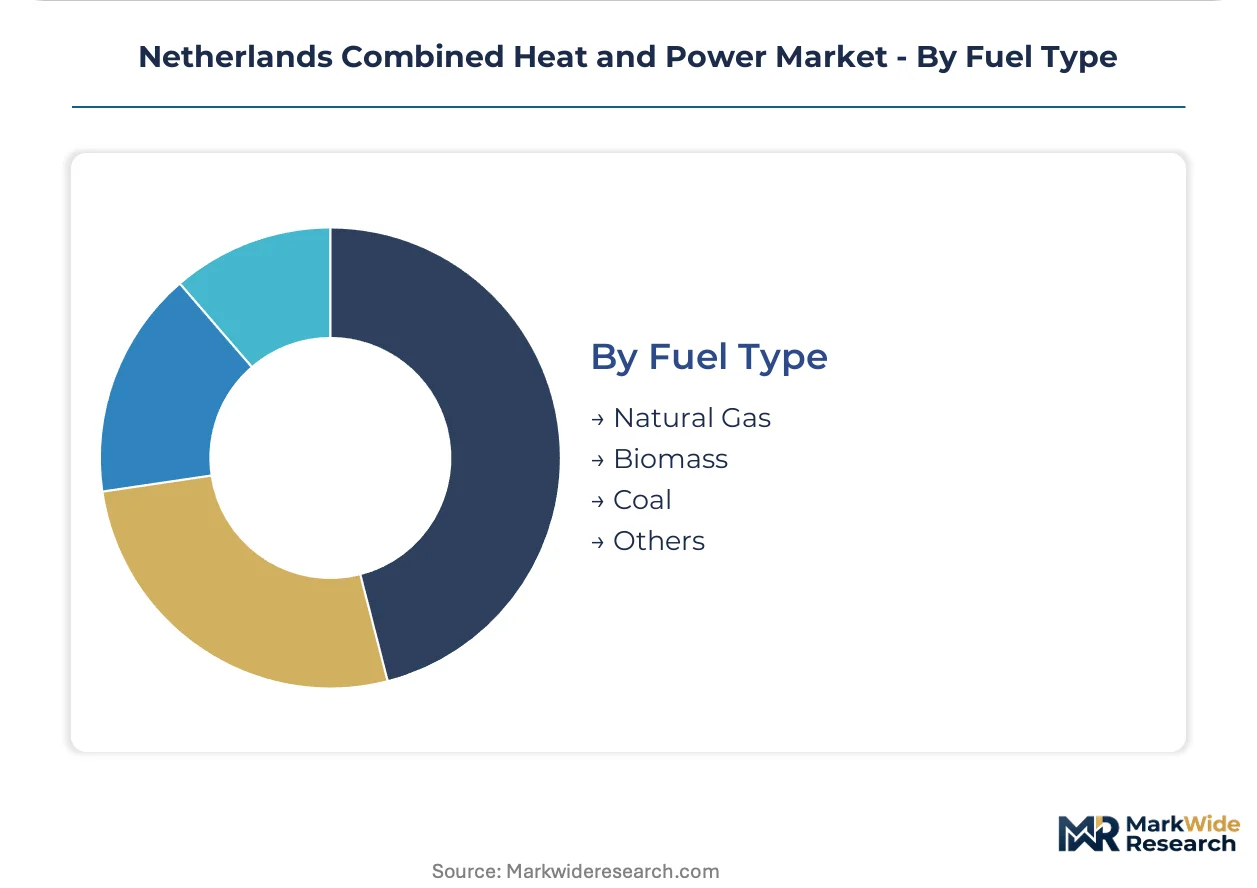
- Natural Gas:Groningen field phase-out accelerates infrastructure conversion. TTF hub pricing volatility compresses operating margins for unhedged operators.
- Biomass:Agricultural residues and woody biomass qualify for top-tier SDE++ support. Supply chain localization requirements favor Dutch and neighboring feedstock sourcing.
- Coal:Remaining units face accelerated retirement under EU ETS carbon pricing.
- Others:Hydrogen and biogas pathways are piloting at Rotterdam port complexes.
Natural gas dominates installed base. Biomass is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam hydrogen backbone underwrites Dutch CHP infrastructure conversion, connecting electrolyzer clusters to industrial thermal users before pipeline networks mature.
Randstad
Greenhouse horticulture around Westland and Aalsmeer deploys reciprocating engine CHP for baseload heat, power, and CO2 fertilization. The Netherlands Enterprise Agency channels SDE++ subsidies toward these installations. District heating cooperatives aggregate thermal demand across glasshouse operations, creating procurement scale for energy service companies.
Brabant
Eindhoven industrial facilities expand CHP adoption to secure process heat for semiconductor and chemical manufacturing. The Dutch Emissions Authority enforces CO2 performance standards under EU ETS that penalize standalone fossil generation. High-tech campuses negotiate directly with turbine manufacturers for fuel-flexible configurations.
Port of Rotterdam
Chemical processors pilot 10 MW-class hydrogen-ready gas turbines with 30% co-firing capability. The EU F-Gas Regulation restricts synthetic refrigerants in absorption cooling systems, forcing equipment redesign. Alkaline electrolyzer pairing with gas turbines displaces conventional boiler investments as baseline thermal infrastructure.
Amsterdam Metro
Commercial building retrofits source compact boiler-turbine packages for 1970s-era hydronic distribution systems. The Warmtenet 2.0 framework mandates renewable heat quotas for municipal network concessions. Heat-as-a-service contracting transfers operational risk from developers to energy service companies in new-build residential zones.
Utrecht Region
Data center thermal loads create premium pricing pools for dedicated CHP supply of electricity and absorption cooling. Grid interconnection queues from regional transmission operators delay utility-scale synchronization approvals. Hyperscale facilities seek long-term thermal supply agreements with integrated energy service models.
Netherlands Combined Heat and Power Market Competitive Landscape
Listed leaders compete with private specialists across technology integration depth, with publicly traded conglomerates anchoring utility-scale turbine supply while privately held fabricators capture commercial retrofit niches. The vendor base stratifies into three tiers: multinational energy technology groups with hydrogen-ready portfolios, regional boiler-turbine packagers serving building retrofits, and integrated utilities bundling asset ownership with long-term service contracts. Market structure rewards fuel flexibility engineering and heat network concession capture. Dominant competitive moves include strategic partnerships with hydrogen infrastructure developers and geographic expansion through municipal heat network concessions.
Among Dutch and German-origin specialists, BDR Thermea Group BV, Siemens AG, and Eneco occupy distinct archetype positions. BDR Thermea Group BV exemplifies the compact system packager archetype targeting commercial building retrofits. Siemens AG represents the multinational technology conglomerate tier with gas turbine portfolios engineered for industrial hydrogen blending. Eneco anchors the integrated utility archetype, bundling CHP asset ownership with thermal supply agreements and grid balancing services under long-term contracting structures.
| Leading Market Players |
|---|
| BDR Thermea Group BV |
| Siemens AG |
| ABB Ltd. |
| Caterpillar Inc. |
| Capstone Turbine Corporation |
| Viessmann Werke GmbH & Co. KG |
| Microgen Engine Corporation Holding B.V. |
| Senertec Kraft-Warme-Energiesysteme GmbH |
| Eneco |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracting between Dutch greenhouse cooperatives and biogas CHP developers locks in feedstock supply visibility while stabilizing thermal output pricing across the SDE++ subsidy window. This structure transfers commodity price risk from growers to energy service companies, concentrating procurement leverage with district heating utilities that aggregate multiple glasshouse operations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the Dutch CHP market by hydrogen blending capability and service bundling intensity. Premium tiers command engineering premiums for 30% hydrogen-ready gas turbines with integrated long-term service agreements, while economy tiers cover reciprocating engine packages without grid balancing revenue sharing. Price differentiation hinges on SDE++ subsidy tier eligibility and after-sales thermal contracting depth. Cost compression in standard-tier natural gas systems is intensifying because heat pump substitution threatens residential micro-CHP penetration. Greenhouse horticulture buyers exhibit lowest price sensitivity due to CO2 fertilization co-benefits, while commercial building retrofitters face acute capital constraints.
Supply Chain Analysis
Inventory lead times for hydrogen-ready combustor components now extend 14-18 months, forcing Dutch project developers to place speculative orders before final investment decisions. Manufacturing concentration rests on Germany, the Netherlands, and Denmark for precision turbine components and control systems. Raw material dependencies include high-grade nickel alloys for hot gas path parts, rare earth elements for power electronics, and specialized ceramics for thermal barrier coatings. Single-source vulnerability concentrates in dry low-NOx combustor technology licensed from a limited supplier pool. Distribution runs through regional EPC contractors that bundle equipment procurement with installation and commissioning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dutch CHP market functions as a service-attach opportunity where long-term thermal supply agreements and grid balancing contracts expand faster than hardware shipments. Recurring revenue from asset operation and maintenance now exceeds equipment margin pools for integrated utilities.
For Market Incumbents: Shield installed base profitability by embedding fuel-flexibility upgrade pathways into existing turbine service contracts before hydrogen pipeline infrastructure matures. Acquire specialized grid synchronization engineering capabilities to address talent scarcity compressing commissioning timelines. Prioritize Warmtenet 2.0 concession capture in Utrecht and Amsterdam Metro corridors where municipal renewable heat quotas mandate CHP procurement. For New Entrants and Emerging Players: CE marking fast-track for hydrogen-ready micro-CHP units opens residential retrofit penetration in Amsterdam's net-zero building stock. Target data center thermal load contracts around Utrecht where hyperscale facilities seek dedicated absorption cooling supply. Pursue heat-as-a-service partnerships with municipal developers preferring opex-based heating solutions over capital-intensive plant ownership. For Investors and Strategic Acquirers: Capital is best deployed toward integrated energy service companies with captive district heating concessions and demonstrated SDE++ subsidy capture capabilities. Long-term viability across the projection horizon hinges on hydrogen infrastructure rollout synchronization and carbon border adjustment mechanism timing. Monitor Port of Rotterdam electrolyzer cluster offtake contract announcements as the critical inflection signal for industrial CHP fuel switching economics.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Blending Certification | SDE++ subsidy eligibility now requires demonstrated 30% hydrogen co-firing capability from Dutch CHP assets. |
| District Heating Concession Capture | Warmtenet 2.0 frameworks in Utrecht and Amsterdam Metro lock in 15-year thermal supply monopolies for winning bidders. |
| Grid Balancing Service Integration | TenneT frequency regulation contracts supplement thermal economics for Westland greenhouse reciprocating engine operators. |
| Electrolyzer Partnership Structuring | Port of Rotterdam hydrogen hub offtake agreements future-proof gas turbine assets against Groningen field phase-out. |
| Natural Refrigerant Redesign | EU F-Gas Regulation compliance forces ammonia and water-lithium bromide absorption cooling system re-engineering. |
Research Methodology
Cross-validation between primary interviews with Dutch CHP stakeholders and secondary regulatory filings anchors the qualitative findings in documented policy trajectories. The research program combined structured discussions with greenhouse horticulture operators, district heating cooperative managers, turbine OEM technical directors, and RVO subsidy administrators. Secondary sources included SDE++ scheme documentation, NEa emissions performance filings, EU ETS registry data, and TenneT grid interconnection queue records. Bottom-up project pipeline tracking and top-down subsidy allocation analysis were triangulated to validate capacity deployment assumptions.
Sensitivity analysis around hydrogen infrastructure rollout timelines and TTF hub price volatility bounds the forecast range across the modeling period. The analytical framework segments by technology type, end-user category, application mode, and fuel source, with additional granularity on hydrogen blending readiness tiers. CAGRs were derived from regression-based capacity buildout modeling against historical SDE++ award patterns. Key forecast inputs include electrolyzer deployment schedules at Rotterdam port complexes and municipal heat network concession award calendars.
The analysis sits within stated boundaries; outcomes outside sustained SDE++ subsidy authorization or accelerated Groningen field closure would require recalibration. Forecasts reflect assumptions on hydrogen pipeline commissioning sequences and carbon border adjustment implementation scope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Boiler Control Market
Boilers
Boiler System Market
Boilers
Global Domestic Boilers Market
Boilers
Superheater Tubes Market
Boilers
Hydrogen Boilers Market
Boilers
Commercial Boiler Market
Boilers
Industrial and Residential Heating Market
Boilers
North America Industrial Boiler Market
Boilers
Feed Water Heater for Power Plants Market
Boilers
Residential Boiler Market
Boilers
North America and Europe Electric Boilers Market
Boilers
Superheater Market
Boilers
Watertube Boilers Market
Boilers
Brazil Combined Heat and Power Market
Boilers
US Boiler Market
Boilers
Middle East and Africa Power Plant Boiler Market