
 GCC Electric Water Heater Market | 2026-2036
GCC Electric Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Electric Water Heater Market Foresight
Saudi Arabia's updated energy efficiency standards for building services is rebalancing procurement criteria across the GCC. A.O. Smith Corp. leverages its regional manufacturing footprint to anchor supply contracts with major Saudi developers. Rheem Manufacturing Company competes through specialized commercial-grade lines targeting the hospitality sector in Dubai and Abu Dhabi. Haier Inc. extends its distribution reach via partnerships with UAE-based electrical distributors serving retrofit demand.
GCC electric water heaters are pressurized vessels that convert electrical energy into thermal energy through immersion or tubular heating elements, typically operating at 1.5 kW to 6 kW power ratings and storing 30 to 200 liters for residential applications. Storage water heaters dominate volume across the GCC due to lower upfront cost and compatibility with existing electrical infrastructure in legacy buildings. Instant water heaters are gaining share in high-rise residential towers across the UAE where space constraints and peak-load management drive specification. Heat pump water heaters remain nascent but attract premium project interest in Saudi Arabia's NEOM and Red Sea developments where renewable energy integration is mandated.
Gulf Standardization Organization (GSO) technical regulations govern electrical safety and energy labeling across member states, while Saudi Standards, Metrology and Quality Organization (SASO) enforces stricter efficiency tiers for products entering the Kingdom. The UAE's Emirates Authority for Standardization and Metrology (ESMA) operates parallel certification requirements that create dual compliance obligations for manufacturers serving multiple GCC markets. Stakeholders must monitor divergence between national efficiency programs as Saudi Arabia accelerates its own tightening timeline independent of GSO harmonization efforts.
Market Dynamics
Saudi Arabia's unilateral acceleration of energy efficiency mandates is fragmenting regulatory harmonization across the GCC, forcing manufacturers to maintain parallel certification tracks for products entering the Kingdom versus other member states. This divergence is compressing product development cycles and redrawing competitive boundaries.
Growth Catalysts
- SASO Energy Efficiency Tiers:The Saudi Standards, Metrology and Quality Organization's tightening minimum performance standards for electric water heaters are phasing out low-efficiency imports and creating replacement demand across Riyadh, Jeddah, and Dammam housing stock.
- Megaproject Integration Mandates:NEOM, the Red Sea Project, and Qiddiya developments specify smart-enabled water heating systems with renewable energy coupling, establishing new specification baselines for premium residential and hospitality segments.
- Retrofit Cycles in Legacy Buildings:Aging storage water heater fleets across Dubai and Sharjah's 1990s-era residential towers are reaching end-of-life, driving wholesale replacement demand through UAE-based electrical distributors.
Market Restraints
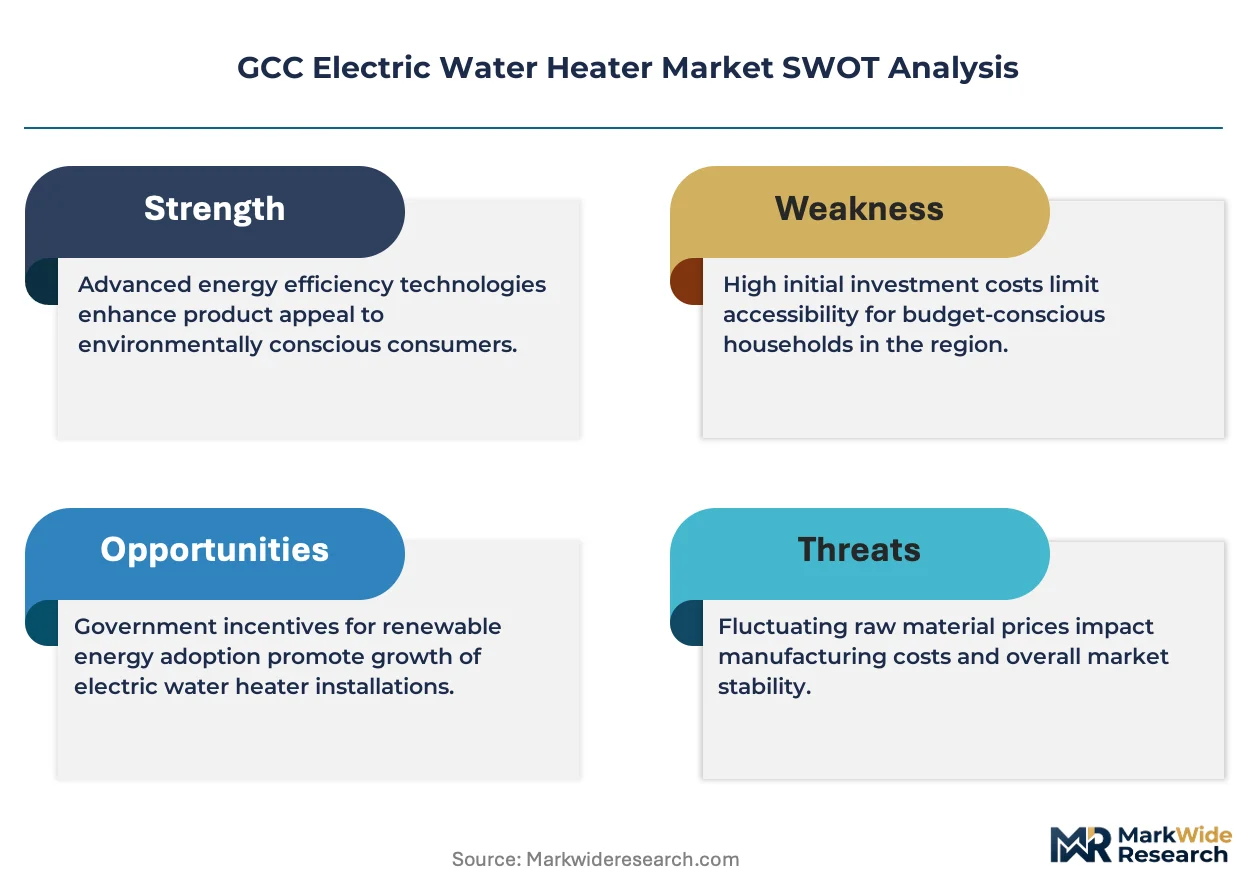
- Copper and Steel Input Volatility:Heating element manufacturing and tank fabrication depend on copper coil and galvanized steel sheet pricing, which fluctuates with commodity markets and compresses margin predictability for regional assemblers.
- Dual Certification Burden:The divergence between GSO harmonized standards and Saudi-specific SASO requirements creates redundant testing costs and extends product registration timelines for manufacturers serving multiple GCC markets.
- Heat Pump Substitution Threat:Where renewable energy integration is mandated or subsidized, heat pump water heaters displace electric resistance units on lifecycle cost grounds, particularly in Saudi Arabia's premium development corridors.
Strategic Opportunities
- Kuwait and Oman Underpenetration:These markets maintain lower electric water heater replacement rates per housing unit than Saudi Arabia or the UAE, presenting volume expansion potential for distributors establishing localized service networks.
- Smart Home Convergence:Integration of water heating controls with building management systems and grid-responsive demand management creates premium positioning for manufacturers with IoT-enabled product lines.
- ESMA Efficiency Labeling Uptake:The UAE's Emirates Authority for Standardization and Metrology energy labeling program is elevating consumer awareness of operating costs, favoring rated products in retail channels.
Industry Challenges
- SASO Certification Timeline Compression:Accelerated regulatory updates in Saudi Arabia are outpacing testing laboratory capacity, creating backlog risks for product launches timed to construction procurement windows.
- Legacy Electrical Infrastructure Mismatch:Older residential buildings across the GCC lack circuit capacity for high-power instant water heaters, limiting retrofit specification and requiring costly electrical upgrades.
- Technical Workforce Scarcity:Installation and maintenance of smart-enabled and heat pump systems demands skills beyond conventional electric water heater servicing, constraining service network expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Electric Water Heater Market |
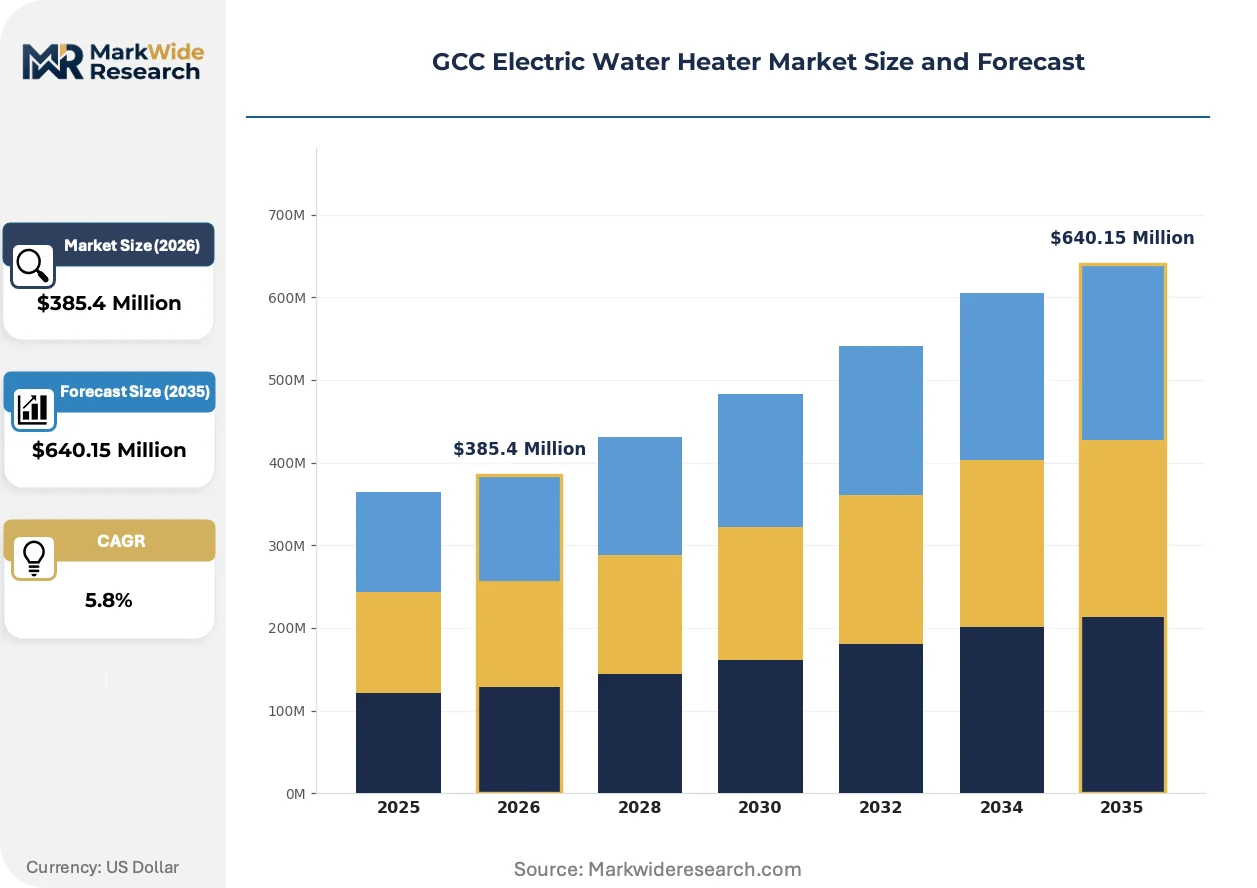
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage Water Heater, Instant Water Heater, Heat Pump Water Heater, Solar Water Heater Technology: Thermostat Controlled, Immersion Heater, Tubular Heating Element, Dry Heating Element End User: Residential Buildings, Hospitality Sector, Commercial Complexes, Industrial Facilities Distribution Channel: Online Retailers, Specialty Stores, General Merchandisers, Electrical Distributors |
| Companies Covered | A.O. Smith Corp., Bajaj, Whirlpool, Haier Inc., Rinnai Corporation, General Electric Co., Bradford White, Havells India Ltd, Rheem Manufacturing Company, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Electric Water Heater Market Shifts & Advancements
Thermostat-controlled and connectivity-enabled water heating systems are displacing mechanical controls across new construction specifications. This shift is compressing the addressable market for basic units while expanding service revenue pools for connected product ecosystems.
Digital thermostat interfaces with smartphone integration and energy consumption monitoring are consolidating specification preference in Saudi Arabia's premium residential segment. Major developers in Riyadh and Jeddah now mandate connected controls as standard fit-out. This consolidation is marginalizing mechanical thermostat suppliers and elevating electronics integration capabilities as a competitive prerequisite.
Saudi Arabia's Saudi Building Code energy chapter and SASO's independent efficiency tier implementation are operating ahead of GSO harmonization timelines. Manufacturers must now maintain separate product variants and certification documentation for the Kingdom versus other GCC markets. Commercial-grade specification in Saudi Arabia's hospitality and healthcare verticals is most affected, with procurement teams demanding SASO-specific compliance documentation.
Specification authority is migrating from individual contractors to master developer procurement departments across the GCC's megaproject pipeline. Bulk purchasing agreements for entire residential districts are displacing fragmented unit-by-unit procurement. This concentration is most visible in Dubai's master-planned communities and Saudi Arabia's giga-project developments, where standardized product selection reduces variation and service complexity.
GCC Electric Water Heater Market Segmentation
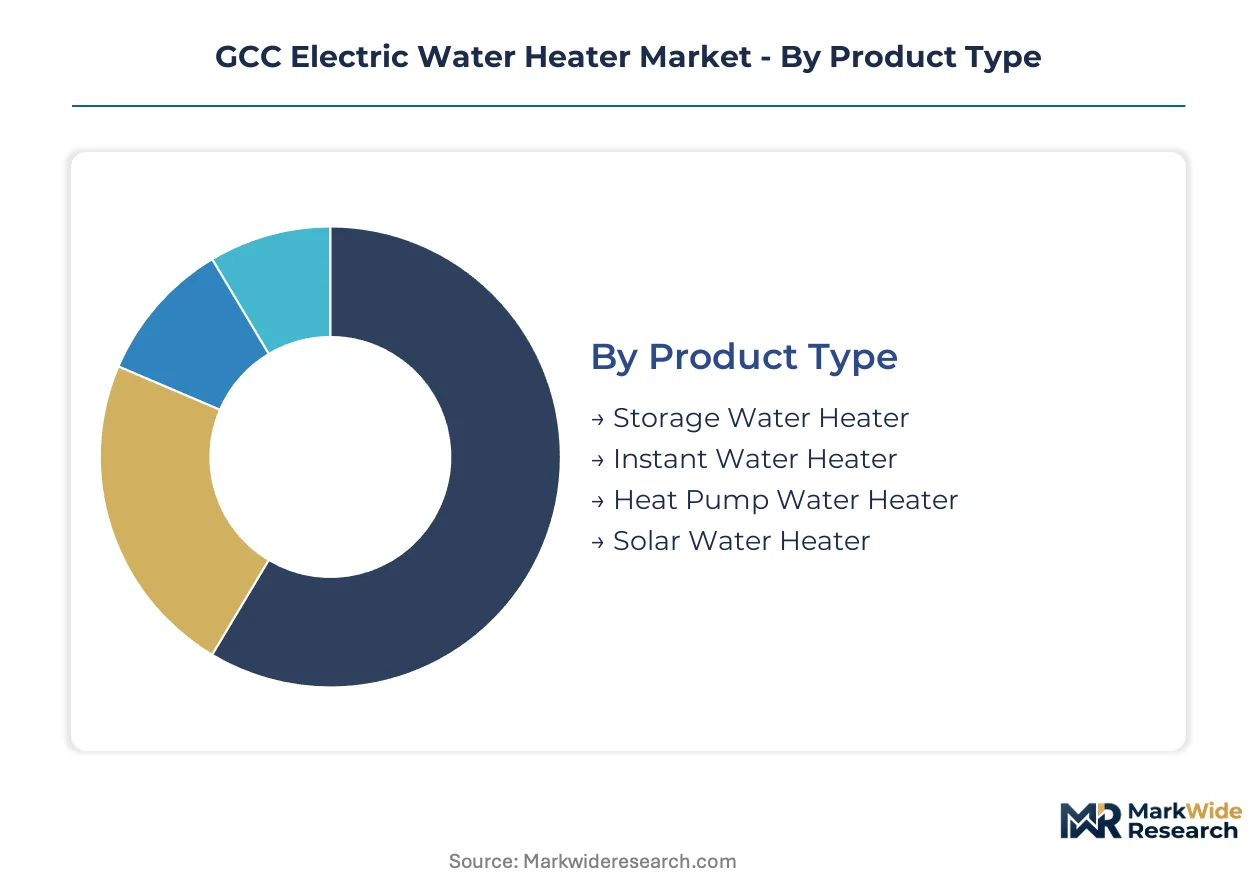
Electric water heater procurement across the GCC fragments along four critical dimensions that determine specification authority, margin structure, and competitive positioning. Product type and technology choices anchor upfront capital decisions, while end-user verticals and distribution channels govern go-to-market economics and service requirements.
Product Type:
Volume concentrates in legacy storage systems, while premium specification tilts toward instant and heat pump alternatives in new construction corridors.
- Storage Water Heater:Pressurized vessels with 30-200 liter capacities and 1.5-6 kW immersion elements dominate existing housing stock across Riyadh, Jeddah, and Dubai's 1990s-era towers. Lower upfront cost and compatibility with legacy electrical infrastructure sustain replacement demand through UAE-based electrical distributors serving retrofit cycles.
- Instant Water Heater:Compact tankless units with 3-6 kW tubular elements are displacing storage systems in Saudi Arabia's NEOM and Red Sea developments where space constraints and peak-load management drive specification. Smart-enabled controls with demand-response capability command premium positioning in high-rise residential towers across Dubai and Abu Dhabi.
- Heat Pump Water Heater:Refrigerant-cycle systems extracting ambient thermal energy attract giga-project interest where renewable energy coupling is mandated.
- Solar Water Heater:Evacuated-tube and flat-plate collectors with electric backup elements serve off-grid installations and sustainability-mandated developments.
Today's leader: Storage Water Heater. Tomorrow's challenger: Instant Water Heater.
Technology:
Control sophistication separates commodity supply from premium specification, with digital interfaces displacing mechanical systems in new construction.
- Thermostat Controlled:Digital thermostat interfaces with smartphone integration and energy consumption monitoring consolidate preference in Saudi Arabia's premium residential segment. Major Riyadh and Jeddah developers now mandate connected controls as standard fit-out, marginalizing mechanical alternatives.
- Immersion Heater:Direct-resistance elements submerged in storage tanks deliver cost-efficient baseline performance for economy-tier replacement demand.
- Tubular Heating Element:Sheathed resistance coils with magnesium oxide insulation provide durability for commercial-grade specification in hospitality and healthcare verticals.
- Dry Heating Element:Surface-mounted heating elements with ceramic insulation reduce corrosion risk in high-hardness water conditions prevalent across the GCC.
Specification gravity centers on Thermostat Controlled systems in new construction, while replacement markets sustain Immersion Heater volume.
End User:
Procurement authority migrates from fragmented contractor purchasing to concentrated master developer decisions across megaproject pipelines.
- Residential Buildings:Single-family villas and multi-unit towers across Saudi Arabia's Riyadh-Dammam corridor drive volume demand, with SASO efficiency tiers phasing out low-efficiency imports and creating replacement cycles.
- Hospitality Sector:Hotels and serviced apartments in Dubai and Abu Dhabi specify commercial-grade tubular element systems with redundant capacity for 24-hour hot water availability.
- Commercial Complexes:Office buildings and retail centers prioritize lifecycle operating cost over upfront capital, favoring rated efficiency products under UAE ESMA labeling programs.
- Industrial Facilities:Process heating and worker accommodation applications demand heavy-duty storage capacities with accelerated recovery rates.
Residential Buildings anchor current volume. Hospitality Sector represents the steepest expansion trajectory for premium specification.
Distribution Channel:
Channel selection determines service reach, installation support capability, and access to specification authority in concentrated procurement environments.
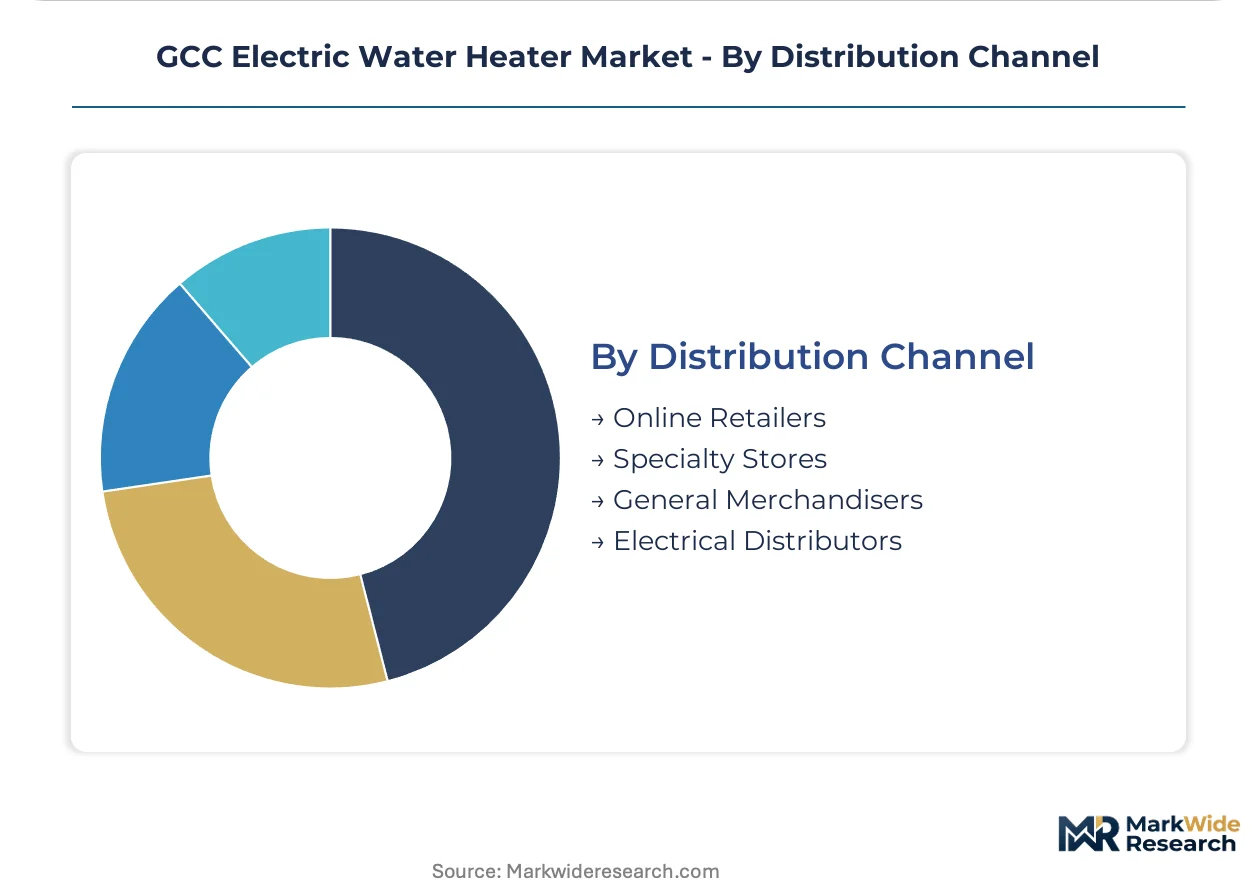
- Electrical Distributors:UAE-based distributors with localized service networks dominate retrofit demand across Dubai and Sharjah, capturing replacement cycles in aging residential towers through contractor relationships and same-day availability.
- Specialty Stores:Dedicated plumbing and heating retailers serve consumer-direct replacement and premium upgrade demand with technical consultation.
- Online Retailers:E-commerce platforms capture price-sensitive comparison shopping for standard-capacity residential units.
- General Merchandisers:Big-box retailers and hypermarkets move entry-level storage heaters through high-traffic locations.
Electrical Distributors control project specification. Online Retailers are gaining share fastest in consumer-direct segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric water heater manufacturing first scaled in North American and European industrial corridors during the mid-20th century, with technology transfer to Gulf markets accelerating after 2000 as regional construction booms created localized demand centers.
Saudi Arabia
Riyadh's residential construction surge and Jeddah's hospitality expansion drive specification volume for thermostat-controlled units. SASO's independent efficiency tier implementation operates ahead of GSO harmonization, forcing dedicated product variants for Kingdom entry. The Riyadh-Dammam corridor concentrates megaproject procurement authority where NEOM and Red Sea developments mandate smart-enabled systems.
United Arab Emirates
Dubai's high-rise residential towers and Abu Dhabi's commercial complexes sustain replacement cycles and new installation demand. ESMA's parallel certification requirements create dual compliance obligations alongside GSO standards for manufacturers serving multiple Gulf markets. Sharjah's aging 1990s-era residential stock generates retrofit demand through electrical distributor networks.
Kuwait
Lower per-housing-unit replacement rates than Saudi Arabia or the UAE present volume expansion potential for distributors establishing localized service networks. The country's national standards body maintains alignment with GSO technical regulations while enforcing additional electrical safety protocols. Kuwait City's residential development corridors show emerging specification interest in compact instant water heaters for space-constrained towers.
Oman
Underpenetrated market conditions relative to regional peers attract entry strategies focused on electrical distributor partnerships and contractor relationships. The Sultanate's national standardization organization participates in GSO harmonization efforts without unilateral acceleration timelines seen in Saudi Arabia. Muscat's master-planned communities and Salalah's hospitality corridor represent concentrated demand pockets for commercial-grade specification.
Qatar
World Cup legacy hospitality stock and ongoing residential district construction sustain premium product specification. The Qatar General Organization for Standardization enforces GSO-aligned requirements with additional emphasis on energy labeling transparency. Doha's Lusail development and Education City precincts concentrate procurement authority for connected-control water heating systems.
GCC Electric Water Heater Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification sophistication and control system integration. The vendor base stratifies into three tiers: multinational appliance conglomerates with regional manufacturing footprints, specialized heating equipment manufacturers with Gulf distributor networks, and regional assemblers serving price-sensitive replacement demand. Dominant competitive moves include backward integration into heating element production and strategic partnerships with master developers for megaproject specification.
Within the multinational appliance tier, A.O. Smith Corp. and Haier Inc. exemplify scale-driven positioning through regional supply chain anchoring. Rheem Manufacturing Company occupies a specialist position representing commercial-grade specification expertise. These three entities demonstrate how geographic manufacturing presence and certification portfolio breadth determine competitive access across Saudi Arabia's accelerated regulatory timeline versus broader GCC markets.
| Leading Market Players |
|---|
| A.O. Smith Corp. |
| Bajaj |
| Whirlpool |
| Haier Inc. |
| Rinnai Corporation |
| General Electric Co. |
| Bradford White |
| Havells India Ltd |
| Rheem Manufacturing Company |
| Others |
Supply & Pricing Matrix
SASO's renewable energy coupling mandates for premium developments gate qualified supply and premium-tier pricing access, compressing margin pools for manufacturers lacking smart-enabled product portfolios while elevating certified suppliers in Saudi Arabia's megaproject corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates connected-control systems from basic thermostat units from commodity storage replacements. Price differentiation rests on SASO certification grade and after-sales service bundling, with premium tiers commanding positioning through renewable integration capability. Cost compression in economy-tier replacement demand is intensifying because copper coil and galvanized steel sheet volatility compresses assembler margins. Contractor buyers in Dubai's retrofit channels exhibit highest price sensitivity, while master developers in NEOM and Red Sea projects prioritize lifecycle operating cost over upfront capital.
Supply Chain Analysis
Dual-sourcing requirements from Saudi master developers mandate multi-supplier qualification, forcing manufacturers to maintain redundant heating element and control system vendors. Manufacturing concentrates in China, South Korea, and domestic Saudi assembly facilities for tariff-advantaged Kingdom delivery. Raw material dependencies center on copper coil for immersion elements, galvanized steel sheet for tank fabrication, and ceramic insulation for dry heating systems. Single-source vulnerability in semiconductor-based thermostat components creates procurement risk for smart-enabled product lines. Distribution runs through UAE-based electrical distributors capturing retrofit demand and direct master developer contracts for megaproject specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC electric water heater market reads as a late-cycle quality story, with procurement authority consolidating around thermostat-controlled and connectivity-enabled specifications that displace mechanical alternatives across Saudi Arabia's residential construction surge.
For Market Incumbents: Hedge against heat pump substitution threat by deepening backward integration into heating element production and accelerating SASO certification investment ahead of GSO harmonization divergence. Anchor supply contracts with Riyadh-Dammam corridor master developers to lock out emerging competitors from megaproject specification windows. For New Entrants and Emerging Players: Launch via electrical distributor partnerships in Kuwait and Oman where localized service networks remain underdeveloped relative to Saudi Arabia and UAE penetration. Target compact instant water heater specification in Kuwait City's space-constrained residential towers, leveraging lower certification burden versus Saudi-specific SASO tracks. For Investors and Strategic Acquirers: Roll-up economics work for regional assemblers with captive heating element supply because SASO timeline compression and dual certification burdens are forcing consolidation among sub-scale manufacturers lacking testing laboratory relationships. Monitor backlog risks at Saudi testing laboratories as the inflection indicator for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Element Production | Captive copper coil supply insulates margin compression from commodity volatility across GCC assembler networks. |
| SASO Certification Acceleration | Early compliance with Saudi efficiency tiers secures megaproject specification ahead of GSO harmonization divergence. |
| Smart Control Platform Development | IoT-enabled thermostat systems capture premium positioning in Riyadh and Jeddah developer mandates. |
| Electrical Distributor Partnership Expansion | Localized service networks in Kuwait and Oman unlock underpenetrated replacement cycles beyond Saudi-UAE concentration. |
| Heat Pump Product Line Introduction | Refrigerant-cycle systems address NEOM and Red Sea renewable integration mandates displacing resistance units. |
Research Methodology
Bottom-up residential and commercial modeling reconciled against top-down manufacturing and import tracking forms the analytical core of this study. Primary interviews with master developer procurement directors, electrical distributor category managers, and heating element procurement leads at regional assemblers combined with secondary validation from SASO efficiency registry filings, GSO technical regulation updates, and UAE customs trade data. Triangulation across these sources calibrated volume estimates and specification mix assumptions.
Historical trendline analysis of construction permit issuance, housing stock age distribution, and replacement cycle timing informed projection modeling across the analysis window. Segmentation dimensions include product type, control technology, end-user vertical, and distribution channel, with CAGRs derived from correlated macro drivers including residential construction velocity and regulatory efficiency tier implementation. Forecast inputs incorporate copper and steel price trajectory assumptions and master developer procurement concentration indices.
Several conditions sit outside the modeled scope, including geopolitical disruption to Red Sea shipping corridors and unilateral regulatory acceleration beyond Saudi Arabia's current SASO timeline. Forecasts reflect documented assumptions regarding megaproject completion schedules and GSO harmonization progress. Deviation in testing laboratory capacity constraints or heat pump subsidy expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Industrial Boiler MRO Market
Boilers
Hydrogen Boilers Market
Boilers
Utility Boiler Market
Boilers
Industrial Biomass Boiler Market
Boilers
North America and Europe Electric Boilers Market
Boilers
Biomass Boiler Market
Boilers
Space Heating Boilers Market
Boilers
Fuel Operated Heaters Market
Boilers
Boiler Control Market
Boilers
Europe Residential Boiler Market
Boilers
Marine Boiler Burner Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
Asia-Pacific Power Plant Boiler Market
Boilers
Global Domestic Boilers Market
Boilers
US Combined Heat and Power (CHP) Market
Boilers
Germany Combined Heat and Power Market