
 Middle East and Africa Power Plant Boiler Market | 2026-2036
Middle East and Africa Power Plant Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Power Plant Boiler Market Foresight
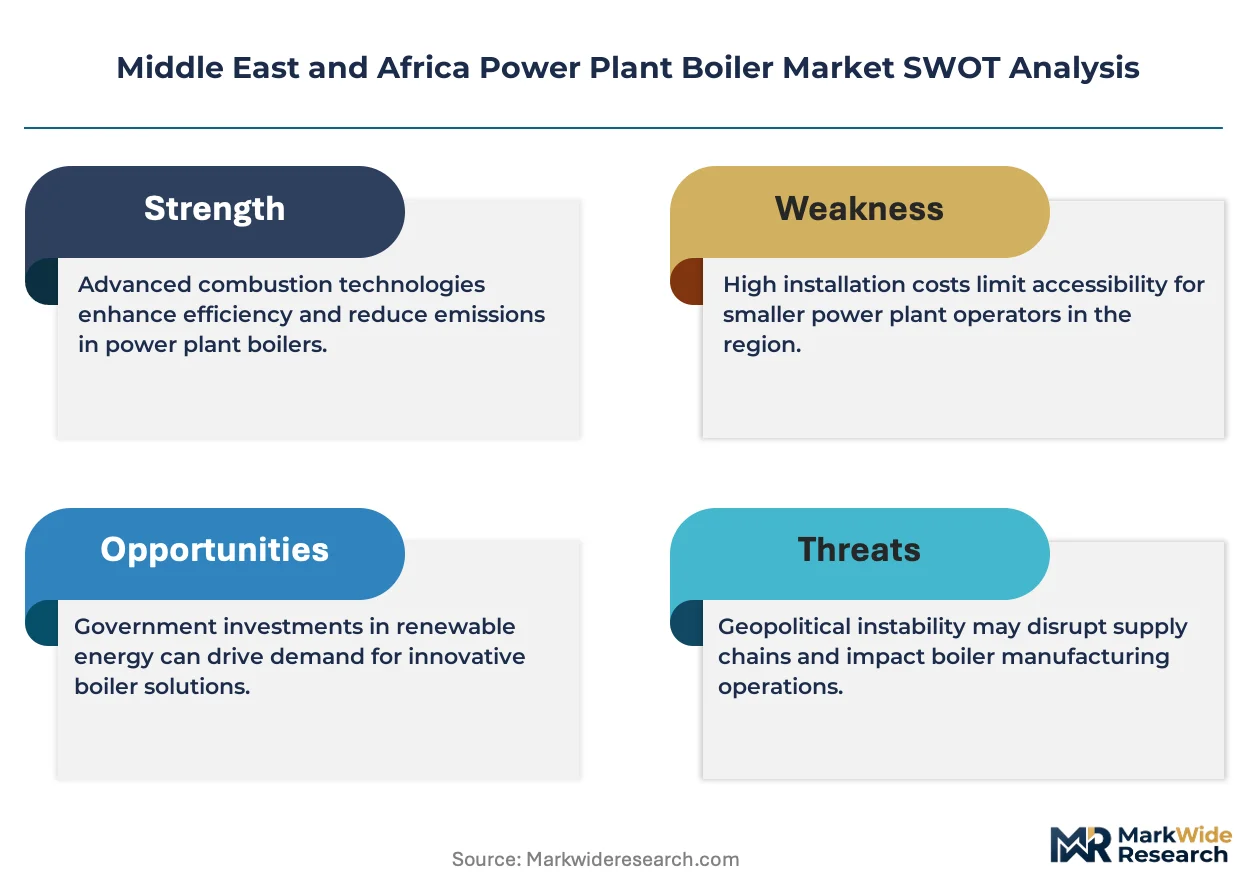
Alloy steel tubing is rebalancing cost structures across supercritical boiler fabrication as nickel-chrome-molybdenum grades replace carbon-steel pressure boundaries. Siemens AG leverages its European forging partnerships to sustain high-alloy rotor and drum supply chains into Middle Eastern projects. Bharat Heavy Electrical Limited anchors its regional presence through technology licensing arrangements with local EPC contractors. Doosan Heavy Industries & Construction competes on seawater-cooled boiler island designs tailored for Red Sea and Arabian Gulf coastal sites.
A power plant boiler is a closed pressure vessel that converts feedwater into high-temperature, high-pressure steam through combustion or heat recovery, operating at thresholds exceeding 540°C and 250 bar in supercritical configurations to drive steam turbine generators for electricity production. Supercritical units command the premium project pipeline across the Middle East and Africa as governments prioritize thermal efficiency above 40% to stretch domestic gas reserves. Natural gas-fired boilers dominate new order books by fuel type, though biomass co-firing gains traction in East African sugar and paper complexes with captive fuel supplies. The utility end-user segment occupies the largest capital allocation, while industrial combined heat and power applications in petrochemical zones represent the fastest-growing margin pool.
Saudi Arabia's SFDA and the UAE's MOHAP oversee industrial safety certifications that intersect with pressure equipment standards, while South Africa's central energy regulator enforces emission limits on coal-fired baseload units that directly shape boiler technology selection. Egypt's environmental compliance framework for Mediterranean coastal plants is tightening particulate and NOx thresholds, forcing retrofits or supercritical replacements on aging subcritical assets. Stakeholders must monitor how carbon border adjustments and domestic hydrogen blending mandates recalibrate long-term fuel strategy for boiler fleets across the region.
Market Dynamics
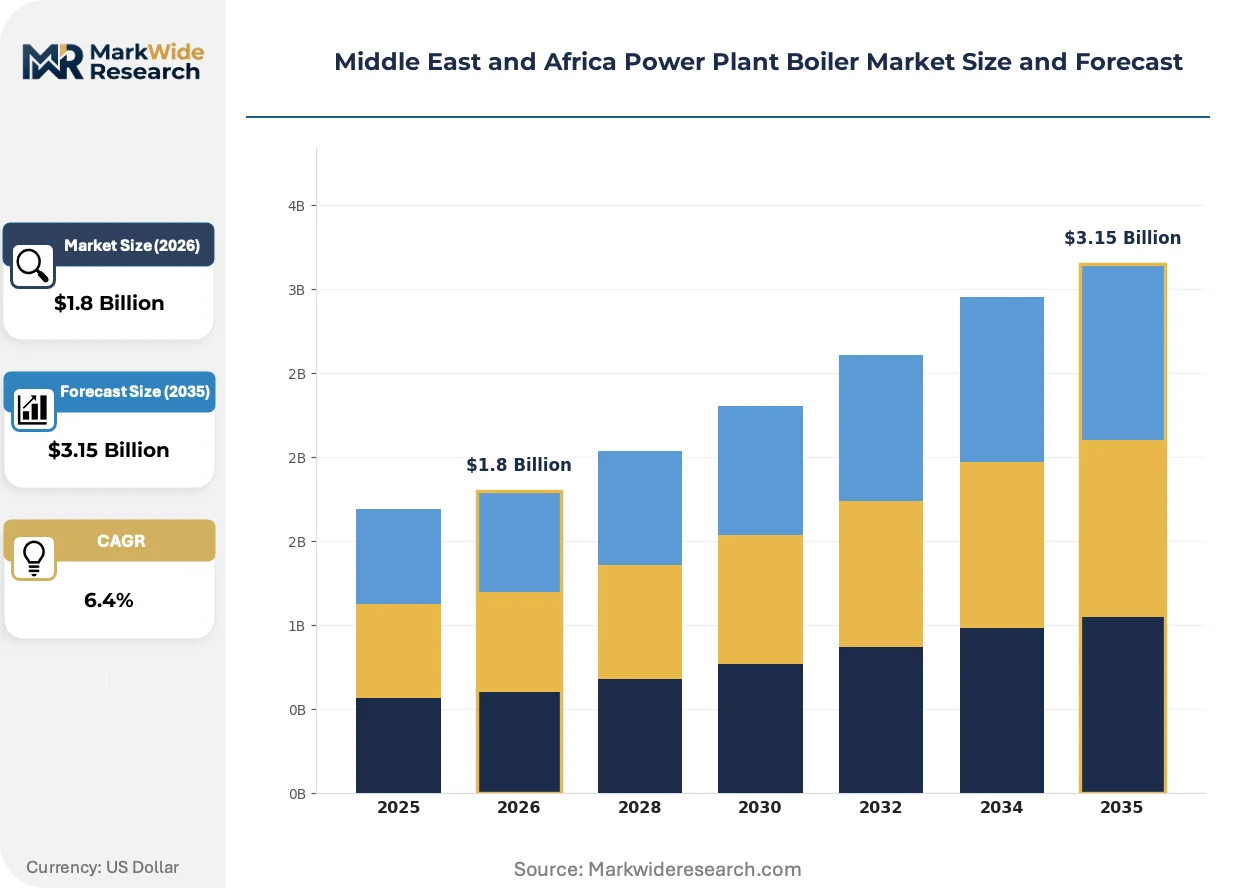
The Middle East and Africa power plant boiler market is being restructured by the region's pivot toward supercritical steam cycles, driven by Saudi Arabia and the UAE's mandates to stretch domestic gas reserves through efficiency gains above 40 percent thermal conversion.
Growth Catalysts
- SFDA Pressure Equipment Standards:Saudi Arabia's safety certification framework for industrial boilers is accelerating replacement cycles for aging subcritical units along the Red Sea coast.
- Desalination-Power Cogeneration:Saudi Arabia's integrated water-power complexes are driving procurement of high-capacity boiler islands designed for simultaneous steam extraction.
- Supercritical Alloy Advances:Nickel-chrome-molybdenum tubing grades are enabling higher pressure boundaries that cut fuel consumption per megawatt-hour.
Market Restraints
- High-Alloy Steel Supply Concentration:European forging partnerships control rotor and drum supply chains, creating bottlenecks for Middle Eastern EPC timelines.
- South African Emission Limits:The central energy regulator's tightening NOx and particulate thresholds on coal-fired baseload units are forcing premature asset retirement before capital recovery.
- Seawater Corrosion Engineering:Coastal Red Sea and Arabian Gulf sites require specialized metallurgy that adds 15-20 percent to boiler island fabrication costs.
Strategic Opportunities
- East African Biomass Co-Firing:Sugar and paper complexes in Kenya and Ethiopia with captive bagasse and wood waste supplies represent untapped demand for stoker-grate boiler retrofits.
- Egyptian Mediterranean Retrofits:Egypt's environmental compliance framework for coastal plants is creating replacement demand as aging subcritical assets face particulate threshold violations.
- Hydrogen Blending Readiness:UAE dual carbon goals are mandating boiler procurement specifications compatible with future hydrogen-natural gas fuel mixing.
Industry Challenges
- Welding Certification Bottlenecks:ASME Section IX and EN 287-1 qualified welders for high-alloy pressure boundaries remain scarce across Saudi and Emirati fabrication yards.
- Technology Licensing Complexity:Local EPC contractors in the Gulf face protracted negotiations with European and Asian boiler technology licensors over performance guarantees and IP transfer terms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Power Plant Boiler Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Boiler Type: Supercritical, Subcritical, Organic Rankine Cycle, Heat Recovery Steam Generator Fuel Type: Coal, Natural Gas, Biomass, Oil End User: Utilities, Industrial, Commercial, Residential Application: Power Generation, Process Heat, District Heating, Combined Heat and Power |
| Companies Covered | Mitsubishi Hitachi Power Systems, Dongfang Electric Corporation, Siemens AG, Andritz Group, IHI Corporation, Babcock & Wilcox Enterprise, General Electric, Bharat Heavy Electrical Limited, Doosan Heavy Industries & Construction, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Power Plant Boiler Market Shifts & Advancements
Boiler system architecture across the Middle East and Africa is being reconfigured by three intersecting forces: the physical scale of supercritical units, the regulatory compression of emission budgets, and the restructuring of how utilities contract for thermal assets.
Once-through supercritical boiler designs are modularizing project delivery for Saudi desalination-power complexes. These units integrate feedwater heating, steam generation, and reheat stages within single pressure-boundary structures that slash footprint by 30 percent versus drum-type subcritical configurations. Saudi Aramco and ACWA Power are specifying these designs for Ras Al-Khair and Jubail Industrial City expansions, compressing EPC schedules from 42 to 30 months.
Egypt's environmental compliance framework for Mediterranean coastal plants is forcing particulate and NOx threshold reductions that obsolete subcritical pulverized coal assets. The regulation mandates continuous emissions monitoring systems and selective catalytic reduction retrofits by 2027, pushing Cairo's East Delta and West Damietta plants toward supercritical replacement rather than marginal upgrades. Egyptian Electricity Holding Company procurement is now prioritizing units with 45 percent thermal efficiency minimums.
Long-term service agreements are displacing traditional equipment-only contracts across UAE and Saudi utility procurement. Buyers now unbundle boiler island supply from 15-year operation and maintenance packages, transferring performance risk to OEM-EP consortia. This restructuring is most visible in Dubai's Hassyan clean coal project and Saudi PIF-backed greenfield developments, where availability guarantees above 92 percent are now standard tender requirements.
Middle East and Africa Power Plant Boiler Market Segmentation
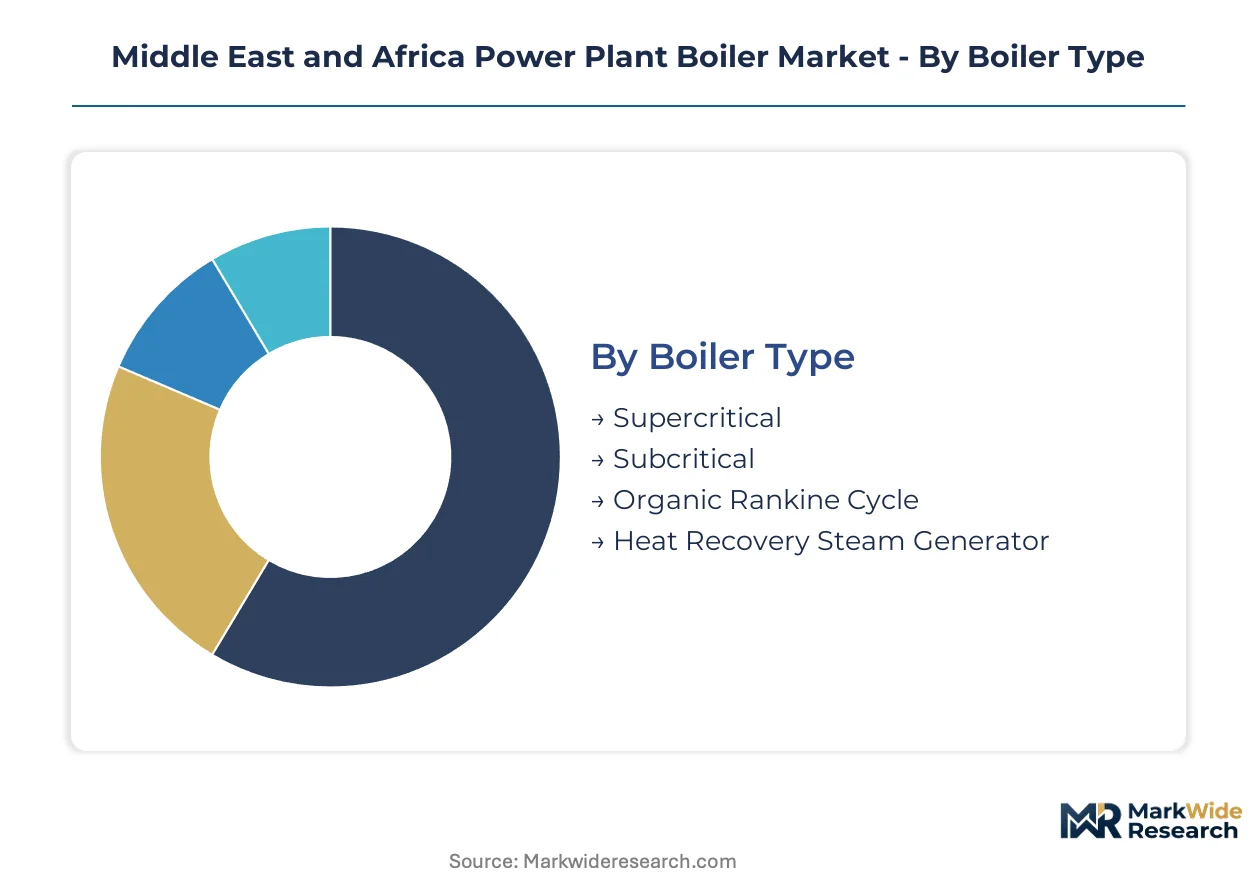
Boiler procurement across the Middle East and Africa fragments across pressure-cycle technology, fuel source, and end-use economics. Each segmentation axis determines metallurgy requirements, emission compliance pathways, and long-term service contract structures.
Boiler Type:
Capital intensity peaks with supercritical units demanding nickel-chrome-molybdenum pressure boundaries and European-forged rotors, while subcritical assets carry lower upfront costs but higher lifetime fuel burn.
- Supercritical:Once-through designs operate above 540°C and 250 bar, converting feedwater directly to steam without drum separation. Saudi Aramco and ACWA Power specify these for Ras Al-Khair desalination-power complexes where thermal efficiency above 40 percent stretches domestic gas reserves.
- Subcritical:Drum-type configurations with steam-water separation remain prevalent across Egypt's aging Mediterranean fleet. Cairo's East Delta and West Damietta plants face replacement pressure as environmental thresholds tighten particulate and NOx limits.
- Organic Rankine Cycle:Low-temperature heat recovery systems suit geothermal and waste-heat applications in East African industrial zones.
- Heat Recovery Steam Generator:Combined-cycle integration captures gas turbine exhaust for supplementary steam generation across UAE greenfield developments.
Supercritical units absorb the bulk of installed capacity; Heat Recovery Steam Generators are expanding most quickly as combined-cycle configurations dominate UAE and Saudi procurement.
Fuel Type:
Feedstock selection determines emission compliance burden, metallurgy specifications for corrosive combustion products, and long-term fuel price exposure across 15-25 year asset lifecycles.
- Natural Gas:Dominates new order books across Saudi Arabia and the UAE where domestic reserves and dual carbon goals favor lower-carbon baseload. Procurement specifications increasingly mandate hydrogen blending readiness for future fuel flexibility.
- Biomass:Bagasse and wood waste co-firing gains traction in Kenyan and Ethiopian sugar and paper complexes with captive fuel supplies and stoker-grate retrofit demand.
- Coal:Concentrated in South African baseload replacement cycles and Dubai's Hassyan clean coal project where supercritical efficiency offsets emission compliance costs.
- Oil:Residual fuel oil units persist in remote off-grid locations and backup power applications across North African coastal installations.
Natural Gas claims the largest share of new capital deployment; Biomass is climbing the fastest as East African industrial complexes exploit captive waste streams.
End User:
Contracting structures diverge sharply between utility-scale availability guarantees and industrial combined heat and power margin optimization.
- Utilities:Saudi Electricity Company and Egyptian Electricity Holding Company drive procurement through 15-year operation and maintenance unbundling, transferring performance risk to OEM-EP consortia with 92 percent availability guarantees.
- Industrial:Petrochemical zones in Jubail and Yanbu represent the steepest expansion trajectory as combined heat and power configurations optimize steam extraction for process applications.
- Commercial:District cooling and desalination complexes in UAE urban centers require mid-scale boiler islands with flexible load-following capability.
- Residential:Micro-cogeneration and small-scale district heating applications remain marginal across the region's climate and infrastructure profile.
Utilities command the dominant capital allocation; Industrial end users are gaining share fastest as petrochemical expansion accelerates across Saudi Arabia's Red Sea coast.
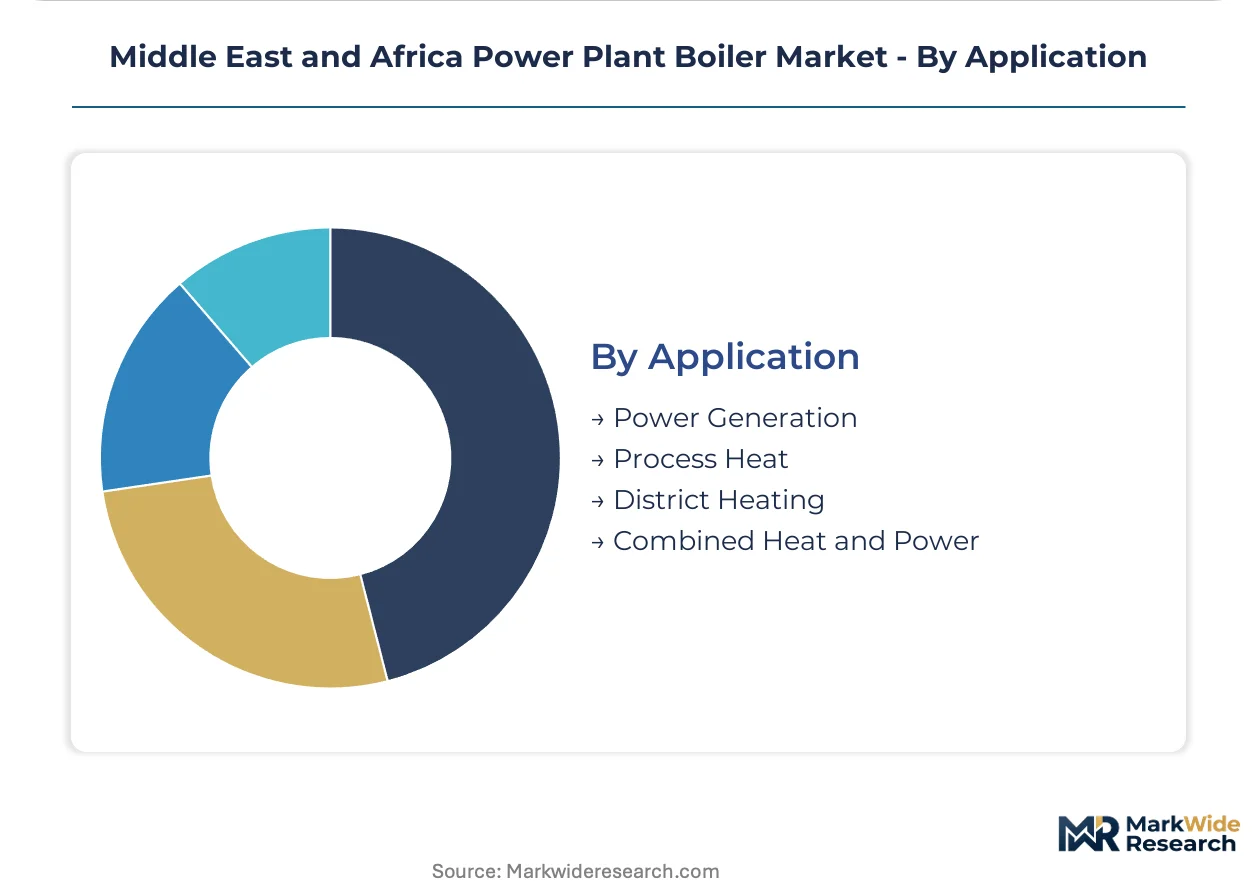
Application:
Steam use-case determines pressure-temperature profiles, extraction configurations, and integration complexity with desalination or process heat networks.
- Power Generation:Pure electricity production remains the default specification for Saudi and Egyptian utility procurement, with supercritical efficiency mandates above 40 percent thermal conversion.
- Combined Heat and Power:Simultaneous steam extraction for industrial process or desalination distillation commands premium configurations across Saudi Arabia's integrated water-power complexes.
- Process Heat:Dedicated steam supply for refineries and chemical plants requires pressure stability and redundancy engineering in Jubail Industrial City expansions.
- District Heating:Seasonal load variation and distribution network integration constrain deployment to high-density urban clusters in Morocco and Tunisia.
Power Generation retains the largest installed footprint; Combined Heat and Power is expanding most rapidly as cogeneration economics improve across desalination-integrated sites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for power plant boilers concentrates in Saudi Arabia's desalination-power complexes and South Africa's industrial baseload replacement cycle. The UAE's dual carbon mandates redirect procurement toward supercritical configurations. Egypt's Mediterranean coastal plants face tightening emission thresholds that accelerate asset replacement timelines.
Saudi Arabia
Saudi Aramco and ACWA Power are scaling procurement for Ras Al-Khair and Jubail Industrial City expansions with once-through supercritical designs. SFDA pressure equipment standards accelerate replacement cycles for aging subcritical units along the Red Sea coast. The Eastern Province hosts concentrated EPC activity where 30-month compressed construction schedules are now standard tender requirements.
United Arab Emirates
Dubai's Hassyan clean coal project and Abu Dhabi greenfield developments specify 92 percent availability guarantees through unbundled 15-year operation and maintenance contracts. MOHAP industrial safety certifications intersect with procurement specifications mandating hydrogen blending readiness for future fuel flexibility. Coastal Arabian Gulf sites require specialized seawater-cooled metallurgy that adds fabrication premiums.
South Africa
The central energy regulator's tightening NOx and particulate thresholds on coal-fired baseload units are forcing premature asset retirement before capital recovery. Eskom's procurement prioritizes supercritical replacements that stretch domestic coal reserves through thermal efficiency gains above 40 percent. Industrial zones around Johannesburg and Durban drive combined heat and power configurations for petrochemical process steam.
Egypt
Cairo's East Delta and West Damietta plants face particulate threshold violations under Mediterranean coastal environmental compliance frameworks. Egyptian Electricity Holding Company procurement now mandates 45 percent thermal efficiency minimums that obsolete subcritical pulverized coal assets. The Suez Canal Economic Zone concentrates new supercritical installations with continuous emissions monitoring systems required by 2027.
Israel
Natural gas-fired supercritical units dominate procurement as the Tamar and Leviathan fields anchor domestic fuel supply security. The Ministry of Environmental Protection enforces emission budgets that favor combined-cycle configurations with heat recovery steam generators. Haifa's industrial corridor and Ashkelon coastal complexes represent the primary demand clusters for high-efficiency boiler islands.
Middle East and Africa Power Plant Boiler Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with European forging partnerships controlling high-alloy rotor and drum supply chains while Asian fabricators compete on modular project delivery. The market structures around three tiers: technology licensors with performance guarantee capabilities, regional EPC contractors with local certification relationships, and specialized metallurgy suppliers for seawater-cooled coastal specifications. Strategic moves concentrate on technology licensing arrangements with IP transfer terms and 15-year service unbundling that transfers operational risk to OEM consortia.
Among Asian boiler fabricators, Dongfang Electric Corporation and IHI Corporation exemplify the scale-driven archetype with supercritical pressure boundary capabilities. Siemens AG anchors the European technology licensing tier through forging partnerships that sustain high-alloy supply chains into Middle Eastern projects. Bharat Heavy Electrical Limited occupies a distinct position within the regional contractor ecosystem through arrangements with local EPC partners across the Gulf.
| Leading Market Players |
|---|
| Mitsubishi Hitachi Power Systems |
| Dongfang Electric Corporation |
| Siemens AG |
| Andritz Group |
| IHI Corporation |
| Babcock & Wilcox Enterprise |
| General Electric |
| Bharat Heavy Electrical Limited |
| Doosan Heavy Industries & Construction |
| Others |
Supply & Pricing Matrix
Saudi Aramco's compressed 30-month tender schedules for Ras Al-Khair expansions are forcing European forging partners to reallocate high-alloy rotor capacity, tightening supply responsiveness and elevating fabrication premiums for nickel-chrome-molybdenum pressure boundaries.
Pricing Analysis
Volume procurement by Saudi Electricity Company and Egyptian Electricity Holding Company commands project-based contract structures with 15-year operation and maintenance unbundling, while smaller industrial CHP buyers in Jubail and Yanbu face spot-market exposure for standard subcritical units. Price differentiation rests on ASME Section IX welding certification tiers and hydrogen-blending readiness specifications mandated by UAE dual carbon goals. Cost compression in standard drum-type configurations is intensifying as Asian fabricators modularize delivery. Industrial petrochemical zones show least price sensitivity due to process steam margin optimization, while East African biomass retrofit buyers prioritize lowest capital outlay.
Supply Chain Analysis
Welder certification scarcity across Saudi and Emirati fabrication yards is extending European and South Korean manufacturing backlogs for supercritical pressure boundaries. Geographic supply concentration centers on Germany, Japan, and South Korea for high-alloy forgings, with India anchoring stoker-grate fabrication for East African biomass applications. Raw material dependencies include Indonesian nickel, South African chromium, and Australian molybdenum for supercritical tubing grades. Single-source vulnerability runs through European rotor and drum supply chains controlled by Siemens AG forging partnerships. Distribution runs through EPC contractor consortia with local SFDA and MOHAP certification relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa power plant boiler market is executing a technology-transition phase as once-through supercritical designs displace drum-type subcritical assets across Saudi desalination-power complexes and Egyptian Mediterranean retrofits.
For Market Incumbents: Anchor high-alloy forging partnerships through exclusive capacity reservations with European suppliers to defend against Asian modular fabricators gaining share in standard configurations. Deepen backward integration into nickel-chrome-molybdenum tubing supply through captive arrangements with Indian metallurgy specialists. Prioritize welding certification academy investments in Saudi Arabia's Eastern Province to alleviate ASME Section IX bottlenecks threatening EPC timelines. For New Entrants and Emerging Players: The premium-to-economy price gap in hydrogen-blending-ready specifications opens white-space targeting for modular HRSG specialists serving UAE combined-cycle greenfield developments. East African biomass co-firing retrofits in Kenyan and Ethiopian sugar complexes represent the most penetrable segment given captive bagasse supply and absent incumbent service infrastructure. A licensing-plus-local-fabrication go-to-market angle bypasses European forging dependencies while satisfying SFDA pressure equipment standards. For Investors and Strategic Acquirers: Re-rating potential sits with EPC contractors possessing MOHAP and SFDA certification relationships given accelerating supercritical procurement timelines across the Gulf. Long-term viability over the analysis window favors consortia with unbundled 15-year service contract capabilities transferring operational risk from utility buyers. The signal to watch is Egyptian Electricity Holding Company tender releases for Mediterranean coastal retrofits mandating 45 percent thermal efficiency minimums.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Arrangement | Bharat Heavy Electrical Limited leverages IP transfer terms to anchor Gulf EPC partnerships for supercritical deployments. |
| Backward Integration into High-Alloy Supply | Captive nickel-chrome-molybdenum sourcing reduces European forging dependency for Saudi Red Sea coastal projects. |
| Long-term Service Agreement Unbundling | 15-year O&M contracts with 92 percent availability guarantees transfer performance risk to OEM consortia across UAE procurement. |
| Welding Certification Academy Investment | ASME Section IX qualified welder pipelines alleviate fabrication bottlenecks in Saudi Aramco's compressed tender schedules. |
| Hydrogen Blending Readiness Specification | MOHAP-mandated fuel flexibility future-proofs natural gas-fired units against UAE dual carbon policy evolution. |
Research Methodology
Regulatory filings from SFDA, MOHAP, and Egypt's environmental compliance framework, trade databases tracking high-alloy steel imports, and EPC contract award announcements formed the secondary backbone. Primary interviews with utility planning officers at Saudi Electricity Company, IPP project developers at ACWA Power, EPC contractors in the Eastern Province, and aftermarket service heads at Doosan Heavy Industries validated demand assumptions. Bottom-up unit deployment tallies across desalination-power complexes and top-down macro energy demand projections were triangulated to anchor market sizing.
Historical trendline analysis of supercritical adoption rates, subcritical retirement timelines, and combined-cycle capacity additions informed the projection framework. Segmentation dimensions modeled include pressure-cycle technology, fuel source, end-user economics, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to utility capital expenditure plans and industrial CHP expansion pipelines. Forecast inputs incorporated domestic gas reserve depletion trajectories and hydrogen blending mandate evolution across the Gulf.
Inputs from EPC contract databases and environmental compliance filings were available through the study window; gaps in proprietary forging capacity utilization data introduce uncertainty bands around high-alloy supply constraints. Forecasts reflect assumptions regarding welding certification pipeline expansion and European supplier capacity allocation priorities. Material deviation in Saudi PIF-backed greenfield tender timelines or Egyptian regulatory enforcement acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Fuel Operated Heaters Market
Boilers
Advanced Utility Boilers Market
Boilers
Electric Boiler Market
Boilers
Global Fuel Flexible Boiler Market
Boilers
Asia-Pacific Power Plant Boiler Market
Boilers
Gas Fired Boilers Market
Boilers
Residential Boiler Market
Boilers
Watertube Boilers Market
Boilers
Coal-Saving Combustion-Supporting Agent Market
Boilers
District Heating Market
Boilers
North America and Europe Electric Boilers Market
Boilers
Micro Combined Heat and Power (CHP) Market
Boilers
Waste Heat Boiler Market
Boilers
Biomass Boiler Market
Boilers
Superheater Tubes Market
Boilers
US Commercial Boiler Market