
 Europe Residential Boiler Market | 2026-2036
Europe Residential Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Residential Boiler Market Analysis
Retrofit-oriented homeowners are reorganizing demand patterns across the Europe Residential Boiler Market as energy renovation mandates intensify. Viessmann leverages its hydronic expertise to dominate premium condensing lines in German-speaking markets. Bosch Thermotechnology anchors mid-market gas-to-hybrid transitions through integrated control systems. Ariston Holding competes aggressively on compact combi formats tailored to Mediterranean apartment stock.
A residential boiler is a pressure vessel that heats water or generates steam for space heating and domestic hot water, typically operating at 1-3 bar with efficiency ratings governed by seasonal performance metrics. Gas-fired combi boilers lead volume across Northern Europe, while biomass systems carve margin pools in Alpine rural zones where district heating penetration remains low. Smart technology integration is the fastest-growing segment as connected thermostats and modulation protocols reshape replacement cycles.
The EU Green Deal, Ecodesign Directive, and F-Gas Regulation collectively mandate minimum efficiency thresholds and restrict high-GWP refrigerants in hybrid heat-pump combinations. CE marking and national building codes in France, Italy, and Poland create fragmented compliance landscapes that favor manufacturers with modular certification capabilities. Stakeholders must monitor how national heat pump deployment targets reshape boiler replacement incentives and channel economics.
Market Dynamics
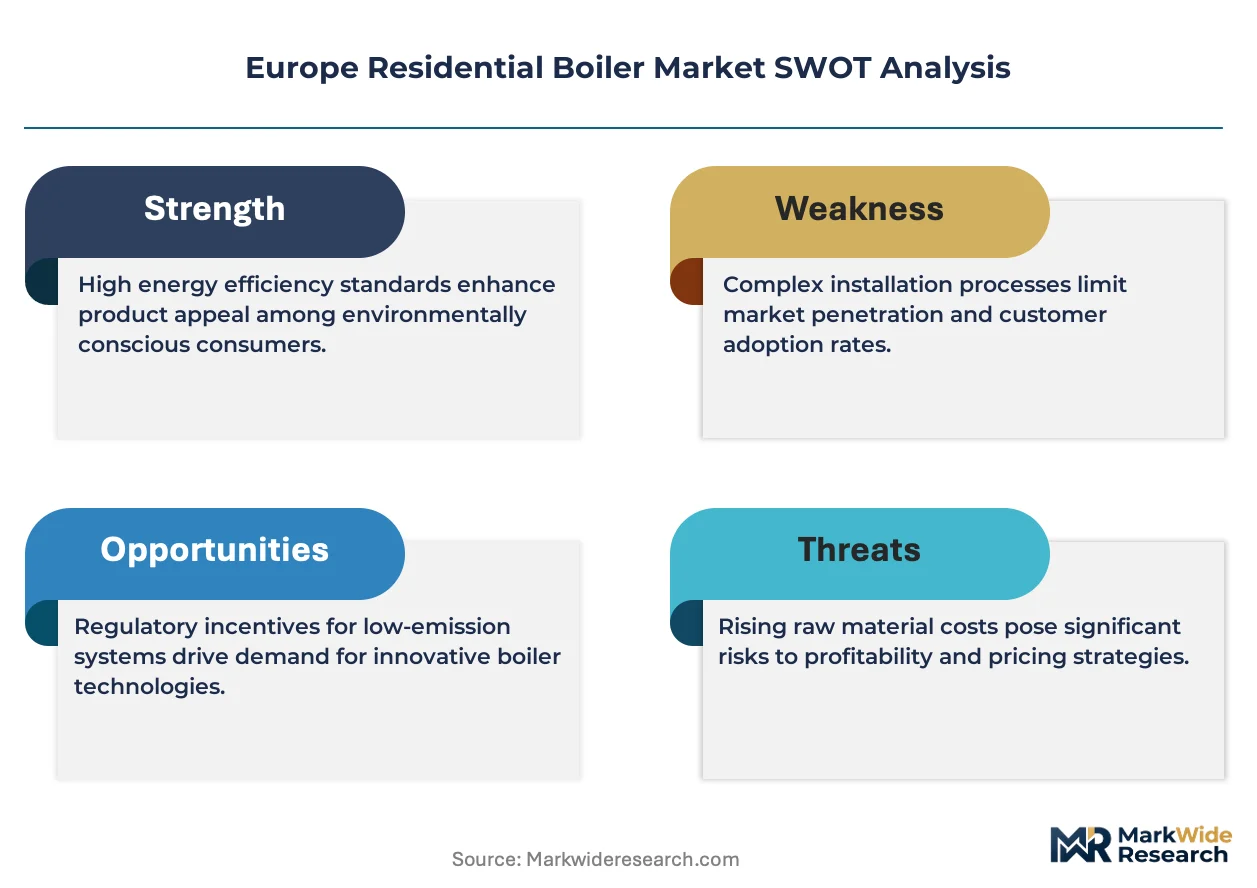
The EU Green Deal and F-Gas Regulation are forcing a wholesale reconfiguration of Europe's heating infrastructure, compelling manufacturers to pivot from pure combustion systems toward hybrid-ready platforms that bridge fossil and electric heat sources.
Growth Catalysts
- Retrofit mandates in aging urban housing:Germany's building energy law and France's renovation wave are accelerating replacement cycles in post-war apartment blocks.
- Condensing technology maturation:Seasonal efficiency thresholds under the Ecodesign Directive are pushing non-condensing units out of distribution channels.
- Alpine biomass carve-outs:Rural zones in Austria and Switzerland with limited district heating access are sustaining premium margins for pellet-fired systems.
Market Restraints
- Copper and stainless steel input volatility:Heat exchanger material costs swing with commodity markets, compressing OEM margins on mid-range combi units.
- Heat pump substitution acceleration:National deployment targets in the Netherlands and Denmark are redirecting subsidies away from gas-only boilers.
- CE marking fragmentation:Divergent national building codes in Italy, Poland, and Belgium multiply certification burdens for cross-border suppliers.
Strategic Opportunities
- Polish and Romanian new-build penetration:These markets show low heat pump saturation and rising mortgage-linked efficiency requirements.
- Hybrid system convergence:Gas boiler-electric heat pump combinations capture incentives under the EU Green Deal while hedging grid capacity constraints.
- Digital service channel expansion:Remote diagnostics and predictive maintenance contracts are displacing traditional installer relationships in the United Kingdom.
Industry Challenges
- Hydronics-software integration gap:Manufacturers struggle to recruit control systems engineers capable of embedding IoT modulation protocols.
- Legacy system interoperability:Installer networks face retraining costs to configure smart thermostats with 20-year-old radiator circuits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Residential Boiler Market |
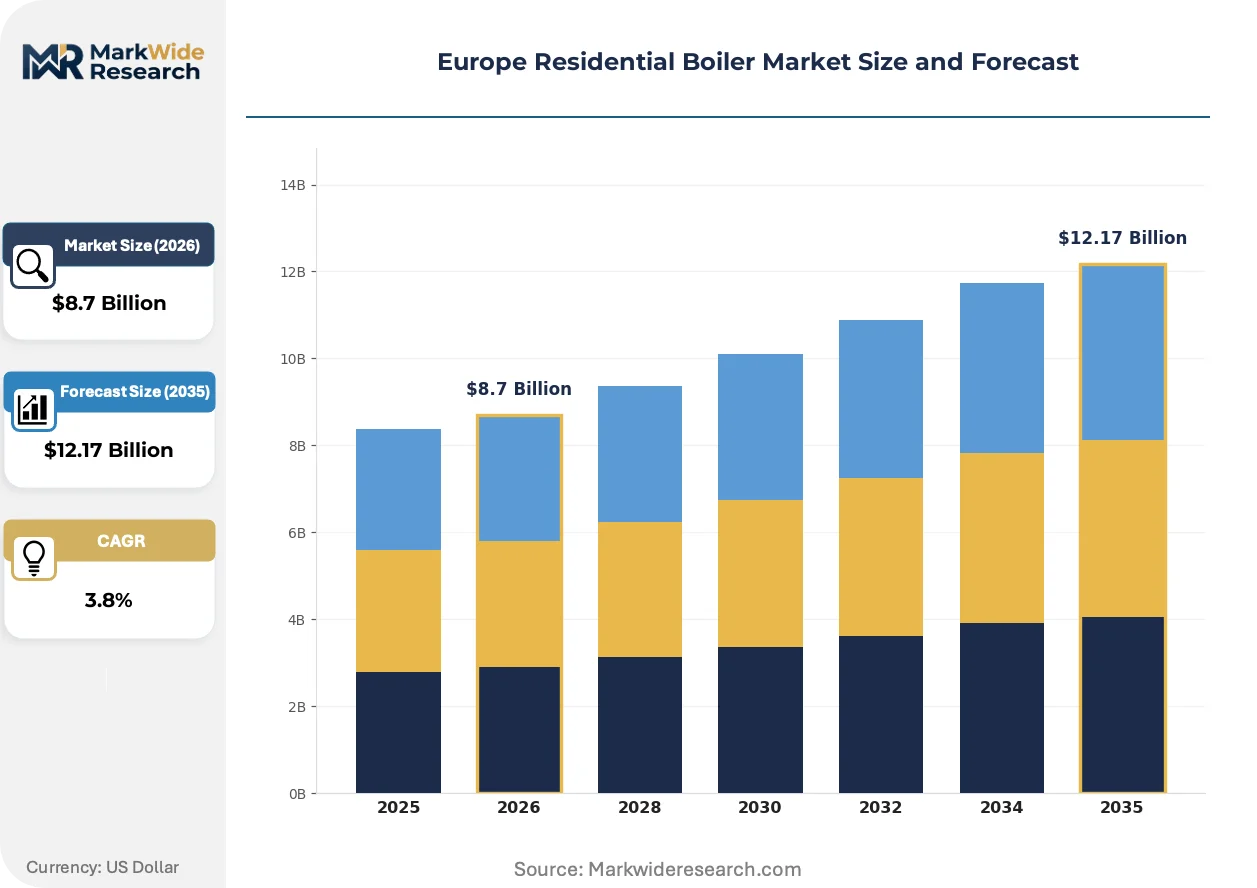
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Gas, Oil, Electric, Biomass Boiler Type: Combi, System, Regular, Condensing Technology: Conventional, Smart, Hybrid, Economical Installation Type: New Build, Retrofit, Replacement, Maintenance |
| Companies Covered | Bosch Thermotechnology, Immergas, Viessmann, Hoval, Daikin Industries, Vaillant Group, Ariston Holding, FERROLI, BDR Thermea Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Residential Boiler Market Emerging Trajectories
Modulation protocols and connected controls are compressing replacement cycles while regulatory pressure fuses hardware with software capabilities across European heating systems.
Modulating burner technology with sub-1:5 turn-down ratios is displacing fixed-output units in German and Austrian single-family retrofits. These systems match heat output to real-time demand, cutting cycling losses. Installers in the Rhine-Ruhr corridor are specifying them as standard for heat-pump-ready hydronic layouts.
The F-Gas Regulation is restricting refrigerant choices in hybrid heat-pump combinations, forcing boiler manufacturers to certify propane and CO2-based systems. This compresses product development timelines. Italian OEMs are accelerating R&D partnerships to secure CE marking ahead of the 2027 threshold reductions.
Homeowner purchasing patterns are fragmenting across digital and traditional channels. British consumers increasingly research efficiency ratings through comparison platforms before contacting installers. This disintermediation pressures merchant distributors to add configuration tools and financing interfaces to retain specification influence.
Europe Residential Boiler Market Segmentation
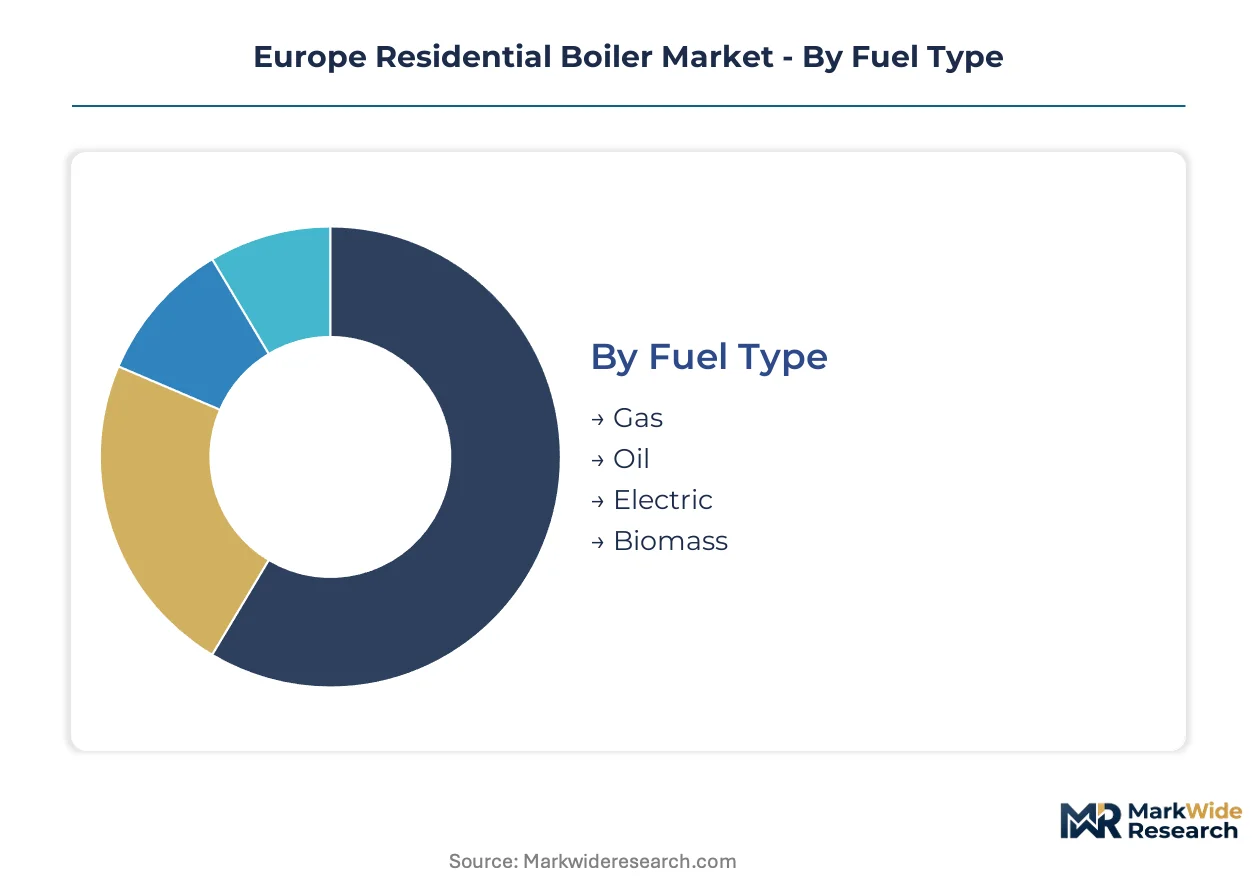
Segmentation in the Europe Residential Boiler Market reveals how regulatory pressure and infrastructure legacy reshape procurement decisions. Fuel availability, building stock age, and national efficiency mandates fragment demand across otherwise standardized product categories.
Fuel Type:
Ecodesign Directive thresholds and F-Gas Regulation refrigerant restrictions create divergent compliance burdens across combustion technologies.
- Gas:Natural gas-fired units dominate volume in Germany, Italy, and the United Kingdom where distribution infrastructure remains dense. Ecodesign seasonal efficiency mandates are accelerating condensing unit penetration while hybrid-ready platforms capture renovation subsidies.
- Oil:Kerosene and heating oil systems persist in rural France, Ireland, and parts of Eastern Europe beyond gas grid reach. Carbon taxation under the EU Green Deal is eroding total cost of ownership advantages against biomass alternatives.
- Electric:Resistance and electrode boilers serve Alpine apartments and Scandinavian districts with low-carbon grid intensity. Heat pump substitution is compressing pure electric boiler share in the Netherlands and Denmark.
- Biomass:Pellet and wood-chip systems command premium margins in Austrian and Swiss rural zones where district heating penetration remains minimal.
Established volume favors Gas; emerging adoption favors Biomass.
Boiler Type:
Building stock characteristics and hot water demand patterns determine specification splits across Northern and Mediterranean Europe.
- Combi:Single-unit space and domestic hot water systems dominate British and Irish retrofits where cylinder space is constrained. Modulating burner technology with sub-1:5 turn-down ratios is displacing fixed-output variants in Rhine-Ruhr corridor renovations.
- System:Separated hot water cylinder configurations serve German and Austrian multi-bathroom households with higher simultaneous demand. Heat-pump-ready hydronic layouts are standardizing around system boiler architectures.
- Regular:Traditional heat-only units persist in legacy British housing with existing gravity-fed hot water tanks. Replacement cycles are shortening as efficiency regulations render non-condensing regular boilers non-compliant.
- Condensing:Secondary heat exchanger technology capturing latent flue gas energy is now baseline for CE marking across all EU member states.
Combi holds the steepest expansion trajectory in urban retrofits; Regular contracts fastest in legacy housing zones.
Technology:
Digital capability and energy source integration are redefining product tier boundaries beyond traditional efficiency metrics.
- Conventional:Basic on/off control systems without connectivity retain share in Polish and Romanian price-sensitive new-build segments. CE marking compliance without smart features suffices for minimum regulatory entry.
- Smart:Connected thermostats, modulation protocols, and remote diagnostics are compressing replacement cycles in the United Kingdom. Predictive maintenance contracts are displacing traditional installer relationships.
- Hybrid:Gas boiler-electric heat pump combinations capture EU Green Deal incentives while hedging grid capacity constraints. F-Gas Regulation refrigerant restrictions are forcing propane and CO2-based system certifications.
- Economical:Stripped-down condensing units without connectivity serve budget renovation segments in Southern and Eastern Europe.
Smart technology is gaining share fastest in mature Western markets; Hybrid platforms expand most quickly where heat pump targets reshape subsidy structures.
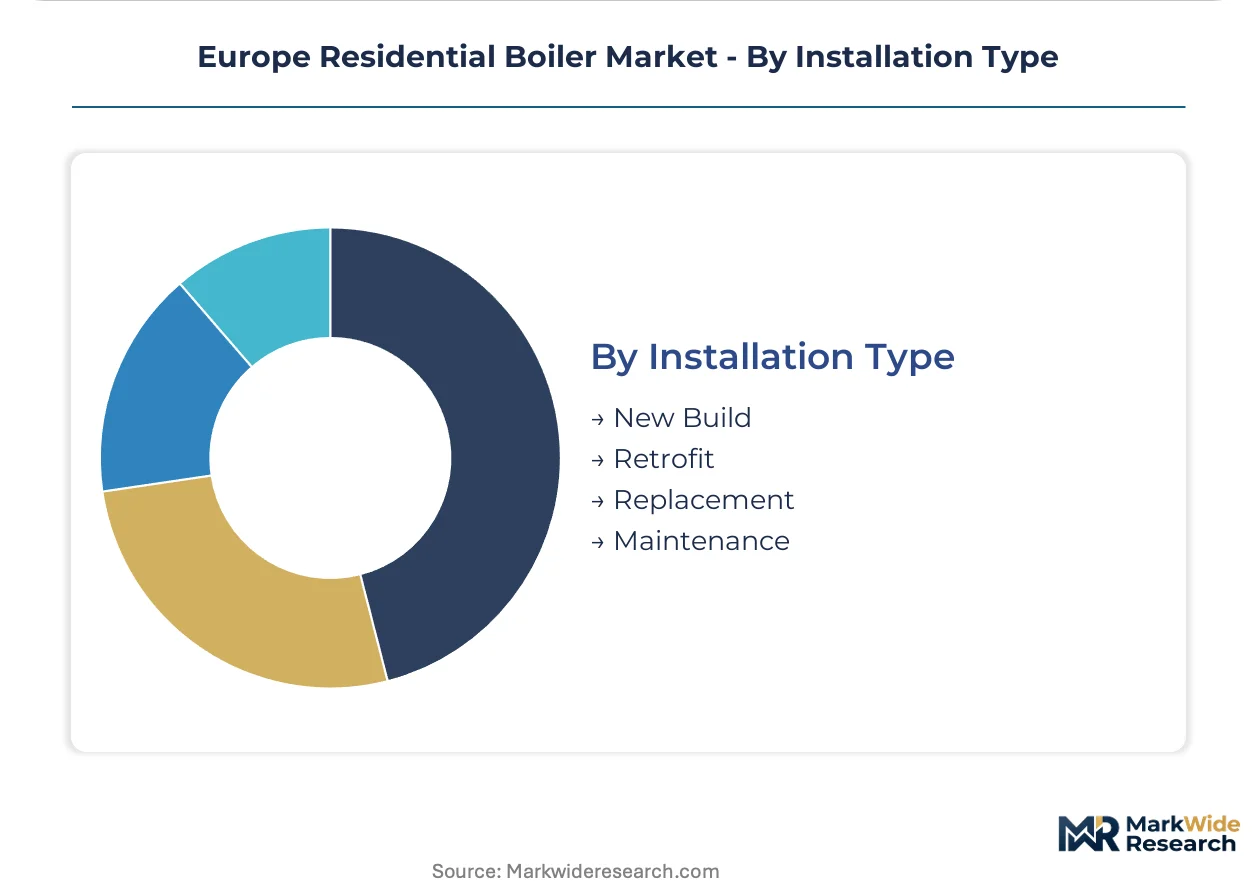
Installation Type:
Construction cycle timing and regulatory enforcement intensity determine channel economics across replacement and new-build flows.
- New Build:Boiler specifications locked at architectural design stage in Poland and Romania where mortgage-linked efficiency requirements are rising. Heat pump-ready hydronic pre-installation is becoming standard.
- Retrofit:Energy renovation mandates in Germany's building energy law and France's renovation wave are accelerating replacement cycles in post-war apartment blocks. Installer networks face retraining costs for smart thermostat configuration.
- Replacement:Emergency failure-driven procurement dominates British and Irish volume, compressing decision timelines and specification research.
- Maintenance:Service contract attachment rates are rising as OEMs deploy remote diagnostics platforms to secure recurring revenue streams.
Retrofit commands the largest absolute volume; New Build offers the steadiest specification pipeline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea-Baltic gas grid interconnector underwrites Germany's central role in European heating infrastructure, channeling distribution capacity across the continent's densest pipeline network. This asset anchors retrofit demand cycles while enabling cross-border hydrogen blending trials that reshape boiler specifications.
Germany
Post-war apartment blocks in the Rhine-Ruhr corridor drive condensing boiler replacements as the Building Energy Law tightens efficiency mandates. The Federal Network Agency regulates grid conversion timelines for hydrogen-ready appliances. Viessmann's Wolfsburg engineering cluster supplies modulation technology for heat-pump-ready hydronic layouts across Bavaria and Baden-Württemberg.
United Kingdom
Emergency replacement cycles dominate British procurement patterns where combi boilers serve space-constrained Victorian terraces. The Boiler Upgrade Scheme redirects subsidies toward heat pumps while preserving gas boiler demand in off-grid rural zones. Greater Manchester's installer networks face retraining costs for smart thermostat configuration with legacy radiator circuits.
Italy
Mediterranean apartment stock sustains compact combi specifications as Ariston Holding targets efficiency renovations in Lombardy and Veneto. The National Recovery and Resilience Plan funds building envelope improvements that trigger boiler replacements. Emilia-Romagna's manufacturing belt produces pellet-fired systems for Alpine zones beyond gas grid reach.
France
Rural oil heating persists in Brittany and Normandy beyond gas infrastructure, though carbon taxation erodes cost advantages against biomass alternatives. The Renovation Wave accelerates condensing penetration in Île-de-France social housing blocks. Auvergne-Rhône-Alpes hosts testing facilities for propane-based hybrid heat-pump combinations under F-Gas Regulation timelines.
Poland
New-build mortgage-linked efficiency requirements drive boiler specifications in Warsaw and Kraków construction pipelines where heat pump saturation remains low. The Clean Air Programme subsidizes heating system upgrades in smog-affected Silesian municipalities. Lower Silesia's manufacturing corridor supplies stripped-down condensing units for price-sensitive Eastern European markets.
Europe Residential Boiler Market Vendor Landscape
Listed leaders compete with private specialists across capital structure and R&D intensity, creating a tiered competitive matrix where scale advantages clash with niche engineering depth. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with heating divisions, pure-play hydronic specialists with generational expertise, and HVAC crossovers leveraging heat pump synergies. Consolidation pressure intensifies as CE marking fragmentation raises compliance costs for sub-scale participants. M&A activity targets control systems capabilities while strategic partnerships secure refrigerant certification pathways under F-Gas Regulation thresholds.
Among German-based fabricators, Viessmann GmbH and Bosch Thermotechnology anchor the premium engineering tier through multigenerational hydronic expertise. Ariston Holding occupies a position within the Mediterranean efficiency-focused segment, exemplifying specialization in compact formats for space-constrained installations. These three entities represent divergent competitive responses to hybrid system convergence: conglomerate-backed scale, family-owned technical depth, and publicly traded regional focus.
| Leading Market Players |
|---|
| Bosch Thermotechnology |
| Immergas |
| Viessmann |
| Hoval |
| Daikin Industries |
| Vaillant Group |
| Ariston Holding |
| FERROLI |
| BDR Thermea Group |
| Others |
Supply Flow & Price Mechanics
Copper-to-aluminum heat exchanger substitution in mid-range combi units is simultaneously shifting procurement geography toward Turkish and Polish rolling mills and compressing OEM margins as buyers resist price premiums for legacy stainless steel configurations. This input transition reshapes tier boundaries across the European market.
Pricing Analysis
Volume-discount tiering structures separate premium Viessmann and Bosch configurations from economy stripped-down units sourced through Polish distributors. Price differentiation rests on CE marking tier, smart connectivity bundling, and installer certification depth. Cost compression in the economy tier is intensifying because Silesian manufacturers compete on stripped specification for Romanian new-build flows. Price sensitivity concentrates among Polish and Romanian first-time buyers, while German retrofit homeowners prioritize efficiency ratings over upfront outlay.
Supply Chain Analysis
Just-in-time inventory strategies dominate German and Austrian OEM assembly lines, though strategic stockpiling of copper and stainless steel persists among Italian pellet-boiler fabricators facing commodity volatility. Heat exchanger sourcing draws from Germany, Italy, and Turkey, with control system semiconductors anchored in Dutch and German electronics clusters. Single-source vulnerability concentrates in propane refrigerant supply for hybrid heat-pump combinations under F-Gas Regulation timelines. Distribution runs through merchant distributors in Britain, direct-to-installer channels in Germany, and retail hardware networks in Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is restructuring the Europe Residential Boiler Market as hydronic-software interoperability becomes the primary specification lever, with homeowner decision-making migrating toward connected control ecosystems that transcend individual hardware brands.
For Market Incumbents: Compound hydronic expertise with control systems acquisitions to defend against HVAC crossover entrants leveraging heat pump synergies. Backward integration into heat exchanger manufacturing in Poland secures margin control against Turkish aluminum roller competition. Certification investment in propane-based hybrid systems under F-Gas Regulation timelines preserves specification access. For New Entrants and Emerging Players: Lead with digital service platforms targeting British emergency replacement cycles where installer relationships fragment and comparison platforms disintermediate traditional distributors. Polish new-build penetration offers the most penetrable geography given low heat pump saturation and rising mortgage-linked efficiency requirements. Go-to-market execution should anchor on remote diagnostics bundling rather than hardware margin capture. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors control systems specialists over pure hardware fabricators, as software capability determines replacement cycle compression and recurring revenue attachment. Long-term viability across the projection horizon rests on IoT modulation protocol ownership and predictive maintenance contract penetration. Acquisition targets should display CE marking modularization across multiple national codes. The signal to watch as inflection indicator is national heat pump deployment target acceleration redirecting subsidy flows away from gas-only configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Control Systems Acquisition | Viessmann and Bosch are embedding IoT modulation protocols to compress replacement cycles. |
| Propane Refrigerant Certification | Italian OEMs are accelerating R&D partnerships to secure CE marking ahead of F-Gas threshold reductions. |
| Polish Manufacturing Footprint | Lower Silesia's corridor supplies stripped-down condensing units for price-sensitive Eastern European markets. |
| Remote Diagnostics Platform Launch | British OEMs are deploying predictive maintenance contracts to displace traditional installer relationships. |
| Hybrid System Convergence | Gas boiler-electric heat pump combinations capture EU Green Deal incentives while hedging grid constraints. |
Methodological Framework
The analysis maps gas-fired, oil, electric, and biomass boiler sub-sectors, each validated through hydronic system engineers, installer network heads, merchant distribution managers, and building energy regulators. Primary interviews with OEM product directors and national building code administrators combined with secondary validation through EU Ecodesign Directive filings, F-Gas Regulation compliance databases, and national renovation program disclosures. Bottom-up unit shipment modeling and top-down energy consumption triangulation anchored volume estimates.
Consistency checks against external benchmarks validated analytical framework outputs across the projection horizon. Segmentation dimensions modeled include fuel type, boiler architecture, technology tier, and installation channel, with regional regulatory cluster as an industry-specific overlay. CAGRs were derived through replacement cycle analysis and subsidy flow modeling, with heat pump substitution elasticity and copper price volatility as key forecast inputs.
Underlying assumptions cover subsidy continuity under EU Green Deal implementation, with deviation risk concentrated in national heat pump target acceleration and F-Gas Regulation refrigerant phase-out timelines. Revision becomes warranted when hydrogen-ready appliance certification crosses grid conversion feasibility thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
North America Residential Boiler Market
Boilers
District Heating Market
Boilers
Middle East and Africa Power Plant Boiler Market
Boilers
Residential Boiler Market
Boilers
Industrial Boiler MRO Market
Boilers
North America Commercial Boiler Market
Boilers
Waste Heat Boiler Market
Boilers
Hydrogen Boilers Market
Boilers
GCC Electric Water Heater Market
Boilers
Superheater Market
Boilers
Power Boiler Market
Boilers
Asia-Pacific Combined Heat and Power Market
Boilers
Brazil Combined Heat and Power Market
Boilers
Oil-Fired Boiler Market
Boilers
Global Domestic Boilers Market
Boilers
Gas Fired Boilers Market