
 United Kingdom Data Center Processor Market | 2026-2036
United Kingdom Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Data Center Processor Market Insights
Hyperscale cloud operators are unwinding legacy enterprise dominance in UK processor procurement. NVIDIA Corporation leverages its GPU architecture leadership to anchor AI training deployments across British colocation facilities. Intel Corporation competes through x86 server CPU refreshes targeting virtualization workloads at Tier-1 providers. ARM Holdings differentiates via energy-efficient core designs that sustain edge computing rollouts in Manchester and Birmingham metro zones.
Data center processors are integrated circuits engineered to execute compute workloads within centralized or distributed IT facilities, typically fabricated on sub-5nm process nodes with thermal design power ratings exceeding 200W for high-performance variants. These devices orchestrate virtualization, analytics, and machine learning pipelines across server racks. GPU segments command premium positioning as machine learning adoption deepens among UK financial services and pharmaceutical firms. CPU categories retain volume leadership in enterprise virtualization and legacy workload consolidation. FPGA deployments occupy specialized niches in low-latency trading infrastructure and adaptive acceleration for edge computing applications.
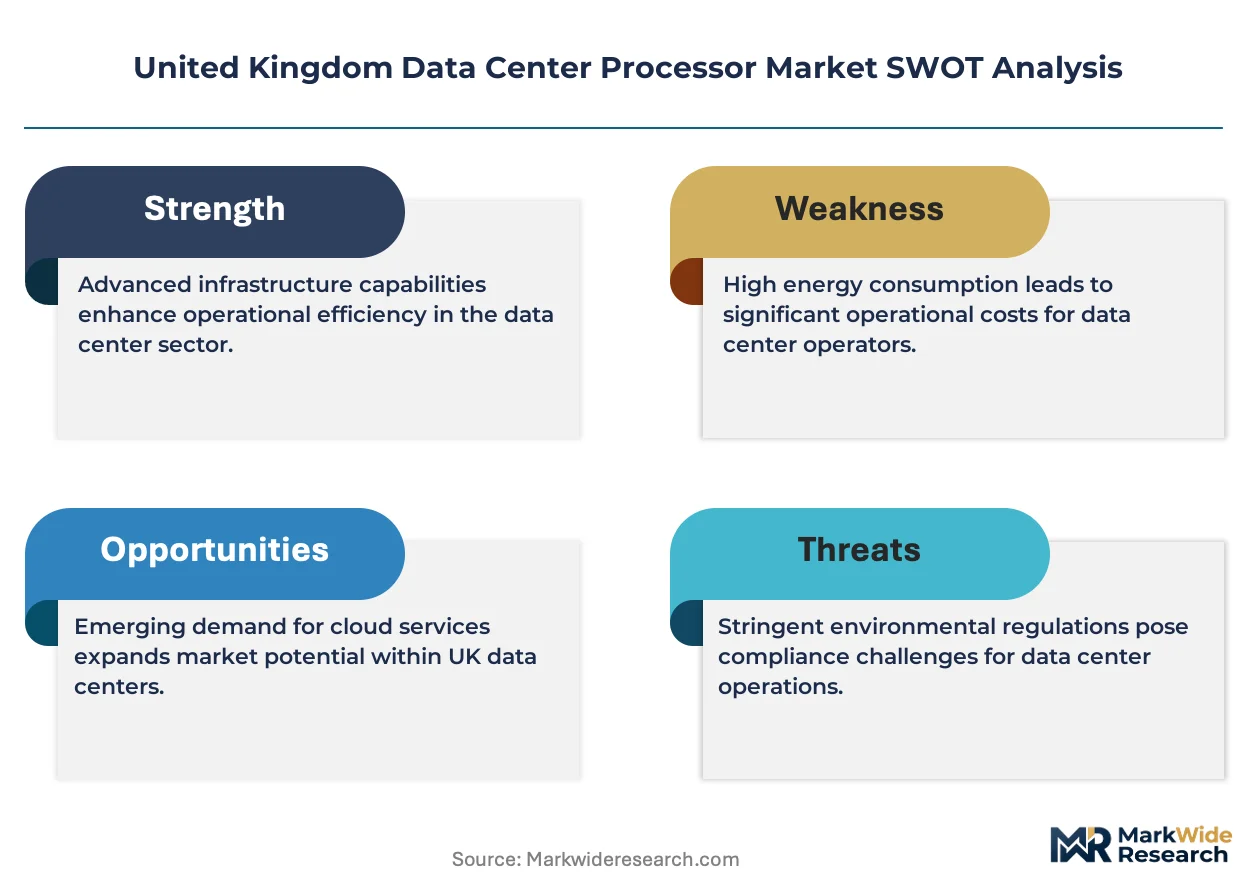
Ofcom spectrum allocations and the UK National AI Strategy shape processor procurement criteria around computational efficiency and domestic supply chain resilience. BSI standards for data center energy performance, alongside Environment Agency emissions guidelines, constrain thermal and power specifications for new installations. Stakeholders must monitor how the UK Semiconductor Advisory Panel's domestic manufacturing incentives rebalance import dependency against foundry capacity timelines.
Market Dynamics
AI inference workloads are compressing procurement cycles across British colocation facilities, forcing hyperscale operators to renegotiate silicon supply agreements ahead of traditional server refresh timelines. The UK government's net-zero mandates for data center efficiency are simultaneously tightening thermal design power ceilings and accelerating ARM-based adoption curves.
Growth Catalysts
- AI Sector Deal procurement mandates:The UK government's AI Sector Deal directs public-sector cloud spending toward domestic processing capacity, channeling sovereign compute contracts into Thames Valley facilities.
- Financial services inference demand:London-based trading firms and insurance underwriters are deploying GPU clusters for real-time risk modeling, expanding accelerator procurement beyond traditional virtualization budgets.
- Sub-5nm process maturation:Advanced lithography yields from TSMC and Samsung Foundry are reducing per-watt silicon costs for high-performance variants, enabling denser rack configurations in Greater London.
Market Restraints
- TSMC supply concentration:Foundry dependency on Taiwanese advanced-node production creates geopolitical exposure for UK operators unable to source domestic alternatives within the National AI Strategy timelines.
- BSI energy performance ceilings:British Standards Institution thermal efficiency mandates constrain legacy x86 refresh options, forcing premature write-downs of still-serviceable server fleets.
- Copper interconnect bottlenecks:High-bandwidth memory packaging shortages are extending lead times for AI training accelerators beyond 52 weeks, freezing expansion timelines at Manchester edge sites.
Strategic Opportunities
- Scotland renewable-powered clusters:Aberdeen and Edinburgh metro zones offer stranded wind assets for carbon-negative compute, attracting hyperscale pre-commitments ahead of grid interconnection.
- FPGA-NIC convergence:Adaptive acceleration for low-latency trading infrastructure combines programmable logic with smart network interface cards, opening niche procurement at London Stock Exchange proximity facilities.
- UK Semiconductor Advisory Panel incentives:Domestic manufacturing grants for compound semiconductor packaging could reshore advanced substrate production from Asian supply chains.
Industry Challenges
- Power distribution engineering scarcity:Qualified electrical contractors capable of 480V direct-to-chip rack designs are concentrated among fewer than twelve UK firms, extending commissioning timelines.
- Immersion cooling retrofit complexity:Legacy air-cooled facilities in Slough and Reading face structural floor-loading constraints when converting to dielectric fluid systems, requiring phased decommissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Data Center Processor Market |
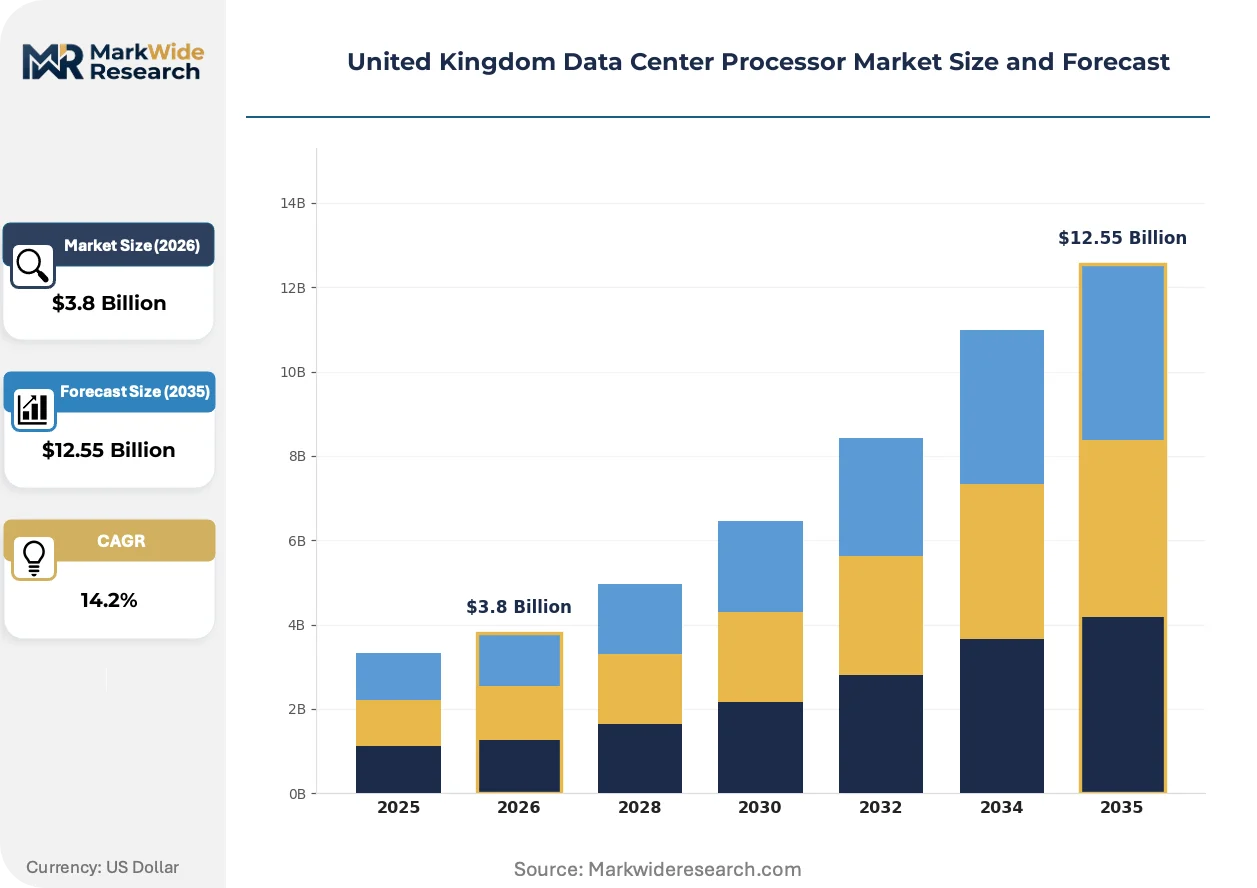
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CPU, GPU, FPGA, ASIC Technology: X86, ARM, RISC-V, Itanium End User: Tier-1 Providers, Colocation Services, Cloud Services, Enterprises Application: Virtualization, Big Data Analytics, Machine Learning, Edge Computing |
| Companies Covered | Intel Corporation, NVIDIA Corporation, Advanced Micro Devices Inc., ARM Holdings, Qualcomm Technologies, IBM Corporation, Fujitsu, Hewlett Packard Enterprise, Huawei Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Data Center Processor Market Trends and Innovations
Silicon architecture specialization is fragmenting procurement patterns across British data centers. General-purpose compute dominance is yielding to heterogeneous processing configurations optimized for specific workload signatures.
Chiplets-based server CPUs are supplanting monolithic die designs in hyperscale virtualization deployments. AWS and Microsoft Azure procurement teams are specifying multi-tile processors for their UK East and UK South regions, reducing yield-related cost premiums on large die sizes. This modular approach is compressing refresh cycles from 36 months toward 24-month intervals as socket compatibility extends across generations.
Ofcom's 26GHz and 40GHz spectrum releases are enabling millimeter-wave backhaul for edge micro-data centers, reshaping processor distribution geography. The regulator's local licensing framework permits campus-scale deployments without national carrier intermediation, accelerating Manchester and Birmingham metro edge builds. Financial services firms are exploiting these allocations for sub-10-microsecond latency to primary trading venues.
Carbon-intensity clauses are penetrating colocation contracts across the Thames Valley corridor. Enterprise buyers now specify grams-CO2-per-kWh thresholds in their RFPs, disqualifying facilities without real-time renewable matching. This behavioral shift favors Scotland and Wales locations with direct power purchase agreements, rotating demand northward from traditional London-centric procurement patterns.
United Kingdom Data Center Processor Market Segmentation
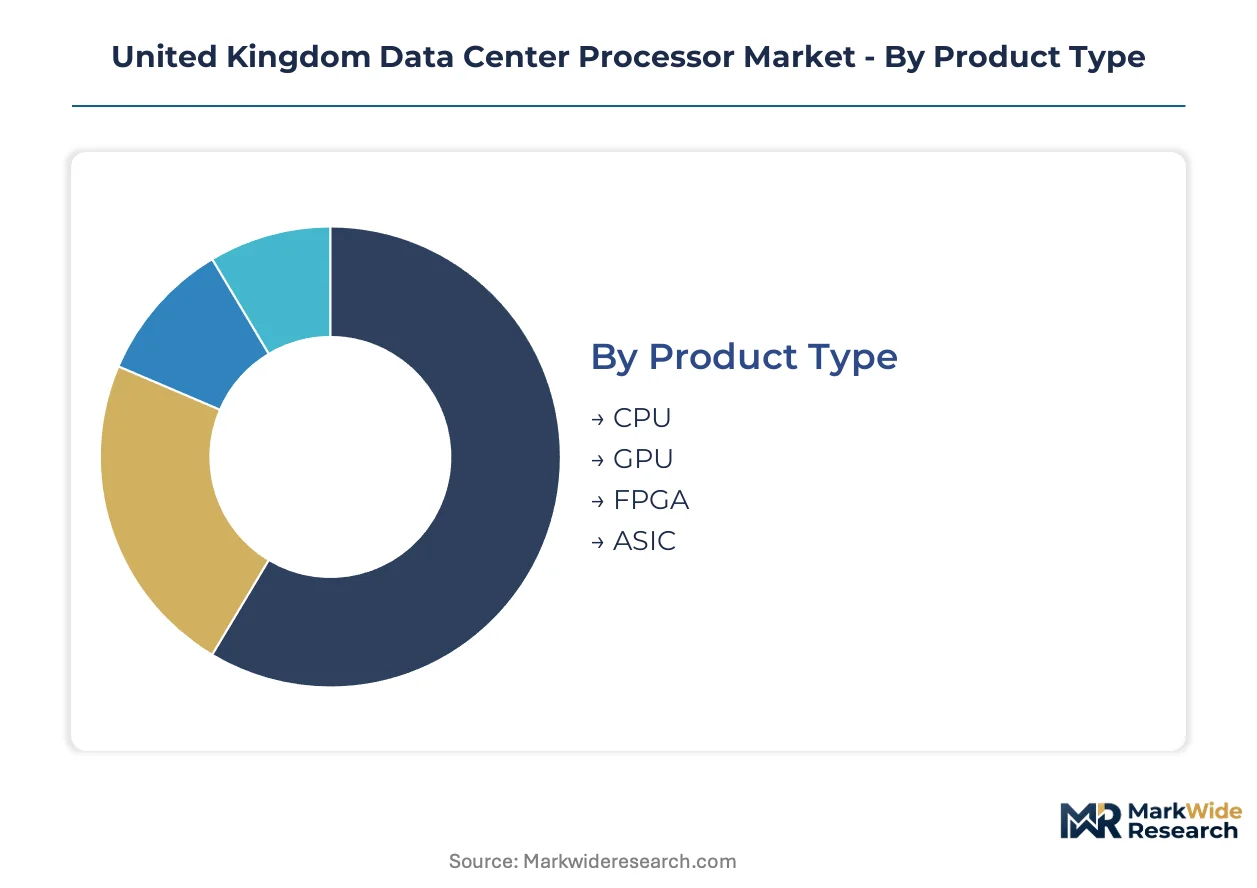
Processor segmentation in the United Kingdom reflects divergent workload requirements across Thames Valley hyperscale clusters and emerging edge zones. Procurement teams specify silicon architectures based on thermal constraints, inference latency targets, and BSI energy compliance thresholds.
Product Type:
GPU accelerators face the most intense substitution pressure from emerging ASIC inference engines, while CPU sockets defend entrenched positions in legacy virtualization estates.
- CPU:x86 and ARM-based server processors orchestrate general-purpose compute across Tier-1 provider racks. Demand concentrates in Greater London colocation facilities where VMware and Hyper-V estates require socket-compatible refresh cycles under BSI thermal efficiency mandates.
- GPU:Parallel processing architectures from NVIDIA and AMD anchor AI training and inference deployments. Financial services firms in the City of London procure H100 and MI300 clusters for real-time risk modeling, stretching procurement budgets beyond traditional server capital allocations.
- FPGA:Programmable logic devices from Xilinx and Intel enable adaptive acceleration for low-latency trading infrastructure.
- ASIC:Custom silicon designs from Google TPU and Amazon Trainium optimize inference cost-per-query at hyperscale.
CPU sockets anchor the volume base while GPU shipments gain share at the steepest rate.
Technology:
Instruction set architecture selection increasingly follows power density constraints rather than legacy software compatibility alone.
- X86:Intel and AMD server processors retain dominance in enterprise virtualization workloads. Thames Valley hyperscale operators specify Sapphire Rapids and Genoa chips for socket-compatible refreshes, though BSI thermal ceilings accelerate ARM evaluation timelines.
- ARM:Neoverse-based designs from Ampere and AWS Graviton penetrate cloud-native workloads. Manchester and Birmingham edge micro-data centers specify 128-core ARM chips for watt-per-rack-density compliance under Environment Agency emissions guidelines.
- RISC-V:Open instruction set architectures attract niche deployments in academic and defense-adjacent compute clusters.
- Itanium:Legacy EPIC architecture persists in isolated mission-critical systems requiring extended support contracts.
x86 retains the installed base majority while ARM climbs fastest among new socket commitments.
End User:
Procurement authority is shifting from enterprise IT departments toward cloud provider infrastructure teams with direct foundry relationships.
- Tier-1 Providers:AWS, Microsoft Azure, and Google Cloud specify processors for UK East and UK South regions. These operators negotiate directly with TSMC and Samsung Foundry, bypassing traditional distributor channels.
- Colocation Services:Equinix and Digital Realty facilities in Slough and Reading aggregate enterprise demand. Their customers specify socket configurations through managed service contracts rather than direct silicon procurement.
- Cloud Services:SaaS operators and platform providers procure through Tier-1 provider APIs, abstracting hardware selection.
- Enterprises:FTSE 100 manufacturers and pharmaceutical firms maintain on-premises estates in the Midlands, constrained by BSI write-down schedules for serviceable legacy fleets.
Tier-1 Providers concentrate procurement volume while Colocation Services expand rack commitments most quickly.
Application:
Workload-specific silicon optimization is fragmenting what was previously homogeneous server procurement.
- Virtualization:Hypervisor consolidation workloads prioritize core count and memory bandwidth over accelerator attachment. CPU sockets with high thread density dominate this segment across Reading enterprise data centers.
- Big Data Analytics:Spark and Hadoop clusters balance CPU and memory resources for batch processing. Financial services firms in Edinburgh deploy AMD EPYC configurations for regulatory reporting pipelines.
- Machine Learning:Training and inference pipelines drive GPU and ASIC attachment rates. London-based insurance underwriters specify NVIDIA H100 clusters for stochastic modeling, with carbon-intensity clauses in their Thames Valley colocation contracts.
- Edge Computing:Sub-10kW micro-data centers in Manchester and Birmingham metro zones specify ARM-based low-TDP processors. Ofcom's 26GHz spectrum releases enable millimeter-wave backhaul for these deployments.
Virtualization retains the largest socket count while Machine Learning accelerates procurement value fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced lithography capacity concentrates among Taiwanese and South Korean foundries, creating geographic exposure for UK operators sourcing sub-5nm silicon. Domestic processor demand flows through Thames Valley hyperscale clusters, Midlands enterprise estates, and emerging Scottish renewable-powered facilities.
Greater London and Thames Valley
Hyperscale cloud operators anchor procurement volume across Slough, Reading, and London Docklands facilities. BSI energy performance standards constrain thermal design power for new installations. Financial services firms in the City specify GPU clusters for real-time risk modeling within Equinix LD5 and Telehouse North proximity.
Midlands Engine Corridor
Automotive and pharmaceutical manufacturers maintain on-premises virtualization estates across Birmingham and Nottingham. Environment Agency emissions guidelines accelerate ARM-based server evaluations for watt-density compliance. Jaguar Land Rover and AstraZeneca operations drive enterprise CPU refresh cycles under BSI write-down schedules.
Scotland
Stranded wind assets in Aberdeen and Edinburgh metro zones enable carbon-negative compute commitments. The UK Semiconductor Advisory Panel's domestic packaging incentives attract hyperscale pre-commitments ahead of grid interconnection. Microsoft and Amazon Web Services negotiate renewable power purchase agreements for planned facilities near Dundee.
Wales
Cardiff and Newport edge deployments exploit lower land costs and grid access for AI inference micro-data centers. Ofcom's local spectrum licensing framework permits campus-scale millimeter-wave backhaul without national carrier intermediation. Welsh Government technology investment programs channel grant funding toward compound semiconductor research clusters.
Northern England
Manchester and Leeds metro zones host financial services backup and analytics workloads displaced from London core sites. Copper interconnect bottlenecks for high-bandwidth memory packaging extend accelerator lead times beyond 52 weeks at MediaCityUK facilities. Northern Powerhouse investment partnerships target data center construction skills training for qualified electrical contractor scarcity.
United Kingdom Data Center Processor Market Competitive Landscape
Concentration sits with x86 incumbents and GPU architecture specialists who anchor procurement at Tier-1 cloud providers. The vendor base stratifies across three archetypes: established semiconductor designers with foundry relationships, fabless AI accelerator specialists, and systems integrators bundling processor supply with server platforms. Competitive moves center on heterogeneous chiplet packaging partnerships and sovereign manufacturing incentives that rebalance import dependency.
Within the established semiconductor tier, Intel Corporation and NVIDIA Corporation exemplify divergent architecture strategies for UK data center procurement. Advanced Micro Devices Inc. occupies a position bridging CPU and GPU segments through multi-tile processor designs. ARM Holdings anchors the energy-efficient core licensing model that Manchester and Birmingham edge operators specify under Environment Agency thermal constraints.
| Leading Market Players |
|---|
| Intel Corporation |
| NVIDIA Corporation |
| Advanced Micro Devices Inc. |
| ARM Holdings |
| Qualcomm Technologies |
| IBM Corporation |
| Fujitsu |
| Hewlett Packard Enterprise |
| Huawei Technologies |
| Others |
Pricing and Supply Chain Analysis
Fifty-two-week lead times for high-bandwidth memory packaging concentrate pricing power with TSMC and Samsung Foundry, forcing UK operators to accept cost-plus contract structures or face allocation rationing. This supply bottleneck feeds directly into rack-level procurement decisions across Thames Valley hyperscale facilities.
Pricing Analysis
BSI energy performance standards dictate the pricing tier structure across British data center processor procurement. Three-tier pricing separates AI training accelerators from general-purpose virtualization CPUs from edge-optimized ARM sockets. Price differentiation hinges on thermal design power compliance thresholds and volume scale commitments above ten-thousand-unit annual offtake. Cost compression in legacy x86 refreshes is intensifying because BSI write-down schedules force premature fleet replacement. Enterprise IT departments in the Midlands exhibit highest price sensitivity, while Tier-1 cloud providers with direct foundry relationships demonstrate lowest sensitivity due to long-term capacity reservations.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for sub-5nm process nodes, with the United States supplying advanced packaging equipment and design IP. UK procurement draws from silicon wafers, EUV lithography systems, and high-bandwidth memory stacks. Single-source vulnerability concentrates in Taiwanese advanced-node capacity, where geopolitical exposure threatens supply continuity for Thames Valley AI training deployments. Distribution runs through direct foundry relationships for hyperscale operators and distributor-mediated channels for enterprise colocation customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed services and carbon-intensity verification layers expand faster than bare-metal hardware across UK data center processor deployments, creating service-attach multiples above traditional silicon margins.
For Market Incumbents: Shield socket-compatible refresh cycles by accelerating ARM-based product roadmaps ahead of BSI thermal ceiling enforcement. Secure capacity reservations at TSMC Arizona and Samsung Taylor to mitigate Taiwan Strait exposure. Deepen backward integration into chiplet packaging through UK Semiconductor Advisory Panel grant applications. For New Entrants and Emerging Players: Differentiate on sovereign compute compliance by targeting NHS and Ministry of Defence AI inference contracts under AI Sector Deal procurement mandates. Scotland's stranded wind zones offer the most penetrable geography for carbon-negative positioning. Lead with immersion-cooling-integrated server platforms to bypass legacy air-cooled retrofit complexity at Slough and Reading facilities. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because AI inference demand embeds processor procurement into recurring sovereign compute contracts. Target fabless AI accelerator specialists with existing TSMC N3E tape-outs and UK customer relationships. Watch Ofcom spectrum auction timing as inflection indicator for edge micro-data center buildout velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Chiplet Packaging Partnership | Multi-tile processor designs reduce yield costs for AWS and Microsoft Azure UK regions. |
| Scotland Renewable PPA | Stranded wind assets near Dundee attract hyperscale carbon-negative compute pre-commitments. |
| FPGA-NIC Convergence | Programmable logic plus smart network cards capture London Stock Exchange proximity demand. |
| Domestic Substrate Reshoring | UK Semiconductor Advisory Panel incentives target compound semiconductor packaging capacity. |
| Immersion Cooling Retrofit | Dielectric fluid systems overcome BSI thermal ceilings at legacy Slough air-cooled facilities. |
Research Methodology
The analysis maps CPU, GPU, FPGA, and ASIC processor categories, each validated through hyperscale infrastructure planners, colocation facility operators, semiconductor procurement executives, and BSI compliance officers. Primary interviews with Thames Valley data center engineering teams and secondary validation against TSMC and Samsung Foundry public disclosures, Ofcom spectrum allocation records, and UK government AI Sector Deal documentation establish demand-side triangulation. Bottom-up socket deployment estimates and top-down foundry capacity allocation models cross-validate volume projections.
Consistency checks against hyperscaler capex disclosures and Environment Agency emissions permit filings validate analytical outputs across the projection horizon. Segmentation dimensions modeled include processor architecture, instruction set technology, end-user procurement authority, and workload application type. CAGRs derive from unit shipment trajectories weighted by average selling price bands. Forecast inputs incorporate BSI thermal efficiency mandate timelines and Ofcom 26GHz spectrum release schedules.
Forecasts assume regulatory continuity in BSI energy performance standards and Environment Agency emissions guidelines; material policy shifts would require re-modeling. Supply chain disruptions at Taiwanese foundries or copper interconnect shortages could compress expansion timelines. Recalibration cycles align with material shifts in AI Sector Deal procurement thresholds and TSMC advanced-node yield announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
VR Gaming Hardware Chipsets Market
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
Automotive Gateway Chips Market
Chipset and Processors
Surgical Chips Market
Chipset and Processors
Power Architecture Market
Chipset and Processors
System on Chip (Soc) Market
Chipset and Processors
Edge AI Processor Market
Chipset and Processors
Microprocessor Market
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
Deep Learning Chip Market
Chipset and Processors
Multi-Core Processors Market
Chipset and Processors
Global Digital Light Processing Chipset Market
Chipset and Processors
India Data Center Processor Market
Chipset and Processors
Tablet Application Processor Market
Chipset and Processors
Global Microprocessor and GPU Market