
 Global Microprocessor and GPU Market | 2026-2036
Global Microprocessor and GPU Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microprocessor and GPU Market Outlook
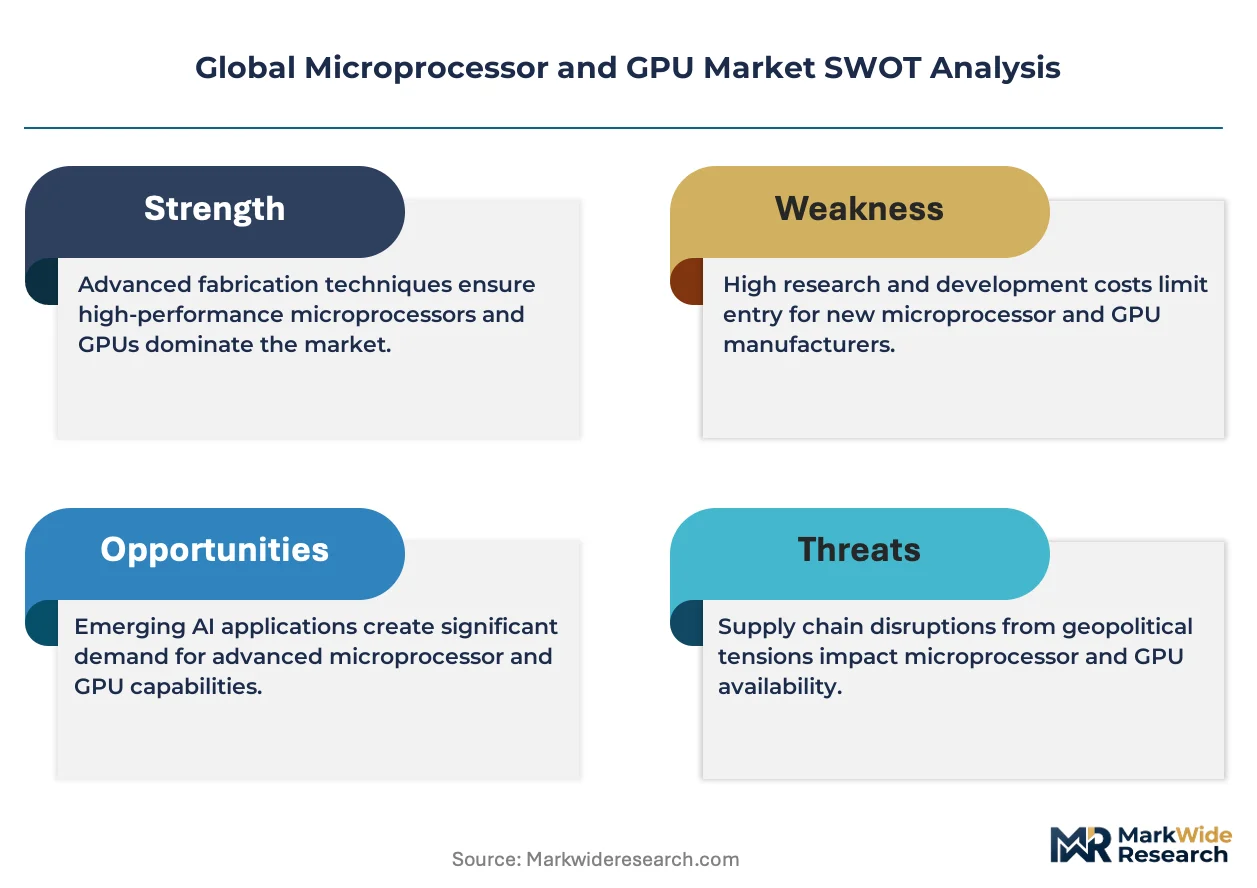
Chiplet-based modular packaging is consolidating buyer preference across server and AI accelerator procurement. NVIDIA Corporation leverages its CUDA software ecosystem to sustain pricing power in training workloads. Intel Corporation anchors its foundry ambitions with advanced packaging investments in Oregon and Arizona fabs. Advanced Micro Devices competes through chiplet architectures that reduce silicon waste across Zen and RDNA product lines.
A microprocessor is a central processing unit fabricated on a monolithic semiconductor die, typically integrating billions of transistors on silicon using photolithography with feature sizes now reaching 3nm-class nodes; its purpose is to execute sequential instruction sets for general-purpose computing across devices from smartphones to supercomputers. GPUs parallelize thousands of arithmetic operations simultaneously, originally designed for graphics rasterization but now dominant in matrix mathematics for artificial intelligence. The GPU segment captures the largest margin pool as hyperscalers deploy dedicated AI training clusters. Embedded processors serve mature automotive and industrial controllers where 28nm and larger nodes persist due to qualification cycles. Application-Specific Integrated Circuits attract custom silicon investments from Apple and Amazon Web Services seeking workload-optimized performance per watt.
The US Department of Commerce Bureau of Industry and Security restricts export of advanced GPUs to specific countries, redirecting supply toward allied data centers and domestic cloud providers. The EU AI Act imposes transparency and risk-classification requirements on high-performance AI systems, influencing processor validation protocols for European deployments. China's MIIT advances domestic substitution targets through national integrated circuit investment funds, accelerating local GPU design houses. Stakeholders must monitor how foundry capacity allocation between trailing-edge automotive chips and leading-edge AI accelerators reshapes delivery timelines and contract structures.
Market Dynamics
Chiplet-based modular architectures are redrawing competitive boundaries as foundry capacity allocation tilts toward AI accelerators and away from trailing-edge automotive controllers, compressing delivery timelines for legacy nodes.
Growth Catalysts
- Generative AI training clusters:Hyperscalers in the United States and Taiwan are expanding GPU deployments for large language model development, pulling advanced packaging capacity from automotive and industrial segments.
- EU AI Act transparency mandates:Risk-classification requirements for high-performance AI systems are accelerating processor validation protocols across European data center deployments.
- Memory-integrated packaging corridors:South Korea's HBM supply chain is consolidating advanced substrate and interposer capacity, enabling higher bandwidth connectivity for training workloads.
Market Restraints
- Photolithography equipment concentration:Extreme ultraviolet lithography systems depend on single-source supply from Dutch equipment vendors, creating bottlenecks at 3nm-class node transitions.
- Export control friction:US Bureau of Industry and Security restrictions on advanced GPU shipments to specific markets are redirecting supply toward allied data centers, fragmenting demand geography.
- Silicon wafer input volatility:Polysilicon purification and 300mm wafer substrate costs fluctuate with energy pricing in Germany and Japan, compressing foundry margin stability.
Strategic Opportunities
- India's PLI scheme for semiconductors:Production-linked incentives are attracting assembly and test capacity for mature-node microcontrollers serving industrial automation.
- Automotive edge AI inference:Sensor fusion requirements for advanced driver-assistance systems in Germany and Japan are opening demand for low-power neural processing units at 28nm nodes.
- Convergence of optical and electrical I/O:Co-packaged optics with GPU accelerators is enabling rack-scale bandwidth density for next-generation training clusters in Taiwan and the United States.
Industry Challenges
- Advanced packaging talent scarcity:Chiplet integration expertise in 2.5D and 3D stacking remains concentrated among a limited pool of substrate designers in Taiwan and South Korea.
- Multi-die certification complexity:Functional safety validation for automotive chiplets under ISO 26262 is extending qualification cycles beyond traditional monolithic processor timelines.
- IP licensing fragmentation:Cross-licensing negotiations for high-bandwidth memory interfaces and interconnect standards are delaying product ramps for second-tier accelerator vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microprocessor and GPU Market |
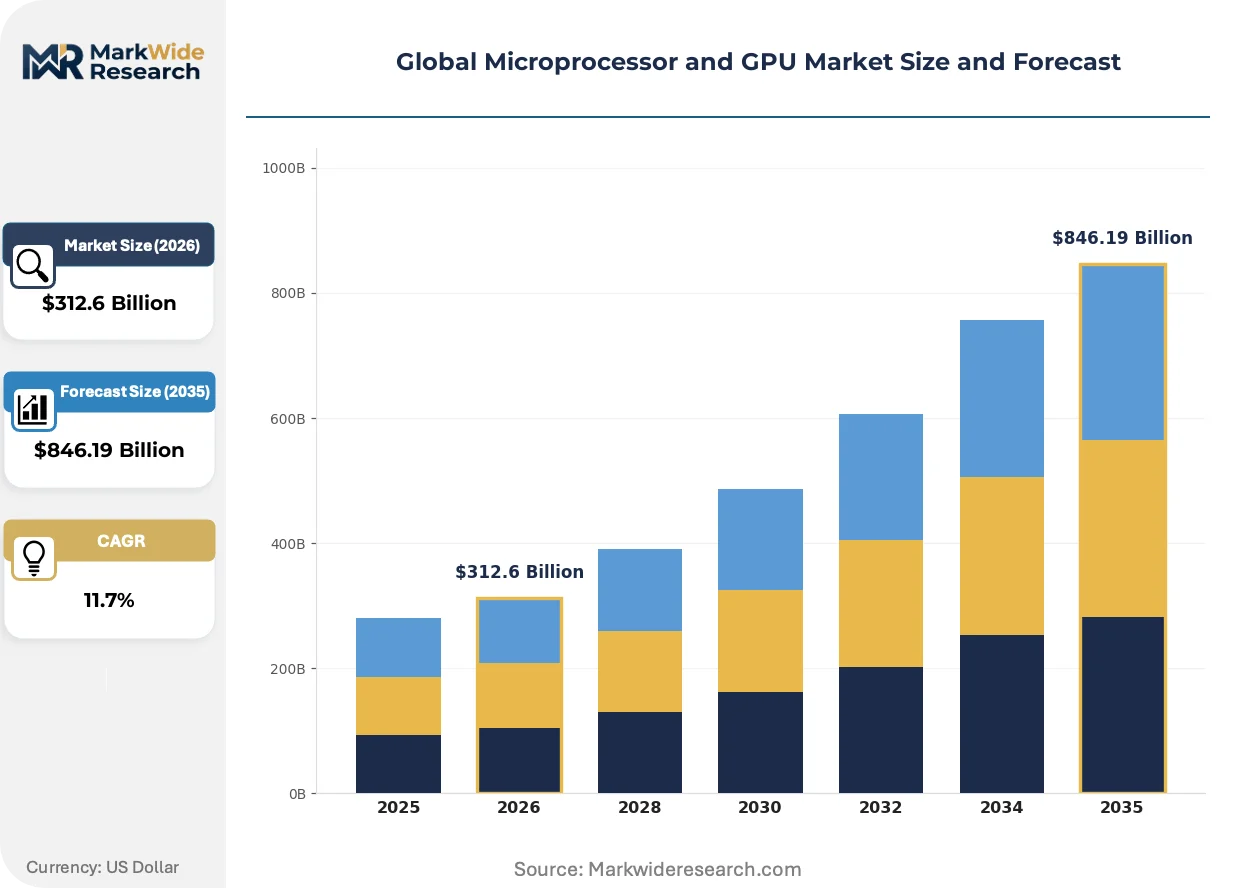
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $846.19 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microprocessors, GPUs, Embedded Processors, Application-Specific Integrated Circuits Technology: 7nm, 10nm, 14nm, 28nm End User: Consumer Electronics, Gaming, Data Centers, Automotive Application: High-Performance Computing, Artificial Intelligence, Machine Learning, Cryptography |
| Companies Covered | Intel Corporation, NVIDIA Corporation, Advanced Micro Devices, Qualcomm Incorporated, Samsung Electronics, Broadcom Inc., MediaTek Inc., Texas Instruments, ARM Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microprocessor and GPU Market Strategic Shifts
Photolithography roadmaps and advanced packaging architectures are converging to reshape how processing units are designed, manufactured, and deployed across computing tiers.
Chiplet-based disaggregation is consolidating buyer preference across server and AI accelerator procurement. Hyperscalers are standardizing on modular die configurations that mix compute, memory, and I/O tiles from multiple process nodes. This architecture is consolidating supply chain leverage toward advanced packaging houses capable of high-yield interposer assembly.
The EU AI Act imposes transparency and risk-classification requirements on high-performance AI systems deployed within European borders. Processor vendors must now document training data provenance and model architecture for systems above specified compute thresholds. Cloud providers operating Frankfurt and Amsterdam data centers are adjusting procurement specifications to preempt regulatory disqualification.
Hyperscaler procurement patterns are compressing traditional semiconductor sales cycles into direct foundry allocations and multi-year capacity reservations. Tier-one cloud operators in the United States and Taiwan are bypassing distribution channels to secure wafer starts at leading-edge nodes. This concentration is visible most acutely in NVIDIA and AMD accelerator supply agreements, where volume commitments now precede silicon availability by eighteen to twenty-four months.
Global Microprocessor and GPU Market Segmentation
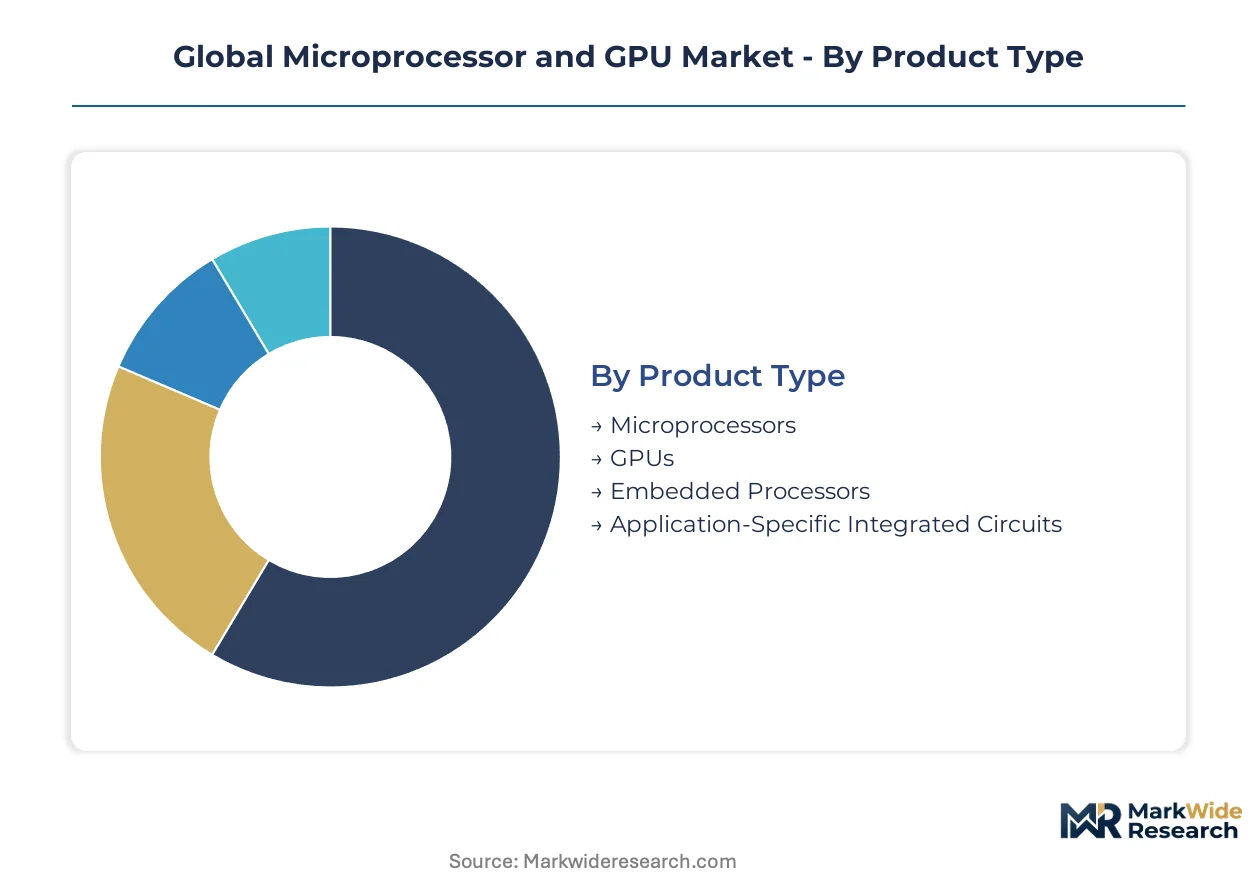
Processor segmentation reveals how architectural specialization fragments procurement patterns across computing tiers. Buyers now disaggregate monolithic silicon into workload-optimized configurations, reshaping contract structures and foundry allocation priorities.
Product Type:
Customization intensity spans from general-purpose instruction execution to silicon purpose-built for single workloads.
- GPUs:Parallel processing architectures execute thousands of simultaneous arithmetic operations through matrix-optimized cores. Hyperscalers in the United States and Taiwan are pulling advanced packaging capacity toward training clusters, tightening supply for other segments.
- Microprocessors:Sequential instruction-set engines integrate billions of transistors for general-purpose computing across device categories. Data center operators in Germany and Japan balance core-count scaling against thermal design power constraints.
- Embedded Processors:Mature-node controllers serve automotive and industrial automation where 28nm qualification cycles persist.
- Application-Specific Integrated Circuits:Custom silicon designs from cloud operators optimize performance per watt for proprietary workloads.
Leading the category by volume: Microprocessors. Expanding most quickly: GPUs.
Technology:
Node migration economics separate premium pricing tiers from cost-optimized production.
- 7nm:Extreme ultraviolet lithography enables dense transistor packing for flagship AI accelerators and server CPUs. Taiwan's foundry ecosystem concentrates capacity allocation here, with delivery timelines stretching eighteen to twenty-four months for new entrants.
- 10nm:FinFET architectures balance density gains against yield maturity for mid-range computing products. Intel Corporation's Oregon fabs anchor supply for this node class.
- 14nm:Proven manufacturing economics sustain production for mainstream client computing and networking equipment.
- 28nm:Planar transistor structures dominate automotive microcontroller supply where ISO 26262 qualification requirements extend product lifecycles.
Dominating wafer starts: 7nm. Steepest cost-per-transistor decline: 10nm.
End User:
Application maturity determines whether buyers prioritize leading-edge performance or supply security.
- Data Centers:Hyperscale facilities deploy GPU clusters for generative AI training, consuming the majority of advanced packaging output. The EU AI Act's risk-classification requirements are reshaping procurement specifications for Frankfurt and Amsterdam deployments.
- Automotive:Advanced driver-assistance systems in Germany and Japan drive neural processing unit demand at 28nm nodes, with functional safety validation extending qualification timelines.
- Consumer Electronics:Smartphone and PC OEMs negotiate volume commitments for mobile processors and integrated graphics.
- Gaming:Discrete GPU demand from enthusiast segments competes with AI training for foundry allocation.
Highest revenue concentration: Data Centers. Gaining share fastest: Automotive.
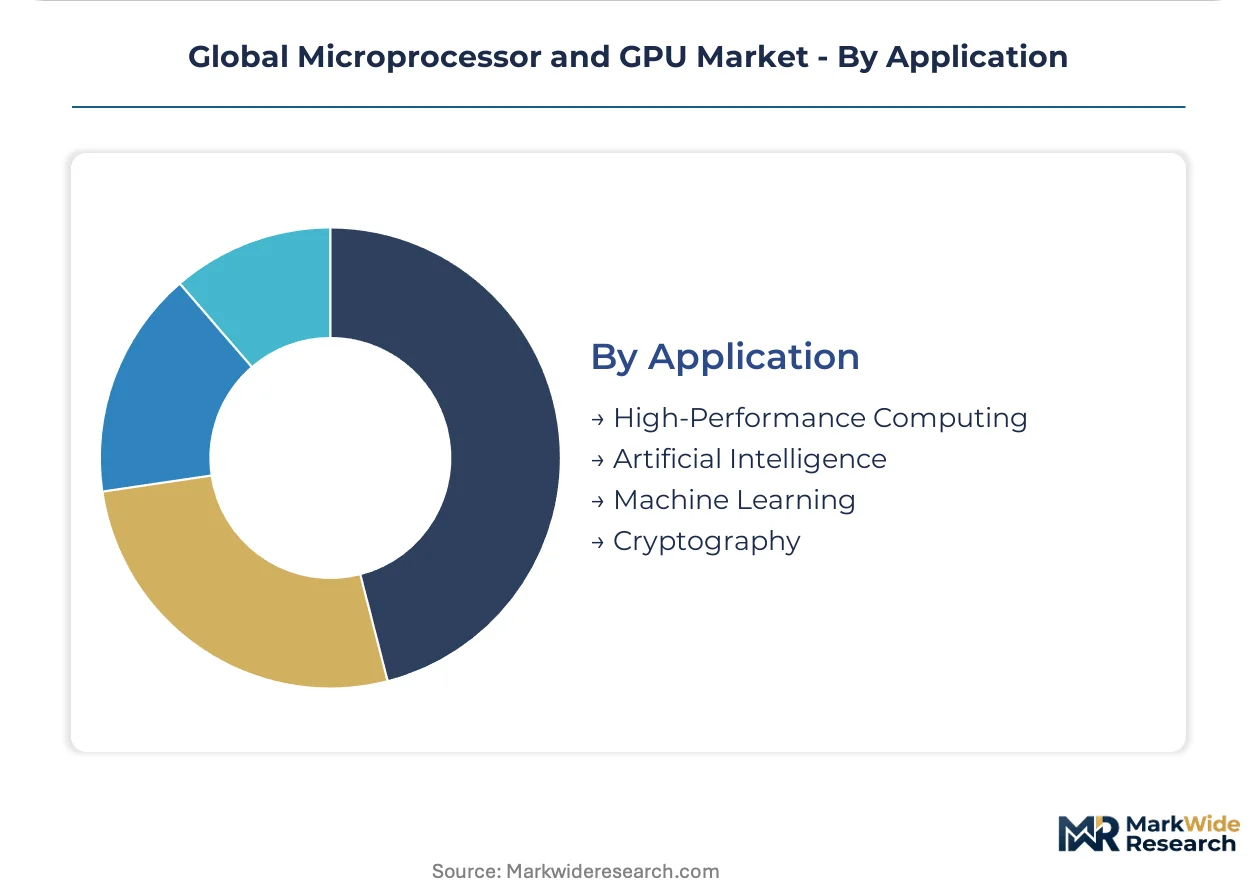
Application:
Computational intensity separates commodity inference from premium training workloads.
- Artificial Intelligence:Large language model training requires memory-bandwidth-optimized accelerators with high-bandwidth memory integration. South Korea's HBM supply chain anchors this application tier.
- Machine Learning:Inference deployment at the edge favors power-efficient architectures for real-time prediction tasks.
- High-Performance Computing:Scientific simulation workloads in national laboratories demand precision-optimized floating-point performance.
- Cryptography:Blockchain and security applications utilize specialized hashing accelerators with deterministic execution paths.
Commanding premium pricing: Artificial Intelligence. Broadening fastest: Machine Learning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hsinchu Science Park anchors wafer fabrication capacity, drawing equipment vendors and substrate specialists into Taiwan's northern corridor. Fiscal incentives in Dresden and Phoenix are redrawing foundry investment maps. Regulatory frameworks in Washington, Brussels, and Beijing are fragmenting equipment procurement and talent mobility.
United States
CHIPS Act subsidies are pulling advanced packaging investments toward Arizona and Oregon fabs. The Bureau of Industry and Security restricts EUV equipment re-export, compressing supply timelines for domestic cloud operators. Intel's Hillsboro campus anchors R&D for next-generation node development.
Taiwan
TSMC's Hsinchu and Tainan facilities concentrate 3nm-class capacity for NVIDIA and Apple accelerators. The National Science and Technology Council funds domestic photoresist and metrology tool development. Taichung's precision machinery cluster supplies wafer handling equipment to foundry expansion sites.
South Korea
Samsung Electronics and SK Hynix dominate high-bandwidth memory output for AI training clusters. The Ministry of Trade, Industry and Energy backs domestic EUV pellicle production to reduce Dutch equipment dependency. Pyeongtaek's semiconductor complex houses the world's largest memory-integrated packaging corridor.
Germany
Intel's Magdeburg fab project and TSMC's Dresden joint venture are anchoring European leading-edge capacity. The KBA and federal economic ministries coordinate automotive chip qualification timelines with foundry partners. Saxony's Silicon Saxony cluster supplies 300mm wafer substrates and specialty gases.
China
MIIT's national integrated circuit investment funds accelerate domestic GPU design houses including Moore Threads and Biren Technology. Yangtze Memory Technologies expands 3D NAND capacity in Wuhan despite equipment access constraints. Shanghai's Zhangjiang Hi-Tech Park concentrates fabless chip design talent.
Global Microprocessor and GPU Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the processor hierarchy. The vendor base clusters into three tiers: integrated device manufacturers with captive fabs, fabless design houses leveraging foundry partnerships, and intellectual property licensors monetizing instruction-set architectures. Strategic moves center on advanced packaging capacity reservation and software ecosystem lock-in through proprietary compiler and runtime frameworks.
Within the fabless accelerator tier, NVIDIA Corporation and Advanced Micro Devices exemplify divergent approaches to workload optimization. NVIDIA's CUDA software stack represents the ecosystem-anchoring archetype, while AMD's chiplet architectures exemplify modular disaggregation. Intel Corporation occupies a hybrid position spanning design and manufacturing, reflecting the integrated model under fiscal pressure to separate foundry operations.
| Leading Market Players |
|---|
| Intel Corporation |
| NVIDIA Corporation |
| Advanced Micro Devices |
| Qualcomm Incorporated |
| Samsung Electronics |
| Broadcom Inc. |
| MediaTek Inc. |
| Texas Instruments |
| ARM Limited |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed foundry operators in Taiwan and South Korea anchor wafer pricing discipline through multi-year capacity reservations, while private-equity-rolled-up packaging specialists in the United States compress margin structures to secure substrate allocation. This ownership pattern concentrates pricing power upstream with equipment-constrained foundries while fragmenting negotiation leverage among fabless design houses competing for advanced node access.
Pricing Analysis
Margin tightening in leading-edge accelerators reflects eighteen-to-twenty-four-month foundry allocation queues that force hyperscalers into prepayment structures for NVIDIA and AMD silicon. Three-tier pricing structure across flagship AI training chips, mainstream data center CPUs, and mature-node embedded controllers separates buyers by workload certification requirements and volume scale commitments. Cost-down pressure on trailing-edge automotive microcontrollers intensifies because foundry capacity redirection toward AI accelerators has extended delivery timelines for 28nm node products. Automotive Tier 1 suppliers exhibit highest price sensitivity due to fixed contract structures with OEMs, while cloud operators demonstrate lowest sensitivity given workload-optimized performance per watt requirements.
Supply Chain Analysis
Packaging engineer scarcity in Taiwan's Hsinchu corridor and South Korea's Pyeongtaek complex constrains interposer assembly expansion despite capital equipment availability. Geographic supply concentration centers on Taiwan for 3nm-class wafer fabrication, South Korea for high-bandwidth memory integration, and the United States for advanced substrate development in Arizona and Oregon. Raw material dependencies draw from 300mm silicon wafers sourced from Japan and Germany, EUV photoresists supplied by Japanese chemical specialists, and neon gas purification facilities in Ukraine and Russia. Single-source vulnerability in extreme ultraviolet lithography equipment from Dutch vendors creates structural risk for node migration timelines. Distribution runs through direct foundry allocation agreements that bypass traditional semiconductor distribution channels for tier-one cloud operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extreme ultraviolet lithography equipment scarcity at Dutch suppliers props accelerator pricing by capping foundry capacity expansion regardless of capital availability. This supply-constrained structure rewards early capacity commitment and penalizes speculative procurement.
For Market Incumbents: Extend software ecosystem lock-in through proprietary compiler frameworks that increase switching costs for hyperscaler customers facing CUDA-optimized workload migration. Anchor advanced packaging capacity in Taiwan and South Korea through equity partnerships with substrate vendors to defend against emerging chiplet integration specialists. Prioritize certification investment for EU AI Act transparency requirements to preempt regulatory disqualification in Frankfurt and Amsterdam data center deployments. For New Entrants and Emerging Players: Automotive edge AI inference buyers in Germany and Japan represent underserved demand for 28nm neural processing units with ISO 26262 functional safety validation, where qualification timelines deter incumbent refocusing from leading-edge accelerators. Target India's production-linked incentive scheme for mature-node microcontroller assembly and test capacity serving industrial automation. Pursue co-development partnerships with European automotive Tier 1 suppliers seeking supply security alternatives to Taiwan-centric procurement. For Investors and Strategic Acquirers: Distressed-cycle entries favor advanced packaging specialists with 2.5D and 3D stacking expertise in Taiwan and South Korea, where talent scarcity creates acquisition premiums during demand pullbacks. Long-term viability across the projection horizon hinges on securing intellectual property licensing positions for high-bandwidth memory interfaces before standard consolidation. Watch for EU AI Act enforcement patterns as inflection indicator for processor validation protocol investments.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Packaging Capacity Reservation | Multi-year substrate allocation agreements with TSMC and Samsung Electronics secure interposer supply for AI training clusters. |
| Software Ecosystem Lock-In | Proprietary CUDA extensions and ROCm optimizations increase hyperscaler switching costs for workload migration. |
| Regulatory Pre-Certification | EU AI Act transparency documentation investments preempt procurement disqualification in European data centers. |
| Chiplet Architecture Standardization | Universal Chiplet Interconnect Express adoption reduces IP licensing fragmentation for second-tier accelerator vendors. |
| Co-Packaged Optics Integration | Silicon photonics partnerships with Intel and Broadcom enable rack-scale bandwidth density for next-generation training infrastructure. |
Study Parameters
SEC filings from NVIDIA, AMD, and Intel, EUV equipment shipment disclosures from ASML, and hyperscaler capital expenditure reports formed the secondary backbone for demand quantification. Primary interviews with data center procurement officers, foundry account managers, automotive Tier 1 semiconductor buyers, advanced packaging substrate designers, and EU regulatory affairs specialists validated capacity allocation assumptions. Bottom-up wafer start projections and top-down AI training cluster deployment estimates were triangulated against Bureau of Industry and Security export license data.
Historical trendline analysis of foundry utilization rates, memory pricing cycles, and packaging yield improvements informed the analytical framework across the projection horizon. Segmentation dimensions modeled include processor architecture type, process node tier, end-use application intensity, geographic regulatory cluster, and workload optimization level. CAGRs were derived from regression analysis of capital expenditure trajectories and equipment lead time constraints, with EUV scanner delivery schedules and HBM supply elasticity as semiconductor-specific forecast inputs.
Revisions become necessary when export control expansion alters demand geography, EU AI Act enforcement accelerates validation protocol investments, or foundry capacity allocation shifts between automotive and AI accelerator segments materialize. Forecasts reflect assumptions about photolithography equipment availability, substrate assembly yield maturation, and sovereign subsidy program continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
United Kingdom Data Center Processor Market
Chipset and Processors
Global AI Processor Market
Chipset and Processors
Global Battery Management IC Market
Chipset and Processors
Accelerated Processing Unit (APU) Market
Chipset and Processors
France Data Center Processor Market
Chipset and Processors
Global Heterogeneous Mobile Processing and Computing Market
Chipset and Processors
Wi-Fi Chipset Market
Chipset and Processors
Edge Artificial Intelligence Chips Market
Chipset and Processors
Consumer Electronics Chip Market
Chipset and Processors
DNA Sequencing Chip Market
Chipset and Processors
Data Center Chip Market
Chipset and Processors
Automotive Battery Management System (BMS) Chip Market
Chipset and Processors
Audio Processor Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
Edge AI Processor Market
Chipset and Processors
United States Wi-Fi Chipset Market