
 Tablet and E-Reader Application Processor Market | 2026-2036
Tablet and E-Reader Application Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Tablet and E-Reader Application Processor Market Analytics
Enterprise procurement for fleet tablets is rebalancing away from consumer OEMs toward vertically integrated device manufacturers. Qualcomm Inc. leverages its Snapdragon compute platform to anchor premium enterprise contracts. MediaTek Inc. competes aggressively on mid-range silicon for education-focused OEMs. Samsung Electronics Co., Ltd. sustains captive demand through in-house Galaxy Tab production while supplying select external brands.
Tablet and e-reader application processors are system-on-chip (SoC) devices integrating CPU cores, GPU, memory controllers, and I/O interfaces on a single die, typically fabricated at 5nm to 7nm process nodes for flagship tiers. These processors manage display rendering, touch response, wireless connectivity, and power states to deliver responsive mobile computing experiences. High-performance ARM-based SoCs command the dominant margin pool in premium devices, while entry-level and ultra-low power tiers absorb volume in emerging markets and dedicated e-reader hardware. RISC-V architectures are gaining traction among cost-sensitive designers seeking ISA licensing flexibility outside ARM's royalty structure.
EU REACH substance restrictions and RoHS hazardous material limits constrain solder compositions and substrate materials in processor packaging. The US FCC and EU CE marking frameworks mandate electromagnetic compatibility and RF emission thresholds that shape antenna integration and shielding designs. China's MIIT enforces domestic cybersecurity review requirements for processors deployed in government and education procurement channels. Stakeholders must monitor evolving semiconductor export control classifications and regional content requirements that could abruptly reroute supply relationships.
Market Dynamics
Domestic OEM sourcing concentration in China is compressing margin pools for non-captive silicon vendors while rerouting design win flows toward local ARM and RISC-V licensees.
Growth Catalysts
- K-12 Education Procurement:North American school districts and Asia-Pacific ministries of education are refreshing device fleets with managed tablet deployments. Bulk purchasing agreements favor processors validated for classroom management software stacks.
- EU Ecodesign and RoHS:Stricter substance thresholds for hazardous materials in electronics packaging are accelerating qualification of lead-free solder and halogen-free substrate materials in processor assembly.
- 5nm Process Migration:Foundry capacity allocation for advanced nodes is enabling flagship-tier SoCs to integrate dedicated neural processing units for on-device AI inference in premium tablets.
Market Restraints
- Foundry Concentration Risk:Leading-edge wafer fabrication concentrates in Taiwan and South Korea, exposing supply continuity to geopolitical friction and export control volatility.
- ARM Royalty Structure:Per-unit licensing fees for Cortex CPU and Mali GPU cores erode margins in sub-$200 tablet segments where bill-of-materials pressure is most acute.
- E-Reader Volume Ceiling:Dedicated e-ink device demand plateaus in mature markets as multi-function tablets absorb casual reading use cases.
Strategic Opportunities
- RISC-V ISA Adoption:Open instruction set architectures are expanding into cost-sensitive tablet tiers as Chinese chip designers seek royalty-free alternatives to ARM cores.
- India PLI Scheme:Production-linked incentives for electronics manufacturing are attracting assembly and test investments that localize processor sourcing for domestic brands.
- Enterprise Fleet Refresh:Vertical device manufacturers are capturing procurement contracts previously held by consumer OEMs through customized Android builds and extended support lifecycles.
Industry Challenges
- RF Integration Complexity:5G modem integration into tablet SoCs demands specialized mmWave antenna engineering talent that remains scarce outside Qualcomm and MediaTek.
- Cybersecurity Certification Lag:China's MIIT security review timelines for government and education channel processors extend product qualification cycles by six to nine months.
- Legacy Android Fragmentation:Extended support obligations for chipsets across multiple OS version branches strain software engineering resources and delay end-of-life planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tablet and E-Reader Application Processor Market |
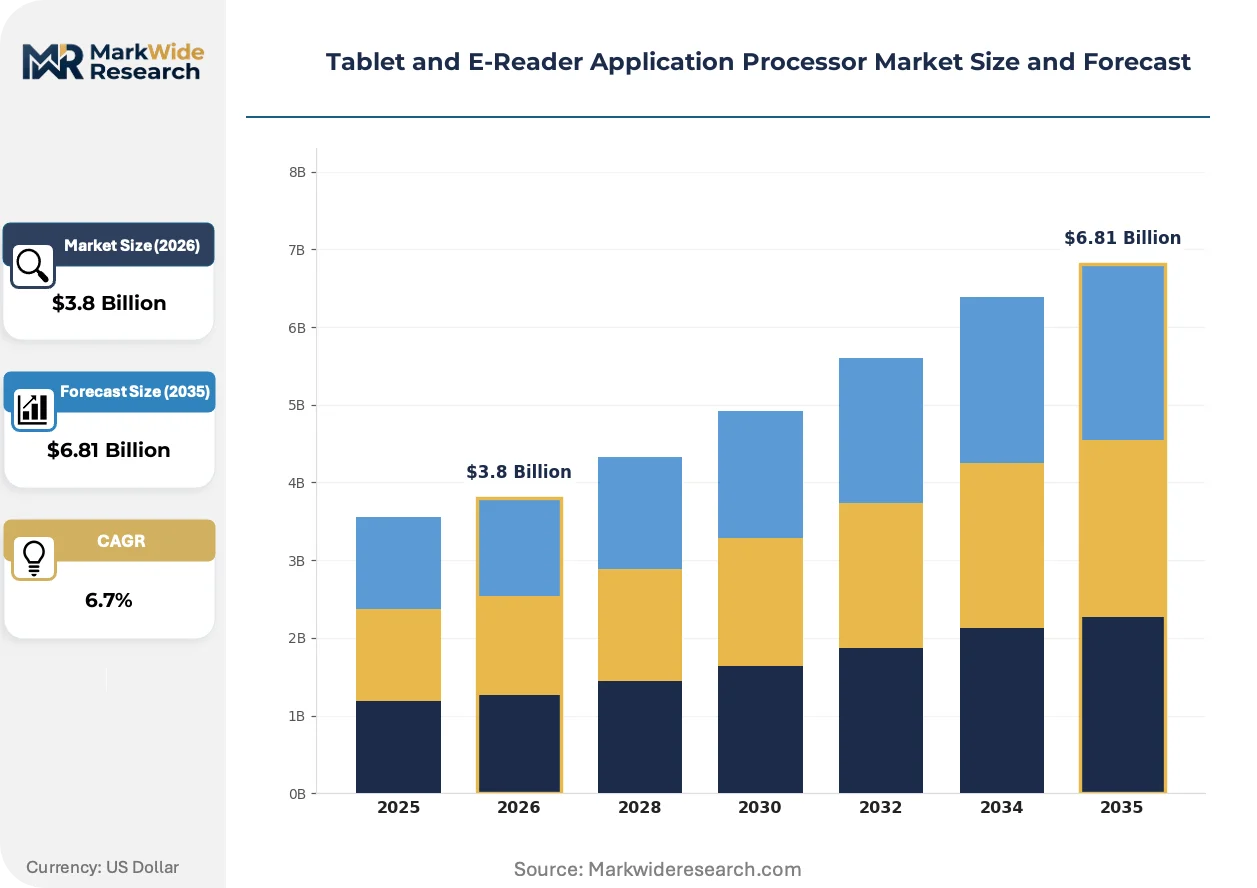
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Performance, Mid-Range, Entry-Level, Ultra-Low Power Technology: ARM, x86, AArch64, RISC-V Form Factor: System on Chip, Multi-Chip Module, Integrated Circuit, Discrete Component End User: Consumers, Schools, Enterprises, Developers |
| Companies Covered | Qualcomm Inc., MediaTek Inc., Samsung Electronics Co., Ltd., Apple Inc., Intel Corp., Rockchip Electronics Co., Ltd., Texas Instruments Inc., NXP Semiconductors NV, Renesas Electronics Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tablet and E-Reader Application Processor Market Evolving Landscape
Silicon architecture specialization and procurement channel bifurcation are fragmenting competitive positioning between premium compute platforms and education-optimized value tiers.
Chiplets are expanding into tablet SoC designs as a modular alternative to monolithic die integration. MediaTek and emerging Chinese designers are adopting chiplet architectures to mix process nodes—combining 5nm compute tiles with older I/O dies—reducing wafer costs for mid-range education tablets. This disaggregation is expanding into cost engineering strategies that compress time-to-market for feature refreshes.
EU REACH substance restrictions are tightening compliance thresholds for processor packaging materials, specifically targeting restricted phthalates and flame retardants in substrate laminates. Semiconductor assemblers are reformulating solder mask compositions and engaging alternative underfill materials to maintain CE marking eligibility. Premium-tier tablet vendors with European distribution exposure are absorbing qualification costs fastest, while budget brands face supply base consolidation.
Enterprise procurement patterns are fragmenting across direct-from-manufacturer contracts and traditional distributor channels. Fleet managers in North American logistics and healthcare verticals are bypassing retail-oriented OEMs to source ruggedized tablets with five-year support guarantees from vertically integrated device builders. This channel compression is most visible in Germany and the United States, where IT procurement teams prioritize total cost of ownership over upfront hardware pricing.
Tablet and E-Reader Application Processor Market Segmentation
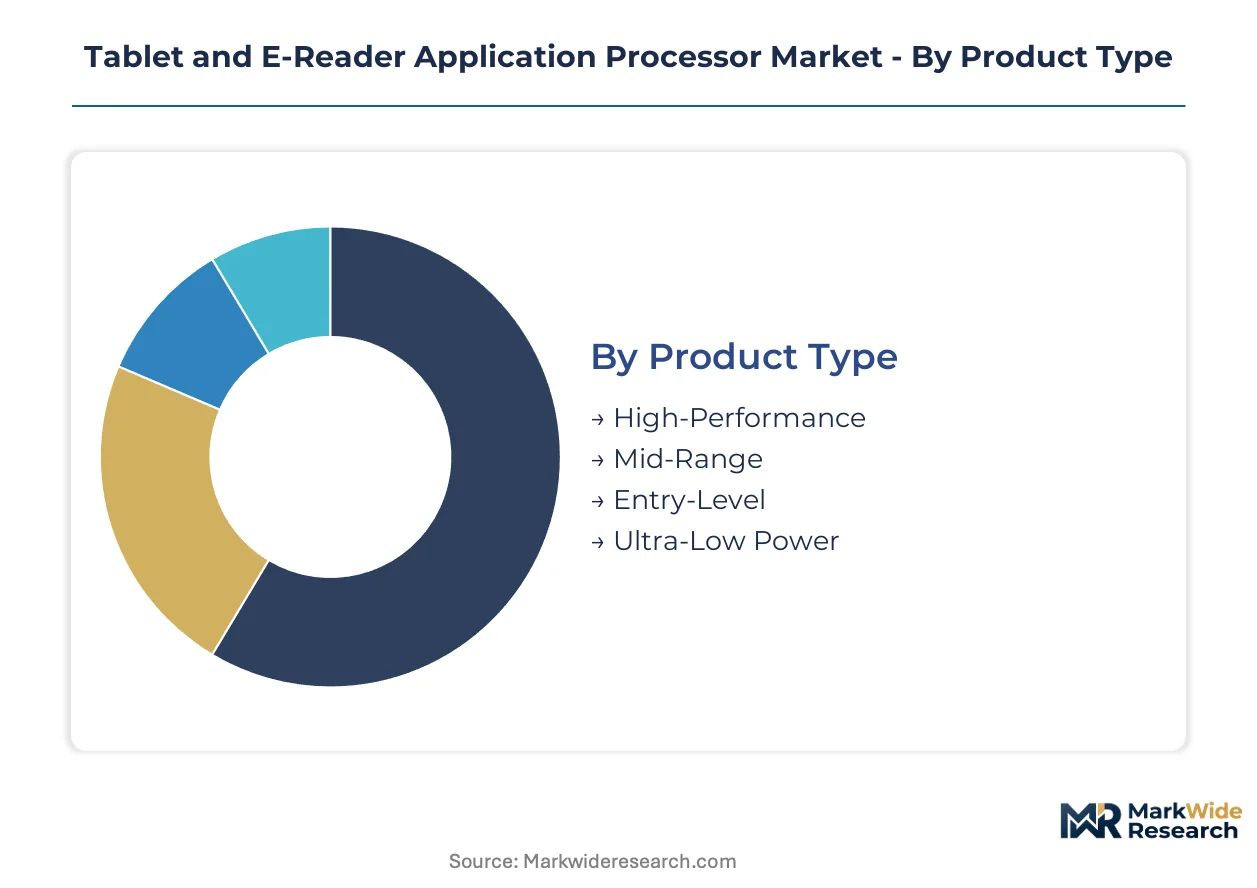
Processor segmentation in tablets and e-readers maps directly to power-performance tradeoffs and procurement channel economics. Distinct silicon tiers serve divergent use cases from premium stylus-driven workstations to single-purpose e-ink readers. Understanding these boundaries clarifies where margin pools concentrate versus where volume absorbs commodity pressure.
Product Type:
Standardization dominates at the bottom of the performance stack while customization expands at the top, with education and enterprise buyers demanding validated software stacks that lock configurations across refresh cycles.
- High-Performance:Flagship SoCs integrate 5nm to 7nm compute tiles with dedicated neural processing units for on-device AI inference. Qualcomm Snapdragon compute platforms anchor premium enterprise contracts in Germany and the United States where fleet managers prioritize five-year support lifecycles.
- Mid-Range:Silicon balancing cost and responsiveness for education-focused OEMs, typically fabricated at 6nm to 12nm nodes with validated classroom management software compatibility. MediaTek competes aggressively here as North American school districts and Asia-Pacific ministries refresh device fleets under bulk purchasing agreements.
- Entry-Level:Cost-optimized designs for emerging market volume, absorbing ARM per-unit licensing pressure through thinner margins and simplified I/O integration.
- Ultra-Low Power:E-ink dedicated processors with aggressive sleep state management and weeks-long battery endurance, facing demand ceiling pressure as multi-function tablets absorb casual reading use cases.
Most installed capacity flows through Mid-Range. Expansion is steepest in High-Performance as enterprise fleet refresh accelerates.
Technology:
Instruction set architecture choice reflects royalty structure exposure versus ecosystem maturity, with cost-sensitive designers increasingly exploring alternatives to incumbent licensing models.
- ARM:Dominant Cortex CPU and Mali GPU ecosystem with mature software stacks and broad OEM familiarity. Per-unit licensing fees erode margins in sub-$200 tablet segments where bill-of-materials pressure concentrates most acutely.
- x86:Intel and AMD processor architectures enabling full Windows compatibility for enterprise productivity tablets. Demand concentrates in corporate procurement channels requiring legacy application support.
- AArch64:64-bit ARM execution state standardizing across Android and ChromeOS tablet stacks, with Qualcomm and MediaTek implementations driving the transition from 32-bit legacy support.
- RISC-V:Open instruction set architecture gaining traction among Chinese chip designers seeking royalty-free alternatives outside ARM's structure. MIIT security review requirements extend qualification timelines for government and education channel deployment.
ARM retains the largest installed base. RISC-V is climbing the fastest as domestic OEM sourcing concentration in China compresses margin pools for licensed cores.
Form Factor:
Integration density decisions trade wafer cost against packaging complexity, with modular approaches expanding as foundry allocation pressures reshape mid-range economics.
- System on Chip:Monolithic die integration of CPU, GPU, memory controllers, and I/O interfaces delivering optimal power efficiency for flagship tablets. Qualcomm and Samsung sustain captive demand through in-house production while supplying select external brands.
- Multi-Chip Module:Disaggregated chiplets mixing process nodes—combining 5nm compute tiles with older I/O dies—to reduce wafer costs for education-optimized value tiers. MediaTek and emerging Chinese designers adopt this approach to compress time-to-market for feature refreshes.
- Integrated Circuit:Legacy package-on-package configurations persisting in cost-constrained entry-level tablets with simplified thermal and power delivery requirements.
- Discrete Component:Separated processor and modem configurations enabling vendor mixing for specialized connectivity requirements in ruggedized enterprise devices.
System on Chip carries the most installed capacity. Multi-Chip Module is gaining share fastest as chiplet architectures penetrate mid-range education tablets.
End User:
Procurement authority fragmentation separates retail consumer channels from institutional buyers with extended validation cycles and support liability requirements.
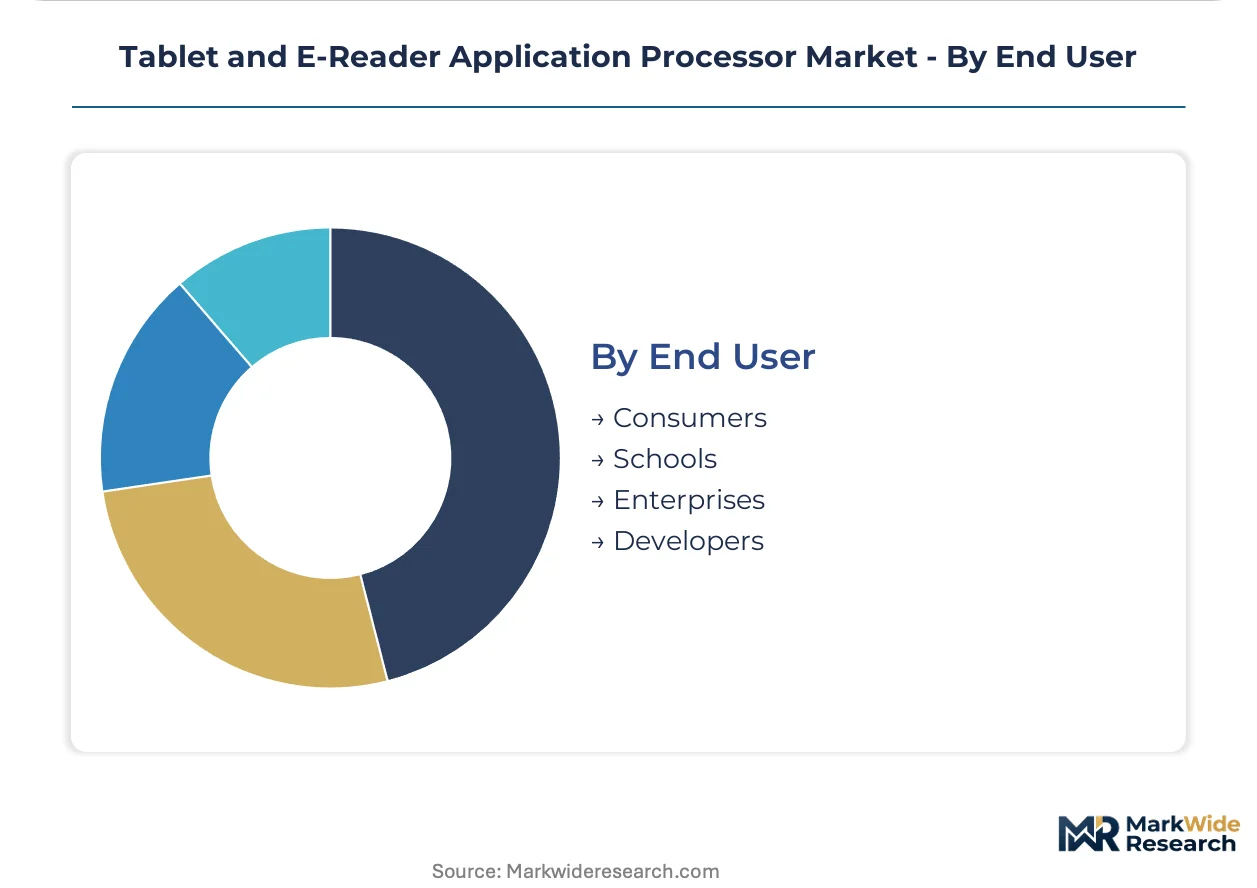
- Consumers:Individual purchasers prioritizing upfront hardware pricing over total cost of ownership, driving volume concentration in retail-oriented OEMs with annual refresh cadences.
- Schools:K-12 districts and higher education institutions requiring classroom management software validation and multi-year support guarantees. Bulk purchasing agreements favor processors pre-qualified for district-wide deployment at scale.
- Enterprises:Fleet managers in logistics and healthcare verticals bypassing retail OEMs to source ruggedized tablets with customized Android builds from vertically integrated device manufacturers. Channel compression is most visible in Germany and the United States.
- Developers:Niche demand for reference platforms and debug-capable silicon enabling application optimization across performance tiers, typically served through direct manufacturer relationships rather than distributor channels.
Consumers represent the largest installed base. Enterprises are expanding most quickly as procurement rebalances toward vertically integrated device builders with extended support obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Taiwan and South Korea anchor leading-edge foundry operations, while Chinese chip designers concentrate in Shenzhen and Shanghai. Regulatory divergence across Washington, Brussels, and Beijing is fragmenting qualification pathways for processor vendors.
United States
Enterprise fleet procurement in logistics and healthcare verticals drives demand for ruggedized tablets with extended support lifecycles. The FCC mandates electromagnetic compatibility and RF emission thresholds that shape antenna integration designs. Austin and San Diego host Qualcomm's compute platform engineering centers serving premium enterprise contracts.
China
Domestic OEMs source heavily from local ARM and RISC-V licensees, compressing margin pools for non-captive silicon vendors. MIIT enforces cybersecurity review requirements extending product qualification cycles by six to nine months for government and education channels. Shenzhen's electronics corridor concentrates chip design houses serving tablet brands with cost-optimized SoCs.
Germany
IT procurement teams in industrial and healthcare sectors prioritize total cost of ownership over upfront hardware pricing for fleet deployments. EU Ecodesign requirements and RoHS substance restrictions tighten compliance thresholds for processor packaging materials. Munich and Stuttgart anchor enterprise tablet distribution channels serving Central European markets.
South Korea
Samsung sustains captive demand through in-house Galaxy Tab production while supplying select external brands with Exynos processors. The national regulator enforces electromagnetic compatibility standards aligned with CE marking frameworks. Seoul's semiconductor corridor hosts foundry operations fabricating 5nm to 7nm compute tiles for flagship-tier SoCs.
India
Production-linked incentives for electronics manufacturing attract assembly and test investments localizing processor sourcing for domestic brands. BIS certification requirements govern safety and interoperability standards for tablet deployments. Karnataka and Tamil Nadu concentrate contract manufacturing operations serving education procurement channels.
Tablet and E-Reader Application Processor Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered performance segments. The vendor base concentrates around three strategic archetypes: vertically integrated device manufacturers with captive silicon operations, fabless chip designers leveraging foundry partnerships, and diversified electronics conglomerates spanning multiple end markets. Competitive maneuvering centers on process node migration and ISA licensing flexibility as cost pressure intensifies in sub-$200 tablet tiers.
Among fabless specialists, Qualcomm Inc., MediaTek Inc., and Rockchip Electronics Co., Ltd. exemplify divergent positioning strategies. Qualcomm occupies the premium enterprise tier through Snapdragon compute platforms. MediaTek represents aggressive mid-range competition for education-focused OEMs. Rockchip anchors the value tier serving cost-sensitive domestic Chinese brands seeking alternatives to licensed core architectures.
| Leading Market Players |
|---|
| Qualcomm Inc. |
| MediaTek Inc. |
| Samsung Electronics Co., Ltd. |
| Apple Inc. |
| Intel Corp. |
| Rockchip Electronics Co., Ltd. |
| Texas Instruments Inc. |
| NXP Semiconductors NV |
| Renesas Electronics Corp. |
| Others |
Value Network & Pricing Analysis
Silicon wafer spot prices in Taiwan and South Korea cascade through foundry tariffs into tiered processor pricing, compressing margins for education-focused OEMs while premium enterprise buyers absorb qualification premiums for five-year support guarantees.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for mid-range tablet SoCs as Samsung Foundry expands 5nm allocation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with CE-marked processors commanding 15-20 point premiums over uncertified alternatives. Pricing pressure stems from ARM per-unit royalties in sub-$200 tablet tiers where bill-of-materials constraints concentrate most acutely. Education procurement teams exhibit highest price sensitivity, while German healthcare fleet managers prioritize total cost of ownership over upfront hardware costs.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based foundry operations fabricating leading-edge 5nm to 7nm compute tiles for flagship-tier SoCs. Taiwan, South Korea, and the United States anchor wafer fabrication capacity, drawing from silicon ingots, photoresist chemicals, and EUV lithography equipment as critical inputs. Tariff exposure on semiconductor manufacturing equipment threatens supply continuity for Chinese chip designers seeking domestic alternatives. Distribution runs through vertically integrated device manufacturers in Germany and the United States, bypassing traditional retail-oriented OEM channels for enterprise fleet contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: MIIT security review timelines in China extend qualification cycles six to nine months, while India's PLI scheme accelerates assembly localization at 15-20 point cost advantages for domestic brands.
For Market Incumbents: Hedge ARM royalty exposure by accelerating RISC-V ISA investments for education-tier silicon, while securing five-year support contracts with German healthcare and US logistics fleet managers to lock recurring revenue against MediaTek's mid-range aggression. Foundry capacity reservations in South Korea provide the priority lever for flagship-tier allocation security.
For New Entrants and Emerging Players: Capture white-space in India's education procurement channel where PLI-localized assembly creates first-mover advantages for cost-optimized SoCs, and target ruggedized enterprise tablets for North American healthcare verticals seeking alternatives to Qualcomm's premium positioning. Direct manufacturer relationships bypass distributor markups and compress time-to-market.
For Investors and Strategic Acquirers: Asymmetric upside sits with Chinese RISC-V chip designers possessing MIIT pre-qualification for government and education channels, as domestic OEM sourcing concentration compresses margin pools for licensed-core vendors. Long-term viability hinges on ISA licensing flexibility and foundry partnership depth. The signal to watch is ARM's per-unit royalty rate adjustments for sub-$200 tablet tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| RISC-V ISA Adoption | Chinese chip designers gain royalty-free alternatives outside ARM's licensing structure for education-tier volume. |
| Chiplet Architecture Migration | MediaTek and emerging designers mix 5nm compute tiles with older I/O dies to reduce wafer costs for mid-range tablets. |
| Enterprise Fleet Certification | Five-year support guarantees with German and US fleet managers lock premium pricing against consumer OEM commoditization. |
| India PLI Localization | Assembly and test investments in Karnataka and Tamil Nadu compress landed costs for domestic education procurement. |
| EU Ecodesign Compliance | Lead-free solder and halogen-free substrate qualification maintains CE marking eligibility for European distribution. |
Research Methodology
Bottom-up education and enterprise procurement modeling reconciled against top-down foundry capacity tracking forms the analytical core. Primary interviews with tablet OEM procurement directors, semiconductor packaging engineers, K-12 district IT administrators, and MIIT certification consultants combined with secondary validation against SEC 10-K filings, Taiwan Semiconductor Industry Association capacity reports, and EU Ecodesign regulatory databases. Triangulation between bill-of-materials teardowns and channel shipment estimates anchors volume sizing.
Historical trendline analysis across processor architecture transitions and foundry node migrations informed projection frameworks. Segmentation dimensions span performance tier, instruction set architecture, form factor integration density, and end-user procurement channel. CAGRs derive from elasticity modeling against education fleet refresh cycles and enterprise Windows-to-Android migration patterns. Forecast inputs incorporate ARM royalty rate trajectories and RISC-V ecosystem maturity indicators.
Export control reclassification, foundry geopolitical disruption, and MIIT security review timeline extensions are the dominant revision risks. Forecasts reflect documented assumptions about process node yield curves and procurement channel stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
Consumer Electronics Chip Market
Chipset and Processors
United Arab Emirates Data Center Processor Market
Chipset and Processors
Mexico Data Center Processor Market
Chipset and Processors
Application Processor Market
Chipset and Processors
Global Wireless Chipsets Market
Chipset and Processors
Secure Microcontrollers/Processors Market
Chipset and Processors
South Korea Edge AI Processor Market
Chipset and Processors
Quantum Processing Units (QPU) Market
Chipset and Processors
Germany Data Center Processor Market
Chipset and Processors
Global AI Processor Market
Chipset and Processors
Hybrid Chip Market
Chipset and Processors
Microserver Market
Chipset and Processors
Graphics Processing Unit (GPU) Market
Chipset and Processors
Neuromorphic Chip Market
Chipset and Processors
Europe Digital Signal Processor Market