
 Advanced Audio Processor Market | 2026-2036
Advanced Audio Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Audio Processor Market Outlook
Premium audio processor architectures is decoupling from commodity codec chips in both cost structure and design complexity. Texas Instruments leverages its integrated analog-digital portfolio to sustain margins in automotive DSP sockets. Qualcomm anchors premium tier competition through its Snapdragon Sound platform and wireless audio subsystem dominance.
Advanced audio processors are mixed-signal integrated circuits that execute real-time digital signal processing at sampling rates exceeding 96 kHz with 24-bit resolution, primarily to render, enhance, and route audio streams across consumer and industrial systems. Digital Signal Processors lead product type revenue due to their computational density in beamforming and active noise cancellation pipelines. Automotive Systems within the application dimension commands the fastest structural expansion as cabin audio zones multiply from two to twelve or more channels per vehicle.
The EU F-Gas Regulation and REACH framework restrict fluorinated greenhouse gas use in semiconductor etching and substrate bonding processes, directly elevating compliance costs for European-sourced fab capacity. The FCC in the United States governs electromagnetic interference thresholds for wireless audio transmission modules, shaping product certification timelines for Bluetooth-enabled processors. Stakeholders must monitor how automotive OEMs reconcile their own software-defined audio roadmaps with silicon vendor hardware release cadences.
Market Dynamics
Automotive OEMs now specify multi-channel DSP architectures directly into infotainment head units, bypassing tiered audio module suppliers and compressing traditional component hierarchies into vertically integrated silicon sockets.
Growth Catalysts
- EU F-Gas Regulation:Semiconductor fabs across Germany and the Netherlands accelerate halogen-free substrate transitions, creating premium capacity for automotive-grade processors.
- Cabin audio zone multiplication:Domestic EV brands in China now embed twelve or more independent channels per vehicle, expanding DSP socket counts beyond legacy four-channel architectures.
- Beamforming compute density:Active noise cancellation pipelines in commercial aviation headsets drive 96 kHz sampling rate specifications into mid-tier consumer segments.
Market Restraints
- European fab compliance costs:REACH substrate bonding restrictions elevate wafer processing expenses for audio-specific mixed-signal foundry capacity.
- Fluorinated gas supply concentration:Etching chemistry for high-resolution ADC architectures concentrates among three specialty gas suppliers in Belgium and Japan.
- Wireless coexistence complexity:FCC electromagnetic interference thresholds for Bluetooth-enabled processors extend certification timelines by four to six months.
Strategic Opportunities
- Software-defined audio roadmaps:OEMs in Germany and South Korea seek programmable DSP platforms that decouple hardware release cadences from firmware update cycles.
- Spatial audio engine licensing:Headphone manufacturers in Japan pursue object-based rendering algorithms previously captive to cinema processor vendors.
- India PLI scheme:Electronics manufacturing incentives for semiconductor packaging attract audio module assembly away from coastal China clusters.
Industry Challenges
- Mixed-signal design talent scarcity:Audio-specific IC architects capable of 24-bit resolution analog-digital integration command compensation premiums exceeding general-purpose DSP engineers.
- Automotive qualification timelines:AEC-Q100 stress testing for cabin-grade processors adds eighteen months to product development before OEM socket allocation.
- Legacy codec integration friction:Head unit manufacturers in the US face firmware incompatibility when bridging new DSP architectures with existing amplifier control buses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Audio Processor Market |
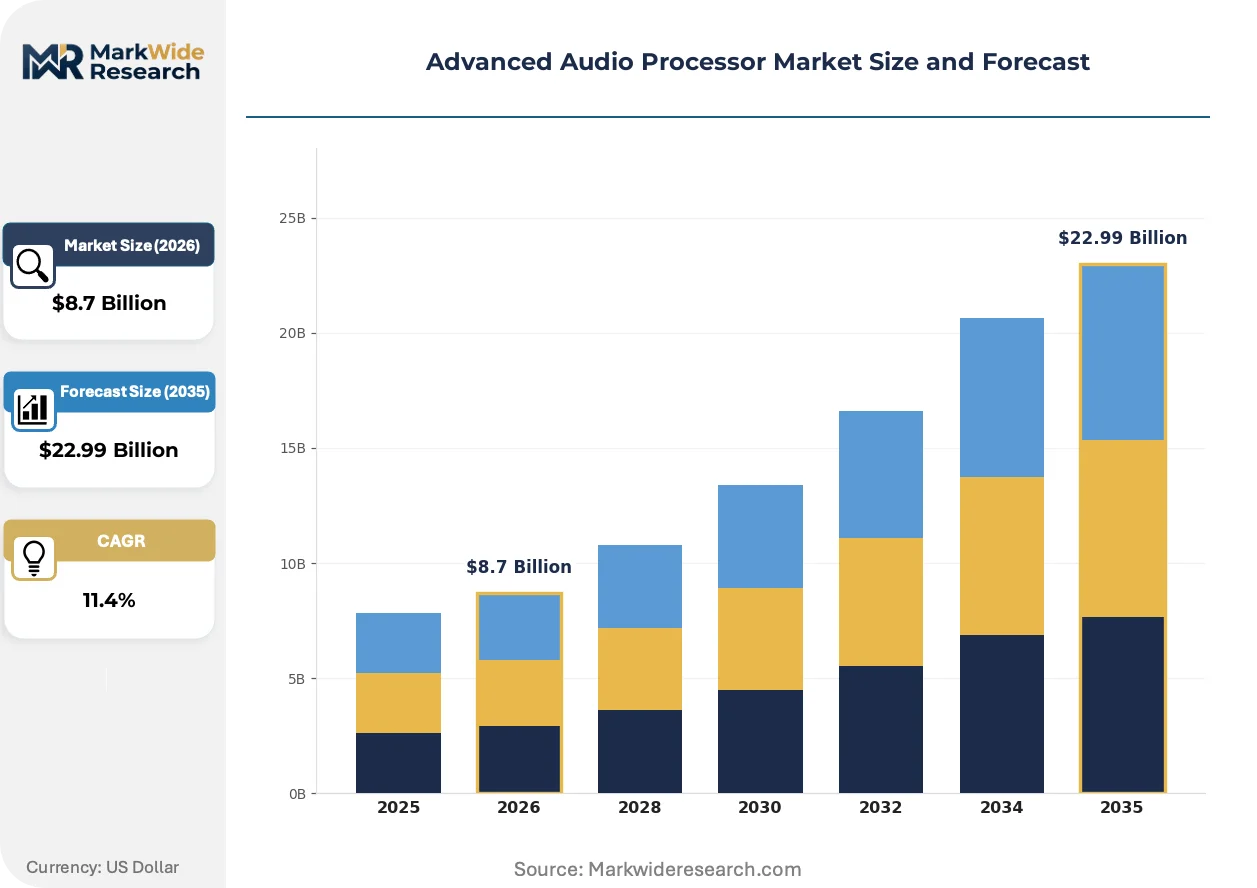
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Signal Processors, Audio Amplifiers, Mixers, Equalizers Feature: Noise Cancellation, Surround Sound, Bluetooth Connectivity, Voice Recognition Application: Consumer Electronics, Automotive Systems, Pro Audio, Home Theater End User: Musicians, Audiophiles, Content Creators, General Consumers |
| Companies Covered | Texas Instruments, Analog Devices, NXP Semiconductors, Cirrus Logic, STMicroelectronics, Infineon Technologies, ON Semiconductor, Qualcomm, Renesas Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Audio Processor Market Strategic Shifts
Silicon vendors now embed neural processing units directly into audio DSP cores, enabling real-time voice biometrics and adaptive sound field rendering without external accelerator chips.
Neural audio processing is integrating into automotive head unit SoCs, enabling cabin-specific voice isolation without dedicated microphone arrays. Tier 1 suppliers in Germany and Japan now specify NPU-augmented DSPs for 2026 model year platforms. This compression of inference workload into main audio silicon is displacing discrete voice processor modules.
REACH framework amendments in 2024 restrict per- and polyfluoroalkyl substances in semiconductor substrate bonding, directly affecting European-sourced mixed-signal fab capacity. Manufacturers now qualify halogen-free laminate alternatives from Taiwanese material suppliers. Automotive processor sockets face the steepest cost adjustments due to extended thermal cycling reliability requirements.
Chinese EV brands now procure DSP architectures through direct silicon vendor relationships, bypassing traditional tiered audio subsystem integrators. Procurement authority has shifted from acoustic module houses to vehicle platform electronics teams. This disintermediation is most visible in Shenzhen and Shanghai, where NIO, Xpeng, and BYD maintain in-house acoustic engineering centers.
Advanced Audio Processor Market Segmentation
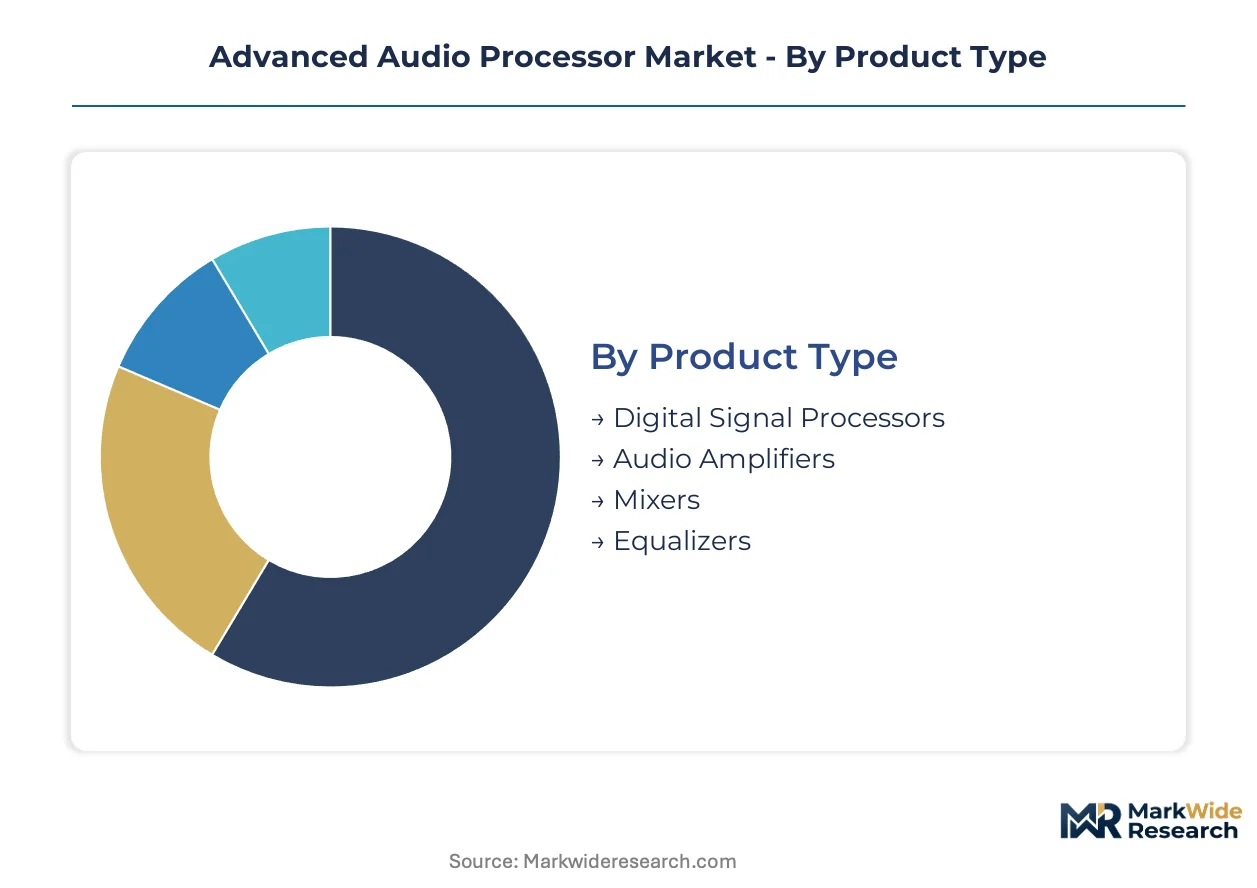
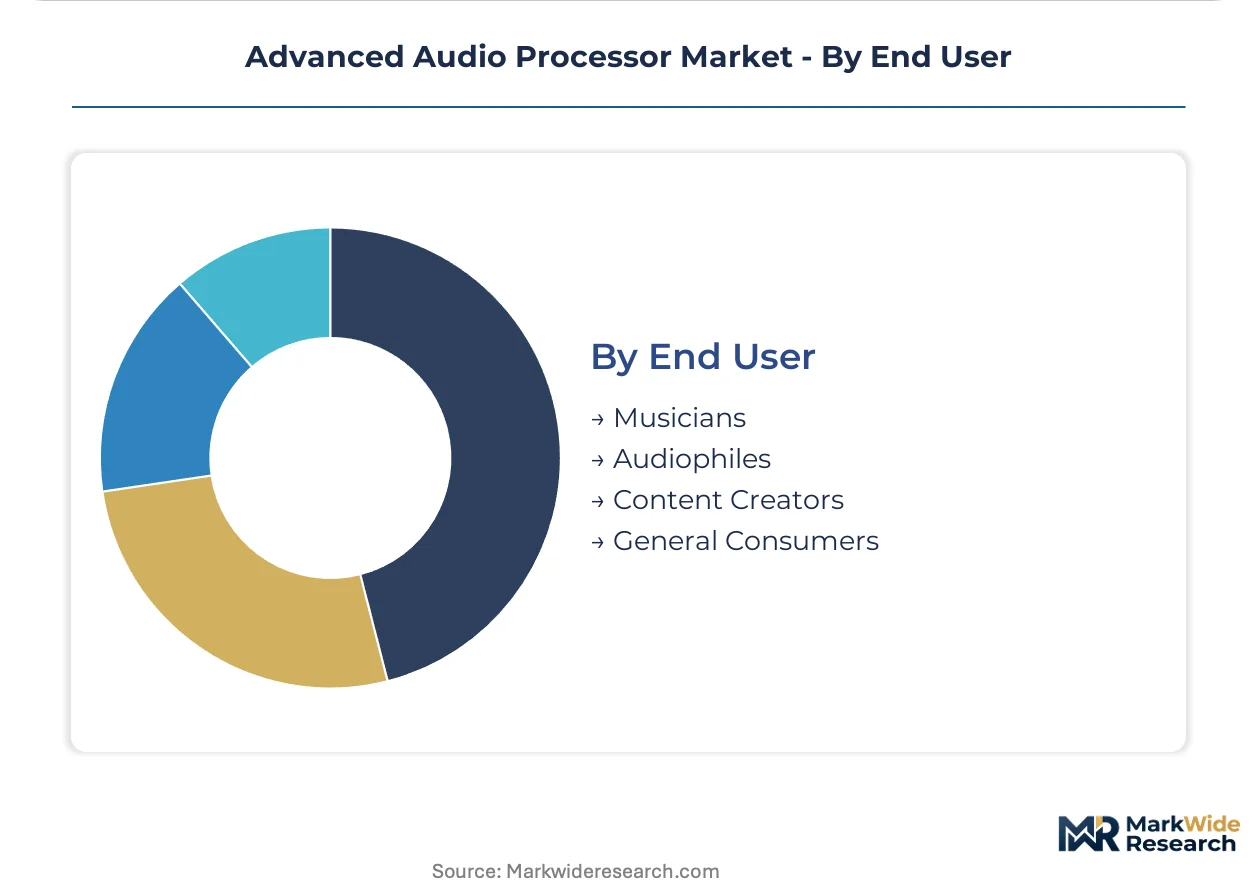
Audio processor segmentation reveals how certification burdens, performance tiers, and end-use requirements fragment procurement patterns. Each dimension carries distinct regulatory and technical gatekeepers that shape vendor selection and margin structures.
Product Type:
AEC-Q100 automotive qualification separates cabin-grade silicon from consumer-tier chips, while FCC Part 15 governs wireless-integrated variants.
- Digital Signal Processors:Mixed-signal ICs executing real-time algorithms at 96 kHz sampling with 24-bit resolution. Automotive Systems in China specify twelve-channel architectures for EV cabin zones, compressing traditional module hierarchies into single-socket designs.
- Audio Amplifiers:Power stages delivering wattage to speaker loads with thermal protection and load monitoring. Pro Audio applications in Germany and Japan demand Class-D topologies with <0.01% THD for studio monitoring chains.
- Mixers:Multi-input routing matrices with gain staging and bus architecture. Content Creators in South Korea drive USB-C connectivity requirements for portable production workflows.
- Equalizers:Frequency response shaping circuits implemented in analog or digital domains. Audiophile segments specify parametric control with 1/3-octave precision for high-resolution streaming sources.
Leading the category by volume: Digital Signal Processors. Growing fastest: Audio Amplifiers.
Feature:
Cost tier stratification separates premium licensed algorithms from commodity implementations.
- Noise Cancellation:Adaptive filtering pipelines using feedforward and feedback microphone arrays. Commercial aviation headsets specify 96 kHz processing for ANC, cascading specifications into mid-tier consumer segments.
- Surround Sound:Object-based rendering engines positioning audio elements in three-dimensional space. Home Theater installations in the United States and Japan license cinema-derived algorithms for living room playback.
- Bluetooth Connectivity:Wireless audio transmission modules governed by FCC electromagnetic interference thresholds. Certification timelines extend four to six months for products integrating these radios.
- Voice Recognition:Neural processing workloads for biometric authentication and command interpretation. Automotive OEMs in Germany and South Korea embed NPUs directly into head unit SoCs, displacing discrete voice processor modules.
Highest margin capture: Noise Cancellation. Steepest volume trajectory: Voice Recognition.
Application:
Customer type dictates socket access, with automotive platforms commanding longest qualification cycles.
- Consumer Electronics:Portable and fixed devices including smartphones, tablets, and wireless earbuds. Shenzhen manufacturing clusters concentrate procurement authority for Bluetooth-enabled processor modules.
- Automotive Systems:Cabin audio, voice isolation, and engine sound synthesis for electric vehicles. Domestic EV brands in China now embed spatial audio engines directly into infotainment head units, bypassing tiered subsystem integrators.
- Pro Audio:Recording studios, live sound reinforcement, and broadcast facilities. Germany and Japan maintain specification leadership for low-latency monitoring and mastering chains.
- Home Theater:Multi-channel reproduction systems for residential entertainment spaces. Object-based rendering adoption spreads from cinema processor vendors to consumer amplifier manufacturers.
Dominant revenue share: Consumer Electronics. Fastest structural expansion: Automotive Systems.
End User:
Geography shapes preference clusters, with East Asian markets driving feature integration density.
- Musicians:Performers and composers requiring low-latency monitoring and effects processing. India PLI scheme incentives attract audio interface assembly away from coastal China clusters.
- Audiophiles:Enthusiasts prioritizing fidelity metrics and premium component selection. Japanese and South Korean buyers specify discrete DAC architectures over integrated codec solutions.
- Content Creators:Streamers, podcasters, and video producers needing broadcast-quality capture. USB-C DSP interfaces with real-time monitoring dominate procurement in the United States and Germany.
- General Consumers:Mass-market buyers accepting bundled audio in smartphones, laptops, and vehicles. Price compression in this segment favors single-chip codec-DSP integration from Taiwanese and Chinese silicon vendors.
Largest absolute volume: General Consumers. Highest specification intensity: Content Creators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors procurement authority for Bluetooth-enabled processor modules, with domestic EV brands in Shanghai and Beijing driving twelve-channel cabin audio specifications. The EU F-Gas Regulation and REACH framework reshape European fab economics, while India PLI scheme incentives attract assembly migration from coastal China clusters.
China
NIO, Xpeng, and BYD embed spatial audio engines directly into infotainment head units, bypassing tiered subsystem integrators. MIIT governs electromagnetic compatibility standards for wireless audio transmission. Shenzhen manufacturing clusters concentrate procurement authority for DSP modules serving both automotive and consumer electronics sockets.
United States
FCC Part 15 electromagnetic interference thresholds extend certification timelines four to six months for Bluetooth-enabled processors. The IRA semiconductor manufacturing incentives attract packaging investment away from traditional Asian hubs. Austin and Phoenix emerging as design centers for automotive-grade mixed-signal architectures.
Germany
ECHA REACH restrictions on per- and polyfluoroalkyl substances elevate wafer processing expenses for European-sourced mixed-signal capacity. KBA automotive qualification requirements add eighteen months to AEC-Q100 stress testing cycles. Stuttgart and Munich host specification leadership for low-latency pro audio monitoring chains.
India
Electronics manufacturing PLI scheme incentives attract audio module assembly away from coastal China clusters. BIS certification requirements govern import compliance for semiconductor packaging operations. Karnataka and Tamil Nadu emerging as preferred locations for DSP interface manufacturing serving musician and content creator segments.
Japan
METI industrial policy supports NPU-augmented DSP specifications for 2026 model year automotive platforms. JIS standards govern precision requirements for audiophile-grade discrete DAC architectures. Tokyo and Osaka maintain leadership in object-based rendering algorithm licensing for headphone manufacturers.
Advanced Audio Processor Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification grade and sampling rate resolution. The vendor base concentrates among integrated analog-digital portfolios and wireless audio subsystem specialists. Three archetypes dominate: automotive-qualified mixed-signal houses, consumer-tier codec-DSP integrators, and neural-augmented platform vendors. Competitive moves center on strategic partnerships with tier-1 automotive module suppliers and technology licensing of spatial audio rendering algorithms.
Within the integrated portfolio tier, Texas Instruments and Analog Devices occupy positions exemplifying sustained margin capture in automotive DSP sockets. Qualcomm anchors premium-tier competition through wireless audio subsystem dominance. STMicroelectronics and Infineon Technologies represent European-based fabricators navigating REACH compliance costs in mixed-signal foundry capacity. NXP Semiconductors and Renesas Electronics sit within the automotive-qualified archetype addressing AEC-Q100 stress testing requirements for cabin-grade processors.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| NXP Semiconductors |
| Cirrus Logic |
| STMicroelectronics |
| Infineon Technologies |
| ON Semiconductor |
| Qualcomm |
| Renesas Electronics |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation and REACH substrate bonding restrictions gate qualified supply for automotive-grade mixed-signal processors, compressing premium-tier pricing access to fabs with halogen-free laminate certifications. This environmental compliance tiering separates AEC-Q100 qualified silicon from consumer-grade alternatives, embedding sustainability costs directly into margin structures for cabin audio DSP sockets.
Pricing Analysis
AEC-Q100 certification grade anchors value-based pricing for automotive DSP sockets, with tiered pricing separating twelve-channel cabin architectures from four-channel legacy designs. Price differentiation rests on sampling rate resolution and neural processing unit integration, with German and South Korean OEMs showing lowest price sensitivity for programmable platforms. Cost compression in consumer-tier codec-DSP integration intensifies as Taiwanese and Chinese silicon vendors consolidate single-chip solutions. General Consumers exhibit highest price sensitivity, while Automotive Systems buyers prioritize firmware update decoupling over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle procurement for Chinese EV brands embedding spatial audio engines directly into infotainment head units, bypassing traditional tiered subsystem integrators. Fabrication concentrates in Taiwan, South Korea, and Germany, with mixed-signal foundry capacity drawing from halogen-free substrate suppliers and fluorinated etching chemistry concentrated in Belgium and Japan. Single-source vulnerability in specialty gas supply for high-resolution ADC architectures elevates procurement risk for European-sourced wafer processing. Distribution runs through Shenzhen manufacturing clusters for Bluetooth-enabled modules serving both automotive and consumer electronics sockets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neural processing unit integration into automotive head unit SoCs is displacing discrete voice processor modules, marking a technology-transition phase where inference workload compression reshapes competitive positioning.
For Market Incumbents: Anticipate margin compression from Chinese EV brands procuring DSP architectures through direct silicon vendor relationships, bypassing traditional acoustic module houses. Defensive consolidation through backward integration into halogen-free substrate qualification programs in Taiwan secures premium fab capacity. Certification investment in AEC-Q100 automotive qualification timelines extends competitive moats against consumer-tier codec-DSP integrators. For New Entrants and Emerging Players: India PLI scheme electronics manufacturing incentives open a window for audio module assembly serving musician and content creator segments, with Karnataka and Tamil Nadu emerging as preferred packaging locations. Target USB-C DSP interfaces with real-time monitoring for South Korean and German content creator procurement. Go-to-market angle emphasizes India-based assembly cost structures against coastal China clusters for portable production workflows. For Investors and Strategic Acquirers: Tier 1 automotive suppliers in Germany and Japan specifying NPU-augmented DSPs for 2026 model year platforms is the leading indicator that neural-augmented platform vendors will command acquisition premiums. Long-term viability frames around software-defined audio roadmap alignment with OEM firmware update cycles. Acquisition target archetype: automotive-qualified mixed-signal houses with programmable DSP platforms. Signal to watch: OEM procurement authority shifts from acoustic module houses to vehicle platform electronics teams.| Strategic Initiative | Industry Significance |
|---|---|
| Neural Processing Unit Integration | STMicroelectronics and Infineon embed inference workloads directly into automotive head unit SoCs, displacing discrete voice modules. |
| Halogen-Free Substrate Qualification | Taiwanese material suppliers capture laminate alternatives as REACH restrictions elevate European fab processing expenses. |
| Direct OEM Silicon Procurement | NIO, Xpeng, and BYD compress traditional module hierarchies through in-house acoustic engineering centers in Shenzhen and Shanghai. |
| Spatial Audio Engine Licensing | Japanese headphone manufacturers pursue object-based rendering algorithms previously captive to cinema processor vendors. |
| India PLI Scheme Assembly Migration | Karnataka and Tamil Nadu attract DSP interface manufacturing for musician and content creator segments away from coastal China. |
Study Parameters
Multi-period observation of AEC-Q100 qualification timelines, REACH substrate bonding transitions, and neural processing unit integration roadmaps anchored the trend analysis, supplemented by interviews with automotive platform electronics teams, Tier 1 supplier procurement leads, semiconductor fab process engineers, and acoustic subsystem integrators. Secondary validation drew from MIIT electromagnetic compatibility filings, FCC Part 15 certification databases, ECHA REACH amendment documentation, and SEC semiconductor sector disclosures. Bottom-up socket counting across Chinese EV brand platforms triangulated with top-down foundry capacity assessments.
Input-output matrices modeled unit shipments and average selling prices across product type, feature integration, application, and end user dimensions throughout the projection horizon. Segmentation dimensions included certification grade, sampling rate resolution, channel count architecture, and neural processing capability. CAGRs derived from regression analysis of historical penetration rates against OEM platform rollout schedules, with beamforming compute density and cabin audio zone multiplication serving as industry-specific forecast inputs.
The model assumes a particular technology adoption path for neural-augmented DSP integration; alternative pathways for discrete voice processor retention would alter the outlook. Forecasts reflect base-case assumptions regarding REACH compliance cost pass-through and Chinese EV brand procurement centralization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Surgical Chips Market
Chipset and Processors
Combo Chip Market
Chipset and Processors
Europe MPU Market
Chipset and Processors
5G Chipset Market
Chipset and Processors
Application Processor Market
Chipset and Processors
Automotive Smart Chip Market
Chipset and Processors
France Data Center Processor Market
Chipset and Processors
Thailand Data Center Processor Market
Chipset and Processors
Electric Vehicle Silicon Chip Market
Chipset and Processors
Global Multimedia Chipsets Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Mexico Data Center Processor Market
Chipset and Processors
Airbag Chip Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
Microprocessor Market
Chipset and Processors
Brazil Data Center Processor Market