
 LED High Bay Drivers Market | 2026-2036
LED High Bay Drivers Market Size, Share, and Industry Trends Forecast 2026-2036
LED High Bay Drivers Market Analytics
Modular driver-luminaire bundling is broadening procurement options for facility managers seeking upgrade flexibility without full fixture replacement. Signify leverages its vertical integration into LED packages and control systems to capture bundled project contracts. MEAN WELL Enterprises anchors the aftermarket with standardized form factors that compete on interchangeability across Asian manufacturing sites.
LED high bay drivers are power conversion devices that regulate electrical input to high-output LED arrays in ceiling-mounted industrial luminaires, typically operating at 100-480V AC input with power factors above 0.9 and efficiency ratings exceeding 90%. Constant current variants dominate volume shipments due to their compatibility with high-lumen COB and SMD modules, while programmable segments attract premium positioning by enabling tunable output and integration with building management protocols. Dimmable drivers command higher margins in exhibition halls and commercial spaces where daylight harvesting and occupancy-based control justify the added cost.
EPA ENERGY STAR certification and DOE lighting standards shape product eligibility for utility rebate programs in the United States, while EU RoHS and REACH restrictions constrain material choices for PCB assemblies and housing compounds. China's GB standards and NEEA efficiency labeling create parallel compliance tracks for export-bound versus domestic-market production. Stakeholders must monitor divergence between regional efficiency tiers as driver platforms face pressure to serve multiple certification regimes from single manufacturing lines.
Market Dynamics
Retrofit urgency among warehouse operators is compressing replacement cycles, while the EU Ecodesign Directive's tightening efficiency floors force simultaneous redesign of driver platforms and luminaire architectures.
Growth Catalysts
- EPA ENERGY STAR certification:Utility rebate eligibility in the United States pulls facility managers toward certified driver-luminaire bundles, accelerating warehouse retrofit timelines.
- China's manufacturing belt:Concentrated demand around Shenzhen and Dongguan sustains volume production of standardized 100-480V AC drivers for export markets.
- Constant current topology:Compatibility with high-lumen COB and SMD modules positions this variant as the default specification for industrial ceiling installations.
Market Restraints
- Copper and rare-earth magnet costs:Input price volatility squeezes margin on magnetics-heavy driver designs, particularly affecting high-power constant current variants above 200W.
- Driver foundry concentration:Taiwan and mainland China dominate power semiconductor packaging, creating geographic chokepoints for critical MOSFET and diode supply.
- Legacy magnetic ballast substitution:Fluorescent high bay retrofits proceed slower than LED-native installations where existing wiring requires complete circuit redesign.
Strategic Opportunities
- India's industrial corridor expansion:Underpenetrated warehousing and logistics infrastructure outside Delhi-Mumbai creates first-mover positioning for programmable driver suppliers.
- Daylight harvesting integration:Dimmable driver demand in exhibition halls and commercial spaces opens premium positioning above standard industrial specifications.
- Building management protocol convergence:DALI-2 and wireless mesh integration enable driver suppliers to capture recurring software-layer revenue.
Industry Challenges
- Power electronics engineering talent:Scarcity of designers fluent in both magnetics optimization and firmware development for tunable output drivers.
- Multi-certification platform engineering:Single manufacturing lines must simultaneously satisfy EPA ENERGY STAR, EU RoHS, and China's GB standards without SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED High Bay Drivers Market |
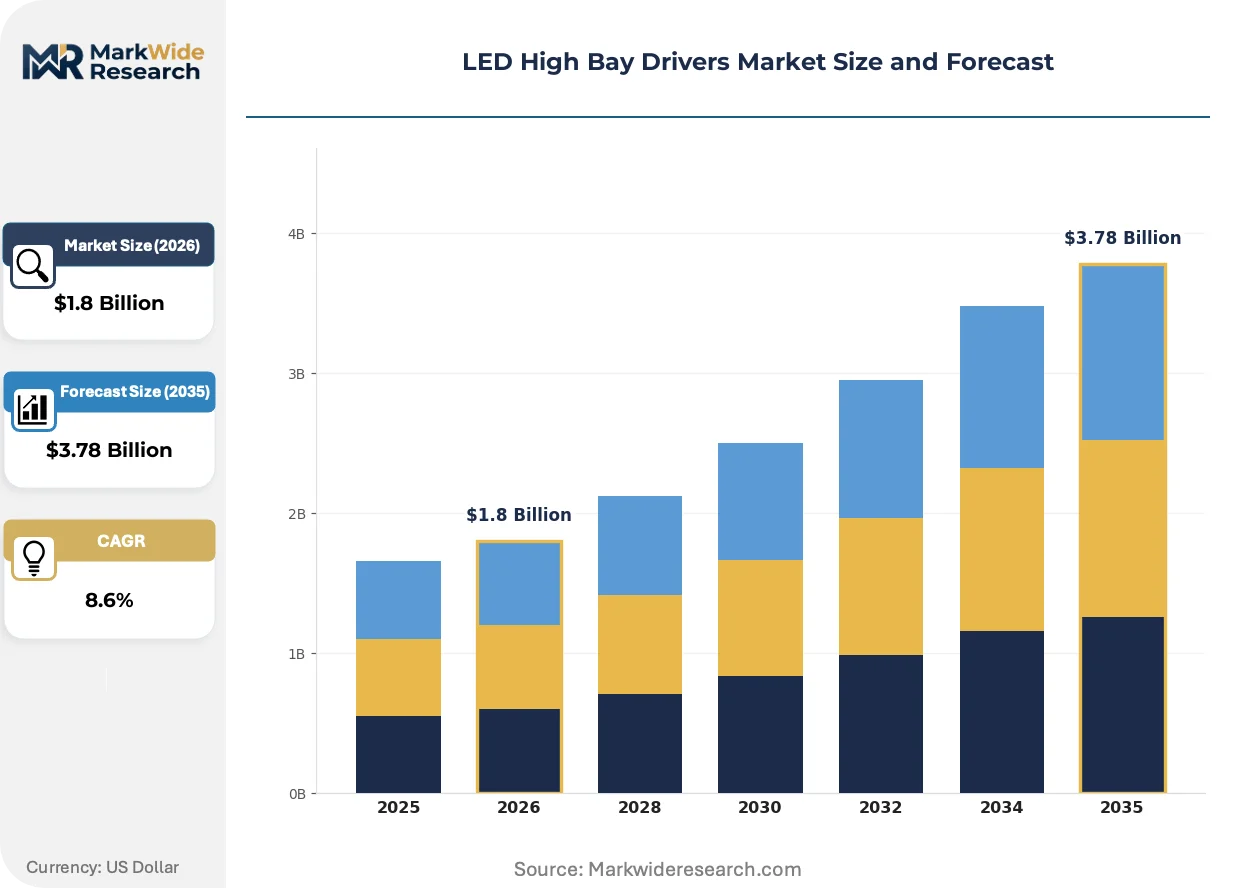
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Constant Current, Constant Voltage, Dimmable, Programmable Application: Industrial Lighting, Commercial Spaces, Warehouses, Exhibition Halls Technology: Low Voltage, High Voltage, Smart Technology, Wireless Control End User: Manufacturers, Retailers, Contractors, Facility Managers |
| Companies Covered | Signify, ams OSRAM, Acuity Brands Lighting, Hubbell Incorporated, Eaton, Lutron Electronics, MEAN WELL Enterprises, Texas Instruments, Tridonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED High Bay Drivers Market Evolving Landscape
Silicon carbide power semiconductors and programmable output architectures are rewriting performance benchmarks, while procurement patterns shift toward lifecycle cost evaluation over upfront fixture expenditure.
Silicon carbide MOSFETs replace silicon IGBTs in high-power driver stages, cutting switching losses by half in 480V industrial applications. European automotive suppliers now specifying SiC for plant lighting retrofits are pulling adoption timelines forward. This substrate transition is rewriting thermal management requirements and enabling higher wattage density in compact form factors previously reserved for lower-output designs.
The EU Ecodesign Directive's 2025 efficiency tier revision mandates minimum 94% driver efficiency for industrial luminaires above 100W. Manufacturers serving European distribution channels must redesign magnetics and topology to meet thresholds that exceed current ENERGY STAR specifications. German industrial buyers are already filtering procurement shortlists against draft tier levels, compressing design cycles for export-bound platforms.
Facility managers now evaluate drivers on ten-year energy cost models rather than fixture-first capex. This analytical shift elevates efficiency and dimming capability in bid scoring, disadvantaging interchangeability-focused suppliers. The behavior change is most visible in United States warehouse networks where REITs and third-party logistics operators centralize lighting procurement decisions.
LED High Bay Drivers Market Segmentation
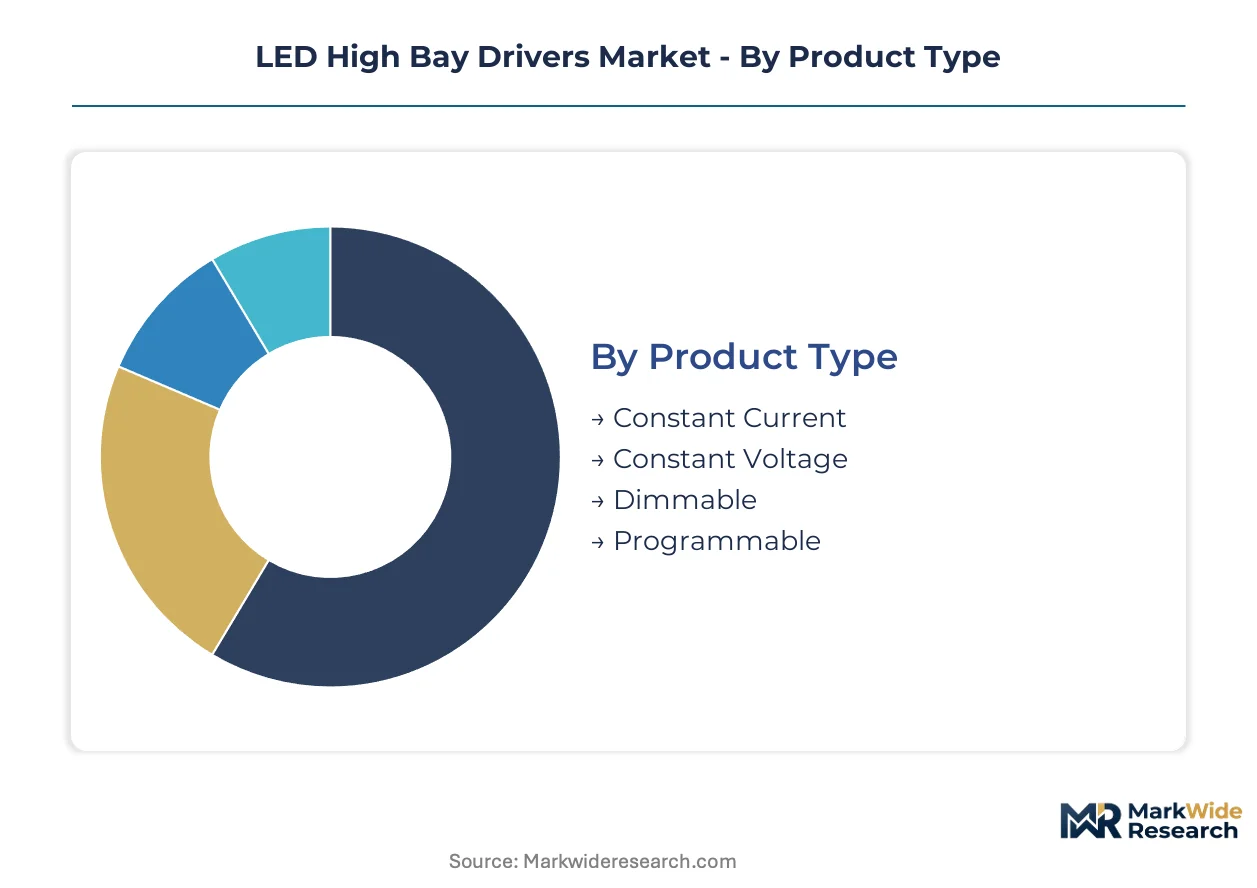
LED high bay driver procurement varies sharply by operational context. Facility managers prioritize interchangeability for retrofit fleets, while new construction specifiers demand programmable architectures for building integration.
Product Type:
Capital intensity escalates from basic magnetics designs through firmware-enabled programmable units, with semiconductor content and engineering hours driving cost differentials.
- Constant Current:Delivers fixed output current to high-lumen COB and SMD arrays regardless of input fluctuations. Demand concentrates in Shenzhen-Dongguan manufacturing corridors where standardized 100-480V AC units ship for global industrial retrofit programs. The topology dominates volume due to magnetic ballast replacement urgency in United States warehousing.
- Programmable:Embeds microcontroller firmware for tunable output curves and protocol bridging. Premium positioning accelerates in German automotive plant retrofits where DALI-2 integration justifies higher upfront expenditure against ten-year energy models.
- Constant Voltage:Maintains stable output voltage for LED strip configurations in auxiliary industrial lighting.
- Dimmable:Enables 0-10V or DALI phase-cut control for daylight harvesting in exhibition halls and commercial atriums.
Most installed capacity flows through Constant Current. Expansion is steepest in Programmable.
Application:
Operating hour intensity and ceiling height create divergent performance requirements across installation environments.
- Warehouses:24/7 operations with 30-40 foot mounting heights demand 90%+ efficiency and 50,000-hour rated life. United States third-party logistics operators compress replacement cycles to capture EPA ENERGY STAR utility rebates, pulling volume through standardized driver-luminaire bundles.
- Exhibition Halls:Variable occupancy and daylight ingress mandate dimmable architectures with sub-1% flicker thresholds. Premium positioning here reflects commissioning complexity and controls integration rather than raw driver cost.
- Industrial Lighting:Heavy manufacturing floors with vibration and thermal stress require potted magnetics and extended temperature ratings.
- Commercial Spaces:Retail and office high bay installations prioritize aesthetic compatibility and wireless mesh readiness over industrial-grade durability.
Warehouse retrofits absorb the largest share of annual shipments. Exhibition hall specifications are climbing the fastest.
Technology:
Voltage classification and intelligence layers segment engineering talent requirements and supply chain sourcing.
- Smart Technology:Integrates onboard sensing, edge analytics, and cloud connectivity for predictive maintenance. Adoption concentrates in Netherlands distribution centers where CSRD-mandated energy transparency drives connected lighting investment.
- High Voltage:277-480V direct drive eliminates step-down transformers in North American industrial infrastructure. Demand clusters around Chicago and Dallas logistics hubs where legacy 480V distribution persists.
- Low Voltage:100-240V universal input serves retrofit compatibility and international voltage standards.
- Wireless Control:Bluetooth mesh and proprietary RF protocols enable retrofit controls without dedicated wiring.
High Voltage platforms carry the heaviest installed base. Smart Technology is gaining share fastest.
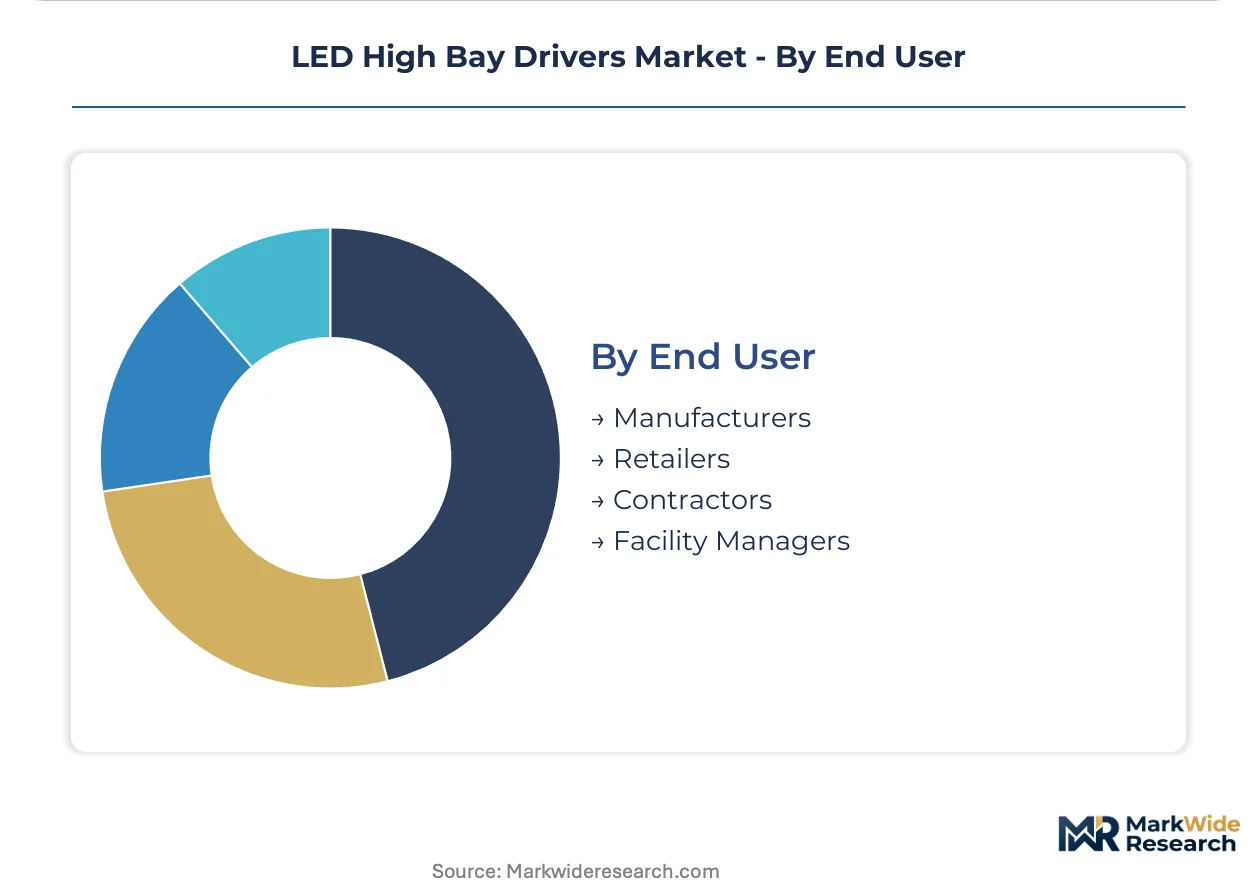
End User:
Procurement authority and technical sophistication determine specification depth and supplier relationship intensity.
- Facility Managers:Centralized purchasing for REIT and logistics networks evaluates ten-year total cost of ownership, elevating efficiency and warranty terms in scoring algorithms. United States warehouse operators now require ENERGY STAR certification as a baseline qualifier.
- Contractors:Installation-speed and interchangeability drive preference for standardized form factors with tool-free wiring compartments. MEAN WELL's aftermarket positioning captures this segment through distributor availability.
- Manufacturers:Luminaire OEMs specify custom driver platforms for thermal and mechanical integration, often requiring captive supply arrangements.
- Retailers:Big-box and specialty lighting chains prioritize SKU consolidation and private label margin over technical differentiation.
Facility managers control the largest contract value. Contractor channel volume is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
LED high bay driver manufacturing originated in East Asian electronics clusters during the 2000s, with Taiwan and mainland China developing the core magnetics and semiconductor packaging infrastructure that now supplies global industrial lighting retrofits.
United States
Third-party logistics operators and REITs drive retrofit urgency across distribution networks. EPA ENERGY STAR certification requirements filter procurement shortlists for utility rebate eligibility. Chicago and Dallas logistics hubs concentrate demand for 277-480V high-voltage drivers compatible with legacy industrial electrical infrastructure.
Germany
Automotive plant retrofits pull adoption of programmable drivers with DALI-2 integration. The EU Ecodesign Directive's 2025 efficiency tier revision mandates 94% minimum driver efficiency for industrial luminaires above 100W. Industrial buyers in Baden-Württemberg and Bavaria filter procurement against draft tier levels ahead of formal implementation.
China
Export manufacturing around Shenzhen and Dongguan sustains volume production of standardized 100-480V AC drivers. GB standards and NEEA efficiency labeling create parallel compliance tracks for export-bound versus domestic-market production. The Pearl River Delta cluster ships standardized form factors to global retrofit programs.
India
Industrial corridor expansion between Delhi and Mumbai creates first-mover positioning for programmable driver suppliers in underpenetrated warehousing infrastructure. The Bureau of Indian Standards enforces efficiency labeling for industrial luminaires under CEA regulations. Gujarat and Maharashtra manufacturing zones attract driver assembly investment for domestic and export markets.
Netherlands
CSRD-mandated energy transparency drives connected lighting investment in distribution centers. Smart technology adoption concentrates around Rotterdam and Eindhoven logistics hubs where edge analytics and cloud connectivity justify premium positioning. Dutch facility managers evaluate ten-year energy cost models in centralized procurement decisions.
LED High Bay Drivers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the efficiency-certification spectrum, with programmable and dimmable architectures commanding price multiples over basic constant current units. The vendor base organizes into three tiers: vertically integrated lighting conglomerates with captive driver production, specialized power electronics manufacturers serving aftermarket interchangeability demands, and semiconductor suppliers providing reference designs and control ICs. Competitive moves center on backward integration into LED package manufacturing and strategic partnerships with building management system providers.
Within the integrated lighting tier, Signify and ams OSRAM occupy positions spanning driver-luminaire bundling and LED package supply. MEAN WELL Enterprises anchors the aftermarket-focused tier through standardized form factors and distributor availability across Asian manufacturing sites. These three exemplify the strategic archetypes shaping procurement options: bundled project contracting, component interchangeability, and semiconductor platform licensing.
| Leading Market Players |
|---|
| Signify |
| ams OSRAM |
| Acuity Brands Lighting |
| Hubbell Incorporated |
| Eaton |
| Lutron Electronics |
| MEAN WELL Enterprises |
| Texas Instruments |
| Tridonic |
| Others |
Value Network & Pricing Analysis
EU Ecodesign Directive efficiency mandates gate qualified supply access and premium-tier pricing power for industrial luminaire drivers, compressing margin structures for uncertified platforms while rewarding multi-certification engineering investment. Buyers in Germany and the Netherlands now filter procurement shortlists against draft tier levels ahead of formal implementation, forcing suppliers to absorb compliance costs or surrender volume positions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates programmable DALI-2 integrated units from basic constant current variants and unbranded aftermarket interchangeability products. Certification grade under EPA ENERGY STAR and EU RoHS compliance creates the primary price differentiation vector, with utility rebate eligibility in the United States commanding measurable premiums. Cost compression in standard-tier magnetics-heavy designs above 200W is intensifying because copper and rare-earth magnet input volatility squeezes foundry margins. Contractor channels exhibit highest price sensitivity through distributor price-shopping behavior, while facility managers at REITs and third-party logistics networks prioritize ten-year total cost of ownership over upfront unit cost.
Supply Chain Analysis
India's Bureau of Indian Standards efficiency labeling and domestic-content preferences under CEA regulations are reshaping sourcing patterns for assembly investment in Gujarat and Maharashtra manufacturing zones. Taiwan and mainland China anchor power semiconductor packaging for critical MOSFET and diode supply, with the Pearl River Delta cluster feeding magnetics and PCB substrate inputs. Single-source vulnerability concentrates in Taiwan foundry capacity for SiC substrate transition, threatening adoption timelines for 480V industrial applications. Distribution runs through luminaire OEM captive arrangements and specialized power electronics distributors serving aftermarket interchangeability demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LED high bay driver procurement has shifted into a late-cycle quality phase where programmable architectures and multi-certification compliance separate viable suppliers from commodity margin erosion. Facility managers now mandate EPA ENERGY STAR baselines and evaluate DALI-2 integration as standard rather than premium specification.
For Market Incumbents: Acquire magnetics optimization engineering talent and firmware development capabilities to address the scarcity of designers fluent in both disciplines. Backward integration into LED package manufacturing secures thermal-mechanical integration control against luminaire OEM captive supply pressure. Defensive consolidation through distributor channel control in Chicago and Dallas logistics hubs protects 277-480V high-voltage driver positions from emerging programmable specialists. For New Entrants and Emerging Players: EPA ENERGY STAR certification requirements in the United States open a window for rebate-eligible bundled driver-luminaire contracting against interchangeability-focused incumbents. India's industrial corridor expansion between Delhi and Mumbai presents the most penetrable geography for programmable driver suppliers in underpenetrated warehousing infrastructure. Go-to-market positioning through building management system provider partnerships captures software-layer recurring revenue. For Investors and Strategic Acquirers: Roll-up economics work for specialized power electronics manufacturers with standardized form factor positioning because distributor availability and aftermarket interchangeability create defensible revenue streams against integrated lighting conglomerates. Five-to-ten year viability hinges on SiC substrate transition execution and multi-certification platform engineering capability. Watch for German automotive plant retrofit pull-through of programmable DALI-2 specifications as inflection indicator for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Transition | Half switching loss reduction in 480V applications pulls European automotive supplier adoption timelines forward. |
| Multi-Certification Platform Engineering | Single manufacturing lines serving EPA ENERGY STAR, EU RoHS, and China's GB standards prevent SKU proliferation costs. |
| DALI-2 Protocol Integration | German automotive plant retrofits justify premium positioning against ten-year energy cost evaluation models. |
| Building Management System Partnerships | Wireless mesh and edge analytics enable recurring software-layer revenue capture in Netherlands distribution centers. |
| Aftermarket Distributor Channel Control | Tool-free wiring compartment standardization secures contractor preference across Asian manufacturing site retrofits. |
Research Methodology
Bottom-up warehouse and logistics facility modeling reconciled against top-down driver foundry and LED package production tracking forms the analytical core of this study. Primary interviews with facility managers at REITs and third-party logistics operators, luminaire OEM procurement teams, power electronics engineering directors, and distributor channel managers combined with secondary validation from EPA ENERGY STAR certification databases, EU Ecodesign Directive draft tier documentation, China's GB standards filings, and customs trade data for magnetics and semiconductor inputs.
Input-output matrices map constant current, programmable, and dimmable driver segments across warehouse, exhibition hall, and industrial lighting applications through the projection horizon. Segmentation dimensions include product topology, voltage classification, end-user procurement authority, and regional regulatory framework clusters. CAGRs derive from installation volume trajectories, replacement cycle compression, and efficiency mandate compliance deadlines. Forecast inputs incorporate copper and rare-earth magnet price volatility assumptions and SiC MOSFET adoption curves in high-power stages.
Revisions become necessary when EU Ecodesign Directive implementation timelines shift, Taiwan foundry capacity constraints intensify, or India's industrial corridor investment accelerates beyond baseline assumptions. Forecasts reflect documented assumptions about rebate program continuity and building management protocol convergence velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
High Power LED Market
LED
South America LED Lighting Market
LED
Japan LED Market
LED
India LED Lighting Market
LED
Gan Micro LED Market
LED
Middle East LED Lighting Market
LED
North America Outdoor LED Lighting Market
LED
Global Waterproof LED Module Market
LED
Global Chip Scale Package (CSP) LED Market
LED
Middle East and Africa Outdoor LED Lighting Market
LED
LED Driver Market
LED
LED Tester Market
LED
Mexico LED Lighting Market
LED
Microled Market
LED
North America Indoor LED Lighting Market
LED
LED Lighting Controllers Market