
 DC Power Supplies Market | 2026-2036
DC Power Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
DC Power Supplies Market Intelligence
Aftermarket calibration and recertification services is rewriting margin distribution across the DC power supplies value chain. Keysight Technologies leverages its installed base of precision instruments to sustain recurring revenue streams from enterprise laboratories. Ametek anchors North American industrial demand through its programmable power portfolio. Chroma ATE dominates Asia-Pacific test equipment channels with localized service networks.
A DC power supply converts electrical energy from a source into a regulated direct current output, with switching architectures achieving efficiency above 85% through high-frequency transistor modulation and feedback control loops. These devices provide stable voltage and current for testing electronic components, powering industrial automation, and charging battery systems. Switching power supply designs lead volume shipments due to their compact magnetics and thermal performance, while programmable power supply units command premium positioning in semiconductor validation workflows where sweep sequencing and remote programmability reduce test cycle times. Battery charger segments are maturing in consumer electronics but finding renewed application in electric vehicle powertrain development.
The US Department of Energy enforces minimum efficiency standards under external power supply regulations that disqualify linear designs in many consumer and industrial categories. The EU Ecodesign Directive and CE marking requirements under the Low Voltage Directive shape product architecture decisions for any supplier seeking European market access. China's GB standards and NMPA testing protocols add compliance layers for medical and automotive diagnostic applications. Stakeholders must monitor how efficiency tier migrations and region-specific electromagnetic compatibility certifications reshape sourcing strategies and factory qualification timelines.
Market Dynamics
Switching power supply architectures are displacing linear designs across industrial and consumer categories, driven by the US Department of Energy's minimum efficiency standards and the EU Ecodesign Directive's tiered requirements. This regulatory compression is accelerating factory qualification timelines and reshaping supplier competitive positioning.
Growth Catalysts
- Semiconductor fabrication expansion:Taiwan and South Korea are expanding programmable power supply procurement to support advanced node testing workflows. This demand concentrates in facilities migrating to sub-3nm process nodes.
- EU Ecodesign Directive:Tightening efficiency standards are forcing replacement cycles in European industrial installations. Suppliers must redesign magnetics and control loops to meet 2026 tier migrations.
- Electric vehicle battery testing corridors:China's NEV powertrain development is creating concentrated demand for high-current programmable units. Domestic and foreign suppliers compete for qualification slots in CATL and BYD supply chains.
Market Restraints
- Input cost volatility:Rare earth magnet prices and copper winding costs fluctuate with Chinese export quotas. This compresses margins on high-frequency transformer assemblies.
- Supply concentration risk:Taiwan-based semiconductor foundries dominate MOSFET and IGBT fabrication for switching controllers. Geographic concentration creates vulnerability to seismic and geopolitical disruption.
- Linear design obsolescence:Residual demand for ultra-low noise linear supplies in precision instrumentation faces technical limitation. Switching ripple specifications below 1mV remain difficult to achieve without hybrid architectures.
Strategic Opportunities
- Underpenetrated medical diagnostics:India's CDSCO is streamlining NMPA-equivalent testing protocols for imported diagnostic power supplies. Early entrants capture qualification slots in diagnostic imaging and patient monitoring.
- Regulatory tailwind:The US Inflation Reduction Act's domestic content bonuses incentivize reshoring of power supply manufacturing. Contract manufacturers are qualifying US-based SMT and magnetics suppliers.
- Technology convergence:Digital control loops and wide-bandgap GaN semiconductors are converging to enable 95%+ efficiency at higher switching frequencies. This compresses thermal management requirements and enclosure volumes.
Industry Challenges
- Certification timeline compression:China's GB standards and NMPA testing protocols add parallel compliance tracks for medical and automotive applications. Dual-track qualification extends time-to-revenue by 8-14 months.
- Legacy system integration friction:Industrial automation buyers require backward compatibility with 4-20mA analog control interfaces. Digital-native power supplies must embed protocol bridges, adding BOM complexity.
- Electromagnetic compatibility skill scarcity:Filter design and EMI mitigation expertise concentrates in senior engineers at tier-one suppliers. Mid-tier manufacturers struggle to recruit qualified compliance engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DC Power Supplies Market |
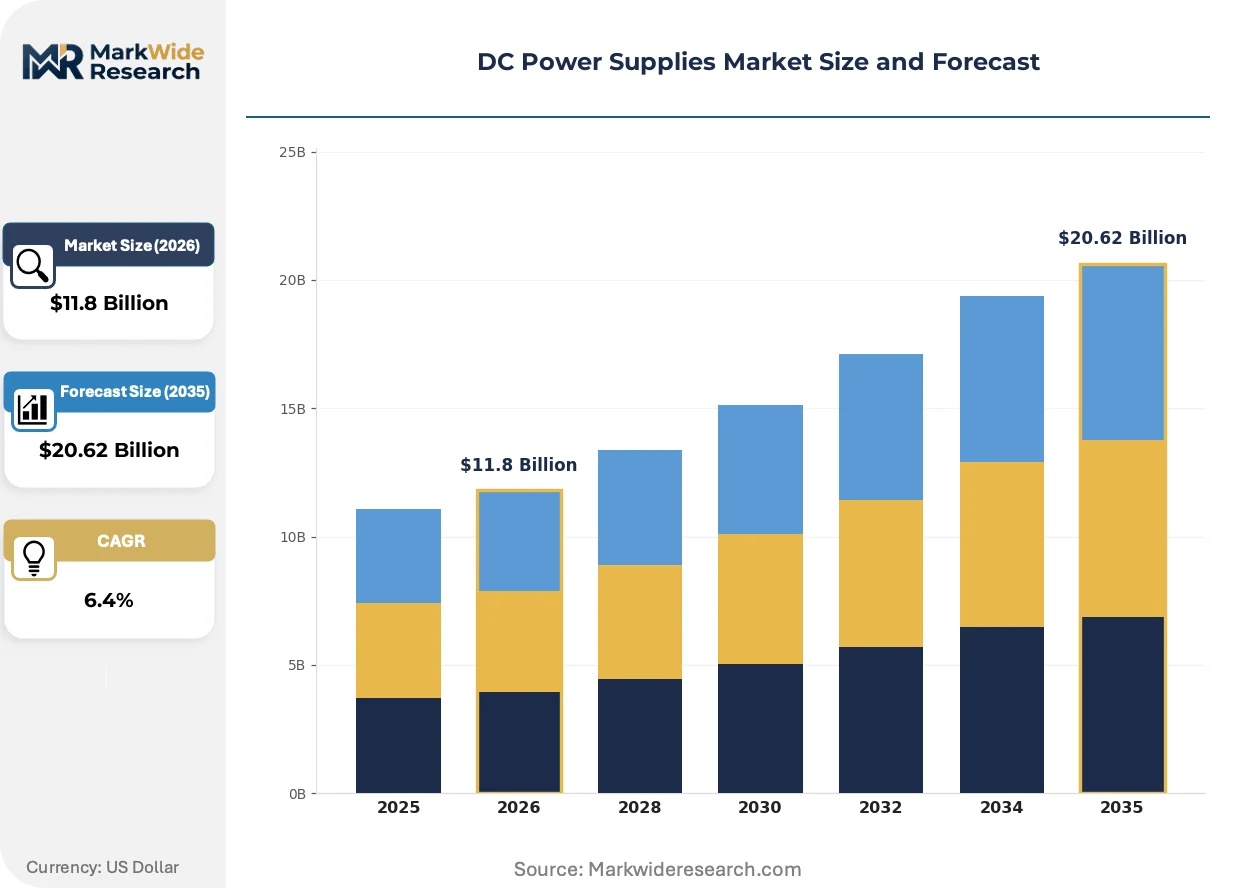
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Power Supply, Switching Power Supply, Programmable Power Supply, Battery Charger End User: Telecommunications, Industrial Equipment, Consumer Electronics, Automotive Application: Test and Measurement, Laboratory, LED Lighting, Automotive Diagnostic Technology: AC-DC Converter, DC-DC Converter, Isolated Converter, Non-isolated Converter |
| Companies Covered | Keysight Technologies Inc., Ametek Inc., Chroma ATE Inc., B&K Precision Corporation, MEAN WELL Enterprises Co. Ltd., Rohde & Schwarz GmbH & Co KG, TDK Corporation, Magna-Power Electronics Inc., Good Will Instrument Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DC Power Supplies Market Strategic Shifts & Innovations
Silicon carbide and gallium nitride wide-bandgap semiconductors are rewriting thermal and efficiency boundaries across DC power supply architectures. These material shifts enable higher power density while compressing magnetics volume and cooling overhead.
GaN HEMT switches are collapsing the traditional trade-off between switching frequency and efficiency loss in high-density designs. Data center power architects are adopting 100kHz+ switching topologies to reduce inductor size by 40-60%. This is collapsing enclosure form factors and enabling 1U rack-mount supplies previously requiring 2U or 3U heights.
The EU Ecodesign Directive's 2026 tier is mandating active power factor correction above 75W in external supplies. Industrial OEMs are redesigning front-end stages to meet harmonic distortion limits under EN 61000-3-2. Server and telecom power supply categories face the steepest redesign cycles, with European qualification gates now requiring third-party efficiency certification.
Aftermarket calibration and recertification services are unbundling from original equipment sales in enterprise laboratory channels. Buyers are extending asset lifecycles through third-party metrology providers rather than trading up to new hardware. This pattern concentrates in North American and European R&D facilities with depreciated installed bases of programmable instruments.
DC Power Supplies Market Segmentation
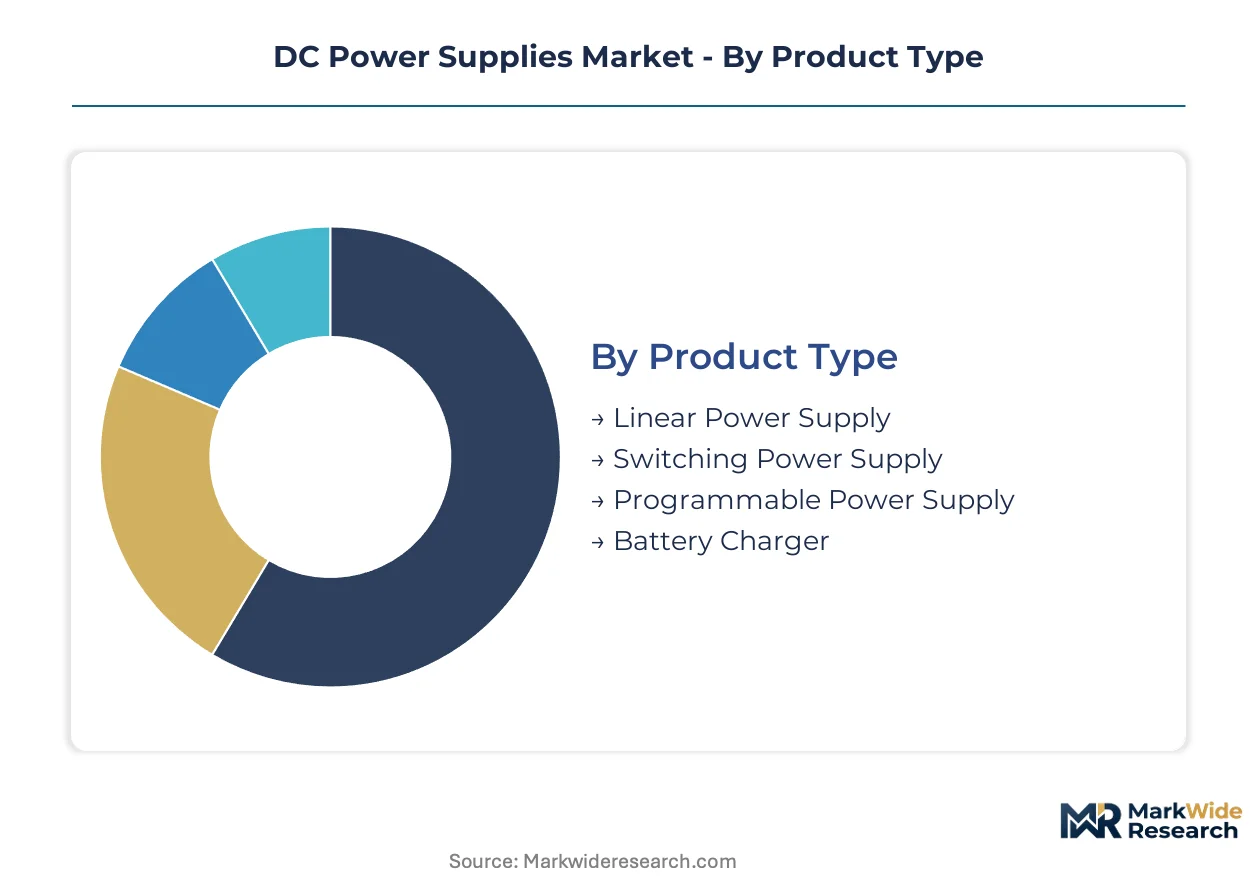
DC power supply segmentation reveals how technical architecture, end-use requirements, and application environments reshape procurement priorities. Buyers select architectures based on efficiency mandates, noise tolerance, and programmability needs rather than unit cost alone.
Product Type:
Mature linear designs coexist with emerging wide-bandgap switching architectures across industrial and consumer categories.
- Switching Power Supply:High-frequency transistor modulation achieves efficiency above 85% through compact magnetics and feedback control loops. Demand concentrates in China's electric vehicle battery testing corridors where thermal performance and power density determine supplier qualification.
- Programmable Power Supply:Sweep sequencing and remote programmability reduce test cycle times in semiconductor validation workflows. Taiwan and South Korea fabrication facilities expanding to sub-3nm process nodes drive procurement of these premium units.
- Linear Power Supply:Residual demand persists in precision instrumentation requiring ultra-low noise below 1mV ripple. Hybrid architectures address technical limitations as pure linear designs face obsolescence under US Department of Energy efficiency standards.
- Battery Charger:Consumer electronics applications mature while electric vehicle powertrain development renews demand for high-current programmable charging systems.
Switching power supply handles the majority of throughput; programmable power supply is expanding most quickly on share.
End User:
Cost tier stratification separates mission-critical industrial applications from price-sensitive consumer segments.
- Industrial Equipment:Factory automation and process control demand ruggedized units with 4-20mA analog compatibility. Ametek anchors North American demand through programmable power portfolios serving manufacturing and aerospace test facilities.
- Automotive:Electric vehicle battery testing and powertrain development require high-current programmable units with CAN bus integration. China's NEV corridors concentrate procurement competition between domestic and foreign suppliers.
- Telecommunications:Server and telecom power supply categories face steep redesign cycles under EU Ecodesign Directive 2026 tier requirements for active power factor correction above 75W.
- Consumer Electronics:External power supply regulations disqualify linear designs across many product categories, compressing margins and accelerating supplier consolidation.
Industrial equipment commands the premium tier; automotive is climbing the fastest as electrification accelerates test equipment procurement.
Application:
Volume concentration in laboratory channels contrasts with emerging demand in automotive diagnostic environments.
- Test and Measurement:Enterprise laboratories extend asset lifecycles through aftermarket calibration and recertification services rather than hardware replacement. Keysight Technologies leverages installed bases to sustain recurring revenue streams.
- Automotive Diagnostic:China's GB standards and NMPA testing protocols add compliance layers for imported diagnostic power supplies. India's CDSCO is streamlining equivalent protocols, creating early-entrant opportunities in diagnostic imaging.
- Laboratory:North American and European R&D facilities with depreciated installed bases drive unbundling of metrology services from original equipment sales.
- LED Lighting:Commercial and industrial retrofit cycles sustain demand for constant-current drivers with power factor correction.
Test and measurement dominates current installed value; automotive diagnostic is gaining share fastest on regulatory expansion.
Technology:
Supply concentration in wide-bandgap semiconductors reconfigures converter architecture roadmaps.
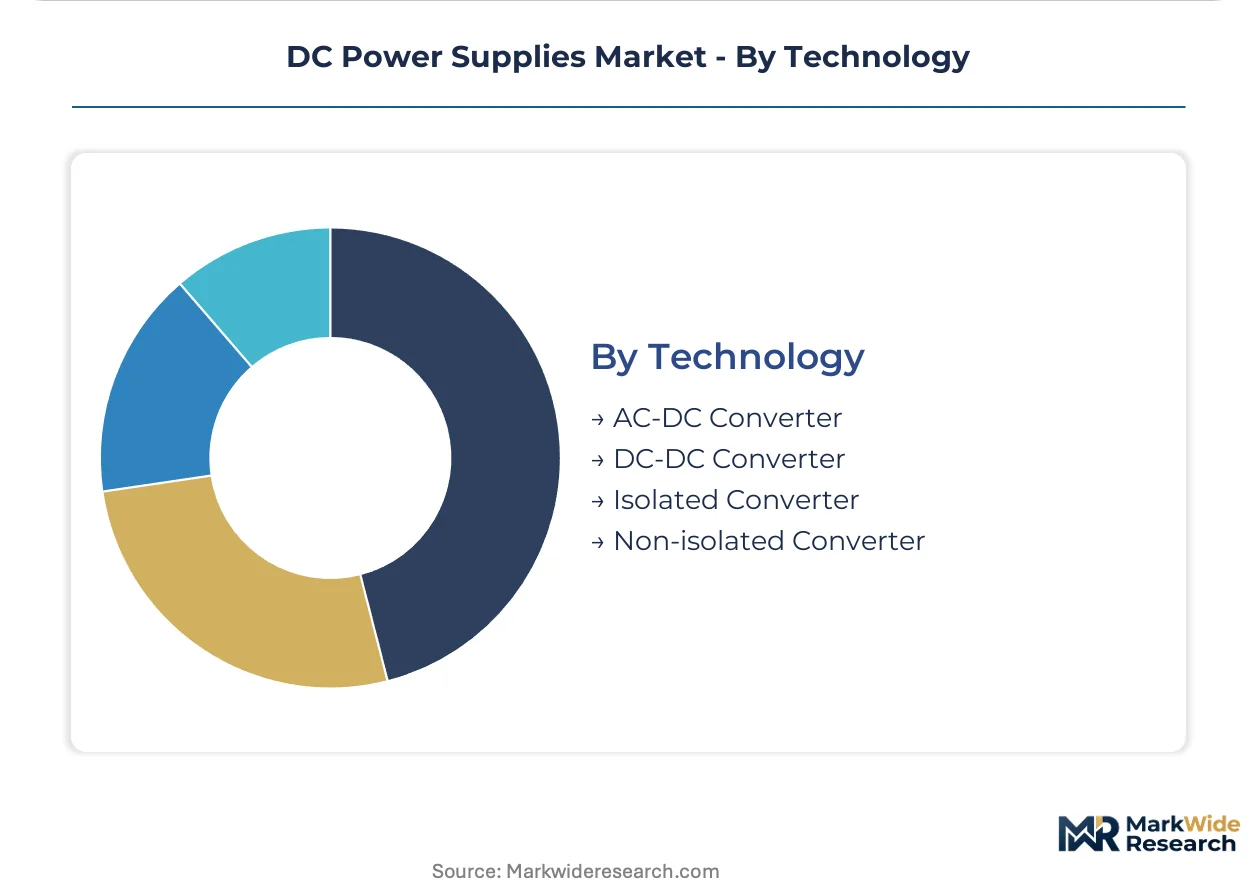
- AC-DC Converter:Front-end stages redesign to meet EU Ecodesign Directive harmonic distortion limits under EN 61000-3-2. Active power factor correction above 75W is now mandatory for European market access.
- DC-DC Converter:Wide-bandgap GaN semiconductors enable 95%+ efficiency at switching frequencies above 100kHz. Data center architects adopt these topologies to compress inductor size by 40-60%.
- Isolated Converter:Medical and automotive diagnostic applications require galvanic isolation meeting reinforced insulation standards. China's NMPA and India's CDSCO impose parallel certification tracks extending qualification timelines.
- Non-isolated Converter:Point-of-load applications in consumer electronics and embedded systems prioritize cost and footprint over isolation.
AC-DC converter carries the broadest regulatory exposure; DC-DC converter shows the steepest expansion trajectory on wide-bandgap adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply by application maturity. Laboratory buyers in North America and Western Europe resist hardware replacement, extending calibration contracts instead. Chinese automotive testing corridors show the opposite pattern: qualification slots command premiums as battery cell production scales.
United States
Industrial automation and aerospace test facilities drive programmable power procurement. The US Department of Energy enforces minimum efficiency standards under external power supply regulations that disqualify linear designs. Greater Boston and Pacific Northwest clusters concentrate R&D facilities extending asset lifecycles through third-party metrology services rather than capital expenditure.
Germany
Automotive powertrain electrification and industrial machinery export demand sustain premium-tier procurement. The EU Ecodesign Directive's 2026 tier mandates active power factor correction above 75W, forcing front-end stage redesigns. Bavaria's automotive testing corridors and Baden-Württemberg's precision engineering clusters absorb high-current programmable units for validation workflows.
China
Electric vehicle battery testing corridors generate the steepest demand acceleration globally. GB standards and NMPA testing protocols impose parallel compliance tracks for medical and automotive diagnostic applications. Yangtze River Delta and Pearl River Delta manufacturing belts concentrate competition between domestic suppliers and foreign incumbents for CATL and BYD qualification slots.
South Korea
Semiconductor fabrication expansion to sub-3nm process nodes drives precision programmable power supply procurement. METI-equivalent efficiency frameworks shape industrial procurement specifications. Seoul Capital Area fabrication facilities anchor Asia-Pacific demand for sweep sequencing and remote programmability in advanced node testing workflows.
India
Diagnostic imaging and patient monitoring equipment create early-entrant opportunities as CDSCO streamlines NMPA-equivalent testing protocols. BIS certification requirements and PLI scheme incentives reshape sourcing strategies for imported power supplies. Maharashtra and Karnataka medical device manufacturing corridors attract qualification-focused suppliers seeking first-mover positioning.
DC Power Supplies Market Key Industry Players
Test equipment specialists and industrial power fabricators split the market along application boundaries. The vendor base concentrates around three strategic archetypes: precision instrumentation incumbents with installed base leverage, programmable power specialists serving semiconductor validation, and volume switching supply manufacturers competing on magnetics cost. Consolidation pressure intensifies as efficiency regulations compress margins on legacy architectures. Geographic expansion and technology licensing dominate competitive moves, with wide-bandgap semiconductor partnerships rewriting thermal performance benchmarks.
Within the precision instrumentation tier, Keysight Technologies Inc. and Rohde & Schwarz GmbH & Co KG exemplify archetypes leveraging calibration service networks to sustain recurring revenue. Chroma ATE Inc. occupies a position representing Asia-Pacific channel dominance through localized service infrastructure. These three anchors illustrate how installed base scale and regional service density separate sustainable positioning from commodity competition in regulated efficiency environments.
| Leading Market Players |
|---|
| Keysight Technologies Inc. |
| Ametek Inc. |
| Chroma ATE Inc. |
| B&K Precision Corporation |
| MEAN WELL Enterprises Co. Ltd. |
| Rohde & Schwarz GmbH & Co KG |
| TDK Corporation |
| Magna-Power Electronics Inc. |
| Good Will Instrument Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Taiwan-based MOSFET and IGBT foundries compresses both margin buffers and supplier pricing power across programmable and switching power supply tiers. This concentration forces buyers into premium qualification slots while exposing procurement budgets to seismic and geopolitical disruption premiums.
Pricing Analysis
Aftermarket calibration and recertification services anchor lifetime value capture for precision instrumentation suppliers. Three-tier pricing structure across premium programmable units, standard switching architectures, and economy linear designs separates semiconductor validation workflows from industrial automation procurement. Cost compression in economy tiers intensifies because efficiency regulations disqualify legacy linear designs. Consumer electronics buyers exhibit highest price sensitivity; aerospace test facilities demonstrate lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates sourcing decisions for magnetics and final assembly operations. Taiwan, South Korea, and Japan anchor semiconductor controller fabrication; China concentrates winding and enclosure manufacturing. Rare earth magnet and copper winding costs feed from Chinese export quota volatility. Single-source vulnerability in wide-bandgap GaN substrate supply creates qualification bottlenecks. Distribution runs through authorized test equipment distributors and direct OEM contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across efficiency tiers and regional certification tracks creates niche entry points for specialists. Electrification of automotive powertrains splits demand between high-current programmable units and commodity switching supplies.
For Market Incumbents: Entrench installed base leverage through captive calibration networks and backward integration into magnetics production. Keysight Technologies and Chroma ATE demonstrate how regional service density defends against price erosion. Threat from digital-native power supply entrants with embedded protocol bridges demands certification investment in medical and automotive diagnostic tiers. For New Entrants and Emerging Players: Pursue India's diagnostic imaging corridors as CDSCO streamlines NMPA-equivalent testing protocols. Underpenetrated medical power supply segments in Maharashtra and Karnataka offer lowest competitive density. Go-to-market through local contract manufacturers with existing BIS certification accelerates qualification timelines. For Investors and Strategic Acquirers: The market sits at a regulatory compression phase that favors wide-bandgap technology specialists with captive GaN supply agreements. Long-term viability over the next decade hinges on efficiency tier migration execution. Acquisition target archetype: mid-tier programmable power suppliers with automotive CAN bus integration capabilities. Signal to watch: US Inflation Reduction Act domestic content bonus qualification rates.| Strategic Initiative | Industry Significance |
|---|---|
| Wide-Bandgap Technology Licensing | GaN and SiC partnerships with Taiwan foundries compress thermal management costs below silicon baselines. |
| Regional Certification Expansion | Parallel NMPA and CDSCO qualification tracks capture medical diagnostic power supply slots in Asia-Pacific. |
| Backward Integration into Magnetics | In-house transformer production insulates margins from rare earth export quota volatility. |
| Aftermarket Service Unbundling | Third-party metrology contracts extend revenue streams from depreciated enterprise laboratory installed bases. |
| Automotive Qualification Partnership | CATL and BYD supply chain slots anchor high-current programmable unit demand in China's NEV corridors. |
Research Approach
The analysis maps switching architectures, programmable precision units, linear residual demand, and battery charger segments, each validated through procurement managers at semiconductor fabrication facilities, test equipment distributors, and automotive powertrain engineers. Primary interviews with calibration service heads and regulatory compliance officers at tier-one suppliers combined with secondary validation from US Department of Energy efficiency filings, EU Ecodesign Directive tier documentation, and China GB standards releases. Bottom-up shipment data and top-down industrial automation capex triangulation anchor volume estimates.
Assumptions held fixed include efficiency tier migration timelines under external power supply regulations and wide-bandgap semiconductor cost curves; variables tested include rare earth export quota severity and automotive electrification penetration rates. Segmentation dimensions modeled span product architecture, end-use industry, application environment, and converter technology across the projection horizon. CAGRs derive from shipment trajectory analysis against industrial equipment and automotive test equipment procurement cycles. GaN adoption rates in data center power supplies and NEV battery testing corridor expansion serve as demand-side sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in copper and rare earth pricing, Taiwan seismic risk realization, or US-China tariff escalation would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology substitution elasticities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Integrated UPS Market
Power Systems
Charge Pumps Market
Power Systems
Static VAR Compensator (SVC) Market
Power Systems
Europe Variable Frequency Drive Market
Power Systems
South America Battery Management System Market
Power Systems
Marine Variable Frequency Drives Market
Power Systems
Nimh Rechargeable Battery Market
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market
Power Systems
Gan-Powered Chargers Market
Power Systems
Flyback Transformer Market
Power Systems
Burner Management System (BMS) Market
Power Systems
Organic Fixed Power Capacitors Sales Market
Power Systems
Intelligent Power Module (IPM) Market
Power Systems
HVDC Converters Market
Power Systems
Global Plasma Generators Market
Power Systems
Central Battery Systems Market