
 Australia Energy-As-A-Service Market | 2026-2036
Australia Energy-As-A-Service Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Energy-As-A-Service Market Outlook
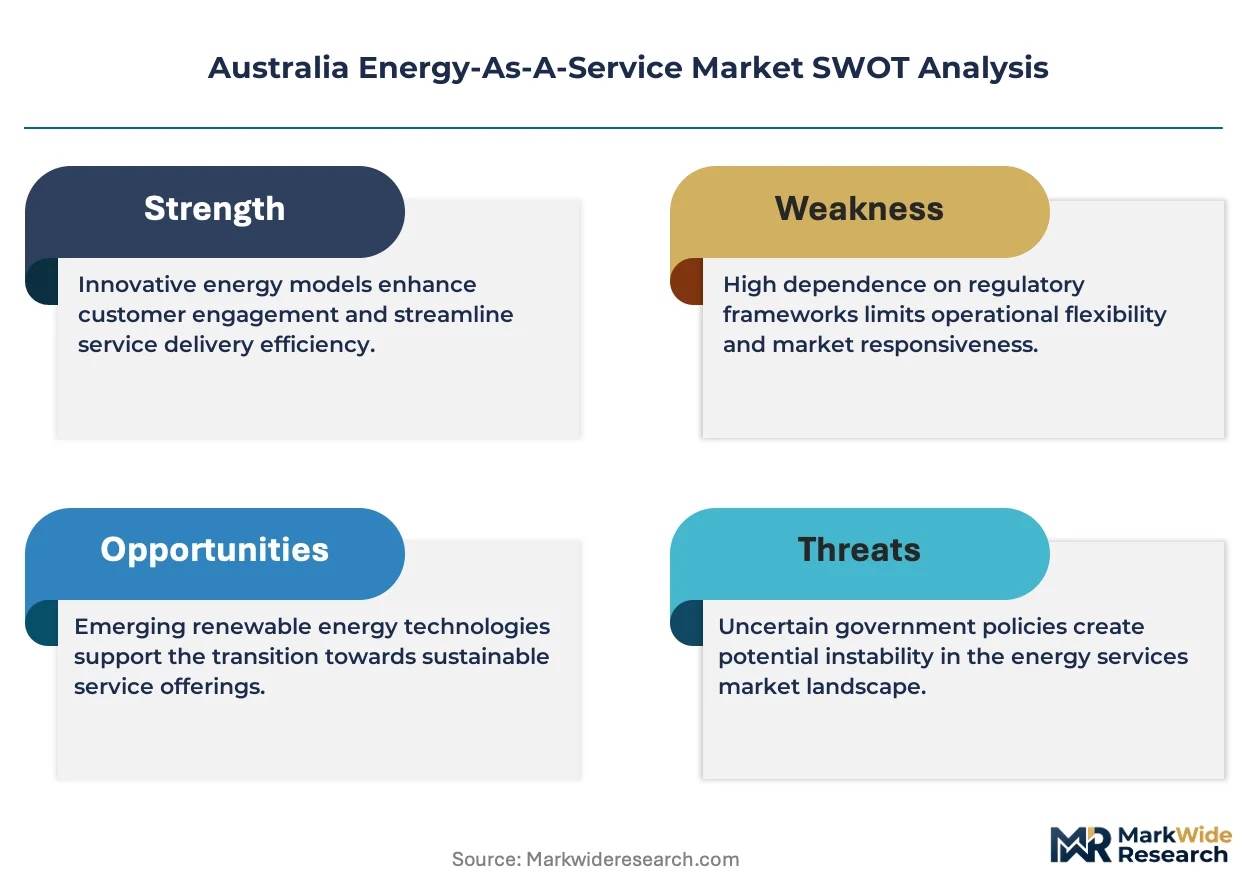
Commercial property portfolios and data center operators are redrawing procurement priorities in the Australia Energy-As-A-Service Market, shifting capital expenditure away from owned generation assets toward performance-contracted outcomes. Schneider Electric leverages its integrated microgrid and digital energy management stack to anchor large industrial accounts across Queensland and Western Australia. ENGIE competes through its distributed solar-plus-storage offerings, while Siemens specializes in building automation and energy optimization software for healthcare and retail verticals.
Energy-as-a-Service encompasses the outsourced provision of energy generation, storage, efficiency, and management functions through long-term contractual arrangements, typically structured around guaranteed cost reductions, reliability metrics, or carbon outcomes rather than equipment ownership. The model relies on real-time metering, predictive analytics, and automated dispatch to align onsite asset operation with wholesale price signals and network constraint events. Renewable Energy and Storage Solutions together command the dominant share of contracted value, as falling battery costs and firming requirements reshape customer economics. Demand Response represents the fastest-expanding service category, driven by Australian Energy Market Operator frequency control ancillary service reforms and commercial hunger for demand-side revenue streams.
The Australian Energy Regulator and Australian Energy Market Commission jointly govern market access rules, connection standards, and consumer protections that directly determine which EaaS providers can participate in wholesale and retail markets. The Clean Energy Finance Corporation's concessional debt programs and the Safeguard Mechanism reforms under the National Greenhouse and Energy Reporting Act are channeling industrial customers toward contracted decarbonization pathways. Stakeholders must track how the five-minute settlement rule and evolving distributed energy resource standards reshape the value stack available to behind-the-meter providers.
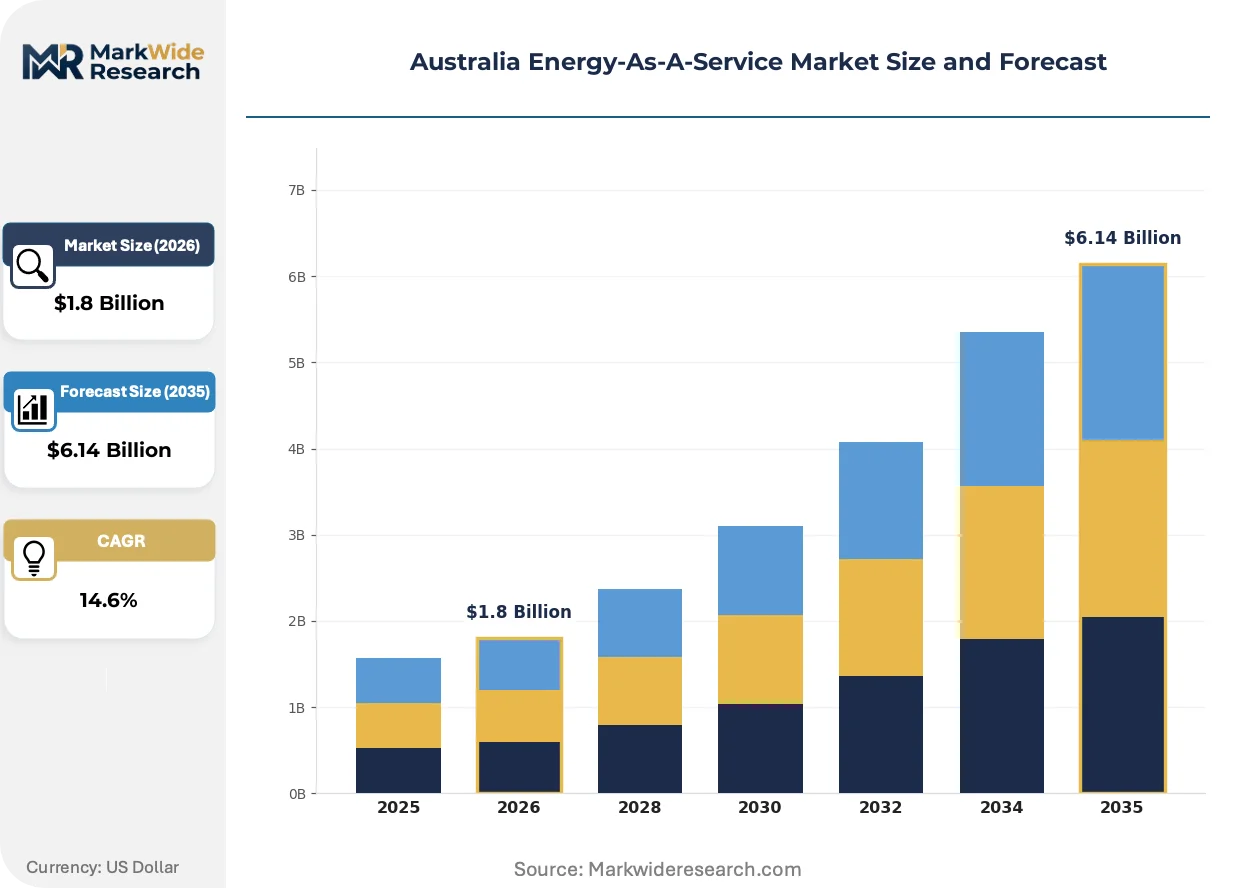
Market Dynamics
The Australian Energy Market Operator's five-minute settlement rule and distributed energy resource integration mandates are compressing procurement cycles and forcing commercial and industrial load centers to outsource real-time energy optimization to third-party providers.
Growth Catalysts
- AEMO Frequency Control Ancillary Services:The Australian Energy Market Operator's market reforms enable demand response aggregators to monetize behind-the-meter flexibility, pulling data center operators and cold storage facilities into long-term EaaS contracts.
- Safeguard Mechanism Reforms:Australia's National Greenhouse and Energy Reporting Act amendments impose baseline emission reductions on large facilities, channeling mining and manufacturing toward contracted decarbonization pathways with guaranteed carbon outcomes.
- Behind-the-Meter Solar-Plus-Storage:Falling lithium-ion battery costs and rising network constraint events in New South Wales and Victoria make onsite firming economically viable for commercial building portfolios without capital deployment.
Market Restraints
- Grid Connection Queues:The Australian Energy Regulator's technical standards and distribution network service provider approval timelines stretch 12-24 months for commercial-scale distributed energy resources, delaying contracted revenue recognition.
- Lithium Supply Concentration:Battery storage procurement depends on concentrated upstream processing in China, exposing Australian EaaS providers to input cost volatility and supply security risks outside their hedging capacity.
- Wholesale Price Volatility:The National Electricity Market's exposure to gas-fired generation marginal pricing creates revenue forecasting complexity that constrains long-term contract pricing and financier risk appetite.
Strategic Opportunities
- Queensland Industrial Load:Mining and smelting operations in Gladstone and Townsville remain underpenetrated by performance-contracted energy services, presenting first-mover advantage for providers with heavy industrial microgrid expertise.
- Clean Energy Finance Corporation Debt:The CEFC's concessional loan programs for energy efficiency and renewable projects reduce weighted average cost of capital for EaaS providers structuring asset-heavy balance sheets.
- Virtual Power Plant Aggregation:Convergence of residential battery fleets with commercial demand response platforms enables EaaS providers to stack wholesale market revenues across customer classes without incremental asset deployment.
Industry Challenges
- Power Systems Engineering Talent:The specialized skill set combining grid integration, predictive analytics, and commercial structuring remains scarce in Australian labor markets, inflating personnel costs and constraining deployment velocity.
- Legacy Building Management System Integration:Commercial property portfolios operate fragmented HVAC and lighting control architectures that resist standardized API connectivity, forcing costly custom integration work for each EaaS deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Energy-As-A-Service Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Renewable Energy, Storage Solutions, Energy Efficiency, Demand Response Industry Vertical: Manufacturing, Healthcare, Retail, Telecommunications Installation: Onsite, Offsite, Hybrid, Remote Customer Type: Commercial, Industrial, Residential, Government |
| Companies Covered | Schneider Electric, ENGIE, General Electric, Edison International, Enertika, Enel X, Ameresco, Johnson Controls, Siemens, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Energy-As-A-Service Market Strategic Shifts
Digital energy management platforms are compressing the traditional boundaries between generation asset control, demand-side dispatch, and wholesale market participation, creating new service categories that bundle previously separate functions.
Artificial intelligence-driven predictive analytics is decomposing the traditional split between energy procurement and facility operations. Large retail and healthcare building operators are adopting integrated platforms that automate HVAC, lighting, and battery dispatch against real-time price signals. This convergence is collapsing the vendor stack and forcing standalone building automation providers to reposition as software modules within broader EaaS offerings.
The Australian Energy Market Commission's evolving distributed energy resource standards are rewriting connection and dispatch obligations for behind-the-meter assets. Industrial facilities with onsite generation must now comply with revised fault ride-through and frequency response requirements. Queensland and Western Australia mining operations face the steepest compliance curves as they retrofit existing microgrids to meet synchronous condenser and grid-forming inverter specifications.
Commercial property funds are consolidating energy decision authority at portfolio level rather than individual asset level. Blackstone and Charter Hall-type vehicles now mandate centralized EaaS procurement across their Australian office and logistics holdings, displacing site-level facility manager discretion. This concentration is most visible in Sydney and Melbourne CBD commercial towers where landlords negotiate master service agreements covering multiple buildings under single performance guarantees.
Australia Energy-As-A-Service Market Segmentation
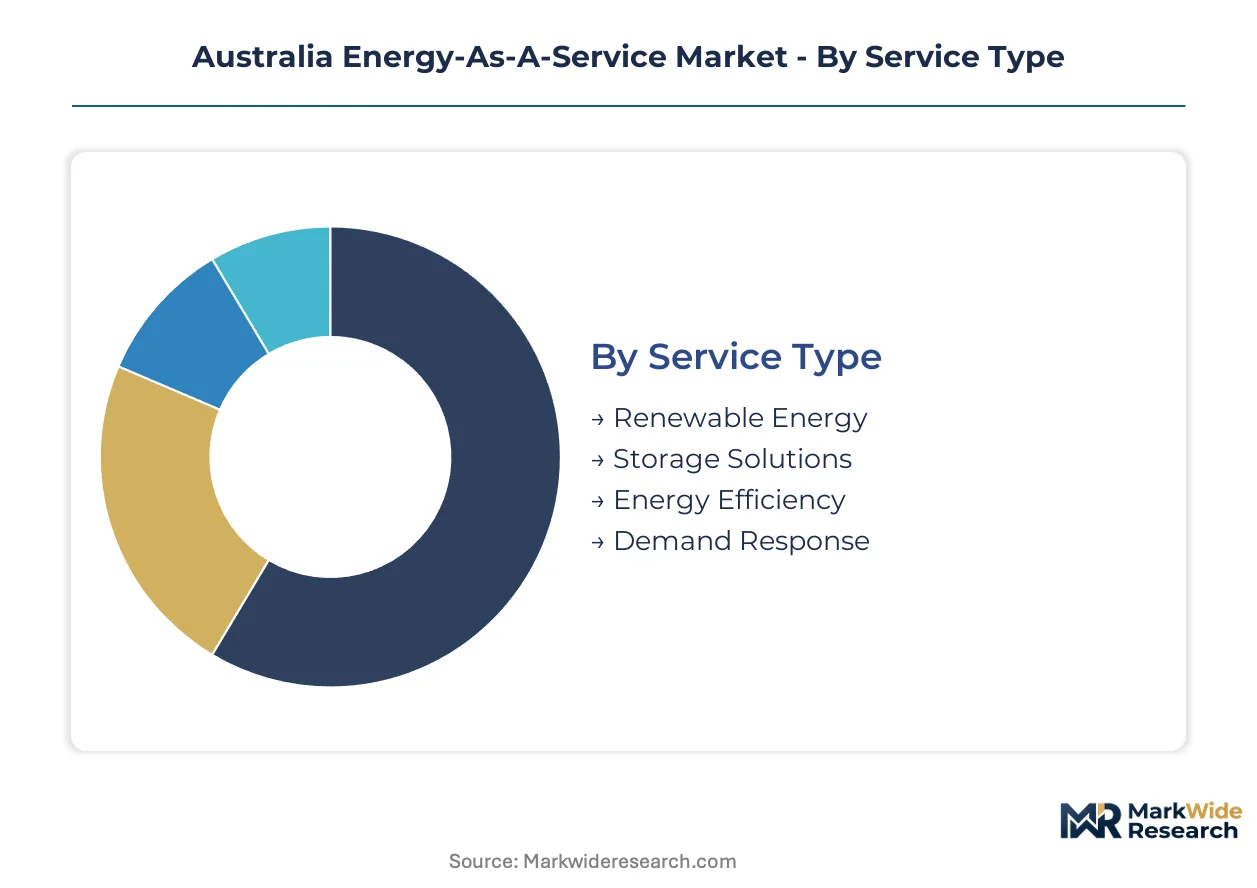
EaaS procurement patterns diverge sharply across service categories and customer profiles. Contract structures, performance guarantees, and asset ownership models vary by segment, reshaping provider economics and competitive positioning.
Service Type:
Channel strategy bifurcates between asset-heavy generation contracts and software-driven optimization services, with distinct sales cycles and margin profiles for each pathway.
- Renewable Energy:Solar and wind generation assets delivered through power purchase agreements with guaranteed production levels. Mining operations in Western Australia and Queensland anchor procurement volume, driven by Safeguard Mechanism compliance deadlines and grid isolation requirements.
- Storage Solutions:Battery energy storage systems providing peak shaving, backup power, and wholesale market arbitrage. Data centers in Sydney and Melbourne drive deployment concentration, responding to Australian Energy Market Operator frequency control ancillary service reforms that monetize behind-the-meter flexibility.
- Energy Efficiency:Lighting retrofits, HVAC optimization, and building envelope improvements contracted on savings-guarantee terms.
- Demand Response:Load curtailment services aggregating commercial and industrial flexibility for wholesale market participation.
By volume, Renewable Energy leads. By growth pace, Demand Response is climbing the fastest.
Industry Vertical:
Cost tier segmentation separates capital-intensive heavy industry from margin-sensitive commercial services, with contract duration and performance metrics calibrated to each vertical's cash flow profile.
- Manufacturing:Continuous process loads requiring high reliability and power quality. Smelters and food processing facilities in Victoria and New South Wales concentrate demand, where network constraint events and escalating network use of system charges make onsite firming economically compelling.
- Healthcare:Critical facility infrastructure with zero-tolerance outage requirements. Hospital networks across metropolitan Australia prioritize microgrid resilience and emergency power guarantees over marginal cost optimization.
- Retail:Distributed store portfolios with standardized energy profiles enabling scalable platform deployment.
- Telecommunications:Remote tower sites and data centers with 24/7 baseload requirements.
Manufacturing commands the largest contract value per site. Healthcare shows the steepest contract growth rate.
Installation:
Application architecture determines asset location relative to customer load, with implications for grid connection complexity, regulatory jurisdiction, and revenue stack composition.
- Onsite:Behind-the-meter assets physically colocated with customer facilities. Industrial parks in New South Wales and Victoria dominate deployment, where Australian Energy Regulator connection standards and distribution network service provider approvals govern commissioning timelines.
- Offsite:Remote generation or storage assets delivering energy through wheeling arrangements or virtual net metering. Corporate renewable energy buyers with distributed operations favor this model for portfolio-scale procurement without site-by-site complexity.
- Hybrid:Combined onsite and offsite assets optimizing across multiple value streams.
- Remote:Fully off-grid systems serving isolated facilities without network connection.
Onsite installations dominate contracted megawatts. Hybrid configurations are expanding most quickly as customers seek to optimize across retail and wholesale market exposures.
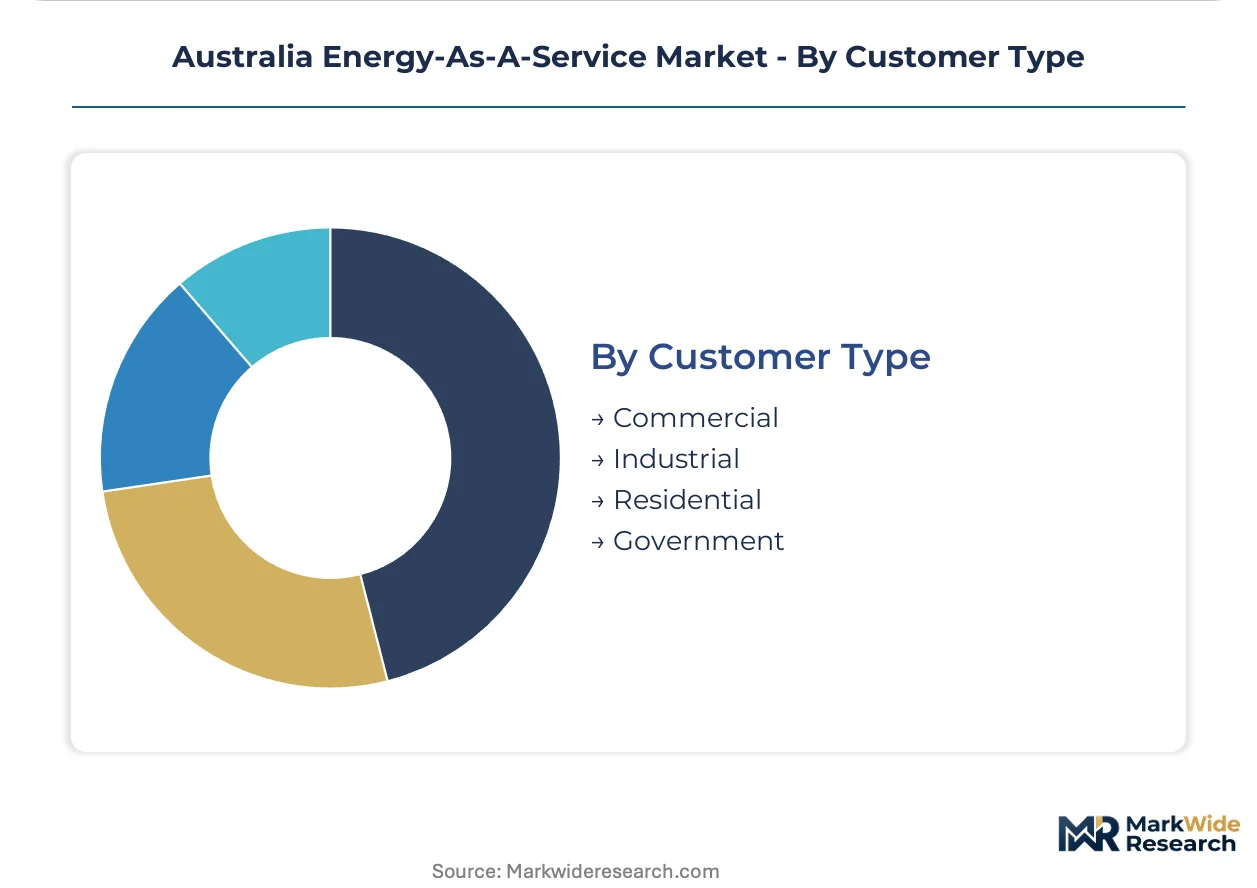
Customer Type:
Maturity gradients separate sophisticated energy buyers with dedicated procurement teams from price-sensitive segments requiring education and risk mitigation.
- Commercial:Office buildings, retail centers, and hospitality assets with predictable load profiles. Property funds in Sydney and Melbourne CBDs are consolidating procurement at portfolio level, mandating centralized EaaS contracts across multiple assets under single performance guarantees.
- Industrial:Heavy manufacturing and resource extraction with complex power quality requirements. Mining operations in Queensland and Western Australia represent underpenetrated opportunity for providers with industrial microgrid expertise.
- Residential:Single-family and multi-unit dwellings accessing EaaS through community solar or virtual power plant aggregation.
- Government:Public buildings, defense facilities, and infrastructure assets with mandated sustainability targets.
Industrial customers generate the highest revenue per contract. Commercial portfolios are gaining share fastest as property funds centralize energy decision authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provider capability clusters in New South Wales and Victoria, where network constraint events and commercial electricity cost pressures concentrate procurement activity. The Australian Energy Market Operator's grid modernization mandates reshape competitive positioning across state boundaries.
New South Wales
Data center operators and cold storage facilities drive storage-plus-solar procurement in Sydney and surrounding industrial corridors. The Australian Energy Regulator's five-minute settlement implementation compresses decision timelines for commercial load centers. Property funds in the Sydney CBD negotiate master service agreements covering multiple towers under unified performance guarantees.
Victoria
Manufacturing and food processing facilities anchor demand response aggregation, responding to frequency control ancillary service reforms. The Clean Energy Finance Corporation's concessional debt programs reduce capital barriers for industrial efficiency retrofits. Melbourne's commercial building portfolios centralize energy procurement decisions at fund level, displacing site-level facility manager discretion.
Queensland
Mining operations in Gladstone and Townsville present underpenetrated opportunity for heavy industrial microgrid providers. The Safeguard Mechanism reforms channel smelting and resource extraction toward contracted decarbonization pathways with guaranteed carbon outcomes. Retrofit compliance curves steepen as existing microgrids adapt to synchronous condenser and grid-forming inverter specifications.
Western Australia
Remote mining camps and isolated industrial facilities drive off-grid and hybrid system deployment outside the National Electricity Market. The Australian Energy Market Commission's distributed energy resource standards govern connection and dispatch obligations for behind-the-meter assets. Pilbara iron ore operations retrofit existing generation infrastructure to meet revised fault ride-through requirements.
South Australia
Virtual power plant aggregation platforms converge residential battery fleets with commercial demand response capabilities. The state's high renewable penetration and grid stability challenges create premium value for firming services. Adelaide metropolitan commercial load centers participate in wholesale market arbitrage through automated battery dispatch against real-time price signals.
Australia Energy-As-A-Service Market Competitive Environment
Concentration sits with integrated energy majors possessing balance sheet capacity for asset-heavy performance contracts. The vendor base spans three tiers: global industrial conglomerates with microgrid and digital energy stacks, European utilities specializing in distributed solar-plus-storage, and North American efficiency specialists with building automation expertise. Strategic moves center on portfolio diversification into adjacent service categories and geographic expansion into underpenetrated industrial load centers.
Within the integrated industrial tier, Schneider Electric and Siemens occupy positions combining microgrid hardware with predictive analytics platforms. ENGIE exemplifies the European utility archetype competing through distributed renewable and storage offerings. Johnson Controls represents the building automation specialist segment repositioning software modules within broader EaaS structures.
| Leading Market Players |
|---|
| Schneider Electric |
| ENGIE |
| General Electric |
| Edison International |
| Enertika |
| Enel X |
| Ameresco |
| Johnson Controls |
| Siemens |
| Others |
Value Chain & Pricing Dynamics
The Australian Energy Regulator's technical standards and connection approval protocols gate both supplier qualification and contract pricing tiers simultaneously. Providers meeting synchronous condenser and grid-forming inverter specifications command performance premiums, while those lacking certification face margin compression from extended commissioning timelines.
Pricing Analysis
The Australian Energy Market Commission's evolving distributed energy resource standards dictate the pricing tier structure across the EaaS landscape. Three-tier pricing separates premium guaranteed-performance contracts from standard service-level agreements and economy monitoring-only packages. Price differentiation rests on certification grade against AEMO frequency control standards and volume scale of contracted megawatts. Cost compression in the standard tier is intensifying because lithium supply bottlenecks squeeze battery procurement economics. Data center operators show least price sensitivity due to zero-tolerance reliability requirements, while retail property portfolios exhibit highest sensitivity as energy costs compete with occupancy margins.
Supply Chain Analysis
Inventory lead times for lithium-ion battery systems stretch 12-24 months as Australian providers buffer against grid connection queue uncertainty. Supply concentrates in China for cell manufacturing, South Korea for battery management systems, and Japan for power electronics components. Raw material dependencies center on lithium carbonate, cobalt sulfate, and refined copper busbar. Single-source vulnerability in Chinese upstream processing exposes providers to input cost volatility outside hedging capacity. Distribution runs through EPC contractors with distribution network service provider relationships, who bundle hardware procurement with installation and commissioning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia Energy-As-A-Service Market functions as a service-attach opportunity where predictive analytics and automated dispatch layers expand faster than underlying generation hardware. Recurring software revenue from digital energy management platforms outpaces contracted equipment margins.
For Market Incumbents: Fortify positions by deepening backward integration into battery storage supply chains and securing synchronous condenser certification ahead of AEMO compliance deadlines. Grid-forming inverter capability scarcity threatens to displace non-compliant providers from Queensland mining contracts. Channel control through exclusive EPC partnerships represents the critical defensive lever against European utility entrants. For New Entrants and Emerging Players: Demand response aggregation for cold storage facilities presents a service-layer gap where incumbents under-serve with generic building automation tools. Queensland industrial load centers in Gladstone and Townsville offer the most penetrable geography given underdeveloped microgrid expertise among established providers. A software-first go-to-market angle targeting automated HVAC dispatch against five-minute settlement price signals bypasses capital-heavy balance sheet requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across virtual power plant aggregation as software platforms scale without incremental asset deployment. Long-term viability favors providers stacking wholesale market revenues across customer classes rather than single-site generation contracts. Acquisition targets should display portfolio-level procurement relationships with property funds. The signal to watch is CEFC concessional debt uptake rates as an indicator of which providers can sustain asset-heavy growth without equity dilution.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | Long-term offtake contracts with mining operations in Western Australia anchor revenue visibility against NEM price volatility. |
| Virtual Power Plant Platform Development | Aggregation software converging residential battery fleets with commercial demand response stacks wholesale market revenues. |
| Backward Integration into Storage | In-house battery system integration reduces exposure to Chinese lithium supply concentration and procurement delays. |
| Grid-Forming Inverter Certification | AEMO compliance for synchronous condenser capability gates participation in Queensland industrial microgrid tenders. |
| Predictive Analytics Acquisition | AI-driven dispatch software targets five-minute settlement arbitrage opportunities in New South Wales data center load centers. |
Study Parameters
The analysis maps renewable energy supply, storage solutions, energy efficiency retrofits, and demand response aggregation, each validated through utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary fieldwork combined structured interviews with secondary validation against AEMO market reports, AER regulatory filings, Clean Energy Finance Corporation disclosure statements, and project development databases. Bottom-up contract aggregation across service categories triangulates against top-down market sizing from regulatory capacity forecasts.
Consistency checks validated volume and value outputs against external benchmarks including AEMO integrated system plan projections and CEFC investment deployment data. The analytical framework segments by service type, customer vertical, installation architecture, and state regulatory jurisdiction across the projection horizon. CAGRs derive from contracted pipeline analysis and historical commissioning velocity. Forecast inputs incorporate Safeguard Mechanism compliance deadlines and five-minute settlement rule implementation timelines.
Underlying assumptions cover lithium cost trajectories, grid connection approval timelines, and frequency control ancillary service market depth, with deviation risk concentrated in wholesale price volatility and Chinese supply chain disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Connected Energy Market
Energy Management
Remote Renewable Management Systems Market
Energy Management
Asia-Pacific Exhaust Heat Recovery System Market
Energy Management
Europe Energy Management Systems Market
Energy Management
APAC Energy Management Systems (EMS) Market
Energy Management
APAC Building Energy Management Systems Market
Energy Management
South Korea Residential Heat Pump Market
Energy Management
Energy Harvesting System Market
Energy Management
Thermostat Market
Energy Management
Power SCADA Market
Energy Management
Heat Meter Market
Energy Management
Energy Security Market
Energy Management
Demand Response Management System Market
Energy Management
Smart Energy Solutions Market
Energy Management
Solar Panel Monitoring System Market
Energy Management
Electric Service Companies (Escos) Market