
 Canada Electric Vehicle Battery Electrolyte Market | 2026-2036
Canada Electric Vehicle Battery Electrolyte Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Electric Vehicle Battery Electrolyte Market Insights
Canadian electrolyte production capacity is rebalancing toward domestic blending operations to reduce import dependence on Asian suppliers. BASF SE leverages its global materials science platform to position specialty additive packages for cold-climate performance requirements. LG Chem Ltd. anchors its North American electrolyte supply chain through integrated relationships with Ontario-based cell manufacturers. Mitsubishi Chemical Group competes on lithium hexafluorophosphate purity grades that meet stringent OEM qualification protocols.
Canada electric vehicle battery electrolyte comprises lithium salts dissolved in organic carbonate solvents, typically operating within a viscosity range of 3-10 mPa·s and conductivity thresholds above 7 mS/cm at 25°C, functioning as the ionic transport medium between anode and cathode during charge-discharge cycles. Lithium-ion electrolyte formulations dominate current commercial deployment, though solid-state chemistry segments are attracting R&D capital as manufacturers pursue energy density targets above 400 Wh/kg. Passenger vehicle applications command the largest volume share, while commercial vehicle segments present higher per-unit electrolyte requirements due to larger pack capacities and extended cycle life specifications.
Health Canada and Environment and Climate Change Canada jointly oversee chemical substance assessments under the Canadian Environmental Protection Act, influencing electrolyte solvent registration and handling protocols for domestic blending facilities. Transport Canada's Motor Vehicle Safety Standards and the federal zero-emission vehicle sales mandate shape OEM procurement timelines and qualification requirements for electrolyte suppliers. Stakeholders must monitor evolving battery passport traceability rules and provincial critical minerals processing incentives that could redirect supply chain investment toward Quebec and Ontario refining corridors.
Market Dynamics
Domestic blending capacity expansion is reshaping supply chain architecture as Canadian cell manufacturers reduce dependence on Asian electrolyte imports through Ontario-based production facilities.
Growth Catalysts
- Federal zero-emission vehicle mandate:Ottawa's sales targets force OEMs to accelerate local battery supply chain qualification timelines, pulling forward electrolyte procurement commitments from domestic blenders.
- Passenger vehicle OEM expansion:Windsor and Oakville assembly clusters are scaling lithium-ion cell production, creating anchored demand for high-purity electrolyte formulations within 200-kilometer distribution radius.
- Quebec critical minerals processing:Provincial refining incentives are attracting lithium salt purification investments that feed directly into Ontario electrolyte blending operations.
Market Restraints
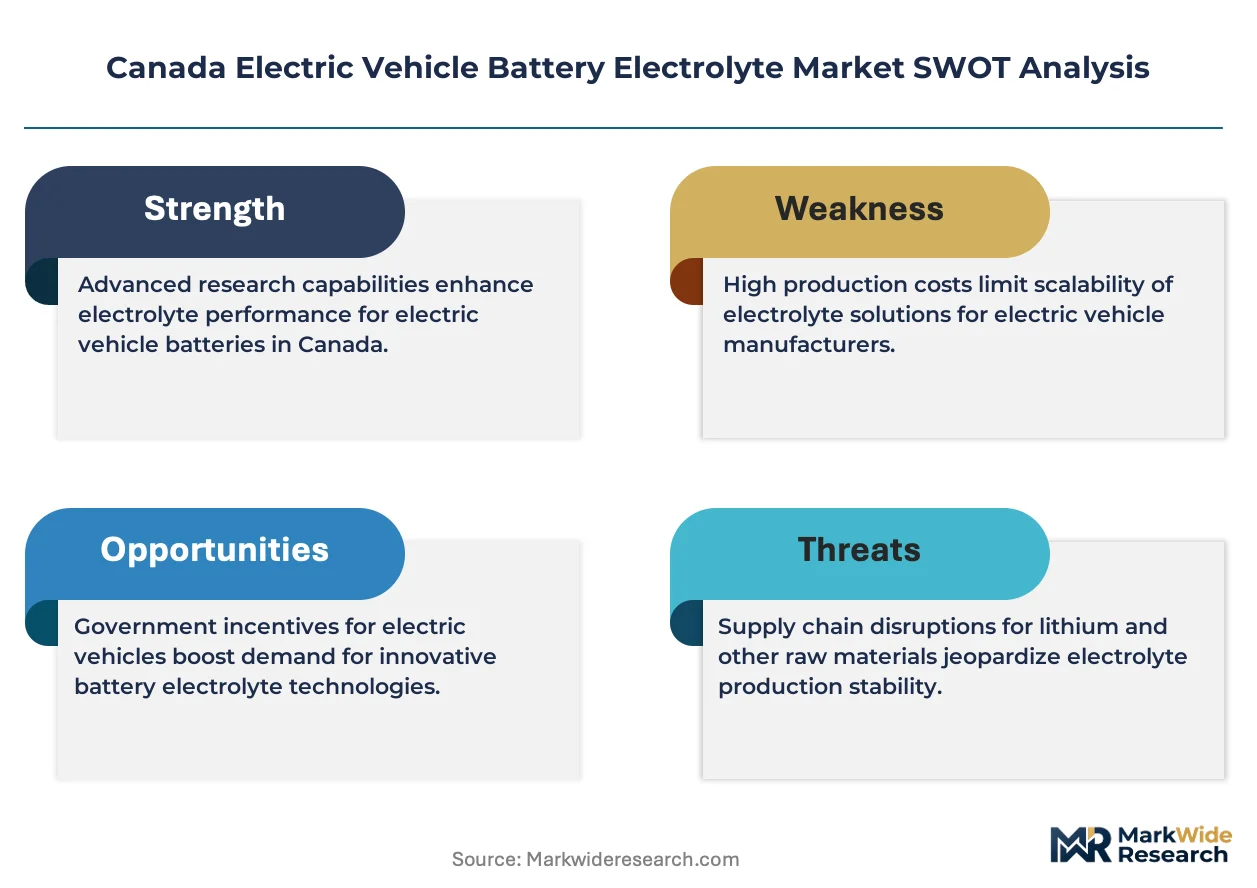
- Asian supply concentration:Over 70% of global lithium hexafluorophosphate production remains concentrated in Chinese and South Korean chemical complexes, exposing Canadian blenders to input cost volatility and shipping bottlenecks.
- Cold-climate performance threshold:Standard carbonate electrolyte formulations face viscosity degradation below -20°C, requiring costly additive packages that compress blending margins.
- Canadian Environmental Protection Act registration:Health Canada solvent assessment timelines extend 18-24 months for new organic carbonate blends, delaying product commercialization.
Strategic Opportunities
- Western Canada cell manufacturing:British Columbia's clean electricity grid and port access position Vancouver corridor for electrolyte distribution to Pacific Northwest battery investments.
- Solid-state chemistry convergence:Sulfide and oxide solid electrolyte R&D programs at Canadian national laboratories are creating intellectual property licensing pathways for domestic specialty chemical firms.
- Quebec hydro-powered refining:Low-carbon electricity tariffs are attracting lithium salt crystallization investments that could integrate backward into captive electrolyte precursor supply.
Industry Challenges
- Electrochemical engineer scarcity:Ontario and Quebec universities produce insufficient graduates with lithium-ion formulation expertise, forcing blenders to recruit from Asian battery clusters at premium compensation.
- OEM qualification timeline compression:Cell manufacturers demand 12-month electrolyte validation cycles that conflict with 24-month regulatory registration requirements under Transport Canada safety protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Electric Vehicle Battery Electrolyte Market |
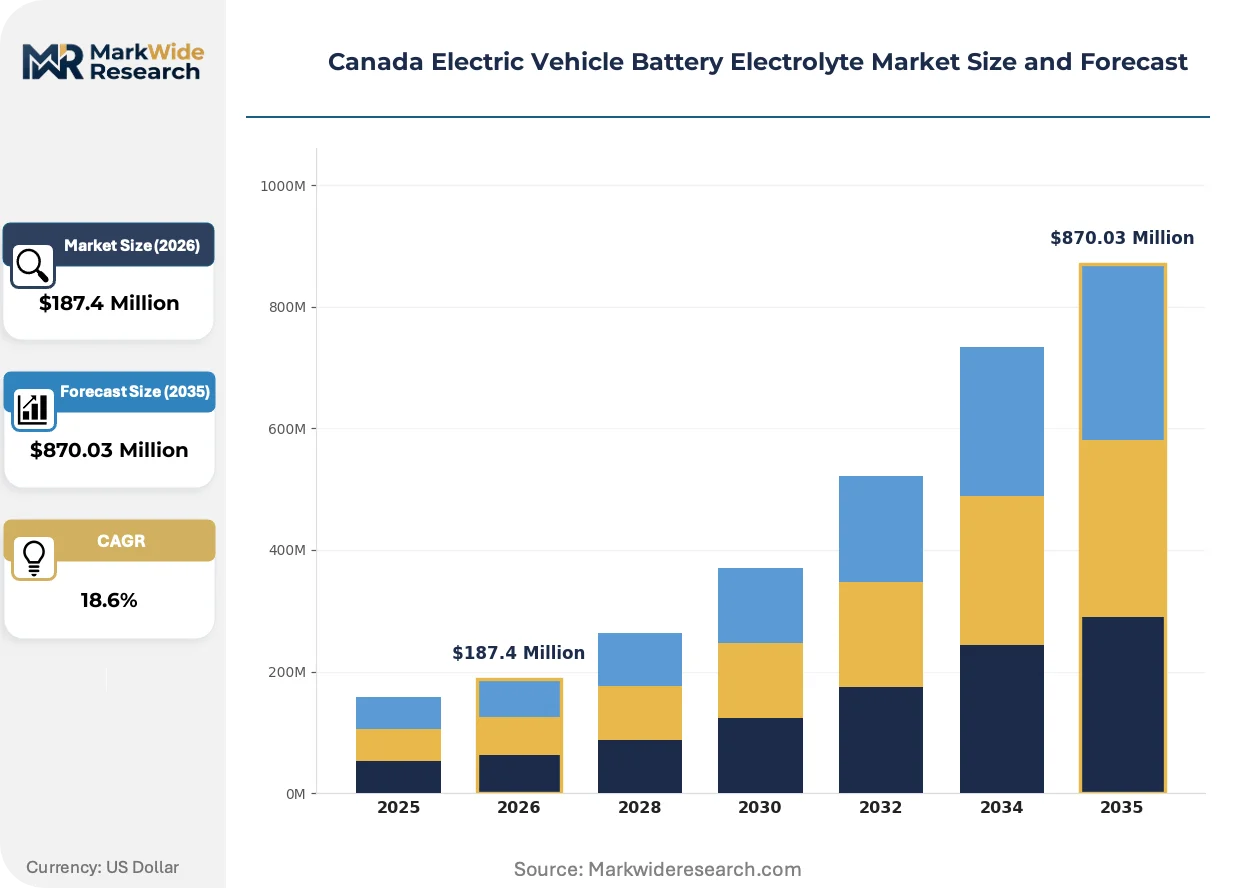
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Electrolyte Type: Lithium-ion, Solid-state, Gel, Aqueous Battery Chemistry: LFP, NMC, NCA, LTO Application: Passenger Vehicles, Commercial Vehicles, E-Bikes, E-Scooters Distribution Channel: OEMs, Retail, Online, Distributors |
| Companies Covered | Mitsubishi Chemical Group, 3M, Umicore N.V, Solvay SA, BASF SE, Asahi Kasei Corporation, Cabot Corporation, Clariant AG, LG Chem Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Electric Vehicle Battery Electrolyte Market Trends and Innovations
Electrolyte chemistry is pivoting toward multi-functional additive systems that simultaneously address thermal stability, cycle life extension, and fast-charge compatibility in cold-climate operating conditions.
Fluorinated ether co-solvents are penetrating high-voltage cathode formulations for nickel-rich lithium-ion cells operating above 4.3V. Canadian cell manufacturers serving premium passenger vehicle OEMs are qualifying these blends for 800V architectures. This chemistry is converging with silicon-anode electrolyte requirements as manufacturers pursue energy density targets that demand stable solid-electrolyte interphase formation.
Environment and Climate Change Canada is tightening volatile organic compound emission thresholds for electrolyte solvent handling facilities under amended Canadian Environmental Protection Act regulations. Blending operations in Ontario's manufacturing corridor must retrofit vapor recovery systems or face production limitations. Commercial vehicle battery suppliers with larger electrolyte throughput volumes are absorbing compliance costs faster than emerging cell startups.
Fleet operators and commercial vehicle OEMs are consolidating electrolyte procurement through direct long-term supply agreements with blenders, bypassing traditional chemical distributor networks. This channel compression concentrates volume commitments among three Ontario-based suppliers with Transport Canada certification. The St. Catharines-Niagara battery corridor exhibits the most pronounced disintermediation as municipal transit electrification programs demand transparent chemical sourcing for ESG reporting.
Canada Electric Vehicle Battery Electrolyte Market Segmentation
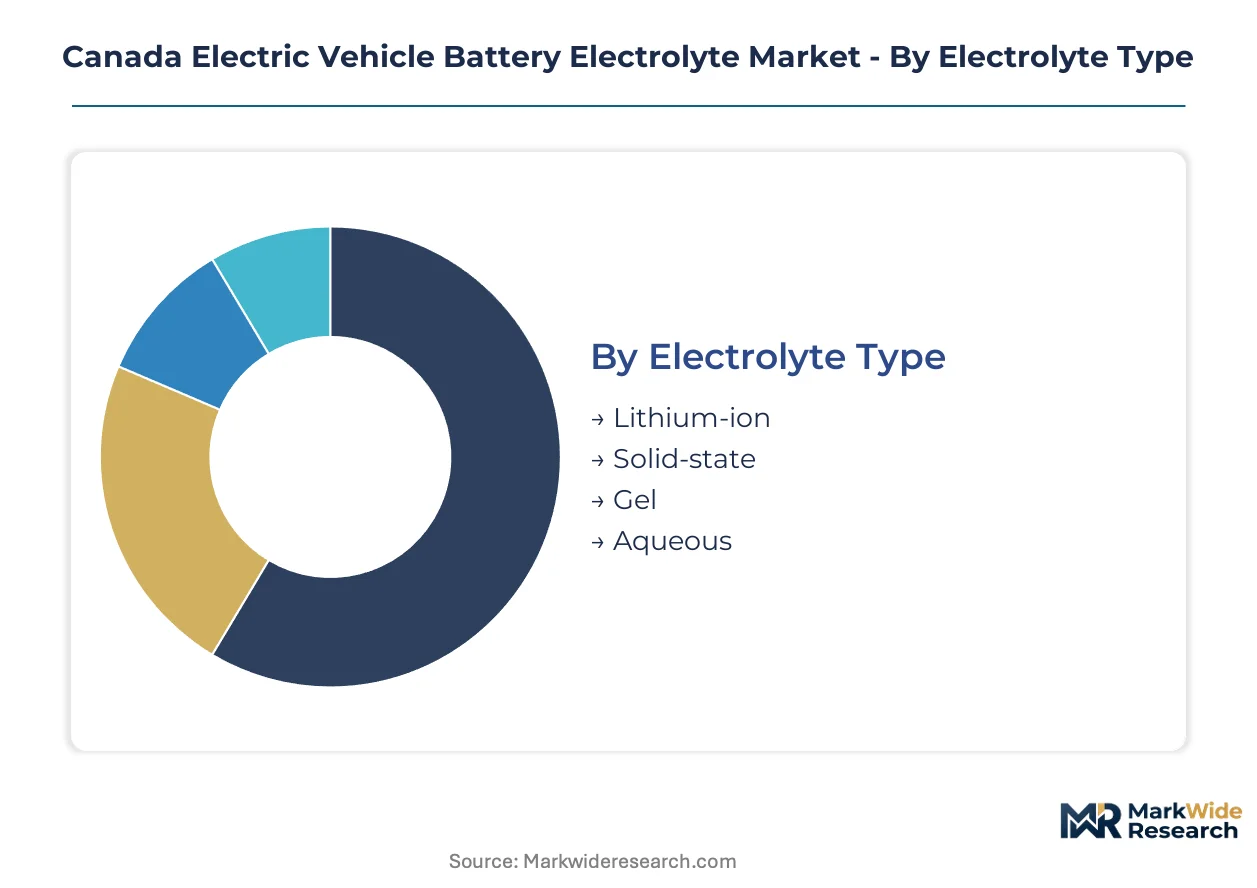
Electrolyte procurement patterns diverge sharply between high-volume passenger vehicle contracts and specialized commercial formulations. Cell manufacturers segment their supplier base by chemistry compatibility, cold-climate performance thresholds, and OEM qualification status.
Electrolyte Type:
Volume deployment concentrates in liquid formulations, while premium pricing attaches to next-generation solid-state precursors.
- Lithium-ion:Carbonate solvent systems with lithium hexafluorophosphate salts dominate Ontario cell manufacturing. Windsor and Oakville assembly clusters specify these formulations for their established supply chain qualification and -20°C operational thresholds.
- Solid-state:Sulfide and oxide electrolyte R&D programs at Canadian national laboratories are creating intellectual property licensing pathways. Quebec hydro-powered refining corridors attract pilot-scale investments for sulfide precursor purification.
- Gel:Polymer matrix systems serve niche e-mobility applications requiring leak resistance.
- Aqueous:Water-based electrolytes occupy safety-critical segments with limited energy density requirements.
Mature deployment sits with lithium-ion carbonate systems. Newer deployment is concentrated in solid-state chemistry programs.
Battery Chemistry:
OEM procurement splits between cost-optimized iron phosphate and energy-dense nickel formulations.
- LFP:Lithium iron phosphate cells command volume share in municipal transit electrification programs. Toronto and Vancouver fleet operators specify LFP packs for their thermal stability and extended cycle life under stop-start duty cycles.
- NMC:Nickel-manganese-cobalt formulations serve premium passenger vehicle OEMs pursuing 800V architectures. Health Canada chemical substance assessments under the Canadian Environmental Protection Act influence cobalt sourcing transparency requirements.
- NCA:Nickel-cobalt-aluminum chemistry occupies high-performance segments with stringent energy density specifications.
- LTO:Lithium titanate anode systems target commercial vehicle fast-charge applications.
Cost-sensitive procurement clusters around LFP. Performance-premium positioning attaches to NMC.
Application:
Pack capacity scales determine electrolyte volume requirements and formulation complexity.
- Passenger Vehicles:Light-duty OEM contracts anchor Ontario electrolyte blending capacity. St. Catharines-Niagara corridor suppliers qualify formulations for 60-100 kWh packs with 10-year cycle life warranties.
- Commercial Vehicles:Transit bus and medium-duty truck segments demand 200+ kWh configurations with extended thermal management. British Columbia municipal electrification programs specify commercial-grade electrolyte throughput for ESG traceability reporting.
- E-Bikes:Low-voltage formulations occupy price-sensitive consumer segments.
- E-Scooters:Compact cell designs prioritize energy density over cycle life.
High-volume deployment concentrates in passenger vehicles. Steepest expansion trajectory appears in commercial vehicle electrification.
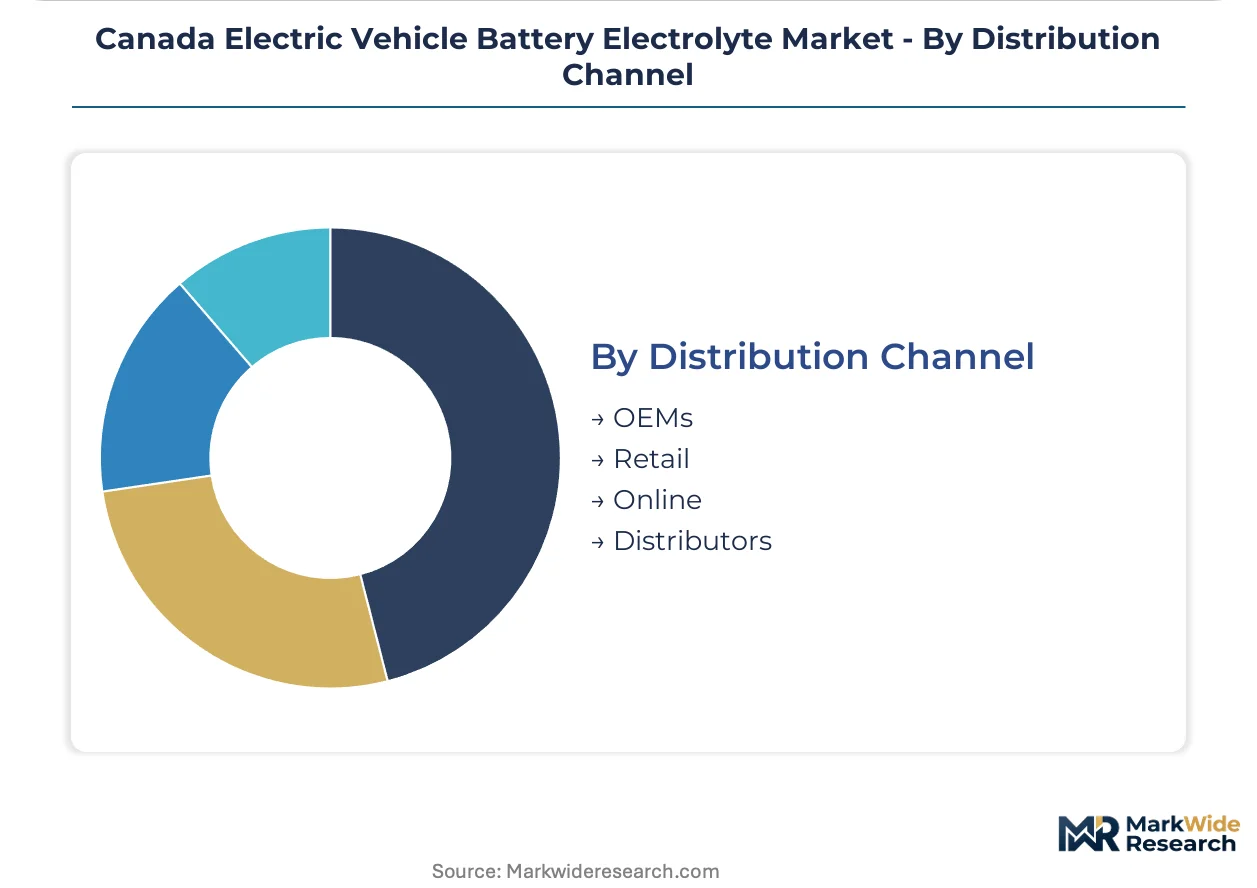
Distribution Channel:
Channel structure compresses as cell manufacturers consolidate procurement relationships.
- OEMs:Direct supply agreements dominate Canadian cell manufacturing procurement. Three Ontario-based blenders with Transport Canada certification capture consolidated volume commitments from Windsor assembly clusters.
- Distributors:Traditional chemical distribution networks face disintermediation as fleet operators seek transparent sourcing. Municipal transit electrification programs in the St. Catharines-Niagara corridor bypass distributors for ESG reporting compliance.
- Retail:Aftermarket segments serve replacement battery markets.
- Online:Digital procurement channels occupy small-scale and specialty formulation segments.
Established procurement runs through OEM direct agreements. Emerging volume is concentrating in distributor-bypass arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's lithium salt refining corridor anchors Canadian electrolyte production geography. Quebec's hydroelectric grid attracts precursor purification investments. British Columbia's Pacific port infrastructure positions Vancouver for distribution to battery manufacturing clusters.
Ontario
Windsor and Oakville assembly clusters drive anchored demand for high-purity electrolyte formulations. Transport Canada's Motor Vehicle Safety Standards shape OEM qualification timelines for domestic blenders. The St. Catharines-Niagara corridor concentrates three certified suppliers serving passenger vehicle cell manufacturers within 200-kilometer distribution radius.
Quebec
Provincial critical minerals processing incentives attract lithium hexafluorophosphate crystallization investments. Environment and Climate Change Canada oversees solvent emission thresholds for blending facilities under Canadian Environmental Protection Act amendments. Montreal and Bécancour refining corridors integrate backward into captive electrolyte precursor supply chains.
British Columbia
Clean electricity tariffs and Pacific port access position Vancouver for electrolyte distribution to Pacific Northwest battery investments. Health Canada chemical substance assessments influence solvent registration protocols for coastal blending operations. Metro Vancouver's industrial zones attract pilot-scale solid-state electrolyte R&D programs leveraging low-carbon power.
Alberta
Potential lithium extraction from oilfield brines creates feedstock proximity for future electrolyte salt production. The province's petrochemical infrastructure offers organic carbonate solvent manufacturing capabilities. Calgary-based chemical engineering firms explore electrolyte additive formulation partnerships with Ontario cell manufacturers.
Canada Electric Vehicle Battery Electrolyte Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solid-state chemistry licensing and cold-climate additive specialization. The supplier base concentrates among integrated chemical conglomerates with materials science platforms and regional blenders with Transport Canada certification. Three archetypes dominate: global electrolyte formulators with multi-continent R&D networks, Asian lithium salt suppliers with North American distribution partnerships, and domestic blending specialists with OEM qualification status. Competitive moves center on backward integration into lithium salt purification and capacity expansion within 300 kilometers of Ontario cell manufacturing clusters.
Within the global formulator tier, Mitsubishi Chemical Group and BASF SE exemplify materials science platforms positioning specialty additive packages for stringent OEM protocols. LG Chem Ltd. anchors the Asian supplier archetype through integrated relationships with Ontario-based cell manufacturers. These three companies represent contrasting strategic positions: Japanese precision chemistry, German industrial diversification, and Korean battery materials integration.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group |
| 3M |
| Umicore N.V |
| Solvay SA |
| BASF SE |
| Asahi Kasei Corporation |
| Cabot Corporation |
| Clariant AG |
| LG Chem Ltd. |
| Others |
Pricing and Supply Chain Analysis
Lithium hexafluorophosphate feedstock costs cascade through carbonate solvent blending operations into three distinct procurement tiers serving Ontario cell manufacturers, Windsor fleet operators, and emerging solid-state pilot programs.
Pricing Analysis
Warranty bundling separates qualified electrolyte supply from commodity carbonate blends, with Transport Canada-certified Ontario blenders commanding premium positioning through 10-year cycle life guarantees. Price differentiation rests on cold-climate additive packages and OEM qualification status, with standard formulations facing cost compression from Asian import competition. Municipal transit procurement in the St. Catharines-Niagara corridor shows lowest price sensitivity due to ESG traceability mandates, while emerging cell startups absorb margin pressure from extended Health Canada registration timelines.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and South Korean lithium salt crystallization complexes that feed over 70% of global hexafluorophosphate production. Canadian blending operations draw from these Asian precursor sources while domesticating carbonate solvent production through Alberta petrochemical infrastructure. Tariff exposure on purified lithium salts constitutes the dominant structural risk, with distribution running through direct OEM agreements that bypass traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's electric vehicle battery electrolyte sector sits at a liquid-to-solid chemistry transition point, with sulfide and oxide solid-state formulations displacing established carbonate systems in next-generation cell architectures.
For Market Incumbents: Deploy backward integration into Quebec lithium salt crystallization to secure precursor supply against Asian concentration risk. BASF SE and Mitsubishi Chemical Group should accelerate cold-climate additive R&D to defend margin position from emerging domestic blenders with Transport Canada certification. Capacity expansion within 200 kilometers of Windsor assembly clusters anchors volume commitments.
For New Entrants and Emerging Players: Launch via direct fleet supply agreements targeting British Columbia municipal electrification programs seeking ESG-transparent sourcing. Western Canada cell manufacturing presents the most penetrable geography, with Vancouver corridor distribution leveraging Pacific port access. Solid-state electrolyte licensing from Canadian national laboratories offers differentiation against established carbonate blenders.
For Investors and Strategic Acquirers: Quebec hydro-powered refining investments reaching pilot-scale crystallization is the leading indicator that captive precursor supply will reshape competitive economics. Acquisition targets should concentrate on Ontario-based blenders with OEM qualification status and existing Transport Canada certification. Long-term viability favors integrated operations spanning salt purification through formulated electrolyte delivery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Salt Purification | Quebec hydroelectric tariffs enable low-carbon crystallization investments that reduce Asian precursor dependence. |
| Cold-Climate Additive Package Development | Health Canada registration for -30°C formulations opens premium procurement from Windsor passenger vehicle OEMs. |
| Direct Fleet Supply Agreement Consolidation | St. Catharines-Niagara municipal transit programs bypass distributors for transparent ESG reporting compliance. |
| Solid-State Electrolyte Licensing Program | Canadian national laboratory R&D creates intellectual property pathways for sulfide precursor commercialization. |
| Ontario Blending Capacity Expansion | Transport Canada certification within 200 kilometers of Oakville assembly clusters captures anchored OEM demand. |
Research Methodology
Independent corroboration across electrolyte procurement leads at Ontario cell manufacturers, technical directors at Quebec refining operations, and regulatory affairs specialists at Health Canada underwrites the qualitative findings. Primary fieldwork engaged blending plant managers, OEM platform engineers at Windsor assembly clusters, and distribution channel partners serving municipal fleet operators. Secondary validation drew from Environment and Climate Change Canada emission filings, Transport Canada safety standard disclosures, and provincial critical minerals incentive program documentation. Bottom-up volume estimates triangulated against top-down market sizing across electrolyte type, battery chemistry, and application segments.
Comparable-period anchoring to historical lithium-ion deployment curves informed the projection framework across the analysis window. Segmentation modeling captured electrolyte formulation tiers, battery chemistry compatibility, pack capacity scaling, and regional production cluster proximity. CAGRs derived from electrolyte throughput per kWh benchmarks, OEM electrification timeline acceleration, and solid-state chemistry penetration assumptions. Forecast inputs incorporated federal zero-emission vehicle mandate compliance trajectories and Quebec hydroelectric capacity expansion for precursor refining.
Asian supply disruption, extended Health Canada solvent registration timelines, and solid-state chemistry substitution acceleration are the dominant revision risks that could compress or extend forecast outcomes. Forecasts reflect documented assumptions about OEM qualification cycle stability and provincial incentive program continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Europe Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market
EV Batteries
South America Hybrid Electric Vehicle Battery Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
Electric Vehicle Battery Thermal Management Systems Market
EV Batteries
Japan EV Battery Pack Market
EV Batteries
Asia-Pacific Electric Vehicle Solid State Battery Market
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
Europe LFP Battery Pack Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
Germany EV Battery Pack Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Italy Electric Vehicle Battery Electrolyte Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market