
 Germany Fuel Cell Market | 2026-2036
Germany Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Fuel Cell Market Foresight
A shortage of certified hydrogen systems engineers is redrawing competitive boundaries across the Germany fuel cell sector. Proton Motor Fuel Cell GmbH leverages its Bavarian production base to dominate German-made proton exchange membrane stacks for bus and rail applications. SFC Energy AG specializes in portable and off-grid fuel cell systems, sustaining its position in defense and industrial remote power. ElringKlinger AG anchors the supply chain through precision fuel cell stack components and bipolar plate manufacturing.
A fuel cell converts chemical energy from hydrogen or hydrogen-rich fuels into electricity through electrochemical reactions, typically operating at efficiencies between 40 and 60 percent for electrical output with usable heat co-generation. Proton exchange membrane technology leads German deployments due to its favorable power density and cold-start performance for mobility applications. Solid oxide fuel cells command premium positioning in combined heat and power installations across commercial facilities and public institutions, where high-grade waste heat recovery improves total system economics. Stationary fuel cells occupy the dominant product category, while mobile fuel cells for heavy transport represent the fastest-expanding segment as freight operators electrify long-haul routes.
Germany's KBA enforces type-approval standards for hydrogen-powered vehicles, while the Federal Ministry for Economic Affairs and Climate Action coordinates national hydrogen strategy funding that shapes capex timelines for fleet operators. REACH and the EU's F-Gas Regulation govern material inputs and cooling system chemistries, directly affecting stack design choices and supplier qualification requirements. Stakeholders must monitor Berlin's implementation speed for hydrogen core network infrastructure and the availability of domestically produced green hydrogen to validate total cost of ownership models for fuel cell investments.
Market Dynamics
The Germany fuel cell sector is being reshaped by the tension between electrolyzer capacity buildout and the scarcity of certified hydrogen systems engineers, forcing manufacturers to compete on talent access rather than scale alone.
Growth Catalysts
- EU Alternative Fuels Infrastructure Regulation:Mandates hydrogen refueling station density along core transport corridors, compelling freight operators in North Rhine-Westphalia to accelerate fleet conversion timelines.
- Ruhr industrial cluster demand:Steel and chemical producers in Duisburg and Essen are contracting for megawatt-scale stationary fuel cells to displace natural gas in process heat applications.
- Proton exchange membrane cold-start performance:Enables year-round bus operations in Bavarian alpine regions where battery-electric range collapses below minus ten degrees Celsius.
Market Restraints
- Platinum group metal cost volatility:Stack manufacturers face margin compression when palladium and iridium prices spike, with no near-term material substitution pathway for membrane electrode assemblies.
- Electrolyzer supply concentration:German project developers depend on Nordic and Middle Eastern equipment suppliers for alkaline and PEM electrolysis systems, exposing capex schedules to shipping bottlenecks.
- F-Gas Regulation compliance friction:Cooling system chemistries containing fluorinated gases require reformulation, extending product recertification cycles by twelve to eighteen months.
Strategic Opportunities
- Port of Hamburg logistics corridor:Container handling equipment and short-sea shipping represent untapped demand for maritime-certified fuel cell powertrains.
- Combined heat and power in municipal buildings:Solid oxide fuel cells qualify for federal building energy efficiency subsidies under the National Hydrogen Strategy implementation guidelines.
- Electrolyzer-to-fuel cell vertical integration:Bavarian industrial zones enable co-location of hydrogen production and stack manufacturing, compressing logistics costs for integrated system suppliers.
Industry Challenges
- Certified hydrogen systems engineer shortage:Vocational training programs at German technical universities cannot match absorption rates by Proton Motor and ElringKlinger, inflating recruitment costs.
- KBA type-approval timeline variability:Vehicle homologation for hydrogen-powered trucks lacks standardized test protocols, creating uncertainty for fleet operators planning route electrification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Fuel Cell Market |
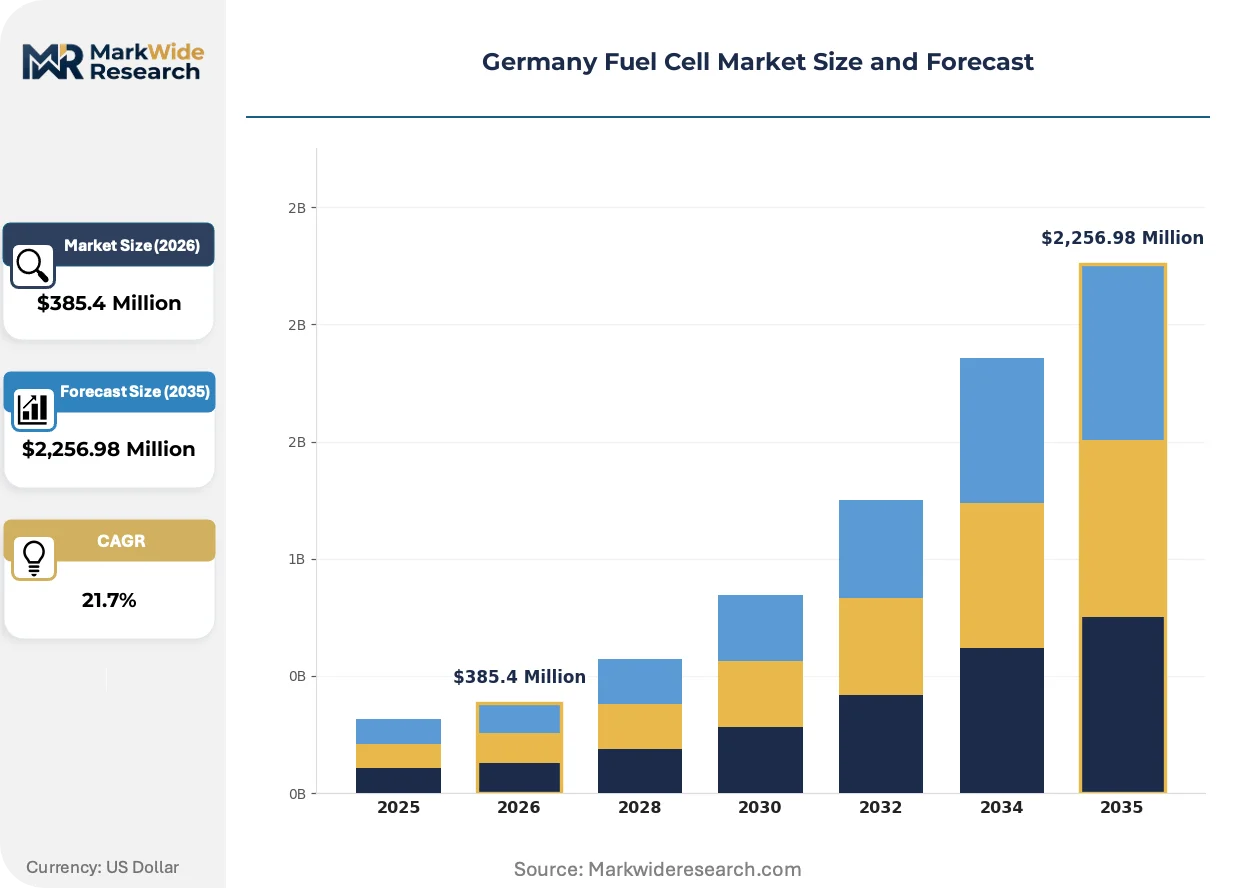
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $2,256.98 Million |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Proton Exchange Membrane, Solid Oxide, Alkaline, Phosphoric Acid, Molten Carbonate Application: Backup Power, Material Handling, Portable Power, Combined Heat and Power, Telecommunications End User: Residential Properties, Commercial Facilities, Data Centers, Warehousing Facilities, Public Institutions Product Type: Stationary Fuel Cells, Portable Fuel Cells, Mobile Fuel Cells, Micro Fuel Cells, Auxiliary Power Units |
| Companies Covered | Proton Motor Fuel Cell GmbH, Hydrogenics Corporation, SFC Energy AG, cellcentric, ElringKlinger AG, Ballard Power Systems Inc., Plug Power Inc., Bloom Energy Corporation, FuelCell Energy Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Fuel Cell Market Shifts & Advancements
Stack architecture is converging with thermal management advances, while regulatory pressure on cooling chemistries and freight operator procurement models are compressing traditional equipment supply relationships.
Solid oxide fuel cell systems operating at six hundred to one thousand degrees Celsius are displacing conventional gas turbines in combined heat and power installations across German hospital and university campuses. Municipal energy utilities in Baden-Württemberg are piloting these systems for district heating feed-in. The technology is displacing centralized cogeneration by enabling building-level energy autonomy with seventy percent total system efficiency.
Berlin's implementation of the National Hydrogen Strategy funding mechanisms is redirecting capex flows from pure electrolyzer manufacturing toward integrated hydrogen valley projects. The Federal Ministry for Economic Affairs and Climate Action ties grants to domestic green hydrogen offtake agreements. Heavy-duty fleet operators in Lower Saxony are restructuring procurement to require fuel cell vehicle suppliers to bundle hydrogen supply contracts.
Freight operators are consolidating vendor relationships from multi-source equipment purchasing toward single-source hydrogen ecosystem partnerships. Logistics providers in the Rhine-Ruhr corridor now contract directly with electrolyzer developers for dedicated hydrogen supply rather than spot market purchases. This concentration is most visible among Bavarian grocery distributors operating temperature-controlled trailer fleets on fixed routes.
Germany Fuel Cell Market Segmentation
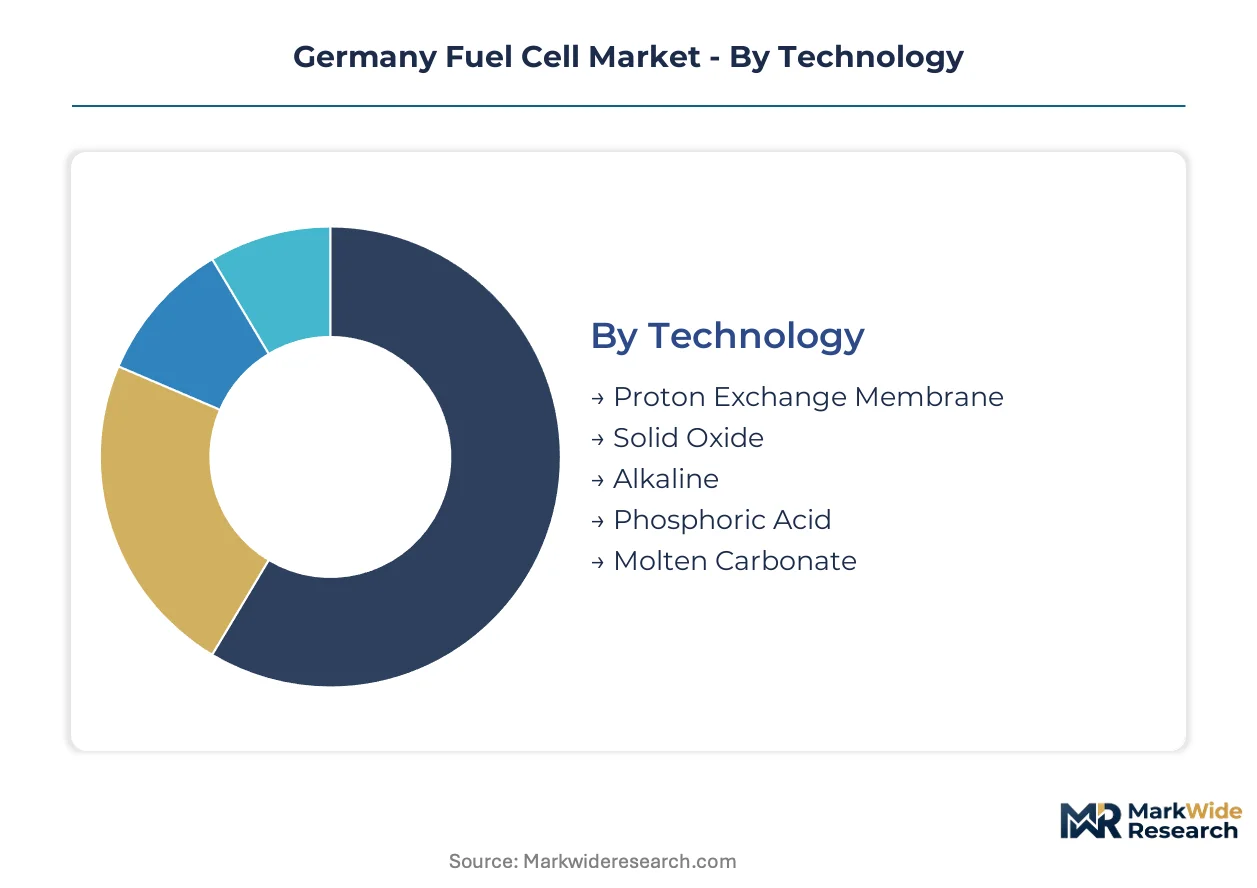
Segmentation in the Germany fuel cell market reveals how technology choices, application requirements, and end-user procurement power channel demand toward distinct supplier capabilities and certification standards. Understanding these divisions exposes where pricing leverage concentrates and which segments absorb capital fastest under national hydrogen funding programs.
Technology:
Proton exchange membrane and solid oxide systems flow through specialized industrial distributors serving mobility and stationary power channels respectively, while alkaline and phosphoric acid technologies reach buyers via electrolyzer integrators and energy service companies.
- Proton Exchange Membrane:Operates at 60-80°C with platinum catalyst-coated membranes enabling rapid cold-start below freezing. Demand concentrates in Bavarian bus fleets and North Rhine-Westphalia heavy trucking where KBA type-approval for sub-zero reliability is mandatory.
- Solid Oxide:Ceramic electrolyte systems run at 600-1000°C with combined heat and power efficiency reaching 70%. Ruhr region steel mills and municipal district heating operators in Baden-Württemberg contract directly for megawatt installations displacing gas turbines.
- Alkaline:Liquid electrolyte technology using potassium hydroxide achieves lower capital cost per kilowatt for stationary bulk power. German project developers source through Nordic equipment suppliers for industrial cluster deployments.
- Phosphoric Acid:Phosphoric acid-doped silicon carbide matrix delivers 40% electrical efficiency with 85°C waste heat. Commercial building operators in Frankfurt and Munich procure through energy performance contracting firms.
- Molten Carbonate:High-temperature carbonate salt electrolyte systems suit continuous baseload applications above one megawatt. Chemical process industries evaluate for captive power where grid stability is secondary to thermal integration.
By volume, proton exchange membrane leads. By growth pace, solid oxide is ahead.
Application:
Cost tiers separate these applications: combined heat and power commands premium pricing through efficiency subsidies, while backup power competes on capital cost against battery alternatives.
- Backup Power:Stationary fuel cell systems providing uninterruptible electricity for critical infrastructure. Data centers in Frankfurt and telecommunications hubs prioritize F-Gas Regulation-compliant cooling architectures.
- Material Handling:Fuel cell-powered forklifts and warehouse vehicles eliminate battery swapping downtime. Logistics operators in Hamburg port corridors and Rhine-Ruhr distribution centers contract for hydrogen supply bundled with equipment.
- Portable Power:Compact systems below five kilowatts for defense and industrial remote operations. SFC Energy dominates German military procurement through Bavarian production.
- Combined Heat and Power:Simultaneous electricity and thermal output for commercial and public buildings. Solid oxide qualifies for Federal Ministry for Economic Affairs and Climate Action building efficiency subsidies under National Hydrogen Strategy guidelines.
- Telecommunications:Off-grid and backup power for cellular base stations and network infrastructure. Operators evaluate total cost of ownership against diesel generator fuel logistics in rural Bavaria and Lower Saxony.
Combined heat and power captures the highest average selling prices. Material handling is expanding most quickly as warehouse operators electrify fleets.
End User:
Customer type determines procurement channel: public institutions run competitive tenders under EU procurement rules, while commercial facilities negotiate direct with integrated hydrogen ecosystem providers.
- Residential Properties:Single-family and multi-unit building installations typically below ten kilowatts. Deployment remains limited by hydrogen distribution infrastructure gaps in suburban regions.
- Commercial Facilities:Office complexes, retail centers, and manufacturing plants seeking energy cost stabilization. Baden-Württemberg and Bavarian industrial zones lead contracting activity.
- Data Centers:Hyperscale and colocation facilities requiring 99.999% uptime with carbon reduction commitments. Frankfurt and Berlin operators pilot solid oxide for baseload displacement.
- Warehousing Facilities:Distribution centers and cold storage operations with intensive material handling equipment cycles. Temperature-controlled grocery logistics in Bavaria drive fuel cell forklift adoption.
- Public Institutions:Hospitals, universities, and government buildings eligible for federal subsidy programs. Municipal energy utilities in North Rhine-Westphalia aggregate demand for district heating feed-in.
Commercial facilities lead by installed capacity. Data centers are gaining share fastest as sustainability commitments harden.
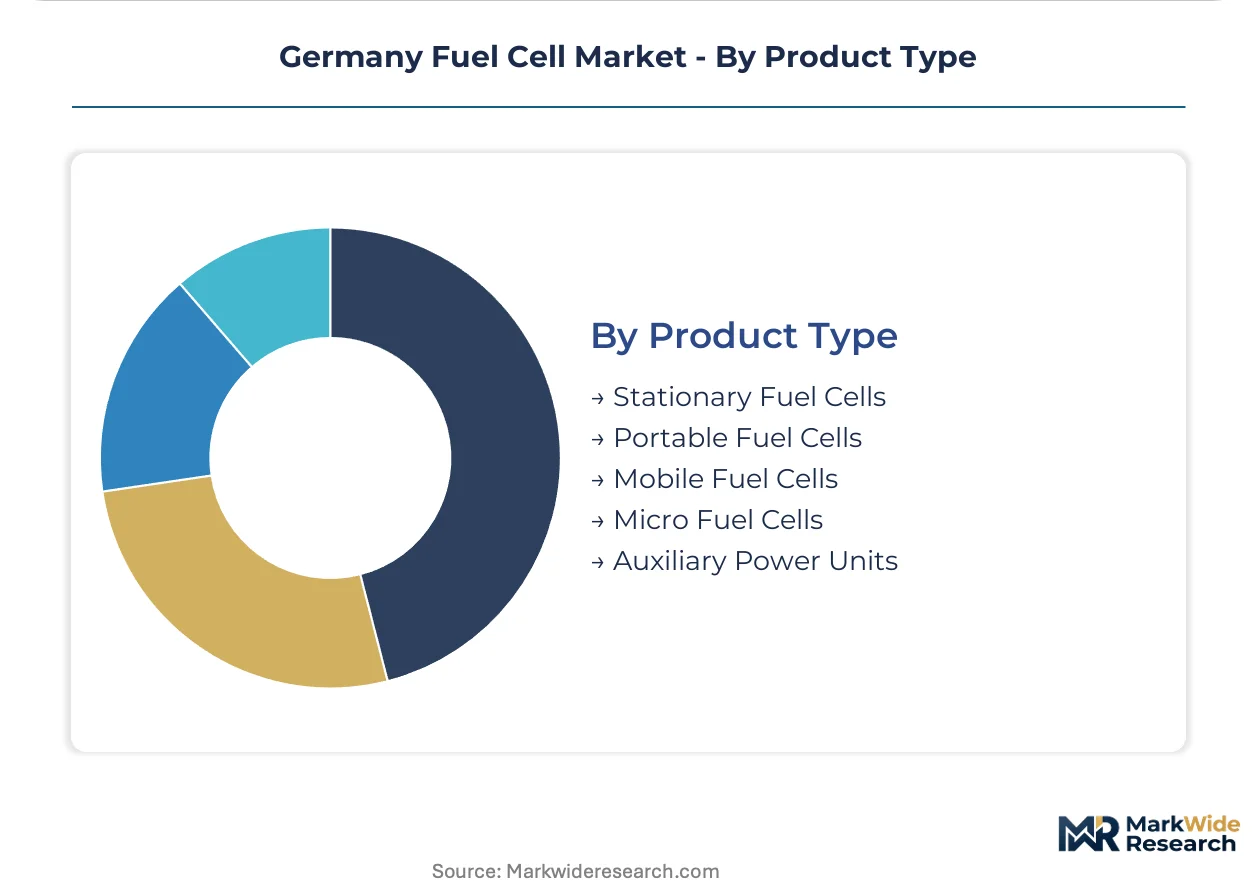
Product Type:
Maturity curves separate these categories: stationary systems have decades of operational history in German pilot programs, while mobile fuel cells remain pre-commercial for most heavy transport segments.
- Stationary Fuel Cells:Fixed installations for primary power, backup, or combined heat and power. ElringKlinger supplies precision stack components to system integrators serving Ruhr industrial clusters.
- Portable Fuel Cells:Man-portable and vehicle-transportable systems for off-grid applications. Defense procurement through Bundeswehr technical offices sustains domestic manufacturing.
- Mobile Fuel Cells:Vehicle-integrated powertrains for buses, trucks, and rail. Proton Motor dominates German-made proton exchange membrane stacks as KBA certification pathways stabilize.
- Micro Fuel Cells:Sub-kilowatt systems for consumer electronics and small appliances. Limited commercial traction due to hydrogen cartridge distribution economics.
- Auxiliary Power Units:Supplementary electricity generation for vehicle hotel loads and idle reduction. Truck OEMs evaluate for long-haul sleeper cab applications pending hydrogen station density improvements.
Stationary fuel cells dominate current revenue. Mobile fuel cells hold the steepest expansion trajectory as freight operators restructure procurement around hydrogen ecosystem partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA type-approval standards anchor Germany's fuel cell deployment geography, with federal hydrogen strategy funding channeling capex toward industrial clusters in Bavaria and the Ruhr region.
Bavaria
Alpine bus fleets and defense procurement drive proton exchange membrane demand around Munich. The Federal Ministry for Economic Affairs and Climate Action directs National Hydrogen Strategy grants toward Bavarian hydrogen valleys. Proton Motor Fuel Cell GmbH manufactures stacks for cold-start applications at its Puchheim facility.
North Rhine-Westphalia
Heavy-duty trucking contracts and steel industry process heat applications absorb megawatt-scale stationary systems. EU Alternative Fuels Infrastructure Regulation mandates hydrogen station density along the A2 and A3 corridors. Duisburg-Essen industrial clusters displace natural gas with solid oxide fuel cells in combined heat and power configurations.
Baden-Württemberg
Municipal utilities pilot solid oxide systems for district heating feed-in across Stuttgart and Karlsruhe. Federal building energy efficiency subsidies under National Hydrogen Strategy guidelines accelerate hospital and university campus deployments. Precision component suppliers in the Stuttgart region feed bipolar plate demand from stack manufacturers.
Lower Saxony
Temperature-controlled grocery logistics operators restructure procurement around bundled hydrogen supply contracts. KBA certification pathways for heavy trucks stabilize as freight operators electrify fixed routes between Hanover and Hamburg. Electrolyzer developers contract directly with fleet operators for dedicated green hydrogen offtake.
Hamburg
Port logistics corridors generate demand for maritime-certified fuel cell powertrains in container handling equipment. Short-sea shipping operators evaluate hydrogen bunkering infrastructure at Tollerort and Burchardkai terminals. The city's industrial zones attract electrolyzer-to-fuel cell co-location investments.
Germany Fuel Cell Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the German fuel cell sector organizing around membrane electrode assembly capabilities and bipolar plate manufacturing precision. Stack integrators compete on KBA certification speed while component suppliers defend position through material science IP. Two strategic archetypes dominate: Bavarian-focused mobility specialists and Ruhr-anchored industrial power providers. Competitive moves concentrate on electrolyzer-to-stack vertical integration and hydrogen supply contract bundling.
Within the German specialist tier, Proton Motor Fuel Cell GmbH and SFC Energy AG exemplify divergent positioning archetypes. Proton Motor occupies the mobility-integrated position through its Bavarian manufacturing base, while SFC Energy represents the portable-off-grid specialist model serving defense procurement channels. ElringKlinger AG anchors the precision component supply tier. Hydrogenics Corporation and Ballard Power Systems Inc. sit within the North American-originated multinational tier competing for German fleet operator contracts.
| Leading Market Players |
|---|
| Proton Motor Fuel Cell GmbH |
| Hydrogenics Corporation |
| SFC Energy AG |
| cellcentric |
| ElringKlinger AG |
| Ballard Power Systems Inc. |
| Plug Power Inc. |
| Bloom Energy Corporation |
| FuelCell Energy Inc. |
| Others |
Supply & Pricing Matrix
Electrolyzer manufacturing scale economies in Bavaria and North Rhine-Westphalia compress unit economics for stack integrators while elevating price floors for smaller competitors lacking captive hydrogen production. This concentration forces mid-tier suppliers to absorb platinum group metal volatility or cede margin to vertically integrated leaders.
Pricing Analysis
Bavarian proton exchange membrane stacks command premium pricing over Nordic alkaline imports due to KBA certification speed and cold-start performance guarantees. Three-tier pricing structure across certified premium, standard commercial, and uncertified economy levels segments buyers by fleet scale and route criticality. Pricing pressure stems from palladium cost spikes in membrane electrode assemblies, squeezing margins for non-integrated stack assemblers. Municipal utilities and hospital procurement committees exhibit lowest price sensitivity, while independent freight operators in Lower Saxony negotiate aggressively on total cost of ownership.
Supply Chain Analysis
Inventory buffers for iridium-coated catalysts stretch to six months as South African mining output fluctuates, forcing German stack manufacturers to pre-position strategic reserves. Supply concentrates in Japan for precision bipolar plates, South Korea for ceramic electrolyte substrates, and domestic Stuttgart-region machining for fuel cell housings. Raw material dependencies span platinum group metals from South Africa, high-purity graphite from China, and fluoropolymer membranes from Belgium. Single-source vulnerability in iridium supply chains exposes capex timelines to geological and geopolitical disruption. Distribution runs through specialized industrial distributors serving mobility channels and direct OEM contracts for stationary power installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany fuel cell market is cycling through electrolyzer capacity overbuild, with green hydrogen offtake agreements now determining which stack manufacturers secure production slots. Fleet operator procurement consolidation signals the recovery phase.
For Market Incumbents: Shield market position by locking Bavarian and Ruhr industrial zones through exclusive hydrogen supply partnerships before electrolyzer developers contract rival stack integrators. Accelerate backward integration into membrane electrode assembly production to neutralize platinum group metal cost spikes. Prioritize KBA certification pipeline investment to maintain premium pricing tier access. For New Entrants and Emerging Players: Differentiate on maritime-certified fuel cell powertrains for Hamburg port logistics, the least contested application segment. Target short-sea shipping operators and container handling equipment OEMs bypassing incumbent trucking relationships. Lead with bundled hydrogen bunkering contracts rather than equipment-only sales to match freight operator procurement restructuring. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision component specialists with bipolar plate IP and electrolyzer-to-stack integration capabilities over pure-play system integrators. Five-to-ten year viability hinges on domestic green hydrogen cost parity with gray hydrogen imports. Monitor Berlin's hydrogen core network infrastructure auction results as the critical inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer-to-Stack Vertical Integration | Bavarian co-location of hydrogen production and fuel cell manufacturing compresses logistics costs for integrated suppliers. |
| KBA Certification Fast-Track Investment | Accelerated type-approval timelines for cold-start performance unlock premium pricing in alpine bus and heavy trucking segments. |
| Maritime Powertrain Certification | Hamburg port logistics corridors generate first-mover advantage for container handling and short-sea shipping applications. |
| Platinum Group Metal Substitution R&D | Reduced iridium loading in membrane electrode assemblies defends margins against South African supply volatility. |
| Hydrogen Supply Contract Bundling | Direct electrolyzer offtake agreements match freight operator procurement consolidation in Lower Saxony and North Rhine-Westphalia. |
Research Methodology
A spread of perspectives from fuel cell stack engineering directors, hydrogen procurement leads at freight operators, KBA certification specialists, electrolyzer project developers, and industrial gas supply managers converged on the working assumptions. Primary interview insights were validated against secondary sources including Federal Ministry for Economic Affairs and Climate Action funding disclosures, KBA type-approval registries, EU Alternative Fuels Infrastructure Regulation implementation reports, and trade data on platinum group metal imports. Bottom-up stack shipment tallies by technology and application were triangulated against top-down electrolyzer capacity buildout projections.
Segmentation dimensions modeled span proton exchange membrane, solid oxide, alkaline, phosphoric acid, and molten carbonate technologies; stationary, portable, mobile, and auxiliary power product types; and commercial facilities, data centers, warehousing, and public institution end users. CAGRs were derived from installed capacity buildout curves cross-referenced with hydrogen refueling station deployment schedules and green hydrogen offtake contract volumes across the projection horizon. Industry-specific forecast inputs include KBA certification queue lengths and Federal Network Agency hydrogen core network auction timelines.
The analysis sits within stated boundaries; outcomes outside sustained National Hydrogen Strategy funding levels, stable platinum group metal supply, and KBA certification protocol finalization would require recalibration. Forecasts reflect documented assumptions on electrolyzer capacity utilization rates and fleet operator electrification commitments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
North America Microbial Fuel Cell Market
Fuel Cell Technology
PEM Electrolyzer Market
Fuel Cell Technology
Residential Fuel Cell Market
Fuel Cell Technology
Japan Fuel Cell Market
Fuel Cell Technology
Direct Methanol Fuel Cell Market
Fuel Cell Technology
Regenerative Fuel Cell (RFC) Technologies Market
Fuel Cell Technology
Asia-Pacific Direct Methanol Fuel Cell Market
Fuel Cell Technology
Microbial Fuel Cell Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
Global Fuel Cell Balance of Plant (BOP) Market
Fuel Cell Technology
Helium Recovery Systems Market
Fuel Cell Technology
Fuel Cells for Marine Vessels Market
Fuel Cell Technology
Portable Fuel Cells Market
Fuel Cell Technology
Bipolar Plate Coatings Market
Fuel Cell Technology
Protonic Ceramic Fuel Cell (PCFC) Market