
 Fruit and Vegetable Juice Market | 2026-2036
Fruit and Vegetable Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit and Vegetable Juice Market Analysis
Subscription-based replenishment services for home-delivered juice packs is expanding how manufacturers monetize recurring consumption rather than one-off retail purchases. PepsiCo leverages its direct-to-consumer infrastructure to sustain recurring revenue streams in North American metropolitan corridors. The Coca-Cola Company anchors global volume through its Minute Maid and Simply branded portfolios across mass retail. Döhler Group specializes in ingredient and flavor systems that supply private-label juice programs for European retailers.
Fruit and vegetable juice comprises aqueous extracts from pressed or macerated produce, typically standardized to specific brix levels between 10 and 14 degrees and either pasteurized or processed through high-pressure processing to achieve microbial stability without thermal degradation of heat-labile vitamins. The category serves commercial refreshment, nutritional supplementation, and culinary ingredient applications across foodservice and retail channels. The 100% Juice segment leads value contribution due to clean-label positioning and parental purchasing preferences for children's beverages, while Smoothies command expanding shelf space as meal-replacement occasions proliferate in convenience retail. Online Retail distribution is accelerating fastest among channels as cold-chain logistics maturity enables direct shipment of refrigerated juices to residential addresses.
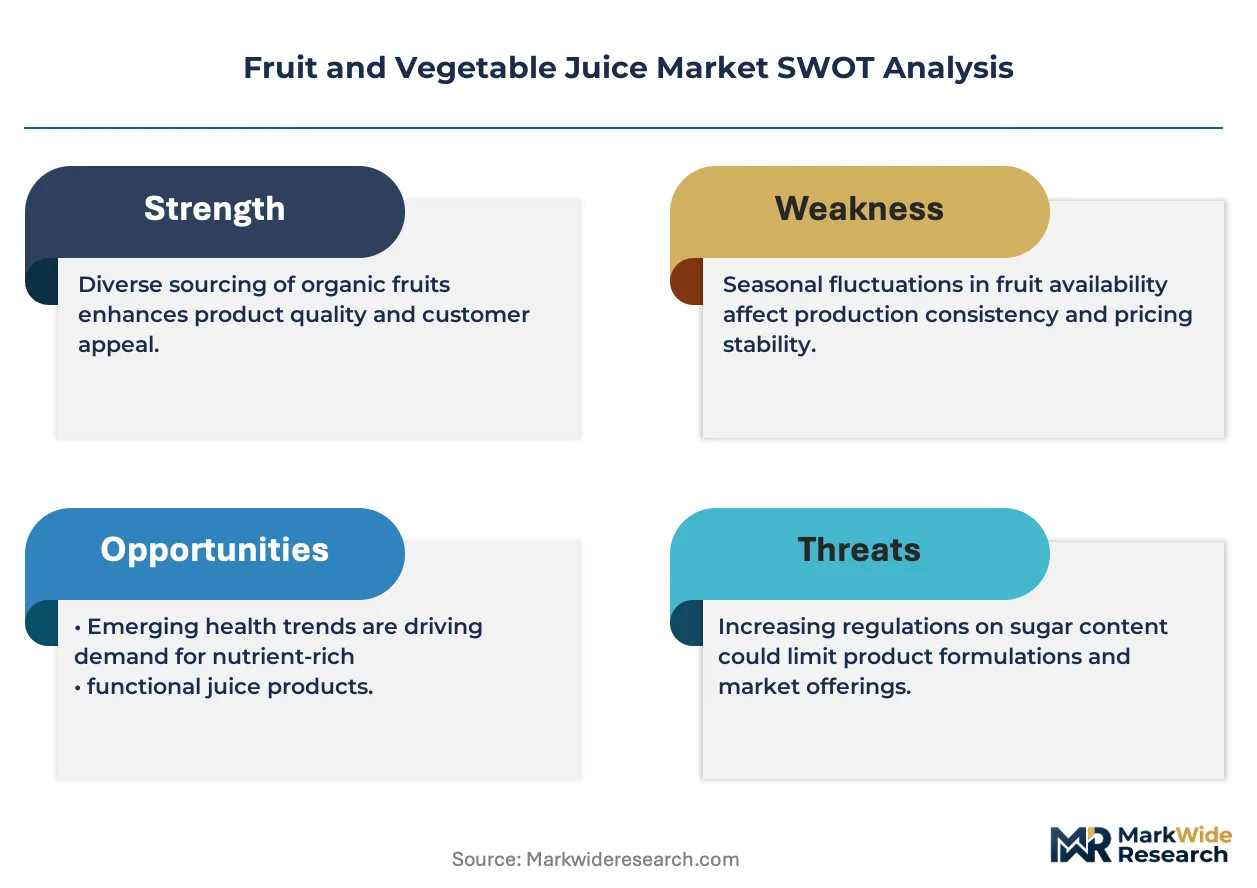
FDA juice hazard analysis and critical control point regulations govern pasteurization standards and warning label requirements for untreated products sold across interstate commerce in the United States. EFSA and EU Food Information to Consumers regulations mandate precise fruit content declarations and restrict health claims that lack substantiated clinical evidence throughout European member states. BIS certification requirements and FSSAI labeling norms in India shape import eligibility and domestic manufacturing compliance for both local producers and multinational entrants. Stakeholders must monitor evolving sugar taxation frameworks and front-of-pack warning label mandates that threaten conventional juice drink positioning in multiple jurisdictions.
Market Dynamics
Cold-pressed extraction and high-pressure processing are compressing shelf-life limitations without thermal degradation, enabling clean-label positioning that commands premium placement across retail and foodservice channels.
Growth Catalysts
- HPP Pasteurization Standards:FDA juice HACCP regulations validate non-thermal microbial stability, accelerating interstate distribution of refrigerated unpasteurized products.
- Hotel and Restaurant Chain Expansion:Beverage menu diversification programs at full-service and fast-casual operators drive bulk concentrate procurement and fountain dispense systems.
- Brazilian Tropical Sourcing:Domestic consumption patterns and export-grade fruit cultivation in São Paulo and Minas Gerais concentrate volume leadership for açaí, guava, and passion fruit derivatives.
Market Restraints
- Perishability Infrastructure:Cold-chain requirements from processing through retail limit distribution radius and elevate logistics expenditure for refrigerated SKUs.
- Input Cost Volatility:Orange juice concentrate futures and fresh fruit procurement expose margins to weather-driven supply fluctuations in Florida and São Paulo.
- Sugar Taxation Frameworks:Front-of-pack warning labels and beverage excises in Mexico, the United Kingdom, and South Africa compress demand for conventional juice drinks.
Strategic Opportunities
- Subscription Replenishment Models:Direct-to-consumer cold-chain logistics enable recurring revenue capture through weekly or biweekly home delivery programs.
- Meal-Replacement Smoothie Positioning:Protein-fortified and fiber-enriched formulations capture convenience retail shelf space previously occupied by conventional beverages.
- EU Green Deal Alignment:Packaging sustainability mandates and extended producer responsibility schemes favor aseptic carton and recyclable PET investments.
Industry Challenges
- Refrigerated Distribution Network Scaling:Last-mile cold-chain integrity requires capital deployment in fleet expansion and temperature-monitoring systems.
- Clean-Label Certification Timelines:Organic, non-GMO, and fair-trade validation processes extend product development cycles and constrain rapid formulation pivots.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit and Vegetable Juice Market |
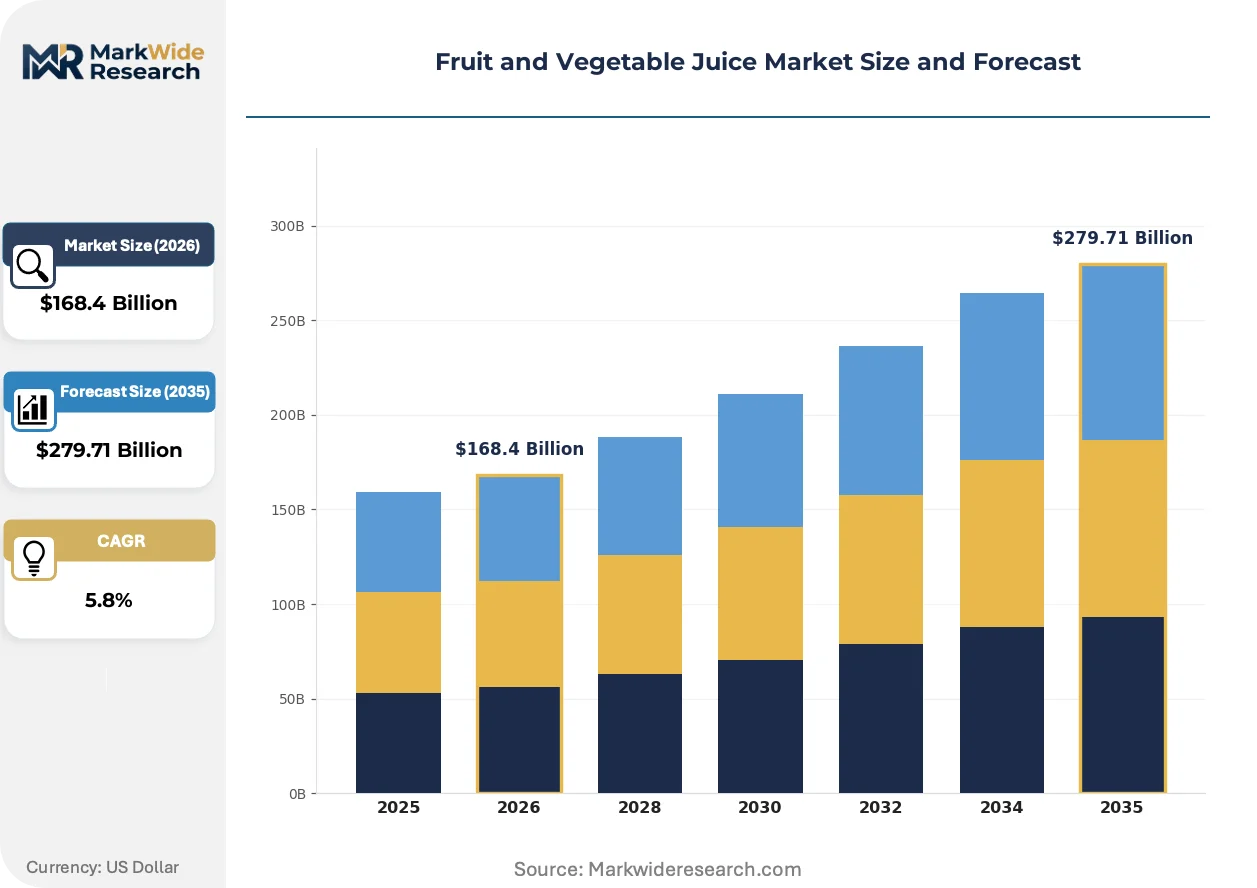
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $279.71 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 100% Juice, Juice Drinks, Concentrates, Smoothies Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores End User: Households, Restaurants, Cafés, Hotels Packaging Type: Cartons, Bottles, Cans, Pouches |
| Companies Covered | Keurig Dr Pepper, Del Monte Foods, PepsiCo, Ocean Spray Cranberries, Dole Packaged Foods, The Coca-Cola Company, Campbell Soup Company, Döhler Group, The Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit and Vegetable Juice Market Emerging Trajectories
Processing technology convergence and regulatory pressure on added sugars are forcing simultaneous investment in extraction efficiency and formulation restructuring across the value chain.
High-pressure processing equipment is modularizing production footprints, allowing smaller regional processors to achieve pasteurization-equivalent shelf stability without centralized thermal infrastructure. Mid-size co-packers in California and Texas are adopting skid-mounted HPP units to serve private-label contracts. This distributed processing model is compressing freight costs and enabling farm-to-bottle regional branding.
Front-of-pack warning label mandates are proliferating across Latin American jurisdictions, with ANVISA in Brazil and COFEPRIS in Mexico implementing nutritional profiling systems that restrict marketing claims. Reformulation toward reduced-sugar and 100% juice positioning dominates R&D allocation. Multinational portfolios are most affected, requiring SKU rationalization and label redesign.
Buyer concentration in club and e-commerce channels is displacing conventional supermarket procurement patterns. Amazon Fresh and Costco are negotiating direct-supplier relationships that bypass traditional distributor markups. This channel shift is most visible in North American metropolitan corridors, where same-day delivery expectations and bulk pack formats reshape volume concentration.
Fruit and Vegetable Juice Market Segmentation
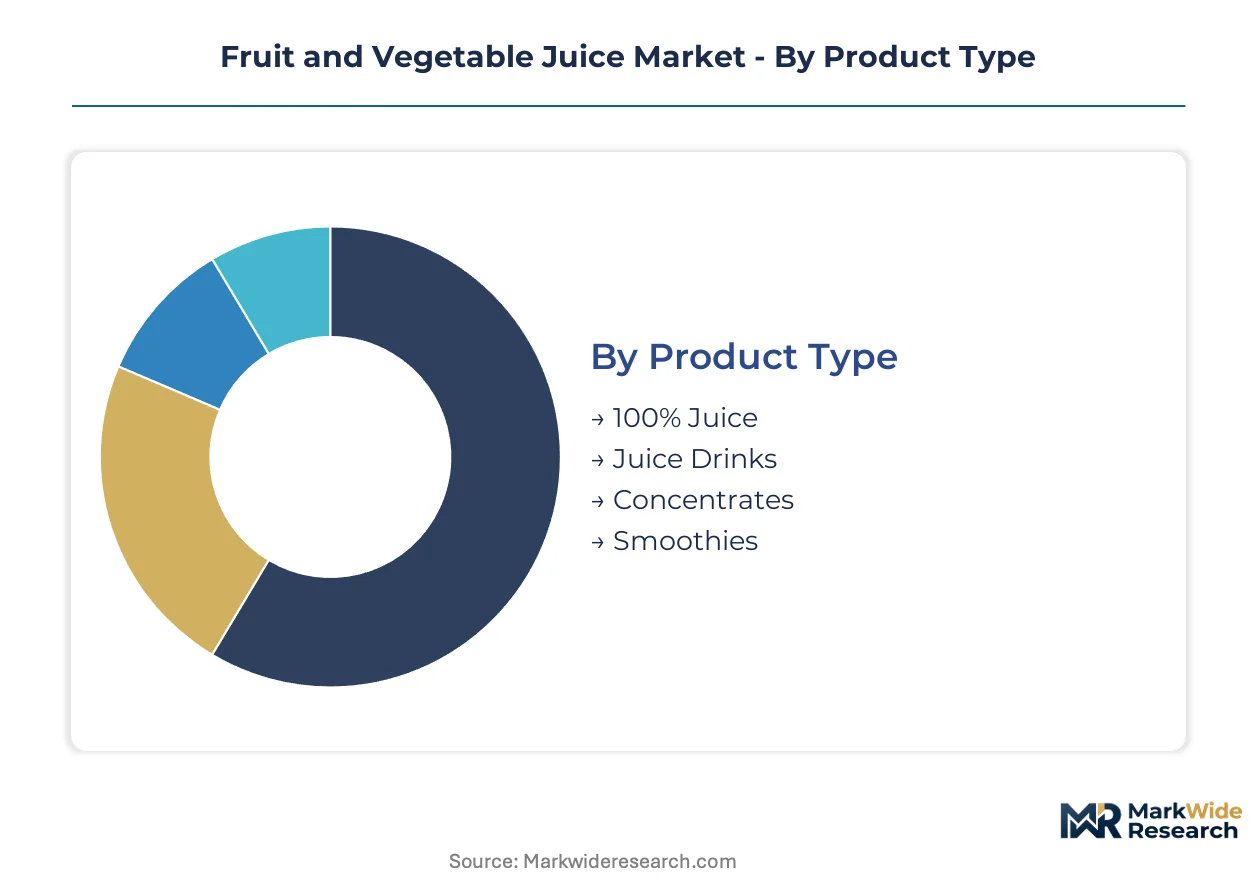
Juice market segmentation reveals divergent capital requirements across product formats, with cold-chain infrastructure and processing technology investments determining competitive entry barriers. Understanding these structural differences exposes where margin pools concentrate and which segments attract strategic repositioning.
Product Type:
Capital intensity peaks in segments requiring refrigerated distribution networks and specialized extraction equipment, while concentrate operations leverage thermal stability for lower fixed-cost structures.
- 100% Juice:Single-strength aqueous extracts standardized to 10–14 degrees brix, pasteurized or HPP-treated to preserve heat-labile vitamins. Parental purchasing preferences in São Paulo and Florida drive premium positioning for children's beverage occasions. Cold-chain requirements elevate distribution costs but command retail price premiums.
- Smoothies:Fiber-retaining blends with protein fortification and meal-replacement positioning. Convenience retail in North American metropolitan corridors allocates expanding shelf space as protein-enriched formulations displace conventional beverages. HPP pasteurization extends shelf life without thermal degradation.
- Juice Drinks:Diluted formulations with added sugars or alternative sweeteners, targeting price-sensitive volume segments. Front-of-pack warning label mandates in Mexico and the United Kingdom compress demand.
- Concentrates:Evaporated extracts with reduced water content for freight efficiency and extended ambient stability. Brazilian orange and açaí derivatives supply global reconstitution operations.
Most installed capacity flows through 100% Juice. Expansion is steepest in Smoothies.
Distribution Channel:
Channel economics separate high-velocity retail requiring trade promotion investment from emerging direct-to-consumer models demanding last-mile cold-chain deployment.
- Supermarkets:Dominant volume channel with centralized procurement and slotting fee structures. PepsiCo and The Coca-Cola Company anchor shelf presence through branded portfolio breadth.
- Online Retail:Fastest-climbing trajectory as cold-chain logistics maturity enables direct shipment of refrigerated juices to residential addresses. Amazon Fresh and subscription replenishment services capture recurring revenue.
- Specialty Stores:Curated assortment targeting organic and cold-pressed positioning. Smaller format limits volume but sustains premium pricing.
- Convenience Stores:Impulse-driven single-serve purchases with limited refrigerated facings. Meal-replacement smoothies gain traction in urban locations.
Supermarkets retain the largest revenue base. Online Retail gains share fastest.
End User:
Demand concentration shifts from household replenishment toward foodservice operators expanding beverage menu diversity.
- Households:Core consumption segment with parental preference for clean-label children's beverages driving 100% juice selection.
- Restaurants:Full-service and fast-casual operators procure bulk concentrate and fountain dispense systems for beverage program expansion.
- Cafés:Specialty coffee chains integrate cold-pressed juices into morning occasion bundling.
- Hotels:Breakfast service and minibar programs standardize premium juice offerings as amenity differentiators.
Households absorb the greatest volume. Restaurants show the steepest procurement growth.
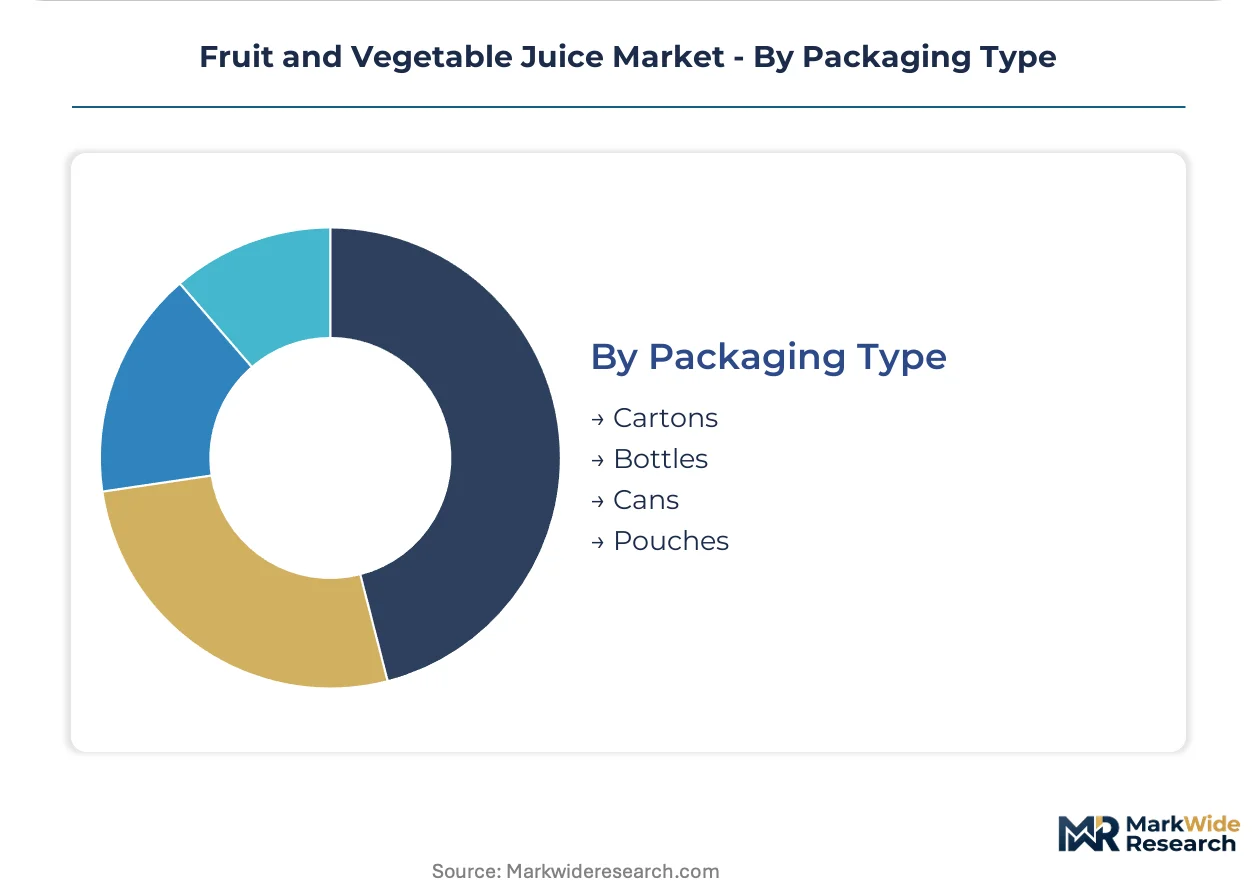
Packaging Type:
Sustainability mandates and extended producer responsibility schemes favor material investments with recycling infrastructure alignment.
- Cartons:Aseptic multilayer packaging dominates ambient-stable concentrates and 100% juice. EU Green Deal alignment favors fiber-based formats with established recycling streams.
- Bottles:PET and glass formats serve refrigerated premium positioning. Recyclable PET investments respond to regulatory pressure in European member states.
- Cans:Aluminum formats expand in single-serve juice drinks and carbonated variants.
- Pouches:Flexible formats target children's portion control and on-the-go consumption.
Cartons hold the largest installed base. Bottles expand most quickly in premium refrigerated segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where juice concentrate production migrates, with Brazil's ANVISA enforcement gaps and India's FSSAI labeling flexibilities attracting contract manufacturing investment away from stricter EU jurisdictions. Producers exploit these compliance-cost differentials while cold-chain infrastructure gaps limit premium refrigerated distribution in emerging markets.
Brazil
Tropical fruit sourcing dominance and domestic açaí consumption anchor volume leadership in São Paulo and Minas Gerais. ANVISA's front-of-pack warning label implementation lags European timelines, preserving conventional juice drink positioning longer than in regulated markets. São Paulo's industrial corridor concentrates extraction and concentrate processing for export-grade orange and passion fruit derivatives.
United States
Subscription replenishment services and direct-to-consumer cold-chain logistics drive metropolitan corridor demand in New York, Los Angeles, and Chicago. FDA juice HACCP regulations validate HPP pasteurization for interstate distribution of refrigerated unpasteurized products. California's Central Valley and Florida's citrus belt concentrate fresh fruit procurement and regional processing infrastructure.
Germany
Private-label juice program expansion and EU Green Deal packaging mandates shape retailer procurement patterns. EFSA restrictions on unsubstantiated health claims constrain marketing vocabulary across member states. Hamburg and Lower Saxony host ingredient systems suppliers and aseptic carton manufacturing aligned with extended producer responsibility schemes.
India
Domestic mango and guava processing scales amid import substitution policies and rising middle-class beverage consumption. BIS certification requirements and FSSAI labeling norms govern both local manufacturing and multinational import eligibility. Maharashtra and Gujarat concentrate fruit processing clusters serving retail and foodservice channels with ambient-stable concentrates.
Mexico
Orange juice concentrate re-export operations and domestic fruit juice consumption face COFEPRIS nutritional profiling and sugar taxation pressure. Front-of-pack warning labels compress demand for conventional juice drinks faster than in Brazil. Jalisco and Nuevo León concentrate beverage manufacturing serving both domestic retail and North American reconstitution operations.
Fruit and Vegetable Juice Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational beverage conglomerates anchoring mass retail through portfolio breadth while regional co-packers capture private-label and foodservice contracts. The market structure tiers between scale-driven branded players with direct-to-consumer infrastructure and ingredient-system suppliers serving retailer own-label programs. Three archetypes dominate: integrated beverage conglomerates with fountain and retail presence, ingredient and flavor system specialists supplying private-label programs, and regional cold-pressed processors with subscription replenishment models. Competitive moves concentrate on M&A to secure tropical fruit sourcing contracts and strategic partnerships to deploy modular HPP equipment across distributed processing networks.
Among North American beverage conglomerates, PepsiCo and The Coca-Cola Company exemplify the integrated archetype with branded portfolio breadth spanning Minute Maid, Simply, and Tropicana positioning. Döhler Group occupies the ingredient-system specialist tier, supplying European retailers with flavor systems and private-label juice programs. These three entities represent distinct competitive positions without overlapping strategic emphasis, allowing segmented market development across branded retail, private-label supply, and foodservice concentrate procurement.
| Leading Market Players |
|---|
| Keurig Dr Pepper |
| Del Monte Foods |
| PepsiCo |
| Ocean Spray Cranberries |
| Dole Packaged Foods |
| The Coca-Cola Company |
| Campbell Soup Company |
| Döhler Group |
| The Kraft Heinz Company |
| Others |
Supply Flow & Price Mechanics
EU Green Deal packaging mandates gate qualified supply access and premium-tier pricing power, as aseptic carton recyclability certifications and extended producer responsibility compliance separate approved suppliers from spot-market alternatives in European retail procurement.
Pricing Analysis
Capacity additions in Brazil are reshaping price floors for tropical fruit concentrates, compressing spot-market premiums for açaí and passion fruit derivatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by cold-chain certification and organic validation, with HPP-treated refrigerated SKUs commanding the widest spreads. Cost compression in conventional juice drinks intensifies because front-of-pack warning label mandates in Mexico and the United Kingdom force reformulation expenditure. Quick-service restaurant chains show the highest price sensitivity due to fountain dispense system standardization, while specialty coffee chains absorb premiums for cold-pressed morning occasion bundling.
Supply Chain Analysis
Dual-sourcing requirements from North American retailers mandate multi-supplier qualification for orange juice concentrate, forcing procurement diversification across Brazil, Florida, and Mexico. Raw material flows draw from São Paulo citrus belts, Minas Gerais açaí cultivation, and Central Valley vegetable processing clusters. Single-source vulnerability concentrates in Brazilian tropical fruit derivatives, where climate-driven harvest variability disrupts reconstitution operations. Distribution runs through temperature-controlled freight networks serving refrigerated SKUs, with ambient-stable concentrates bypassing cold-chain infrastructure for cost efficiency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story, as parental purchasing preferences for clean-label children's beverages shift demand toward 100% juice and HPP-treated premium positioning.
For Market Incumbents: Acquire modular HPP processing equipment to secure pasteurization-equivalent shelf stability without centralized thermal infrastructure. Defensive consolidation should concentrate on tropical fruit sourcing contracts in São Paulo and Minas Gerais, locking supply access against emerging regional co-packers. Channel control through direct-to-consumer cold-chain logistics anchors recurring revenue capture against subscription replenishment disruptors.
For New Entrants and Emerging Players: ANVISA enforcement gaps in Brazil open a window for conventional juice drink positioning before front-of-pack warning label implementation compresses demand. White-space targets include meal-replacement smoothie formulations for North American convenience retail and private-label supply for European retailers seeking EU Green Deal alignment. Go-to-market execution should leverage skid-mounted HPP units for farm-to-bottle regional branding with compressed freight costs.
For Investors and Strategic Acquirers: Roll-up economics work for regional cold-pressed processors because distributed processing networks fragment across metropolitan corridors with underdeveloped last-mile cold-chain infrastructure. Long-term viability centers on recurring revenue capture through subscription replenishment models rather than one-off retail velocity. Signal to watch: Amazon Fresh and Costco direct-supplier negotiations that bypass traditional distributor markups, indicating channel power concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| HPP Equipment Deployment | Modular pasteurization units enable regional processors to achieve shelf stability without thermal degradation. |
| Tropical Sourcing Contracts | Locked supply agreements in São Paulo secure açaí and passion fruit concentrate access against climate volatility. |
| Subscription Replenishment Launch | Direct-to-consumer cold-chain logistics capture recurring revenue through weekly home delivery programs. |
| EU Green Deal Alignment | Aseptic carton and recyclable PET investments satisfy extended producer responsibility schemes in European markets. |
| Meal-Replacement Smoothie Positioning | Protein-fortified formulations displace conventional beverages in convenience retail shelf space allocation. |
Methodological Framework
Bottom-up foodservice and retail channel modeling reconciled against top-down concentrate processing capacity tracking forms the analytical core. Primary interviews with beverage category buyers at supermarket chains, procurement leads at hotel and restaurant operators, cold-chain logistics coordinators, and formulation scientists at ingredient system suppliers combined with secondary validation from FDA juice HACCP filings, EFSA guidance documents, ANVISA regulatory bulletins, and Nielsen retail audit data. Triangulation across these sources ensures demand-side consumption patterns align with supply-side production capacity.
Input-output matrices map fruit procurement volumes through extraction, pasteurization, and packaging stages across product type, distribution channel, end user, and packaging format segmentation. CAGRs derive from volume trajectory modeling against price realization trends throughout the forecast period. Industry-specific forecast inputs include orange juice concentrate futures volatility, HPP equipment adoption curves, and front-of-pack warning label implementation timelines across Latin American jurisdictions.
Revisions become necessary when regulatory enforcement timelines accelerate, climate-driven harvest disruptions exceed historical variance bands, or cold-chain logistics infrastructure investments lag subscription replenishment demand growth. Deviation in Brazilian tropical fruit yield patterns would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Fusion Beverages Market
Beverages
North America Juices Market
Beverages
Drinking Water Market
Beverages
India Soy Beverages Market
Beverages
Rose Floral Water Market
Beverages
South America Energy Drink Market
Beverages
Premium Bottled Water Market
Beverages
Europe Smoothies Market
Beverages
NFC JUICE Market
Beverages
Root Beer Market
Beverages
Packaged Cactus Water Market
Beverages
Citrus Water Market
Beverages
Crystal Boba Market
Beverages
South America Dairy Based Beverages Market
Beverages
Kvass Market
Beverages
Ready-To-Drink (RTD) Beverages Market