
 Intensive Sweeteners Market | 2026-2036
Intensive Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Intensive Sweeteners Market Foresight
Flavor formulation services is decoupling bulk commodity sales from value capture in intensive sweeteners. Cargill, Incorporated leverages its stevia extraction infrastructure to anchor supply contracts with multinational beverage brands. Tate & Lyle PLC sustains competitive positioning through specialized sucralose modification capabilities. Ajinomoto Co., Inc. dominates aspartame quality benchmarks for pharmaceutical and food-grade applications.
Intensive sweeteners are high-potency sugar substitutes—typically 200 to 600 times sweeter than sucrose—engineered for minimal caloric contribution in processed foods and beverages. Stevia glycoside formulations now lead product type demand as clean-label preferences reshape procurement criteria among food manufacturers. Application concentration in beverages generates the deepest margin pools, while bakery and confectionery segments require more complex bulking agent co-formulations that dilute sweetener economics.
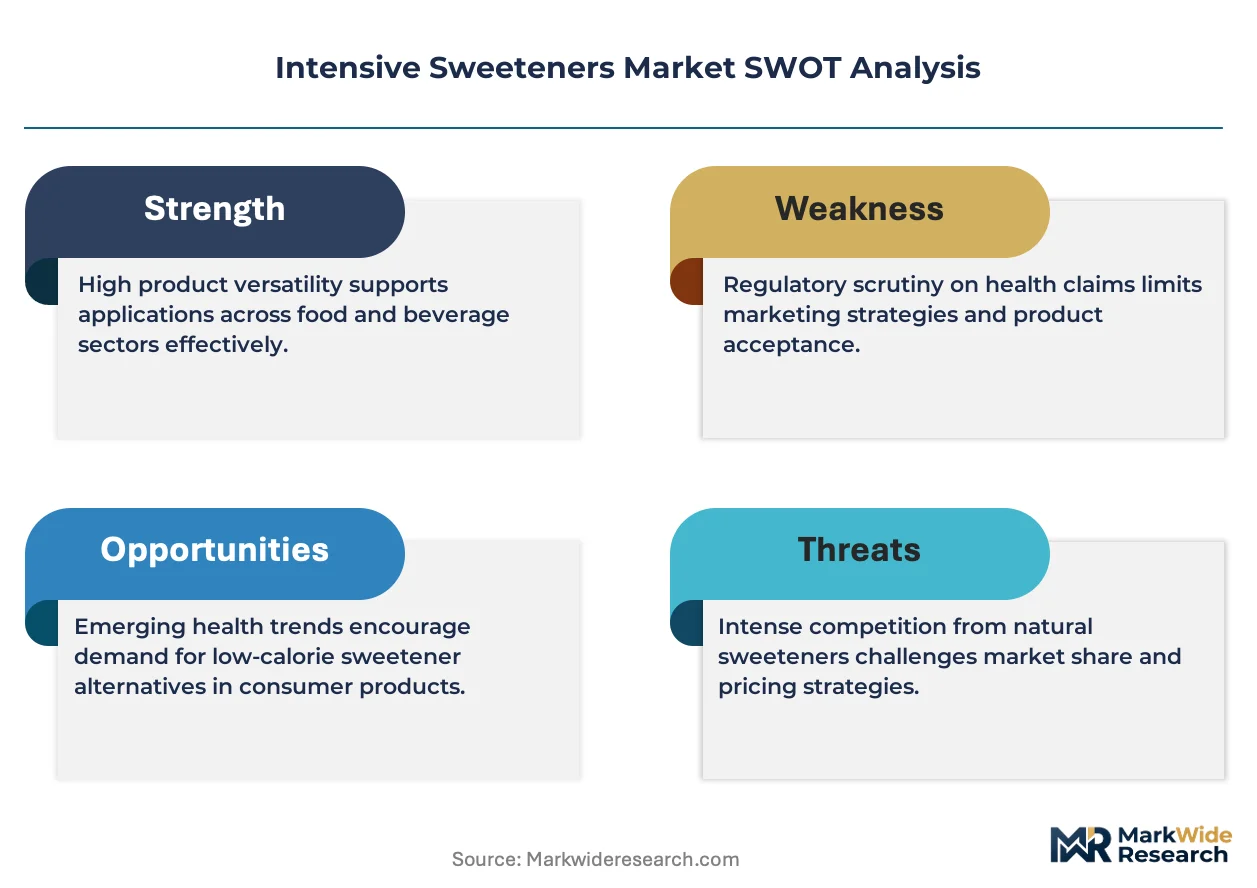
FDA GRAS determinations and EFSA acceptable daily intake protocols govern new molecule approval timelines across North America and Europe. India's FSSAI and China's NMPA are tightening import testing protocols for stevia and sucralose shipments, extending certification cycles for exporters. Stakeholders must monitor evolving WHO guidance on non-sugar sweeteners and assess reformulation costs before committing to next-generation molecule platforms.
Market Dynamics
Clean-label mandates from major beverage brands are forcing intensive sweetener suppliers to abandon synthetic molecule portfolios and rebuild extraction infrastructure around stevia glycosides and monk fruit derivatives.
Growth Catalysts
- Sugar reduction mandates:WHO guidance on non-sugar sweeteners is pressuring national health ministries across Mexico, South Africa, and Thailand to impose mandatory sugar caps on carbonated beverages.
- Stevia extraction advances:Bioconversion processes using engineered yeast strains now yield Reb M and Reb D glycosides without bitter aftertaste, unlocking clean-label applications in premium sports drinks.
- Pharmaceutical excipient demand:Aspartame and sucralose quality grades for chewable tablets and liquid formulations are expanding procurement from drug manufacturers in India and Germany.
Market Restraints
- Stevia leaf supply concentration:Raw material sourcing clusters in China's Sichuan and Yunnan provinces, creating weather-driven volatility and quality inconsistency for global extractors.
- Regulatory friction:India's FSSAI extended certification timelines for imported stevia extracts to 14-18 months, blocking rapid market entry for new suppliers.
- Technical limitations:Heat instability of stevia glycosides above 120°C restricts direct substitution in baked goods without expensive encapsulation or bulking agent co-formulation.
Strategic Opportunities
- Underpenetrated dairy applications:Flavored yogurt and ice cream segments in Brazil and Indonesia remain dependent on sucrose, creating first-mover advantage for reformulated clean-label alternatives.
- EU regulatory tailwind:The EU Green Deal's farm-to-fork strategy prioritizes natural sweetener cultivation within member states, offering subsidy support for domestic stevia farming pilots in Spain and Italy.
- Direct-to-manufacturer platforms:B2B ingredient marketplaces are collapsing traditional distributor markups, enabling mid-sized sweetener extractors to secure contracts with regional beverage brands.
Industry Challenges
- Specialized formulation talent scarcity:Food scientists capable of balancing sweetness intensity with mouthfeel restoration in reduced-sugar applications command premium salaries, constraining R&D expansion at mid-tier suppliers.
- GRAS self-determination liability:FDA notification pathways for novel glycoside variants require toxicology investment exceeding $2 million per molecule, favoring incumbents with established regulatory affairs departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intensive Sweeteners Market |
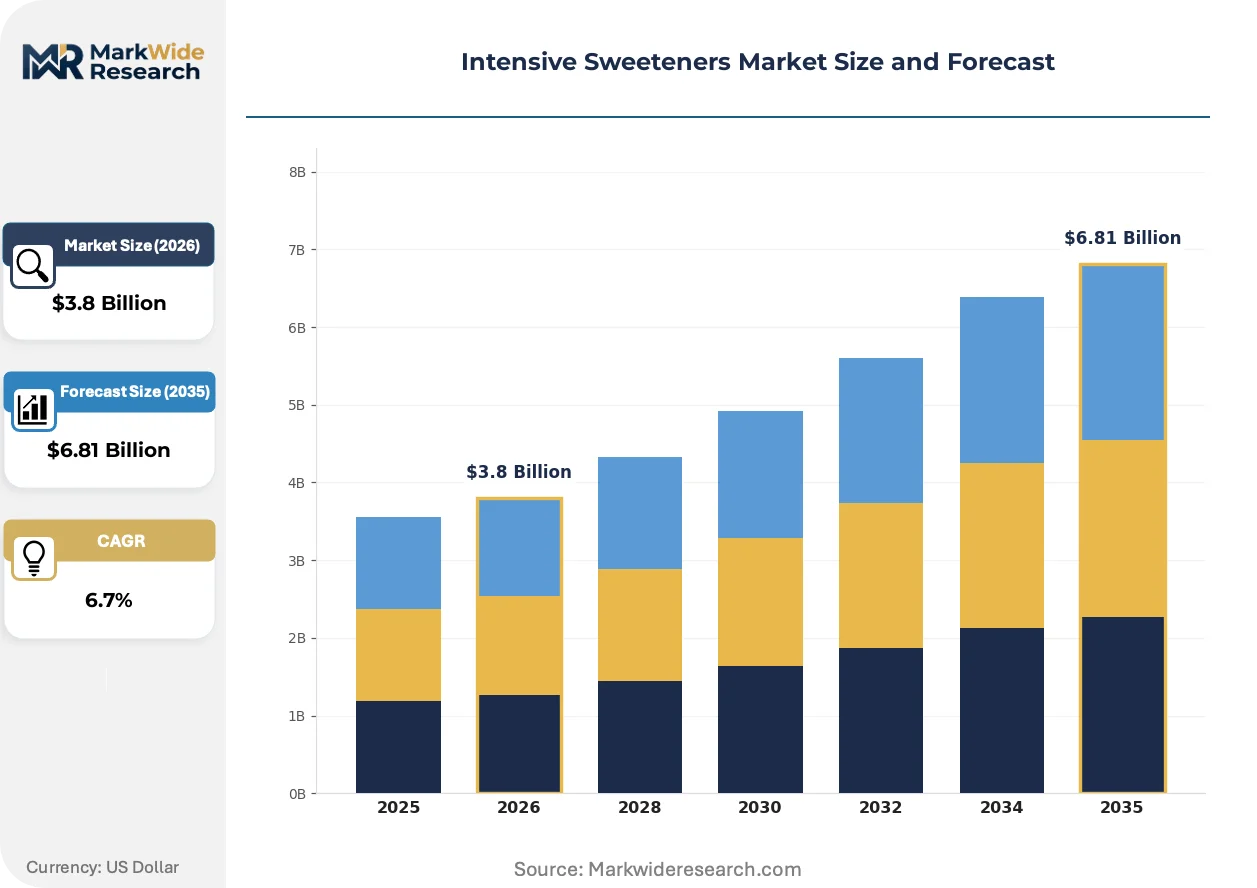
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia, Sucralose, Aspartame, Acesulfame K Application: Beverages, Dairy Products, Bakery, Confectionery Customer Type: Food Manufacturers, Beverage Companies, Retailers, Health-conscious Consumers Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Stores |
| Companies Covered | Cargill, Incorporated, Tate & Lyle PLC, Ingredion Incorporated, Archer Daniels Midland Company, Ajinomoto Co., Inc., Roquette Frères, NutraSweet Property Holdings, Inc., JK Sucralose Inc., Hermes Sweeteners Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intensive Sweeteners Market Shifts & Advancements
Biotechnology is rewriting extraction economics while regulatory arbitrage between jurisdictions creates competitive advantage for suppliers with multi-territory compliance infrastructure.
Precision fermentation of stevia glycosides is electrifying cost structures in high-purity Reb M production. Biotech firms in California and Denmark are licensing yeast strains to traditional extractors, collapsing the 300:1 leaf-to-sweetener ratio toward 10:1 biomass efficiency. Beverage multinationals are locking 5-year offtake agreements with fermentation-derived supply, marginalizing conventional agriculture-dependent competitors.
EFSA's 2023 revised acceptable daily intake protocols for sucralose triggered reformulation cascades across European sports nutrition brands. Manufacturers previously dependent on single-sweetener systems now face dual-validation requirements for blend ratios, extending new product development cycles. German and Dutch contract manufacturers are investing in sensory testing infrastructure to maintain client certification compliance.
Clean-label procurement criteria now dominate RFP scoring at North American beverage conglomerates. Technical buyers are disqualifying suppliers unable to demonstrate stevia supply chain traceability to specific cooperative farms. This behavioral shift is compressing margins for traders and rewarding extractors with captive cultivation operations in Paraguay and Kenya.
Intensive Sweeteners Market Segmentation
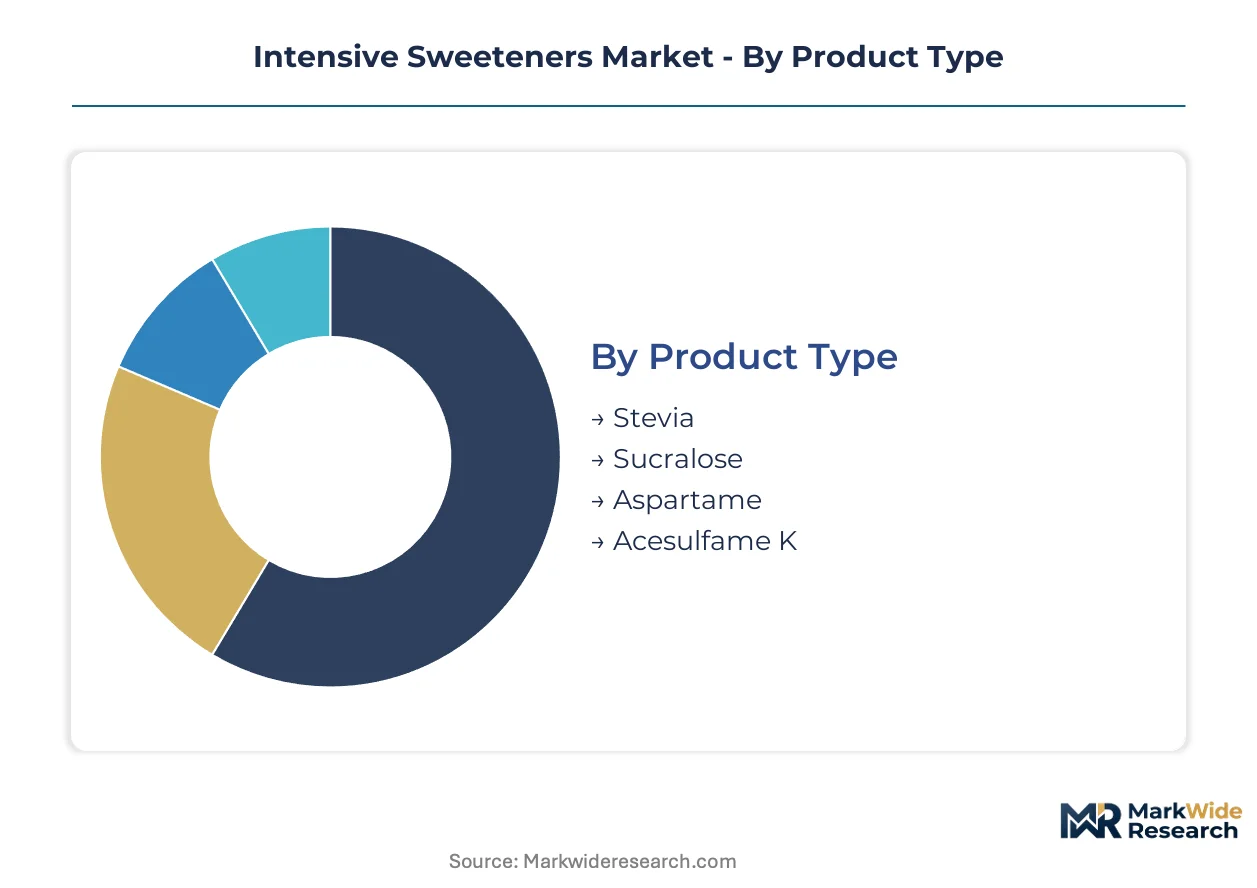
Intensive sweetener procurement patterns diverge sharply across product chemistry, end-use formulation requirements, and customer technical capabilities. Each segment carries distinct regulatory certification burdens and margin structures that reshape supplier prioritization.
Product Type:
Stevia glycosides require FDA GRAS self-determination or EFSA novel food approvals, while synthetic molecules face stricter purity benchmarks under USP-NF and FCC standards.
- Stevia:Plant-derived glycoside extracts—primarily Reb A, Reb M, and Reb D variants—deliver 200-400x sucrose sweetness with zero caloric contribution. Beverage multinationals in Mexico and Germany are locking supply contracts for Reb M specifically, driven by clean-label mandates that exclude synthetic alternatives. Heat stability limitations above 120°C restrict bakery applications without encapsulation investment.
- Sucralose:A trichlorinated sucrose derivative offering 600x sweetness intensity and exceptional thermal stability across pH ranges. EFSA's revised acceptable daily intake protocols triggered reformulation cascades among European sports nutrition brands, compressing single-sweetener formulations toward blended systems. Heat tolerance enables direct substitution in baked goods without bulking agent co-formulation.
- Aspartame:Methyl ester dipeptide compound requiring pharmaceutical-grade purity for excipient applications in chewable tablets.
- Acesulfame K:Synthetic potassium salt stable across baking temperatures, concentrated in confectionery and tabletop sweetener formats.
Stevia sits at the top of the volume ranking, with Reb M and Reb D glycoside variants climbing the fastest.
Application:
Formulation complexity and mouthfeel restoration requirements create tiered margin structures, with liquid applications commanding premium pricing over dry-mix formats.
- Beverages:Carbonated soft drinks, sports drinks, and flavored waters represent the deepest margin pool, requiring only dissolution stability and clean-label positioning. Sugar reduction mandates in Mexico, South Africa, and Thailand are accelerating procurement of stevia-sucralose blends for mid-calorie repositioning. Technical buyers now require supply chain traceability to specific cooperative farms.
- Dairy Products:Flavored yogurt and ice cream segments in Brazil and Indonesia remain sucrose-dependent, creating first-mover advantage for reformulated clean-label alternatives. Protein interaction effects and freeze-thaw stability demands complicate direct substitution, extending development cycles.
- Bakery:Maillard reaction requirements and moisture retention needs force expensive encapsulation or bulking agent co-formulation, diluting sweetener economics.
- Confectionery:Hard candy and chocolate applications depend on crystallization control and melting point manipulation, favoring sucralose-acesulfame K blends.
Beverages generate the steepest margin expansion, with dairy applications gaining share fastest as clean-label penetration accelerates.
Customer Type:
Technical sophistication and regulatory affairs capabilities determine whether customers self-determine GRAS status or outsource compliance to ingredient suppliers.
- Food Manufacturers:Mid-sized baked goods and snack producers with limited R&D staffing rely on supplier-provided formulation services and pre-validated blend ratios.
- Beverage Companies:Multinational brands with captive sensory testing infrastructure negotiate direct extraction contracts, bypassing distributor markups.
- Retailers:Private-label tabletop sweetener programs concentrate procurement among traders with multi-origin supply flexibility.
- Health-conscious Consumers:Direct-to-consumer subscription models for organic stevia extracts are collapsing traditional retail channel economics.
Beverage companies sit at the top of the volume ranking, with health-conscious consumers climbing the fastest through direct-to-platform purchasing.
Distribution Channel:
Channel selection correlates with customer technical autonomy—sophisticated buyers disintermediate traditional distribution entirely.
- Online Retail:B2B ingredient marketplaces enable mid-sized extractors to secure contracts with regional beverage brands, collapsing traditional distributor markups.
- Supermarkets:Mass-market tabletop sweetener placement requires slotting fee investment and promotional support, favoring incumbent brands with trade marketing budgets.
- Convenience Stores:Single-serve packet formats dominate impulse purchases, with placement concentrated in fuel retail and urban transit hubs.
- Specialty Stores:Organic and natural product retailers command premium positioning for Paraguayan and Kenyan-origin stevia with farm-level traceability certification.
Supermarkets sit at the top of the volume ranking, with online retail climbing the fastest as B2B platforms disintermediate legacy distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate toward jurisdictions with faster novel-food approval pathways and lower compliance costs. Cost-of-compliance gaps between the FDA's GRAS notification system and EFSA's centralized authorization create strategic relocation incentives for extraction infrastructure.
United States
Beverage reformulation mandates in California and New York are accelerating stevia procurement for mid-calorie carbonated drinks. FDA GRAS self-determination pathways allow faster market entry for Reb M glycosides than EFSA's novel food authorization. Extraction facilities cluster in California's Central Valley near agricultural biotechnology research centers.
China
Domestic sugar reduction campaigns in tier-one cities are expanding sucralose demand for local beverage brands. NMPA import testing protocols for stevia extracts now require 14-18 month certification cycles, blocking rapid foreign supplier entry. Sichuan and Yunnan provinces host concentrated stevia leaf cultivation cooperatives supplying global extractors.
Germany
Sports nutrition manufacturers in Bavaria are reformulating sucralose-based products following EFSA's revised acceptable daily intake protocols. EU Green Deal farm-to-fork subsidies now support domestic stevia cultivation pilots in Spain and Italy, pressuring German importers. Contract manufacturers around Cologne are investing in sensory testing infrastructure for dual-sweetener validation.
Brazil
Flavored yogurt and ice cream segments remain sucrose-dependent, creating first-mover openings for clean-label reformulation. ANVISA's regulatory framework for novel sweeteners lags FDA and EFSA timelines, extending product registration for imported glycosides. São Paulo-based beverage conglomerates are piloting direct procurement from Paraguayan stevia cooperatives.
India
Pharmaceutical excipient demand for aspartame quality grades is expanding from drug manufacturers in Hyderabad and Mumbai. FSSAI extended import certification timelines for stevia extracts to 14-18 months, protecting domestic extraction investments. Karnataka and Maharashtra states are emerging as contract manufacturing hubs for chewable tablet formulations.
Intensive Sweeteners Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational ingredient suppliers commanding beverage procurement while regional extractors serve bakery and confectionery niches. The vendor base organizes around three strategic archetypes: agricultural-integrated extractors with captive cultivation, biotechnology licensors with precision fermentation platforms, and pharmaceutical-grade purity specialists serving excipient applications. M&A activity concentrates on fermentation technology acquisitions, while capacity expansion focuses on Reb M bioconversion facilities.
Among agricultural-integrated suppliers, Cargill, Incorporated and Tate & Lyle PLC exemplify the scale-driven archetype with established extraction infrastructure. Ajinomoto Co., Inc. occupies a differentiated position within pharmaceutical-grade purity tiers, representing the quality-specialist archetype for excipient applications. These three companies anchor competitive positioning across distinct value-chain segments without overlapping core competencies.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| Ajinomoto Co., Inc. |
| Roquette Frères |
| NutraSweet Property Holdings, Inc. |
| JK Sucralose Inc. |
| Hermes Sweeteners Ltd. |
| Others |
Supply & Pricing Matrix
Stevia leaf price volatility in China's Sichuan basin cascades through extraction economics into three distinct procurement tiers. Beverage multinationals with direct cultivation contracts capture margin advantages unavailable to traders dependent on spot markets.
Pricing Analysis
Distributor markups collapse under pressure from B2B ingredient marketplaces connecting mid-sized extractors directly to regional beverage brands. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade glycoside purity from food-grade Reb A and commodity leaf extracts. Cost compression in standard grades intensifies because fermentation-derived Reb M is collapsing leaf-to-sweetener efficiency ratios. Regional beverage brands exhibit highest price sensitivity, while multinational conglomerates with captive sensory infrastructure prioritize supply security over unit cost.
Supply Chain Analysis
Reverse-logistics flows for rejected stevia leaf batches concentrate quality-control costs at extraction facilities in China, Paraguay, and Kenya. Raw material sourcing draws from Sichuan and Yunnan cultivation cooperatives, California bioconversion facilities, and Kenyan contract farming operations. Single-source vulnerability in China's leaf supply creates weather-driven disruption exposure for conventional extractors. Distribution runs through direct-to-manufacturer platforms for multinational beverage brands and traditional ingredient distributors serving mid-tier food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intensive sweeteners market compounds steadily as sugar reduction mandates harden across national health ministries. Reformulation service capabilities now determine supplier viability more than extraction scale.
For Market Incumbents: Hedge conventional agriculture exposure by licensing precision fermentation technology from California and Danish biotech licensors before Reb M bioconversion marginalizes leaf-dependent competitors. Defend margin position through backward integration into Paraguayan and Kenyan cultivation cooperatives, securing traceability documentation that satisfies clean-label procurement criteria at North American beverage conglomerates.
For New Entrants and Emerging Players: EU Green Deal farm-to-fork subsidies in Spain and Italy open a window for domestic stevia cultivation pilots capturing subsidy-supported first-mover positioning. Target underpenetrated dairy applications in Brazil and Indonesia where sucrose dependence persists in flavored yogurt and ice cream segments. Establish direct-to-manufacturer platform presence to collapse distributor markups and secure regional beverage brand contracts.
For Investors and Strategic Acquirers: Asymmetric upside sits with biotechnology licensors holding precision fermentation platforms for Reb M and Reb D glycoside production. Long-term viability favors extractors with multi-territory compliance infrastructure spanning FDA GRAS self-determination and EFSA novel food pathways. Monitor WHO guidance evolution on non-sugar sweeteners as inflection indicator for national sugar cap implementation cascades.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Licensing | Bioconversion platforms collapse 300:1 leaf-to-sweetener ratios toward 10:1 biomass efficiency. |
| Cultivation Cooperative Integration | Captive supply from Paraguay and Kenya satisfies traceability requirements at clean-label beverage brands. |
| Regulatory Multi-Territory Compliance | Parallel FDA GRAS and EFSA novel food pathways accelerate molecule approval timelines versus single-jurisdiction specialists. |
| Reformulation Service Expansion | Flavor-masking and mouthfeel restoration capabilities capture value beyond commodity glycoside sales. |
| Dairy Application Development | Freeze-thaw stability and protein interaction expertise unlocks Brazilian and Indonesian yogurt and ice cream procurement. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combining structured interviews with extraction facility managers, beverage company procurement directors, regulatory affairs specialists at ingredient suppliers, and contract manufacturing executives at pharmaceutical excipient producers. Secondary validation draws from FDA GRAS notifications, EFSA novel food approvals, FSSAI import certification records, customs trade data for stevia and sucralose shipments, and SEC filings of publicly traded ingredient companies. Bottom-up volume modeling triangulates against top-down market sizing across product chemistry tiers.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. Segmentation dimensions modeled include glycoside variant chemistry, application formulation complexity, customer technical sophistication, and regional regulatory framework clusters. CAGRs derive from elasticity-adjusted demand projections incorporating sugar reduction mandate implementation timelines and fermentation technology adoption curves. Industry-specific inputs capture bioconversion yield improvements and clean-label procurement scoring weights at multinational beverage brands.
Revisions become necessary when WHO guidance on non-sugar sweeteners materializes in strengthened national sugar cap regulations, when fermentation-derived supply achieves cost parity with conventional extraction, or when major import jurisdictions extend certification timelines. Practitioners should monitor EFSA acceptable daily intake protocol evolution, NMPA and FSSAI import testing requirement changes, and biotechnology licensing deal velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Asia-Pacific Plant-Derived and Synthetic Sugar Market
Sweeteners
Invert Sugar Market
Sweeteners
Sanding Sugar Market
Sweeteners
Europe Sugar Substitute Market
Sweeteners
Cassava Syrup Market
Sweeteners
China Saccharin Market
Sweeteners
Rice Syrup Market
Sweeteners
United Kingdom Food Sweetener Market
Sweeteners
Refined Cane Sugar Market
Sweeteners
Molasses Market
Sweeteners
Glucose Syrup Market
Sweeteners
Vanilla Sugar Market
Sweeteners
Coconut Sugar Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
Dry Molasses Market
Sweeteners
Date Sugar Market