
 Europe Smoothies Market | 2026-2036
Europe Smoothies Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smoothies Market Intelligence
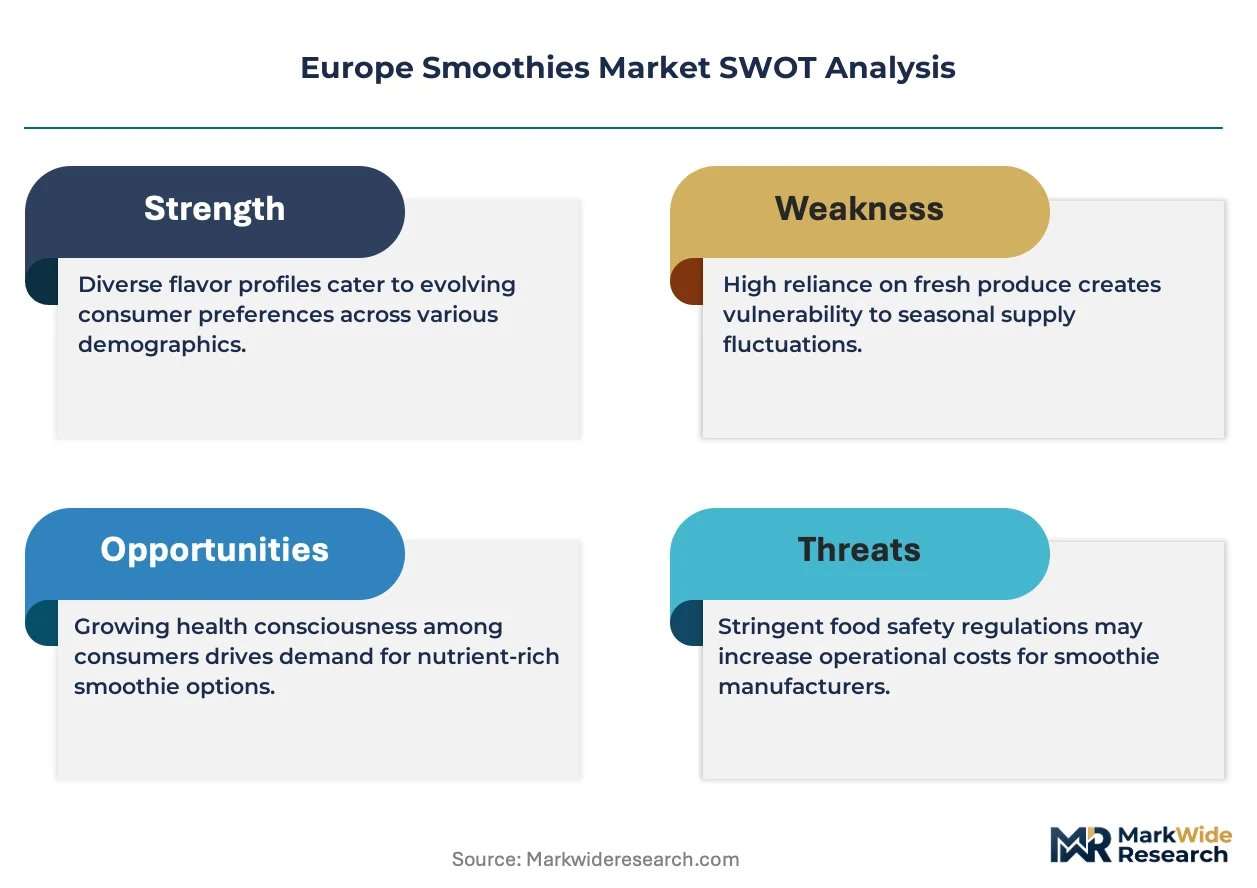
Fresh produce procurement expertise across Southern Europe is collapsing as climate stress shrinks reliable strawberry and mango supply windows. Danone leverages its dairy-adjacent cold-chain infrastructure to dominate refrigerated smoothie distribution in France and Spain. Innocent Drinks anchors its competitive position through vertical control over banana and berry sourcing from Latin American partner farms. True Fruits GmbH specializes in premium glass-bottled formulations with minimal pasteurization, commanding shelf space in German health food stores.
Europe smoothies are blended beverages typically containing fruit, vegetable, or dairy bases processed through high-pressure processing or flash pasteurization to preserve nutrient density without chemical preservatives, designed for convenient consumption as meal replacements or functional nutrition. Organic and functional product types capture expanding margin pools as EFSA-aligned health claims justify price premiums over conventional offerings. Ready-to-drink formats lead volume through supermarket and online retail channels, while berry and green flavor profiles attract health enthusiasts seeking antioxidant positioning and vegetable-derived micronutrient density.
EFSA nutrition and health claims regulation shapes permissible marketing language, constraining functional benefit communication to clinically substantiated statements. The EU Green Deal and REACH frameworks mandate progressive packaging sustainability transitions, compelling manufacturers to abandon multilayer plastics for mono-material or fiber-based alternatives. Stakeholders must monitor ECHA substance restriction proposals and national deposit-return scheme expansions to anticipate compliance cost trajectories and format adaptation requirements.
Market Dynamics
The EU Green Deal's packaging waste directives are decomposing established supply chain architectures, forcing manufacturers to abandon multilayer plastics and rebuild around mono-material or fiber-based alternatives before deposit-return schemes expand.
Growth Catalysts
- EFSA-aligned health claims:Clinically substantiated functional benefit communication justifies price premiums for organic and fortified blends across German and French retail channels.
- High-pressure processing:Flash pasteurization and HPP systems preserve nutrient density without chemical preservatives, unlocking clean-label positioning for meal replacement formats.
- Cold-chain infrastructure density:Urban Germany, the United Kingdom, and France maintain refrigerated distribution networks that support premium ready-to-drink penetration.
Market Restraints
- Fresh produce procurement collapse:Climate stress is compressing reliable strawberry and mango supply windows across Southern Europe.
- REACH substance restrictions:ECHA proposals on chemical additives create compliance cost trajectories that disadvantage smaller format specialists.
- Dairy-based alternatives:Plant-based oat and almond blends are displacing conventional yogurt-smoothie hybrids in French and Spanish convenience retail.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania lack health-food retail density, creating first-mover space for cold-chain investors.
- Functional vegetable blends:Green flavor profiles with vegetable-derived micronutrient density attract antioxidant-seeking consumers in urban France.
- CSRD reporting alignment:Corporate sustainability disclosure requirements reward transparent supply chain documentation with institutional procurement preference.
Industry Challenges
- Reformulation talent scarcity:Food technologists skilled in minimal-pasteurization stabilization are concentrated in Germany and the Netherlands.
- Packaging reconfiguration capex:Mono-material line conversions demand capital outlays that strain mid-cap manufacturers before scale economies materialize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smoothies Market |
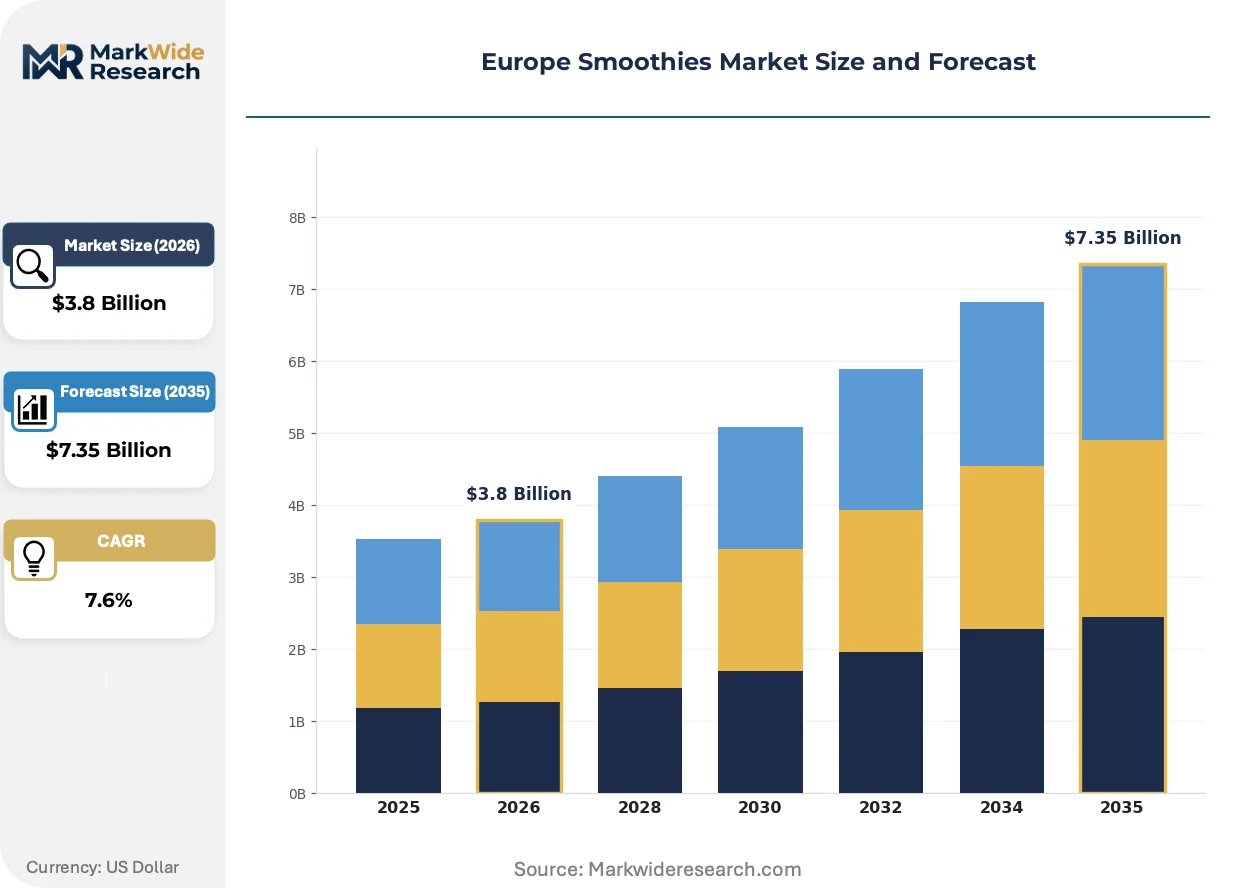
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Functional, Ready-to-Drink Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Shops Flavor Profile: Berry, Tropical, Green, Mixed Fruit End User: Health Enthusiasts, Busy Professionals, Students, Families |
| Companies Covered | Danone, Fruska, Innocent Drinks, True Fruits GmbH, Yeo Valley, PepsiCo Inc., The Coca-Cola Company, Eckes-Granini Group GmbH, Nestlé S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smoothies Market Strategic Shifts & Innovations
Refrigerated distribution networks are rewiring competitive advantage around captive cold-chain control rather than brand equity alone. Three distinct vectors are compressing legacy operating models.
High-pressure processing technology is decomposing the trade-off between shelf stability and nutrient retention. German health food retailers are adopting HPP-equipped private label programs at accelerating pace. This capability compression is enabling shorter supply chains with reduced preservative loads.
REACH frameworks and EU Green Deal packaging mandates are eliminating multilayer plastic formats from supermarket shelves. Industrial consequence includes forced line retrofits and supplier consolidation around mono-material certified partners. German deposit-return scheme expansions are accelerating format adaptation most aggressively.
Urban French and German consumers are rotating toward vegetable-forward blends as meal replacements rather than snacks. Direct-to-subscription channels are displacing impulse supermarket purchases for functional nutrition seekers. Berlin and Paris clusters exhibit the fastest behavioral transition velocity.
Europe Smoothies Market Segmentation
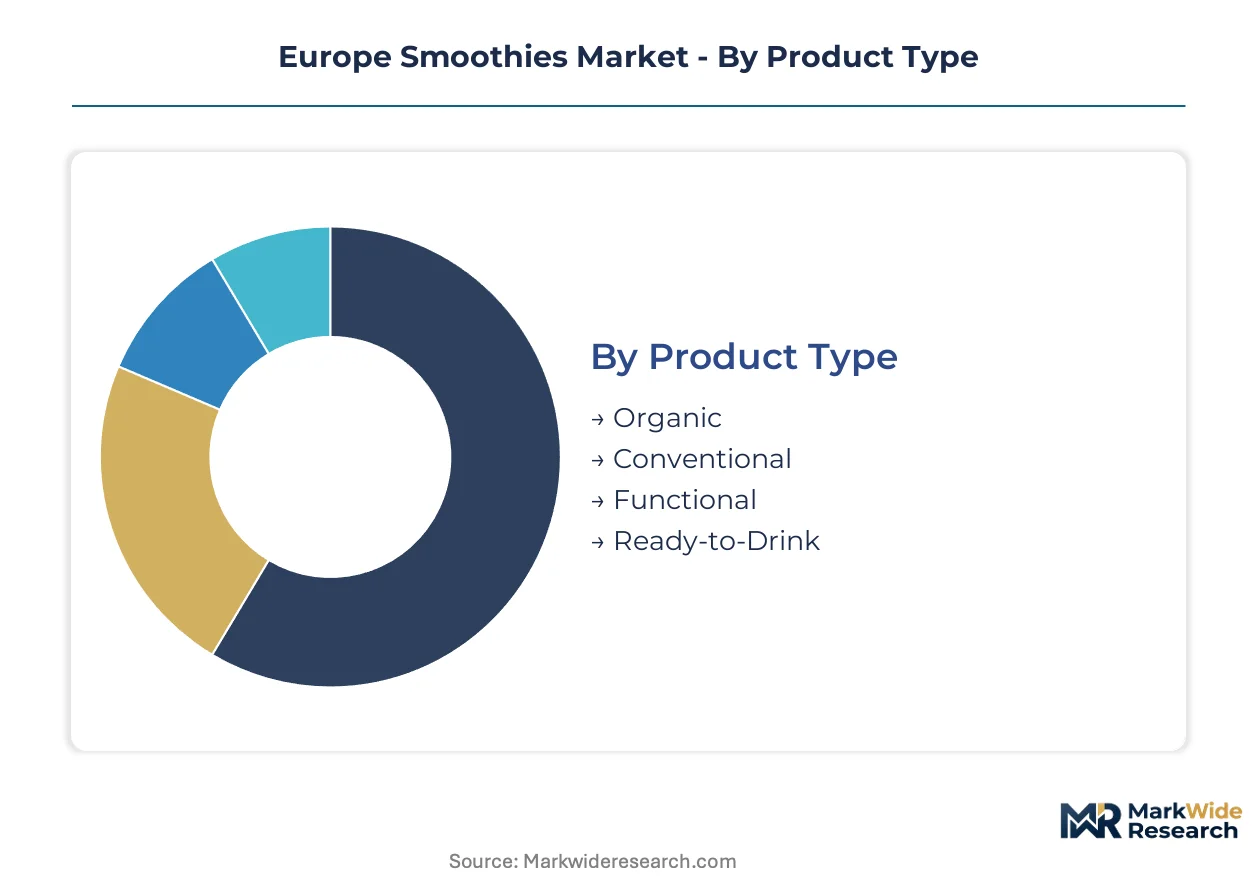
Segmentation in the European smoothies market reveals how substitution pressures from adjacent beverage categories reshape competitive boundaries across product tiers and channel strategies. Understanding these divides exposes where margin pools concentrate and where defensive positioning proves necessary.
Product Type:
Conventional formulations face acute displacement risk from functional alternatives and private-label organic offerings as EFSA-aligned health claims reframe purchasing criteria.
- Organic:Certified fruit and vegetable blends without synthetic pesticide residues command shelf-space premiums in German and French health food retail. EFSA organic logo recognition drives repeat purchase behavior among urban health enthusiasts seeking clean-label assurance.
- Functional:Fortified blends with clinically substantiated protein, fiber, or probiotic additions target meal replacement occasions in Paris and Berlin convenience channels. EFSA health claim compliance enables premium pricing that conventional products cannot match.
- Conventional:Standard fruit-based formulations without certification or fortification compete primarily on price in supermarket value tiers across Spain and Italy.
- Ready-to-Drink:Pre-packaged single-serve formats leverage cold-chain density for impulse capture in UK and German urban convenience retail.
Conventional blends anchor the volume base while functional variants gain share at the steepest rate.
Distribution Channel:
Channel cost structures stratify sharply between mass retail scale and specialty service intensity, with online fulfillment economics still unsettled.
- Supermarkets:Multi-format retailers in Germany and France dominate volume through refrigerated aisle placement and promotional slotting fees. Cold-chain infrastructure investments by Rewe and Carrefour enable national distribution of premium HPP-treated lines.
- Health Food Stores:Independent and chain specialists in Berlin, Munich, and Amsterdam curate premium glass-bottled offerings with minimal pasteurization. Staff consultation drives trial of higher-margin functional blends unfamiliar to supermarket shoppers.
- Online Retail:Direct-to-subscription models bypass retail margin capture for recurring delivery in London and Paris metropolitan zones.
- Specialty Shops:Juice bars and fitness center kiosks in urban Spain and Italy provide immediate consumption with customization options.
Supermarkets retain volume dominance while online channels expand most quickly among subscription-oriented professionals.
Flavor Profile:
Flavor preferences track antioxidant positioning and vegetable-content credibility across northern and southern European consumption clusters.
- Berry:Strawberry, blueberry, and raspberry blends leverage established antioxidant health narratives in UK and German retail. Supply reliability concerns from Southern European climate stress are compressing procurement windows and raising input costs.
- Green:Spinach, kale, and celery-forward formulations attract meal replacement seekers in Paris and Copenhagen seeking vegetable-derived micronutrient density. EFSA-aligned chlorophyll and fiber claims support premium positioning.
- Tropical:Mango, pineapple, and passion fruit profiles dominate Spanish and Italian summer consumption with established taste familiarity.
- Mixed Fruit:Multi-fruit combinations balance accessibility and perceived variety in family-oriented German supermarket purchasing.
Berry profiles sustain volume leadership while green blends show the steepest expansion trajectory among urban functional nutrition seekers.
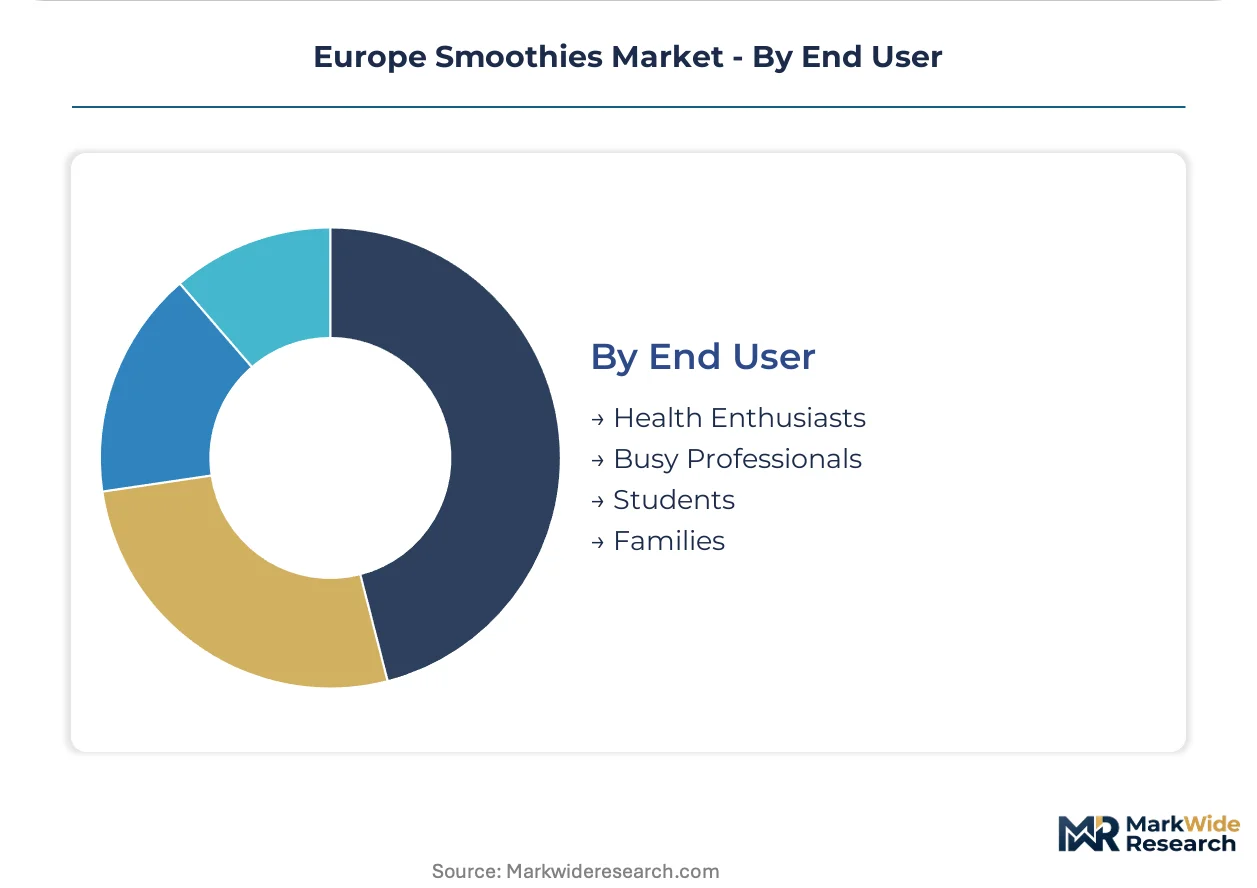
End User:
User occasion segmentation separates snack substitution from meal replacement intent, with distinct price tolerance and format requirements.
- Health Enthusiasts:Nutrition-tracking consumers in Berlin and Amsterdam prioritize EFSA-verified health claims, organic certification, and HPP processing transparency. Direct subscription relationships and health food store loyalty programs capture this highest-margin segment.
- Busy Professionals:Time-constrained urban workers in London and Paris seek convenient breakfast replacement with sufficient protein and fiber content for satiety. Grab-and-go refrigerated formats in transport hubs and office district convenience stores dominate this occasion.
- Students:Price-sensitive younger consumers in university towns across Poland and Romania favor conventional supermarket promotions and private-label alternatives.
- Families:Multi-person households in suburban Germany and France purchase larger-format mixed fruit offerings for shared consumption occasions.
Families provide the volume foundation while health enthusiasts generate the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA nutrition and health claims regulation anchors competitive positioning across Germany, where the largest refrigerated distribution networks support premium smoothie penetration. Cold-chain infrastructure density in urban clusters determines market access more than brand recognition alone.
Germany
Health enthusiasts in Berlin and Munich drive demand for organic-certified and HPP-treated functional blends. The national deposit-return scheme expansion under EU Green Deal packaging mandates forces rapid format adaptation toward mono-material alternatives. Bavaria's food technology corridor concentrates reformulation talent for minimal-pasteurization stabilization.
United Kingdom
Busy professionals in London seek convenient breakfast replacement formats with elevated protein and fiber content for satiety. EFSA-aligned health claim compliance enables premium pricing that supermarket private labels struggle to match. The Southeast England logistics cluster supports direct-to-subscription fulfillment economics for recurring delivery models.
France
Urban consumers in Paris rotate toward vegetable-forward green blends as meal replacements rather than snacks. REACH substance restrictions on chemical additives create compliance cost trajectories that reshape competitive dynamics. The Île-de-France refrigerated distribution hub enables national penetration of premium glass-bottled offerings.
Spain
Tropical flavor profiles dominate summer consumption patterns in Barcelona and Madrid with established taste familiarity. Climate stress compresses reliable strawberry supply windows from Southern European growing regions. The Valencia agricultural belt faces procurement pressure as reliable mango sourcing windows shrink.
Poland
Price-sensitive students in Warsaw and Krakow favor conventional supermarket promotions and private-label alternatives. Health-food retail density remains underdeveloped relative to Western European benchmarks. The Mazovia region presents first-mover space for cold-chain investors seeking Eastern European expansion.
Europe Smoothies Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with multinational beverage conglomerates leveraging dairy-adjacent cold-chain infrastructure against focused craft formulators. The upper tier commands refrigerated aisle placement through scale economies in distribution. Three archetypes define competitive positioning: dairy-leveraged conglomerates with captive cold-chain networks, premium glass-bottled specialists with minimal-processing credentials, and private-label programs equipped with HPP technology. Dominant competitive moves include strategic partnerships for Latin American fruit sourcing and forced line retrofits for mono-material packaging compliance.
Within the premium specialist tier, True Fruits GmbH exemplifies the German craft formulator archetype through its glass-bottled positioning, while Innocent Drinks anchors the vertically integrated sourcing model with partner farm relationships. Danone represents the dairy-leveraged conglomerate archetype, exploiting refrigerated distribution networks built for yogurt and fresh dairy adjacencies. These three entities illustrate how cold-chain control, sourcing transparency, and format premiumization separate sustainable positioning from commodity competition.
| Leading Market Players |
|---|
| Danone |
| Fruska |
| Innocent Drinks |
| True Fruits GmbH |
| Yeo Valley |
| PepsiCo Inc. |
| The Coca-Cola Company |
| Eckes-Granini Group GmbH |
| Nestlé S.A. |
| Others |
Cost & Logistics Intelligence
Cold-chain capacity utilization in Germany and France anchors margin structures across premium and economy tiers, compressing price floors for mid-cap operators lacking refrigerated distribution density. EU Green Deal packaging mandates force parallel investments in mono-material line conversions, elevating fixed cost thresholds that reshape competitive entry economics.
Pricing Analysis
Price spreads between Berlin health food stores and Warsaw supermarkets exceed 40 percent for equivalent HPP-treated functional blends. Three-tier pricing structure across premium glass-bottled, standard refrigerated, and economy ambient-stable levels reflects certification grade and cold-chain investment intensity. Pricing pressure stems from private-label organic expansion in German supermarket channels, eroding branded premium capture. Students in Eastern European markets exhibit highest price sensitivity, while health enthusiasts in Amsterdam and Copenhagen tolerate significant premiums for EFSA-aligned health claim transparency.
Supply Chain Analysis
Just-in-time fresh produce procurement dominates Northern European operations, while strategic stockpiling of aseptic purees buffers Spanish and Italian manufacturers against Southern European climate volatility. Latin American banana and berry sourcing concentrates in Ecuador, Colombia, and Costa Rica, with mango procurement drawing from Peruvian and Mexican growing regions. Single-source vulnerability in Ecuadorian banana supply creates concentration risk for vertically integrated specialists. Distribution runs through captive refrigerated networks controlled by dairy-leveraged conglomerates and specialized cold-chain logistics operators serving health food retail clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based recurring delivery models in London and Paris metropolitan zones expand faster than one-time retail purchases, transforming smoothie consumption from impulse acquisition to planned nutrition service. This service-attach dynamic rewards cold-chain operators capable of integrating direct-to-consumer fulfillment with existing refrigerated infrastructure.
For Market Incumbents: Secure Latin American sourcing partnerships before climate stress compresses reliable procurement windows further, locking in multi-year supply agreements with Ecuadorian and Colombian grower cooperatives. Accelerate mono-material packaging line conversions ahead of German deposit-return scheme expansions to preempt compliance cost disadvantages against smaller format specialists. Reinforce health food store shelf presence through exclusive HPP-equipped private label programs that leverage existing refrigerated distribution density.
For New Entrants and Emerging Players: EFSA organic certification fast-track enables premium positioning in Polish and Romanian markets where health-food retail density remains underdeveloped relative to Western European benchmarks. Target Warsaw and Krakow university corridors with direct-to-subscription models bypassing conventional supermarket slotting fee barriers. Partner with regional dairy distributors for cold-chain access rather than building captive refrigerated networks from origin.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors HPP-equipped regional specialists with established Latin American sourcing relationships and compliant mono-material packaging capabilities. Five-to-ten year viability hinges on climate adaptation infrastructure and EFSA health claim substantiation pipelines. Monitor German deposit-return scheme implementation velocity as inflection indicator for format adaptation cost trajectories and mid-cap manufacturer consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Latin American Sourcing | Captive supply of Ecuadorian bananas and Colombian berries insulates margin structures from climate-driven procurement compression. |
| Mono-Material Packaging Line Conversion | EU Green Deal compliance enables continued German supermarket shelf access ahead of deposit-return scheme enforcement. |
| Direct-to-Subscription Channel Launch | Recurring revenue models in London and Paris bypass retail margin capture and build consumption habit formation. |
| HPP Technology Partnership | High-pressure processing capability unlocks clean-label positioning and extended shelf stability without chemical preservatives. |
| Eastern European Cold-Chain Expansion | First-mover refrigerated infrastructure in Poland and Romania captures underpenetrated health enthusiast demand. |
Research Approach
The analysis maps organic, functional, conventional, and ready-to-drink product segments, each validated through category buyers at Rewe and Carrefour, supply planners at Latin American fruit cooperatives, cold-chain logistics operators, and health food store proprietors in Berlin and Amsterdam. Primary interviews combined with secondary validation against Nielsen retail audit data, EFSA health claim registries, EU customs import records, and SEC filings of publicly traded beverage conglomerates. Bottom-up volume modeling triangulated against top-down category spending estimates.
Consistency checks validated volume and value outputs against refrigerated distribution capacity expansion rates, HPP equipment installation tracking, and EFSA health claim approval timelines across the projection horizon. Segmentation dimensions modeled include product certification tier, flavor profile antioxidant positioning, distribution channel cold-chain intensity, and end-user occasion segmentation between snack substitution and meal replacement intent. CAGRs derived from trend extrapolation of health food retail density, subscription service adoption curves, and packaging format transition velocities.
Underlying assumptions cover EFSA regulatory stability, Latin American growing region climate patterns, and EU Green Deal implementation timelines, with deviation risk concentrated in Southern European fresh produce supply reliability and German packaging mandate acceleration. Revision becomes warranted when deposit-return scheme adoption crosses threshold coverage of 70 percent of EU population or when Ecuadorian banana export volumes decline sequentially for four consecutive quarters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Soft Serve Premix Market
Beverages
Ginger Ale Market
Beverages
United States Soy Beverages Market
Beverages
Spring Water Market
Beverages
Detox Drinks Market
Beverages
Sparkling Water Machine Market
Beverages
Europe Sugar Free Energy Drinks Market
Beverages
Hydrogen Water Bottle Market
Beverages
Coconut Milk Beverages Market
Beverages
Hydration Infusers Market
Beverages
Growlers Market
Beverages
GCC Coconut Water Market
Beverages
Sparkling Juice Drinks Market
Beverages
Sparkling Water Market
Beverages
Beverage Premix Market
Beverages
North America Juices Market