
 Milk Pasteurization Machines Market | 2026-2036
Milk Pasteurization Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Pasteurization Machines Market Foresight
The capability gap between integrated system builders and component assemblers is collapsing as modular skid designs lower capital barriers for mid-scale dairy processors. Tetra Pak International S.A. leverages its aseptic packaging ecosystem to bundle pasteurization with downstream filling lines, locking in long-term service contracts. GEA Group AG anchors its position through captive supply of plate heat exchanger cores, while Alfa Laval AB competes on energy recovery efficiency in high-volume continuous systems.
Milk pasteurization machines are thermal processing systems designed to heat raw milk to precise temperatures—typically 72°C for 15 seconds in HTST protocols or 63°C for 30 minutes in batch vat methods—before rapid cooling to eliminate pathogenic microorganisms while preserving nutritional and sensory qualities. Continuous pasteurizers dominate large dairy processing plants where throughput exceeds 10,000 liters per hour, whereas batch pasteurizers retain share among artisan creameries and specialty cheese operations requiring smaller runs with recipe flexibility. High-pressure processing represents the fastest-growing technology segment, as cold pasteurization extends shelf life without thermal degradation of whey proteins, though thermal pasteurization still captures the majority of installed base due to lower per-unit capital cost and regulatory familiarity.
FDA pasteurized milk ordinances and EU MDR-equivalent food contact material standards shape equipment design, mandating sanitary welding, CIP-compatible surfaces, and full batch traceability that add engineering cost but create compliance moats for certified manufacturers. EFSA's evolving listeria monitoring protocols and state-level dairy inspectorates in Wisconsin and California drive replacement cycles for aging vat systems that lack automated logging. Stakeholders must weigh energy efficiency gains against retrofit complexity as carbon pricing mechanisms expand and grid-dependent thermal systems face operating cost pressure.
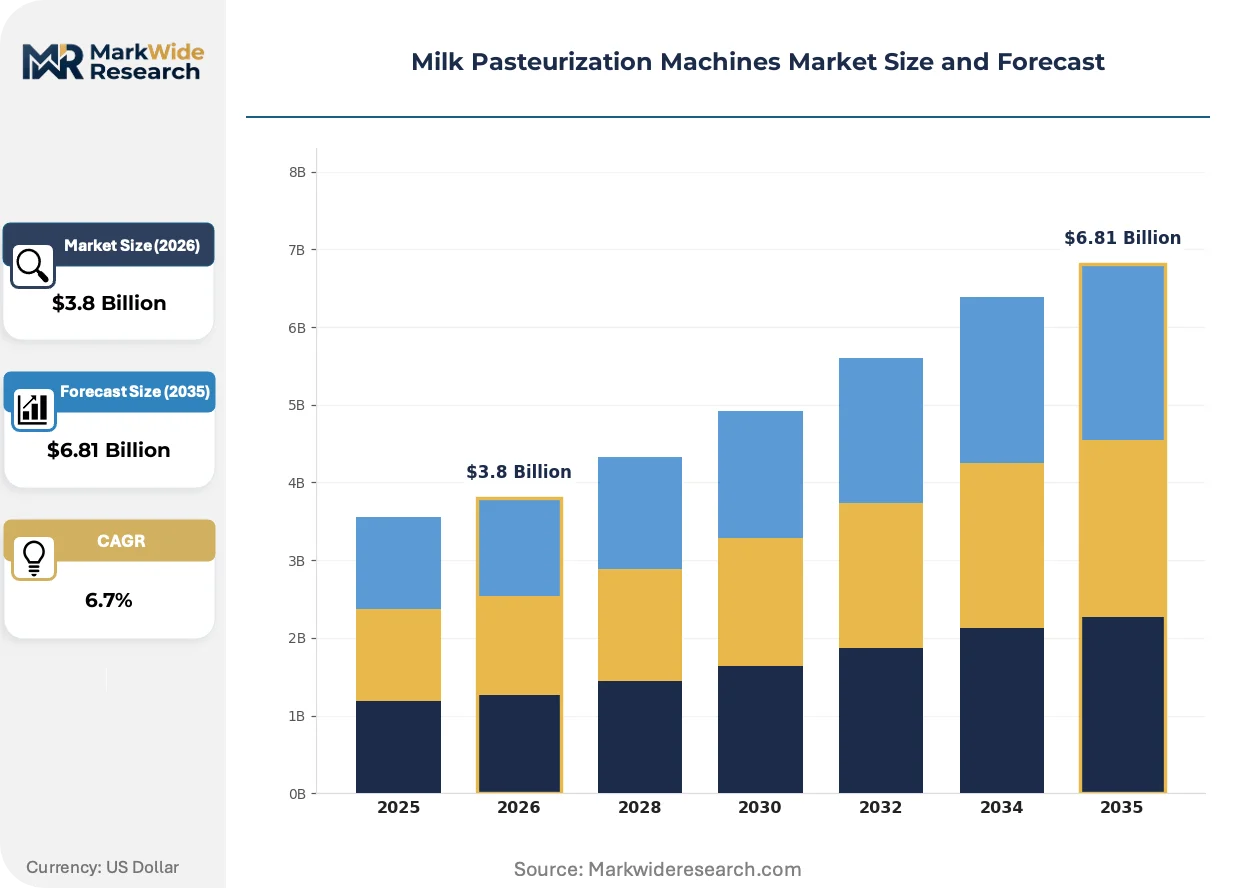
Market Dynamics
Modular skid architectures are collapsing the historical barrier between integrated system builders and component assemblers, enabling mid-scale dairy processors to access continuous pasteurization technology without captive engineering teams. This structural democratization is accelerating replacement cycles for aging batch vat systems across artisanal and regional operations.
Growth Catalysts
- EFSA Microbial Threshold Tightening:The European Union's Farm to Fork Strategy mandates stricter listeria and pathogen limits, forcing equipment upgrades across member state dairy cooperatives.
- High-Pressure Processing Maturation:Cold pasteurization technology extends shelf life without thermal whey protein degradation, attracting specialty fluid milk and functional dairy beverage producers.
- Bavarian Cooperative Modernization:Germany's dairy cluster is systematically replacing 1980s-era thermal systems with automated continuous pasteurizers to meet export certification requirements.
Market Restraints
- Stainless Steel Input Volatility:Grade 316L plate material for heat exchanger cores faces price swings tied to nickel and molybdenum commodity markets, compressing fabricator margins.
- Skilled Welder Scarcity:Sanitary orbital welding certification for dairy-grade CIP-compatible surfaces limits qualified labor pools in North American and European manufacturing hubs.
- Grid-Dependent Operating Costs:Thermal pasteurization systems face margin pressure from expanding carbon pricing mechanisms and electricity rate volatility in jurisdictions with aggressive decarbonization mandates.
Strategic Opportunities
- Artisanal Cheese Facility Automation:French and Italian PDO-certified creameries seek semi-automated batch systems with recipe flexibility for heritage cheese varieties.
- Energy Recovery Integration:Regenerative heat exchanger technology convergence with pasteurization skids offers 30-40% thermal efficiency gains for high-volume processors.
- India FSSAI Harmonization:The Food Safety and Standards Authority of India's alignment with Codex Alimentarius standards creates upgrade demand among organized dairy cooperatives in Gujarat and Punjab.
Industry Challenges
- Retrofit Integration Complexity:Legacy vat systems in Wisconsin and California dairies lack automated batch logging required by state inspectorates, demanding costly control system overhauls.
- Sanitary Welding Certification Timelines:ASME BPE and 3-A SSI compliance documentation for custom-fabricated equipment extends delivery lead times by 8-14 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Pasteurization Machines Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Pasteurizers, Continuous Pasteurizers, Plate Heat Exchangers, Tubular Pasteurizers Technology: Thermal Pasteurization, High-Pressure Processing, Microwave Pasteurization, Indirect Pasteurization End User: Dairy Processing Plants, Food Service Providers, Food Retailers, Restaurants Functionality: Cooling, Heating, Homogenization, Sterilization |
| Companies Covered | Tetra Pak International S.A., GEA Group AG, Alfa Laval AB, Krones AG, SPX FLOW, Dion Engineering, IMA Group, Della Toffola, Paul Mueller Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Pasteurization Machines Market Shifts & Advancements
Three distinct vectors are reshaping equipment design and procurement patterns in milk pasteurization: thermal technology substitution, regulatory data architecture mandates, and service model unbundling. Each trend carries specific implications for capital deployment and vendor selection.
Pulsed electric field pasteurization is supplanting conventional HTST thermal processing in niche functional beverage applications where protein denaturation must be minimized. European whey protein isolate manufacturers and North American extended-shelf-life fluid milk processors are piloting commercial-scale systems at 5,000-10,000 liter per hour throughput. This non-thermal approach compresses energy operating costs while enabling label claims around "minimally processed" positioning.
EFSA's evolving listeria monitoring protocols now require automated environmental sampling integration with pasteurization batch records, creating compliance architecture mandates. Equipment manufacturers must embed IoT-enabled temperature logging and cloud-based traceability modules to satisfy dairy inspectorates in France, Italy, and Germany. Small-to-mid scale processors in these jurisdictions face disproportionate engineering cost burdens relative to large integrated operators with captive IT infrastructure.
After-sales service unbundling is disrupting traditional bundled maintenance contracts among North American dairy cooperatives. Third-party specialized technicians certified by 3-A SSI and EHEDG are capturing preventive maintenance and CIP optimization work previously retained by original equipment manufacturers. This channel fragmentation is most visible in California's Central Valley, where independent service providers now handle 40% of plate heat exchanger re-gasketing and calibration work for aging installed bases.
Milk Pasteurization Machines Market Segmentation
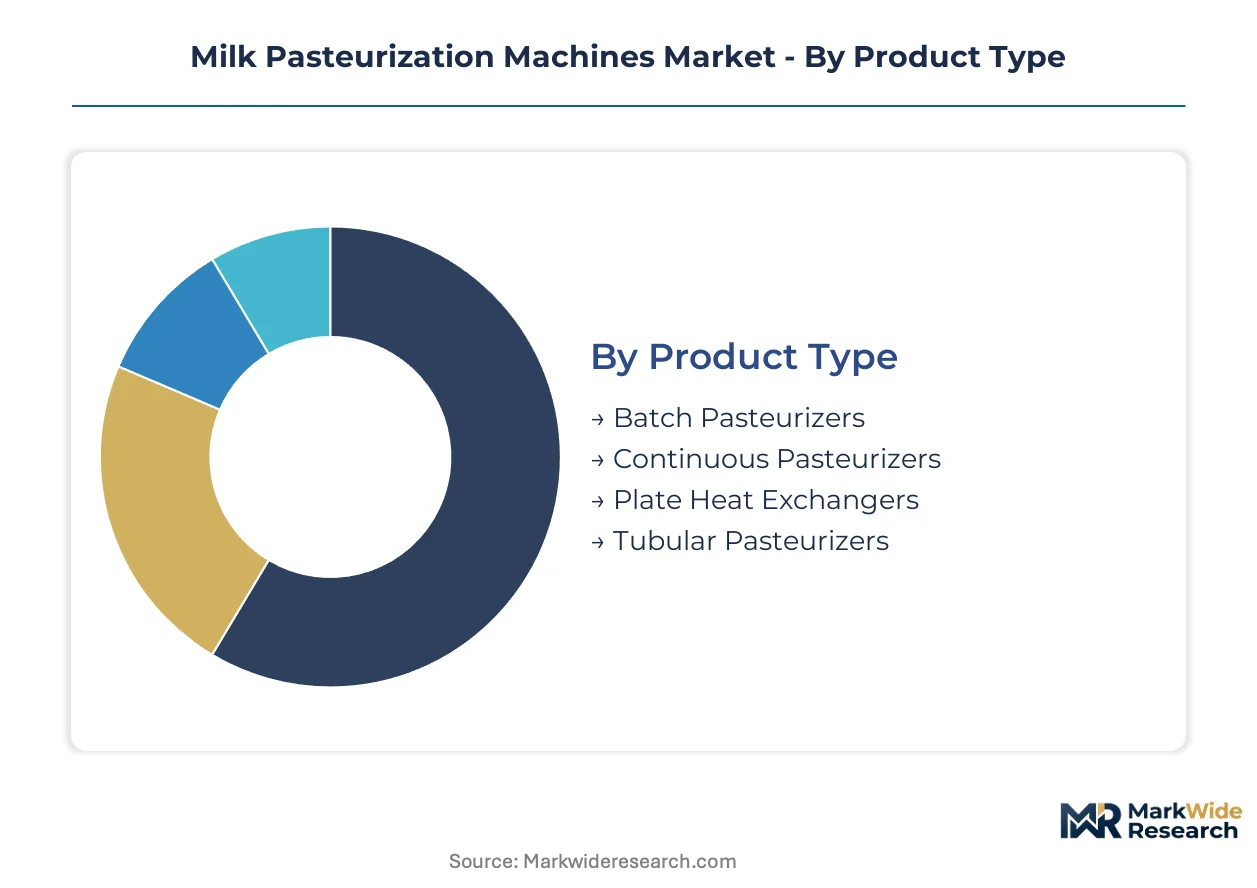
Equipment selection in milk pasteurization hinges on throughput scale, regulatory compliance architecture, and thermal efficiency targets. Segmentation reveals where high-pressure processing and modular continuous systems are displacing legacy batch configurations.
Product Type:
Continuous pasteurizers face the strongest substitution pressure from high-pressure processing systems in extended-shelf-life fluid milk applications, while batch configurations defend share in artisanal cheese operations.
- Batch Pasteurizers:Vat-style thermal systems heat discrete milk volumes to 63°C for 30-minute holding periods, suited for recipe-flexible operations. French and Italian PDO-certified creameries in Normandy and Lombardy specify these units for heritage cheese varieties where thermal profiles must vary by batch.
- Continuous Pasteurizers:HTST tunnel systems process 10,000+ liters hourly through plate heat exchanger arrays with 72°C/15-second protocols. Germany's Bavarian dairy cluster demands these for export certification compliance, replacing 1980s-era thermal infrastructure.
- Plate Heat Exchangers:Regenerative thermal transfer cores enable 30-40% energy recovery in high-volume lines. GEA Group and Alfa Laval dominate supply through captive manufacturing of Grade 316L stainless assemblies.
- Tubular Pasteurizers:Annular-channel designs handle viscous products and particulate-laden dairy beverages. Limited penetration outside whey protein concentrate and yogurt drink processing.
Continuous pasteurizers retain volume leadership; high-pressure processing holds the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive cold pasteurization from accessible thermal systems, with microwave variants occupying a narrow mid-market position.
- Thermal Pasteurization:Conventional HTST and vat methods using steam or hot water heating. FDA Pasteurized Milk Ordinance and EU MDR-equivalent standards lock in this technology for 80%+ of installed base due to regulatory familiarity and lower per-unit capital cost.
- High-Pressure Processing:Cold pasteurization at 600 MPa eliminates pathogens without whey protein denaturation. North American extended-shelf-life fluid milk processors and European whey isolate manufacturers pilot 5,000-10,000 liter per hour commercial systems.
- Microwave Pasteurization:Dielectric heating achieves rapid volumetric temperature rise. Niche adoption in small-batch organic dairy operations seeking energy efficiency gains over conventional steam systems.
- Indirect Pasteurization:Heat transfer through jacketed surfaces without direct steam injection. Preferred in clean-label positioning where "no direct steam contact" claims matter for premium fluid milk.
Thermal pasteurization dominates installed base; high-pressure processing climbs the fastest.
End User:
Application scale determines automation depth, with large integrated processors demanding full IoT-enabled traceability that food service operators rarely specify.
- Dairy Processing Plants:Large cooperatives and multinational operators running 24/7 continuous lines. EFSA's automated listeria logging mandates and batch traceability requirements drive control system upgrades across German, French, and Italian facilities.
- Food Service Providers:Institutional caterers and contract food manufacturers requiring mid-scale batch flexibility. California's Central Valley independent service providers now capture 40% of maintenance work previously retained by OEMs.
- Food Retailers:Private-label fluid milk processors and store-brand yogurt operations. Specifications emphasize CIP-compatible surfaces and rapid changeover between SKUs.
- Restaurants:Limited on-premise pasteurization for specialty ice cream and fresh cheese programs. Minimal equipment throughput, high labor intensity.
Dairy processing plants command the largest equipment volume; food service providers show the most rapid automation adoption.
Functionality:
Margin concentration follows energy recovery integration, where regenerative heating functions capture value from carbon pricing pressures.
- Heating:Precision temperature ramp to pasteurization setpoints with ±0.5°C control tolerance. Plate heat exchanger configurations dominate efficiency metrics in high-throughput German installations.
- Cooling:Rapid post-pasteurization chill to 4°C to arrest microbial activity and preserve sensory quality. Regenerative systems pre-cool using incoming raw milk, cutting refrigeration load.
- Homogenization:High-pressure valve disruption of fat globules to prevent cream separation. Often integrated downstream of pasteurization in extended-shelf-life fluid milk lines.
- Sterilization:Ultra-high-temperature processing at 135-150°C for aseptic packaging compatibility. Tetra Pak bundles this function with downstream filling equipment in turnkey contracts.
Heating and cooling functions anchor system value; energy recovery integration delivers the fastest payback improvement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European dairy processors deploy continuous pasteurization for export certification while Indian cooperatives favor batch systems for buffalo milk variability. This consumption-mix differential shapes equipment specification patterns across major dairy economies.
Germany
Bavarian cooperatives modernize 1980s-era thermal infrastructure to meet EFSA's tightened microbial thresholds under the Farm to Fork Strategy. The country's dairy cluster around Munich and Nuremberg demands automated continuous pasteurizers with full batch traceability for export certification to Asian markets.
United States
Wisconsin and California state inspectorates mandate automated logging capabilities that aging vat systems cannot provide, forcing control system overhauls. FDA pasteurized milk ordinances lock in thermal pasteurization standards while carbon pricing pressures in California drive energy recovery retrofits across Central Valley processing plants.
France
Normandy PDO-certified creameries seek semi-automated batch pasteurizers with recipe flexibility for heritage cheese varieties. ANSM and EFSA compliance documentation extends equipment delivery timelines, favoring established fabricators with captive sanitary welding certification over new entrants.
India
Gujarat and Punjab organized dairy cooperatives upgrade facilities as FSSAI harmonizes with Codex Alimentarius standards. Buffalo milk's higher fat content and seasonal volume variability favors batch pasteurization configurations over continuous systems in most sub-regional processing plants.
Italy
Lombardy and Emilia-Romagna artisanal cheese facilities expand automated pasteurization capacity to meet Protected Designation of Origin standards. Regional equipment demand concentrates on flexible batch systems capable of handling multiple heritage cheese thermal profiles within single production facilities.
Milk Pasteurization Machines Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in milk pasteurization equipment supply. The upper tier bundles pasteurization with downstream packaging and filling lines, capturing long-term service contracts through turnkey project structures. Specialist fabricators compete on custom batch configurations for artisanal creameries and regional cooperatives. Two dominant competitive moves define current positioning: captive supply of heat exchanger cores to control margin capture, and modular skid architectures that collapse historical barriers between integrated builders and component assemblers.
Among European-based integrated system builders, Tetra Pak International S.A. and GEA Group AG exemplify contrasting archetypes. Tetra Pak occupies a position bundling pasteurization with aseptic packaging ecosystems, while GEA Group anchors its presence through captive manufacturing of plate heat exchanger cores. Alfa Laval AB represents the energy recovery efficiency vector in high-volume continuous systems. These three names illustrate how geographic origin and corporate structure map to distinct competitive positioning in thermal processing equipment supply.
| Leading Market Players |
|---|
| Tetra Pak International S.A. |
| GEA Group AG |
| Alfa Laval AB |
| Krones AG |
| SPX FLOW |
| Dion Engineering |
| IMA Group |
| Della Toffola |
| Paul Mueller Company |
| Others |
Supply & Pricing Matrix
Capacity utilization at German and Danish heat exchanger foundries shapes margin structures across the equipment value chain, concentrating pricing power among integrated builders with captive plate manufacturing while forcing component assemblers toward modular skid strategies to defend price floors.
Pricing Analysis
After-sales service revenue from plate re-gasketing, calibration contracts, and spare parts distribution drives lifetime customer value beyond initial equipment sales. Equipment pricing stratifies across premium certified systems with full 3-A SSI documentation, mid-tier modular skids for regional cooperatives, and economy batch units for small artisanal creameries. Cost compression in the economy tier intensifies because stainless steel input volatility and skilled welder scarcity squeeze fabricator margins. Food service providers in California's Central Valley exhibit the highest price sensitivity, whereas large Bavarian dairy cooperatives prioritize energy recovery efficiency and traceability compliance over capital cost.
Supply Chain Analysis
Strategic stockpiling of Grade 316L stainless steel plate dominates inventory strategy among heat exchanger core manufacturers, buffering against nickel and molybdenum commodity swings that disrupt just-in-time fabrication schedules. Manufacturing concentration rests on Germany, Denmark, and Italy for precision plate heat exchanger assemblies, with secondary fabrication spreading to Poland and Czech Republic for standardized skid components. Supply chain risk centers on single-source vulnerability for sanitary orbital welding certification, where qualified labor pools in North American and European hubs constrain expansion capacity. Distribution runs through OEM-direct channels for large integrated processors and specialized dairy equipment distributors for mid-scale regional operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
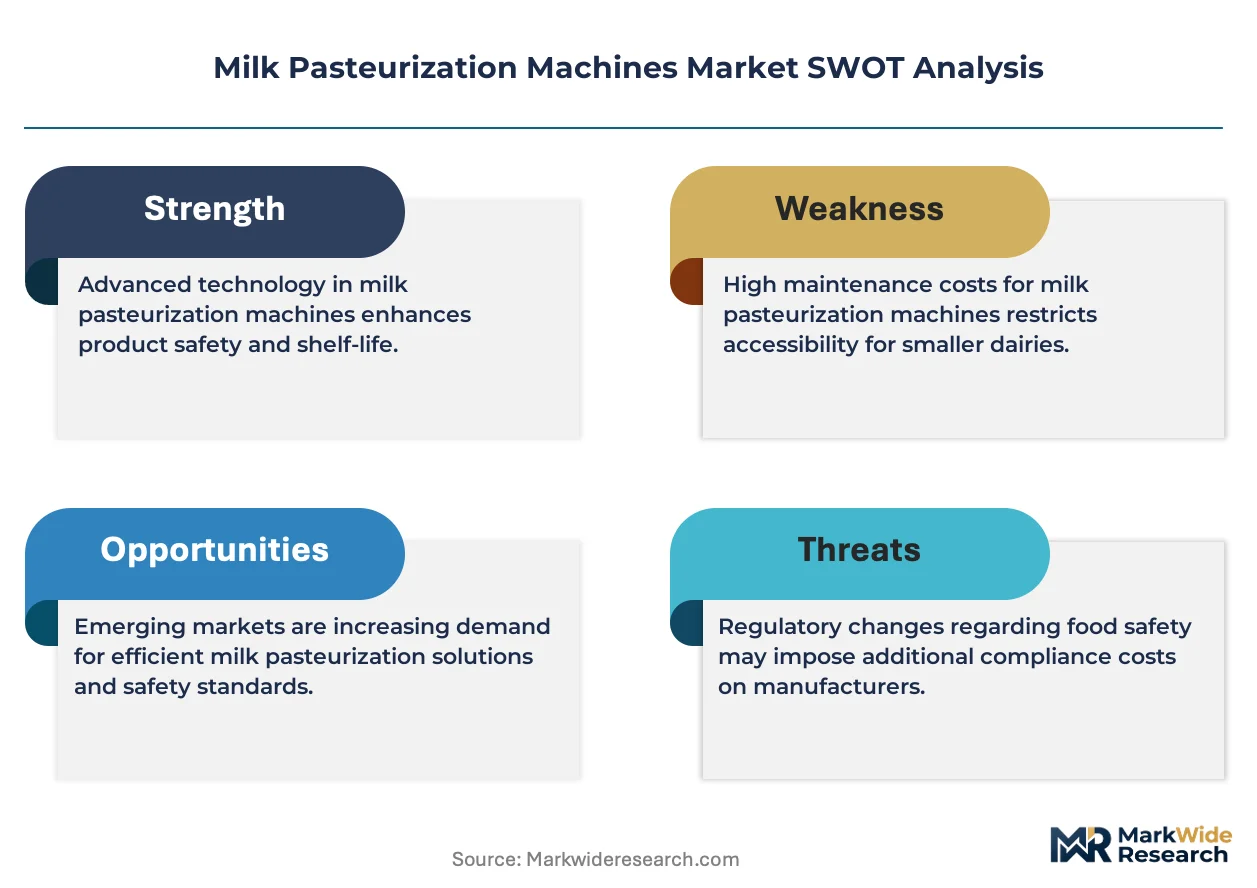
This market functions as a defensive-moat story anchored in regulatory entrenchment, where EFSA compliance documentation and 3-A SSI certification timelines create barriers that compound over successive replacement cycles.
For Market Incumbents: Compound captive supply advantages in heat exchanger core manufacturing to lock in margin capture against modular skid entrants. Expand automated logging and IoT-enabled traceability modules ahead of EFSA's evolving listeria monitoring protocols, which will force costly control system overhauls on competitors with legacy installed bases. Prioritize energy recovery integration partnerships to capture carbon pricing-driven retrofit demand across California and German processing clusters. For New Entrants and Emerging Players: EHEDG certification fast-track programs offer entry pathways into French and Italian PDO-certified creamery segments where semi-automated batch flexibility commands premium positioning. Target India's Gujarat and Punjab organized dairy cooperatives during FSSAI harmonization with Codex Alimentarius standards, where buffalo milk variability favors batch configurations that incumbent continuous-system builders underserve. Pursue independent service provider partnerships in California's Central Valley to capture the 40% maintenance market share already fragmenting away from OEM bundled contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized fabricators with sanitary welding certification depth over diversified industrial conglomerates. The five-to-ten year viability window rewards acquisition targets holding captive plate heat exchanger manufacturing and established 3-A SSI documentation capabilities. Watch for inflection when high-pressure processing pilot systems achieve commercial scale validation at 10,000 liter per hour throughput, signaling substitution pressure on thermal pasteurization's regulatory lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Core Manufacturing | Captures margin from Grade 316L plate supply and insulates against nickel price volatility. |
| IoT-Enabled Traceability Module Development | Locks in long-term service contracts as EFSA mandates automated batch logging across member states. |
| High-Pressure Processing Pilot Scale-Up | Positions for cold pasteurization substitution in extended-shelf-life fluid milk segments. |
| Independent Service Network Expansion | Captures maintenance revenue fragmenting from OEMs in California's Central Valley dairy cluster. |
| EHEDG Certification Fast-Track Investment | Accelerates entry into French and Italian PDO-certified artisanal cheese facility upgrades. |
Research Methodology
A spread of perspectives from dairy processing plant engineers, equipment procurement managers at Bavarian cooperatives, aftermarket service technicians, and regulatory affairs specialists at EFSA-aligned inspectorates converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through equipment shipment customs records, 3-A SSI certification databases, and SEC filings from publicly traded thermal processing equipment manufacturers. Bottom-up unit economics from individual dairy processing facilities triangulated against top-down capacity estimates from national dairy federation statistics.
Segmentation dimensions modeled include pasteurizer configuration type, thermal versus non-thermal technology, end-user scale tier, and energy recovery integration level across the analysis window. CAGRs were derived from installed base replacement cycle analysis, export certification demand trajectories, and carbon pricing mechanism expansion scenarios. Forecast inputs incorporated stainless steel commodity price elasticity, skilled welder certification pipeline constraints, and FSSAI regulatory harmonization timelines for Indian cooperative modernization.
Underlying assumptions cover EFSA microbial threshold enforcement continuity, nickel price band stability, and carbon pricing mechanism geographic expansion, with deviation risk concentrated in high-pressure processing technology maturation acceleration. Forecasts reflect these documented assumptions with explicit sensitivity testing. Revision becomes warranted when cold pasteurization throughput validation crosses commercial-scale thresholds or when sanitary welding certification backlogs exceed sixteen-week delivery extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Commercial Milkshake Machine Market
Dairy Processing Machinery
Electric Milkshake Machine Market
Dairy Processing Machinery
Cheese Liners Market
Dairy Processing Machinery
Modified Milk Powder Market
Dairy Processing Machinery
Cream Separator Market
Dairy Processing Machinery
Milk Processing Systems Market
Dairy Processing Machinery
Milk Chiller Market
Dairy Processing Machinery
Dairy Machines Market
Dairy Processing Machinery
Dairy Filtration Systems Market
Dairy Processing Machinery
Concentrated Whey Market
Dairy Processing Machinery
Cheese Cutting Machine Market
Dairy Processing Machinery
Milk Clarifier Market
Dairy Processing Machinery
Dairy Processing Equipment Market
Dairy Processing Machinery
Dairy Products Membrane Filtration Equipment Market
Dairy Processing Machinery
Milk Homogenizer Machine Market
Dairy Processing Machinery
Yogurt Cup Market