
 India Soy Beverages Market | 2026-2036
India Soy Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
India Soy Beverages Market Foresight
Subscription-based replenishment models for soy milk cartons is repositioning how brands secure recurring revenue in Indian metros. Nestle India Ltd leverages its cold-chain infrastructure to dominate modern trade shelf space. Life Health Foods India Private Limited anchors its portfolio in health-food shop channels with specialized positioning. Soyaam Food differentiates through regional flavor profiles tailored to South Indian palates.
Soy beverages comprise aqueous extracts of dehulled soybeans, typically standardized to 2.5-3.5% protein and 1.5-2% lipid content, processed via ultra-high temperature treatment and aseptic packaging to deliver shelf-stable plant-based nutrition for direct consumption and foodservice blending. Flavored soy milk leads volume contribution as vanilla and chocolate variants capture younger demographics, while soy protein drinks represent the fastest-growing category among health club subscribers seeking post-workout recovery. Plain soy milk retains mature household penetration but faces margin compression from private-label competition in supermarket channels.
FSSAI fortification mandates and BIS beverage quality standards shape product formulation requirements, compelling manufacturers to align micronutrient claims with approved thresholds. The Food Safety and Standards Authority of India enforces label integrity for protein content declarations, while state-level food safety commissioners conduct periodic market surveillance. Stakeholders must monitor evolving PLI scheme eligibility for plant-based foods and anticipate whether export-oriented units will redirect capacity toward Middle East markets.
Market Dynamics
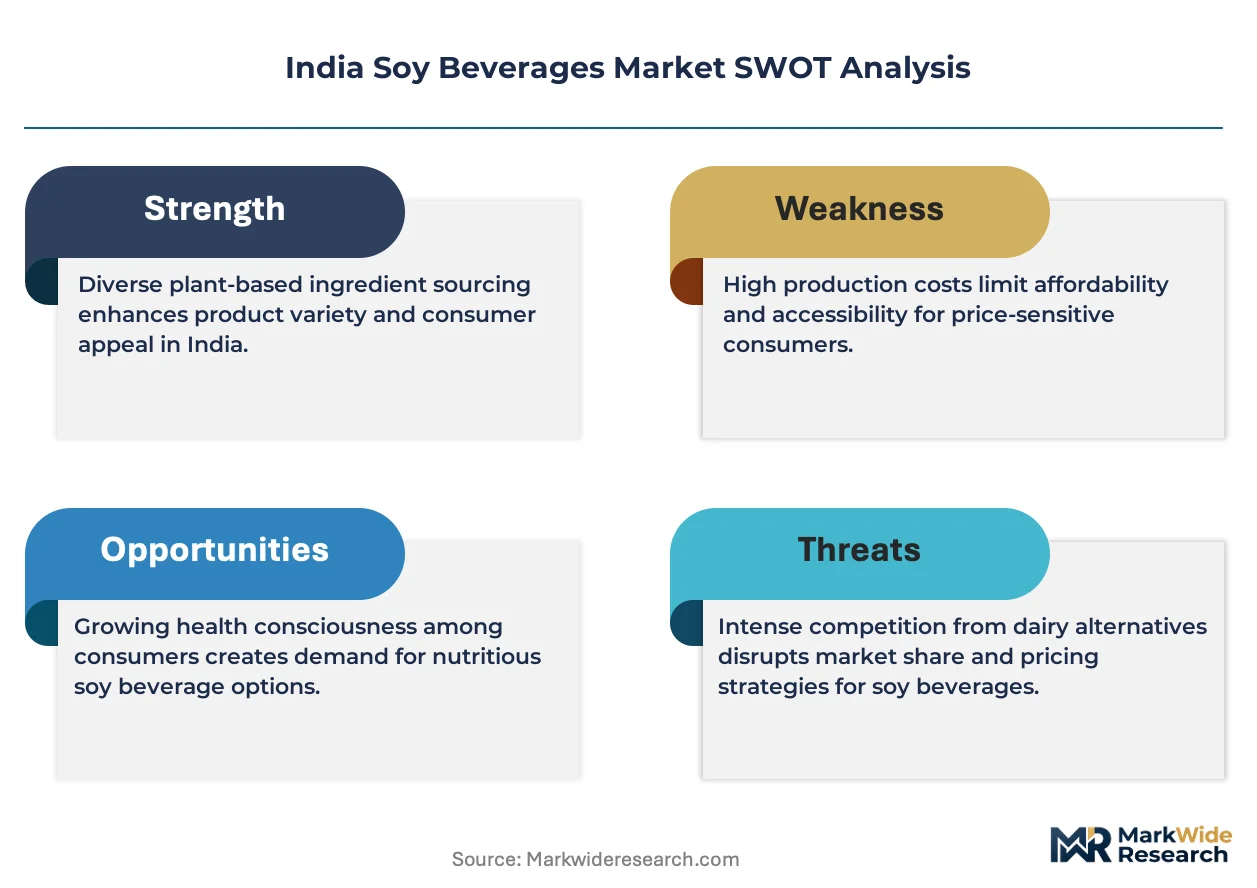
FSSAI fortification mandates are compressing formulation flexibility while simultaneously opening premium positioning for compliant manufacturers who can absorb micronutrient standardization costs faster than regional processors.
Growth Catalysts
- Urban Household Consumption Clusters:Mumbai and Bangalore households are driving flavored variant adoption through modern retail penetration, creating density economics for cold-chain dependent distribution.
- PLI Scheme Eligibility:India's Production Linked Incentive scheme for plant-based foods is redirecting capital toward aseptic packaging capacity expansion and protein standardization infrastructure.
- Post-Workout Recovery Demand:Health club subscribers in Maharashtra and Karnataka are accelerating soy protein drink consumption, pulling volume through specialized nutrition channels.
Market Restraints
- Input Cost Volatility:Dehulled soybean prices fluctuate with monsoon-dependent domestic harvests and import parity from Argentina, squeezing margin buffers for non-integrated processors.
- Private-Label Compression:Supermarket chains in Karnataka are capturing plain soy milk volume through captive label programs, eroding branded household penetration.
- BIS Certification Timeline:Bureau of Indian Standards beverage quality testing creates 4-6 month product launch delays for new entrants lacking established laboratory relationships.
Strategic Opportunities
- Regional Flavor Localization:South Indian palate-specific variants using cardamom and saffron profiles remain underdeveloped in Tamil Nadu and Kerala modern trade.
- Subscription Replenishment Models:Direct-to-home carton delivery is capturing recurring revenue in Bangalore gated communities, bypassing traditional retail slotting fees.
- Export Capacity Pivot:Middle East markets with large South Asian diaspora populations present offtake potential for FSSAI-certified manufacturers facing domestic margin pressure.
Industry Challenges
- Aseptic Technician Scarcity:Ultra-high temperature processing specialists command premium wages in Maharashtra, constraining line utilization rates for second-tier manufacturers.
- Cold-Chain Capex Intensity:Shelf-stable soy milk requires refrigerated distribution for quality maintenance, demanding fleet investment that fragments working capital across smaller players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Soy Beverages Market |
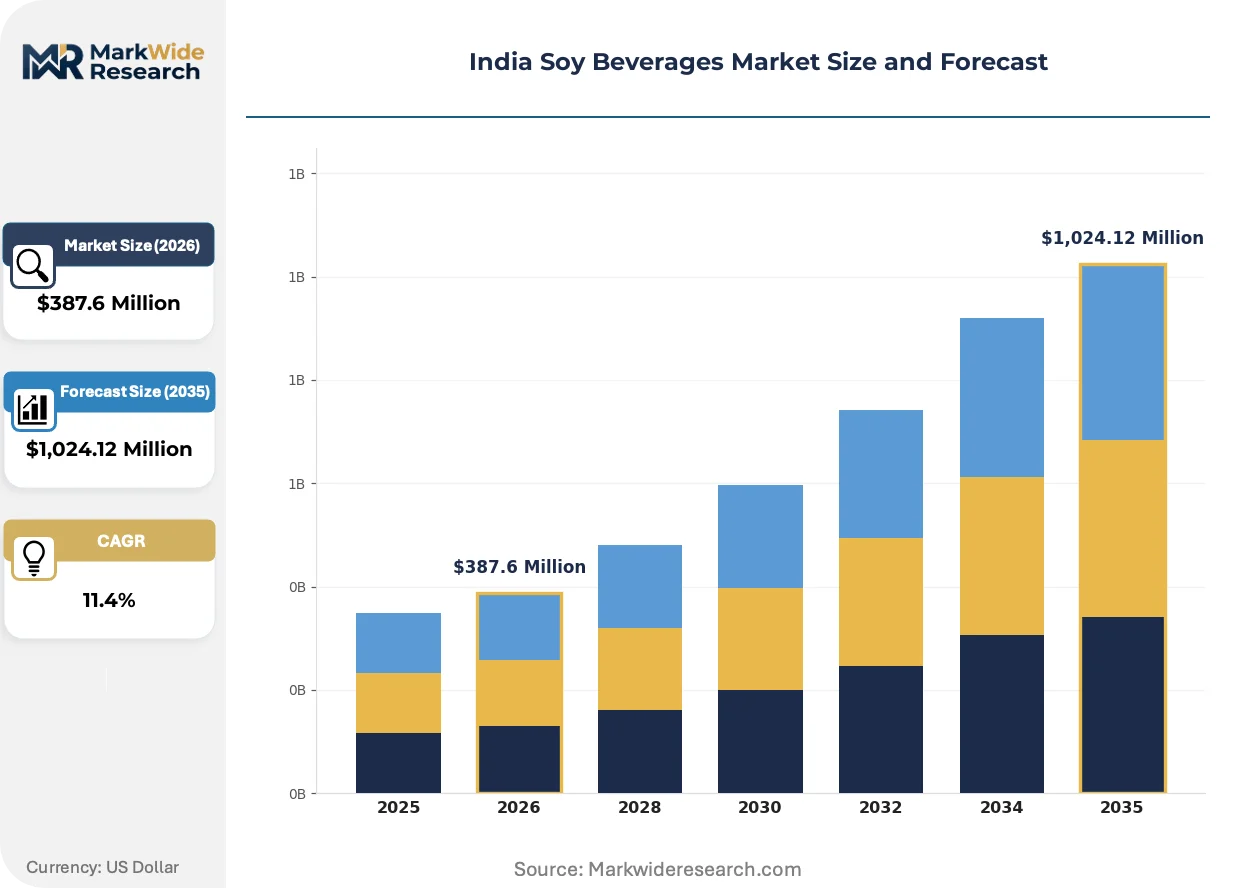
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain Soy Milk, Flavored Soy Milk, Soy Yoghurt, Soy Protein Drinks End User: Households, Cafes, Restaurants, Health Clubs Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Shops Packaging Type: Cartons, Bottles, Tetra Packs, Pouches |
| Companies Covered | Chetran Foods Private Limited, Soyaam Food, The Hershey Company, Pacific Foods of Oregon LLC, Midas Soy Nutritions, Life Health Foods India Private Limited, Invigorate Foods Pvt Ltd, Sanitarium Health and Wellbeing Company, Nestle India Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Soy Beverages Market Shifts & Advancements
Protein standardization technology and channel restructuring are compressing traditional value capture models while enabling new entrants to bypass incumbent shelf dominance through direct distribution.
Enzymatic protein extraction is electrifying yield efficiency in soybean processing, enabling 3.5% protein standardization with reduced thermal degradation. Mid-tier manufacturers in Maharashtra are adopting membrane filtration systems at accelerated pace. This technology is electrifying cost structures for processors previously dependent on imported protein isolates.
FSSAI label integrity enforcement for protein content declarations is tightening micronutrient claim thresholds across all packaged soy beverages. State food safety commissioners in Karnataka and Maharashtra have intensified market surveillance sampling. Flavored soy milk variants with functional positioning face the steepest compliance recalibration.
Health-food shop channel specialization is displacing supermarket dependency for premium soy protein drinks. Life Health Foods India Private Limited anchors this positioning, while Nestle India Ltd defends modern trade through cold-chain infrastructure leverage. Bangalore health club proximate retail captures the highest per-liter realization for post-workout formulations.
India Soy Beverages Market Segmentation
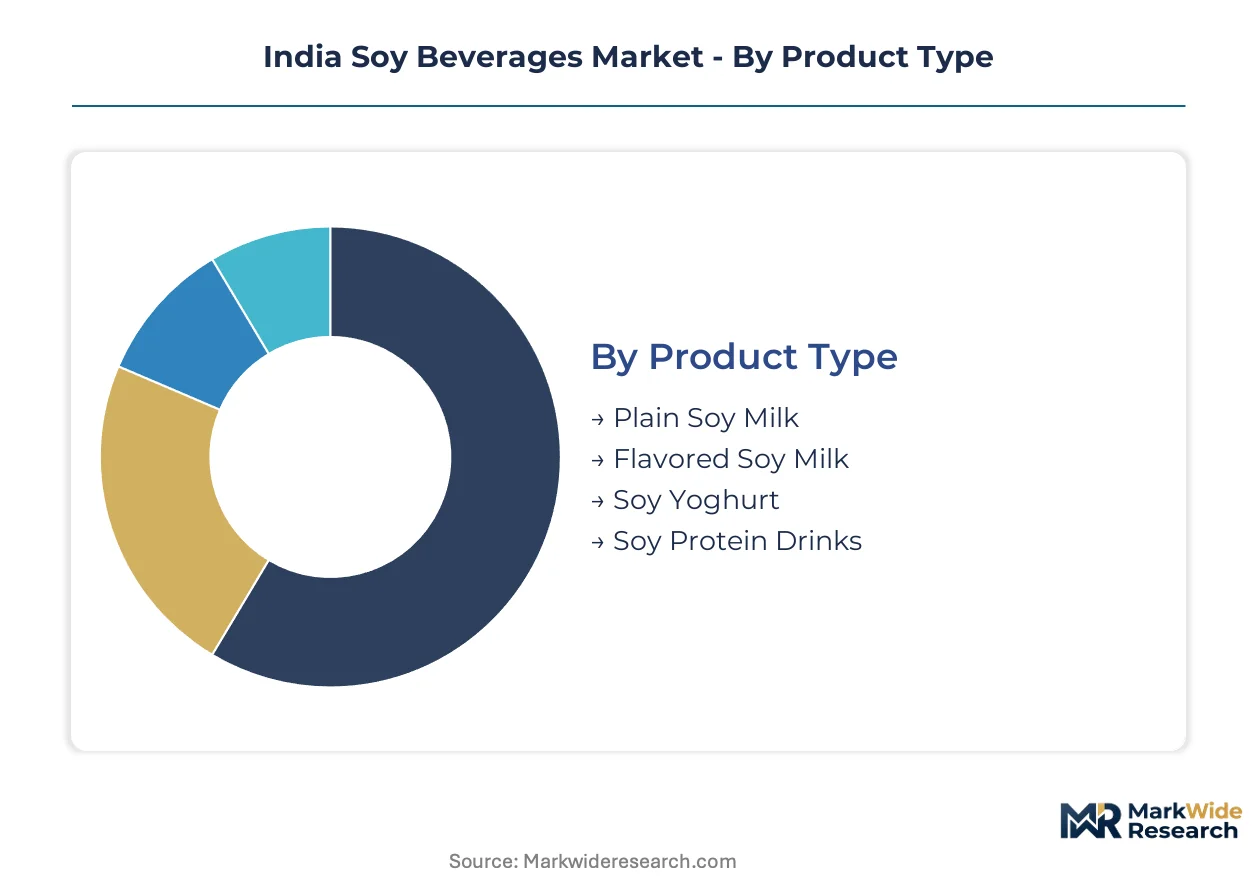
Soy beverage segmentation in India reflects divergent technical requirements across processing methods, consumption occasions, and cold-chain dependencies. Manufacturers configure production lines around protein standardization levels and aseptic packaging formats rather than pursuing universal platforms.
Product Type:
Protein concentration and thermal processing intensity separate product tiers, with formulation flexibility tightening under FSSAI fortification mandates.
- Plain Soy Milk:Aqueous extract standardized to 2.5-3.5% protein content, processed through ultra-high temperature treatment and aseptic packaging for shelf stability. Maharashtra and Karnataka households sustain volume through modern retail penetration, though margin compression from private-label competition is eroding branded positioning.
- Flavored Soy Milk:Vanilla and chocolate variants targeting younger demographics with added sweetness and flavor masking systems. Mumbai and Bangalore urban clusters are driving adoption density, pulling volume through cold-chain dependent supermarket channels.
- Soy Yoghurt:Fermented soy base requiring refrigerated distribution throughout the supply chain. Tamil Nadu and Kerala modern trade shows underdeveloped penetration relative to dairy alternatives.
- Soy Protein Drinks:Higher protein fortification targeting post-workout recovery occasions. Health club subscribers in Maharashtra and Karnataka are accelerating consumption through specialized nutrition channels.
Plain soy milk leads on scale; soy protein drinks lead on momentum.
End User:
Consumption occasion fragmentation is forcing channel-specific formulation strategies with divergent price-realization profiles.
- Households:Recurring carton replenishment in gated communities, with subscription models capturing Bangalore density economics. FSSAI label integrity enforcement shapes protein claim thresholds for family-oriented packaging.
- Cafes:Barista-grade frothing performance requirements favor higher lipid content formulations. Mumbai café chains are standardizing soy milk as default dairy alternative.
- Restaurants:Foodservice blending applications demanding neutral flavor profiles for recipe integration. Karnataka restaurant procurement is shifting toward bulk aseptic bag-in-box formats.
- Health Clubs:Post-workout recovery positioning commands premium per-liter realization. Bangalore health club proximate retail captures the highest margins for functional formulations.
Households anchor volume contribution; health clubs expand most quickly.
Distribution Channel:
Cold-chain infrastructure availability and slotting fee structures determine channel economics across metro versus non-metro deployment.
- Supermarkets:Karnataka chains are capturing plain soy milk volume through private-label programs, compressing branded shelf space. Refrigerated display requirements fragment working capital for second-tier manufacturers.
- Online Retail:Direct-to-home carton delivery bypasses traditional retail slotting fees in Bangalore gated communities. Subscription replenishment models are securing recurring revenue streams.
- Convenience Stores:Impulse-oriented single-serve packaging with limited refrigerated facings. Maharashtra urban density supports viable route economics.
- Health Food Shops:Specialized channel anchoring premium soy protein drinks with highest per-liter realization. Life Health Foods India Private Limited dominates this positioning.
Supermarkets concentrate volume throughput; health food shops command margin premiums.
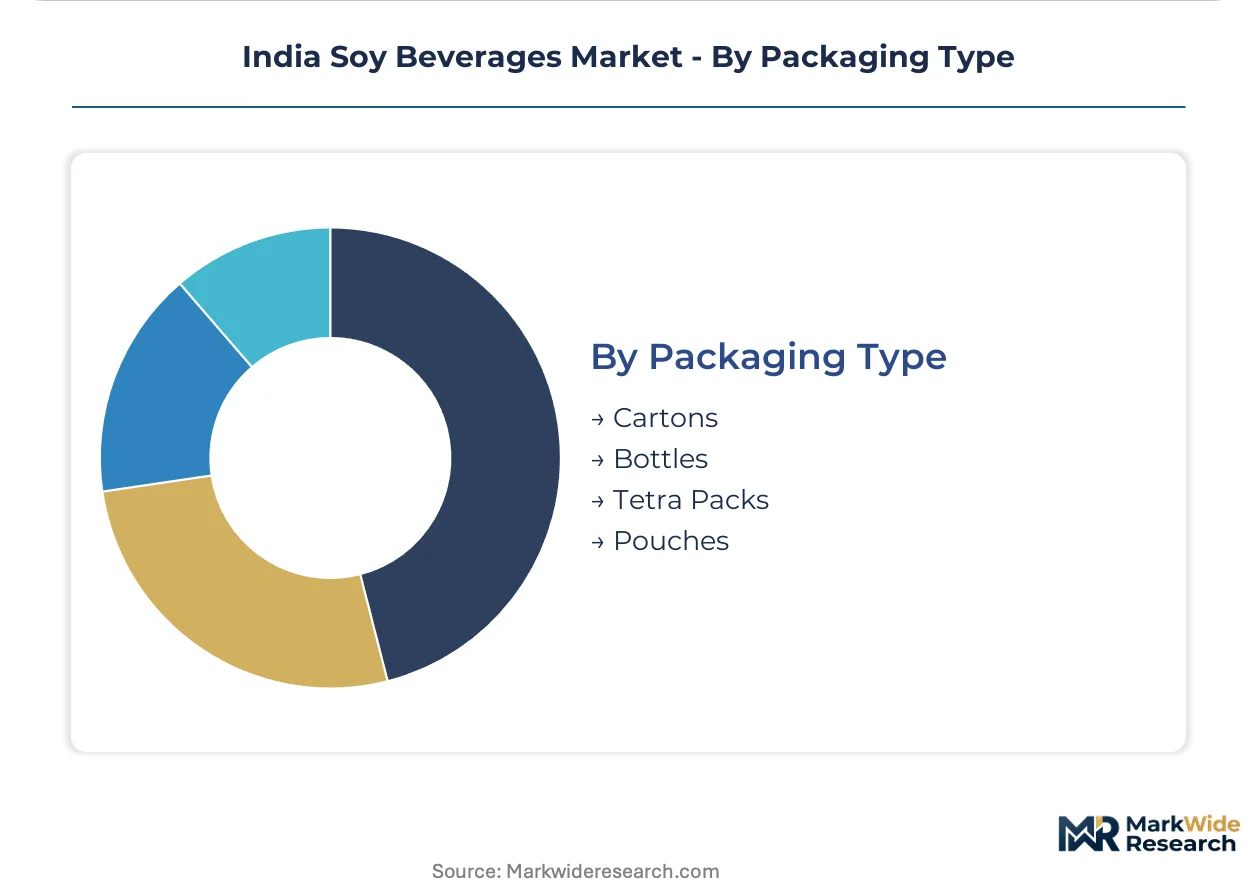
Packaging Type:
Aseptic technology investment and recycling infrastructure shape format selection across shelf-stable versus chilled product lines.
- Cartons:Aseptic brick packs dominating household subscription models with extended ambient shelf life. Bangalore gated community delivery networks favor this format.
- Bottles:Refrigerated distribution requirement constraining penetration to cold-chain equipped metros. Visual transparency supports premium positioning.
- Tetra Packs:Established aseptic platform with proven recycling infrastructure in Maharashtra and Karnataka. Standard for flavored variants.
- Pouches:Lowest unit cost format for price-sensitive plain soy milk segments. Limited to short shelf-life chilled distribution.
Tetra packs hold installed base dominance; cartons gain share fastest through subscription channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's soy beverage demand concentrates in western and southern states where modern retail infrastructure penetrates deepest, contrasting with northern markets where dairy alternatives dominate household consumption patterns.
Maharashtra
Mumbai households drive flavored soy milk adoption through supermarket channels, while health club subscribers in Pune accelerate protein drink consumption. FSSAI fortification mandates shape product formulations for manufacturers operating in this state. The Mumbai-Pune industrial corridor hosts aseptic packaging facilities serving western India distribution networks.
Karnataka
Bangalore gated communities sustain subscription-based carton replenishment models, bypassing traditional retail economics. BIS beverage quality standards create compliance timelines that favor established processors with laboratory relationships. The city's health-food shop channel captures premium realization for functional soy protein formulations targeting post-workout recovery.
Tamil Nadu
Chennai's café culture standardizes soy milk as default dairy alternative, pulling barista-grade formulations through foodservice channels. State food safety commissioners intensify market surveillance sampling for protein content declarations. Soy yoghurt penetration lags dairy alternatives in modern trade, presenting localization opportunities for fermented variants.
Gujarat
Surat and Ahmedabad processors benefit from proximity to domestic soybean cultivation zones, reducing input cost volatility for dehulled raw material. PLI scheme eligibility redirects capital toward protein standardization infrastructure in this region. The state's chemical processing heritage supports membrane filtration technology adoption for yield efficiency gains.
Delhi-NCR
National Capital Region households exhibit price sensitivity that favors pouch-format plain soy milk through convenience store channels. FSSAI label integrity enforcement tightens micronutrient claim thresholds for family-oriented packaging. Cold-chain capex intensity fragments working capital for second-tier manufacturers attempting metro penetration.
India Soy Beverages Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated beverage conglomerates defending modern trade shelf space while regional processors capture price-sensitive volume through alternative channels. Market structure tilts toward consolidation at the premium tier and fragmentation in plain soy milk segments. Three archetypes dominate: cold-chain infrastructure leveraged multinationals, health-food channel specialists, and regional flavor localizers. Competitive moves concentrate on subscription model deployment and aseptic capacity expansion.
Among India-based health-food specialists, Life Health Foods India Private Limited anchors premium positioning through specialized retail channels, while Soyaam Food exemplifies regional flavor adaptation for South Indian palate profiles. Nestle India Ltd occupies the scale-driven multinational tier, leveraging established distribution infrastructure. These three represent distinct competitive vectors: channel specialization, geographic customization, and operational scale.
| Leading Market Players |
|---|
| Chetran Foods Private Limited |
| Soyaam Food |
| The Hershey Company |
| Pacific Foods of Oregon LLC |
| Midas Soy Nutritions |
| Life Health Foods India Private Limited |
| Invigorate Foods Pvt Ltd |
| Sanitarium Health and Wellbeing Company |
| Nestle India Ltd |
| Others |
Supply & Pricing Matrix
Membrane filtration technology adoption in Maharashtra and Gujarat is simultaneously compressing protein extraction costs and concentrating processing capacity among manufacturers with capital for yield-enhancing equipment. This technological shift redraws competitive economics between integrated processors and regional toll manufacturers dependent on imported isolates.
Pricing Analysis
Capacity additions in Karnataka and Maharashtra are reshaping price floors for aseptic soy milk as new entrants absorb micronutrient standardization costs faster than legacy processors. Three-tier pricing structure across premium functional formulations, standard fortified variants, and economy plain segments stratifies the market. Pricing pressure stems from private-label programs in Karnataka supermarket chains compressing branded household margins. Health club subscribers exhibit lowest price sensitivity for post-workout recovery formulations, while Delhi-NCR households drive volume through pouch-format economy tiers.
Supply Chain Analysis
Reverse logistics for aseptic carton collection and recycling infrastructure remains underdeveloped in Tamil Nadu and Kerala, constraining closed-loop packaging economics for sustainability-positioned brands. Domestic soybean cultivation in Madhya Pradesh and Maharashtra supplies dehulled raw material, though processors draw from Argentine import parity during monsoon shortfalls. Single-source vulnerability concentrates in cold-chain fleet operators serving Bangalore and Mumbai distribution networks. Distribution runs through modern retail chains in western and southern states, with direct-to-home subscription models bypassing traditional slotting fees in gated communities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India soy beverages market reads as a late-cycle quality story where FSSAI fortification mandates and BIS certification requirements filter out subscale processors, concentrating returns among compliant manufacturers with laboratory relationships and cold-chain infrastructure.
For Market Incumbents: To counter private-label compression in Karnataka supermarket channels, Nestle India Ltd and integrated processors should deepen backward integration into Madhya Pradesh soybean cultivation zones while securing exclusive health-food shop shelf space through specialized protein drink formulations. Certification investment in FSSAI-compliant micronutrient standardization infrastructure creates defensive moats against regional toll manufacturers lacking laboratory scale. For New Entrants and Emerging Players: The price-point gap between premium Bangalore health club formulations and economy Delhi-NCR pouch segments offers white-space entry for mid-tier processors with membrane filtration capacity. Tamil Nadu and Kerala modern trade shows underdeveloped soy yoghurt penetration relative to dairy alternatives. Subscription replenishment models in Bangalore gated communities provide direct-to-home go-to-market angles bypassing incumbent retail slotting dominance. For Investors and Strategic Acquirers: Valuations sit cheapest among regional processors with aseptic packaging lines but underutilized protein standardization capacity. Long-term viability across the projection horizon hinges on PLI scheme eligibility for plant-based foods redirecting capital toward export-oriented units. Acquisition targets should screen for FSSAI laboratory relationships and Maharashtra cold-chain fleet access. The signal to watch is Middle East offtake agreements for FSSAI-certified manufacturers as domestic margin pressure intensifies.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Capacity Expansion | PLI scheme eligibility in Gujarat redirects investment toward protein standardization infrastructure. |
| Regional Flavor Localization | Cardamom and saffron profiles for Tamil Nadu and Kerala modern trade capture underdeveloped palate segments. |
| Subscription Model Deployment | Bangalore gated community delivery networks secure recurring revenue streams bypassing retail slotting fees. |
| Export Capacity Pivot | Middle East markets with South Asian diaspora populations absorb FSSAI-certified manufacturer output. |
| Health-Food Channel Specialization | Premium soy protein drinks through specialized retail capture highest per-liter realization in Maharashtra. |
Research Methodology
Bottom-up household consumption modeling reconciled against top-down aseptic packaging capacity tracking forms the analytical core of this study. Primary interviews with FSSAI compliance officers, modern trade category buyers in Karnataka and Maharashtra, health-food shop proprietors in Bangalore, and soybean procurement managers at integrated processors were cross-validated against secondary sources including FSSAI fortification guidelines, BIS beverage quality standards, PLI scheme notifications, and state-level food safety commissioner surveillance reports.
Input-output matrices mapping dehulled soybean supply from Madhya Pradesh cultivation zones through Maharashtra and Gujarat processing facilities to regional distribution networks anchor the forecast framework. Segmentation dimensions span product type, end-user occasion, distribution channel, and packaging format, with protein standardization technology adoption curves modeled across the analysis window. CAGRs derive from reconciling bottom-up consumption density in Mumbai and Bangalore urban clusters against top-down aseptic line utilization rates and cold-chain fleet expansion plans.
Caveats apply where monsoon-dependent domestic harvest volatility, BIS certification timeline extensions, or PLI scheme eligibility revisions could materially shift the outlook. Forecasts reflect assumptions about FSSAI enforcement intensity and health club subscriber growth in western and southern states. Practitioners should monitor Argentine import parity pricing and Middle East export offtake negotiations for early signals of margin compression or capacity redirection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Double Valve Moka Pots Market
Beverages
Hydration Infusers Market
Beverages
Milk Tea Powder Market
Beverages
Smoothies Market
Beverages
Coconut Water Market
Beverages
Europe Beverage Market
Beverages
Craft Soda Market
Beverages
United Kingdom Energy Drink Market
Beverages
Extra Neutral Alcohol (ENA) Market
Beverages
Sports and Energy Drinks Market
Beverages
Crystal Boba Market
Beverages
Fruit Water Market
Beverages
Asia Pacific Fruits and Vegetables Juice Market
Beverages
India Cafes & Bars Market
Beverages
Canned Beverages Market
Beverages
Ginger Beer Market