
 Ready-To-Drink (RTD) Beverages Market | 2026-2036
Ready-To-Drink (RTD) Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Ready-To-Drink (RTD) Beverages Market Intelligence
The capital-intensity divergence between bottling-network owners and contract-manufacturing entrants is unwinding traditional barriers to scale. PepsiCo leverages its captive distribution infrastructure to sustain shelf-space dominance in North American convenience channels. Nestlé anchors premium positioning through in-house spring-water sourcing and aseptic cold-brew lines. Suntory Holdings Limited differentiates via integrated tea-estate operations in Japan and Southeast Asia.
Ready-to-drink beverages comprise pre-formulated, shelf-stable or chilled liquid products packaged for immediate consumption without dilution, mixing, or preparation, typically processed through hot-fill, aseptic, or retort methods to achieve microbial stability. These products serve commercial and retail channels requiring portable hydration, stimulation, or nutritional supplementation with minimal transaction friction. Carbonated drinks occupy the largest revenue pool though functional beverages command superior per-unit margins. Tea and coffee segments lead volume growth in East Asian markets while sports and energy drinks concentrate margin capture among athlete and working-professional demographics. Dairy-based RTD formats face structural pressure from plant-alternative substitution in European and North American retail sets.
The FDA enforces nutrition-fact labeling and added-sugar disclosure requirements that redirect R&D spending toward zero-calorie sweetener systems. EFSA and national regulators under the EU Green Deal mandate recycled-content thresholds for PET bottles, altering packaging economics across export-oriented producers. BIS certification requirements in India constrain import-dependent brands while accelerating local co-manufacturing partnerships. Stakeholders must monitor divergence between regional recycling infrastructure maturity and packaging-material mandates when committing to multi-year capital deployment.
Market Dynamics
Sugar taxation frameworks across multiple jurisdictions are forcing wholesale reformulation of legacy beverage portfolios, compressing margin structures while accelerating zero-calorie sweetener R&D cycles. This regulatory pressure layer intersects with convenience-seeking urban professionals to reshape competitive positioning.
Growth Catalysts
- Aseptic Cold-Fill Technology:Extended shelf life without preservatives unlocks premium positioning in specialty coffee and functional tea segments. Adoption accelerates among contract manufacturers serving private-label brands.
- India's PLI Scheme for Food Processing:Domestic co-manufacturing partnerships multiply as import-dependent brands seek BIS certification compliance. Local production capacity expands in Maharashtra and Karnataka clusters.
- Working-Professional Hydration Demand:Time-constrained urban commuters in Tokyo, Seoul, and Singapore drive single-serve format velocity through convenience-store channels.
Market Restraints
- Recycled PET Supply Concentration:EU Green Deal mandates outpace recycling infrastructure maturity in Eastern European markets. Virgin resin price volatility transmits through packaging cost structures.
- High-Fructose Corn Syrup Input Costs:Agricultural commodity swings compress formulation economics for mid-tier carbonated portfolios. Substitution to alternative sweeteners requires capital-intensive line retrofits.
- Extended Shelf-Life Technical Limits:Dairy-based RTD proteins face microbial stability ceilings that constrain distribution radius. Cold-chain dependency restricts penetration into ambient retail sets.
Strategic Opportunities
- Vietnam and Indonesia Underpenetration:Convenience-store density lags regional peers, creating first-mover shelf-space capture potential. Local taste preferences favor lower-sugar tea formulations.
- Direct-to-Consumer Subscription Channels:Functional beverage brands bypass traditional retail slotting fees through personalized nutrition algorithms. Recurring revenue models improve working-capital predictability.
- EU Packaging and Packaging Waste Regulation:Reuse-system mandates create infrastructure partnership openings for refillable bottle networks. Deposit-return schemes concentrate in Germany and Nordic markets.
Industry Challenges
- Aseptic Engineering Talent Scarcity:Specialized sterilization process expertise concentrates with legacy equipment vendors. New facility commissioning timelines extend due to certification backlogs.
- Multi-Jurisdiction Labeling Compliance:Divergent added-sugar disclosure thresholds between FDA and EFSA requirements fragment SKUs. Reformulation testing cycles consume 18-24 month lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready-To-Drink (RTD) Beverages Market |
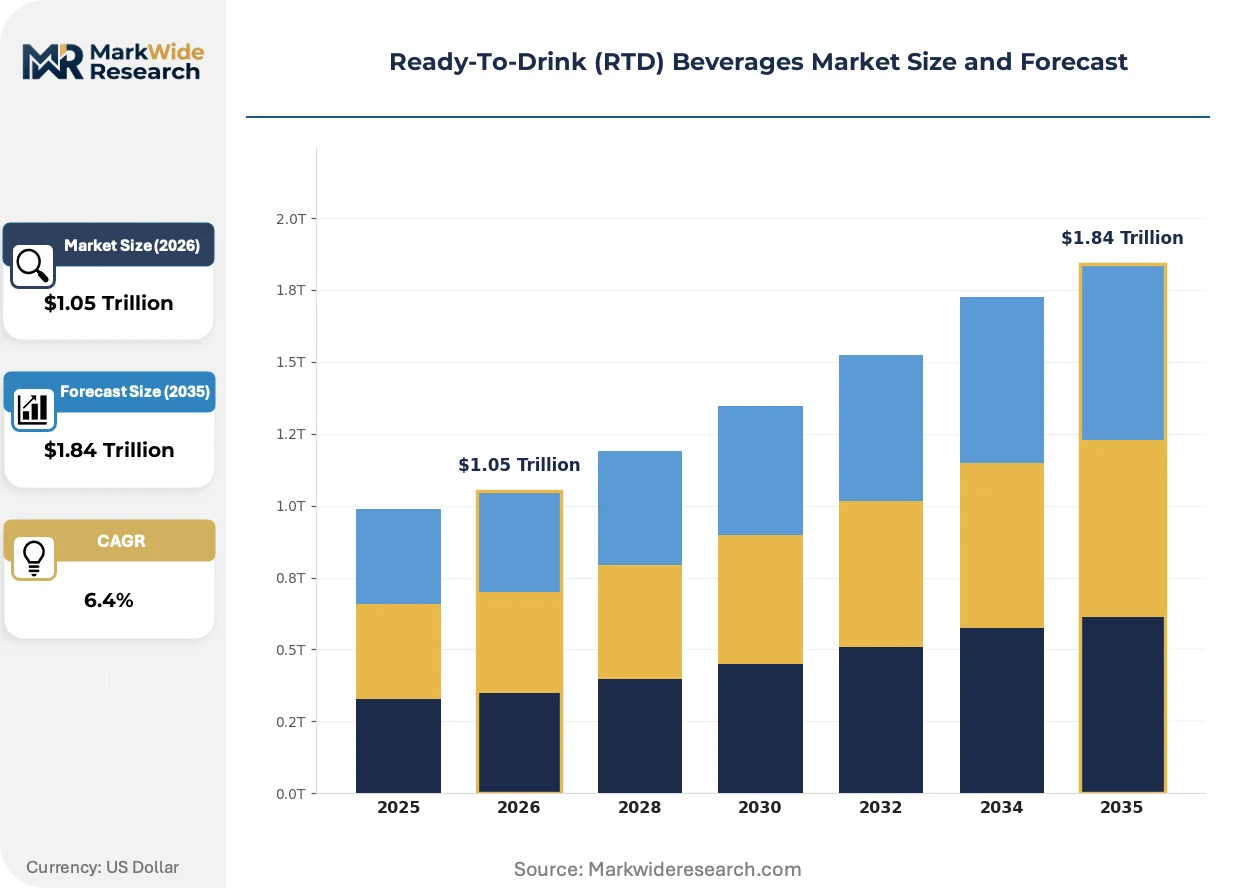
| Market Size in 2026 | $1.05 Trillion |
| Market Size in 2035 | $1.84 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tea & Coffee, Juice & Nectar, Carbonated Drinks, Sports & Energy Drinks, Dairy-Based, Functional Beverages Packaging Type: Bottle, Can, Tetra Pak, Pouch, Carton, Glass Distribution Channel: Supermarkets & Hypermarkets, Convenience Stores, Online Retail, Specialty Stores, Vending Machines, Food Service Consumer Demographic: Millennials, Generation Z, Working Professionals, Health-Conscious Adults, Athletes, Seniors |
| Companies Covered | The Coca-Cola Company, PepsiCo, Nestlé, Danone, Diageo, Suntory Holdings Limited, Anheuser-Busch InBev, Pernod Ricard, Bacardi Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready-To-Drink (RTD) Beverages Market Strategic Shifts & Innovations
Reformulation science and packaging material evolution are decomposing traditional category boundaries between refreshment and functional nutrition. These forces compress product development cycles while expanding addressable use cases.
Pulse-based protein extraction is decomposing dairy's dominance in RTD nutrition formats. Sports nutrition brands in North American and European markets accelerate adoption of pea and fava protein isolates. This technology is decomposing the whey protein supply chain's historical margin capture in ready-to-drink applications.
EFSA's novel food approval pathways for CBD and adaptogenic ingredients are compressing ingredient innovation timelines. Functional beverage developers face extended safety dossier requirements that delay market entry. Botanical extract suppliers concentrate investment in standardized clinical trial packages to preempt regulatory friction.
Urban micro-fulfillment networks are fragmenting traditional wholesale-distributor relationships. Direct-store-delivery models lose share to dark-store replenishment in dense metropolitan corridors. This pattern concentrates in Seoul, Tokyo, and Singapore where convenience-store operators operate captive logistics infrastructure.
Ready-To-Drink (RTD) Beverages Market Segmentation
Segmentation in RTD beverages reveals how formulation priorities, packaging economics, and channel access fragment margin capture across distinct consumer occasions. Manufacturers must align production assets with the specific technical and regulatory requirements of each slice.
Product Type:
Margin pools concentrate in functional and premium tea-coffee formats where aseptic processing creates defendable positioning, while carbonated volumes generate cash flow through scale economics.
- Tea & Coffee:Cold-brew and nitro-infused formats processed through aseptic lines deliver extended shelf life without chemical preservatives. Demand clusters in Tokyo, Seoul, and Singapore where convenience-store operators command dedicated cooler space for single-serve SKUs.
- Functional Beverages:Formulations incorporating adaptogens, nootropics, or protein isolates target working professionals seeking performance optimization. EFSA novel-food approval pathways for CBD and botanical extracts compress innovation timelines and elevate R&D risk.
- Carbonated Drinks:Legacy portfolios face sugar-tax compression across multiple jurisdictions.
- Sports & Energy Drinks:Athlete and fitness-segment targeting drives premium pricing.
- Juice & Nectar:Cold-pressed and HPP-treated variants compete with ambient concentrates.
- Dairy-Based:Plant-alternative substitution pressure constrains growth in European and North American retail.
Carbonated drinks hold installed capacity. Functional beverages are rotating up the share rankings.
Packaging Type:
Material selection determines distribution radius, recycling compliance burden, and shelf-space negotiation leverage with retail buyers.
- Bottle:PET dominates volume through lightweighting and recycled-content integration mandated by EU Green Deal thresholds. Virgin resin price volatility transmits directly through cost structures.
- Can:Aluminum formats command preference in sports and energy segments for chill-speed and portability. Deposit-return scheme participation in Germany and Nordic markets creates circular-economy infrastructure dependencies.
- Tetra Pak:Aseptic carton technology enables ambient distribution of sensitive formulations.
- Pouch:Flexible formats reduce shipping cube for e-commerce fulfillment.
- Carton:Gable-top designs concentrate in chilled juice applications.
- Glass:Premium positioning in specialty coffee and craft formulations.
Bottle formats anchor production lines. Can volumes are climbing the fastest in convenience-channel resets.
Distribution Channel:
Channel mix determines working-capital intensity and consumer data access, with direct-to-consumer models fragmenting traditional wholesale relationships.
- Convenience Stores:Dense urban networks in Tokyo, Seoul, and Singapore drive single-serve velocity through captive logistics infrastructure. Shelf-space fees and cooler access dominate manufacturer negotiations.
- Online Retail:Subscription algorithms enable personalized nutrition recommendations and recurring revenue predictability. Dark-store replenishment models bypass traditional distributor margins.
- Supermarkets & Hypermarkets:Volume concentration demands promotional funding and slotting-fee commitments.
- Specialty Stores:Premium and functional positioning with educated staff recommendation.
- Vending Machines:Cashless payment integration and micro-fulfillment density.
- Food Service:Fountain and dispensed formats for on-premise consumption.
Supermarkets hold legacy volume. Online retail is gaining share fastest through subscription mechanics.
Consumer Demographic:
Targeting precision determines formulation complexity and marketing spend allocation across life-stage and lifestyle cohorts.
- Working Professionals:Time-constrained urban commuters prioritize portability and functional claims over price sensitivity. Hydration and stimulation occasions fragment across morning commute and afternoon energy-collapse moments.
- Health-Conscious Adults:Zero-calorie sweetener acceptance and clean-label ingredient transparency drive purchase decisions. FDA added-sugar disclosure requirements redirect brand loyalty toward reformulated portfolios.
- Millennials:Sustainability credentials and brand purpose alignment influence selection.
- Generation Z:Social-media discovery and trial-oriented purchasing patterns.
- Athletes:Performance-verified formulations with electrolyte or protein delivery.
- Seniors:Nutritional supplementation and ease-of-consumption priorities.
Working professionals anchor volume concentration. Health-conscious adults are rotating up the priority matrix for R&D allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Japanese and Singaporean consumers absorb premium pricing for functional formulations, while Indian and Indonesian buyers remain acutely price-sensitive in mass-market carbonated segments.
United States
Working professionals in New York and Los Angeles drive single-serve functional beverage velocity through convenience-store channels. FDA added-sugar disclosure requirements redirect R&D spending toward zero-calorie sweetener systems. Texas and Georgia bottling clusters expand capacity to serve private-label contract manufacturing demand.
Japan
Tokyo and Osaka commuters sustain the world's highest per-capita RTD tea and coffee consumption through dense vending-machine networks. METI efficiency standards shape packaging lightweighting investments. Suntory's integrated tea-estate operations in Shizuoka Prefecture anchor premium supply-chain control.
Germany
Deposit-return scheme participation concentrates aluminum can preference in sports and energy segments. EU Green Deal recycled-content mandates for PET outpace Eastern European recycling infrastructure maturity. Bavarian and North Rhine-Westphalia production clusters face virgin resin price volatility transmission.
India
Maharashtra and Karnataka manufacturing hubs multiply as import-dependent brands pursue BIS certification compliance. FSSAI labeling requirements and the PLI scheme for food processing accelerate local co-manufacturing partnerships. Mumbai and Bangalore urban corridors drive convenience-store format expansion.
Vietnam
Convenience-store density lags regional peers, creating first-mover shelf-space capture potential. Lower-sugar tea formulations align with local taste preferences. Ho Chi Minh City and Hanoi metropolitan zones concentrate modern-trade channel development.
Ready-To-Drink (RTD) Beverages Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the RTD beverages market. Bottling-network owners command shelf-space leverage through captive distribution infrastructure, while contract-manufacturing entrants erode traditional scale barriers. Three archetypes dominate: beverage conglomerates with diversified portfolios, spirits-to-RTD diversifiers seeking non-alcoholic growth vectors, and integrated tea-coffee specialists with upstream agricultural control. Competitive intensity manifests through portfolio reformulation cycles and packaging-material compliance investments rather than pure price competition.
Among integrated beverage conglomerates, PepsiCo and Nestlé exemplify divergent strategic positioning. PepsiCo leverages North American convenience-channel dominance through captive distribution infrastructure. Nestlé anchors premium positioning through in-house spring-water sourcing and aseptic processing capabilities. Suntory Holdings Limited represents the agricultural-integration archetype, with captive tea-estate operations spanning Japan and Southeast Asia.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| Nestlé |
| Danone |
| Diageo |
| Suntory Holdings Limited |
| Anheuser-Busch InBev |
| Pernod Ricard |
| Bacardi Limited |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts for aseptic processing lines lock in both PET resin supply access and unit cost visibility for RTD beverage manufacturers navigating EU Green Deal recycled-content mandates and virgin resin price swings.
Pricing Analysis
After-market service contracts for aseptic line maintenance and sterilization certification drive lifetime value capture for equipment vendors serving RTD producers. Three-tier pricing structure across premium functional formulations, standard refreshment lines, and economy private-label SKUs segments buyer access. Cost compression in mid-tier carbonated portfolios intensifies as high-fructose corn syrup input volatility transmits through formulation economics. Health-conscious adults exhibit lowest price sensitivity for adaptogen-infused functional claims, while mass-market carbonated buyers in India and Indonesia remain acutely responsive to shelf-price shifts.
Supply Chain Analysis
Inventory buffers for aseptic packaging films and aluminum can sheet extend lead times when sterilization engineering talent scarcity delays new facility commissioning. Supply concentration clusters in China for PET resin and aluminum smelting, Thailand for natural rubber closures, and Germany for aseptic filling equipment manufacturing. Raw material dependencies encompass virgin and recycled PET, high-purity aluminum sheet, and natural sweetener extracts. Single-source vulnerability concentrates in specialized aseptic engineering certification bodies. Distribution runs through captive convenience-store logistics in Tokyo and Seoul, supplemented by dark-store micro-fulfillment networks in dense metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RTD beverages market constitutes a high-growth disruption as aseptic cold-fill technology and sugar taxation frameworks simultaneously unlock premium positioning and mandate wholesale portfolio reformulation.
For Market Incumbents: Shield legacy carbonated margins through accelerated zero-calorie sweetener R&D cycles and captive distribution infrastructure reinforcement in North American convenience channels. Backward integration into recycled PET sourcing hedges against EU Green Deal compliance cost spikes. Channel control through direct-store-delivery relationships in Tokyo and Seoul vending-machine networks defends shelf-space leverage against contract-manufacturing entrants.
For New Entrants and Emerging Players: Direct-to-consumer subscription algorithms for personalized functional nutrition represent a service-layer gap where incumbents under-serve working professionals seeking performance optimization. Vietnam and Indonesia convenience-store underpenetration offers the most penetrable geography for first-mover shelf-space capture. Go-to-market execution through dark-store replenishment partnerships bypasses traditional wholesale distributor margins and slotting-fee barriers.
For Investors and Strategic Acquirers: Agricultural-integration specialists with captive tea-estate operations in Japan and Southeast Asia constitute the priority acquisition target archetype. Long-term viability over a five-to-ten-year window hinges on upstream supply-chain control insulating against commodity input volatility. The signal to monitor is BIS certification compliance acceleration among import-dependent brands pursuing India's PLI scheme for food processing.
| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Cold-Fill Capacity Expansion | Extended shelf life without preservatives unlocks premium positioning in specialty coffee and functional tea segments. |
| Recycled PET Supply Integration | EU Green Deal mandates alter packaging economics for export-oriented producers across multiple jurisdictions. |
| Direct-to-Consumer Subscription Launch | Personalized nutrition algorithms bypass traditional retail slotting fees and improve working-capital predictability. |
| Zero-Calorie Sweetener R&D Investment | FDA added-sugar disclosure requirements redirect formulation priorities toward clean-label alternatives. |
| Convenience-Store Channel Expansion | Dense urban networks in Tokyo, Seoul, and Singapore drive single-serve velocity through captive logistics infrastructure. |
Research Approach
A standing panel of brand managers at multinational beverage conglomerates, category buyers at convenience-store operators, aseptic processing equipment engineers, and supply planners at PET resin suppliers provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against FDA filings, EFSA novel food approval databases, EU Green Deal regulatory texts, and customs trade records for PET and aluminum inputs. Bottom-up volume modeling across packaging formats and top-down macroeconomic triangulation ensured cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented demand by product type, packaging material, distribution channel, and consumer demographic, with geographic regulatory clusters as an additional dimension. CAGRs derived from historical trajectory analysis and forward-looking elasticity assumptions incorporated aseptic technology adoption curves and sugar taxation rollout schedules as industry-specific forecast inputs.
Underlying assumptions cover regulatory compliance timelines, recycled-content mandate enforcement intensity, and commodity input price normalization, with deviation risk concentrated in EU recycling infrastructure maturity gaps and aseptic engineering certification backlogs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Morocco Bottled Water Market
Beverages
Bottled Water Processing Market
Beverages
Hot Cocoa Mix Market
Beverages
CBD-Infused Beverages Market
Beverages
Maple Water Market
Beverages
Detox Drinks Market
Beverages
Hydrogen Water Dispenser Market
Beverages
North America Fruit Juice Market
Beverages
Relaxation Beverages Market
Beverages
Fruit Beverages Market
Beverages
Caffeine Mint Market
Beverages
Global Electrolyte Drinks Market
Beverages
China Soy Beverages Market
Beverages
Collagen Drinks Market
Beverages
Soft Serves Market
Beverages
Europe Coconut Water Market