
 Drinking Water Market | 2026-2036
Drinking Water Market Size, Share, and Industry Trends Forecast 2026-2036
Drinking Water Market Analysis
Market Context
Advanced membrane filtration is rewriting how drinking water is purified at scale, replacing conventional chlorine-dependent systems with nanofiltration and reverse osmosis trains. Niagara Bottling leverages automated bottling lines and direct-store-delivery networks to dominate private-label retail channels. Danone anchors its position through spring-sourced mineral water portfolios and European brand equity. Coca-Cola Company extends reach via Dasani and Smartwater, competing on purification technology and sports sponsorship visibility.
Technical Definition and Segments
Drinking water denotes water treated to meet potable standards for human consumption, typically containing less than 500 mg/L total dissolved solids and maintained at a pH between 6.5 and 8.5 to prevent corrosion and ensure palatability. Its primary purpose spans direct hydration, food preparation, and pharmaceutical manufacturing where microbial and chemical purity are non-negotiable. Bottled water and filtered water command the widest margin pools as health-conscious households trade up from untreated tap sources. Supermarkets and online retailers are absorbing volume from vending machines as last-mile logistics improve. Plastic bottles retain volume leadership while Tetra Packs gain share in institutional channels seeking reduced carbon footprints.
Regulatory Framework
The EPA enforces Maximum Contaminant Levels under the Safe Drinking Water Act, with recent PFAS rulemaking compelling utilities and bottlers to install granular activated carbon or ion exchange systems. The FDA regulates bottled water as a packaged food, imposing standards of identity and quality that exceed tap requirements in several parameters. WHO guidelines influence national standards across emerging markets where codified frameworks remain under development. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment competitive economics.
Market Dynamics
Membrane filtration economics are compressing treatment costs below legacy chlorine-ozone trains, forcing municipal utilities and bottlers to accelerate capital replacement cycles while reconfiguring procurement specifications around energy recovery and brine minimization.
Growth Catalysts
- EPA PFAS Maximum Contaminant Levels:The tightened 4 parts per trillion standard for PFOA and PFOS compels granular activated carbon and ion exchange upgrades across thousands of public water systems and bottling facilities.
- Reverse osmosis-nanofiltration hybrid trains:Southeast Asian megacities including Jakarta and Manila are deploying containerized membrane plants to bypass decades of piped network underdevelopment.
- Pharmaceutical-grade water demand:Biologics manufacturing expansion in India and Ireland is pulling ultrapure water infrastructure investment from equipment suppliers.
Market Restraints
- Membrane fouling and replacement cycles:Polyamide thin-film composite elements require 3-5 year replacement at 15-25% of initial capital cost, degrading project returns in high-turbidity source waters.
- Specialized engineering labor scarcity:Process design expertise for integrated membrane-biological systems concentrates among a handful of regional contractors in Germany, Japan, and Singapore.
- Per- and polyfluoroalkyl substance liability:Emerging tort exposure around historical PFAS contamination is elevating insurance costs and complicating site acquisition for new treatment facilities.
Strategic Opportunities
- Direct-to-consumer filtration subscriptions:Countertop and under-sink reverse osmosis units are bypassing bottled water entirely in South Korean and Taiwanese households with high tap-water salinity concerns.
- EU Green Deal circular packaging mandates:The Packaging and Packaging Waste Regulation's recycled content targets are creating first-mover advantage for refillable glass and aluminum formats in German and French retail.
- Brine mining and resource recovery:Concentrate streams from seawater desalination and inland brackish treatment contain lithium, magnesium, and rare earth elements extractable through emerging electrochemical separation.
Industry Challenges
- Cross-connection control certification:Backflow prevention assembly testing and repair licensing requirements vary by US state, fragmenting service provider qualification and compliance audit protocols.
- Legacy SCADA integration:Municipal utilities operating 1980s-era distributed control systems face protocol translation complexity when connecting new membrane skids to centralized monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drinking Water Market |
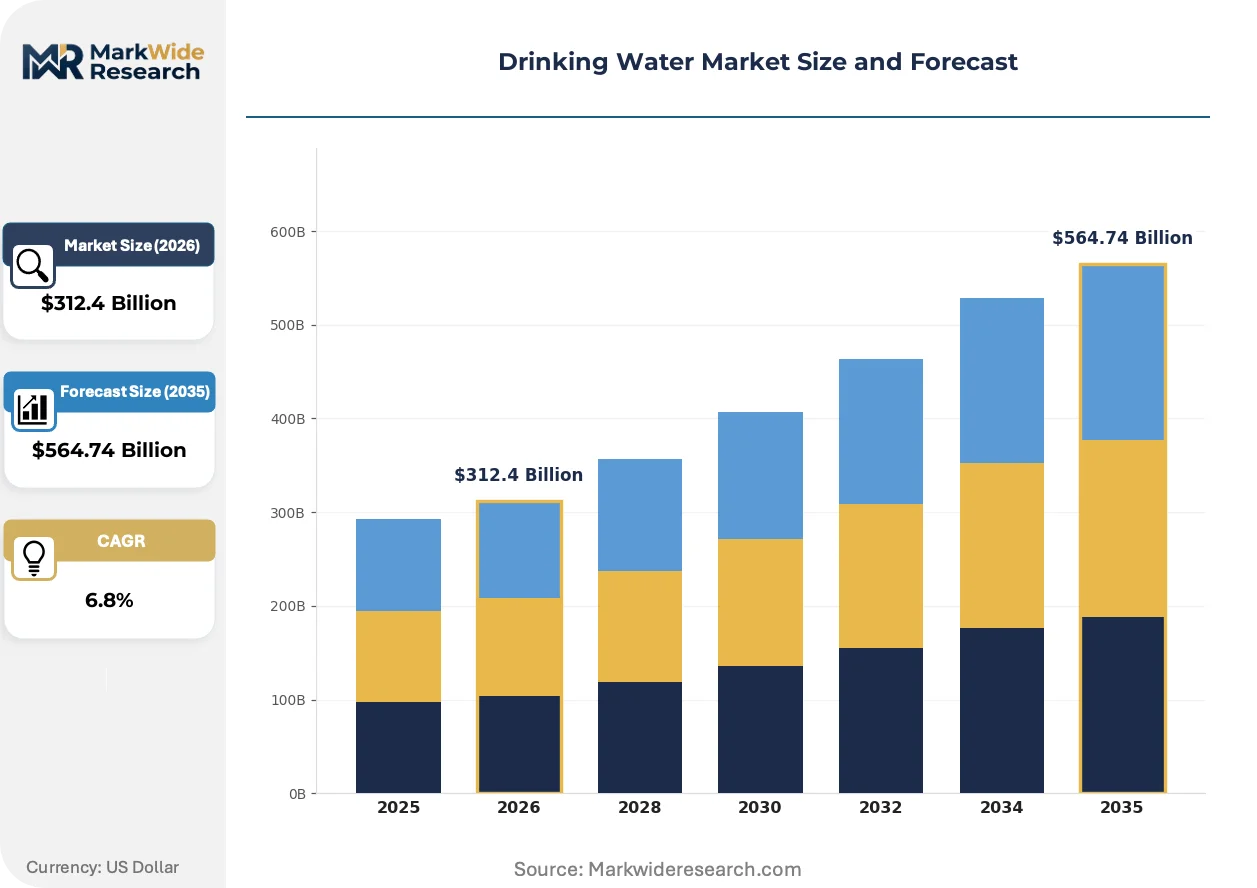
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottled Water, Filtered Water, Tap Water, Spring Water Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Vending Machines Packaging Type: Plastic Bottles, Glass Bottles, Tetra Packs, Pouches End User: Households, Offices, Restaurants, Schools |
| Companies Covered | Niagara Bottling, Danone, BlueTriton Brands, CG Roxane, Nestlé, Coca-Cola Company, Primo Water Corporation, Keurig Dr Pepper, PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drinking Water Market Emerging Trajectories
Water purification is fragmenting into modular, decentralized architectures that bypass centralized plant economics while digital monitoring enables predictive maintenance and quality assurance at remote production nodes.
Ultrafiltration-reverse osmosis-electrodeionization trains are hybridizing into single-skid pharmaceutical water systems that collapse space requirements and validation timelines. Biologics manufacturers in Ireland and Singapore are specifying these compact trains for multi-product facilities requiring rapid changeover. The convergence is compressing equipment vendor margins while elevating system integrator value capture.
REACH restrictions on per- and polyfluoroalkyl substances are forcing membrane manufacturers to reformulate PTFE and PVDF components ahead of 2025 authorization sunsets. European equipment suppliers are accelerating fluoropolymer-free ceramic and polyethersulfone alternatives through qualification protocols. Bottled water exporters to the EU face downstream notification obligations that fragment compliance documentation across supply chains.
Households in Chinese tier-1 cities are abandoning bulk water delivery in favor of subscription-connected purifiers that transmit consumption and filter status data to mobile applications. E-commerce platforms including JD.com and Tmall are capturing recurring revenue streams previously absorbed by neighborhood water stations. The shift is visible in Shanghai and Shenzhen where apartment penetration of internet-connected filtration exceeds 40% among middle-income cohorts.
Drinking Water Market Segmentation
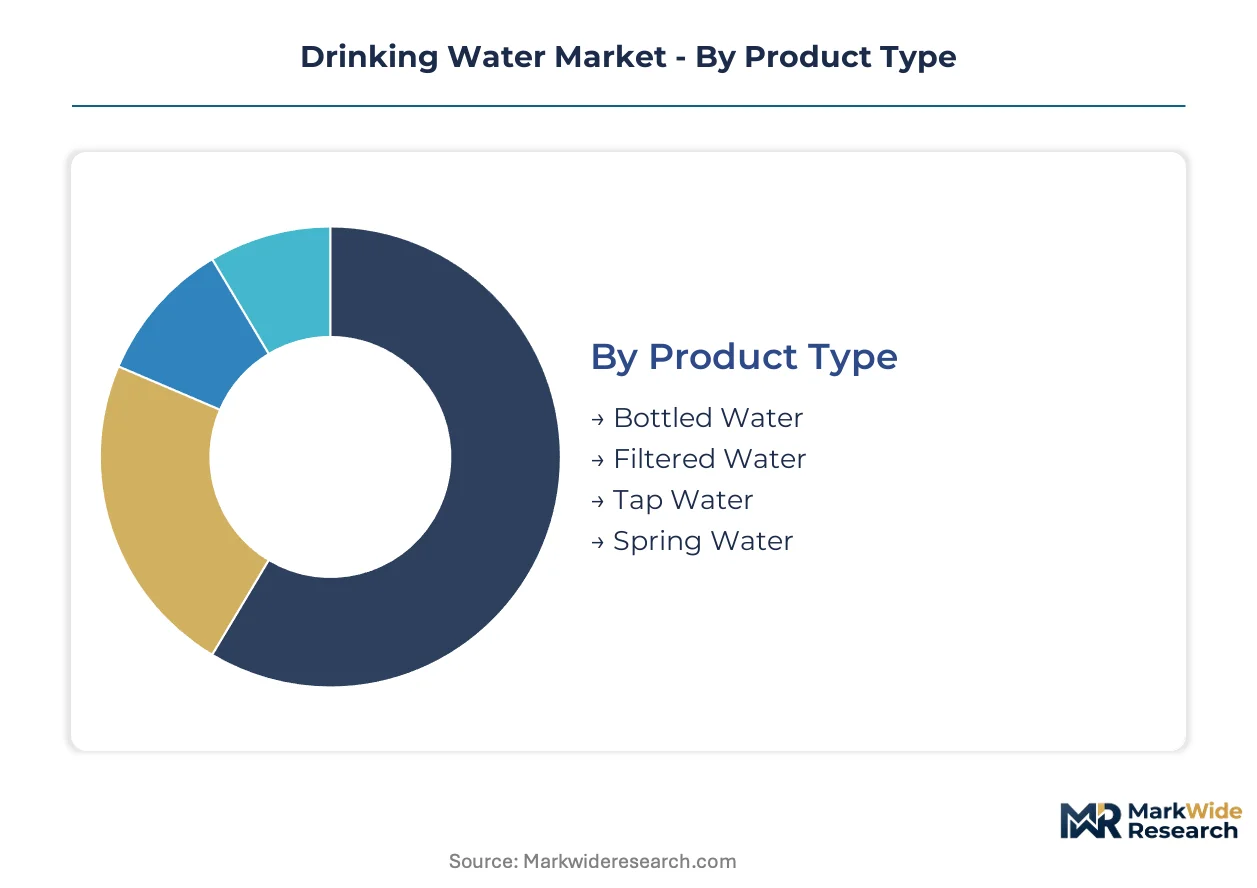
Segmentation in the drinking water market reveals how purification technology, packaging format, and channel economics fragment value capture across consumer and institutional buyers. Understanding these divisions exposes where membrane technology investments translate to margin expansion versus commodity pressure.
Product Type:
The use-case spectrum spans emergency hydration, daily consumption, pharmaceutical manufacturing, and culinary preparation, each imposing distinct purity specifications and price elasticity.
- Bottled Water:Reverse osmosis or spring-sourced water packaged for retail portability, with mineral content adjusted for taste profiling. Demand concentrates in Southeast Asian megacities where municipal piped networks remain underdeveloped and household filtration penetration lags. The EPA's tightened PFAS standards are forcing bottlers to install granular activated carbon or ion exchange systems, elevating treatment costs.
- Filtered Water:Point-of-use treated water produced through countertop, under-sink, or pitcher systems removing chlorine, heavy metals, and microbial contaminants. South Korean and Taiwanese households with high tap-water salinity concerns are driving subscription-connected purifier adoption exceeding 40% penetration among middle-income cohorts in tier-1 cities.
- Tap Water:Municipally treated surface or groundwater meeting EPA Maximum Contaminant Levels under the Safe Drinking Water Act, typically chlorinated for residual disinfection. Municipal utilities in drought-prone US regions are expanding advanced membrane capacity to replace aging chlorine-ozone trains.
- Spring Water:Naturally sourced groundwater bottled at origin with minimal treatment, leveraging mineral content for taste differentiation and brand positioning. European regulatory frameworks under EFSA and national mineral water designations protect geographic indication status.
The dominant share belongs to bottled water, while filtered water is closing the gap fastest.
Distribution Channel:
Channel economics fragment between high-frequency impulse purchase locations and subscription-based recurring revenue platforms with diverging logistics cost structures.
- Supermarkets:Volume-led retail environments where private-label water competes on shelf placement and promotional pricing, absorbing volume from vending machines as last-mile logistics improve.
- Convenience Stores:Immediate-consumption outlets capturing single-serve premium pricing through refrigerated display placement and transit-oriented locations.
- Online Retailers:E-commerce platforms including JD.com and Tmall capturing recurring revenue streams through subscription replenishment models with filter replacement scheduling.
- Vending Machines:Dispensing infrastructure losing share to direct-store-delivery networks and bulk water stations in Chinese residential compounds.
Supermarkets retain volume leadership, though online retailers are climbing the fastest as subscription models lock in household purchasing patterns.
Packaging Type:
Material selection balances carbon footprint compliance, transport efficiency, and consumer perception of quality across regulatory jurisdictions with diverging extended producer responsibility frameworks.
- Plastic Bottles:PET containers dominating volume leadership due to lightweight transport economics and blow-molding manufacturing scale across bottling facilities.
- Glass Bottles:Premium-positioned refillable formats gaining traction under EU Green Deal circular packaging mandates with recycled content targets creating first-mover advantage in German and French retail.
- Tetra Packs:Aseptic cartons expanding share in institutional channels seeking reduced carbon footprints through renewable paperboard sourcing and rectangular shipping efficiency.
- Pouches:Flexible film formats penetrating price-sensitive emerging markets with lower per-unit packaging costs and reduced shipping weight.
Plastic bottles command installed base dominance, yet glass bottles are gaining share fastest on regulatory tailwinds.
End User:
Customer-type concentration determines specification stringency, from residential taste preference to pharmaceutical-grade microbial compliance.
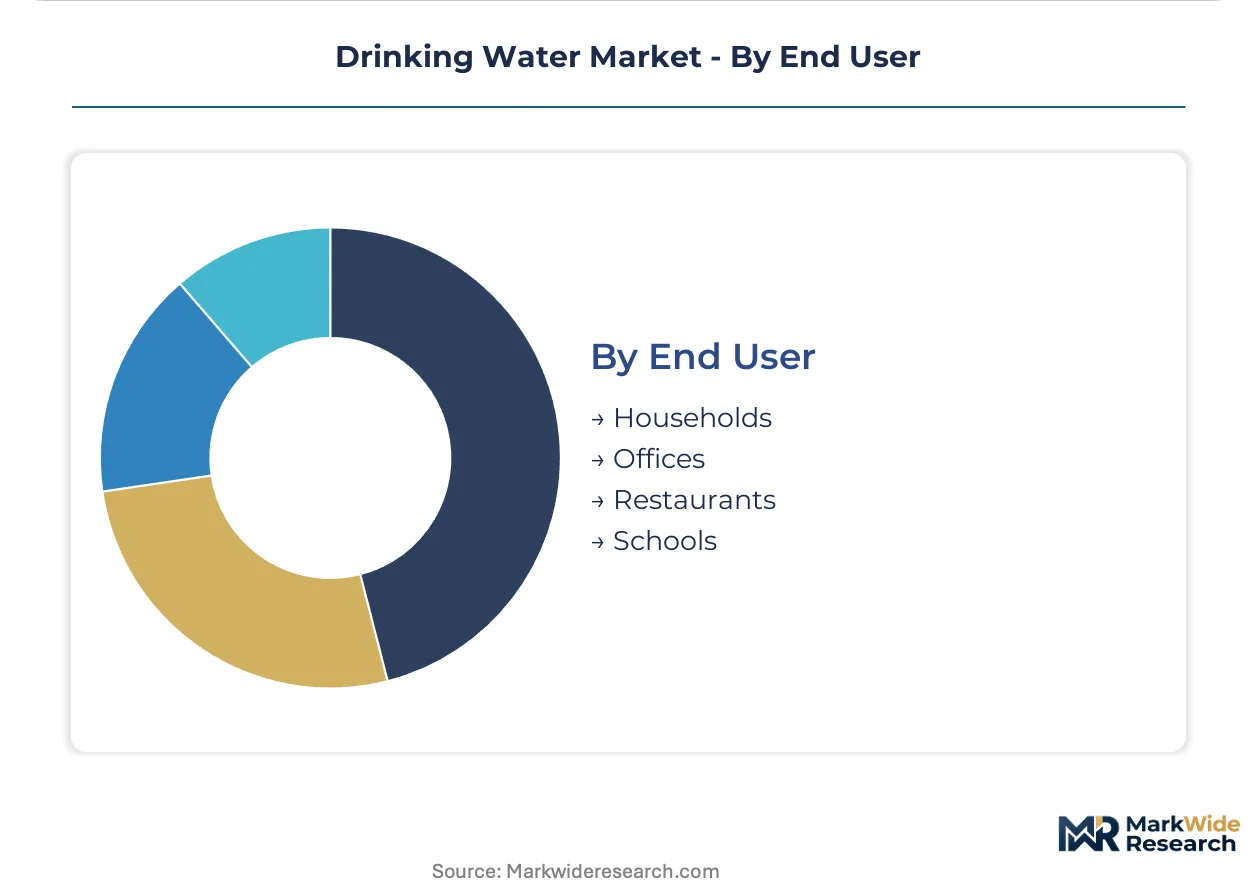
- Households:Residential consumers trading up from untreated tap sources toward health-positioned options, driving countertop reverse osmosis unit installation in high-salinity regions.
- Offices:Commercial facilities requiring bulk dispensing systems with filtration maintenance contracts and hydration station aesthetics for employee amenity positioning.
- Restaurants:Foodservice operators specifying mineral content for coffee extraction and culinary preparation where water chemistry affects end-product quality.
- Schools:Institutional buyers with mandated lead testing and fountain replacement programs under US state-level educational facility standards.
Households absorb the dominant consumption share, while offices are expanding most quickly on corporate wellness program adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Households in water-stressed jurisdictions drive capital deployment toward membrane treatment and alternative sourcing. Municipal buyers in drought-prone areas expand advanced capacity while private bottlers navigate tightening chemical standards. Regional divergence in piped network maturity fragments competitive economics.
United States
EPA's 4 parts per trillion PFAS Maximum Contaminant Levels compel granular activated carbon upgrades across thousands of public water systems. The Safe Drinking Water Act enforcement is accelerating infrastructure replacement cycles in California and Arizona. Phoenix anchors southwestern membrane deployment as Colorado River shortages force municipal utilities toward advanced reuse and brackish desalination.
China
JD.com and Tmall subscription models are displacing neighborhood bulk water stations in tier-1 cities. SAMR quality inspections and GB standards for packaged drinking water tighten bottler compliance obligations. Shanghai and Shenzhen exceed 40% internet-connected purifier penetration among middle-income households as salinity concerns drive countertop reverse osmosis adoption.
Germany
EU Green Deal circular packaging mandates create first-mover advantage for refillable glass formats in retail channels. REACH restrictions on per- and polyfluoroalkyl substances force membrane manufacturers to reformulate fluoropolymer components ahead of authorization sunsets. The Ruhr industrial corridor hosts equipment suppliers accelerating ceramic and polyethersulfone alternative qualification.
India
Biologics manufacturing expansion in Hyderabad and Bengaluru pulls ultrapure water infrastructure investment from equipment suppliers. BIS drinking water standards and state-level municipal reform programs are unevenly implemented across sub-national jurisdictions. The Delhi-NCR corridor concentrates point-of-use filtration demand as groundwater salinity and contamination elevate household treatment expenditure.
South Korea
Subscription-connected purifiers bypass bottled water entirely in Seoul metropolitan households with persistent tap-water quality skepticism. MFDS packaged food regulations and national water quality monitoring frameworks shape bottler compliance architecture. Busan-Ulsan industrial clusters import membrane engineering expertise for semiconductor-grade water systems serving display panel fabrication.
Drinking Water Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent margin structures. The market exhibits tiered concentration with scale-driven bottlers, spring-sourced mineral specialists, and purification-technology platforms occupying distinct competitive positions. Three archetypes dominate: retail-channel dominators leveraging direct-store-delivery density, brand-equity holders commanding premium mineral positioning, and technology-forward purifiers capturing subscription recurring revenue. Capacity expansion and portfolio diversification represent the dominant competitive moves as players respond to regulatory tightening and packaging circularity mandates.
Within the retail-channel tier, Niagara Bottling and Coca-Cola Company occupy positions defined by automated production scale and distribution network density. Danone anchors the spring-sourced mineral water segment through European brand equity and geographic indication protection. These three exemplify how competitive positioning fragments between volume-driven private-label supply, purification-technology marketing, and origin-based premium positioning.
| Leading Market Players |
|---|
| Niagara Bottling |
| Danone |
| BlueTriton Brands |
| CG Roxane |
| Nestlé |
| Coca-Cola Company |
| Primo Water Corporation |
| Keurig Dr Pepper |
| PepsiCo |
| Others |
Supply Flow & Price Mechanics
The Ruhr industrial corridor anchors European membrane manufacturing capacity, where German equipment suppliers' fluoropolymer-free ceramic output tightens bottler procurement timelines and elevates pricing power for qualified vendors serving REACH-compliant markets.
Pricing Analysis
Cost-plus contracts with membrane replacement indexation dominate municipal utility procurement, tying recurring expenditure to polyamide thin-film composite element lifecycles. Pricing stratifies across pharmaceutical-grade, premium bottled, and municipal utility tiers, with certification to EPA PFAS standards commanding substantial premiums. Cost compression in private-label bottled water intensifies as Niagara Bottling and Coca-Cola Company automated lines squeeze regional bottler margins. Municipal utilities exhibit lowest price sensitivity due to regulatory compliance mandates, while price-sensitive households in Southeast Asian megacities gravitate toward bulk water stations.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts polyethersulfone membrane component flows, forcing European and Japanese suppliers to absorb redirected demand. Manufacturing concentrates in Germany, Japan, and Singapore for specialized process design expertise. Raw material dependencies span Saudi Arabian desalination brine for lithium extraction, Chinese rare earth processing for electrodeionization systems, and German ceramic substrate production. Single-source vulnerability concentrates in fluoropolymer reformulation capabilities ahead of REACH authorization sunsets. Distribution runs through direct-store-delivery networks for retail bottled water and containerized membrane skids for municipal deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected purifier platforms are reconfiguring this market around subscription economics, with JD.com and Tmall ecosystems locking household purchasing patterns through filter replenishment interoperability that marginalizes unintegrated bottlers.
For Market Incumbents: Entrench regulatory compliance capabilities by accelerating granular activated carbon and ion exchange system deployment ahead of EPA enforcement waves. Secure backward integration into membrane manufacturing through captive supply agreements with German or Japanese ceramic substrate producers, insulating against fluoropolymer supply disruption from REACH restrictions. For New Entrants and Emerging Players: Pursue white-space penetration in Indian biologics manufacturing corridors where ultrapure water infrastructure demand outpaces qualified system integrator supply. Target Delhi-NCR point-of-use filtration replacement cycles as groundwater salinity elevates household treatment expenditure, deploying mobile-app-enabled subscription models adapted from South Korean market development. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because tightening PFAS standards and circular packaging mandates compound capital replacement cycles across municipal and bottled segments. Acquisition targets should concentrate on membrane system integrators with pharmaceutical qualification protocols and recurring service revenue streams. The signal to watch is EPA enforcement action triggering municipal procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Integration | Hybrid ultrafiltration-reverse osmosis-electrodeionization trains collapse pharmaceutical water system validation timelines for biologics manufacturers in Ireland and Singapore. |
| Direct-to-Consumer Platform Launch | Subscription-connected purifier deployment via JD.com and Tmall captures recurring revenue streams previously absorbed by neighborhood bulk water stations in Chinese tier-1 cities. |
| Regulatory Compliance Infrastructure | Granular activated carbon and ion exchange system upgrades address EPA's 4 parts per trillion PFAS Maximum Contaminant Levels across thousands of public water systems. |
| Circular Packaging Transition | Refillable glass and aluminum format investment creates first-mover advantage under EU Green Deal recycled content mandates in German and French retail channels. |
| Brine Mining Resource Recovery | Electrochemical separation from desalination concentrate streams extracts lithium, magnesium, and rare earth elements, transforming waste liability into revenue. |
Methodological Framework
Initial hypotheses were tested against primary input from municipal utility planning officers, membrane equipment procurement directors, bottled water brand managers, and pharmaceutical facility engineering leads, and refined through secondary validation against EPA enforcement databases, FDA bottled water quality reports, SAMR inspection disclosures, and REACH authorization timelines. Bottom-up triangulation across equipment vendor shipment records and top-down reconciliation against utility capital expenditure disclosures anchored volume estimates.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation modeling spanning purification technology tier, packaging format, distribution channel, and end-user specification stringency. CAGRs were derived from installed base replacement cycles and penetration trajectory analysis for connected purifier platforms. Industry-specific inputs incorporated membrane fouling rate assumptions and PFAS treatment capacity buildout schedules.
Macroeconomic conditions sit as an overlay; deviation in municipal bond financing costs, rare earth processing capacity expansion, or semiconductor fabrication demand would shift the trajectory for ultrapure water infrastructure investment. Forecasts reflect documented assumptions regarding regulatory enforcement timing and membrane replacement cycle stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Europe Smoothies Market
Beverages
Asia-Pacific Energy Drink Market
Beverages
Gluten Free Beverages Market
Beverages
Ginger Beer Market
Beverages
Crystal Boba Market
Beverages
Water Flavor Market
Beverages
Wine Cooler and Chest Freezer Market
Beverages
Soft Serve Premix Market
Beverages
Aloe Vera Drinks Market
Beverages
North America Yerba Mate Market
Beverages
Caffeine-Based Drinks Market
Beverages
Water Bottle Market
Beverages
Sparkling Juice Drinks Market
Beverages
GCC Sports and Energy Drinks Market
Beverages
Double Valve Moka Pots Market
Beverages
North America Sugar Free Energy Drinks Market