
 Fructose Market | 2026-2036
Fructose Market Size, Share, and Industry Trends Forecast 2026-2036
Fructose Market Intelligence
The FSSC 22000 certification for food safety management is redrawing the competitive landscape, setting a high barrier for market entry. Global producers like Cargill Incorporated leverage extensive supply chain control to ensure compliance and consistent quality at scale. Ingredion Incorporated specializes in specialty fructose solutions for clean-label applications demanded by health-conscious consumers. Tate & Lyle competes through its broad portfolio of both corn-based and alternative sweeteners, navigating diverse customer requirements across food categories.
Fructose is a simple ketonic monosaccharide found in many plants, where it is often bonded to glucose to form the disaccharide sucrose. It is commercially produced from corn, sugar cane, or sugar beets and is valued for being the sweetest of all naturally occurring carbohydrates, enhancing palatability in food systems. High Fructose Corn Syrup (HFCS) continues to dominate volume, particularly within the beverages application due to its cost-effectiveness and liquid form. Crystalline fructose shows strong growth in confectionery and bakery segments, where its low water activity and high sweetness are critical functional attributes.
Labeling mandates from regulators like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) directly impact product formulation and marketing claims. In parallel, national standards such as those set by China's State Administration for Market Regulation (SAMR) govern quality and import requirements for sweeteners. Suppliers must now decide whether to invest in producing alternative or organic fructose variants to meet evolving consumer preferences for perceived healthier ingredients.
Market Dynamics
The central tension between industrial demand for cost-effective sweeteners and mounting regulatory pressure on added sugars is the primary force shaping the fructose market, compelling producers to balance volume production with formulation innovation.
Growth Catalysts
- Functional Properties in Beverages:Fructose provides superior sweetness, flavor enhancement, and osmotic stability, extending shelf life in carbonated soft drinks and juices, which drives its high-volume consumption.
- Concentrated Demand in China:The country's expansive food and beverage manufacturing industry, a major global supplier, creates sustained, large-scale demand for fructose as a primary sweetening agent in processed foods.
- Crystalline Fructose Growth:In bakery and confectionery applications, the low water activity and high relative sweetness of crystalline fructose make it a critical functional ingredient for controlling moisture and texture.
Market Restraints
- Substitution from Alternative Sweeteners:Negative consumer perception of HFCS fuels a shift towards natural, non-nutritive sweeteners like stevia and monk fruit, particularly in new product development for the health and wellness sector.
- US FDA Labeling Mandates:The requirement to declare "Added Sugars" on nutrition labels acts as a direct restraint, encouraging manufacturers to reduce or replace fructose to achieve more favorable on-pack claims.
- Feedstock Price Volatility:The market's reliance on corn exposes fructose producers to price fluctuations driven by agricultural yields, weather events, and competing demands from the ethanol and animal feed industries.
Strategic Opportunities
- Clean-Label Formulations:Developing organic and non-GMO fructose variants creates an opportunity to serve the premium segment of the food industry, which prioritizes ingredients with specific certifications.
- Expansion in Southeast Asia:Rising disposable incomes and the growth of local food processing industries in countries like Vietnam and Indonesia present underpenetrated markets for fructose suppliers.
- Application in Sports Nutrition:Fructose's unique metabolic pathway offers potential for formulating specialized energy gels and beverages for athletes, representing a niche but high-value application.
Industry Challenges
- Certification Compliance Costs:Achieving and maintaining food safety certifications like FSSC 22000 requires significant capital investment and operational discipline, posing a challenge for smaller or regional producers.
- Global Supply Chain Complexity:Managing a traceable and contamination-free supply chain from agricultural sources like corn or sugar beets through to final processing presents a constant operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fructose Market |
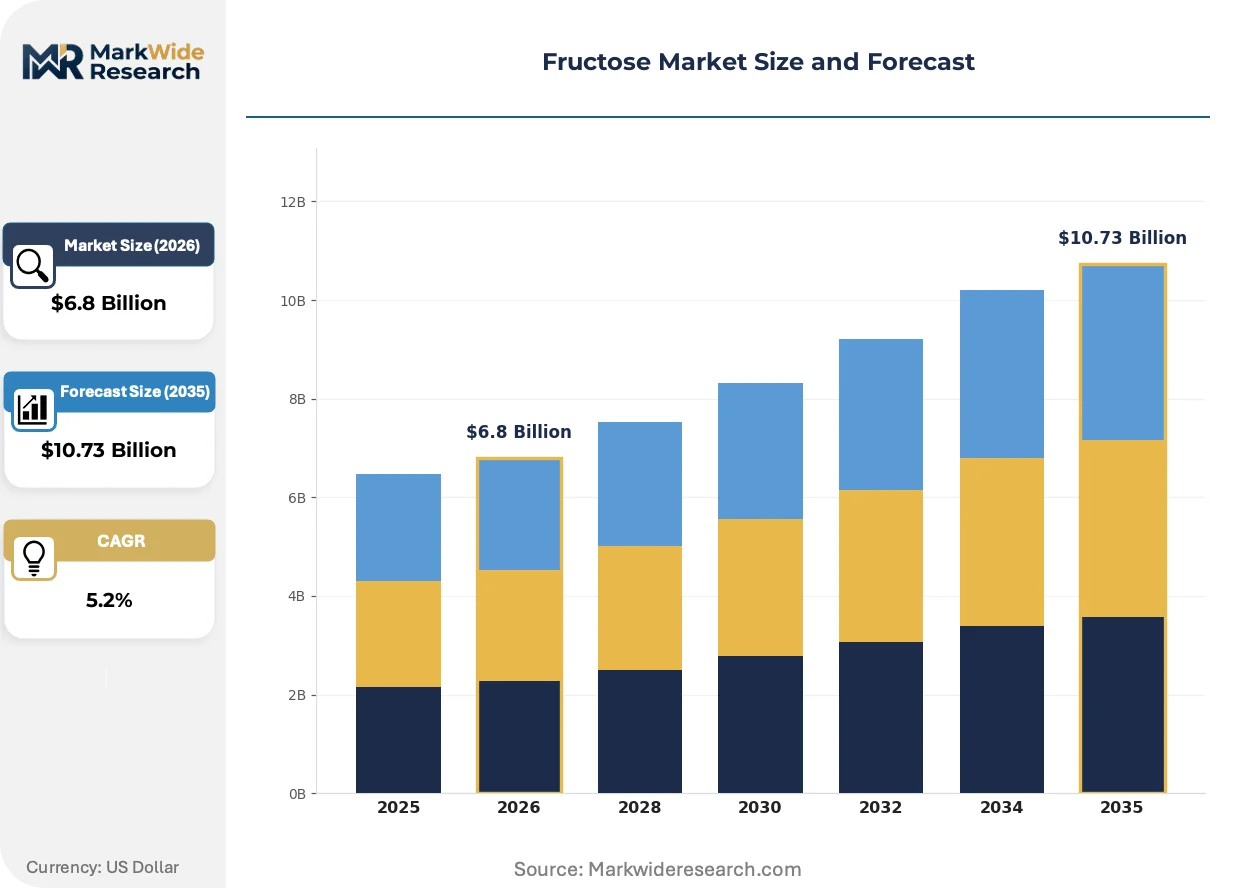
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.73 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Beverages, Confectionery, Bakery, Dairy Product Type: Crystalline Fructose, Liquid Fructose, High Fructose Corn Syrup, Organic Fructose End User: Food Industry, Pharmaceutical, Cosmetics, Nutraceuticals Form: Powder, Syrup, Granule, Paste |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle, DuPont, Roquette Frères, Südzucker AG, Galam, Shijiazhuang Huaxu Pharmaceutical Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fructose Market Strategic Shifts & Innovations
A fundamental conflict between the industrial efficiency of commodity fructose and market demand for differentiated, clean-label sweeteners is compelling a strategic re-evaluation of product portfolios and innovation pipelines across the industry.
Advanced enzymatic and chromatographic separation techniques are enabling the production of high-purity crystalline fructose and specialized organic variants. Premium beverage and confectionery manufacturers are steadily adopting these specialty forms to meet clean-label product briefs. The availability of these distinct grades is fragmenting the sweetener category, moving it away from a one-size-fits-all model previously dominated by standard HFCS.
Regulatory bodies, including the US FDA and EFSA, have intensified scrutiny on added sugars through mandatory on-pack labeling. This directly impacts formulation decisions, pushing manufacturers to reduce total sugar content or seek alternative sweetening systems. The beverage industry, a primary user of HFCS, is most affected, accelerating research into sweetener blends that can lower declared sugar values while maintaining taste profiles.
Certification-driven sourcing is becoming a standard practice, with buyers demanding proof of non-GMO, organic, or specific food safety credentials. This shift disrupts traditional purchasing decisions based purely on price and specification, elevating the importance of a supplier's compliance and documentation capabilities. This behavior is most pronounced in the North American and Western European markets, especially for products targeting the natural and organic retail channels.
Fructose Market Segmentation
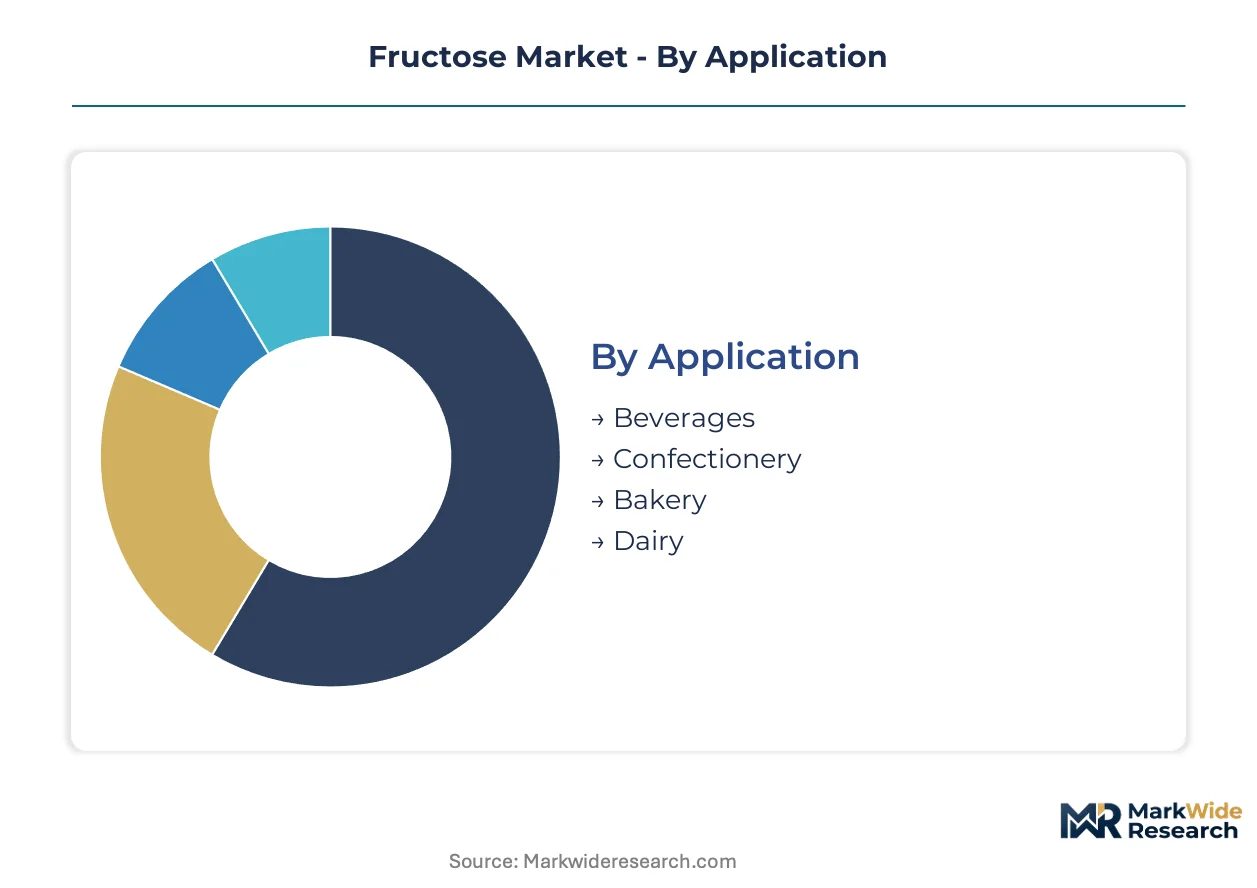
Understanding the diverse applications and forms of fructose is critical for market participants to tailor product offerings and distribution strategies. Segmentation reveals how different product types cater to specific end-user demands, influencing formulation decisions across various industries. This analysis dissects the market to highlight key areas of value creation and strategic focus for producers.
Application:
The distribution of fructose varies significantly across application channels, reflecting distinct requirements for sweetness, texture, and shelf life in consumer products.
- Beverages:Fructose provides superior sweetness and flavor enhancement, crucial for carbonated soft drinks and juices. Demand concentrates in China's expansive food and beverage manufacturing industry, where it drives high-volume consumption.
- Confectionery:This segment utilizes fructose for its high sweetness and ability to control crystallization in candies and chocolates. North American and European markets show strong demand for crystalline fructose in specialty confectionery items.
- Bakery:Fructose enhances palatability and extends shelf life in baked goods like cakes and pastries.
- Dairy:Fructose is used in yogurts and ice creams to improve texture and provide balanced sweetness.
Beverages dominates the installed base for fructose consumption. Confectionery is where expansion concentrates, driven by crystalline fructose.
Product Type:
Product types within the fructose market often align with distinct cost tiers, influencing their adoption across various industrial applications and consumer price points.
- High Fructose Corn Syrup:HFCS continues to dominate volume due to its cost-effectiveness and liquid form, making it a staple in large-scale food production. Its primary application remains within the beverages sector, particularly in North America.
- Crystalline Fructose:This high-purity form is valued for its low water activity and high relative sweetness, essential in specific confectionery and bakery formulations. Its growth is strong in markets seeking precise functional attributes, such as Western Europe.
- Liquid Fructose:This form offers ease of handling and blending, finding applications in various processed foods and drinks.
- Organic Fructose:Targeted at the premium segment, this variant meets evolving consumer preferences for perceived healthier ingredients and clean-label certifications.
The market structure favors High Fructose Corn Syrup for volume, while Organic Fructose commands premium pricing.
End User:
End-user segments reflect the varied scale and specific quality requirements for fructose, from bulk industrial use to highly specialized formulations.
- Food Industry:This segment represents the largest consumer of fructose, driven by its widespread use as a sweetening agent in processed foods and beverages. Demand is particularly concentrated in Asia-Pacific, supporting large-scale manufacturing.
- Nutraceuticals:Fructose finds application in specialized health and wellness products, including sports nutrition and dietary supplements, leveraging its unique metabolic pathway. European and North American markets show rising interest in these functional applications.
- Pharmaceutical:Fructose acts as an excipient and sweetening agent in various oral medications and syrups.
- Cosmetics:In cosmetics, fructose is used as a humectant and skin conditioning agent in personal care products.
The Food Industry segment accounts for the largest share of consumption, with Nutraceuticals exhibiting the steepest expansion trajectory.
Form:
The physical form of fructose is dictated by its intended application, influencing handling, solubility, and functional performance in end products.
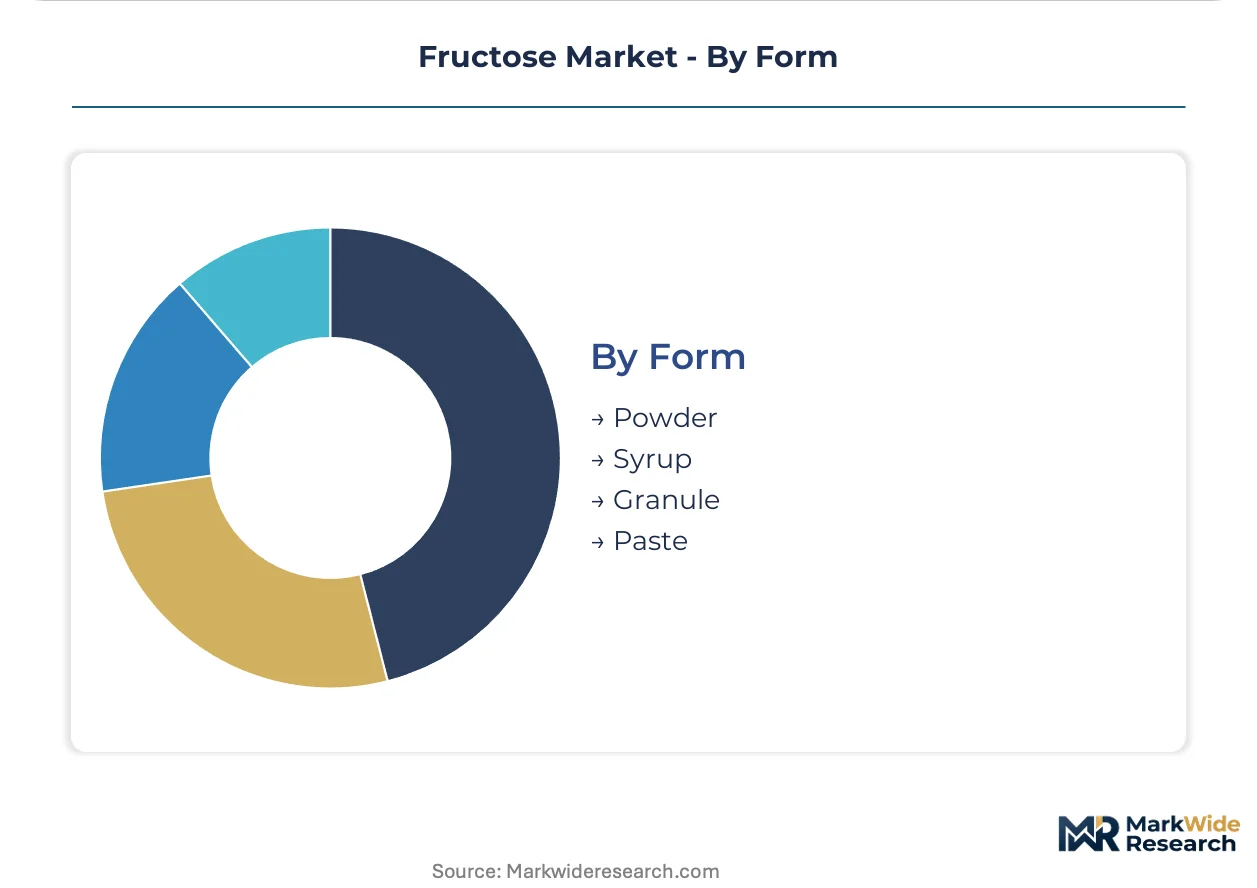
- Syrup:This liquid form, primarily High Fructose Corn Syrup, offers ease of integration into beverage formulations and other liquid food systems. Its cost-effectiveness makes it prevalent in large-volume industrial applications globally.
- Powder:Crystalline fructose is often supplied in powder form, preferred for confectionery and bakery due to its low water activity and precise dosing. Markets like Japan and Germany favor powdered forms for specialty product development.
- Granule:Granular fructose provides good flow properties and is suitable for dry mixes and certain confectionery applications.
- Paste:Fructose in paste form can be used in specific food preparations where a semi-solid consistency is required.
Syrup forms dominate industrial procurement due to volume efficiency. Powdered forms are gaining traction in specialized product lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration for fructose is particularly pronounced in large-scale food and beverage manufacturing hubs globally. These regions drive substantial volume demand for various fructose forms, from bulk high fructose corn syrup to specialty crystalline variants. Regulatory environments and consumer preferences significantly influence local market dynamics.
China
China's expansive food and beverage manufacturing industry creates sustained, large-scale demand for fructose. The State Administration for Market Regulation (SAMR) mandates specific quality and import requirements for sweeteners. The Yangtze River Delta region, a major food processing hub, drives high-volume fructose consumption.
United States
United States beverage manufacturers remain significant consumers of high fructose corn syrup. The US FDA's "Added Sugars" labeling mandates are compelling product reformulation. Corn-belt states like Iowa and Illinois are central to the nation's fructose production and supply chain.
Germany
Germany exhibits strong demand for high-purity crystalline fructose in its advanced confectionery and bakery sectors. European Food Safety Authority (EFSA) guidelines shape ingredient approvals and labeling for all food additives. The North Rhine-Westphalia region, a center for food processing, prioritizes specialized fructose forms.
Vietnam
Vietnam's growing middle class and expanding local food processing industries are fueling increased demand for fructose products. The Ministry of Health sets national food safety and ingredient standards for sweeteners. Industrial zones near Ho Chi Minh City are experiencing a surge in demand for bulk fructose.
Brazil
Brazil's extensive food industry, especially the beverage sector, represents a substantial consumer of cost-effective fructose syrups. ANVISA enforces strict regulations on food additives and nutritional labeling. The state of São Paulo, a major industrial hub, supports local sweetener production and distribution.
Fructose Market Key Industry Players
Player mix skews toward large, integrated agricultural processors and specialty ingredient providers. The market features a blend of global commodity suppliers focused on high-volume production and specialized firms offering differentiated fructose solutions. Key archetypes include multinational food ingredient giants, regional sweetener producers, and innovators in clean-label and organic variants. Strategic competitive moves involve extensive supply chain control and continuous portfolio diversification to meet evolving consumer demands.
Among the multinational food ingredient giants, Cargill Incorporated leverages extensive supply chain control to ensure compliance and consistent quality at scale across its global operations. Ingredion Incorporated occupies a position as a specialist, providing specialty fructose solutions particularly for clean-label applications demanded by health-conscious consumers in premium segments. Tate & Lyle exemplifies a broad portfolio approach, competing through its diverse range of both corn-based and alternative sweeteners to navigate varied customer requirements across numerous food categories. These firms collectively represent the strategic tension between commodity volume and differentiated product offerings in the evolving market.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle |
| DuPont |
| Roquette Frères |
| Südzucker AG |
| Galam |
| Shijiazhuang Huaxu Pharmaceutical Co Ltd |
| Others |
Cost & Logistics Intelligence
FSSC 22000 certification gates fructose supply qualification and drives price differentiation for compliant producers. This regulatory hurdle elevates market entry barriers and influences pricing across segments.
Pricing Analysis
Cost-plus contracts indexed to corn prices govern much of the bulk high fructose corn syrup market. Price differentiation stratifies across premium, standard, and economy tiers based on purity, specific certifications like organic or non-GMO, and geographic delivery costs. Pricing softness stems from intense competition among commodity suppliers and the availability of cheaper alternative sweeteners. Nutraceutical and premium clean-label segments exhibit lower price sensitivity compared to the high-volume beverage sector.
Supply Chain Analysis
Elevated inbound logistics costs, particularly for corn shipments from US Midwest to Asian processing hubs, impact fructose production expenses. Geographic supply concentration centers on the United States, China, and Brazil, drawing heavily from corn and sugar beet feedstocks. Commodity price volatility for these agricultural inputs presents a significant structural risk. Distribution runs through a mix of direct sales to large food manufacturers and specialized ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fructose market is entering a cyclical recovery, driven by stabilizing feedstock prices and renewed industrial demand in the beverage sector. Strategic positioning now can capture upside as consumer preferences for specific sweetener types evolve.
For Market Incumbents: Secure long-term supply agreements for key feedstocks like corn to mitigate commodity price volatility. Invest in advanced enzymatic separation techniques to produce high-purity crystalline and organic fructose, differentiating from standard HFCS and addressing clean-label demand. This proactive approach counters the threat of alternative sweeteners and strengthens compliance with evolving US FDA labeling mandates. Expand production capacity in underpenetrated markets like Southeast Asia to capture new growth.
For New Entrants and Emerging Players: Certification-driven sourcing gaps in organic and non-GMO fructose represent a clear opportunity for new entrants. Target the premium confectionery and nutraceutical segments in Western Europe and North America, focusing on specialized crystalline forms. A go-to-market angle emphasizing transparent sourcing and sustainable production practices can attract health-conscious consumers. Develop flexible production models to quickly respond to niche demands.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the specialty fructose production segment due to advanced separation technologies. The market offers long-term viability for players with strong supply chain control and product differentiation capabilities over a 5-10 year window. Acquisition targets should include mid-sized producers specializing in organic or high-purity crystalline fructose with established clean-label certifications. A signal to watch is the sustained growth in product launches featuring certified organic fructose.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Enzymatic Separation | Enables production of high-purity crystalline fructose, meeting demand for specialized clean-label ingredients. |
| Expand Organic Fructose Capacity | Captures premium market share by catering to health-conscious consumers and certified product lines. |
| Secure Long-Term Feedstock Contracts | Mitigates price volatility for corn and sugar beets, ensuring stable production costs for manufacturers. |
| Target Southeast Asian Markets | Leverages rising disposable incomes and growing food processing industries in countries like Vietnam. |
| Develop Sports Nutrition Applications | Addresses a niche, high-value segment by utilizing fructose's unique metabolic pathway for athletes. |
Research Approach
A standing panel of food technologists, procurement managers, regulatory affairs specialists, and R&D directors provided ongoing calibration for market trends. Primary interviews with industry stakeholders validated quantitative data, cross-referenced with secondary sources including US FDA filings and EFSA reports. Bottom-up data collection for production volumes and top-down market sizing ensured robust triangulation.
Consistency checks against external economic indicators and industry reports validated forecast outputs across the analysis window. The analytical framework modeled segmentation dimensions by application, product type, end user, and geographic region. Compound annual growth rates were derived from historical trends, market drivers, and projected technological advancements. Key forecast inputs included agricultural commodity price forecasts.
Forecasts assume regulatory continuity in US FDA and EFSA regimes; material policy shifts would require re-modeling. The analysis reflects current market dynamics, with significant disruptions like major trade disputes or agricultural crises posing revision risks. Outcomes outside this envelope require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sucrose Acetate Isobutyrate Market
Sweeteners
Russia Food Sweetener Market
Sweeteners
White Sugar Market
Sweeteners
Asia Pacific Food Sweetener Market
Sweeteners
Xylose Market
Sweeteners
France Food Sweetener Market
Sweeteners
Glucose-Fructose Syrup (GFS) Market
Sweeteners
Italy Food Sweetener Market
Sweeteners
Europe B2B Brown Sugar Market
Sweeteners
Stevia Mints Market
Sweeteners
Starch Glucose Syrup Market
Sweeteners
D Psicose Market
Sweeteners
Maltitol Market
Sweeteners
South Africa Food Sweetener Market
Sweeteners
North America Sugar Substitutes Market
Sweeteners
South America Low-Calorie Sweeteners Market