
 Starch Glucose Syrup Market | 2026-2036
Starch Glucose Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Starch Glucose Syrup Market Analysis
Market Context
High-fructose corn syrup is expanding its displacement in favor of tapioca and rice-derived starch glucose syrups across Asian formulation kitchens. Cargill Incorporated leverages integrated corn wet milling infrastructure across the American Midwest to sustain cost-advantaged glucose supply chains. Roquette Frères anchors European pea and potato starch processing, while Tate & Lyle PLC competes through specialty maltodextrin and glucose syrup blends for beverage clients.
Technical Profile and Segment Structure
Starch glucose syrup denotes a refined carbohydrate solution produced through enzymatic or acid hydrolysis of starch, yielding dextrose equivalents ranging from 20 to 100 DE that function as sweeteners, bulking agents, and moisture retainers across industrial food systems. Liquid form dominates volume throughput due to pipeline compatibility with beverage and confectionery manufacturing, though powder form captures premium positioning in pharmaceutical tableting and dry-mix applications. High fructose syrup variants lead value pools within the product type dimension, while food and beverage end use absorbs the majority of commodity-grade output; pharmaceutical-grade specifications command stricter purity thresholds and corresponding margin premiums.
Regulatory Environment and Outlook
EFSA evaluates added sugar labeling thresholds across European member states, while FDA added-sugar disclosure rules on Nutrition Facts panels reshape North American formulation decisions; China's SAMR enforces GB standards for starch-based sweetener purity and labeling claims. These frameworks collectively elevate documentation burdens and shift procurement toward suppliers with certified traceability systems. Stakeholders must monitor evolving carbohydrate classification debates and their downstream effects on formulation substitution timelines.
Market Dynamics
Formulation kitchens across Asia-Pacific are accelerating tapioca and rice-derived starch glucose syrup adoption as high-fructose corn syrup faces displacement pressure from clean-label mandates and carbon-conscious procurement policies.
Growth Catalysts
- EFSA Added Sugar Labeling Thresholds:European confectionery manufacturers are reformulating with lower-DE glucose syrups to navigate pending disclosure requirements. This regulatory pressure redirects procurement toward certified starch hydrolysate suppliers.
- Beverage Pipeline Compatibility:Liquid glucose syrups integrate directly into carbonated and still-drink manufacturing infrastructure without capital retrofit. Asian bottling clusters leverage this technical fit to scale output rapidly.
- Enzymatic Hydrolysis Efficiency:Novel pullulanase and glucoamylase enzyme blends reduce starch conversion cycle times. Processing facilities report throughput gains that compress unit economics for commodity-grade output.
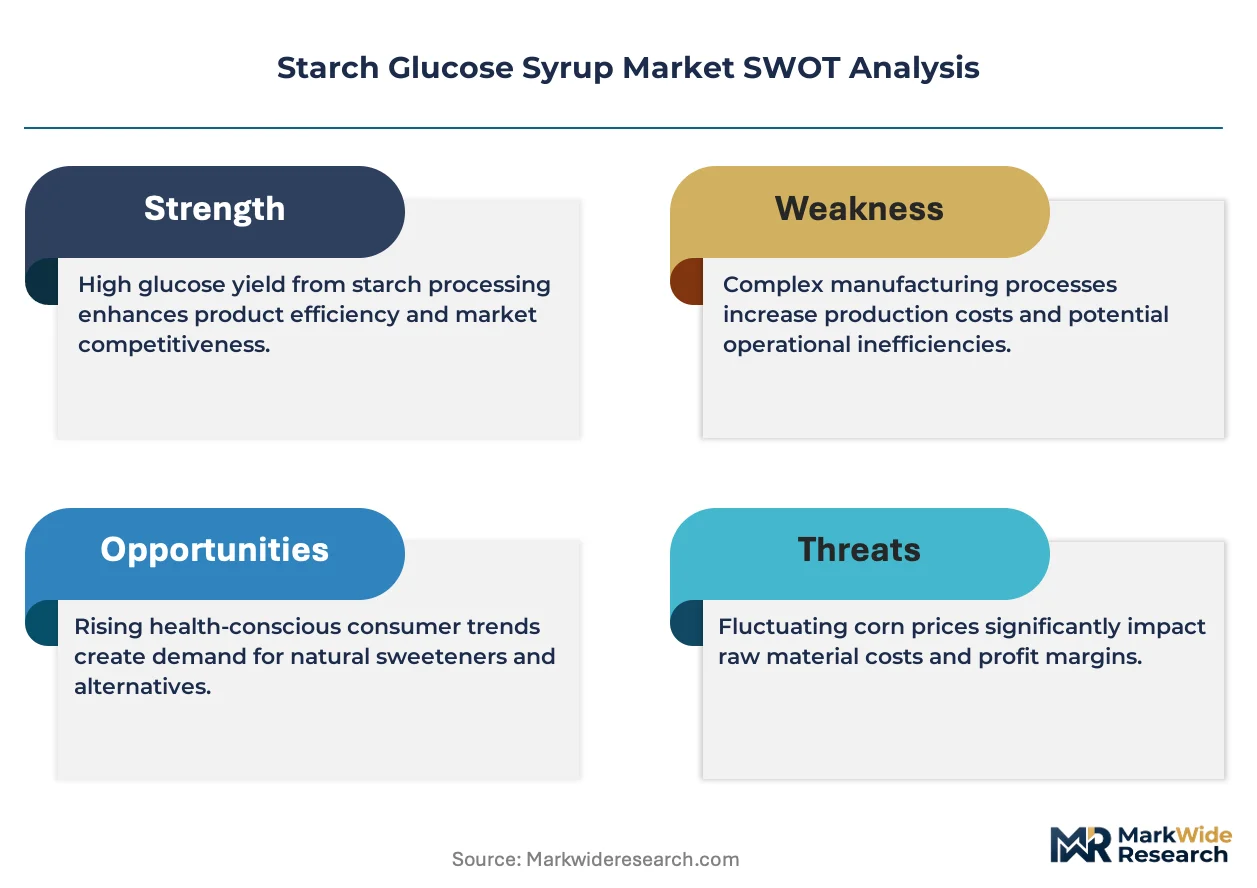
Market Restraints
- Corn Wet Milling Concentration:North American glucose supply chains depend on Midwestern corn processing infrastructure. Weather volatility and input cost spikes transmit directly to syrup pricing.
- GB Standards Compliance Burden:China's SAMR enforces purity thresholds and labeling documentation that extend qualification timelines for new market entrants. Foreign suppliers face extended certification cycles.
- Allulose and Rare Sugar Substitution:Emerging low-calorie sweeteners capture premium beverage formulation share. Starch glucose syrups face displacement risk in reduced-sugar product lines.
Strategic Opportunities
- Pharmaceutical-Grade Specification Gap:Tableting and excipient applications demand higher-purity glucose syrups with documented traceability. Current supply scarcity creates margin expansion potential for qualified producers.
- India PLI Scheme for Food Processing:Production-linked incentives for ingredient manufacturing attract greenfield starch hydrolysis capacity. Early movers secure cost-advantaged positions in expanding domestic confectionery demand.
- Clean-Label Convergence with Carbon Accounting:EU Green Deal supply chain disclosure requirements favor tapioca and potato-derived syrups with verifiable lower-carbon intensity. Certification-ready suppliers capture premium positioning.
Industry Challenges
- Enzyme Biochemist Talent Scarcity:Optimized starch conversion requires specialized expertise in enzyme kinetics and process control. Processing facilities report extended recruitment cycles for qualified technical staff.
- Multi-Jurisdiction Documentation Complexity:Simultaneous compliance with FDA added-sugar disclosure, EFSA threshold evaluations, and SAMR GB standards strains quality assurance bandwidth.
- Legacy Dextrose Equivalent Specification Mismatch:Existing customer formulations lock in specific DE ranges. New hydrolysis technologies producing alternative sweetness profiles face adoption friction without reformulation support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Starch Glucose Syrup Market |
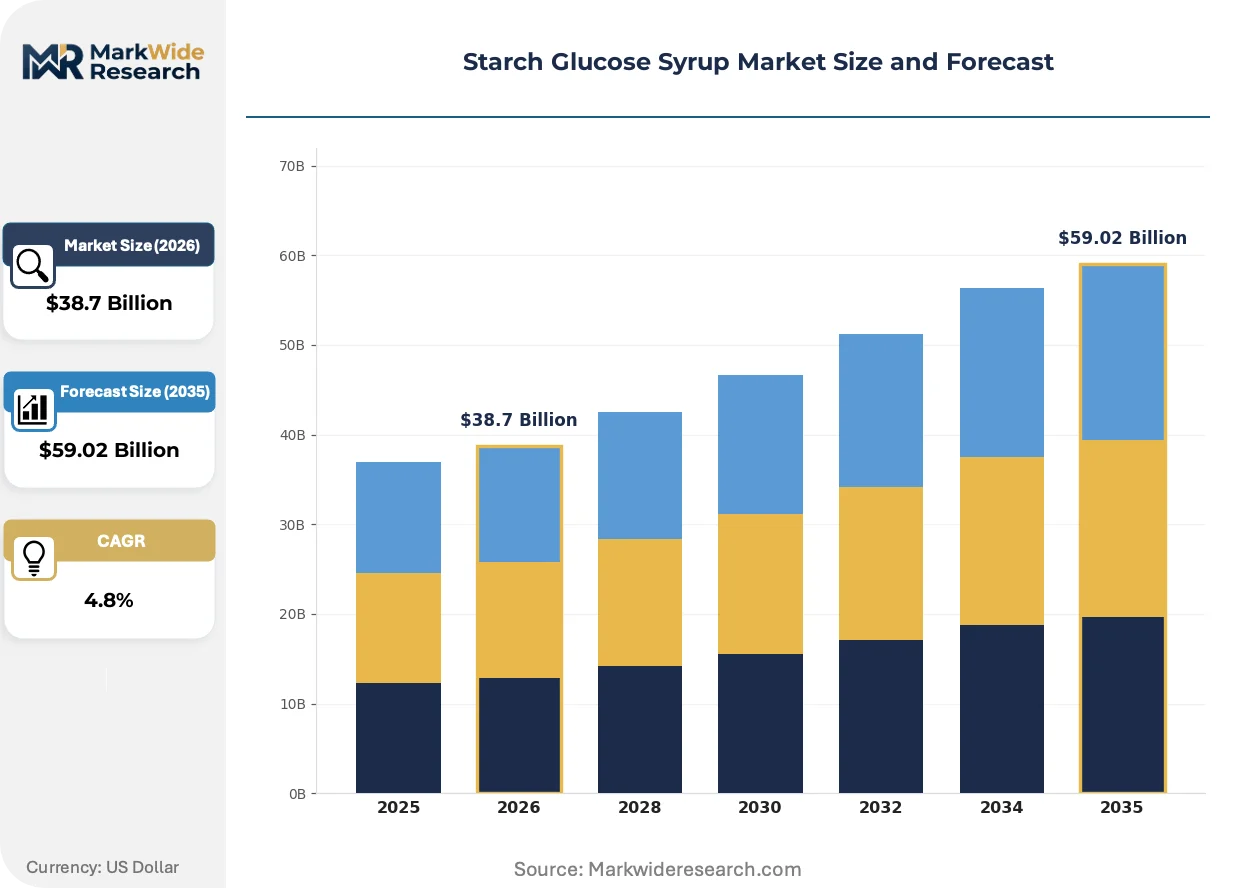
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Syrup, Dark Syrup, High Fructose Syrup, Regular Syrup End Use Industry: Food & Beverage, Pharmaceuticals, Personal Care, Animal Feed Form: Liquid, Powder, Concentrate, Granules Packaging Type: Bottles, Drums, Bags, Bulk Containers |
| Companies Covered | Tate & Lyle PLC, Tereos SCA, Cargill Incorporated, Agrana Group, Südzucker AG, Archer Daniels Midland Company, Roquette Frères, Grain Processing Corporation, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Starch Glucose Syrup Market Emerging Trajectories
Enzymatic precision and regulatory disclosure mandates are converging to reshape starch glucose syrup specification standards, with formulation kitchens now demanding documented carbon intensity alongside traditional sweetness and functionality metrics.
Continuous enzymatic hydrolysis systems employing immobilized enzyme reactors are rewriting process economics for mid-scale processors. Confectionery manufacturers in Thailand and Vietnam adopt these systems to reduce batch-to-batch variation. The technology is compressing capital barriers that previously favored only integrated multinational wet millers.
EU Green Deal supply chain due diligence requirements now extend to imported starch-based sweeteners. European food manufacturers demand documented deforestation-free sourcing and carbon intensity disclosures from Asian suppliers. High-DE syrup categories face the steepest documentation burden as they serve the most label-scrutinized consumer segments.
Beverage formulators are consolidating supplier relationships around integrated ingredient-service partnerships. Technical support for reformulation, rather than commodity pricing alone, now determines procurement decisions. This behavioral shift is most visible in German and Dutch beverage clusters where clean-label positioning commands retail shelf access.
Starch Glucose Syrup Market Segmentation
Starch glucose syrup specifications diverge sharply across certification requirements, with pharmaceutical-grade demands for documented purity and traceability creating margin premiums unavailable in commodity food-grade segments. Understanding these tiered compliance burdens allows suppliers to prioritize qualification investments and capture value pools aligned with their technical capabilities.
Product Type:
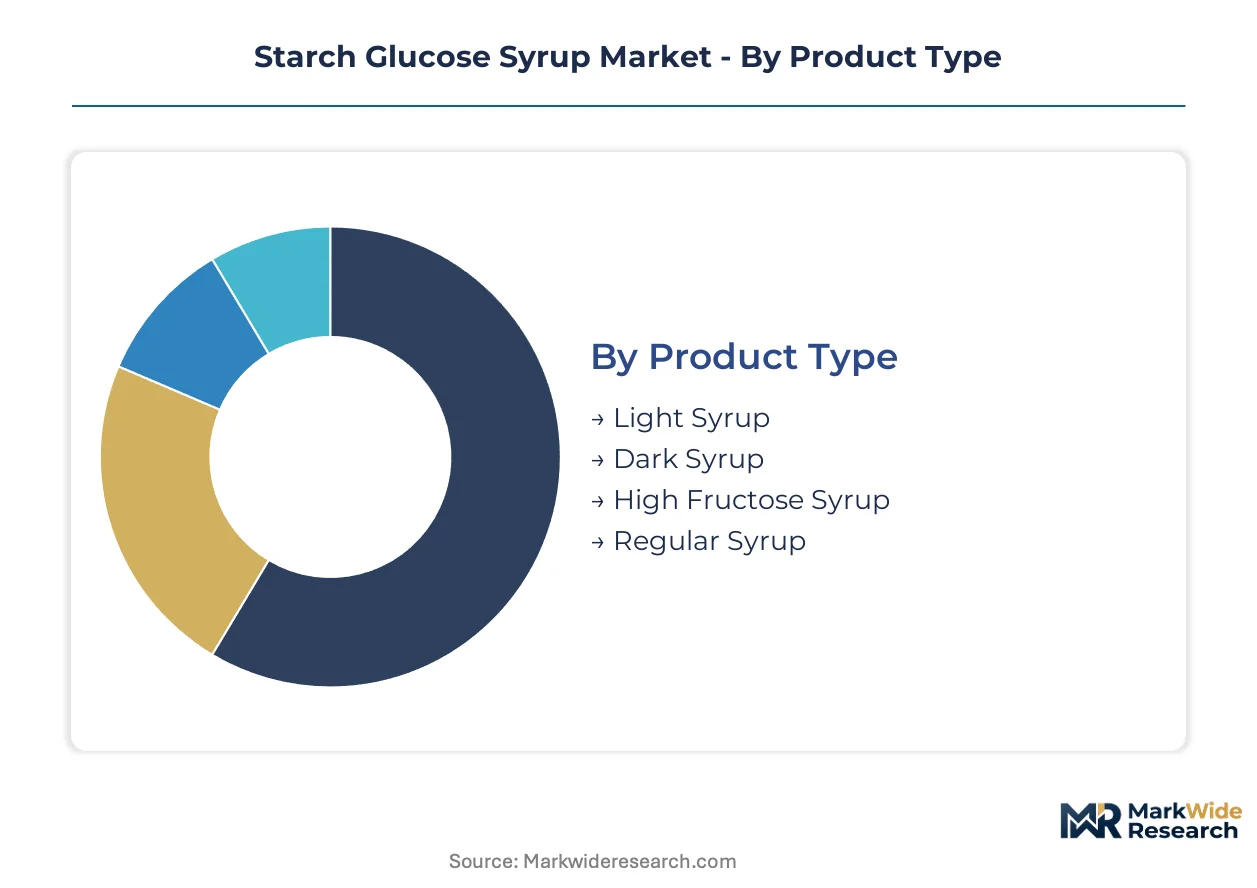
High fructose syrup variants carry the heaviest regulatory documentation load under FDA added-sugar disclosure rules and EFSA threshold evaluations, while light and dark syrups navigate simpler food-grade certification pathways.
- High Fructose Syrup:Enzymatic isomerization elevates fructose content above glucose baseline, yielding sweetness intensity that reduces required dosage in beverage formulations. North American bottling clusters in Atlanta and Chicago concentrate procurement here, though clean-label substitution pressure from tapioca-derived alternatives is accelerating reformulation timelines.
- Light Syrup:Lower dextrose equivalent ranges (20-38 DE) deliver subtle sweetness with enhanced moisture retention for baked goods and confectionery. German and Dutch clean-label manufacturers favor this category for reduced-sugar positioning that satisfies EU Green Deal carbon accounting requirements without triggering added-sugar disclosure thresholds.
- Dark Syrup:Maillard reaction products from extended heating develop color and caramel notes valued in brewing and sauce applications. British and Irish distilleries anchor demand.
- Regular Syrup:Mid-range DE specifications (38-55 DE) balance cost and functionality for standard industrial food manufacturing. Chinese and Indian processors dominate volume output.
Regular syrup sits at the top of the volume ranking, with light syrup climbing the fastest.
End Use Industry:
Cost tier stratification separates pharmaceutical specifications demanding batch-level documentation from commodity food applications where price per kilogram dominates procurement decisions.
- Food & Beverage:Carbonated drink manufacturing in Bangkok and Jakarta, confectionery production in Mumbai and São Paulo, and sauce formulation across Guangdong province absorb the majority of commodity-grade output. Pipeline compatibility with existing liquid handling infrastructure preserves incumbent supplier relationships despite clean-label substitution pressure.
- Pharmaceuticals:Tablet binding and excipient applications require USP-grade purity with documented endotoxin limits and heavy metal thresholds. Supply scarcity in this segment creates margin expansion opportunities for qualified producers willing to maintain dedicated production lines and enhanced quality assurance staffing.
- Personal Care:Humectant properties in skincare formulations leverage lower-purity glucose syrups without pharmaceutical documentation burdens. South Korean and Japanese cosmetic manufacturers drive specialty demand.
- Animal Feed:Palatability enhancement and energy density for livestock and pet nutrition applications tolerate higher moisture content and broader specification ranges. Brazilian and Argentinian feed compounders represent the largest volume purchasers.
Food and beverage commands absolute volume leadership, while pharmaceuticals offers the steepest margin expansion trajectory.
Form:
Volume concentration favors liquid formats compatible with pipeline infrastructure, while powder and concentrate forms capture premium positioning through transportation efficiency and extended shelf stability.
- Liquid:Direct pump compatibility with beverage and confectionery manufacturing lines eliminates handling steps and dust exposure. Thai and Vietnamese processors deploying continuous enzymatic hydrolysis systems report compressed batch-to-batch variation that satisfies multinational buyer specifications.
- Powder:Spray-dried or roller-dried crystallization enables dry-mix applications and pharmaceutical tableting where moisture content must remain below strict thresholds. European and North American buyers pay freight savings premiums for reduced shipping weight.
- Concentrate:Reduced water content lowers transportation costs for long-haul supply chains serving landlocked manufacturing clusters. Indian and Bangladeshi importers favor this format.
- Granules:Free-flowing characteristics suit automated dosing equipment in feed manufacturing and select food processing applications. Limited demand relative to other forms.
Liquid form dominates volume throughput, with powder gaining share fastest in pharmaceutical and premium food segments.
Packaging Type:
Customer type and order scale dictate packaging selection, with bulk containers serving integrated multinational processors and smaller formats addressing regional compounders lacking dedicated liquid handling infrastructure.
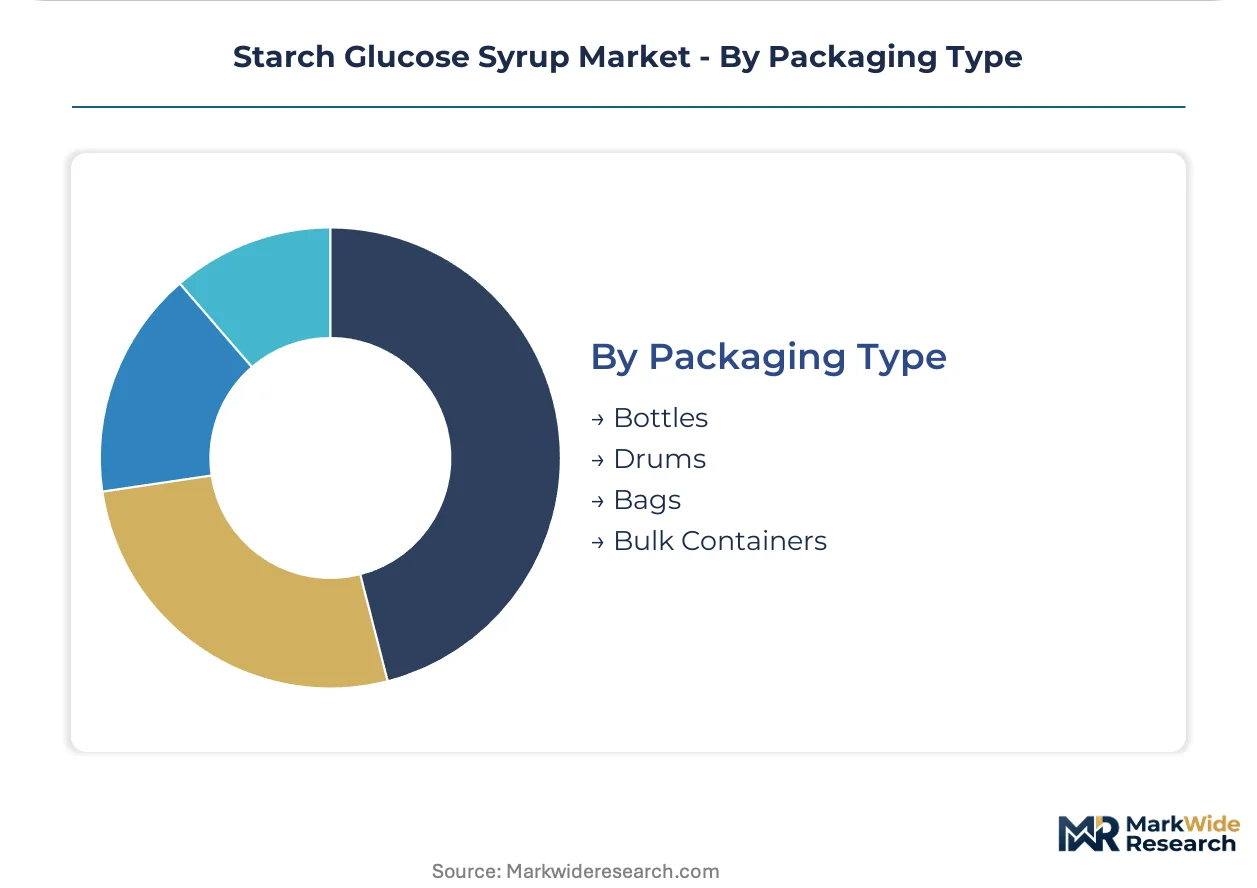
- Bulk Containers:Tanker truck and flexitank delivery to integrated wet millers and large-scale beverage manufacturers minimizes per-unit packaging cost. Cargill's Midwestern corn processing network exemplifies this model.
- Drums:Standard 200-liter steel or plastic drums balance handling convenience with cost for mid-scale confectionery and sauce manufacturers. German and Italian mid-cap food processors represent core demand.
- Bags:Multi-layer laminated sacks suit powder and granule formats for dry-mix and feed applications. Chinese and Indian regional distributors stock this format.
- Bottles:Retail-scale packaging for artisanal food producers and laboratory sampling requirements carries the highest per-unit cost. Limited commercial significance.
Bulk containers sit at the top of the volume ranking, with drums climbing the fastest as mid-scale Asian processors expand capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Guangdong province hosts the densest concentration of starch glucose syrup processing infrastructure, with enzymatic hydrolysis facilities scaling output to serve confectionery and beverage manufacturers across Southeast Asian export corridors.
United States
Midwestern corn wet milling clusters in Iowa and Illinois supply glucose syrup to Atlanta and Chicago bottling operations. FDA added-sugar disclosure rules on Nutrition Facts panels are forcing reformulation toward lower-DE alternatives. Cargill's integrated processing network anchors supply security for multinational beverage clients.
Germany
Clean-label confectionery manufacturers in Cologne and Hamburg are pivoting toward tapioca-derived syrups to satisfy EU Green Deal carbon accounting requirements. EFSA threshold evaluations on added sugar labeling are accelerating procurement shifts. Roquette Frères maintains pea and potato starch processing leadership in Lestrem.
India
Mumbai and Ahmedabad confectionery producers are absorbing expanding domestic glucose syrup output as the PLI scheme for food processing attracts greenfield starch hydrolysis capacity. FSSAI enforcement of purity standards is extending qualification timelines for imported alternatives. Maharashtra's processing clusters report the fastest capacity expansion.
Thailand
Bangkok-area beverage manufacturers deploy continuous enzymatic hydrolysis systems to reduce batch-to-batch variation in tapioca-derived syrup production. The country's national food regulator enforces starch-based sweetener labeling claims that favor domestic suppliers. Chonburi province hosts the densest concentration of enzymatic conversion facilities serving ASEAN export markets.
Brazil
São Paulo feed compounders represent the largest volume purchasers of lower-purity glucose syrups for livestock palatability enhancement. ANVISA pharmaceutical-grade specifications create margin premiums for qualified producers willing to maintain dedicated production lines. Minas Gerais corn processing infrastructure is expanding to reduce import dependence.
Starch Glucose Syrup Market Vendor Landscape
Global majors compete with regional champions across enzymatic conversion technology and certified traceability systems. The market structure divides between integrated multinational wet millers with captive corn supply and mid-scale Asian processors deploying novel continuous hydrolysis systems. Three archetypes dominate: Midwestern corn-based integrated processors, European pea and potato starch specialists, and Southeast Asian tapioca-derived syrup innovators. Competitive intensity centers on M&A activity to secure enzyme biotechnology capabilities and strategic partnerships with beverage formulators seeking reformulation support.
Within the integrated multinational tier, Cargill Incorporated and Tate & Lyle PLC occupy positions defined by geographic processing footprint and customer technical service depth. Roquette Frères exemplifies the European specialty starch archetype, anchoring pea and potato-derived syrup supply for clean-label manufacturers. Among Asia-Pacific tapioca processors, regional champions compete on carbon intensity documentation and EU Green Deal compliance readiness rather than scale alone.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Tereos SCA |
| Cargill Incorporated |
| Agrana Group |
| Südzucker AG |
| Archer Daniels Midland Company |
| Roquette Frères |
| Grain Processing Corporation |
| Ingredion Incorporated |
| Others |
Supply Flow & Price Mechanics
Continuous enzymatic hydrolysis systems are compressing capital barriers for mid-scale processors while simultaneously fragmenting supply concentration away from integrated Midwestern wet millers. This technology diffusion enables Thai and Vietnamese tapioca processors to undercut corn-derived syrup pricing on carbon-accounted tenders, rewiring procurement decisions across European clean-label manufacturers.
Pricing Analysis
Input-cost pass-through from corn futures volatility dominates North American glucose syrup pricing, with Midwestern weather shocks transmitting directly to Atlanta and Chicago bottling contracts. Three-tier pricing structure across pharmaceutical-grade, certified food-grade, and commodity-grade levels separates margin pools sharply. Cost compression in commodity-grade regular syrup is intensifying because Chinese and Indian processors are expanding enzymatic conversion capacity. Animal feed compounders in Brazil and Argentina exhibit the highest price sensitivity, while pharmaceutical tablet manufacturers absorb substantial premiums for USP-grade purity documentation.
Supply Chain Analysis
Freight cost differentials between liquid bulk tankers and powder container loads determine supplier competitiveness for landlocked manufacturing clusters in India and Bangladesh. Supply concentrates in China, Thailand, and the United States, with enzymatic conversion facilities clustering in Guangdong province and Chonburi province. Raw material dependencies on corn, tapioca root, and rice starch create agricultural exposure that feeds from monsoon patterns and harvest cycles. Single-source vulnerability around pullulanase and glucoamylase enzyme suppliers strains batch consistency. Distribution runs through integrated multinational wet millers for large beverage accounts, while regional distributors serve mid-scale confectionery compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in starch glucose syrup hinges on pharmaceutical-grade certification investments and carbon-intensity documentation premiums that command pricing power above commodity tiers.
For Market Incumbents: Cement enzyme biotechnology capabilities through dedicated recruitment pipelines and process control partnerships to defend against talent scarcity eroding conversion efficiency. Deepen backward integration into tapioca and rice starch sourcing in Thailand and Vietnam to secure clean-label supply chains ahead of EU Green Deal due diligence requirements. Prioritize pharmaceutical-grade production line segregation to capture scarcity premiums in tableting applications. For New Entrants and Emerging Players: Artisanal food producers in European metropolitan clusters represent an underserved buyer archetype seeking retail-scale packaging with technical reformulation support. Specialty personal care manufacturers in South Korea and Japan offer white-space demand for humectant-grade syrups without pharmaceutical documentation burdens. Establish direct technical service partnerships rather than competing on commodity pricing alone. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Asian processors deploying continuous hydrolysis systems but lacking multinational certification infrastructure. Long-term viability favors suppliers with documented carbon intensity and deforestation-free sourcing aligned with EU supply chain disclosure mandates. Watch for FDA added-sugar disclosure rule enforcement timelines as inflection indicators for reformulation-driven procurement shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Investment | Dedicated USP-grade production lines capture margin premiums from tablet binding demand scarcity. |
| Backward Integration into Tapioca Sourcing | Captive Thai and Vietnamese starch supply secures EU Green Deal carbon accounting compliance. |
| Continuous Enzymatic Hydrolysis Deployment | Immobilized reactor systems compress batch variation for Bangkok beverage manufacturer specifications. |
| Enzyme Biotechnology Talent Acquisition | Specialized biochemist recruitment pipelines overcome extended hiring cycles constraining throughput gains. |
| Carbon Intensity Documentation Program | Verified lower-carbon intensity certifications unlock premium positioning in German clean-label procurement. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at enzymatic conversion facilities, procurement leads at multinational beverage manufacturers, technical R&D directors at starch processors, and quality assurance heads at pharmaceutical excipient suppliers. Secondary validation drew from FDA added-sugar disclosure filings, EFSA threshold evaluation documents, SAMR GB standard registrations, customs trade data for starch-based sweetener flows, and SEC filings from listed ingredient manufacturers. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Comparable-period anchoring linked projection assumptions to historical enzymatic conversion efficiency trends and regulatory implementation timelines across the analysis window. Segmentation modeling spanned dextrose equivalent tiers, end-use industry specifications, form factors, and regional production hub cost structures. CAGRs were derived from slope analysis of segment-specific demand curves and capacity expansion announcements. Forecast inputs incorporated enzyme kinetics improvement trajectories and clean-label substitution elasticity estimates.
Underlying measurement precision varies by segment; pharmaceutical-grade and certified food-grade categories carry tighter precision than commodity-grade regular syrup given documentation requirements. Forecasts reflect assumptions about regulatory enforcement timing and enzyme technology diffusion rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
South America Sugar Substitutes Market
Sweeteners
Allulose Powder Market
Sweeteners
D Psicose Market
Sweeteners
Tapioca Maltodextrin Market
Sweeteners
Molasses Market
Sweeteners
Sugar Free Lifesavers Market
Sweeteners
Mexico Food Sweetener Market
Sweeteners
Asia-Pacific Low-Calorie Sweeteners Market
Sweeteners
Dry Sweeteners Market
Sweeteners
Refined Cane Sugar Market
Sweeteners
Italy Food Sweetener Market
Sweeteners
Asia-Pacific Plant-Derived and Synthetic Sugar Market
Sweeteners
Liquid Sugar Market
Sweeteners
Plant-Derived Sweetener Market
Sweeteners
Polyphenol Sweetener Market
Sweeteners
Sucralose Market