
 Maltitol Market | 2026-2036
Maltitol Market Size, Share, and Industry Trends Forecast 2026-2036
Maltitol Market Outlook
The EU Green Deal is restructuring procurement priorities across European food manufacturers, pushing reformulation timelines toward low-glycemic sweeteners. Roquette Frères leverages its decades of polyol expertise to anchor supply relationships with premium confectionery brands across Western Europe. Cargill Incorporated competes through backward integration into corn-derived hydrogenation feedstocks, sustaining cost advantages in crystalline maltitol grades. Shandong Futaste Co. dominates export volumes from Shandong Province, positioning its powdered and liquid portfolios for pharmaceutical and nutraceutical off-take.
Maltitol is a hydrogenated disaccharide polyol derived from maltose, typically manufactured through catalytic hydrogenation of starch hydrolysates at 120–160 bar pressure and 120–140°C, yielding a sweetener with approximately 90% of sucrose's sweetness but half the caloric content and negligible glycemic impact. Its primary commercial purpose centers on sugar-free and reduced-calorie food systems where bulking, humectancy, and crystallization control match functional performance of conventional sugars. Granular and powdered formats lead volume given their direct substitutability in bakery and confectionery dry mixes, while liquid maltitol represents the fastest-expanding category as beverage manufacturers seek pumpable, pre-dissolved sweetening systems with improved moisture retention. Crystalline grades command concentrated margin pools from pharmaceutical companies requiring tight particle-size distribution for tablet compression and coating applications.
The FDA maintains GRAS status for maltitol with specified laxation threshold labeling, while EFSA reviews updated daily intake guidance under evolving sweetener safety protocols, and China's NMPA enforces pharmaceutical excipient registration for maltitol entering drug formulations. These frameworks collectively determine market access timelines, purity specifications, and end-use eligibility across the three largest demand jurisdictions. Stakeholders must monitor regulatory divergence on polyol labeling claims and excipient certification requirements to anticipate reformulation costs and geographic expansion feasibility.
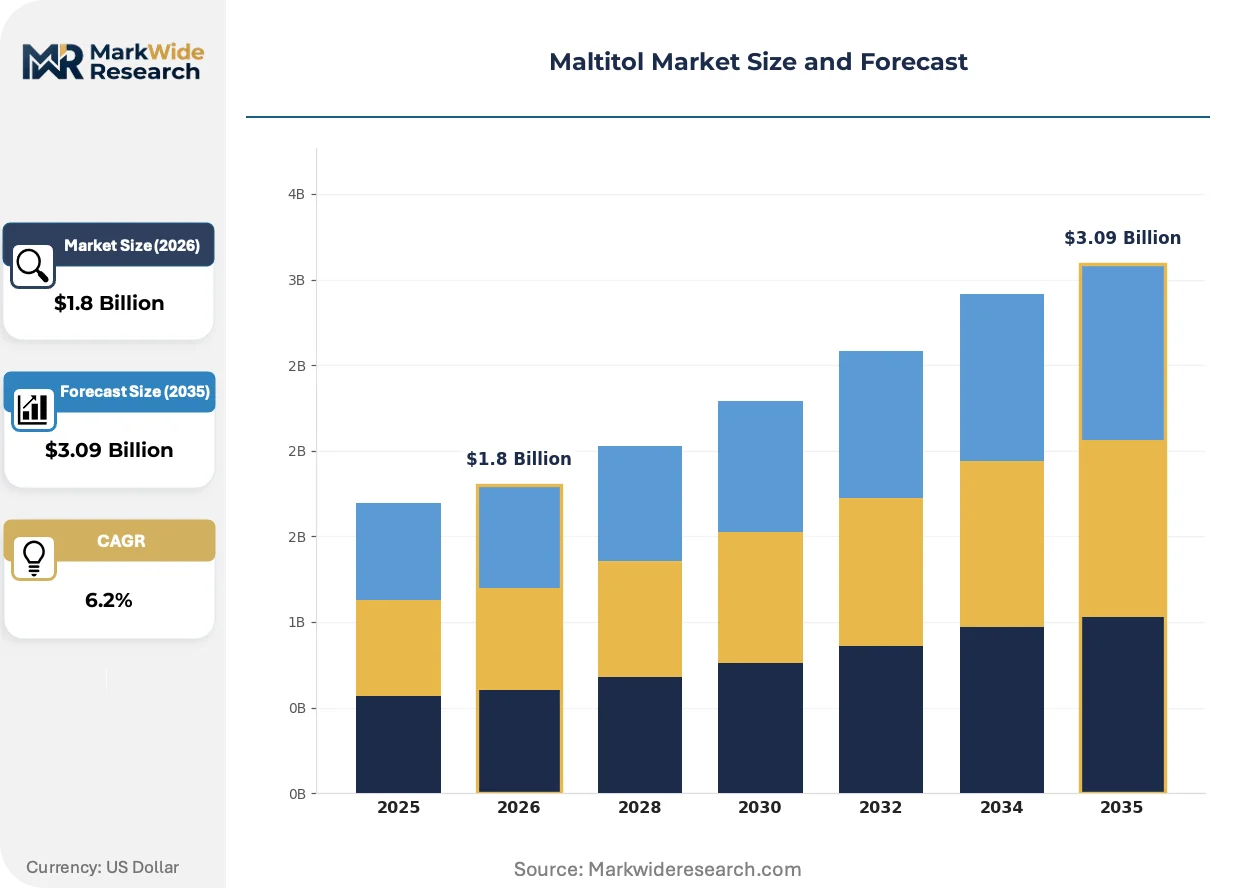
Market Dynamics
Sugar reduction mandates across multiple jurisdictions are compressing reformulation timelines and forcing confectionery manufacturers to secure polyol supply chains ahead of regulatory enforcement deadlines.
Growth Catalysts
- EU Green Deal sustainability criteria:European food manufacturers face procurement protocol overhauls that prioritize low-glycemic sweeteners with verified carbon footprints, accelerating maltitol qualification programs.
- China's pharmaceutical excipient registration:NMPA enforcement of maltitol purity standards for drug formulations is expanding addressable market into nutraceutical tablets and coatings.
- Hydrogenation catalyst efficiency gains:Improved nickel-based catalytic systems at 120–160 bar pressure ranges are reducing energy intensity per ton of crystalline maltitol output.
Market Restraints
- Starch feedstock cost volatility:Corn and wheat hydrolysate prices fluctuate with agricultural commodity cycles, compressing margin predictability for hydrogenation-dependent producers.
- Shandong Province supply concentration:Chinese export volumes cluster within a single provincial production base, creating geographic risk exposure for international pharmaceutical buyers.
- Laxation threshold labeling requirements:FDA GRAS specifications mandate explicit digestive tolerance warnings that limit consumer acceptance in certain confectionery categories.
Strategic Opportunities
- Beverage pumpable systems:Liquid maltitol formats remain underpenetrated in ready-to-drink formulations despite superior moisture retention versus granular alternatives.
- EFSA daily intake guidance revision:Updated polyol safety protocols under review may expand permissible usage levels across European bakery applications.
- Continuous hydrogenation reactor technology:Integration of flow chemistry with membrane separation is enabling real-time purity adjustment for pharmaceutical-grade output.
Industry Challenges
- Pharmaceutical particle-size certification:Tight distribution specifications for tablet compression require capital-intensive micronization equipment and extended validation timelines.
- Dual food-pharma supply chain segregation:Maintaining separate handling protocols for excipient-grade versus food-grade maltitol strains warehouse and logistics infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maltitol Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.09 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powdered, Liquid, Crystalline Application: Beverages, Confectionery, Bakery, Dairy Distribution Channel: Retail, Online, Wholesale, Supermarkets End User: Food Manufacturers, Pharmaceutical Companies, Nutraceuticals, Others |
| Companies Covered | Ingredion Incorporated, Mitsubishi Corporation Life Sciences Limited, Roquette Frères, E.I. du Pont de Nemours and Company, Shandong Futaste Co., Cargill Incorporated, Tate & Lyle PLC, Zhejiang Huakang Pharmaceutical Co., Ltd., Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maltitol Market Strategic Shifts
Manufacturing technology and procurement behavior are diverging sharply across food and pharmaceutical end-uses, creating parallel innovation tracks with distinct purity and scale requirements.
Continuous flow hydrogenation is decentralizing maltitol production economics by enabling smaller-scale reactors to achieve pharmaceutical-grade purity without batch-scale capital thresholds. Mid-sized European confectionery ingredient suppliers are piloting modular 500-ton annual capacity units. This technology is decentralizing geographic production assumptions that previously favored concentrated Asian supply bases.
EFSA's evolving sweetener safety protocols are tightening purity documentation requirements for polyols entering European food systems. Manufacturers must now submit expanded toxicological datasets covering hydrogenation catalyst residue levels. Pharmaceutical excipient buyers in Germany and France are accelerating qualification of suppliers with pre-validated EFSA submission packages.
Long-term offtake contracting is replacing spot purchasing among major confectionery brands seeking supply security for reformulated product lines. Tier-one European chocolate manufacturers now contract eighteen to twenty-four months forward for crystalline maltitol volumes. This pattern is most visible in Belgium and Switzerland where premium sugar-free product portfolios carry higher ingredient specification requirements.
Maltitol Market Segmentation
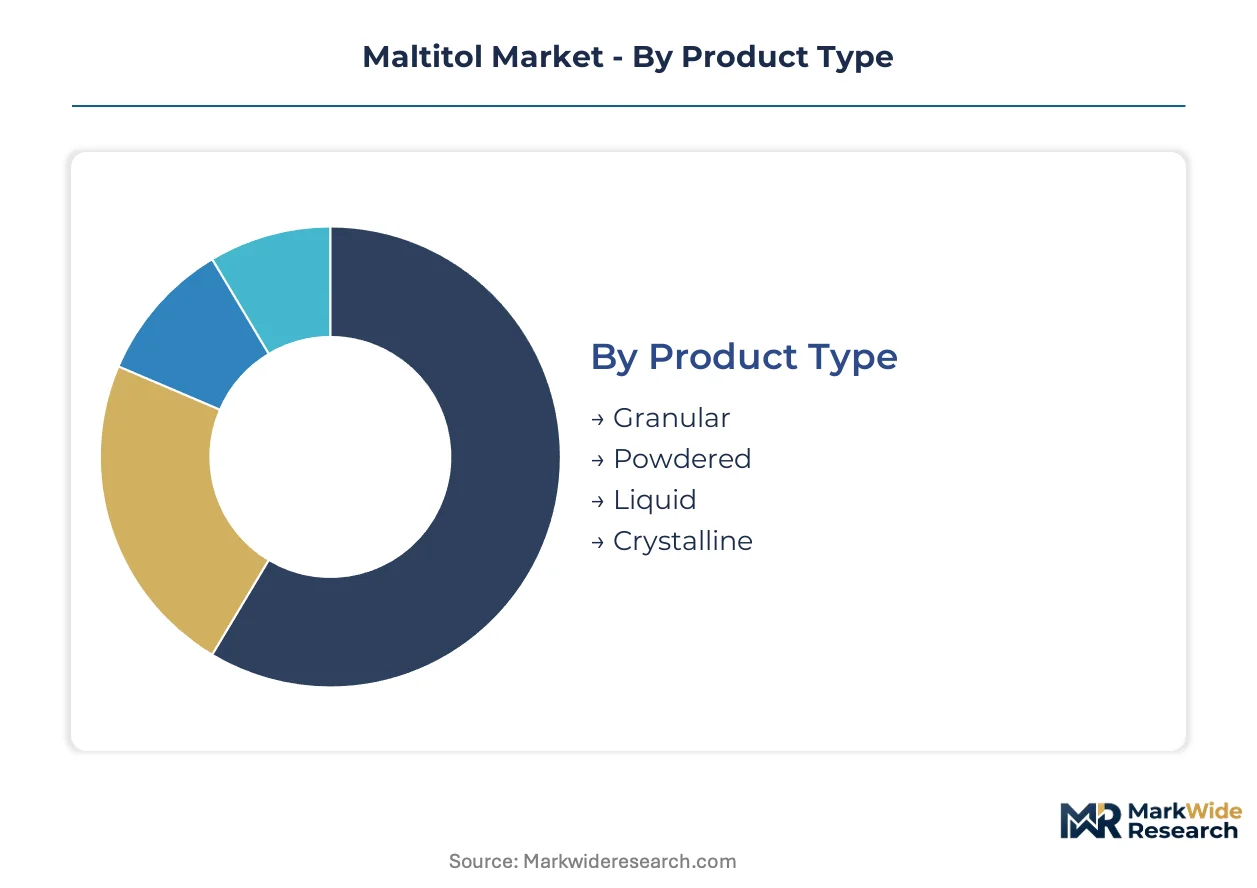
Maltitol's functional versatility across bulking, humectancy, and crystallization control creates distinct specification requirements by end-use. Segmentation reveals where certification burdens concentrate and which formats command premium positioning.
Product Type:
Granular and crystalline grades require pharmaceutical excipient registration under China's NMPA, while liquid formats face lighter food-grade documentation. Powdered variants sit between these tiers depending on particle-size distribution claims.
- Granular:Coarse, free-flowing particles manufactured through controlled crystallization of hydrogenated maltose syrup. Confectionery manufacturers in Belgium and Switzerland contract eighteen to twenty-four months forward for this grade to secure supply for sugar-free chocolate portfolios. FDA GRAS status applies with standard laxation threshold labeling.
- Liquid:Pre-dissolved 70-75% solids solution offering pumpable handling and superior moisture retention in beverage systems. Ready-to-drink manufacturers represent underpenetrated demand despite functional advantages over dry formats. EFSA documentation requirements are lighter than pharmaceutical grades but expanding under revised polyol safety protocols.
- Powdered:Micronized particles below 150 microns for rapid dissolution in dry mixes. Bakery applications dominate offtake where direct sugar substitution simplifies reformulation timelines.
- Crystalline:Tight particle-size distribution specifications for tablet compression and coating. NMPA registration and EMA excipient certification create dual documentation burdens for suppliers serving pharmaceutical buyers in Germany and France.
Granular sits at the top of the volume ranking, with liquid climbing the fastest.
Application:
Cost tier separation is pronounced: confectionery and bakery absorb standard food-grade pricing, while dairy and beverage applications increasingly specify premium-certified grades for clean-label positioning.
- Confectionery:Hard candies, chewing gum, and chocolate represent the anchor application where maltitol's cooling effect and crystallization control match sucrose functionality. EU Green Deal procurement protocols are accelerating qualification programs among Western European manufacturers.
- Beverages:Functional drinks and reduced-sugar juices utilize liquid maltitol for pumpable dosing and moisture retention. Penetration remains limited by formulation complexity and consumer tolerance labeling requirements.
- Bakery:Cookies, cakes, and pastries employ granular and powdered grades for bulk replacement. Reformulation timelines are compressing ahead of sugar reduction mandate enforcement across multiple jurisdictions.
- Dairy:Ice cream and yogurt applications leverage maltitol's freezing point depression and humectancy. Premium positioning in this segment is driving demand for verified low-glycemic certification.
Confectionery holds the largest share, though beverages are gaining share fastest as liquid format adoption accelerates.
Distribution Channel:
Volume concentration varies sharply by customer scale: wholesale dominates industrial offtake to food manufacturers, while retail and online fragment across small-scale nutraceutical formulators.
- Wholesale:Bulk procurement by food and pharmaceutical manufacturers through direct supplier relationships. Long-term offtake contracting is replacing spot purchasing among tier-one European chocolate brands.
- Supermarkets:Packaged consumer formats for home baking and specialty diets. Shelf placement competes with stevia and erythritol alternatives in reduced-sugar aisles.
- Online:Direct-to-nutraceutical formulator sales, particularly for pharmaceutical-grade crystalline grades requiring detailed certificate of analysis documentation.
- Retail:Specialty health food stores and pharmacy chains for consumer-packaged goods. Laxation threshold labeling limits placement in certain confectionery categories.
Wholesale commands the volume lead, with online expanding most quickly as pharmaceutical buyers seek direct supplier relationships.
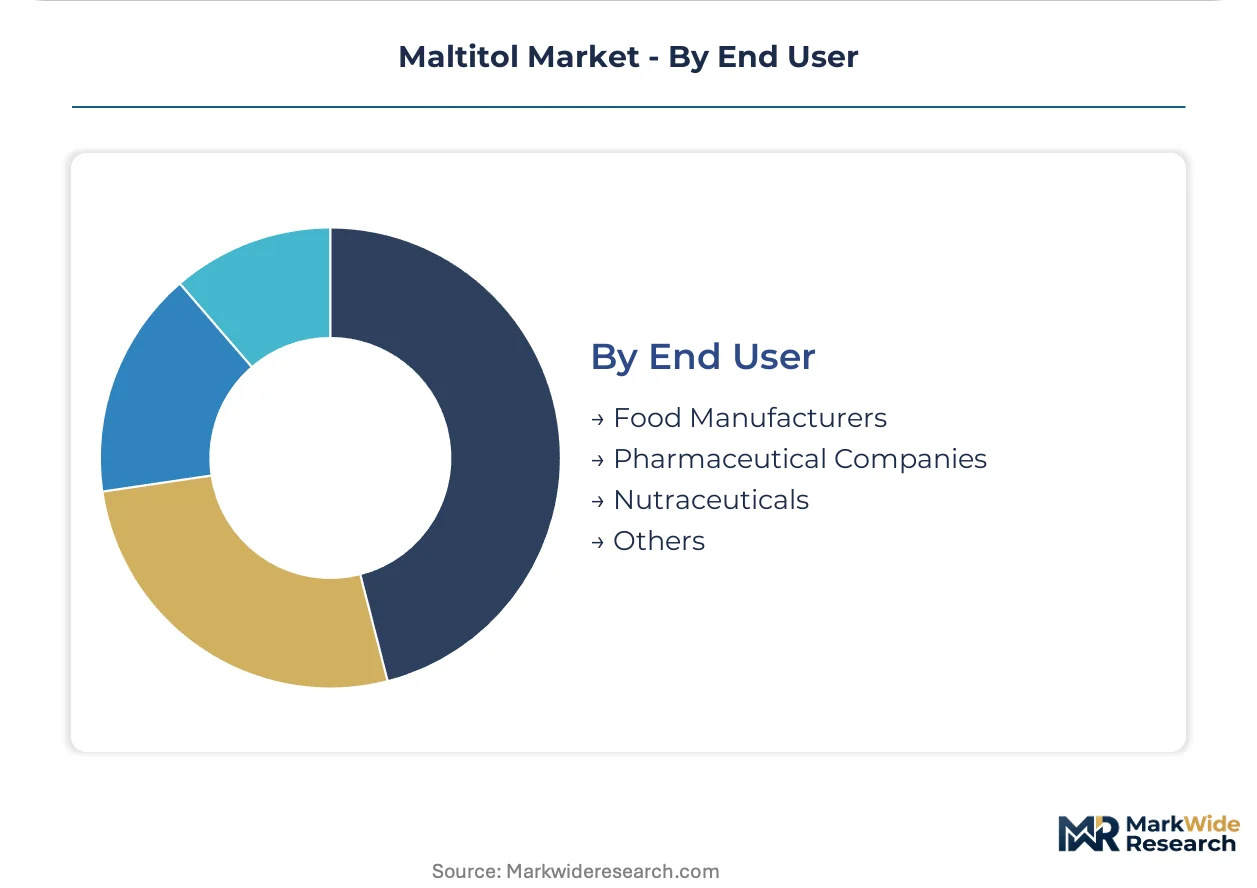
End User:
Margin structure inverts across this dimension: pharmaceutical companies pay 40-60% premiums for excipient-grade certification, while food manufacturers prioritize cost efficiency at scale.
- Food Manufacturers:Confectionery, bakery, and dairy producers driving bulk demand. Shandong Province export volumes cluster to serve this segment, creating geographic concentration risk for international buyers.
- Pharmaceutical Companies:Tablet compression and coating applications requiring tight particle-size distribution. EMA and NMPA dual certification requirements strain supplier qualification timelines.
- Nutraceuticals:Dietary supplements and functional foods occupying the boundary between food and pharma regulations. EFSA daily intake guidance revisions under review may expand permissible usage levels.
- Others:Cosmetics and personal care applications utilizing humectant properties. Regulatory classification varies by jurisdiction, with some markets treating these as cosmetic ingredients rather than food additives.
Food manufacturers dominate volume, with nutraceuticals on the steepest expansion trajectory as regulatory clarity improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maltitol production originated in European starch-processing facilities during the 1970s, with French and Belgian refiners pioneering hydrogenation technologies for commercial polyol manufacture. This historical foundation established Western Europe's early dominance in excipient-grade certification standards and pharmaceutical applications.
China
Shandong Province hosts the world's most concentrated maltitol manufacturing base, with hydrogenation facilities scaling pharmaceutical-grade output for both domestic nutraceutical formulators and export buyers. NMPA enforcement of excipient registration requirements is tightening purity documentation for drug formulations. Qingdao and Weifang industrial clusters are expanding crystalline production capacity to serve EMA-qualified buyers in Germany and France.
Germany
German pharmaceutical companies drive premium demand for tight particle-size distribution grades used in tablet compression and coating applications. EMA excipient certification requirements strain supplier qualification timelines for crystalline maltitol entering drug formulations. The Rhineland chemical corridor maintains specialized handling infrastructure for dual food-pharma supply chain segregation.
United States
Confectionery manufacturers in the Midwest and Northeast are accelerating reformulation timelines ahead of sugar reduction mandate enforcement across multiple state jurisdictions. FDA GRAS status for maltitol maintains specified laxation threshold labeling requirements that limit consumer acceptance in certain product categories. Chicago and Minneapolis industrial zones concentrate dry mix processing for bakery and chocolate applications.
Belgium
Premium chocolate manufacturers in Brussels and Antwerp contract eighteen to twenty-four months forward for crystalline maltitol volumes to secure supply for sugar-free product portfolios. EU Green Deal procurement protocols are accelerating qualification programs among Western European confectionery brands. The Flemish chemical cluster maintains backward integration into corn-derived hydrogenation feedstocks for cost-competitive crystalline grades.
France
Roquette Frères leverages decades of polyol expertise from its Lestrem headquarters to anchor supply relationships with premium confectionery brands across Western Europe. EFSA reviews of updated daily intake guidance under evolving sweetener safety protocols are expanding purity documentation requirements for polyols entering European food systems. The Hauts-de-France region maintains specialized micronization capacity for pharmaceutical particle-size certification.
Maltitol Market Competitive Environment
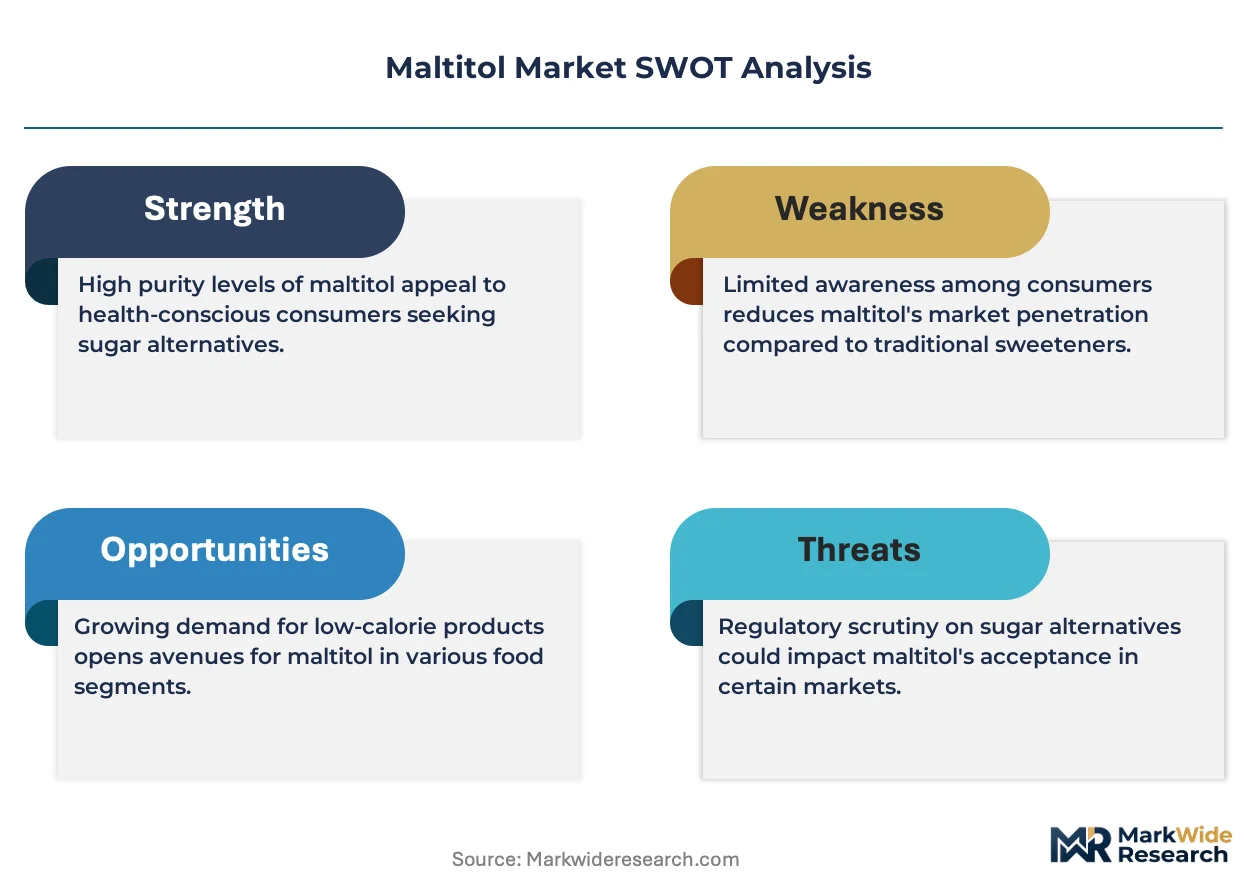
Premium-margin players sit above commodity-margin players across certification-grade tiers, with pharmaceutical excipient qualification creating structural separation from standard food-grade suppliers. The vendor base organizes around three strategic archetypes: integrated starch processors with captive hydrogenation capacity, specialized polyol refiners with pharmaceutical validation capabilities, and regional distributors serving niche nutraceutical formulators. Competitive dynamics center on long-term offtake contracting and backward integration into feedstock supply.
Among integrated processors with global reach, Roquette Frères, Cargill Incorporated, and Shandong Futaste Co. exemplify distinct geographic and tier positioning. Roquette Frères represents the European premium-tier archetype with established pharmaceutical relationships. Cargill Incorporated occupies the North American integrated processor position with upstream control over corn-derived feedstocks. Shandong Futaste Co. anchors the Chinese export-oriented volume tier serving international pharmaceutical and food manufacturers from its Shandong Province production base.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Mitsubishi Corporation Life Sciences Limited |
| Roquette Frères |
| E.I. du Pont de Nemours and Company |
| Shandong Futaste Co. |
| Cargill Incorporated |
| Tate & Lyle PLC |
| Zhejiang Huakang Pharmaceutical Co., Ltd. |
| Archer Daniels Midland Company |
| Others |
Value Chain & Pricing Dynamics
Starch hydrolysate feedstock costs cascade through maltitol's three-tier pricing architecture, with corn and wheat price volatility transmitted from agricultural commodity markets to hydrogenation-dependent producers in Shandong Province and Western Europe. Pharmaceutical-grade crystalline output commands 40-60% premiums over standard food-grade granular, while liquid formats trade at mid-tier positioning despite faster volume expansion.
Pricing Analysis
Long-term offtake contracting dominates volume transactions among tier-one European chocolate manufacturers, compressing spot market liquidity and anchoring price discovery eighteen to twenty-four months forward. Three-tier pricing structure across pharmaceutical excipient, premium food-grade, and standard industrial levels separates margin pools, with EMA and NMPA dual certification requirements sustaining the top tier. Pricing pressure stems from Shandong Province supply concentration and starch feedstock cost volatility. Food manufacturers exhibit highest price sensitivity, while pharmaceutical companies absorb certification premiums for particle-size precision.
Supply Chain Analysis
EU Green Deal domestic-content mandates and NMPA pharmaceutical excipient registration are reshaping raw material sourcing protocols for European and Chinese manufacturers respectively. Production gravity centers on China, Belgium, and France, with hydrogenation capacity clustering in Shandong Province's Qingdao and Weifang industrial zones. The supply chain draws from corn and wheat starch hydrolysates, nickel-based hydrogenation catalysts, and micronization equipment. Single-province concentration in China creates geographic vulnerability for international pharmaceutical buyers. Distribution runs through direct supplier relationships with food and pharmaceutical manufacturers, supplemented by online channels for nutraceutical formulators seeking certificate of analysis documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory momentum into structural demand expansion, with EU Green Deal sustainability criteria and China's NMPA enforcement creating dual jurisdiction pull for certified maltitol output.
For Market Incumbents: To counter Shandong Province supply concentration risk, Roquette Frères and Cargill Incorporated should deepen backward integration into corn-derived hydrogenation feedstocks while accelerating EMA pre-validated submission packages for pharmaceutical buyers in Germany and France. Capacity addition in the Rhineland chemical corridor would reduce geographic dependency for European excipient-grade demand.
For New Entrants and Emerging Players: Capture underpenetrated ready-to-drink beverage applications with liquid maltitol pumpable systems, where formulation complexity barriers have slowed adoption despite functional advantages over dry formats. Target direct-to-nutraceutical formulator sales through online channels with detailed certificate of analysis documentation, leveraging lighter EFSA entry requirements versus pharmaceutical-grade certification burdens.
For Investors and Strategic Acquirers: Consolidation pressure builds where dual food-pharma supply chain segregation strains warehouse infrastructure and extended validation timelines create capability scarcity. Mid-sized European confectionery ingredient suppliers piloting continuous flow hydrogenation technology represent viable acquisition targets over a five-to-ten year viability window. Watch EFSA daily intake guidance revision as the signal for expanded European bakery application permissions.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Secures crystalline maltitol volumes for Belgian and Swiss sugar-free chocolate portfolios ahead of reformulation deadlines. |
| Backward Integration | Cargill's upstream control over corn-derived feedstocks sustains cost advantages in crystalline grades versus hydrogenation-dependent competitors. |
| Green Manufacturing Transition | EU Green Deal procurement protocols prioritize low-glycemic sweeteners with verified carbon footprints for Western European confectionery manufacturers. |
| Capacity Expansion | Shandong Province's Qingdao and Weifang clusters scale pharmaceutical-grade output for EMA-qualified buyers in Germany and France. |
| Joint Venture | Modular 500-ton continuous flow hydrogenation units decentralize production economics for mid-sized European ingredient suppliers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hydrogenation plant managers, procurement leads at European chocolate manufacturers, pharmaceutical excipient buyers in Germany and France, and NMPA regulatory consultants with secondary validation through customs trade data, EFSA submission databases, SEC 10-K filings of integrated starch processors, and pharmaceutical excipient certification records. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Segment-weighting approaches applied differential growth assumptions across pharmaceutical excipient, premium food-grade, and standard industrial tiers, with granular and liquid format splits modeled separately. End-use segmentation incorporated confectionery, beverage, bakery, and dairy application trajectories, while regional clusters captured China, Germany, United States, Belgium, and France production and demand dynamics. CAGRs derived from elasticity-adjusted consumption forecasts tied to sugar reduction mandate enforcement timelines and pharmaceutical registration completion rates.
Starch feedstock price volatility, regulatory divergence on polyol labeling claims, and hydrogenation catalyst supply constraints are the dominant revision risks to modeled consumption trajectories. Forecasts reflect documented assumptions on reformulation timelines and certification completion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Agave Nectar Market
Sweeteners
Steviol Glycoside Market
Sweeteners
Natural Caloric Sweeteners Market
Sweeteners
China Saccharin Market
Sweeteners
Vietnam Food Sweetener Market
Sweeteners
North America Stevia Market
Sweeteners
Raw Beetroot Sugar Market
Sweeteners
Vanilla Sugar Market
Sweeteners
Asia-Pacific Low-Calorie Sweeteners Market
Sweeteners
Africa and Middle East Sugarcane Syrup Market
Sweeteners
Granulated Sugar Market
Sweeteners
Sour Sugar Market
Sweeteners
Maltodextrin Market
Sweeteners
Middle East and Africa Low Calorie Sweeteners Market
Sweeteners
Asia-Pacific Plant-Derived and Synthetic Sugar Market
Sweeteners
D Psicose Market