
 North America Sugar Substitutes Market | 2026-2036
North America Sugar Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sugar Substitutes Market Analytics
The beverage industry is repositioning around reduced-sugar portfolios, pulling demand toward high-intensity sweeteners and plant-derived alternatives. Cargill Incorporated leverages its stevia supply chain and fermentation capabilities to anchor the natural sweetener segment. Ingredion Incorporated competes through specialty polyols and texture-modifying ingredient systems that replace bulk sugar functionality. Tate & Lyle PLC differentiates with its allulose platform, targeting bakers and dairy processors seeking caloric reduction without sensory trade-offs.
North America sugar substitutes comprise non-nutritive and low-calorie compounds engineered to replicate sucrose sweetness intensity, stability under thermal processing, and bulking properties in food matrices. These ingredients typically deliver sweetness potencies ranging from 30 to 600 times that of sucrose, enabling formulation at parts-per-million levels while maintaining FDA-recognized daily intake thresholds. Stevia and allulose currently lead product type expansion, with stevia benefiting from GRAS status and allulose gaining traction through its rare sugar classification and minimal glycemic impact. The powder and granular forms dominate commercial volumes due to handling efficiency in industrial batching, though liquid formats are accelerating in beverage fountain and ready-to-drink applications.
FDA nutrition labeling rules, Health Canada's front-of-package sodium and sugars regulations, and USDA dietary guidance collectively shape permissible health claims and reformulation incentives across the continent. The FDA's updated definition of dietary fiber and added sugars disclosure requirements directly influence how manufacturers position sugar substitute blends on Nutrition Facts panels. Stakeholders must monitor evolving GRAS notification pathways for novel sweeteners and anticipate state-level sugar tax proposals that could accelerate category substitution beyond current trajectories.
Market Dynamics
Beverage manufacturers face mounting pressure from FDA added-sugar disclosure rules and Health Canada front-of-package labeling mandates. These regulatory instruments force rapid reformulation cycles, compressing supplier qualification timelines and redrawing procurement relationships across the continent.
Growth Catalysts
- Clean-Label Mandates:FDA nutrition panel updates require gram-level added sugars disclosure. Beverage brands accelerate high-intensity sweetener adoption to maintain permissible health claims.
- Diabetes Prevalence:Clinical nutrition protocols in US hospital systems and Canadian long-term care facilities prioritize low-glycemic ingredient sourcing for therapeutic foodservice.
- Stevia Supply Maturation:Paraguayan leaf cultivation and US-based fermentation capacity expansion reduce input cost volatility for Reb M and Reb D glycosides.
Market Restraints
- GRAS Notification Bottlenecks:FDA's self-affirmation pathway for novel rare sugars creates 18-24 month market entry delays, advantaging incumbents with existing approvals.
- Sugar Price Volatility:Mexican cane harvest fluctuations and US beet crop yields transmit directly to high-fructose corn syrup pricing, distorting substitute economics seasonally.
- Bulking Functionality Gaps:High-intensity sweeteners lack sucrose's crystallization and browning properties, requiring costly polyol or fiber adjuncts in baked applications.
Strategic Opportunities
- Allulose Scale-Up:Tate & Lyle's Clinton, Iowa fermentation facility and emerging domestic producers target cost parity with erythritol for US bakery and dairy penetration.
- Canadian Provincial Procurement:Quebec and Ontario school nutrition guidelines create institutional foodservice demand for naturally sourced, zero-calorie sweetening systems.
- Liquid Fountain Formats:Ready-to-drink beverage manufacturing corridors in Texas and Georgia accelerate pump-dispensed concentrate adoption for precise sweetness calibration.
Industry Challenges
- Flavor Chemist Shortage:Formulation of clean-taste stevia-allulose blends demands specialized sensory science expertise concentrated in Midwest agricultural research clusters.
- Cross-Border Label Harmonization:Divergent Health Canada and FDA daily value calculations for allulose force dual-SKU production runs, inflating inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sugar Substitutes Market |
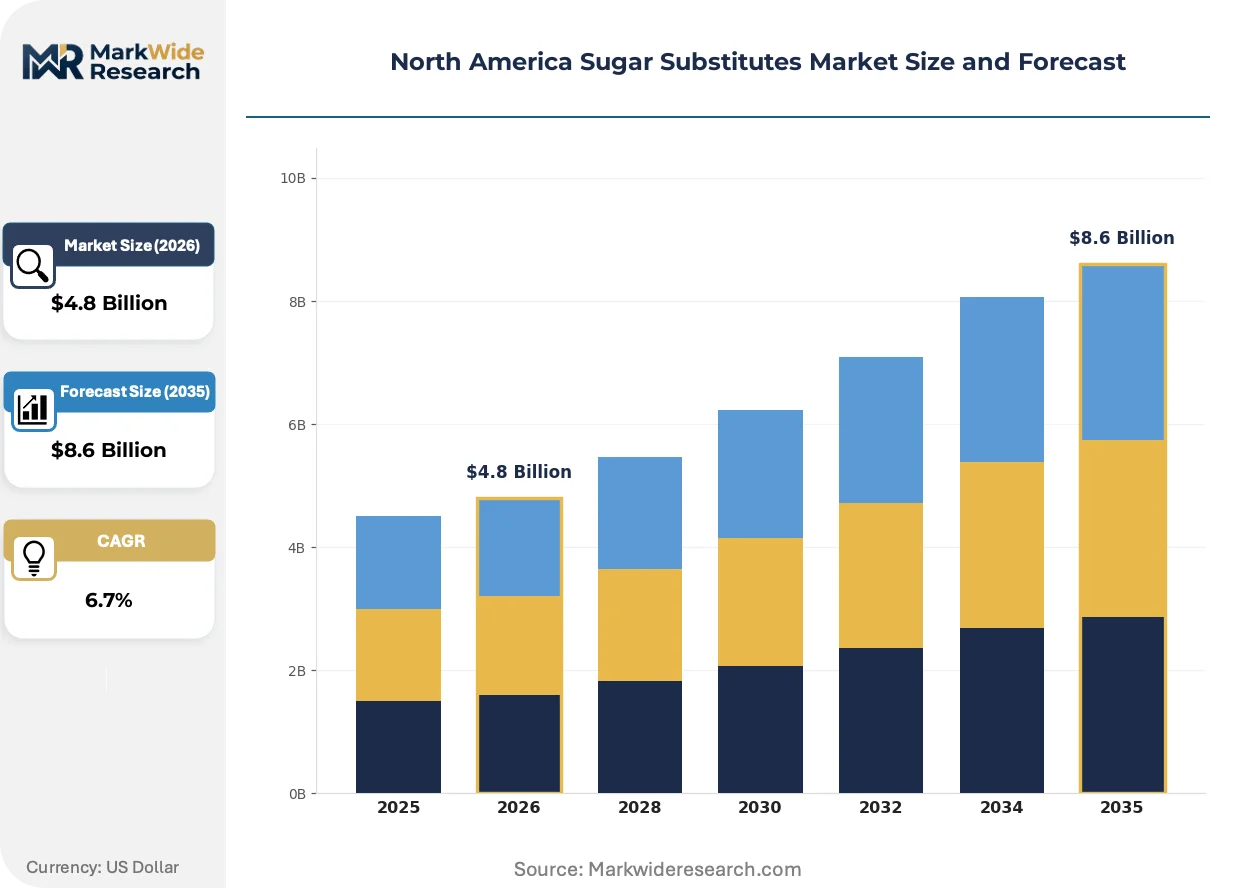
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia, Aspartame, Sucralose, Acesulfame Potassium End User: Food Industry, Beverage Industry, Health & Wellness, Pharmaceuticals Form: Liquid, Powder, Granular, Tablet Application: Baking, Beverages, Dairy, Confectionery |
| Companies Covered | Cargill Incorporated, Ingredion Incorporated, Archer Daniels Midland Company, Tate & Lyle PLC, International Flavors & Fragrances Inc., DuPont de Nemours Inc., Roquette Frères, Ajinomoto Co., Inc., GLG Life Tech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sugar Substitutes Market Evolving Landscape
Bioprocessing advances and regulatory clarity around rare sugars are restructuring how sweetness is manufactured and labeled. These forces converge on fermentation-derived ingredients and precision-blending platforms that reduce reliance on agricultural commodity cycles.
Enzymatic conversion of corn-derived fructose into allulose is modularizing production economics for US manufacturers. Dairy processors and ice cream formulators in the Upper Midwest adopt this route to achieve 70% caloric reduction without compromising freezing-point depression. The technology compresses capital requirements for mid-scale entrants previously excluded by extraction-based supply chains.
Health Canada's 2025 front-of-package nutrition symbol regulations mandate black-and-white "high in sugars" warnings on prepackaged foods. Canadian retail brands reformulate using monk fruit and stevia blends to avoid shelf-space penalties. US exporters to Canadian grocery channels face parallel compliance costs, accelerating cross-border formulation standardization.
Contract manufacturing relationships are shortening from multi-year agreements to 12-18 month pilot programs with performance clauses. Small beverage startups in Austin and Toronto bypass traditional distributor networks, sourcing directly from ingredient houses with minimum order quantities below 500 kilograms. This channel disintermediation concentrates in functional drink and kombucha segments where batch flexibility outweighs unit cost optimization.
North America Sugar Substitutes Market Segmentation
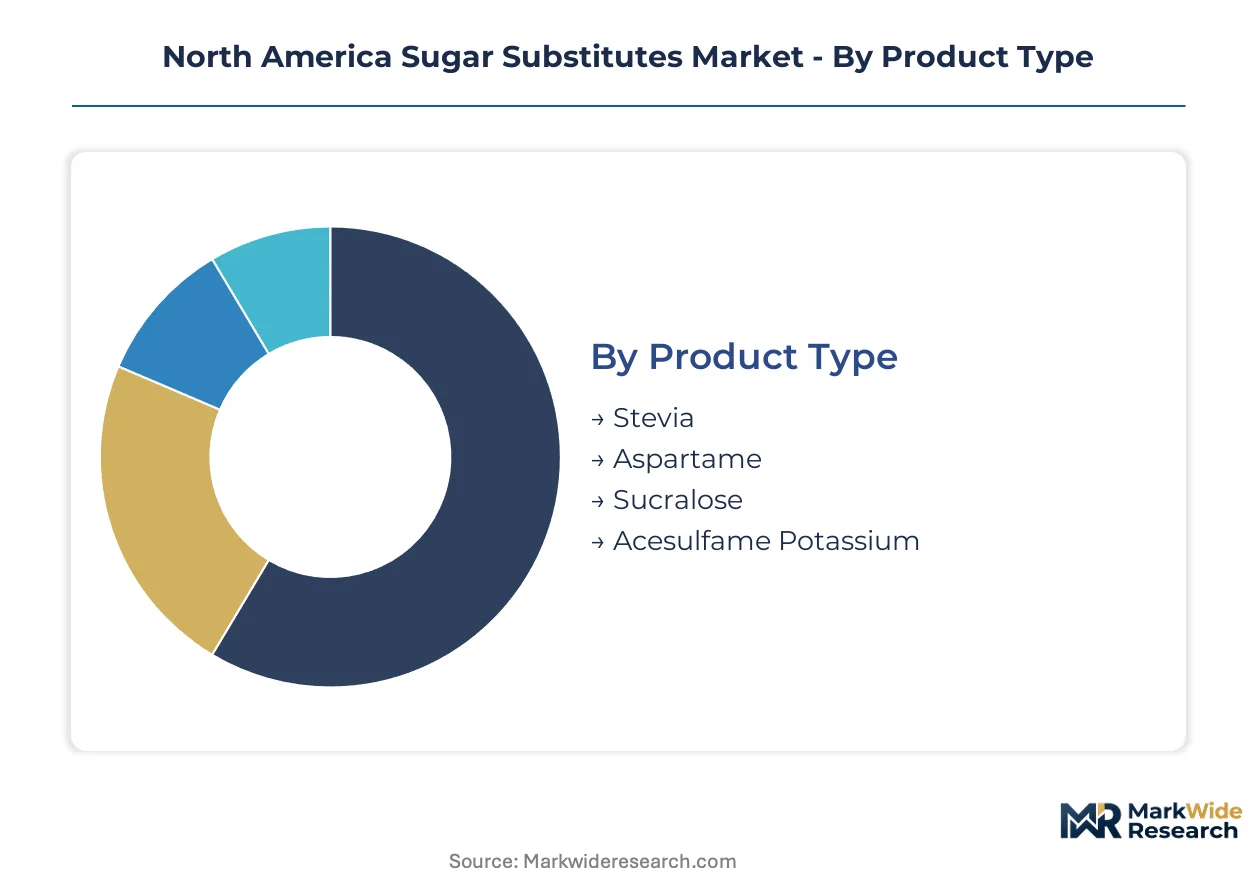
Formulators select sugar substitutes based on thermal stability, sweetness potency, and clean-label positioning. Procurement patterns diver sharply between beverage manufacturers seeking high-intensity solutions and bakery operators demanding bulking functionality. Each segment category reflects distinct technical trade-offs that reshape supplier relationships across the continent.
Product Type:
Cost tier dictates procurement volume, with natural extracts commanding premiums over synthetic alternatives.
- Stevia:Leaf-derived glycosides (Reb M, Reb D) deliver 200-400x sucrose sweetness with GRAS recognition. US beverage corridors in Texas and Georgia concentrate demand as FDA-added-sugar disclosure rules accelerate clean-label reformulation.
- Aspartame:Methyl ester of aspartic acid and phenylalanine provides 180x sweetness intensity at low cost. Canadian carbonated soft drink manufacturers maintain volume commitments despite methyl ester stability limitations under prolonged heat exposure.
- Sucralose:Chlorinated disaccharide tolerates baking temperatures up to 119°C, serving US cookie and cracker manufacturers.
- Acesulfame Potassium:Heat-stable oxathiazinone derivative blends synergistically with aspartame in fountain beverage systems.
Volume sits with Aspartame; growth tilts toward Stevia.
End User:
Application complexity determines formulation service intensity and technical support requirements.
- Beverage Industry:Ready-to-drink and fountain systems demand precise sweetness calibration with minimal aftertaste. Health Canada front-of-package labeling mandates force Canadian bottlers toward rapid reformulation cycles.
- Food Industry:Baked goods, sauces, and condiments require Maillard reaction compatibility and moisture retention. US Midwest bakery clusters prioritize allulose-stevia blends for browning performance.
- Health & Wellness:Sports nutrition and meal replacement powders source high-purity monk fruit and erythritol combinations.
- Pharmaceuticals:Excipient-grade polyols serve chewable tablet and syrup formulations with defined pharmacopeial monographs.
Procurement scale favors Beverage Industry; margin expansion concentrates in Pharmaceuticals.
Form:
Handling efficiency and dosing precision shape manufacturing corridor preferences.
- Powder:Free-flowing crystalline grades dominate industrial batching with standard mesh sizes. US dairy processors in Wisconsin and Minnesota specify powder for yogurt and ice cream base incorporation.
- Liquid:Pump-dispensed concentrates enable real-time sweetness adjustment in high-speed bottling lines. Texas and Georgia RTD manufacturing corridors accelerate liquid format adoption for production flexibility.
- Granular:Table-top packaging for foodservice and retail channels requires flow agents and anti-caking systems.
- Tablet:Unit-dose formats serve institutional foodservice and airline catering with portion-controlled dispensing.
Industrial volume clusters in Powder; format innovation accelerates in Liquid.
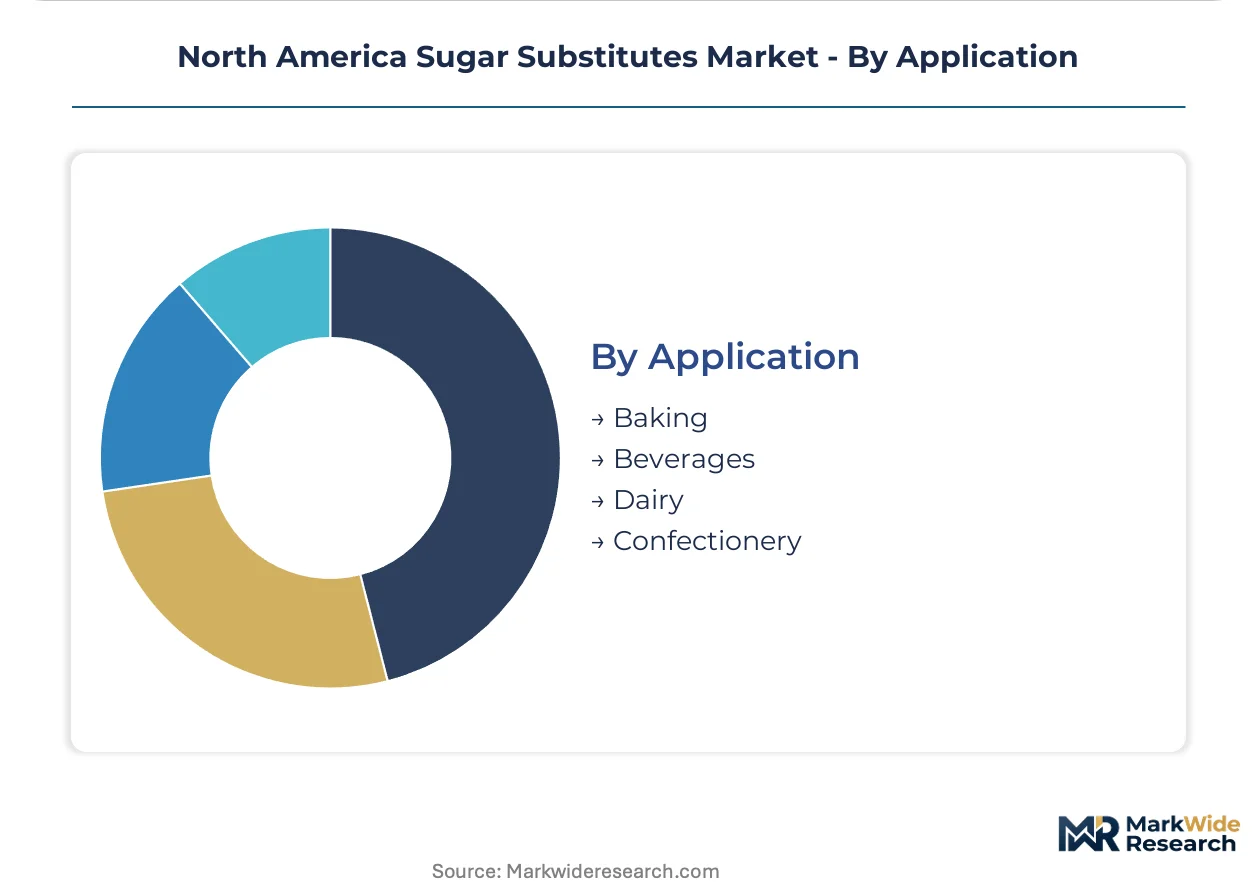
Application:
Functional requirements for sweetness, texture, and shelf stability create distinct specification tiers.
- Beverages:Carbonated soft drinks, sports drinks, and flavored waters demand water-soluble, pH-stable solutions. FDA nutrition panel updates force gram-level added sugar reduction across US bottling operations.
- Baking:Cookies, cakes, and pastries require crystallization control and moisture retention. US Upper Midwest bakery formulators adopt allulose for freezing-point depression in frozen dough applications.
- Dairy:Yogurt, ice cream, and flavored milk prioritize clean taste with minimal cooling effect. Canadian processors navigate Health Canada and FDA divergent daily value calculations for allulose labeling.
- Confectionery:Hard candies and chewing gum depend on hygroscopicity control and sustained sweetness release profiles.
Shipment tonnage concentrates in Beverages; technical complexity peaks in Baking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Foreign-Trade Zone program and Canadian tariff-exemption corridors concentrate sugar substitute formulation and packaging operations along border-adjacent manufacturing belts.
United States
Texas and Georgia bottling corridors drive high-intensity sweetener procurement for carbonated and sports drink production. FDA added-sugar disclosure rules compel gram-level reformulation across ready-to-drink portfolios. Wisconsin and Minnesota dairy processors specify powder-form stevia for yogurt and ice cream base incorporation.
Canada
Quebec and Ontario institutional foodservice channels generate demand for naturally sourced zero-calorie systems under provincial school nutrition guidelines. Health Canada's front-of-package nutrition symbol regulations mandate black-and-white "high in sugars" warnings on prepackaged goods. Toronto-area contract manufacturers shorten procurement cycles to 12-18 month pilot programs with performance clauses.
Mexico
Nuevo León beverage manufacturing clusters supply US Southwest and Central American export markets. Mexican cane harvest fluctuations transmit price volatility to high-fructose corn syrup markets, distorting substitute economics seasonally. Jalisco-based food processors navigate dual compliance requirements for FDA and Health Canada export certifications.
North America Sugar Substitutes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with ingredient houses commanding formulation-intensive categories and toll processors capturing volume-driven beverage corridors. The vendor base organizes around three strategic archetypes: agricultural-commodity processors with fermentation capabilities, specialty polyol manufacturers with texture-modifying expertise, and rare-sugar bioprocessing specialists. Consolidation pressure intensifies through backward integration into stevia leaf cultivation and enzymatic conversion capacity for allulose scale-up.
Within the agricultural-commodity processor tier, Cargill Incorporated and Archer Daniels Midland Company exemplify supply-chain-integrated positioning. Tate & Lyle PLC occupies a specialist position in rare-sugar bioprocessing. Ingredion Incorporated represents the polyol and texture-system archetype.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| International Flavors & Fragrances Inc. |
| DuPont de Nemours Inc. |
| Roquette Frères |
| Ajinomoto Co., Inc. |
| GLG Life Tech Corporation |
| Others |
Value Network & Pricing Analysis
Natural-extract premiums over synthetic alternatives bifurcate procurement strategies across North American sugar substitute markets, with stevia glycoside buyers absorbing agricultural volatility while aspartame purchasers lock in petrochemical-based contract stability. This tier divergence manifests in divergent supply chain configurations: premium natural-sweetener supply chains anchor in Paraguayan leaf cultivation and US fermentation capacity, while commodity synthetic routes feed from Chinese and Indian chemical manufacturing clusters.
Pricing Analysis
Lead-time premiums reward rapid fulfillment, with spot inventory of Reb M and Reb D stevia glycosides trading at discounts to contracted forward positions. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade monk fruit extracts from food-grade stevia blends and commodity synthetic aspartame. Pricing pressure stems from Mexican cane harvest volatility transmitting to high-fructose corn syrup markets, distorting substitute economics seasonally. Beverage manufacturers exhibit highest price sensitivity due to volume procurement and reformulation cycle compression, while pharmaceutical excipient buyers absorb premiums for pharmacopeial certification.
Supply Chain Analysis
Stevia leaf supply rests on Paraguayan cultivation networks and US-based bioprocessing capacity, with synthetic high-intensity sweetener production anchored in China and India. Raw material dependencies span stevia leaf biomass, corn-derived fructose feedstock for allulose enzymatic conversion, and petrochemical precursors for aspartame synthesis. Tariff exposure on Chinese-sourced acesulfame potassium concentrates creates single-source vulnerability for US bottling corridors. Distribution runs through ingredient houses with formulation technical service capabilities, bypassing traditional distributor networks for direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American sugar substitute markets constitute a vertical-integration race, with fermentation capacity and stevia leaf cultivation emerging as the decisive upstream levers for cost-position control.
For Market Incumbents: Cement supply security through captive stevia cultivation partnerships in Paraguay and fermentation facility expansion in Iowa and Minnesota dairy corridors. Defend formulation relationships against emerging rare-sugar bioprocessors by embedding technical service teams within Texas and Georgia beverage manufacturing clusters. FDA GRAS notification bottlenecks for novel sweeteners create defensive moats for existing approval holders. For New Entrants and Emerging Players: Enter via Canadian provincial school nutrition procurement channels, where Quebec and Ontario institutional foodservice guidelines generate demand for naturally sourced zero-calorie systems. White-space concentrates in liquid fountain concentrate formats for Texas and Georgia ready-to-drink corridors, where batch flexibility outweighs unit cost optimization. Direct sourcing relationships with Austin and Toronto beverage startups bypass established distributor minimum order thresholds. For Investors and Strategic Acquirers: Re-rating potential sits with rare-sugar bioprocessing specialists given Health Canada front-of-package labeling mandates and FDA added-sugar disclosure rules accelerating clean-label reformulation cycles. Long-term viability through the projection horizon favors assets with enzymatic conversion capabilities and GRAS-affirmed ingredient portfolios. Monitor GRAS notification approval velocity as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stevia Cultivation | Paraguayan leaf supply agreements reduce input cost volatility for Reb M and Reb D glycosides. |
| Fermentation Capacity Expansion | Clinton, Iowa allulose production targets cost parity with erythritol for bakery penetration. |
| Direct-to-Manufacturer Channel Development | Austin and Toronto beverage startups source below 500 kilogram minimum order quantities. |
| Regulatory Certification Investment | FDA GRAS self-affirmation pathways accelerate market entry for novel rare sugar entrants. |
| Cross-Border Formulation Standardization | US exporters to Canadian grocery channels navigate divergent Health Canada and FDA daily value calculations. |
Research Methodology
Trade databases, FDA GRAS notification filings, and Health Canada regulatory guidance documents formed the secondary backbone, supplemented by customs records and industry association reports. Primary fieldwork engaged formulation chemists at beverage and dairy processors, procurement leads at ingredient houses, regulatory affairs specialists, and contract manufacturing executives. Bottom-up and top-down triangulation validated volume estimates across product type, end user, and form segmentation dimensions.
Bottom-up modeling anchored projections in facility-level production capacity and batch-size economics, while top-down approaches cross-checked against dietary sweetener consumption trends and reformulation cycle frequencies. Segmentation dimensions spanned product type intensity tiers, application thermal stability requirements, and regional regulatory cluster variations. CAGRs were derived from demand elasticity estimates tied to sugar tax proposals and front-of-package labeling enforcement timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated state-level sugar tax adoption or GRAS pathway regulatory revisions. Projections reflect assumptions on stevia supply maturation and allulose scale-up cost curves. A small set of named triggers—Health Canada warning symbol enforcement velocity, FDA rare-sugar notification approval rates, and Mexican cane harvest yields—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
France Food Sweetener Market
Sweeteners
South America Sugar Substitutes Market
Sweeteners
Digestion Resistant Maltodextrin Market
Sweeteners
Nutritive Sweeteners Market
Sweeteners
South America Stevia Market
Sweeteners
Oligofructose Market
Sweeteners
Stevia Mints Market
Sweeteners
Japan Food Sweetener Market
Sweeteners
Global Low Intensity Sweeteners Market
Sweeteners
Crystalline Fructose Market
Sweeteners
Xylose Market
Sweeteners
Intensive Sweeteners Market
Sweeteners
Reduced Sugar Products Market
Sweeteners
Tapioca Maltodextrin Market
Sweeteners
Sugar Syrups Market
Sweeteners
Tagatose Market