
 Italy Food Sweetener Market | 2026-2036
Italy Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Food Sweetener Market Foresight
Asset-light toll manufacturing and third-party blending agreements is rewriting competitive entry barriers in Italian sweetener supply. Südzucker AG anchors European beet sugar sourcing through its established Po Valley processing footprint. Tate & Lyle PLC leverages specialty fiber-sweetener hybrid expertise to serve Italian dairy reformulators. Cargill, Incorporated controls bulk high-fructose corn syrup flows into Mediterranean beverage bottlers.
Food sweeteners encompass caloric and non-caloric substances—sucrose, fructose, steviol glycosides, aspartame—formulated to impart sweetness, control water activity, or modify texture in processed foods, typically measured by relative sweetness intensity against sucrose reference standards. Sucrose still dominates volume in Italian confectionery and bakery applications where crystallization behavior governs product structure. Stevia extracts capture accelerating share in beverage formulations as Italian brands pursue front-of-pack Nutri-Score improvements. Aspartame maintains position in tabletop and diet soft drink segments despite persistent clean-label headwinds from health-conscious Lombard and Emilia-Romagna consumers.
EFSA novel food evaluations and EU Food Information to Consumers Regulation shape which sweetener platforms gain shelf space in Italian retail. Italy's Ministry of Health enforces maximum usage levels for intense sweeteners through national implementation of EU food additive directives. FSSAI-aligned import checks at Trieste and Genoa ports filter non-compliant stevia extracts from Asian suppliers. Stakeholders must track pending EFSA re-evaluations of aspartame and cyclamates to anticipate reformulation mandates before updated EU positive lists publish.
Market Dynamics
EU sugar reduction mandates and Nutri-Score labeling requirements are compressing formulation cycles across Italian food manufacturing, forcing rapid sweetener platform switches before 2025 compliance deadlines hit.
Growth Catalysts
- EFSA novel food pathways:Accelerated approvals for steviol glycoside variants enable faster clean-label launches by Milan-based beverage formulators seeking front-of-pack scoring advantages.
- Dairy reformulation clusters:Lombardy processing hubs drive specialty fiber-sweetener hybrid demand as yogurt and fresh cheese producers target reduced-sugar claims.
- Po Valley beet infrastructure:Established sugar extraction capacity supports regional supply security for confectionery manufacturers requiring crystallization-specific sucrose grades.
Market Restraints
- Beet sugar input volatility:Weather-driven yield fluctuations in Emilia-Romagna growing regions create margin pressure for processors locked into annual supply contracts.
- High-fructose corn syrup concentration:Mediterranean beverage bottlers face single-source dependency risks from bulk HFCS import channels controlled through Trieste port logistics.
- Aspartame re-evaluation friction:Pending EFSA safety reviews generate reformulation uncertainty for tabletop and diet soft drink segments awaiting updated EU positive list publications.
Strategic Opportunities
- Southern Italy underpenetration:Campania and Sicily packaged food corridors lack dedicated clean-label sweetener blending facilities, creating first-mover gaps for toll manufacturing investments.
- Pharmaceutical excipient crossover:Convergence of food-grade stevia extraction with drug tablet sweetening applications opens dual-use certification pathways for Veneto chemical processors.
- FSSAI-aligned import screening:Enhanced Trieste and Genoa port compliance infrastructure reduces Asian supplier rejection rates, lowering entry barriers for compliant stevia extractors.
Industry Challenges
- Reformulation talent scarcity:Lombardy labs compete for flavor chemists capable of balancing stevia's bitter aftertaste in reduced-sugar bakery applications without texture degradation.
- Clean-label certification timelines:EU organic sweetener accreditation requires 18-24 month validation cycles that misalign with quarterly product launch schedules of major retail brands.
- Legacy equipment retrofit costs:Northern Italian confectionery plants face capital-intensive extrusion and drying system upgrades to handle alternative sweetener hygroscopicity profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Food Sweetener Market |
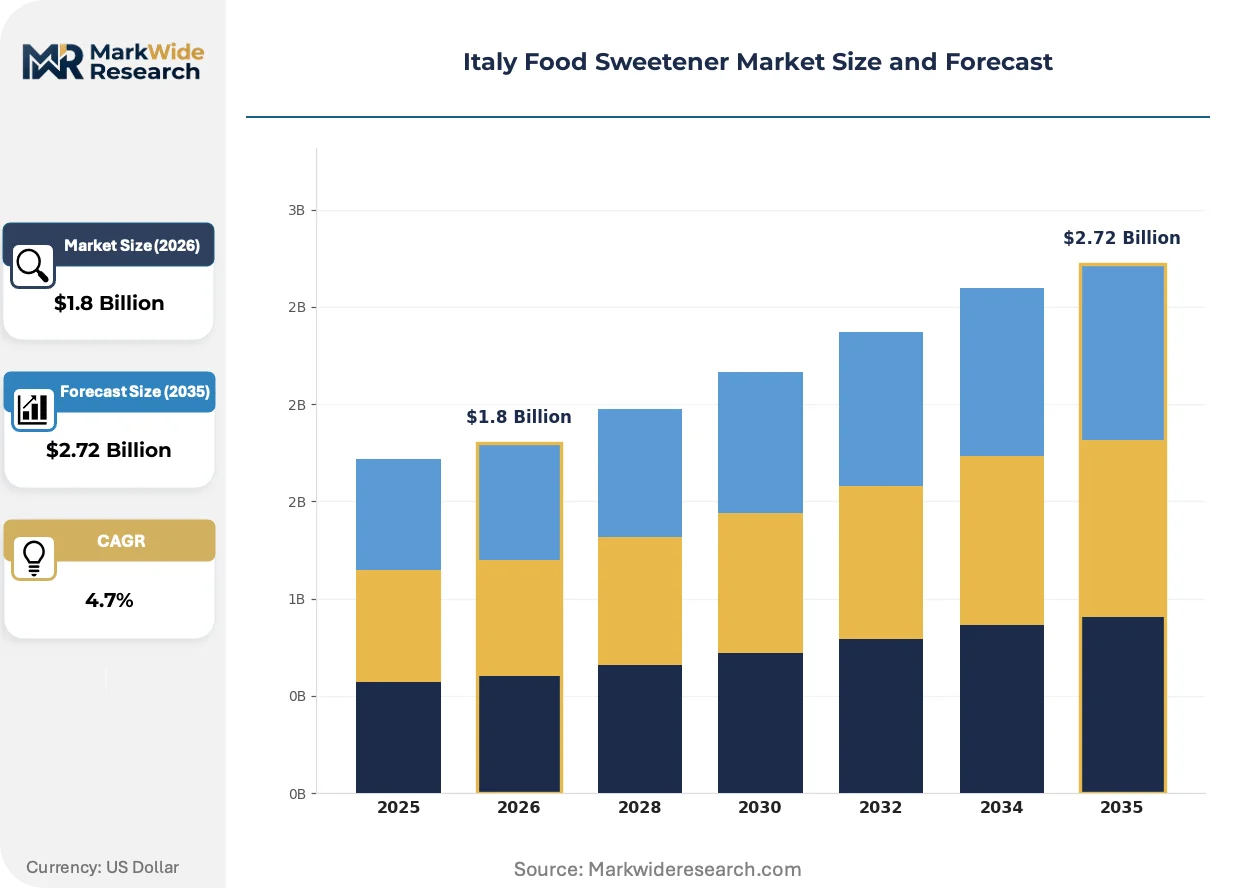
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sucrose, Fructose, Stevia, Aspartame Application: Beverages, Bakery, Dairy Products, Confectionery End User: Food Manufacturers, Restaurants, Retailers, Households Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Ingredion Incorporated, Südzucker AG, Tate & Lyle PLC, Ajinomoto Co., Inc., Tereos S.A, Cargill, Incorporated, Roquette Frères, PureCircle Ltd., Archer Daniels Midland Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Food Sweetener Market Shifts & Advancements
Digital formulation platforms and biosynthetic production methods are compressing development timelines for next-generation sweeteners, while regulatory pressure on established intense sweeteners accelerates platform turnover across Italian food manufacturing.
Enzymatic glycosylation technology is virtualizing stevia extract refinement by enabling precise control over rebaudioside ratios without traditional solvent extraction. Milan-based reformulation labs adopt these biocatalytic systems within 12-month equipment depreciation cycles. The technology is virtualizing competitive barriers between specialty chemical suppliers and traditional botanical extractors by collapsing purity grade differentiation.
Italy's Ministry of Health enforces maximum usage levels for intense sweeteners through national implementation of EU food additive directives. This creates preemptive formulation hedging as manufacturers await EFSA re-evaluation outcomes for aspartame and cyclamates. Beverage and tabletop segments in Lombardy and Emilia-Romagna accelerate stevia and sucralose pipeline diversification to reduce regulatory concentration risk.
Direct procurement from certified extraction facilities is replacing layered distributor networks for major packaged food brands. Large Milan corridor manufacturers now source stevia glycosides through audited single-origin contracts rather than commodity spot markets. This pattern concentrates most visibly in Northern Italy's dairy and beverage verticals where traceability requirements intersect with volume scale.
Italy Food Sweetener Market Segmentation
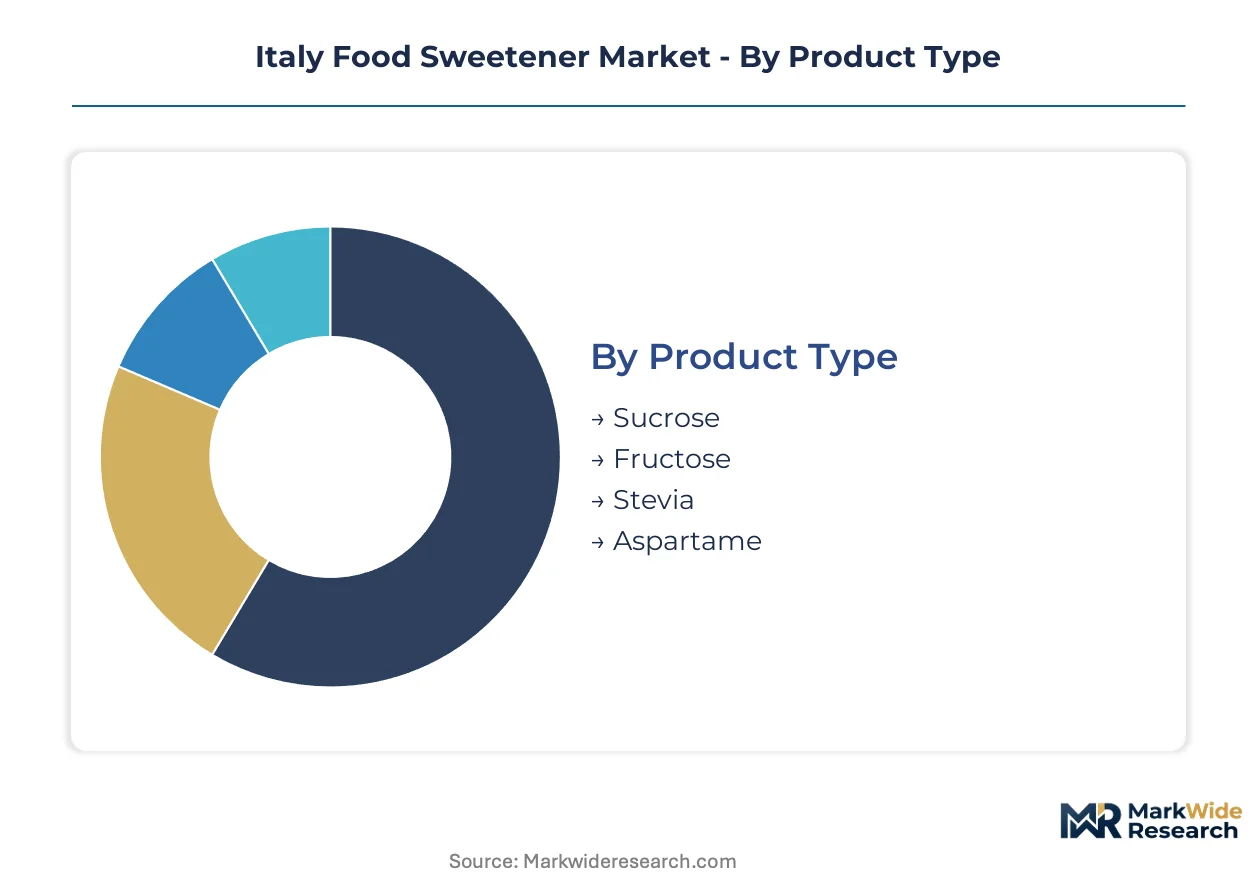
Sweetener selection in Italy hinges on reformulation mandates from EFSA and the Ministry of Health, with each segment responding differently to clean-label pressures and Nutri-Score compliance requirements. Manufacturers balance crystallization performance against front-of-pack scoring advantages when allocating procurement budgets across product categories.
Product Type:
Mature sucrose formulations coexist with emerging enzymatically refined stevia glycosides as Italian processors navigate the transition from volume-based to value-based sweetener procurement.
- Sucrose:Beet-derived crystalline sugar maintains dominance in Italian confectionery and bakery applications where precise control over caramelization and texture formation remains non-negotiable. Northern Italian chocolate manufacturers in Turin and Perugia corridors source specific polarization grades from Po Valley processors to preserve traditional product mouthfeel.
- Stevia:Enzymatically glycosylated rebaudioside extracts command accelerating share in Lombardy beverage reformulation labs seeking clean-label credentials without sacrificing sweetness intensity. Milan-based dairy producers deploy these extracts in reduced-sugar yogurt lines to improve Nutri-Score ratings ahead of retail distribution.
- Fructose:High-purity fruit sugar serves Italian energy drink and sports beverage bottlers requiring rapid dissolution and lower glycemic positioning.
- Aspartame:The methyl ester dipeptide persists in tabletop sweetener sachets and diet carbonated drinks despite pending EFSA re-evaluation uncertainty.
Sucrose retains volume leadership; stevia holds the steepest expansion curve.
Application:
End-use differentiation in Italy tracks the technical complexity of sugar replacement—beverages permit simpler swaps while baked goods demand multi-functional reformulation.
- Beverages:Liquid applications tolerate higher stevia concentrations with minimal texture modification, enabling rapid clean-label transitions by Milan and Bologna bottling facilities. Mineral water and flavored drink producers leverage this flexibility to front-run Nutri-Score labeling requirements.
- Bakery:Maillard reaction dependence and moisture retention needs complicate sweetener substitution in Italian artisanal bread and pastry segments. Emilia-Romagna croissant and biscotti manufacturers invest in specialty fiber-sweetener hybrids to preserve shelf stability while reducing added sugar declarations.
- Dairy Products:Fresh cheese and yogurt applications in Lombardy prioritize bulking agent compatibility alongside sweetness delivery.
- Confectionery:Turin and Perugia chocolate hubs maintain sucrose dependency for crystallization control in praline and gianduja formulations.
Beverage applications show the broadest platform switching; bakery reformulation faces the steepest technical barriers.
End User:
Procurement scale separates Italian sweetener buyers—industrial volumes drive contract negotiation leverage while fragmented retail channels tolerate spot-market pricing.
- Food Manufacturers:Large Milan corridor packaged food producers negotiate direct-origin stevia contracts with audited extraction facilities, bypassing layered distributor markups. These buyers specify rebaudioside purity grades and residual solvent thresholds that exceed baseline EU requirements.
- Households:Individual consumers purchase tabletop sweeteners through supermarket and online channels with limited technical specification visibility. Italian households in Lombardy and Emilia-Romagna demonstrate stronger clean-label preference than southern regions.
- Restaurants:Food service operators in Rome and Florence procurement networks balance cost control against menu transparency demands.
- Retailers:Private-label development teams at major Italian grocery chains increasingly specify stevia blends for own-brand reduced-sugar lines.
Food manufacturers command the deepest supply chain integration; household purchasing shows the most rapid clean-label transition.
Distribution Channel:
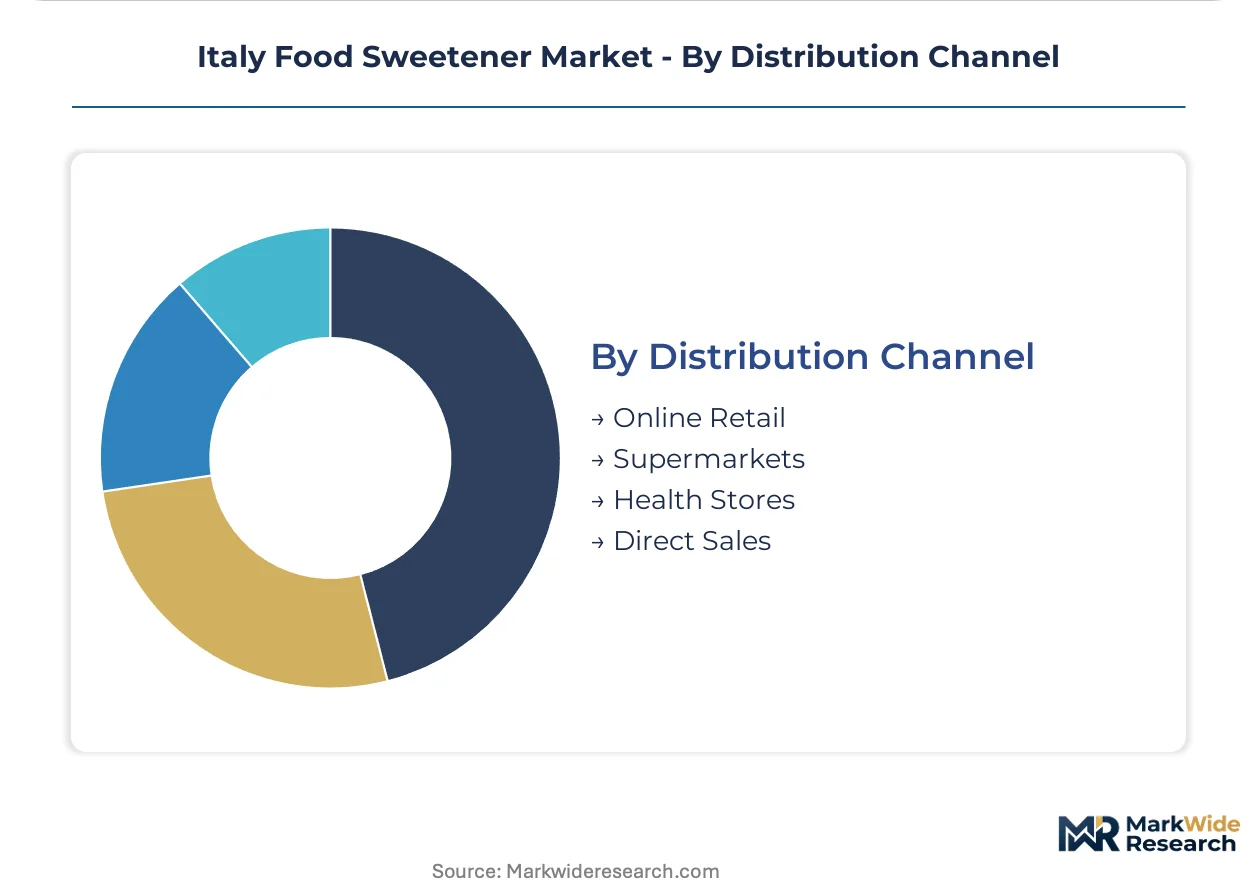
Channel selection in Italy reflects traceability requirements and volume scale—direct sales dominate industrial procurement while health stores capture premium-positioned specialty extracts.
- Direct Sales:Bulk high-fructose corn syrup and crystalline sucrose move through controlled logistics from Trieste port to Mediterranean beverage bottlers and Po Valley confectionery plants. Cargill-controlled import channels concentrate HFCS supply for this segment.
- Health Stores:Premium-positioned organic stevia extracts and monk fruit formulations reach clean-label consumers through specialized retail in Milan, Rome, and Bologna. These channels validate EU organic accreditation and single-origin extraction claims.
- Supermarkets:Mass-market tabletop sweeteners and standard-grade sucrose dominate shelf space across Esselunga, Coop, and Conad networks.
- Online Retail:Direct-to-consumer stevia and specialty sweetener sales accelerate through Amazon Italia and dedicated health platforms.
Direct sales retain volume concentration; health stores capture the fastest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's food sweetener trade flows reveal a structural deficit in high-intensity extracts and a surplus in beet-derived crystalline grades. The Po Valley processing belt exports sucrose to confectionery hubs across the Alps while Mediterranean ports import bulk fructose and stevia glycosides for beverage reformulation.
Lombardy
Milan corridor beverage formulators drive demand for enzymatically refined stevia extracts as Nutri-Score compliance deadlines approach. EFSA novel food pathways enable faster clean-label approvals for regional dairy and soft drink producers. The Lombardy processing cluster concentrates specialty fiber-sweetener hybrid development for reduced-sugar yogurt lines.
Emilia-Romagna
Artisanal bakery and pasta manufacturers in Bologna and Modena corridors grapple with Maillard reaction preservation during sugar reduction campaigns. Italy's Ministry of Health enforces maximum usage levels for intense sweeteners through national implementation of EU directives. Regional croissant and biscotti producers invest in bulking agent compatibility testing for reformulated dough systems.
Piedmont
Turin chocolate manufacturers maintain sucrose dependency for crystallization control in praline and gianduja formulations. EU Food Information to Consumers Regulation shapes front-of-pack labeling strategies for premium confectionery exports. The Turin-Perugia chocolate axis sources specific polarization grades from Po Valley beet processors to preserve traditional mouthfeel profiles.
Veneto
Chemical processors in the Veneto region explore pharmaceutical excipient crossover opportunities from food-grade stevia extraction capabilities. FSSAI-aligned import screening at Trieste port reduces rejection rates for Asian stevia suppliers. Veneto extraction facilities pursue dual-use certification pathways spanning drug tablet sweetening and beverage applications.
Campania and Sicily
Southern packaged food corridors lack dedicated clean-label sweetener blending infrastructure compared to Northern counterparts. EFSA re-evaluation timelines for aspartame generate preemptive formulation hedging among Neapolitan and Palermo manufacturers. Toll manufacturing investments in these regions face first-mover gaps as procurement networks remain tethered to Milan-based distributors.
Italy Food Sweetener Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The Italy food sweetener market structures around three distinct competitive layers: bulk commodity processors controlling port logistics and beet extraction, specialty extractors delivering enzymatically refined glycosides, and toll manufacturers offering asset-light blending services. Strategic archetypes include integrated agribusiness conglomerates, botanical extraction specialists, and regional blending cooperatives. Dominant competitive moves center on backward integration into certified stevia origin contracts and geographic expansion into underpenetrated Southern processing corridors.
Among the named participants, Südzucker AG anchors European beet sugar sourcing through its established Po Valley footprint. Tate & Lyle PLC occupies a position within the specialty fiber-sweetener hybrid tier serving Italian dairy reformulators. Cargill, Incorporated represents the bulk commodity archetype controlling high-fructose corn syrup flows into Mediterranean beverage bottlers through Trieste port logistics.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Südzucker AG |
| Tate & Lyle PLC |
| Ajinomoto Co., Inc. |
| Tereos S.A |
| Cargill, Incorporated |
| Roquette Frères |
| PureCircle Ltd. |
| Archer Daniels Midland Company |
| Others |
Supply & Pricing Matrix
Po Valley beet sugar concentration anchors Italian sucrose pricing, directing margin pools toward Milan corridor dairy reformulators and Turin chocolate manufacturers who lock in annual polarization-grade contracts. This upstream consolidation forces beverage bottlers and bakery processors into spot-market exposure for high-fructose corn syrup and enzymatically refined stevia extracts.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Lombardy and Emilia-Romagna processing hubs. Price differentiation separates organic-certified stevia extracts from commodity-grade aspartame and standard beet sucrose, with certification tier and volume scale as primary drivers. Cost compression in HFCS procurement is intensifying because Mediterranean bottlers face single-source dependency through Trieste port channels. Small artisanal bakeries demonstrate highest price sensitivity, while multinational dairy conglomerates absorb premium fiber-sweetener hybrid costs for Nutri-Score positioning.
Supply Chain Analysis
Tariff exposure between EU member states and third-country stevia suppliers dominates risk calculus for Italian extract importers. Geographic supply concentration centers on China, India, and Vietnam for steviol glycoside raw material; Germany and France for specialty fiber additives; and domestic Po Valley processing for beet-derived sucrose. Raw material dependencies include stevia leaf biomass, corn starch for fructose enzymatic conversion, and sugar beet pulp. Single-source vulnerability persists in HFCS flows through Trieste port logistics controlled by bulk commodity traders. Distribution runs through direct sales contracts for industrial volumes, layered through Milan-based distributors for smaller processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as enzymatically glycosylated stevia extracts displace aspartame in Lombardy beverage formulations ahead of EFSA re-evaluation outcomes.
For Market Incumbents: Insulate formulation pipelines through backward integration into audited stevia origin contracts with Asian extraction facilities. Lock in multi-year polarization-grade sucrose offtake from Po Valley processors to defend chocolate and confectionery margin positions against beet yield volatility. Prioritize certification investment in EU organic sweetener accreditation to extend clean-label pricing premiums. For New Entrants and Emerging Players: Southern Italy's Campania and Sicily corridors offer first-mover gaps for toll manufacturing investments, with packaged food procurement networks currently tethered to Milan-based distributors. Target dairy reformulation clusters in Veneto for pharmaceutical excipient crossover opportunities, leveraging existing chemical processing infrastructure. Deploy asset-light blending agreements rather than capital-intensive extraction capacity to compress entry timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty fiber-sweetener hybrid developers serving Lombardy yogurt reformulators. Long-term viability hinges on platform diversification beyond single-sweetener dependency as EFSA regulatory timelines accelerate category turnover. Watch EFSA novel food approval velocities for steviol glycoside variants as inflection indicators for clean-label adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Stevia Origins | Secures traceability for Milan corridor dairy brands facing Nutri-Score compliance deadlines. |
| Toll Manufacturing Expansion in Southern Italy | Captures underpenetrated Campania and Sicily packaged food procurement networks. |
| Pharmaceutical Excipient Dual-Use Certification | Opens Veneto chemical processors to drug tablet sweetening applications beyond food. |
| Enzymatic Glycosylation Technology Deployment | Enables precise rebaudioside control without solvent extraction for beverage formulators. |
| Direct-Origin Contract Consolidation | Replaces layered distributor networks for large-scale stevia procurement in Northern Italy. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with formulation chemists at Lombardy reformulation labs, procurement directors at Milan corridor dairy processors, regulatory affairs specialists navigating EFSA novel food pathways, and Trieste port logistics coordinators managing stevia extract imports. Secondary validation drew from EU Food Information to Consumers Regulation filings, EFSA novel food approval databases, Italian Ministry of Health additive directives, and customs records tracking HFCS flows through Mediterranean ports. Bottom-up volume triangulation across end-use segments was cross-checked against top-down value estimates from processor revenue disclosures.
Calibration against historical EFSA approval timelines and EU sugar reduction mandate implementation phases shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type hierarchy, application complexity tier, end-user procurement scale, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for policy-driven step changes in formulation cycles. Industry-specific inputs encompassed beet sugar yield variability in Emilia-Romagna growing regions and enzymatic glycosylation technology adoption curves among Milan-based specialty extractors.
Practitioners should monitor EFSA re-evaluation outcomes for aspartame and cyclamates, EU organic sweetener accreditation backlogs, and Trieste port compliance infrastructure investments for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Middle East and Africa Low Calorie Sweeteners Market
Sweeteners
Steviol Glycoside Market
Sweeteners
Sugar Market
Sweeteners
United Kingdom Food Sweetener Market
Sweeteners
Sucrose Acetate Isobutyrate Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Global Plant-Derived and Synthetic Sugar Market
Sweeteners
Natural Malt Sweeteners Market
Sweeteners
Sugar-Free Syrups Market
Sweeteners
Maltodextrin Market
Sweeteners
Intensive Sweeteners Market
Sweeteners
Europe Starch Sweetener Market
Sweeteners
Vanilla Sugar Market
Sweeteners
Europe Sugar Substitute Market
Sweeteners
Fructose Market
Sweeteners
Sweet Modulator Market