
 Asia Pacific Food Sweetener Market | 2026-2036
Asia Pacific Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Food Sweetener Market Outlook
Modern trade channels across Southeast Asia are tilting toward direct sourcing arrangements with sweetener suppliers. Cargill Incorporated leverages its integrated supply chain from Thai sugarcane belts to secure cost positions in bulk high fructose corn syrup. Ajinomoto Co. Inc anchors the aspartame segment through dedicated fermentation facilities in Japan. Tate & Lyle PLC competes on specialty sweetener formulations designed for beverage processors seeking clean-label positioning.
Food sweeteners encompass caloric and non-caloric substances that impart sweetness to food matrices, typically measured by sucrose equivalence or relative sweetness intensity on a gram-for-gram basis, with stevia glycosides achieving 200-400 times the sweetness of sucrose at markedly lower caloric contribution. These ingredients function as flavor modulators, preservation aids, and bulking agents across industrial food production. The product type landscape shows sugar retaining volume dominance while stevia claims the fastest expansion trajectory driven by beverage reformulation mandates. End user segmentation reveals beverages as the primary margin pool, though bakery applications sustain steadier volume offtake due to less volatile formulation switching costs.
FSSAI labeling requirements in India, China's GB standards for food additives under SAMR oversight, and Japan's Food Sanitation Act enforced by MHLW collectively constrain artificial sweetener thresholds while accelerating natural alternative approvals. Compliance with these frameworks determines market access velocity for new entrants and shapes R&D allocation between synthetic and plant-derived portfolios. Stakeholders must monitor regulatory divergence between ASEAN harmonization efforts and national standards to anticipate reformulation timelines and certification investments.
Market Dynamics
Beverage reformulation across Southeast Asia is compressing formulation cycles as FSSAI labeling mandates in India and China's GB standards force rapid sweetener substitution decisions. Supply chain reconfiguration toward direct sourcing is redrawing procurement relationships between manufacturers and fermentation-based ingredient suppliers.
Growth Catalysts
- FSSAI Added Sugar Labeling:India's tightened disclosure requirements for packaged beverages are forcing reformulation toward stevia and aspartame alternatives. Beverage processors in Mumbai and Delhi NCR are accelerating clean-label transitions to preempt consumer backlash.
- Urban China Sweetener Migration:Tier-1 city consumers are displacing traditional cane sugar in packaged goods with high-intensity alternatives. Bakery and dairy applications in Shanghai and Guangzhou are absorbing the bulk of stevia glycoside volume.
- ASEAN Modern Trade Consolidation:Direct sourcing arrangements between retailers and Thai sugarcane belt suppliers are stripping distributor margins. Bulk high fructose corn syrup procurement is concentrating through centralized purchasing desks in Bangkok and Jakarta.
Market Restraints
- Thai Sugarcane Input Volatility:Weather-driven yield fluctuations in the central plains region are compressing margin predictability for bulk sweetener processors. Drought cycles in Nakhon Sawan province directly transmit to HFCS pricing instability.
- Artificial Sweetener Threshold Caps:Japan's Food Sanitation Act enforced by MHLW imposes strict aspartame and acesulfame-K ceilings in soft drinks. Formulators face hard technical ceilings that limit cost-optimized blending ratios.
- Natural Sweetener Taste Limitations:Stevia glycosides carry bitter aftertaste profiles that resist masking in low-pH beverage matrices. Citrus-flavored applications in Vietnam and Philippines show persistent consumer rejection rates.
Strategic Opportunities
- Indonesia Underpenetrated Regions:Eastern Java and Sulawesi packaged food markets remain dominated by cane sugar with minimal high-intensity penetration. Local dairy processors in Surabaya represent untapped conversion potential.
- Fermentation-Derived Rare Sugars:Allulose production via enzymatic conversion of fructose is gaining regulatory traction under China's SAMR novel food approval pathway. Bakery applications seeking bulk replacement with caloric reduction are piloting formulations.
- E-Commerce Ingredient Platforms:B2B procurement digitization through specialized chemical marketplaces is disintermediating traditional distributor networks. Mid-scale beverage manufacturers in Malaysia are adopting direct bulk sweetener purchasing.
Industry Challenges
- Fermentation Scale-Up Expertise Scarcity:Microbial strain optimization for steviol glycoside production requires specialized bioprocess engineers. Japanese and South Korean facilities face recruitment competition from pharmaceutical sectors.
- Dual Certification Burden:Sweetener suppliers seeking pan-Asia distribution must simultaneously navigate FSSAI approvals, China's SAMR GB compliance, and Japan's MHLW positive list maintenance. Parallel track submissions extend time-to-revenue by 18-24 months.
- Legacy Equipment Retrofit Costs:Cane sugar handling infrastructure in Indian and Indonesian processing plants requires capital-intensive modification for hygroscopic high-intensity sweetener powder systems. Dosing precision equipment represents significant unbudgeted capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Food Sweetener Market |
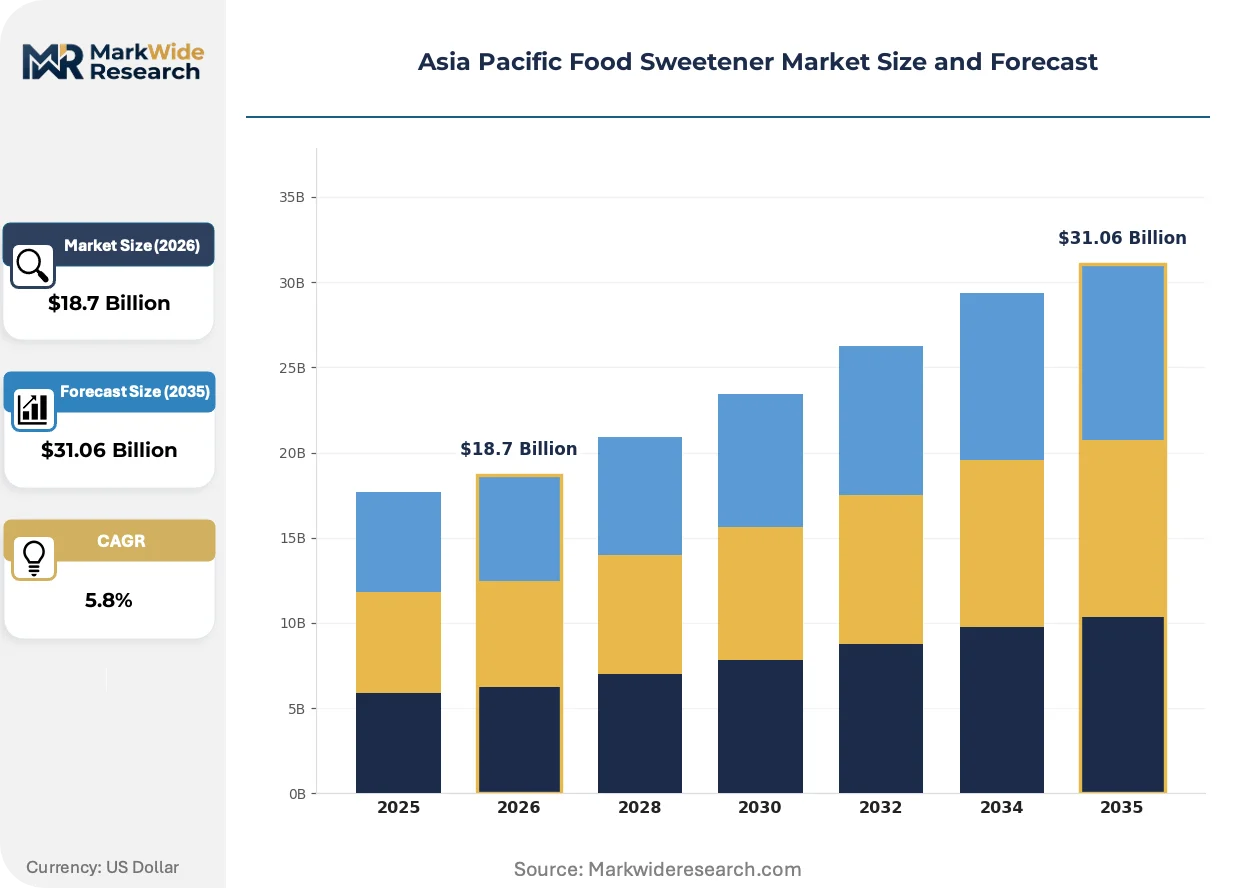
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sugar, High Fructose Corn Syrup, Aspartame, Stevia End User: Food Processing, Beverages, Bakery, Confectionery Form: Liquid, Granular, Powder, Syrup Application: Desserts, Sauces, Snacks, Dairy Products |
| Companies Covered | Cargill Incorporated, Tate & Lyle PLC, Ingredion Incorporated, Archer Daniels Midland Company, DuPont, Ajinomoto Co. Inc, Roquette Frères, Mitsui Sugar Co. Ltd, Foodchem International Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Food Sweetener Market Strategic Shifts
Digital traceability and bioprocess automation are compressing quality assurance cycles while regulatory divergence between national standards forces parallel compliance investments. Sweetener suppliers are embedding sensors and blockchain verification to preempt contamination disputes.
Precision fermentation for steviol glycoside production is digitizing quality control through real-time metabolite monitoring and AI-driven strain optimization. Japanese biotech facilities are deploying in-line spectroscopy to reduce batch-to-batch sweetness variance. This automation is compressing the competitive window for traditional extraction-based suppliers who lack capital for equivalent retrofit.
China's SAMR is tightening GB 2760 food additive standards for synthetic sweeteners while accelerating novel natural substance approvals under streamlined safety review pathways. Aspartame and acesulfame-K face downward pressure in beverage formulations as regulators signal preference for plant-derived alternatives. Domestic Chinese suppliers are redirecting R&D budgets toward fermentation-derived portfolios to align with anticipated standard revisions.
Ingredient specification decisions are migrating from procurement departments to dedicated clean-label innovation teams with veto authority over formulation choices. Southeast Asian beverage manufacturers are establishing cross-functional sweetness councils that override cost-driven purchasing. This organizational shift is most visible in Thailand and Vietnam where export-oriented processors prioritize certification maintenance over unit cost minimization.
Asia Pacific Food Sweetener Market Segmentation
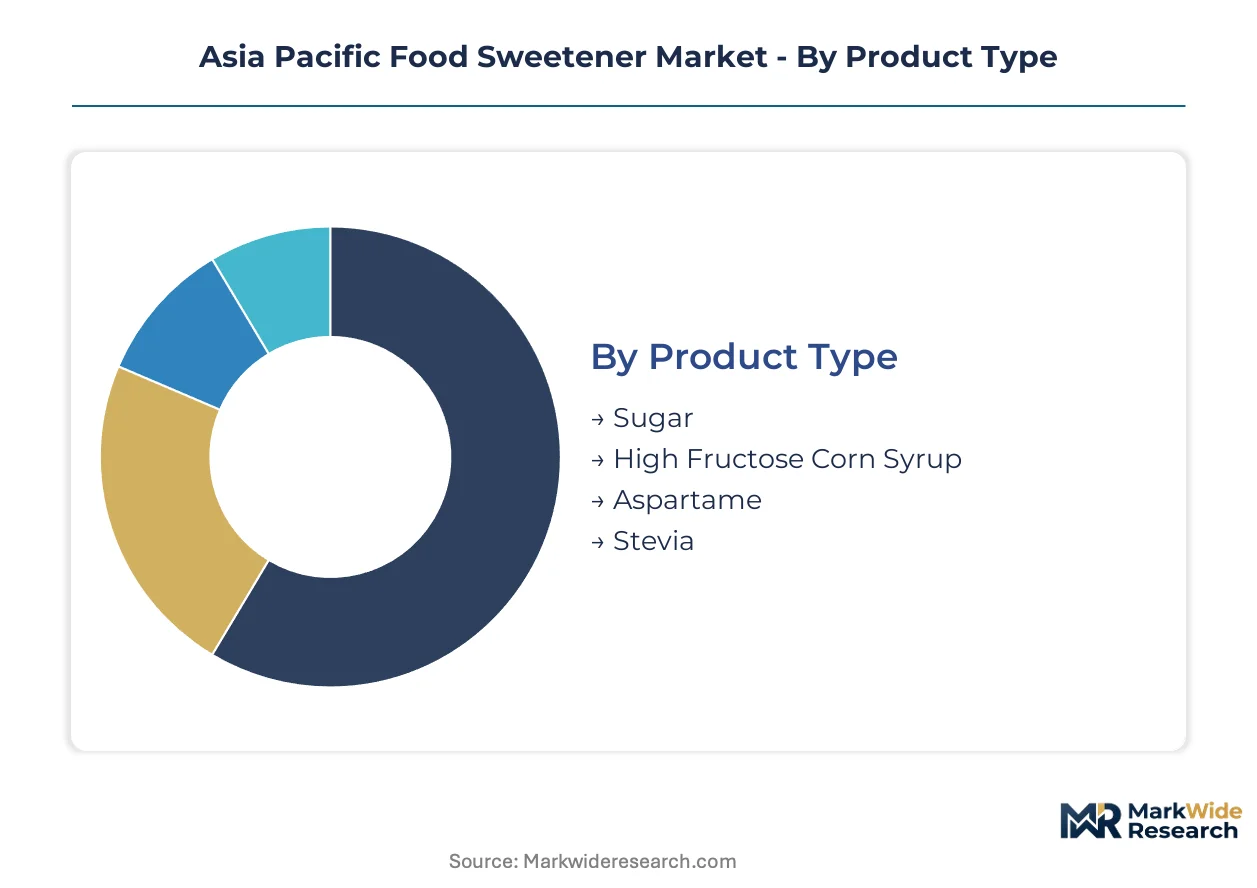
Sweetener selection across Asia Pacific hinges on formulation constraints, regulatory thresholds, and procurement scale. Manufacturers segment portfolios by caloric positioning, physical state, and end-use technical requirements to optimize cost-performance ratios.
Product Type:
Cost tier differentiation separates commodity bulk sweeteners from high-intensity specialty alternatives with steep sweetness multipliers.
- Sugar:Sucrose derived from Thai and Indian sugarcane retains volume dominance in traditional food processing. Indian FSSAI labeling mandates are compressing its share in packaged beverages as reformulation accelerates toward alternatives.
- Stevia:Steviol glycosides achieve 200-400 times sucrose sweetness intensity with negligible caloric contribution. Chinese beverage manufacturers in Shanghai and Guangzhou are absorbing the bulk of glycoside volume for clean-label positioning.
- High Fructose Corn Syrup:Maize-derived liquid sweetener dominates Southeast Asian soft drink manufacturing through Thai belt sourcing.
- Aspartame:Fermentation-derived dipeptide methyl ester faces downward pressure from Japan's MHLW threshold caps in carbonated beverages.
Sugar commands the established base. The steepest expansion runs through stevia glycoside formulations.
End User:
Application-specific formulation requirements create divergent procurement patterns across food manufacturing verticals.
- Beverages:Low-pH matrices and thermal processing demands drive high-intensity sweetener adoption. FSSAI added sugar disclosure rules in India are forcing Mumbai and Delhi NCR processors toward stevia-aspartame blends.
- Bakery:Maillard reaction requirements and bulk volume needs sustain steadier cane sugar offtake with slower formulation switching. Shanghai bakeries are piloting allulose for caloric reduction without structural compromise.
- Food Processing:Industrial-scale manufacturers balance cost minimization against clean-label certification maintenance for export markets.
- Confectionery:Crystallization control and shelf stability requirements favor specific sucrose particle grades over high-intensity alternatives.
Beverages concentrate margin capture. Bakery sustains the most predictable volume commitment.
Form:
Physical state determines handling infrastructure, dosing precision, and dissolution kinetics in target applications.
- Liquid:Pumpable concentrates dominate high-volume beverage manufacturing with integrated dosing systems. Bangkok-based HFCS procurement desks favor liquid delivery for operational efficiency.
- Powder:Hygroscopic high-intensity sweeteners require climate-controlled handling and precision dosing equipment. Indian processors face capital-intensive retrofit costs for legacy cane sugar infrastructure.
- Granular:Free-flowing crystals suit tabletop and small-batch food service applications across Southeast Asian food courts.
- Syrup:Viscous intermediates bridge liquid and solid states for specific confectionery and sauce manufacturing requirements.
Liquid forms anchor industrial procurement. Powdered high-intensity variants are gaining share fastest in reformulation cycles.
Application:
Functional requirements across finished food categories dictate sweetener selection by thermal stability, pH tolerance, and flavor masking needs.
- Dairy Products:Protein interaction and fermentation compatibility constrain sweetener choice in yogurt and flavored milk. Surabaya dairy processors in Eastern Java represent untapped conversion potential from cane sugar.
- Snacks:Coating adhesion and moisture management requirements favor specific syrup viscosities in extruded and puffed products.
- Desserts:Freeze-thaw stability and texture preservation drive formulation decisions in ice cream and frozen novelties.
- Sauces:Viscosity modification and extended shelf stability requirements favor particular reducing sugar profiles.
Dairy applications concentrate reformulation investment. Dessert formulations are expanding most quickly for clean-label positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI labeling mandates in India and China's GB standards under SAMR are accelerating sweetener substitution across manufacturing clusters. Procurement desks in Bangkok and Jakarta are consolidating direct sourcing arrangements with Thai sugarcane belt suppliers.
China
Urban consumers in Shanghai and Guangzhou are displacing cane sugar with stevia glycosides in packaged goods. SAMR's tightening GB 2760 standards for synthetic sweeteners are redirecting R&D budgets toward fermentation-derived alternatives. The Yangtze River Delta concentration of beverage manufacturers is absorbing the bulk of high-intensity sweetener volume for clean-label positioning.
India
Mumbai and Delhi NCR beverage processors are accelerating reformulation toward stevia-aspartame blends to preempt consumer backlash. FSSAI added sugar disclosure requirements for packaged beverages are compressing formulation cycles. Western Maharashtra's dairy and confectionery clusters face capital-intensive retrofit costs for legacy cane sugar infrastructure.
Japan
MHLW enforcement of the Food Sanitation Act imposes strict aspartame and acesulfame-K ceilings in carbonated soft drinks. Kansai region fermentation facilities are deploying precision bioprocess automation for steviol glycoside production. Osaka-based ingredient suppliers face recruitment competition from pharmaceutical sectors for specialized bioprocess engineers.
Thailand
Weather-driven yield fluctuations in Nakhon Sawan province are transmitting volatility to bulk HFCS pricing. Central plains sugarcane belts anchor Cargill's integrated supply chain for high fructose corn syrup procurement. Bangkok-based modern trade retailers are stripping distributor margins through direct sourcing arrangements with belt suppliers.
Indonesia
Eastern Java and Sulawesi packaged food markets remain dominated by cane sugar with minimal high-intensity penetration. Surabaya dairy processors represent untapped conversion potential as clean-label certification becomes export-critical. The country's national food regulator maintains parallel track with ASEAN harmonization efforts while enforcing national standards.
Asia Pacific Food Sweetener Market Competitive Environment
On the supply side, the industry is consolidating around integrated agribusiness conglomerates with captive raw material access and specialized fermentation technology providers. Three archetypes dominate: plantation-integrated commodity processors controlling Thai-to-manufacturer supply chains, Japanese and South Korean precision fermentation specialists, and European formulation houses competing on clean-label certification maintenance. Capacity expansion in enzymatic conversion facilities and backward integration into sugarcane crushing operations represent the dominant competitive moves.
Within the plantation-integrated tier, Cargill Incorporated exemplifies upstream control over Thai belt sourcing. Among fermentation specialists, Ajinomoto Co. Inc occupies a position representing Japanese bioprocess expertise. Tate & Lyle PLC sits within the European formulation archetype, anchoring specialty sweetener positioning for beverage processors seeking certification maintenance. These three represent divergent strategic paths: geographic raw material capture, biotech capability accumulation, and regulatory compliance service bundling.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| DuPont |
| Ajinomoto Co. Inc |
| Roquette Frères |
| Mitsui Sugar Co. Ltd |
| Foodchem International Corporation |
| Others |
Value Chain & Pricing Dynamics
Thai sugarcane yield volatility in Nakhon Sawan province determines both pricing tier spreads and supply chain shape across Asia Pacific food sweetener markets. Weather-driven input compression forces bulk high fructose corn syrup processors into spot-market exposure while fermentation-derived specialty sweeteners command premium stability through captive bioprocess capacity.
Pricing Analysis
Certification level (FSSAI/SAMR/MHLW-grade) creates the primary spread between commodity bulk sweeteners and premium fermentation-derived alternatives. Three-tier pricing structure across premium certified, standard industrial, and economy bulk levels stratifies procurement desks in Bangkok and Jakarta. Pricing pressure stems from cane sugar substitution mandates as India's labeling disclosure rules compress legacy sweetener margins. Mid-scale beverage manufacturers exhibit highest price sensitivity, while export-oriented processors prioritize certification maintenance over unit cost minimization.
Supply Chain Analysis
Extended payment terms from Thai sugarcane belt suppliers to Bangkok-based modern trade retailers are stripping traditional distributor margins through supply-chain finance facilities. Raw material sourcing concentrates in Thailand, China, and India for cane sugar and maize feedstocks, while fermentation capacity clusters in Japan and South Korea. Supply chain risk centers on single-source dependency for steviol glycoside extraction from Chinese leaf processors. Distribution runs through direct sourcing arrangements between manufacturers and belt suppliers, bypassing legacy distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific food sweetener markets are recovering from regulatory-driven reformulation cycles as FSSAI, SAMR, and MHLW mandates compress traditional cane sugar demand. Beverage reformulation waves create cyclical procurement intensity that favors suppliers with fermentation scale and certification agility.
For Market Incumbents: Harden fermentation capacity utilization through precision bioprocess automation at Japanese and South Korean facilities to preempt recruitment competition from pharmaceutical sectors. Deepen backward integration into Thai sugarcane crushing operations to secure cost positions against weather-driven input volatility. Anchor certification maintenance services for export-oriented Southeast Asian processors seeking clean-label positioning. For New Entrants and Emerging Players: Eastern Java and Sulawesi dairy markets offer white-space conversion potential from cane sugar dominance with minimal high-intensity penetration. Surabaya processors represent the most penetrable segment for stevia-aspartame blend pilots. Deploy e-commerce ingredient platforms to disintermediate traditional distributor networks and capture mid-scale Malaysian beverage manufacturers through direct bulk purchasing. For Investors and Strategic Acquirers: SAMR's tightening GB 2760 standards for synthetic sweeteners reshapes the acquisition landscape toward fermentation-derived natural alternative portfolios. Target precision fermentation specialists with steviol glycoside strain optimization capabilities and existing MHLW positive list maintenance. Watch for FSSAI labeling enforcement intensity in Mumbai and Delhi NCR as the inflection signal for reformulation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Japanese bioprocess automation reduces batch-to-batch sweetness variance for steviol glycoside production. |
| Direct Sourcing Arrangements | Bangkok-based retailers strip distributor margins through centralized procurement desks with Thai belt suppliers. |
| Dual Certification Investment | Parallel FSSAI and SAMR submissions compress time-to-revenue for pan-Asia sweetener distribution. |
| Legacy Equipment Retrofit | Indian processors face capital-intensive dosing precision upgrades for hygroscopic high-intensity powder systems. |
| Clean-Label Innovation Teams | Cross-functional sweetness councils in Thailand and Vietnam override cost-driven procurement decisions. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across beverage formulation, bakery procurement, and fermentation technology domains. Primary interviews captured perspectives from FSSAI compliance officers, SAMR regulatory consultants, plant managers at Thai HFCS facilities, and clean-label innovation directors at Southeast Asian beverage manufacturers. Secondary validation drew from FSSAI notification databases, SAMR GB standard filings, Japanese MHLW positive list updates, and ASEAN harmonization working papers. Bottom-up volume estimates triangulated against top-down procurement desk aggregation across the analysis window.
Calibration against historical substitution elasticities and regulatory implementation lags anchored the analytical framework. Segmentation dimensions modeled include product type tier, end-use application, physical form state, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume projections and value-per-unit certification premiums. Industry-specific inputs incorporated weather-driven Thai sugarcane yield variance and precision fermentation capacity expansion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by plantation-integrated commodity processors would shift outcomes beyond projected ranges. Macroeconomic deviation in ASEAN trade flows, regulatory acceleration beyond FSSAI and SAMR announced timelines, or breakthroughs in enzymatic rare sugar conversion would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Asia-Pacific Stevia Market
Sweeteners
D-Mannose Market
Sweeteners
Organic Palm Sugar Market
Sweeteners
Sodium Saccharin Market
Sweeteners
Europe Plant-Derived and Synthetic Sugar Market
Sweeteners
Coconut Sugar Market
Sweeteners
Palm Sugar Market
Sweeteners
North America Starch Sweetener Market
Sweeteners
Global Cane Molasses Market
Sweeteners
Xylitol Market
Sweeteners
Japan Allulose Market
Sweeteners
Asia-Pacific Plant-Derived and Synthetic Sugar Market
Sweeteners
Invert Sugar Market
Sweeteners
South America Food Sweetener Market
Sweeteners
Stevia Mints Market
Sweeteners
Plant-Derived Sweetener Market