
 South America Digestive Health Supplements Market | 2026-2036
South America Digestive Health Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
South America Digestive Health Supplements Market Analytics
A capital-intensity divergence between multinational pharmaceutical conglomerates and specialized nutraceutical firms is redrawing competitive boundaries in the South America Digestive Health Supplements Market. GlaxoSmithKline PLC leverages its clinical trial infrastructure and pharmacy channel relationships to sustain premium positioning across Brazilian metropolitan markets. Bayer AG anchors its portfolio through broad retail distribution and consumer trust built on pharmaceutical heritage. PanTheryx Inc differentiates through bovine colostrum specialization and targeted immune-gut axis science.
South America digestive health supplements comprise orally administered formulations containing live microbial cultures, non-digestible fibers, or hydrolytic enzymes intended to modulate gastrointestinal function, nutrient absorption, or microbiome composition. These products typically deliver colony-forming units measured in billions for probiotics, or standardized activity units for enzymes, with stability requirements dictating refrigerated or shelf-stable packaging formats. Probiotics command the largest revenue pool due to established consumer recognition and clinical validation, while digestive enzymes represent the fastest-expanding category as athletes and aging populations seek targeted protein and carbohydrate breakdown support. Fiber supplements occupy a mature, price-competitive segment where private-label offerings from supermarket chains capture volume.
ANVISA governs product registration and health claim substantiation in Brazil, requiring toxicological and efficacy documentation that filters out undercapitalized entrants. Argentina's national food and drug administration enforces parallel standards for imported supplement labeling and active ingredient disclosure. Colombia's INVIMA maintains accelerated pathways for probiotic strains with established international safety profiles. Stakeholders must monitor how Mercosur harmonization negotiations reshape cross-border formulation approval timelines and mutual recognition protocols.
Market Dynamics
ANVISA's streamlined registration pathways for probiotic formulations are compressing market entry timelines for foreign manufacturers while simultaneously elevating documentation burdens that filter out undercapitalized regional competitors.
Growth Catalysts
- Colostrum science advancement:Bovine colostrum's immune-gut axis validation is opening new therapeutic positioning beyond traditional probiotic claims, particularly among athletic and senior cohorts in Brazil's southeastern corridor.
- Mercosur harmonization momentum:Ongoing mutual recognition protocol negotiations promise to collapse cross-border formulation approval timelines between Brazil, Argentina, and Uruguay.
- Pharmacy channel expansion:Brazilian pharmacy chains are dedicating premium shelf space to digestive wellness SKUs, creating dedicated microbiome sections that drive impulse adoption among chronic condition patients.
Market Restraints
- Refrigerated cold chain dependency:High-potency probiotic strains require temperature-controlled logistics infrastructure that remains patchy outside São Paulo and Buenos Aires metropolitan zones.
- ANVISA toxicological documentation:Foreign entrants face 18-24 month substantiation timelines for novel enzyme formulations, creating working capital traps for mid-tier manufacturers.
- Private-label fiber commoditization:Supermarket chains in Chile and Colombia have captured volume through aggressive inulin and psyllium sourcing, compressing branded margin pools.
Strategic Opportunities
- Amazon basin pharmacy penetration:Northern Brazilian states present underdeveloped retail infrastructure where telehealth-integrated supplement subscription models can bypass traditional distribution gaps.
- Shelf-stable enzyme innovation:Microencapsulation technologies enabling ambient-temperature protease and amylase stability are unlocking gym and travel channel placement previously closed to liquid formats.
- Argentina's accelerated probiotic pathway:ANMAT's fast-track for strains with EFSA or FDA GRAS recognition creates regulatory arbitrage for pre-cleared international portfolios.
Industry Challenges
- Strain-specific stability expertise:Formulation chemists capable of optimizing multi-strain probiotic survival through gastric transit command premium compensation that regional talent pools struggle to supply.
- Legacy ERP integration:Established Brazilian manufacturers face friction connecting batch-level traceability systems to ANVISA's evolving digital submission portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Digestive Health Supplements Market |
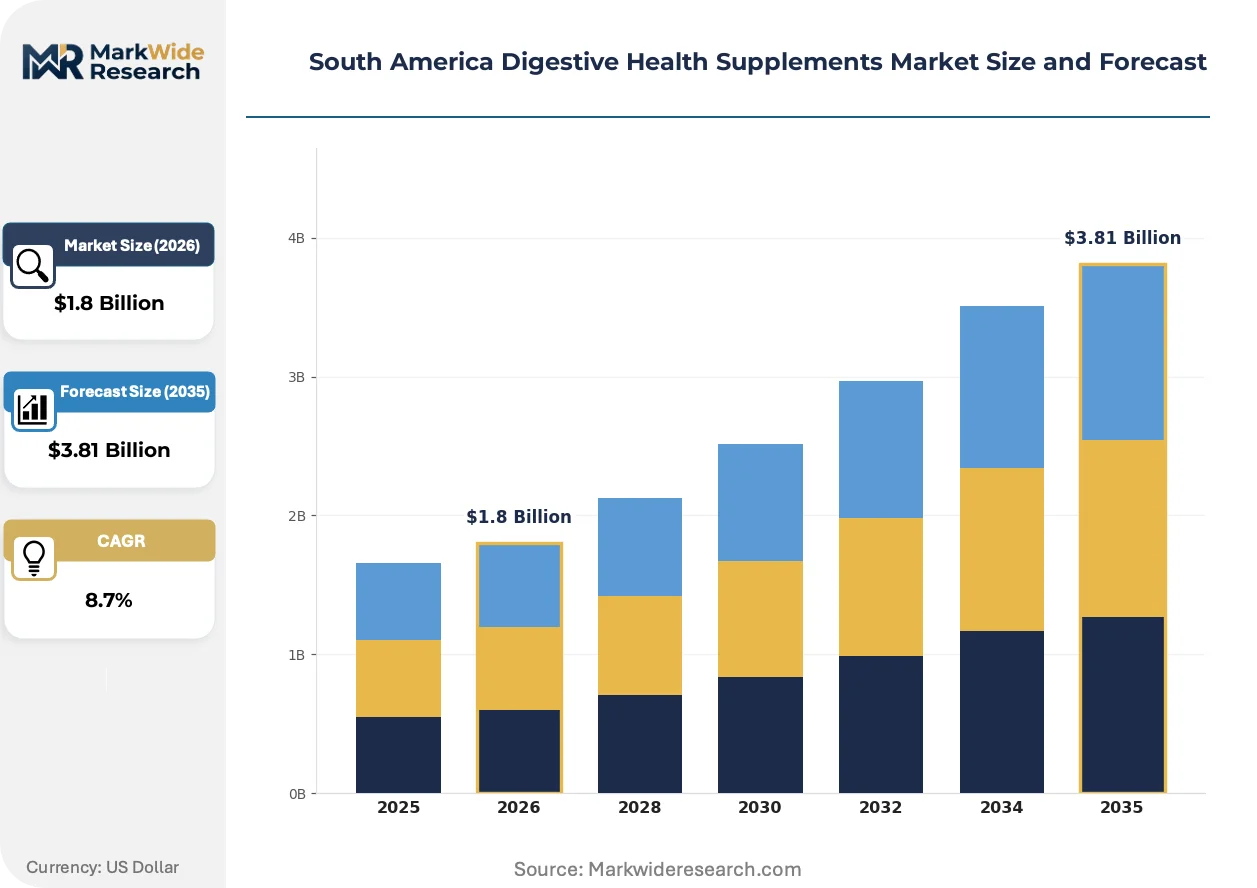
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Digestive Enzymes, Fiber Supplements End User: Adults, Seniors, Children, Athletes Form: Pills, Powders, Liquids, Gummies Distribution Channel: Online, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | GlaxoSmithKline PLC, Bayer AG, PanTheryx Inc, Herbalife International of America Inc, Metagenics Inc, General Nutrition Centers Inc, The Nature's Bounty Co, Koninklijke DSM NV, Zenwise Health, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Digestive Health Supplements Market Evolving Landscape
Microbiome personalization and delivery format innovation are fragmenting traditional supplement categories while regulatory data requirements reshape competitive moats across the Southern Cone.
Microencapsulation via lipid-based matrix systems is displacing traditional freeze-dried powder formats in premium probiotic segments. Brazilian sports nutrition brands and Argentine geriatric care providers are adopting these technologies at accelerating pace. The shift is compressing shelf-space allocation for conventional refrigerated SKUs while enabling pharmacy placement in climate-uncontrolled retail environments.
ANVISA's 2023 updated resolution on health claim substantiation now mandates clinical trial documentation for gastrointestinal function claims exceeding generic maintenance language. This regulatory tightening is forcing reformulation of legacy portfolios and redirecting R&D budgets toward strain-specific human intervention studies. Foreign manufacturers with existing EFSA Article 13.5 dossiers are leveraging mutual recognition arguments to accelerate Brazilian market entry.
Athletes and fitness enthusiasts across São Paulo and Rio de Janeiro are abandoning single-ingredient enzyme tablets for multi-enzyme complexes bundled with adaptogenic botanicals. This consumption-pattern shift is disrupting pharmacy merchandising conventions that historically separated digestive health from sports nutrition aisles. Direct-to-consumer platforms and gym-affiliated nutrition consultants are capturing this crossover demand faster than traditional retail channels can reconfigure.
South America Digestive Health Supplements Market Segmentation
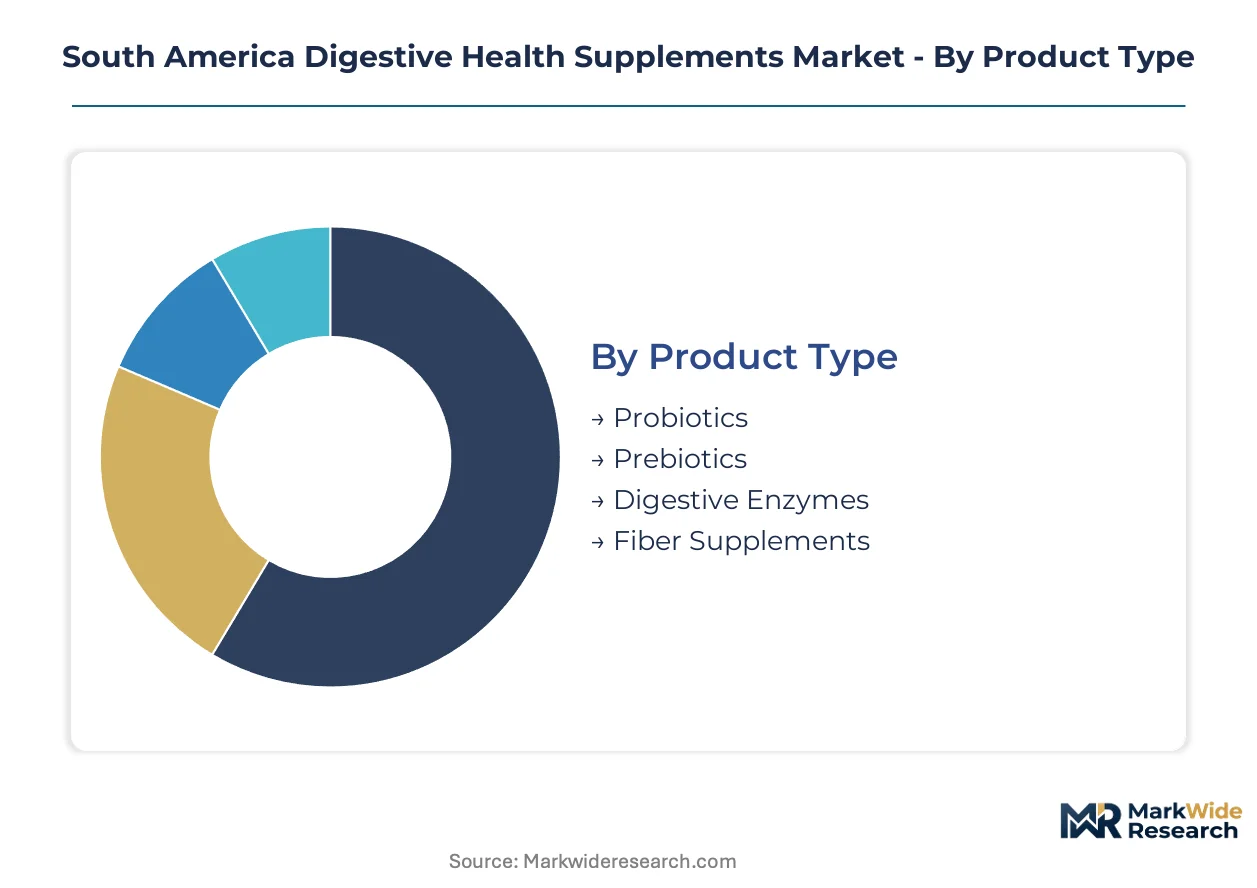
Segmentation in the South America Digestive Health Supplements Market reveals distinct demand patterns across product chemistry, user physiology, and channel infrastructure. Each dimension carries unique regulatory, logistical, and pricing implications that reshape competitive positioning.
Product Type:
Domestic formulation dominates probiotic and enzyme production across Brazil and Argentina, while prebiotic fibers rely heavily on imported inulin from European and North American suppliers.
- Probiotics:Live microbial cultures delivering colony-forming units in billions, typically multi-strain formulations targeting Lactobacillus and Bifidobacterium species. Brazilian pharmacy chains in São Paulo and Minas Gerais drive the bulk of volume, though refrigerated cold chain gaps in northern states constrain penetration. ANVISA's strain-specific registration requirements filter out undercapitalized regional blenders.
- Digestive Enzymes:Hydrolytic proteins—proteases, amylases, lipases—measured in standardized activity units for targeted macronutrient breakdown. Athletes across Rio de Janeiro and gym-affiliated nutrition consultants in São Paulo's southeastern corridor are adopting multi-enzyme complexes faster than traditional retail channels can reconfigure shelf placement.
- Prebiotics:Non-digestible fibers—fructooligosaccharides, galactooligosaccharides—serving as microbiome nutrients rather than live cultures. Argentine and Chilean markets show stronger uptake than Brazil due to European formulation familiarity.
- Fiber Supplements:Psyllium husk and inulin-based products occupying mature, price-competitive positioning. Supermarket private-label offerings from Chilean and Colombian chains have captured significant volume through aggressive sourcing.
Probiotics command the established base. The steepest expansion runs through digestive enzymes.
End User:
Seniors and athletes represent the highest-margin customer tiers, while children and general adults drive volume through broader channel access.
- Adults:General wellness seekers purchasing through supermarkets and online platforms, typically price-sensitive and brand-agnostic in fiber and basic probiotic categories.
- Seniors:Rapidly expanding cohort across Brazil and Argentina where aging demographics drive probiotic and enzyme adoption for nutrient absorption and gastrointestinal maintenance. Brazilian geriatric care providers in the southeastern corridor are adopting microencapsulated formats at accelerating pace.
- Children:Pediatric formulations requiring taste masking and gummy or liquid delivery, with parents prioritizing ANVISA-registered safety documentation over premium pricing.
- Athletes:Fitness enthusiasts abandoning single-ingredient enzyme tablets for bundled multi-enzyme and adaptogenic complexes. Direct-to-consumer platforms capture this crossover demand faster than pharmacy merchandising conventions can adapt.
Seniors anchor margin expansion. Athletes are gaining share fastest through channel disruption.
Form:
Shelf-stable innovations are displacing refrigerated formats, with powder and gummy segments climbing fastest through climate-adapted logistics.
- Pills:Traditional capsule and tablet formats dominating pharmacy channel placement, though swallowing difficulties limit senior and pediatric adoption.
- Powders:Sachet and bulk formats enabling flexible dosing, particularly prevalent in sports nutrition and clinical settings across São Paulo and Buenos Aires metropolitan zones.
- Liquids:Pediatric and geriatric preference for ease of administration, constrained by shorter shelf life and higher shipping costs outside cold chain infrastructure.
- Gummies:Taste-masked delivery systems capturing children and adult wellness seekers through pharmacy and supermarket impulse placement, with Brazilian brands leading regional formulation innovation.
Pills retain volume leadership. Gummies follow the steepest trajectory through format innovation.
Distribution Channel:
Pharmacy chains and digital platforms are consolidating share, while supermarkets face margin compression in commoditized fiber segments.
- Online:Direct-to-consumer platforms and telehealth-integrated subscription models bypassing distribution gaps in northern Brazilian states, capturing athlete and senior demand through personalized recommendation engines.
- Supermarkets:Volume channel for fiber supplements and basic probiotics, with Chilean and Colombian chains leveraging private-label sourcing to compress branded margin pools.
- Health Stores:Specialized retail emphasizing premium and imported formulations, serving educated consumers seeking strain-specific or organic-certified products in Buenos Aires and Santiago.
- Pharmacies:Brazilian chains dedicating premium shelf space to digestive wellness SKUs, creating dedicated microbiome sections that drive impulse adoption among chronic condition patients in the southeastern corridor.
Pharmacies hold the established position. Online channels are expanding most quickly through infrastructure bypass.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian consumers favor probiotic pharmacy purchases, while Argentine buyers gravitate toward European-imported prebiotic fibers. Chilean and Colombian markets exhibit stronger supermarket private-label penetration than elsewhere in the region.
Brazil
Senior populations in São Paulo and Minas Gerais drive multi-strain probiotic adoption through pharmacy chain microbiome sections. ANVISA's streamlined registration pathways compress foreign manufacturer entry timelines while elevating documentation burdens. The southeastern corridor anchors volume concentration, though refrigerated cold chain gaps constrain northern state penetration.
Argentina
Aging demographics in Buenos Aires metropolitan zones accelerate enzyme demand for nutrient absorption support. ANMAT maintains accelerated pathways for probiotic strains with EFSA or FDA GRAS recognition, creating regulatory arbitrage opportunities. European formulation familiarity strengthens prebiotic uptake relative to neighboring markets.
Chile
Supermarket chains capture fiber supplement volume through aggressive inulin and psyllium private-label sourcing. The national pharmaceutical regulator enforces parallel standards for imported supplement labeling and active ingredient disclosure. Santiago-based health stores emphasize premium imported formulations for educated consumers seeking organic-certified products.
Colombia
INVIMA maintains accelerated pathways for probiotic strains with established international safety profiles. Supermarket private-label commoditization compresses branded margin pools in mature fiber segments. Pharmacy infrastructure expansion in Bogotá and Medellín creates dedicated digestive wellness shelf space.
Uruguay
Mercosur harmonization negotiations promise collapsed cross-border formulation approval timelines with Brazil and Argentina. Small population scale limits standalone manufacturing economics, favoring import-dependent distribution models. Montevideo pharmacy networks serve as testbeds for regional product launches targeting Southern Cone portability.
South America Digestive Health Supplements Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the South America digestive health supplements market. Pharmaceutical conglomerates leverage clinical trial infrastructure and pharmacy channel relationships to sustain premium positioning. Specialized nutraceutical firms differentiate through strain-specific science and targeted delivery format innovation. Competitive moves concentrate on portfolio diversification into shelf-stable formats and strategic partnerships with telehealth-integrated distribution platforms.
Within the pharmaceutical heritage tier, GlaxoSmithKline PLC and Bayer AG occupy positions anchored by consumer trust and broad retail distribution networks. PanTheryx Inc represents the specialized science archetype, exemplifying bovine colostrum differentiation and immune-gut axis positioning. These three entities collectively illustrate the capital-intensity divergence redrawing competitive boundaries across Brazilian metropolitan markets and Argentine urban centers.
| Leading Market Players |
|---|
| GlaxoSmithKline PLC |
| Bayer AG |
| PanTheryx Inc |
| Herbalife International of America Inc |
| Metagenics Inc |
| General Nutrition Centers Inc |
| The Nature's Bounty Co |
| Koninklijke DSM NV |
| Zenwise Health |
| Others |
Value Network & Pricing Analysis
Microencapsulation technology substitution for traditional freeze-dried probiotic formats is redrawing supply geography toward Brazilian and Argentine contract manufacturers while collapsing cold chain premiums that once sustained refrigerated SKU margins. This format migration simultaneously elevates formulation complexity costs and compresses finished goods pricing tiers as shelf-stable alternatives flood pharmacy and gym channels.
Pricing Analysis
Subscription-based replenishment programs for chronic condition patients now drive lifetime value beyond initial transaction margins. Three-tier pricing structure across premium strain-specific formulations, standard multi-strain blends, and economy private-label alternatives stratifies the market. Cost compression in fiber supplements intensifies as Chilean and Colombian supermarket chains expand aggressive inulin sourcing. General adult wellness seekers exhibit highest price sensitivity, while seniors managing chronic gastrointestinal conditions accept premium positioning for clinically documented strains.
Supply Chain Analysis
Refrigerated last-mile logistics chokepoints in northern Brazilian states constrain high-potency probiotic penetration outside São Paulo and Minas Gerais metropolitan corridors. Raw material sourcing draws from European inulin suppliers, North American enzyme concentrate producers, and domestic Brazilian colostrum processors. Single-source vulnerability concentrates in specialty strain libraries held by select international culture collections. Distribution runs through pharmacy chain central warehouses, direct-to-consumer fulfillment centers, and supermarket regional distribution hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth-integrated supplement subscription models represent the fastest-expanding service-attach layer, outpacing traditional retail hardware transactions as Brazilian pharmacy chains and digital platforms build recurring revenue infrastructure around chronic patient management.
For Market Incumbents: Consolidate microbiome section shelf space dominance through exclusive strain licensing agreements with international culture collections, countering emerging direct-to-consumer brands that bypass traditional pharmacy merchandising. Deepen backward integration into microencapsulation manufacturing capacity within São Paulo state to capture format innovation margins and reduce third-party toll processing dependency. For New Entrants and Emerging Players: Anchor in Amazon basin telehealth-integrated subscription models, exploiting refrigerated cold chain gaps that constrain incumbent probiotic penetration in northern Brazilian states. Target athletic cohorts in Rio de Janeiro and São Paulo with bundled multi-enzyme adaptogenic complexes, leveraging gym-affiliated nutrition consultant channels that traditional pharmacy merchandising conventions underserve. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Brazilian pharmacy chain consolidators seeking digestive wellness portfolio expansion. Five-to-ten year viability hinges on regulatory arbitrage capture as Mercosur harmonization collapses cross-border approval timelines. Monitor ANVISA digital submission portal integration milestones as inflection indicator for operational scalability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Shelf-Stable Enzyme Innovation | Microencapsulation technologies unlock gym and travel channel placement previously closed to liquid formats. |
| Telehealth Subscription Integration | Direct-to-consumer platforms bypass distribution gaps in northern Brazilian states through personalized recommendation engines. |
| Strain-Specific Registration Investment | ANVISA's toxicological documentation requirements filter out undercapitalized regional blenders from premium positioning. |
| Pharmacy Chain Microbiome Sections | Dedicated shelf space drives impulse adoption among chronic condition patients in São Paulo and Minas Gerais. |
| Mercosur Harmonization Positioning | Accelerated cross-border formulation approvals between Brazil, Argentina, and Uruguay collapse regional expansion timelines. |
Research Methodology
Cross-validation between regulatory filing databases and pharmacy channel inventory audits anchors the qualitative findings on market structure and competitive positioning. Primary interviews with ANVISA registration consultants, Brazilian pharmacy chain category managers, Argentine geriatric care providers, and sports nutrition formulators combine with secondary validation from ANVISA resolution archives, INVIMA safety bulletins, and customs import records. Bottom-up strain-level demand modeling triangulates against top-down retail audit data across the analysis window.
Sensitivity analysis around cold chain infrastructure expansion rates and Mercosur protocol implementation timelines informs the analytical framework. Segmentation dimensions span product chemistry, user physiology, delivery format, and channel infrastructure across the projection horizon. CAGRs derive from patient population epidemiology, pharmacy channel expansion trajectories, and regulatory pathway velocity. Forecast inputs incorporate ANVISA digital portal adoption curves and microencapsulation technology cost reduction slopes.
Underlying assumptions cover sustained ANVISA registration pathway streamlining, with deviation risk concentrated in Mercosur negotiation delays and refrigerated logistics infrastructure buildout pacing. Practitioners should keep alternative scenarios live as regulatory harmonization timelines and cold chain investment commitments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Global Probiotics Food and Cosmetics Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
South America Microbial Food Culture Market
Probiotic Supplements
Global Liquid Feed Supplements Market
Probiotic Supplements
United States Probiotics Market
Probiotic Supplements
United Kingdom Probiotics Market
Probiotic Supplements
Microbial Food Culture Market
Probiotic Supplements
Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market
Probiotic Supplements
Bifidobacteria Lysates Market
Probiotic Supplements
Probiotics for Kids Market
Probiotic Supplements
Single-Strain Probiotics Market
Probiotic Supplements
Probiotic Strains Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
Probiotics Market
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
Vegan Probiotics Market