
 South Africa Food Sweetener Market | 2026-2036
South Africa Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Food Sweetener Market Analytics
Health-conscious beverage producers is bifurcating the South Africa Food Sweetener Market away from traditional sugar-reliant food manufacturers. Cargill leverages its stevia supply chain infrastructure to serve reformulating soft-drink clients. Tate & Lyle anchors the market through its specialty sweetener portfolio targeting reduced-sugar dairy applications. Ingredion competes aggressively on glucose syrup alternatives for bakery sector clients seeking levy-compliant formulations.
Food sweeteners encompass caloric and non-caloric substances—sucrose, fructose, glucose, and stevia glycosides—that impart sweetness to food matrices at specified potency thresholds measured relative to sucrose equivalence. Manufacturers deploy these compounds to achieve targeted sensory profiles while managing energy density, glycemic response, and production costs in processed foods. Sucrose retains volume leadership across bakery and confectionery applications where bulk and browning functionality prove irreplaceable, though margin pools are migrating toward stevia segments driven by clean-label formulation mandates. Liquid sweetener forms dominate beverage manufacturing for homogeneous dispersion, while granulated formats sustain relevance in household and small-scale restaurant channels where handling convenience governs procurement.
The Department of Health's sugar reduction targets and the Health Promotion Levy reshape product standards by penalizing sugar-dense formulations and accelerating reformulation timelines. BIS-equivalent local standards and SABS certification requirements govern import quality thresholds, filtering market access for international suppliers. Stakeholders must monitor enforcement intensity around front-of-pack labeling rules and anticipate how Treasury's levy rate adjustments will redirect procurement between caloric and non-caloric alternatives.
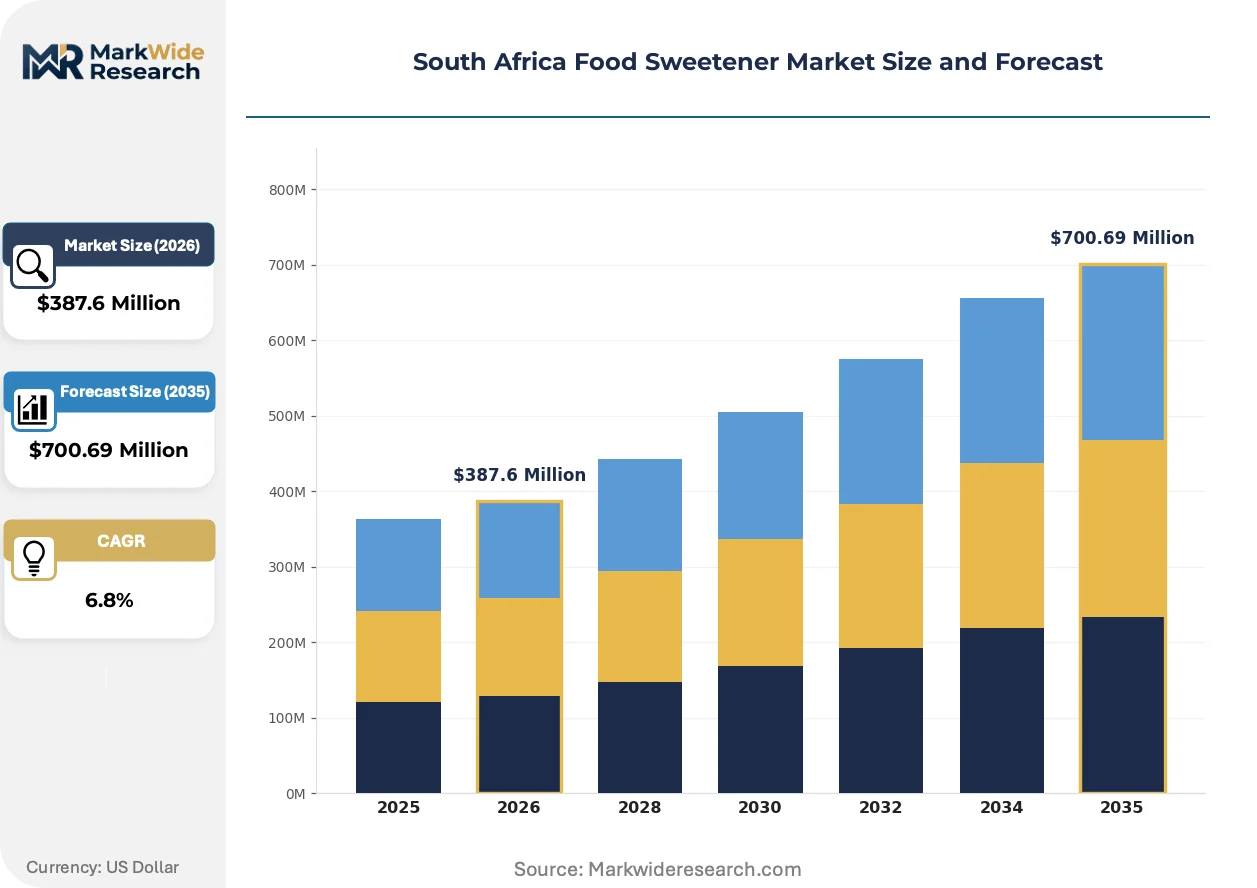
Market Dynamics
The Health Promotion Levy on sugar-sweetened beverages is compressing formulation timelines across South Africa's beverage sector, forcing manufacturers to accelerate procurement of non-caloric alternatives while maintaining sensory parity with legacy recipes.
Growth Catalysts
- Health Promotion Levy:Treasury's sugar tax penalizes high-sugar formulations above specified thresholds, redirecting R&D budgets toward stevia and monk fruit extracts.
- Clean-label mandates:Retailers in Gauteng province now require front-of-pack sugar disclosure, compelling confectionery manufacturers to reformulate with plant-derived high-intensity sweeteners.
- Stevia extraction advances:Enzymatic bioconversion methods are reducing bitter aftertaste in Reb M glycosides, expanding applicability beyond beverages into dairy and bakery matrices.
Market Restraints
- Input cost volatility:Stevia leaf supply concentrates in China and Kenya, exposing South African formulators to currency fluctuation and shipping disruption.
- Technical limitation:Bulking functionality loss when replacing sucrose in baked goods requires expensive hydrocolloid systems to maintain moisture and crumb structure.
- Regulatory friction:SABS certification delays for novel sweetener blends extend product launch timelines by 8-14 months versus standard food additive approvals.
Strategic Opportunities
- Underpenetrated geography:KwaZulu-Natal's emerging beverage bottling corridor offers first-mover positioning for high-intensity sweetener distributors.
- Regulatory tailwind:Department of Health's 2025 sugar reduction targets for processed foods will mandate reformulation across categories currently exempt from the Health Promotion Levy.
- Distribution innovation:Direct-to-manufacturer liquid sweetener dispensing systems are eliminating intermediate packaging costs for large-scale soft-drink producers.
Industry Challenges
- Formulation skill scarcity:South African food technologists trained in traditional sugar chemistry require upskilling in high-intensity sweetener synergy and masking techniques.
- Legacy equipment retrofitting:Existing liquid handling infrastructure designed for 60-70 Brix sucrose solutions demands capital modification for low-dose high-potency alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Food Sweetener Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sucrose, Fructose, Glucose, Stevia Application: Bakery, Confectionery, Beverages, Dairy End User: Food Manufacturers, Beverage Producers, Home Cooks, Restaurants Form: Liquid, Powder, Granulated, Tablet |
| Companies Covered | Cargill, Tate & Lyle, Archer Daniels Midland Company, Ingredion, Ajinomoto, PureCircle, GLG Life Tech Corporation, Chr. Hansen, Novozymes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Food Sweetener Market Evolving Landscape
Bioconversion technologies and regulatory disclosure mandates are fragmenting established procurement patterns. Manufacturers now prioritize sensory-matched sugar reductions over cost-per-kilogram optimization.
Enzymatic stevia glycoside production is fragmenting the supply base for Reb M and Reb D compounds. Synthetic biology firms now compete with traditional agricultural extraction for beverage manufacturer contracts. This technology is fragmenting price benchmarks that previously anchored to leaf-derived commodity stevia, enabling mid-tier brands to access sweetness profiles once restricted to premium formulations.
South Africa's Department of Health front-of-pack labeling regulations are compressing reformulation decision cycles. Manufacturers must disclose added sugar content above defined thresholds, exposing competitive disadvantages in legacy recipes. The beverage sector faces the steepest compliance burden, with major soft-drink producers accelerating pilot programs for allulose-stevia blends ahead of enforcement deadlines.
Direct procurement contracts between sweetener suppliers and large beverage manufacturers are displacing traditional distributor intermediaries. Volume commitments now span 3-5 year horizons with price escalation clauses tied to agricultural commodity indices. This consolidation is most visible in Gauteng province, where concentrated manufacturing clusters enable tanker-delivered liquid sweetener systems at scale.
South Africa Food Sweetener Market Segmentation
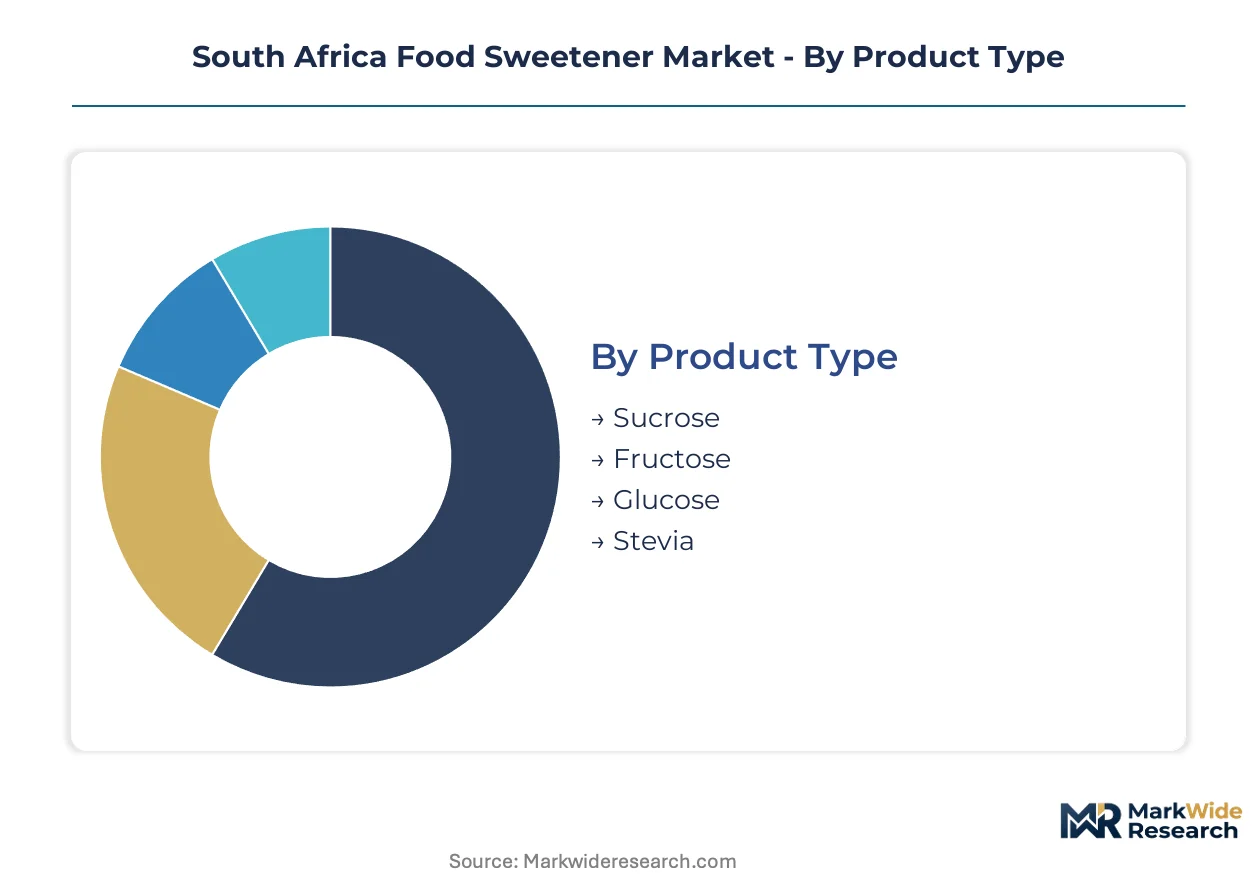
Sweetener procurement patterns in South Africa diverge sharply across product chemistry, application requirements, and end-user scale. Manufacturers optimize formulations against the Health Promotion Levy's sugar thresholds while balancing sensory performance and production economics.
Product Type:
Margin pools concentrate in high-intensity plant-derived segments where clean-label premiums offset extraction technology investments.
- Sucrose:Refined cane and beet sugar delivers bulk sweetness, browning functionality, and crystalline structure critical to traditional confectionery. Gauteng's bakery clusters absorb the majority of industrial volumes despite levy-driven substitution pressure in adjacent beverage categories.
- Stevia:Glycoside extracts—primarily Reb A and advancing Reb M formulations—provide non-caloric sweetness at 200-400x sucrose potency. Beverage producers in Johannesburg and Pretoria manufacturing corridors are the primary demand anchors as front-of-pack labeling mandates accelerate reformulation timelines.
- Fructose:Monosaccharide sweetener derived from corn or sugarcane with enhanced sweetness intensity and lower glycemic impact than sucrose.
- Glucose:Dextrose and glucose syrups supply fermentable substrates, humectancy, and viscosity control across processed food matrices.
The dominant share belongs to Sucrose, while Stevia is closing the gap fastest.
Application:
Volume concentration tracks manufacturing infrastructure density, with beverage and dairy processing clusters driving procurement scale.
- Beverages:Carbonated soft drinks, ready-to-drink teas, and flavored waters require homogeneous sweetness dispersion at cold temperatures. The Health Promotion Levy's per-gram sugar penalty has compressed reformulation cycles, redirecting procurement toward stevia-allulose blends in Gauteng's concentrated bottling facilities.
- Confectionery:Hard candies, chocolates, and chewing gums depend on precise crystallization control and glass transition temperatures. Technical constraints around bulking agent replacement currently limit high-intensity sweetener penetration despite retailer clean-label demands.
- Bakery:Breads, cakes, and pastries utilize sweeteners for yeast activation, moisture retention, and Maillard browning reactions.
- Dairy:Flavored yogurts, ice creams, and milk beverages balance sweetness with protein stability and freeze-thaw performance.
Beverages command the largest procurement volumes, though Confectionery faces the steepest technical barriers to sugar reduction.
End User:
Procurement scale and technical sophistication separate industrial buyers from household channels, with distinct distribution and formulation service requirements.
- Food Manufacturers:Industrial bakeries, confectionery plants, and processed food facilities purchase bulk sweeteners with integrated technical support. These buyers negotiate multi-year supply agreements with price escalation clauses tied to agricultural commodity indices.
- Beverage Producers:Soft-drink bottlers and dairy processors represent the most technically demanding segment, requiring precise sweetness modulation and stability testing.
- Restaurants:Food service operations source granulated and liquid formats for recipe execution with limited reformulation flexibility.
- Home Cooks:Retail-packaged sugar and tabletop sweetener tablets serve household consumption with brand loyalty driving repeat purchase.
Food Manufacturers retain the dominant procurement position, while Beverage Producers are expanding their share fastest through direct supplier contracts.
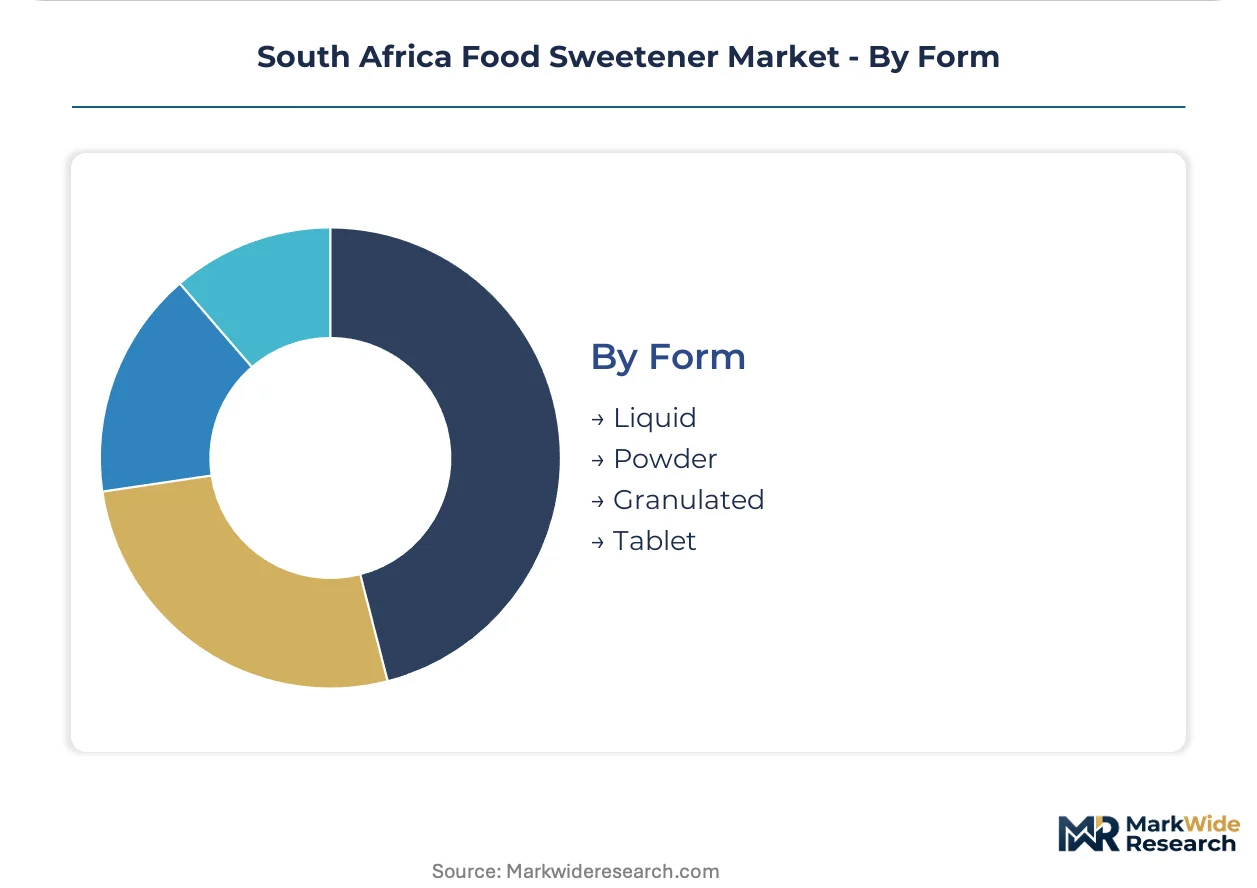
Form:
Physical state determines handling infrastructure, dispersion characteristics, and packaging economics across the supply chain.
- Liquid:High-Brix syrups and concentrated sweetener solutions enable metered dosing in continuous beverage production. Tanker delivery systems eliminate intermediate packaging for large-scale Gauteng manufacturers.
- Powder:Spray-dried and milled sweeteners offer rapid dissolution for dry beverage mixes and instant applications.
- Granulated:Crystalline formats sustain relevance in household channels and small-scale food service where handling convenience governs selection.
- Tablet:Compressed single-serve units target coffee and tea preparation in hospitality settings.
Liquid forms dominate industrial procurement, with Powder formats gaining share fastest in convenience-oriented beverage premixes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
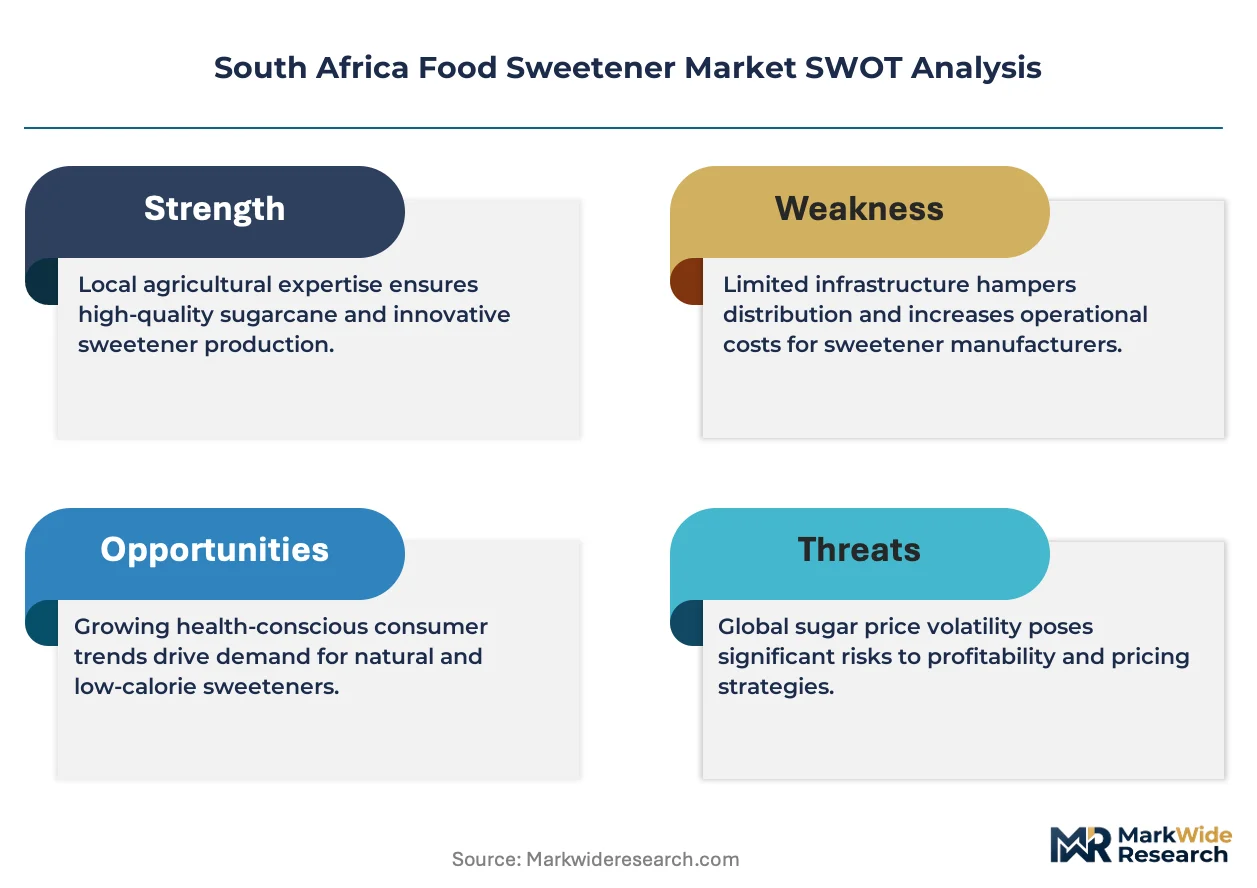
The Richards Bay Coal Terminal and Maputo Corridor rail infrastructure underpin sweetener distribution networks across Southern Africa, connecting Gauteng manufacturing clusters to coastal export channels and regional inland markets.
Gauteng
Johannesburg and Pretoria manufacturing corridors concentrate beverage bottling capacity requiring high-intensity sweetener volumes. The Department of Health's sugar reduction targets apply most stringently here given production density. Industrial parks in Isando and Rosslyn host direct tanker delivery systems for liquid stevia formulations serving reformulating soft-drink clients.
Western Cape
Cape Town's port facilities enable import handling for crystalline sucrose and specialty sweetener intermediates. SABS certification laboratories in the region process novel sweetener blend approvals for national distribution. Paarl and Stellenbosch wine districts drive niche demand for grape-derived sweetener alternatives in premium beverage applications.
KwaZulu-Natal
Durban's container terminal ranks as the primary entry point for Chinese and Kenyan stevia leaf shipments. Emerging beverage bottling corridors around Pietermaritzburg attract distributor investment ahead of provincial industrial expansion programs. The Dube Trade Port special economic zone offers tariff advantages for imported high-intensity sweetener processing.
Eastern Cape
Port Elizabeth automotive manufacturing dominance limits food processing infrastructure relative to other provinces. Coega Industrial Development Zone incentives target agro-processing investments including sweetener blending facilities. Local procurement concentrates in household granulated sugar channels serving lower-income consumer segments.
South Africa Food Sweetener Market Competitive Landscape
Listed leaders compete with private specialists across formulation technology and supply chain scale. The South Africa Food Sweetener Market exhibits tiered concentration with multinational agricultural processors commanding industrial volumes while regional distributors retain household channel relevance. Three archetypes dominate: integrated agricultural commodity traders with stevia supply chain infrastructure, specialty ingredient formulators targeting dairy and bakery applications, and enzymatic technology licensors enabling bioconversion production methods. Competitive moves center on direct-to-manufacturer liquid dispensing system deployment and multi-year volume commitment contracting with price escalation clauses.
Within the integrated commodity trader tier, Cargill and Archer Daniels Midland Company represent archetypal positions anchored to agricultural sourcing networks and bulk handling infrastructure. Tate & Lyle occupies a specialist position exemplifying portfolio diversification toward reduced-sugar dairy applications. These three entities collectively illustrate the competitive spectrum from upstream agricultural control through downstream formulation services.
| Leading Market Players |
|---|
| Cargill |
| Tate & Lyle |
| Archer Daniels Midland Company |
| Ingredion |
| Ajinomoto |
| PureCircle |
| GLG Life Tech Corporation |
| Chr. Hansen |
| Novozymes |
| Others |
Value Network & Pricing Analysis
SABS certification requirements gate both supplier qualification and price differentiation simultaneously, filtering import access for international sweetener suppliers while creating tiered value pools based on compliance speed and formulation technical support.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations between large beverage manufacturers and stevia suppliers, with three-tier pricing separating premium Reb M formulations from standard Reb A extracts and economy-grade commodity stevia. Price differentiation rests on enzymatic bioconversion certification and direct tanker delivery capability, with Gauteng-based bottlers commanding the steepest discounts through multi-year offtake commitments. Pricing pressure stems from Chinese and Kenyan leaf supply volatility, compressing margins for distributors lacking backward integration into extraction facilities. Small-scale confectionery manufacturers exhibit the highest price sensitivity due to limited reformulation budgets, while multinational beverage producers prioritize sensory performance over per-kilogram cost.
Supply Chain Analysis
Inventory lead times for stevia leaf inputs extend 12-16 weeks from Chinese and Kenyan agricultural zones, exposing South African formulators to currency fluctuation and shipping disruption through the Durban container terminal. Raw material dependencies center on stevia leaf biomass, enzymatic conversion catalysts, and hydrocolloid bulking systems for bakery applications. Supply chain risk concentrates in single-source vulnerability for Reb M glycoside bioconversion technology, currently controlled by a limited set of synthetic biology licensors. Distribution runs through direct-to-manufacturer liquid dispensing systems in Gauteng industrial corridors, displacing traditional distributor intermediaries for large-scale beverage accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored to regulatory entrenchment, where SABS certification timelines and Health Promotion Levy compliance expertise create sticky supplier relationships that resist price-based displacement.
For Market Incumbents: Shield market position by deepening captive supply of stevia leaf through equity partnerships with Kenyan agricultural cooperatives, insulating against Chinese supply disruption. Accelerate technical service capacity in dairy and bakery formulation support, as these categories face imminent sugar reduction mandates that will force manufacturer switching decisions. Prioritize certification investment for novel allulose-stevia blends ahead of anticipated Department of Health processed food targets. For New Entrants and Emerging Players: Anchor in KwaZulu-Natal's emerging beverage bottling corridor, where first-mover positioning for high-intensity sweetener distribution remains underdeveloped relative to Gauteng saturation. Target mid-tier dairy processors seeking reformulation partnerships without the minimum volume thresholds imposed by multinational suppliers. Pursue a technical-specialist go-to-market angle emphasizing rapid SABS navigation and customized masking solutions for regional taste preferences. For Investors and Strategic Acquirers: Department of Health sugar reduction targets reshape the acquisition landscape toward enzymatic bioconversion technology holders and regional distributors with SABS-fast-track relationships. Five-to-ten-year viability favors platforms combining upstream agricultural control with downstream formulation services, as pure-play distributors face margin compression from direct procurement trends. Watch enforcement intensity around front-of-pack labeling rules as the signal indicating acceleration of manufacturer switching cycles and valuation inflection for compliance-ready assets.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Bioconversion Capacity Expansion | Reb M glycoside production unlocks premium beverage formulations previously restricted to leaf-extracted supply constraints. |
| Direct Tanker Delivery System Deployment | Liquid sweetener infrastructure in Gauteng industrial parks eliminates packaging costs and locks in multi-year volume commitments. |
| SABS Certification Fast-Track Investment | Accelerated novel blend approvals compress product launch timelines from 14 months toward competitive 8-month benchmarks. |
| Kenyan Agricultural Partnership | Upstream stevia leaf supply control reduces exposure to Chinese currency fluctuation and shipping disruption through Durban. |
| Dairy and Bakery Technical Service Buildout | Specialized formulation support captures reformulation budgets as Department of Health targets extend beyond beverages. |
Research Methodology
Cross-validation between beverage manufacturer procurement interviews and secondary trade data anchors the qualitative findings on stevia adoption trajectories. Primary engagement spanned R&D directors at soft-drink bottlers, category buyers at retail chains, technical sales leads at ingredient distributors, and regulatory affairs managers navigating SABS certification pathways. Secondary sources included customs import records, Department of Health levy implementation reports, and agricultural commodity price indices. Bottom-up segmentation modeling triangulated against top-down market sizing from manufacturing capacity assessments.
Sensitivity analysis around Health Promotion Levy rate adjustments and enforcement timing variations tested forecast robustness across the projection horizon. Segmentation dimensions modeled encompass product chemistry tiers, application requirements across beverage and dairy matrices, end-user scale categories, and provincial manufacturing cluster density. CAGRs derived from weighted average of historical volume trajectories and forward-looking reformulation pipeline analysis, with specific inputs from stevia glycoside potency improvement curves and front-of-pack labeling compliance cost estimates.
Decision-makers should treat outputs as directional under sustained levy enforcement and stable agricultural supply assumptions; material deviation in regulatory intensity or Chinese export policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
United States Food Sweetener Market
Sweeteners
South America Low-Calorie Sweeteners Market
Sweeteners
Natural Caloric Sweeteners Market
Sweeteners
North America Sugar Substitutes Market
Sweeteners
D-Mannose Market
Sweeteners
Russia Food Sweetener Market
Sweeteners
Nutritive Sweeteners Market
Sweeteners
North America High-Intensity Sweeteners Market
Sweeteners
France Food Sweetener Market
Sweeteners
Naturally Derived Sweeteners Market
Sweeteners
Cassava Syrup Market
Sweeteners
Tagatose Market
Sweeteners
Beetroot Molasses Market
Sweeteners
Europe Food Sweetener Market
Sweeteners
Allulose Market
Sweeteners
Vanilla Sugar Market