
 Xylose Market | 2026-2036
Xylose Market Size, Share, and Industry Trends Forecast 2026-2036
Xylose Market Analysis
Contract manufacturing and toll-processing services for xylose refinement is expanding the addressable market beyond captive producers. Shandong Xieli Biotechnology leverages integrated corn cob-to-xylose processing to sustain cost leadership in crystalline grades. DuPont Danisco anchors North American supply through fermentation technology leadership. Roquette Frères competes on pharmaceutical-grade certification and European distribution density.
Xylose is a five-carbon aldose sugar (C5H10O5) extracted from lignocellulosic biomass such as corn cobs, sugarcane bagasse, and hardwood through acid hydrolysis and chromatographic purification; it functions as a low-glycemic sweetener, Maillard reaction precursor, and microbial fermentation substrate. Crystalline xylose commands premium positioning in pharmaceutical applications where particle size and purity specifications determine excipient eligibility. Xylose syrup volumes dominate food and beverage procurement due to lower unit costs and easier handling in liquid processing lines. Powdered xylose occupies a narrowing mid-tier as formulators polarize between crystalline precision and syrup economy.
FDA food additive regulations and EFSA novel food assessments shape market access timelines for new xylose suppliers entering pharmaceutical and nutraceutical channels. China's NMPA and GB standards enforce purity thresholds that determine export eligibility for domestic producers like Healtang Biotech and Futaste Group. REACH registration requirements and the EU F-Gas Regulation indirectly pressure biorefinery energy inputs, altering cost structures for European manufacturers. Stakeholders must monitor regulatory divergence between pharmaceutical-grade and food-grade certification pathways as compliance costs increasingly segment supplier competitiveness.
Market Dynamics
Pharmaceutical formulators are consolidating xylose procurement around crystalline grades as excipient purity standards tighten under FDA and EMA frameworks, compressing margins for syrup-grade suppliers and rewarding integrated biorefiners with chromatographic capabilities.
Growth Catalysts
- Prebiotic formulation expansion:Nutraceutical developers are incorporating xylose into synbiotic blends targeting gut microbiome modulation, driving volume pull from functional food manufacturers in Germany and Japan.
- EU Green Deal biomass mandates:Renewable sourcing requirements for sugar-derived ingredients are accelerating lignocellulosic feedstock investments, advantaging producers with corn cob and bagasse supply chains.
- Fermentation substrate substitution:Microbial cell culture facilities are replacing glucose with xylose in precision fermentation processes to reduce glycation byproducts in therapeutic protein production.
Market Restraints
- Acid hydrolysis energy intensity:Sulfuric acid pretreatment and chromatographic purification consume substantial thermal energy, exposing producers to natural gas price volatility in European manufacturing clusters.
- Feedstock geographic concentration:Corn cob supply chains concentrate in North China plains and US Midwest grain belts, creating single-source vulnerability for non-integrated refiners.
- C5 sugar metabolic limitations:Industrial yeast strains engineered for glucose fermentation require genetic modification to achieve xylose assimilation rates competitive with hexose substrates.
Strategic Opportunities
- Indian pharmaceutical excipient certification:CDSCO's expanding pharmaceutical-grade additive approvals create first-mover positioning for producers achieving ICH Q3D elemental impurity compliance.
- Enzymatic hydrolysis convergence:Cellulase-xylanase cocktail technologies are reducing acid usage and improving pentose yields, enabling green chemistry claims for sustainability-marketed ingredients.
- Direct-to-biotech distribution channels:Fermentation companies are bypassing traditional ingredient distributors through long-term offtake agreements with biorefiners, capturing margin from disintermediation.
Industry Challenges
- Chromatographic purification expertise scarcity:Simulated moving bed separation engineering requires specialized talent concentrated in Swiss and German equipment vendors, constraining capacity scaling.
- Dual certification timeline compression:Simultaneous pursuit of USP-NF excipient monograph compliance and FEMA GRAS designation demands parallel regulatory dossier preparation, stretching quality assurance resources.
- Legacy syrup line retrofit costs:Food-grade xylose producers seeking pharmaceutical qualification must revalidate entire production trains, including crystallization and micronization equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Xylose Market |
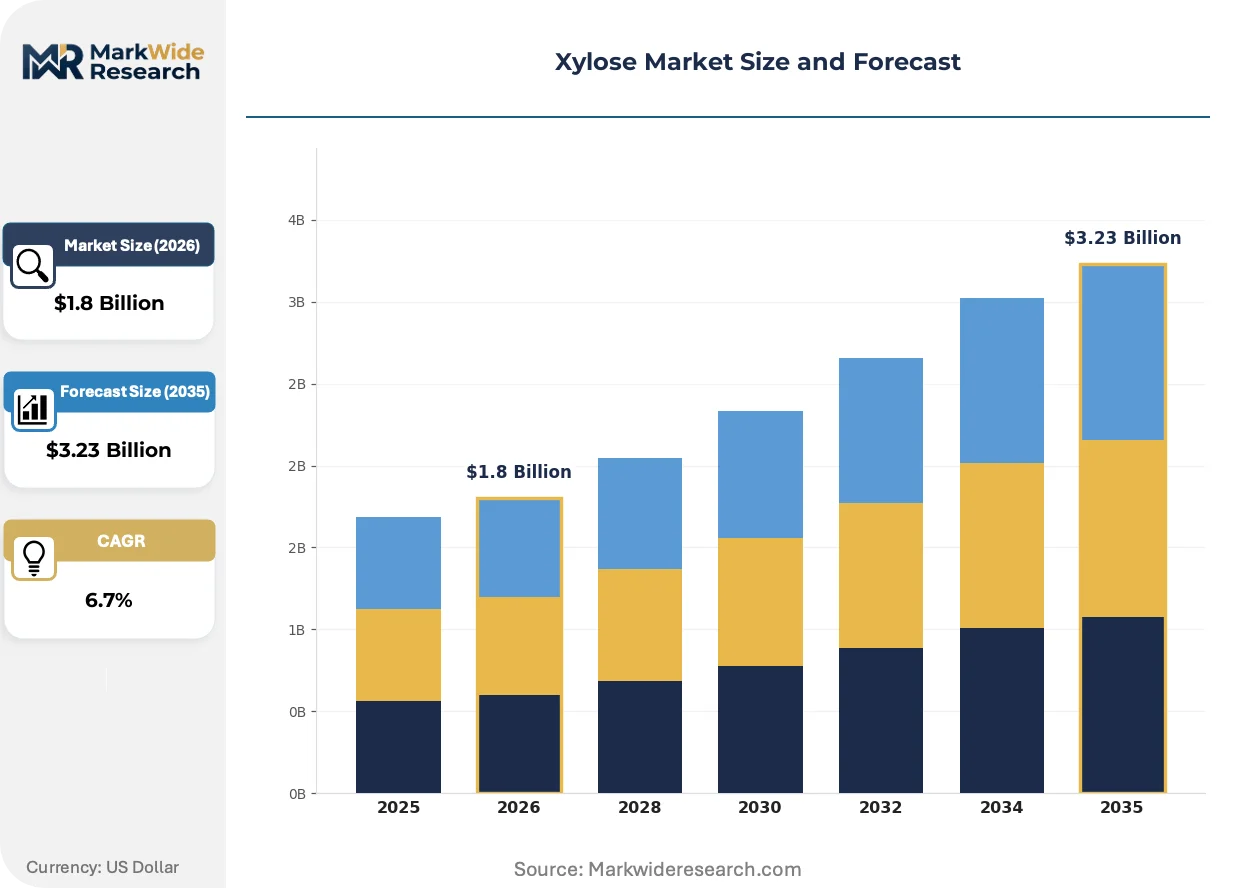
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalline Xylose, Xylose Syrup, Powdered Xylose, Liquid Xylose End User: Food & Beverage, Pharmaceuticals, Nutraceuticals, Animal Feed Application: Sweetener, Flavoring Agent, Humectant, Prebiotic Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | DuPont Danisco, Shandong Xieli Biotechnology, Futaste Group, Zhejiang Huakang Pharmaceutical, International Flavors & Fragrances Inc., Shandong Longlive Bio-Technology, Healtang Biotech, Roquette Frères, CSPC Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Xylose Market Emerging Trajectories
Continuous processing technologies and regulatory convergence around sustainability disclosure are compressing batch-cycle economics while elevating traceability requirements across the xylose value chain.
Membrane filtration systems paired with simulated moving bed chromatography are expanding into pharmaceutical-grade xylose production, replacing traditional acid hydrolysis and solvent extraction sequences. European excipient manufacturers are adopting these integrated separation trains to meet USP-NF particle size distribution specifications with reduced water and energy inputs. The technology is expanding into mid-tier biorefiners seeking to bridge the gap between food-grade syrup output and crystalline pharmaceutical certification.
REACH registration requirements for lignocellulosic derivatives are tightening substance identity and impurity profiling obligations for xylose suppliers accessing European Union markets. ECHA's evolving guidance on UVCB substance characterization demands enhanced analytical capabilities, particularly for hemicellulose-derived pentose mixtures. Pharmaceutical-grade producers are responding by investing in nuclear magnetic resonance and high-resolution mass spectrometry infrastructure to support technical dossier defense.
Biotechnology procurement teams are consolidating supplier relationships around integrated biorefiners offering xylose alongside complementary C5 and C6 sugar portfolios. This concentration pattern displaces fragmented spot-market purchasing for fermentation media formulations, particularly among contract development and manufacturing organizations in Massachusetts and North Carolina. The shift is most pronounced in precision fermentation startups scaling from pilot to commercial manufacturing volumes.
Xylose Market Segmentation
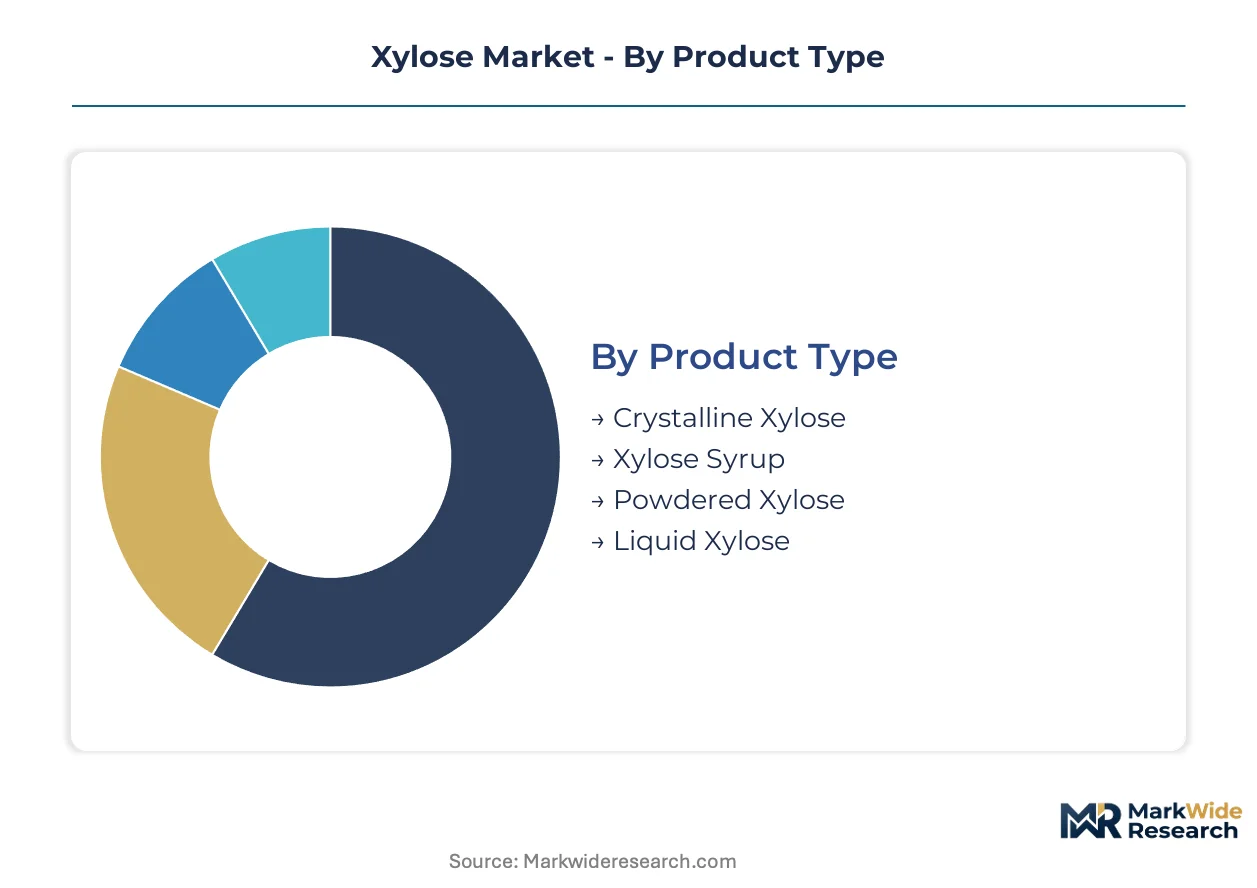
Xylose market segmentation reflects divergent capital requirements across purification technologies and end-use certification tiers. Pharmaceutical-grade specifications demand chromatographic infrastructure that food-grade syrup production avoids entirely.
Product Type:
Capital intensity separates segments sharply: crystallization trains and simulated moving bed systems require multi-million dollar investments that syrup lines circumvent.
- Crystalline Xylose:High-purity pentose sugar meeting USP-NF particle size distribution specifications through controlled nucleation and micronization. Pharmaceutical formulators in Basel and Research Triangle Park specify crystalline grades for tablet disintegration control and excipient stability.
- Xylose Syrup:Aqueous solution of reduced sugars from acid hydrolysis without chromatographic refinement. Beverage manufacturers in São Paulo and Jakarta procure syrup volumes for Maillard reaction browning in caramel formulations and cost-sensitive sweetening applications.
- Powdered Xylose:Spray-dried amorphous solid occupying intermediate purity between crystalline and syrup grades. Nutraceutical blenders in Mumbai utilize powdered xylose for synbiotic premix uniformity where crystalline precision exceeds formulation requirements.
- Liquid Xylose:Concentrated aqueous preparation for industrial fermentation feedstocks. Biorefiners in Shandong province integrate liquid xylose into cell culture media for precision fermentation of therapeutic proteins.
Xylose syrup absorbs the bulk of installed capacity; crystalline xylose is expanding most quickly.
End User:
Margin structure varies dramatically: pharmaceutical certification commands 3-4x price multiples over commodity food applications.
- Food & Beverage:Caramel coloring, low-glycemic sweetening, and Maillard browning in baked goods and beverages. Japanese and German manufacturers lead functional food incorporation.
- Pharmaceuticals:Excipient applications demanding ICH Q3D elemental impurity compliance and USP-NF monograph adherence. FDA and EMA inspections determine supplier eligibility for tablet and capsule formulations.
- Nutraceuticals:Prebiotic positioning in gut microbiome modulation products. Synbiotic developers in Copenhagen and Seoul formulate xylose into fiber blends targeting digestive health claims.
- Animal Feed:Fermentation substrate for probiotic livestock supplements. Brazilian and Vietnamese feed compounders utilize xylose as prebiotic additive in poultry and aquaculture nutrition.
Food and beverage channels dominate volume throughput; pharmaceutical qualification is climbing the fastest.
Application:
Functional performance dictates procurement specifications: sweetness intensity, hygroscopicity, and microbial selectivity create distinct technical requirements.
- Sweetener:Low-glycemic alternative to sucrose and high-fructose corn syrup in diabetic-friendly formulations. Metabolic pathway differences reduce insulin response compared to hexose sugars.
- Flavoring Agent:Maillard reaction precursor generating meaty and caramel notes upon thermal processing. Reaction kinetics with amino acids produce distinct volatile profiles versus glucose or fructose substrates.
- Humectant:Moisture retention in baked goods and confectionery through hygroscopic pentose chemistry. Water activity control extends shelf stability without synthetic additives.
- Prebiotic:Selective fermentation substrate for Bifidobacterium and Lactobacillus species in colon microbiome modulation. Clinical studies in Japanese populations demonstrate xylose-fermenting bacterial enrichment.
Sweetener applications anchor current demand; prebiotic positioning is gaining share fastest.
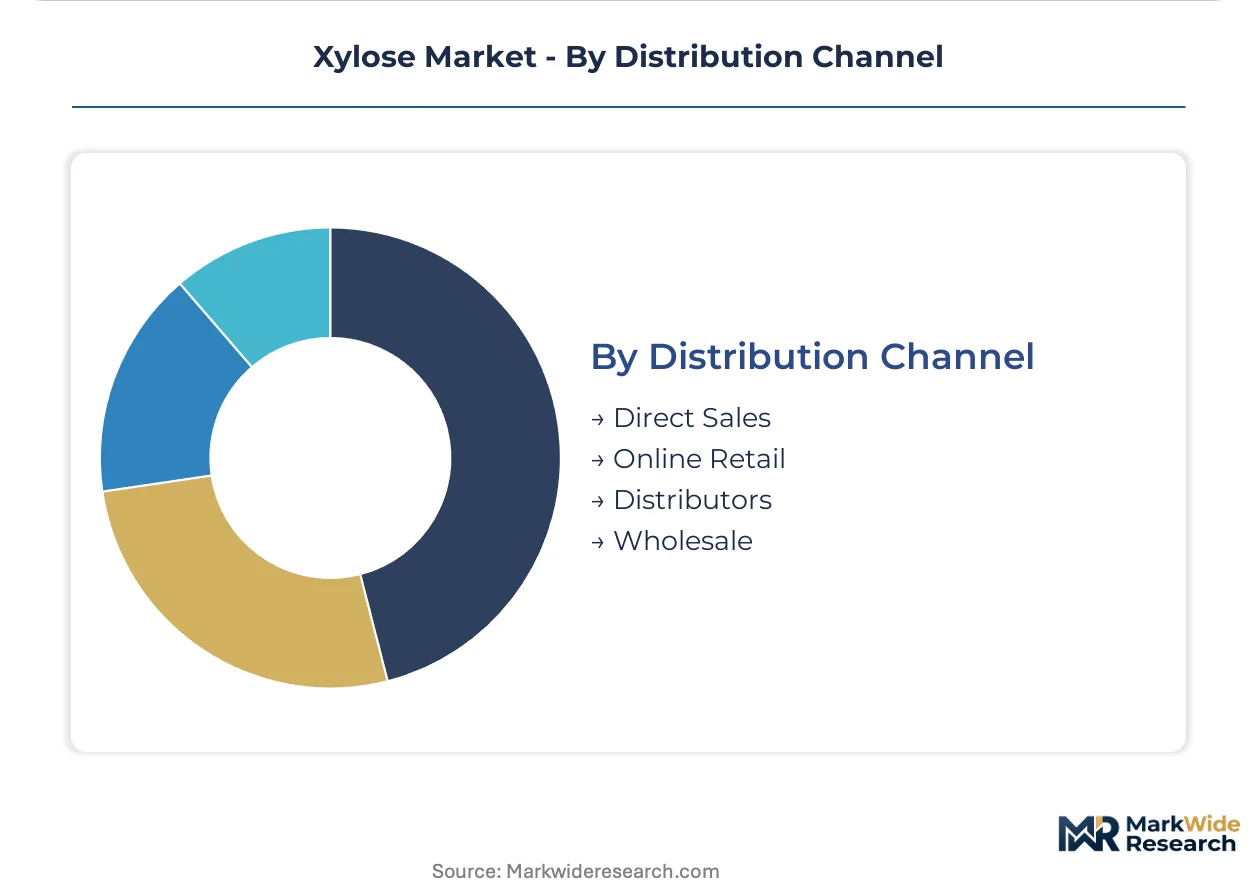
Distribution Channel:
Channel selection reflects customer scale and technical service requirements: bulk fermentation users bypass intermediaries while small formulators rely on distributor technical support.
- Direct Sales:Long-term offtake agreements between integrated biorefiners and pharmaceutical or fermentation customers. Massachusetts and North Carolina biotech clusters negotiate direct supply for multi-ton annual volumes.
- Online Retail:E-commerce platforms serving small-scale nutraceutical formulators and research institutions. Alibaba and specialty chemical marketplaces facilitate sample procurement and kilogram-scale orders.
- Distributors:Regional chemical and ingredient distributors providing technical documentation and lot traceability. Brenntag and Univar Solutions maintain xylose inventories for European and North American compounders.
- Wholesale:Commodity traders aggregating food-grade syrup volumes for beverage and baking manufacturers. Spot market liquidity concentrates in Rotterdam and Singapore trading hubs.
Direct sales capture the majority of pharmaceutical-grade volume; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province anchors xylose production capacity through integrated corn cob processing corridors linking Dezhou and Jinan industrial zones. Regional demand patterns diverge sharply between pharmaceutical-grade crystalline requirements in Basel and Research Triangle Park versus food-grade syrup procurement concentrated in São Paulo and Jakarta.
China
Domestic biorefinery expansion in Shandong and Hebei provinces is absorbing regional corn cob supply chains for crystalline xylose export qualification. NMPA and GB standards enforce purity thresholds that determine European and North American market access for producers. Dezhou industrial clusters are scaling chromatographic separation capacity to meet pharmaceutical-grade certification timelines.
United States
Precision fermentation startups in Massachusetts and North Carolina are consolidating direct procurement relationships with integrated biorefiners for C5 sugar substrates. FDA food additive regulations and USP-NF excipient monographs shape market entry requirements for new xylose suppliers. Research Triangle Park biotech clusters are specifying crystalline grades for therapeutic protein production to reduce glycation byproducts.
Germany
Nutraceutical formulators in Hamburg and Frankfurt are incorporating xylose into synbiotic blends targeting gut microbiome modulation claims. REACH registration requirements and EU Green Deal biomass mandates tighten lignocellulosic feedstock sourcing standards for sugar-derived ingredients. Basel-adjacent pharmaceutical excipient distributors are prioritizing European-manufactured crystalline grades to reduce supply chain documentation burden.
Brazil
Beverage manufacturers in São Paulo procure xylose syrup volumes for Maillard reaction browning in caramel formulations and cost-sensitive sweetening applications. ANVISA regulatory frameworks for food additives determine import eligibility for Asian-produced syrup grades. Southeast industrial corridors are developing sugarcane bagasse supply chains to localize pentose sugar extraction capacity.
India
Nutraceutical blenders in Mumbai utilize powdered xylose for synbiotic premix uniformity where crystalline precision exceeds formulation requirements. CDSCO's expanding pharmaceutical-grade additive approvals create first-mover positioning for producers achieving ICH Q3D elemental impurity compliance. Maharashtra chemical distributors are building technical documentation capabilities to support import substitution for Chinese crystalline grades.
Xylose Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the xylose value chain. Integrated biorefiners with captive corn cob supply chains and chromatographic purification infrastructure dominate crystalline pharmaceutical-grade supply. Asset-light toll processors and contract manufacturers occupy food-grade syrup segments with lower barrier-to-entry economics. Three strategic archetypes define competitive positioning: backward-integrated agricultural processors, fermentation technology licensors, and pharmaceutical-grade certification specialists. Dominant competitive moves include capacity expansion in Shandong province biorefinery clusters and strategic partnerships between European distributors and Asian manufacturers for REACH-compliant supply assurance.
Among China-based agricultural processors, Shandong Xieli Biotechnology and Futaste Group exemplify backward-integrated archetypes with corn cob-to-crystalline processing capabilities. DuPont Danisco occupies a technology-licensor position in North American supply through fermentation substrate expertise. Roquette Frères represents the European pharmaceutical-grade certification specialist archetype with distribution density across continental excipient channels. These three company patterns illustrate how geographic feedstock access, regulatory compliance depth, and end-use technical service requirements segment competitive positioning across the value chain.
| Leading Market Players |
|---|
| DuPont Danisco |
| Shandong Xieli Biotechnology |
| Futaste Group |
| Zhejiang Huakang Pharmaceutical |
| International Flavors & Fragrances Inc. |
| Shandong Longlive Bio-Technology |
| Healtang Biotech |
| Roquette Frères |
| CSPC Pharmaceutical |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade crystalline certification against food-grade syrup commodity pricing creates a bifurcated value architecture that concentrates margin capture among chromatography-equipped biorefiners while relegating acid-hydrolysis-only operators to spot-market volatility. This divergence manifests in supply chain configurations where REACH-registered European distributors command premium positioning for USP-NF monograph-compliant material, whereas Southeast Asian beverage compounders source syrup through Rotterdam commodity traders.
Pricing Analysis
Margin tightening in crystalline pharmaceutical grades reflects chromatographic purification energy costs and specialized equipment depreciation, while food-grade syrup segments face cost-down pressure from corn cob feedstock competition in Shandong province. Three-tier pricing structure across pharmaceutical crystalline, nutraceutical powdered, and beverage syrup levels separates buyers by certification burden and particle specification. Pharmaceutical formulators in Basel and Research Triangle Park exhibit lowest price sensitivity due to excipient qualification switching costs, whereas São Paulo caramel manufacturers prioritize unit economics over purity documentation.
Supply Chain Analysis
REACH registration and USP-NF monograph compliance requirements gate European and North American market access, concentrating qualified supply among Shandong and Hebei province biorefiners with NMPA-certified export protocols. Corn cob supply chains draw from North China plains and US Midwest grain belts, while chromatographic separation equipment sources from Swiss and German vendors. Single-source vulnerability in simulated moving bed engineering talent creates bottleneck risk for capacity scaling. Distribution runs through direct offtake agreements for pharmaceutical volumes and commodity traders for food-grade syrup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chromatographic purification capacity scarcity props pricing power for qualified producers, creating durable margin structures for incumbents with NMPA and REACH-registered infrastructure.
For Market Incumbents: Anchor market position through backward integration into captive corn cob supply chains in Hebei and Shandong provinces, insulating against feedstock competition from non-integrated refiners. Invest in simultaneous USP-NF and ICH Q3D certification to preempt CDSCO pharmaceutical-grade approvals in India. Defend against enzymatic hydrolysis disruptors by locking long-term offtake agreements with Massachusetts and North Carolina precision fermentation clusters. For New Entrants and Emerging Players: Begin with toll-processing partnerships for pharmaceutical-grade crystalline output, avoiding capital-heavy chromatography infrastructure while building technical dossier capabilities. Target Indian nutraceutical blenders in Mumbai with powdered xylose premix uniformity solutions where crystalline precision exceeds formulation requirements. Pursue CDSCO pharmaceutical-grade additive approvals as first-mover positioning before Chinese incumbents achieve ICH Q3D elemental impurity compliance. For Investors and Strategic Acquirers: Re-rating potential sits with integrated biorefiners possessing simultaneous NMPA export certification and REACH substance identity dossiers given tightening ECHA UVCB characterization guidance. Long-term viability centers on producers with enzymatic hydrolysis technology convergence enabling green chemistry claims for sustainability-marketed ingredients. Watch for inflection in direct-to-biotech distribution channel expansion as fermentation companies bypass traditional ingredient distributors through long-term offtake agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Chromatographic Capacity Expansion | Simulated moving bed installation in Dezhou industrial clusters meets pharmaceutical-grade USP-NF particle specifications. |
| Enzymatic Hydrolysis Technology Licensing | Cellulase-xylanase cocktail adoption reduces sulfuric acid usage and improves pentose yields for ESG-marketed ingredients. |
| REACH Registration Dossier Investment | ECHA UVCB substance characterization compliance secures European Union market access for lignocellulosic derivatives. |
| Direct-to-Biotech Distribution Partnership | Long-term offtake agreements with Massachusetts and North Carolina fermentation clusters capture margin from disintermediation. |
| CDSCO Pharmaceutical-Grade Certification | ICH Q3D elemental impurity compliance creates first-mover positioning in Indian excipient additive approvals. |
Methodological Framework
Multi-period observation of NMPA export certification timelines, REACH registration dossier submissions, and chromatographic capacity installations anchored the trend analysis, supplemented by interviews with plant managers at Shandong biorefiners, procurement leads at Basel pharmaceutical formulators, and technical R&D directors at European excipient distributors. Secondary validation drew from ECHA substance registration databases, USP-NF monograph revision notices, customs trade data for pentose sugar imports, and SEC filings of listed agricultural processors. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for lignocellulosic biomass utilization.
Input-output matrices modeled capacity utilization rates, feedstock conversion yields, and certification timeline lags across pharmaceutical crystalline, nutraceutical powdered, food-grade syrup, and liquid fermentation substrate segments. CAGRs were derived from regression analysis of historical price-volume relationships and projected capacity expansion schedules. Industry-specific forecast inputs included natural gas price volatility for acid hydrolysis energy costs and CDSCO approval pipeline velocity for Indian market penetration.
Underlying measurement precision varies by segment; pharmaceutical-grade crystalline volumes carry tighter precision than commodity syrup spot-market estimates due to documented offtake agreement transparency. Forecasts reflect assumptions on regulatory timeline continuity and feedstock supply chain stability. A model refresh is warranted upon material change in EU Green Deal biomass mandate enforcement or NMPA export certification protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Dextrates Market
Sweeteners
Natural Stevia Market
Sweeteners
Europe Stevia Market
Sweeteners
Raw Beetroot Sugar Market
Sweeteners
North America Food Sweetener Market
Sweeteners
Rice Syrup Market
Sweeteners
Global Alternative Sweeteners Market
Sweeteners
Food Sweetener Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
Refined Cane Sugar Market
Sweeteners
Dry Sweeteners Market
Sweeteners
Galactose Market
Sweeteners
Gluten-Free Sugar Syrup Market
Sweeteners
China Saccharin Market
Sweeteners
Xylitol Injection Market
Sweeteners
Digestion Resistant Maltodextrin Market