
 White Sugar Market | 2026-2036
White Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
White Sugar Market Intelligence
Premium-grade refined sugar specification is collapsing the gap between commodity white sugar and pharmaceutical-grade sucrose. Südzucker AG leverages its beet processing network across Central Europe to sustain supply consistency for industrial buyers. Tereos competes through integrated ethanol-sugar flexibility at its Brazilian and European mills. Mitr Phol Sugar Corporation anchors Southeast Asian supply chains with crushing capacity concentrated in Thailand's central plains.
White sugar denotes crystalline sucrose refined to at least 99.85 percent purity, produced through affination, carbonatation, and crystallization of either sugarcane or sugar beet extract; its primary commercial purpose is to deliver standardized sweetness, bulk, and preservation functionality across formulated foods and beverages. Granulated sugar occupies the largest volume share as the default input for industrial food processing, while liquid sugar captures expanding demand from beverage manufacturers seeking reduced handling and faster dissolution. Powdered sugar differentiates within confectionery and bakery segments where particle size directly determines texture and coating performance.
The FDA enforces identity standards for refined sugar under 21 CFR 184.1854, while the EU Green Deal and F-Gas Regulation indirectly reshape beet sugar economics through energy and input cost pressures on European processors. India's FSSAI mandates specific sucrose thresholds and packaging disclosures that filter market access for imported refined product. Stakeholders must monitor how carbon border adjustments and evolving biofuel mandates redirect cane crush allocation between crystal sugar and ethanol in major producing zones.
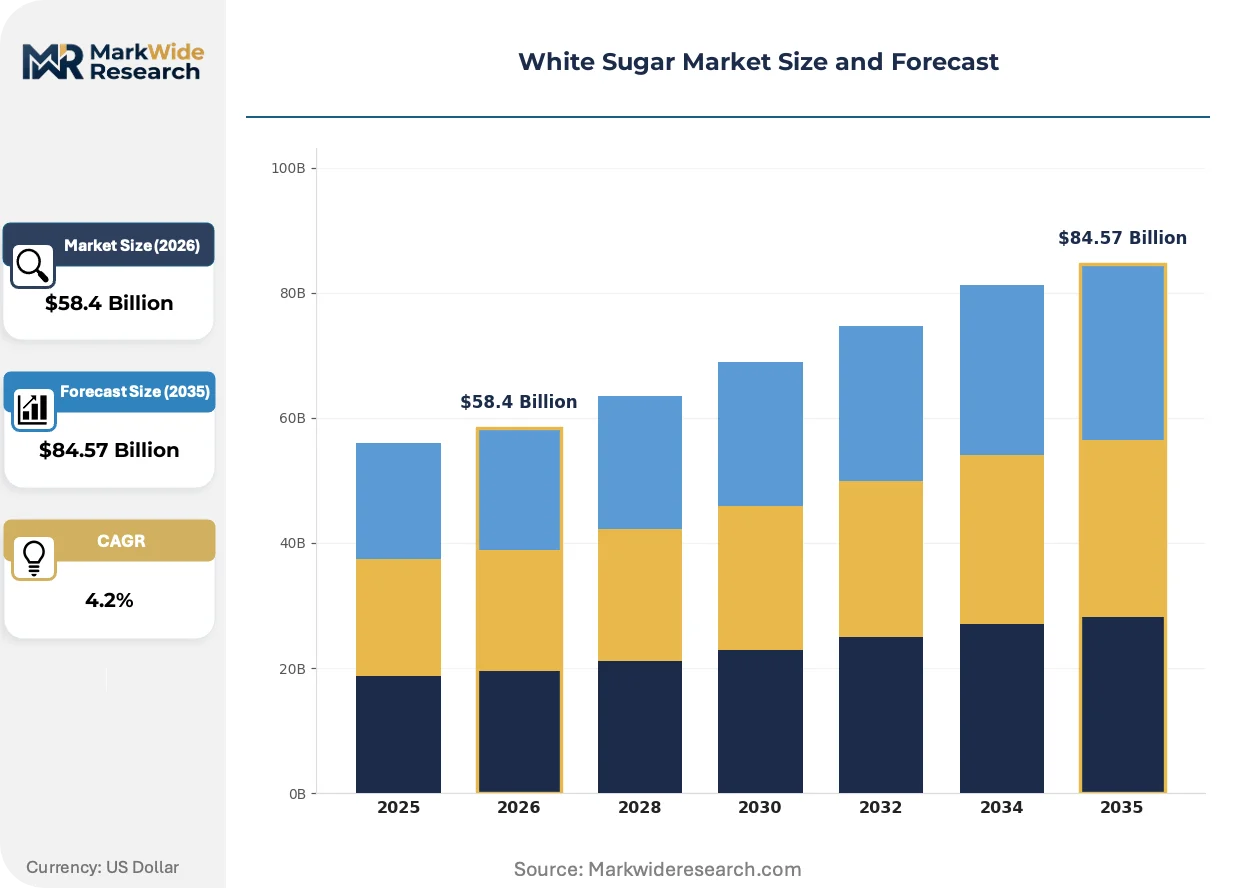
Market Dynamics
Brazilian millers are redirecting cane crush toward crystal sugar production as biofuel economics fluctuate, while beverage manufacturers accelerate clean-label procurement, tightening purity specifications across supply chains.
Growth Catalysts
- Beverage Clean-Label Formulations:Soft drink and ready-to-drink tea bottlers are eliminating artificial sweeteners, pulling pharmaceutical-grade sucrose specifications into commodity procurement.
- FSSAI Purity Benchmarks:India's tightened retail sugar standards are filtering import quality, forcing upgrades at origin mills serving South Asian markets.
- Carbonatation Process Refinement:Advanced liming and filtration systems are reducing color carryover, enabling single-crystal production runs that formerly required double refining.
Market Restraints
- Ethanol Crush Competition:Brazilian Center-South millers maintain swing capacity between crystal sugar and hydrous ethanol, injecting volume volatility when oil prices shift.
- Energy Input Cost Surge:European beet processors face compressed margins from natural gas and electricity pricing under EU Green Deal implementation.
- Beet Supply Geographic Concentration:Frost and drought vulnerability in France, Germany, and Poland concentrates origination risk for Q1-Q2 processing campaigns.
Strategic Opportunities
- Liquid Sugar Distribution Innovation:Bulk tanker delivery systems are displacing 50-pound bags at mid-sized bakeries and dairy processors, capturing handling efficiency premiums.
- Pharmaceutical-Grade Convergence:Premium refined specifications are collapsing quality tiers, opening USP-grade contract manufacturing for excipient and oral dosage form suppliers.
- Thai Export Infrastructure Expansion:Mitr Phol and associated processors are deepening silo and bulk terminal capacity at Laem Chabang, shortening Southeast Asian lead times.
Industry Challenges
- Crystallization Technician Scarcity:Affination and pan boiling expertise is aging out across European and Brazilian operations, degrading recovery rates at legacy facilities.
- Carbon Border Adjustment Compliance:EU importers face documentation complexity tracing embedded emissions in cane sugar originating from non-EU suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Sugar Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $84.57 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated Sugar, Powdered Sugar, Liquid Sugar, Brown Sugar Application: Beverages, Bakery, Confectionery, Food Processing Customer Type: Retail, Wholesale, Food Service, Industry Distribution Channel: Online, Supermarkets, Grocery Stores, Convenience Stores |
| Companies Covered | Südzucker AG, Tereos, Cosan, Mitr Phol Sugar Corporation, Associated British Foods, Nordzucker AG, Wilmar International, Raizen, Louis Dreyfus Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Sugar Market Strategic Shifts & Innovations
Processing technology and regulatory frameworks are compressing traditional quality tiers while procurement models favor just-in-time liquid delivery over bagged inventory.
Membrane filtration systems are replacing conventional carbonatation in greenfield beet installations, cutting lime consumption and waste volumes. Nordic and Baltic processors are piloting these configurations to meet EU F-Gas Regulation discharge limits. The technology is miniaturizing footprint requirements, enabling retrofits at constrained urban refinery sites previously deemed infeasible.
REACH and EU Green Deal carbon intensity disclosures are forcing beet cooperatives to document cultivation inputs and processing energy sources. French and German processors are consolidating campaigns to maximize thermal efficiency. Industrial buyers in confectionery and dairy are now requiring Scope 3 emissions attestations, shifting contract allocation toward verified lower-carbon origins.
Beverage manufacturers are unbundling sugar procurement from flavor house contracts, establishing direct mill relationships for liquid sucrose. This disintermediation concentrates volume with crush-flexible suppliers capable of year-round tanker scheduling. The pattern is most pronounced in North American carbonated soft drink bottling, where regional co-packers are bypassing traditional ingredient distributors.
White Sugar Market Segmentation
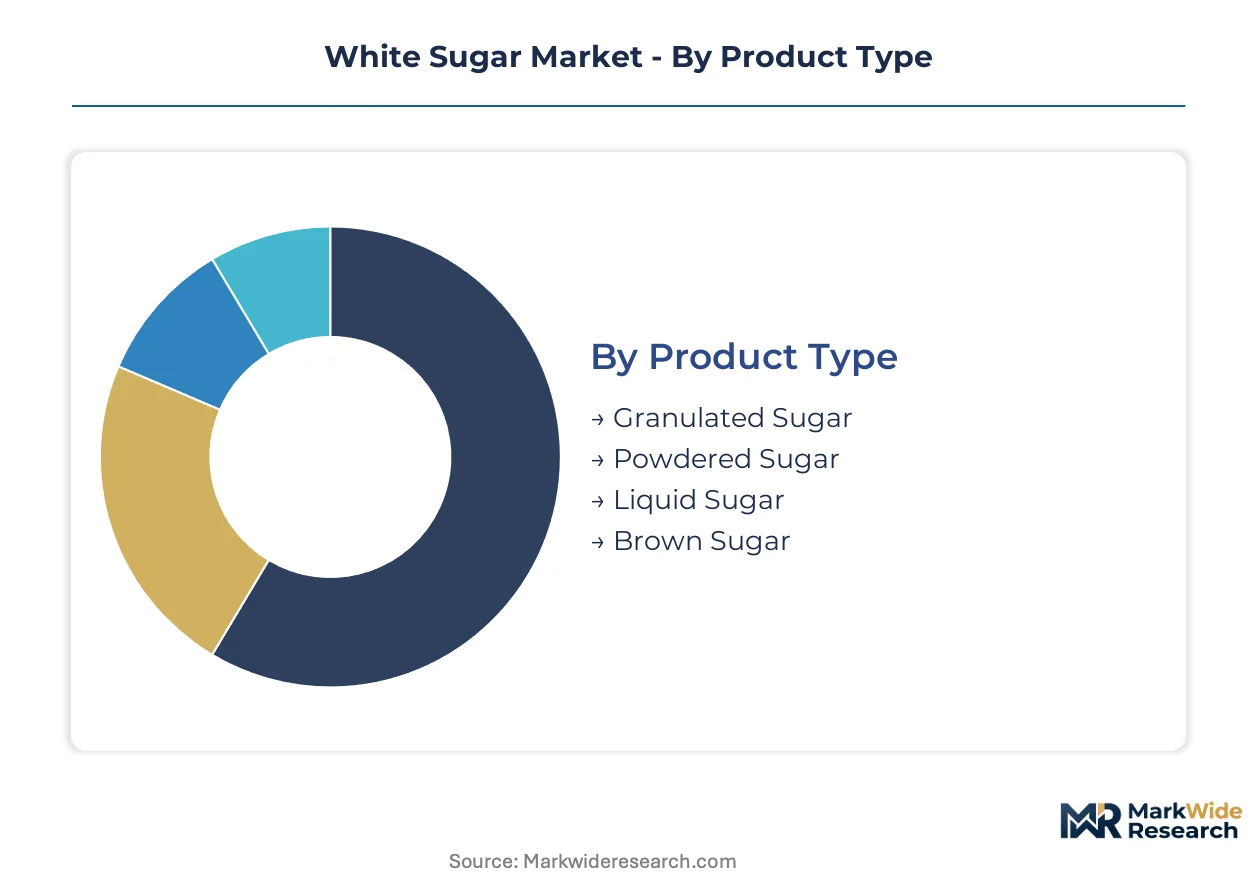
White sugar flows through distinct procurement channels shaped by handling requirements, purity specifications, and volume scale. Each segment category reveals how crystalline sucrose reaches end-users through differentiated logistics and contract structures.
Product Type:
Channel mix varies sharply by physical form—bulk liquid moves through dedicated tanker fleets while bagged granulated products distribute through wholesale grocery networks.
- Granulated Sugar:Crystalline sucrose with standardized 99.85 percent purity serves as the default input for industrial food processing across bakeries and dairy operations. Demand concentrates in Brazil's Center-South cane belt where millers redirect crush toward crystal production when biofuel economics weaken.
- Liquid Sugar:Dissolved sucrose solution delivered in bulk tankers eliminates bag handling and accelerates dissolution for beverage manufacturers. North American carbonated soft drink bottlers are disintermediating flavor houses to establish direct mill relationships for year-round tanker scheduling.
- Powdered Sugar:Finely milled sucrose with anti-caking agents targets confectionery coating and bakery dusting applications where particle size determines texture performance.
- Brown Sugar:Molasses-infused sucrose crystals retain residual cane syrup for specialty baking and ethnic cuisine segments requiring moisture retention and caramel notes.
Granulated sugar dominates installed base. Liquid sugar is where expansion concentrates.
Application:
Cost tier stratification separates commodity-grade procurement for mass-market beverages from premium specifications in pharmaceutical-adjacent confectionery.
- Beverages:Clean-label formulations are eliminating artificial sweeteners and pulling pharmaceutical-grade sucrose specifications into commodity procurement channels. Soft drink and ready-to-drink tea bottlers now mandate tighter purity thresholds than traditional food processing.
- Bakery:Yeast-raised and chemically leavened products require standardized granulated input for consistent fermentation control and crumb structure. Mid-sized operations are converting to bulk liquid delivery to displace 50-pound bag handling.
- Confectionery:Hard candy, fondant, and chocolate applications demand precise crystal size distribution and low invert sugar content to prevent graininess and bloom defects.
- Food Processing:Canned fruit, condiment, and sauce manufacturers prioritize thermal stability and preservative functionality in high-acid formulations.
Beverage applications command premium contract values. Bakery represents the deepest volume pool.
Customer Type:
Volume concentration tilts toward industrial buyers capable of absorbing full tanker loads and multi-year supply agreements.
- Retail:Packaged consumer sugar sold through supermarkets and grocery channels faces tightening purity benchmarks from India's FSSAI for refined product entering domestic distribution.
- Wholesale:Intermediate distributors aggregate smaller industrial orders but are losing share as beverage manufacturers establish direct mill relationships for liquid sucrose.
- Food Service:Restaurants, hotels, and institutional kitchens rely on 25-50 pound bag formats with limited storage infrastructure for bulk liquid conversion.
- Industry:Large-scale food and beverage manufacturers negotiate crush-flexible supply contracts with Brazilian and Thai millers capable of year-round tanker scheduling.
Industrial customers anchor contract volume. Food service is converting slowest to liquid formats.
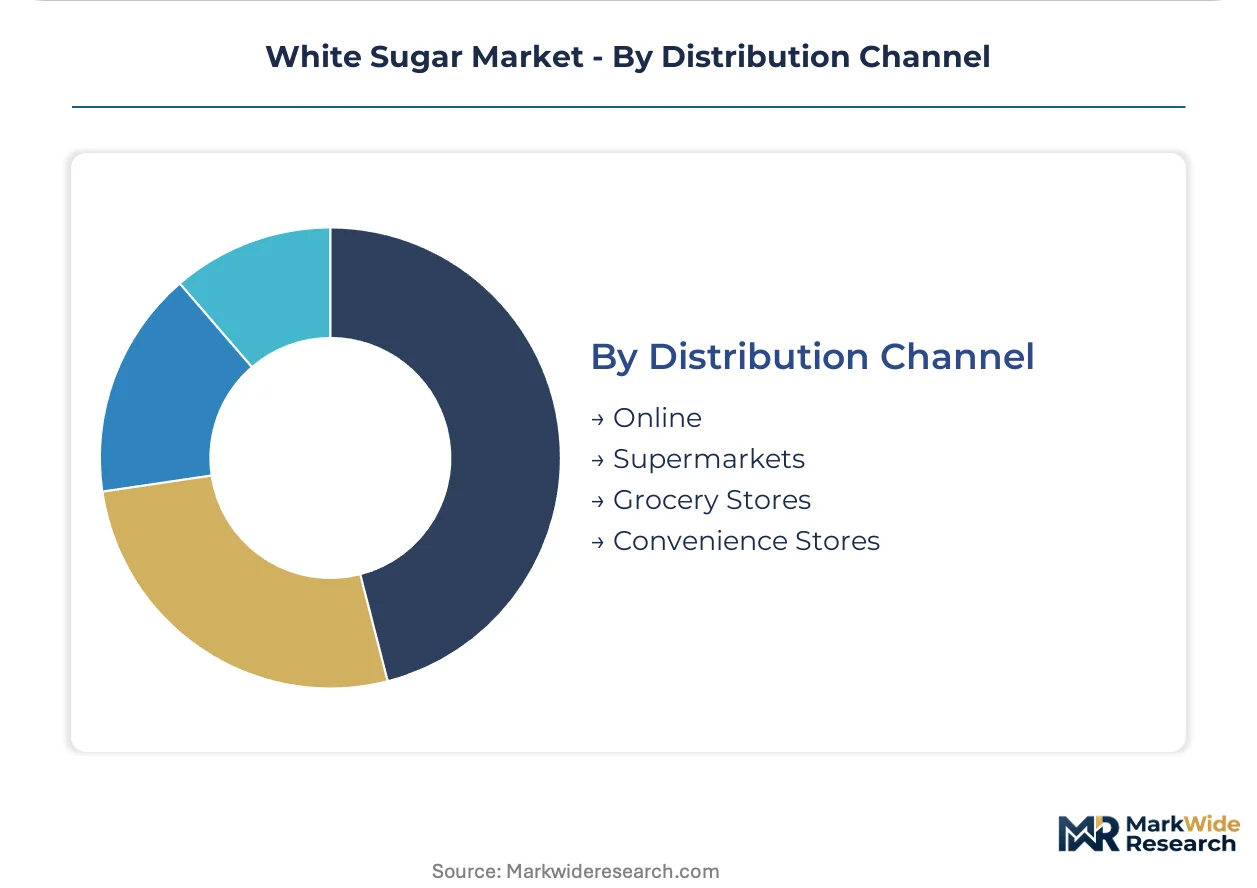
Distribution Channel:
Geographic reach determines channel viability—bulk liquid requires proximity to crush facilities while packaged sugar tolerates extended supply chains.
- Online:E-commerce platforms capture specialty and organic sugar variants for home bakers and small confectionery operations with limited distributor access.
- Supermarkets:Multi-format retailers dominate retail sugar velocity through private label and branded packaged offerings in 2-5 pound formats.
- Grocery Stores:Neighborhood and ethnic grocers stock brown sugar and specialty cane products serving demographic-specific demand clusters.
- Convenience Stores:Grab-and-go locations carry limited impulse-format sugar for emergency replenishment with minimal shelf space allocation.
Supermarkets dominate retail throughput. Online is climbing fastest in specialty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Center-South cane belt dominates crush volumes, yet processing economics oscillate between crystal sugar and hydrous ethanol output. Thai millers anchor Southeast Asian supply chains through expanded bulk terminal infrastructure. European beet processors confront energy cost compression under EU Green Deal implementation.
Brazil
Center-South millers redirect crush toward crystal sugar when biofuel margins weaken, sustaining the world's largest exportable surplus. ANVISA purity protocols filter import eligibility for pharmaceutical-adjacent applications. São Paulo state clusters crush-flexible operations capable of swing allocation between ethanol and crystalline sucrose.
India
FSSAI tightened retail purity benchmarks force origin mill upgrades for South Asian market access. The regulator mandates specific sucrose thresholds and packaging disclosures that constrain imported refined product entry. Uttar Pradesh and Maharashtra processing belts concentrate domestic beet and cane crush capacity.
Thailand
Mitr Phol anchors Southeast Asian supply chains through crushing concentration in the central plains. The Board of Investment incentivizes silo and bulk terminal expansion at Laem Chabang port. Chonburi Province hosts deepening storage infrastructure shortening regional lead times.
Germany
Nordzucker and Südzucker leverage beet processing networks across Central Europe under REACH carbon intensity disclosure requirements. The EU F-Gas Regulation and Green Deal compress thermal efficiency margins during Q1-Q2 campaigns. Lower Saxony and Bavaria concentrate cooperative processing infrastructure.
United States
FDA identity standards under 21 CFR 184.1854 enforce refined sugar specifications for beverage and food processing inputs. Carbonated soft drink bottlers disintermediate flavor houses for direct mill relationships on liquid sucrose. Florida and Louisiana cane belts plus Upper Midwest beet districts supply coastal refining clusters.
White Sugar Market Key Industry Players
Concentration sits with integrated agro-industrial conglomerates capable of crush-flexible allocation between crystal sugar and ethanol. Three to five European and Asian entities command contract volume through owned beet networks or Brazilian milling stakes. Strategic archetypes separate: integrated crush-flexible operators, beet-specialized cooperatives, and Asian trading houses with origination control. Competitive moves cluster on ethanol-sugar swing capacity investments and direct-to-bottler liquid distribution bypassing traditional wholesale tiers.
Within the integrated crush-flexible tier, Südzucker AG exemplifies beet network consolidation across Central Europe. Tereos occupies a position spanning Brazilian cane and European beet processing with ethanol-sugar flexibility. Mitr Phol Sugar Corporation anchors Southeast Asian supply chains through Thai central plains concentration and Laem Chabang terminal expansion. These three represent divergent geographic and feedstock archetypes: Central European beet dominance, transatlantic cane-beet integration, and Southeast Asian cane export specialization.
| Leading Market Players |
|---|
| Südzucker AG |
| Tereos |
| Cosan |
| Mitr Phol Sugar Corporation |
| Associated British Foods |
| Nordzucker AG |
| Wilmar International |
| Raizen |
| Louis Dreyfus Company |
| Others |
Cost & Logistics Intelligence
Crush-flexible mill capacity in Brazil's Center-South creates scale economies that simultaneously concentrate supply origination and compress price floors for exportable refined sugar. This dual dynamic forces buyers into long-term offtake contracts to secure volume access while millers arbitrage between crystal sugar and ethanol margins.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across European beet processing, separating certified low-carbon product from standard-grade refined sugar. Three-tier pricing structure across premium, standard, and economy levels reflects carbon intensity disclosure compliance, volume scale commitments, and geographic proximity to crush facilities. Pricing pressure stems from natural gas cost volatility under EU Green Deal implementation, degrading processor margins during Q1-Q2 campaigns. Mid-sized industrial buyers exhibit highest price sensitivity due to limited storage infrastructure and inability to absorb full tanker loads.
Supply Chain Analysis
Brazil and Thailand anchor global refined sugar export supply, with India's domestic processing belt serving as a swing origination point for regional South Asian markets. Raw cane supply draws from Center-South Brazilian cooperatives, Thailand's central plains crushing networks, and Uttar Pradesh-Maharashtra processing clusters. Single-source vulnerability concentrates in maritime chokepoints connecting Laem Chabang and Santos terminals to Asian and European destination markets. Distribution runs through bulk liquid tanker fleets for beverage manufacturers and 50-pound bag networks for bakery and food service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aging crystallization technician expertise is constraining recovery rates at legacy facilities across European and Brazilian operations, creating a capability bottleneck that favors operators with formalized knowledge-transfer programs and apprenticeship pipelines.
For Market Incumbents: Secure affination and pan boiling expertise through structured apprenticeship partnerships with technical institutes in São Paulo and Lower Saxony processing regions. Invest in membrane filtration retrofits at constrained urban refinery sites to meet EU F-Gas Regulation discharge limits while maintaining thermal efficiency during compressed Q1-Q2 campaigns.
For New Entrants and Emerging Players: Lead with liquid sugar distribution innovation targeting mid-sized North American bakeries and dairy processors currently dependent on 50-pound bag handling. Capture handling efficiency premiums through bulk tanker delivery systems that displace traditional wholesale grocery networks and establish direct mill relationships outside flavor house intermediation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors crush-flexible operators with integrated ethanol-sugar swing capacity and documented Scope 3 emissions attestations. Long-term viability centers on Brazilian and Thai assets capable of redirecting cane crush between crystal sugar and hydrous ethanol as oil prices fluctuate. Watch biofuel mandate revisions in major producing zones as inflection indicators for allocation shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofit | EU F-Gas Regulation compliance enables urban refinery site viability without lime waste expansion. |
| Liquid Sugar Tanker Distribution | Beverage manufacturer direct procurement disintermediates flavor house contracts and shortens lead times. |
| Carbon Intensity Certification | REACH disclosure requirements filter contract allocation toward verified lower-carbon beet origins. |
| Crush-Flexible Capacity Investment | Swing allocation between crystal sugar and ethanol hedges margin volatility under ANVISA purity protocols. |
| Laem Chabang Terminal Expansion | Thai Board of Investment incentives deepen Southeast Asian silo infrastructure for regional supply anchoring. |
Research Approach
Cross-validation between regulatory filing analysis and trade flow databases anchors the qualitative findings on crush allocation patterns and purity specification enforcement. Primary interviews with sugar mill operations directors, beverage procurement leads, and EU cooperative technical managers combined with secondary validation from FDA 21 CFR 184.1854 filings, FSSAI packaging disclosure mandates, and ANVISA import eligibility records. Bottom-up crushing capacity estimates and top-down export volume triangulation reconcile origination data across Brazilian, Thai, and Indian processing belts.
Sensitivity analysis on biofuel margin thresholds and natural gas pricing volatility tests forecast robustness across the projection horizon. Segmentation dimensions modeled include physical form (granulated, liquid, powdered), end-use application (beverage, bakery, confectionery, pharmaceutical-adjacent), customer type (industrial, retail, food service), and regional regulatory cluster (EU Green Deal, FSSAI retail benchmarks, FDA identity standards). CAGRs derive from installed capacity utilization rates and crush-flexible allocation elasticity to ethanol parity pricing.
The analysis sits within stated boundaries; outcomes outside sustained biofuel mandate stability and maritime logistics continuity would require recalibration. Forecasts reflect assumptions on cane yield recovery, beet cooperative campaign consolidation, and carbon border adjustment implementation scope. Recalibration cycles align with material shifts in EU F-Gas Regulation enforcement, Indian FSSAI purity benchmark revisions, and Brazilian Center-South ethanol-sugar arbitrage economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Short-Chain Fructooligosaccharides (Scfos) Market
Sweeteners
Spain Food Sweetener Market
Sweeteners
Global Brown Sugar Market
Sweeteners
Naturally Derived Sweeteners Market
Sweeteners
Middle East and Africa Food Sweetener Market
Sweeteners
Dry Molasses Market
Sweeteners
Aspartame Market
Sweeteners
Sugar Market
Sweeteners
Gluten-Free Sugar Syrup Market
Sweeteners
North America Starch Sweetener Market
Sweeteners
Low-Fat Sugar Market
Sweeteners
Mexico Food Sweetener Market
Sweeteners
China Allulose Market
Sweeteners
France Food Sweetener Market
Sweeteners
North America High-Intensity Sweeteners Market
Sweeteners
Middle East and Africa Sugar Substitutes Market