
 Processed Cashew Market | 2026-2036
Processed Cashew Market Size, Share, and Industry Trends Forecast 2026-2036
Processed Cashew Market Analytics
W320-grade kernel specification is bifurcating the processed cashew trade into premium and commodity tiers. Olam Food Ingredients leverages integrated sourcing networks across West Africa and Vietnam to secure raw nut supply. CBL Natural Foods specializes in organic and fair-trade certified kernels for European retail channels. Haldiram's dominates India's domestic branded snack segment with roasted and flavored product lines.
Processed cashews denote shelled, dried, and graded Anacardium occidentale kernels sorted by kernel count per pound, with W320 and W240 grades commanding distinct price bands based on whiteness, moisture content below 5%, and absence of aflatoxin contamination. These kernels serve as ingredients in confectionery, bakery, and ready-to-eat snack applications where fat content near 47% and protein near 21% deliver functional nutrition. Roasted cashews and flavored cashews lead retail value generation, while cashew butter represents the fastest-growing product type in North American natural food channels. Bulk containers anchor food industry procurement, though jars and branded bags capture higher per-unit margins in supermarket and specialty store distribution.
The EU's EFSA aflatoxin maximum limits and REACH chemical safety protocols shape import testing protocols for Asian and African exporters. India's FSSAI mandates hygiene certification for domestic processors, while the USDA and FDA govern U.S. import inspections and nutritional labeling requirements. Stakeholders must monitor evolving mycotoxin standards and origin traceability mandates as sustainability claims become enforceable rather than voluntary across major destination markets.
Market Dynamics
W320-grade kernel bifurcation is concentrating trade flows into premium and commodity tiers, with Vietnam's Binh Phuoc processing cluster capturing disproportionate value from snack manufacturers in North America and Europe.
Growth Catalysts
- EU EFSA aflatoxin limits:Tightening maximum residue levels are filtering out informal processors and consolidating market share among certified exporters with laboratory testing capabilities.
- Roasted and flavored retail formats:Snack manufacturers are expanding premium nut portfolios through value-added processing that commands higher shelf price points in supermarket channels.
- Vietnam's Binh Phuoc cluster:Concentrated processing infrastructure enables economies of scale in shelling, drying, and grading that lower unit costs for global brand supply contracts.
Market Restraints
- Raw nut supply volatility:West African and Vietnamese raw cashew harvest fluctuations create input cost instability for processors dependent on spot market procurement.
- REACH chemical safety protocols:European registration requirements for processing aids and fumigants add compliance friction and testing costs for Asian exporters.
- Tree nut allergen substitution:Seed-based alternatives and legume-derived proteins threaten ingredient market share in bakery and confectionery applications.
Strategic Opportunities
- Organic and fair-trade certification:European retail channels show structural demand for ethically sourced kernels with full origin traceability and farmer premium payments.
- Cashew butter applications:North American natural food channels represent underpenetrated growth potential for spreadable formats targeting plant-based diet adoption.
- India FSSAI hygiene mandates:Domestic certification requirements are creating tiered market structure that rewards branded processors over unorganized sector suppliers.
Industry Challenges
- Skilled grading labor scarcity:Manual kernel classification by whiteness and defect detection requires trained inspectors that processing clusters struggle to retain.
- Integrated traceability system deployment:Blockchain and IoT sensor integration across fragmented smallholder supply chains demands capital investment many mid-scale processors cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processed Cashew Market |
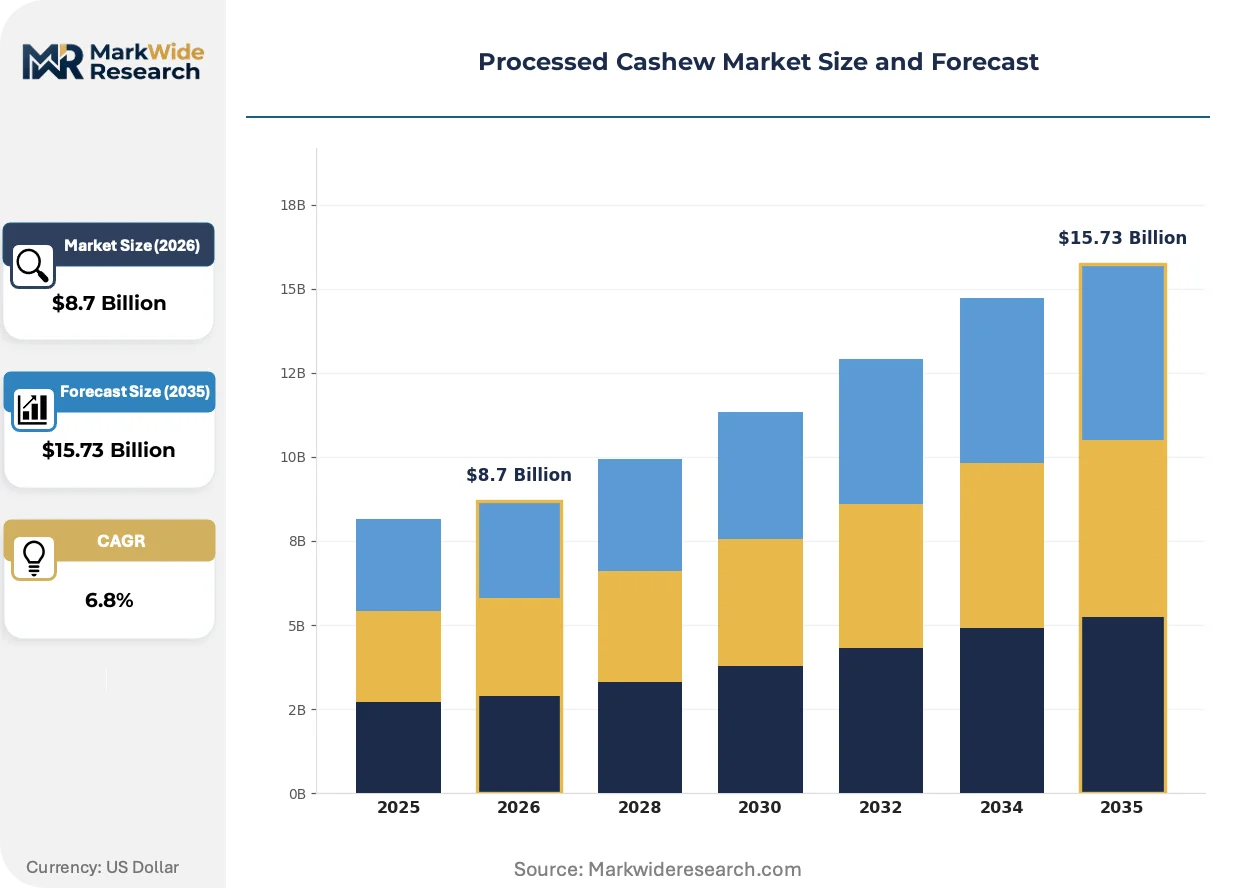
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Cashews, Roasted Cashews, Flavored Cashews, Cashew Butter End User: Food Industry, Snack Manufacturers, Bakeries, Retail Consumers Packaging Type: Bags, Boxes, Jars, Bulk Containers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Olam Food Ingredients, CBL Natural Foods, Haldiram's, Aurora Products Inc., Aryan International, Lafooco, Alphonsa Cashew Industries, Benin Cashew SA, Vietnam Cashew Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processed Cashew Market Evolving Landscape
Steam-based shelling automation and optical sorting systems are compressing processing economics while regulatory traceability mandates and shifting procurement patterns restructure competitive positioning across origin and destination markets.
Steam-shelling technology is displacing traditional manual cutting methods in Vietnam and India. Mid-scale processors are adopting automated steam infusion systems that reduce kernel breakage rates from fifteen percent to under five percent. This capital-intensive shift is displacing artisanal shelling cooperatives and consolidating processing capacity around mechanized facilities with wastewater treatment compliance.
REACH chemical safety protocols are extending registration requirements to fumigants and processing aids used in kernel preservation. European importers now demand third-party laboratory certification for phosphine residues and sulfur dioxide levels. Indian and Vietnamese exporters are responding by investing in alternative controlled-atmosphere storage and steam-based pasteurization to maintain EU market access.
Direct contracting between retail brands and origin processors is shortening traditional multi-layer procurement chains. North American snack manufacturers now source W320 and W240 grades through exclusive supply agreements with Binh Phuoc processors, bypassing regional traders. This disintermediation compresses margin capture for commodity traders while transferring price risk directly to processors with forward contract obligations.
Processed Cashew Market Segmentation
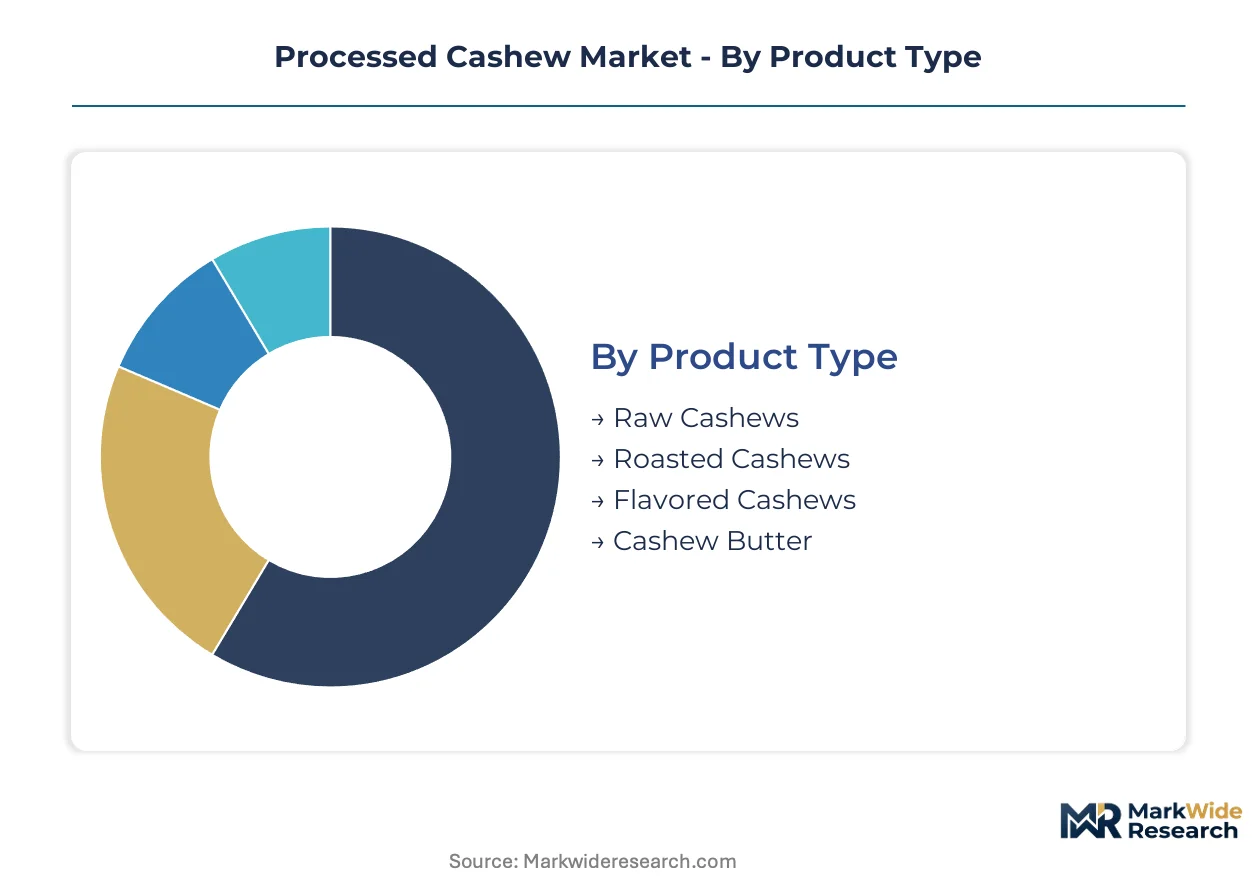
Grade-based kernel sorting and processing intensity create distinct margin architectures across product formats. Distribution channel selection determines whether processors capture commodity spreads or premium retail markups.
Product Type:
Roasted and flavored formats command the widest retail premium spreads, while cashew butter concentrates growth-oriented investment.
- Raw Cashews:Unroasted W320 and W240-grade kernels serve as ingredient inputs for confectionery and bakery applications where fat content near 47% provides functional binding. Demand concentrates in Vietnam's Binh Phuoc processing cluster supplying North American snack manufacturers with forward-contracted volumes. Raw cashews hold installed capacity. Cashew butter is rotating up the share rankings.
- Roasted Cashews:Dry-roasted kernels undergo thermal processing to reduce moisture below 3% and develop Maillard-reaction flavor compounds. European retail channels show structural demand for oil-roasted variants with salt and seasoning applications. Roasted formats anchor supermarket shelf placement.
- Flavored Cashews:Coated kernels with spice, honey, or smoke flavoring target impulse purchase occasions in convenience retail. India's FSSAI mandates additive disclosure for domestic flavored product lines.
- Cashew Butter:Ground kernel paste with near-50% fat content serves spreadable applications in North American natural food channels. Plant-based diet adoption drives formulation trials in bakery substitute applications.
Processing intensity separates commodity kernel traders from value-added snack suppliers.
End User:
Snack manufacturers generate the highest per-kilogram margins through branded retail positioning, while food industry procurement emphasizes volume scale and specification consistency.
- Food Industry:Bulk ingredient buyers in confectionery and bakery applications specify W320-grade kernels for uniform piece size in chocolate enrobing and pastry filling. EU EFSA aflatoxin limits filter supplier qualification to certified exporters with laboratory testing capabilities. Food industry holds installed capacity. Snack manufacturers are rotating up the share rankings.
- Snack Manufacturers:Branded nut portfolios in North America and Europe source through exclusive supply agreements with Vietnamese processors, bypassing regional traders. Value-added roasting and flavoring commands shelf price premiums in supermarket channels.
- Bakeries:Artisan and industrial bakeries utilize cashew pieces and granules for texture and protein fortification in gluten-free formulations.
- Retail Consumers:Direct-to-consumer packaged formats in jars and branded bags capture per-unit margins through convenience positioning in urban markets.
Specification requirements diverge sharply between industrial buyers demanding grade consistency and retail channels prioritizing packaging innovation.
Packaging Type:
Unit-size packaging determines margin capture, with single-serve formats extracting premium pricing and bulk containers anchoring food service procurement.
- Bags:Flexible laminated pouches with nitrogen flushing extend shelf life for roasted and flavored retail formats. Stand-up bags with resealable closures dominate North American natural food channel placement. Bags hold installed capacity. Jars are rotating up the share rankings.
- Boxes:Rigid paperboard packaging supports gift-oriented and seasonal retail occasions in European and Asian markets.
- Jars:Glass and PET containers target cashew butter and premium whole-kernel presentations where visibility and resealability justify higher unit economics.
- Bulk Containers:Food-grade totes and fiber drums anchor food industry and bakery procurement with 25-kilogram and larger pack sizes minimizing per-unit logistics cost.
Packaging selection directly encodes the target customer's price sensitivity and consumption occasion.
Distribution Channel:
Channel control separates origin-integrated processors from margin-dependent traders, with direct retail relationships compressing traditional intermediary layers.
- Online Retail:E-commerce platforms enable subscription-based cashew butter and specialty flavored formats with direct-to-consumer fulfillment bypassing wholesale markups. India's FSSAI hygiene mandates apply to domestic e-commerce food listings. Online retail holds installed capacity. Specialty stores are rotating up the share rankings.
- Supermarkets:Mass retail chains in the US and EU demand W320-grade consistency and third-party organic certification for private label and branded shelf placement.
- Specialty Stores:Natural food and gourmet retailers emphasize fair-trade and single-origin provenance claims with full traceability documentation.
- Wholesale:Traditional trader networks persist in raw kernel spot markets but face disintermediation as retail brands contract directly with Binh Phuoc processors.
Direct contracting is restructuring channel economics away from commodity traders toward processor-retailer partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Binh Phuoc province houses the world's densest concentration of cashew processing infrastructure, with mechanized shelling and optical grading facilities supplying premium W320-grade kernels to North American and European snack manufacturers under strict aflatoxin protocols.
United States
Snack manufacturers in California and Texas drive demand for value-added roasted and flavored formats through direct contracting with Vietnamese processors. FDA nutritional labeling requirements and USDA import inspections govern kernel entry at ports of Houston and Los Angeles. Bulk totes from Binh Phuoc arrive for repackaging into branded retail bags targeting natural food channels.
Germany
Confectionery and bakery ingredient buyers in North Rhine-Westphalia specify W320-grade consistency for chocolate enrobing applications. EFSA aflatoxin maximum limits and REACH chemical safety protocols filter supplier qualification to certified exporters with third-party laboratory documentation. Hamburg serves as the primary EU entry point for containerized kernel shipments.
India
Domestic branded snack consumption concentrates in Maharashtra and Gujarat, where Haldiram's and regional processors operate roasting and flavoring lines. FSSAI hygiene certification mandates create tiered market structure rewarding organized sector suppliers over informal competitors. Kollam in Kerala anchors traditional shelling cooperatives now facing displacement by steam-based automation.
Vietnam
Binh Phuoc province's processing cluster generates economies of scale in shelling, drying, and grading that lower unit costs for global brand supply contracts. Direct exclusive agreements with North American snack manufacturers bypass traditional trader networks. Steam-shelling technology adoption reduces kernel breakage rates and consolidates capacity around mechanized facilities with wastewater compliance.
Netherlands
Rotterdam's port infrastructure handles transshipment of bulk kernel containers for redistribution across European confectionery and bakery channels. EFSA mycotoxin standards and emerging sustainability traceability mandates shape procurement documentation requirements. Dutch traders face margin compression as retail brands contract directly with origin processors.
Processed Cashew Market Competitive Landscape
Concentration sits with vertically integrated processors controlling raw nut supply from West African and Vietnamese origins through to graded kernel export. The market structure tiers between large-scale mechanized facilities with laboratory testing capabilities and artisanal shelling cooperatives losing share to automation. Three archetypes dominate: origin-integrated processors with captive supply networks, certified organic and fair-trade specialists serving European retail, and domestic branded snack manufacturers with roasting and flavoring capabilities. Competitive moves center on backward integration into raw nut procurement and direct contracting partnerships that disintermediate traditional traders.
Among origin-integrated processors, Olam Food Ingredients and Vietnam Cashew Corporation exemplify the scale-driven archetype with Binh Phuoc-based mechanized facilities. CBL Natural Foods occupies a position within the certification-specialist tier, representing fair-trade and organic kernel supply to European retail channels. Haldiram's anchors the domestic branded snack manufacturer archetype in India, with Maharashtra-based roasting and flavored product lines serving FSSAI-certified distribution.
| Leading Market Players |
|---|
| Olam Food Ingredients |
| CBL Natural Foods |
| Haldiram's |
| Aurora Products Inc. |
| Aryan International |
| Lafooco |
| Alphonsa Cashew Industries |
| Benin Cashew SA |
| Vietnam Cashew Corporation |
| Others |
Value Network & Pricing Analysis
Steam-shelling automation replacing manual cutting methods in Vietnam and India simultaneously redraws processing geography around capital-intensive facilities and compresses W320-grade kernel premiums toward commodity parity. This substitution dynamic transfers margin capture from artisanal cooperatives to mechanized clusters with wastewater compliance, while optical sorting investments raise the fixed-cost barrier to tier-one supply contracts.
Pricing Analysis
EU EFSA aflatoxin limits dictate the pricing tier structure by filtering supplier qualification to certified exporters with laboratory testing capabilities. Three-tier pricing structure across premium, standard, and economy levels separates organic fair-trade kernels for European retail from commodity W320 grades and ungraded broken pieces. Cost compression in the standard tier is intensifying because Binh Phuoc processors are absorbing forward-contract price risk previously borne by regional traders. Food industry buyers show highest price sensitivity due to volume procurement and specification fungibility, while specialty retailers demonstrate least sensitivity when traceability documentation commands shelf placement premiums.
Supply Chain Analysis
West African raw nut harvest volatility functions as the primary chokepoint, with Ivorian and Ghanaian crop fluctuations transmitting directly into Vietnamese processor input costs. The supply chain draws from West African farmgate procurement, Vietnamese shelling and grading concentration, and North American snack manufacturer direct contracting. Single-source vulnerability sits with Binh Phuoc's geographic processing dominance, where steam-shelling infrastructure consolidation leaves limited alternative supply for W320-grade consistency. Distribution runs through exclusive processor-retailer agreements that disintermediate traditional commodity traders and compress margin capture at Rotterdam transshipment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct contracting platforms between origin processors and retail brands are reconfiguring this market around traceability-verified supply relationships rather than spot-market commodity exchange. Ecosystem interoperability now hinges on blockchain-integrated grading data that satisfies EU EFSA documentation requirements and North American natural channel provenance claims simultaneously.
For Market Incumbents: Fortify backward integration into West African raw nut procurement to secure captive supply against harvest volatility and spot market price spikes. Invest in steam-shelling automation and optical grading capacity to maintain W320-grade qualification for European retail channels facing tightening EFSA mycotoxin protocols. Channel control through exclusive supply agreements with North American snack manufacturers defends margin position against trader disintermediation. For New Entrants and Emerging Players: Lead with cashew butter formulation trials targeting North American natural food channels where plant-based diet adoption outpaces incumbent capacity allocation. Organic and fair-trade certification for European specialty retail represents the most penetrable white-space, as established processors prioritize volume contracts over farmer premium documentation. Go-to-market execution should emphasize direct e-commerce subscription models that bypass wholesale markups and capture per-unit margins in jars and resealable formats. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-scale Vietnamese processors lacking steam-shelling automation but holding established EU laboratory certification relationships. Long-term viability across the analysis window favors acquisition targets with integrated traceability systems and forward-contracted volume commitments from North American snack manufacturers. The signal to watch is EFSA aflatoxin protocol tightening that would accelerate consolidation toward mechanized facilities with in-house testing capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Nut Procurement | Captive West African supply secures processor margin against harvest volatility and spot price spikes. |
| Steam-Shelling Automation Deployment | Kernel breakage reduction below five percent qualifies W320-grade consistency for EU EFSA protocols. |
| Organic and Fair-Trade Certification Investment | European specialty retail channels structurally demand full origin traceability with farmer premium payments. |
| Direct-to-Consumer E-Commerce Launch | Subscription cashew butter models bypass wholesale markups and capture jar-format premium economics. |
| Blockchain Traceability System Integration | IoT sensor documentation satisfies emerging EU sustainability mandates and North American provenance claims. |
Research Methodology
The analysis maps raw kernel procurement, mechanized shelling and grading, value-added roasting and flavoring, and direct retail distribution channels, each validated through processor operations managers, snack manufacturer procurement leads, European retail category buyers, and West African farmgate cooperatives. Primary interview data triangulated against Vietnam Cashew Association export statistics, EU RASFF rapid alert notifications for aflatoxin violations, Indian FSSAI hygiene certification registries, and North American customs import records. Bottom-up volume modeling from grade-specific kernel throughput converged with top-down value estimates derived from retail shelf price audits.
Outputs were validated against external benchmarks including Vietnamese export value disclosures, EU import volume aggregates, and specialty food channel growth indicators across the projection horizon. Segmentation modeling incorporated product type intensity, end-user specification requirements, packaging format economics, and distribution channel control dynamics alongside regional regulatory cluster differentiation. CAGRs were derived from fitted trend analysis of historical grade-specific price movements and forward-contract volume commitments. Industry-specific forecast inputs included West African harvest yield projections and EFSA protocol amendment trajectories.
Forecasts assume regulatory continuity in EU EFSA mycotoxin enforcement and Indian FSSAI hygiene mandates; material policy shifts would require re-modeling of supplier qualification rates and processing capacity allocation. Specific risks that could revise projections include West African climate-induced harvest collapse, REACH chemical safety protocol extension to additional processing aids, and seed-based allergen substitution acceleration in bakery applications. Practitioners should keep alternative scenarios live as direct contracting platform adoption and traceability mandate enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Global Take Out Fried Chicken Market
Processed Foods
Processed Vegetable Market
Processed Foods
Europe Processed Egg Market
Processed Foods
Global Pasta Market
Processed Foods
Asia-Pacific Ice Cream Market
Processed Foods
Yogurt Dip Market
Processed Foods
Dairy Desserts Market
Processed Foods
United States Food Spread Market
Processed Foods
Broth Market
Processed Foods
Middle East and Africa Processed Meat Market
Processed Foods
Spreadable Fats Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
Instant Cooking Food Market
Processed Foods
Pates Market
Processed Foods
Egg White Cubes Market
Processed Foods
United States Ice Cream Market