
 Europe Molecular Diagnostics Market | 2026-2036
Europe Molecular Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Molecular Diagnostics Market Analysis
Market Context
Multi-source reagent procurement is consolidating as European laboratories seek supply security and regulatory consistency under IVDR transition timelines. Danaher leverages its broad life sciences portfolio to anchor diagnostic workflow integration across European hospital networks. Abbott Laboratories competes through point-of-care molecular platforms that extend testing access beyond centralized laboratories. Roche specializes in high-throughput sequencing and PCR systems that dominate oncology and virology applications in Western Europe.
Technical Definition and Segment Structure
Europe molecular diagnostics encompasses nucleic acid-based testing methods including polymerase chain reaction, next-generation sequencing, and microarray technologies that detect genetic material from pathogens or patient samples with analytical sensitivity reaching single-copy detection. These systems serve clinical decision-making in infectious disease management, cancer profiling, and hereditary risk assessment across hospital, laboratory, and research settings. Reagents and assays capture the largest margin pools due to recurring consumable demand and kit-based IVDR certification requirements, while NGS technology leads growth trajectories driven by oncology panel expansion and pharmacogenomic applications. Instruments represent a mature segment where replacement cycles and platform consolidation determine purchasing patterns among European laboratory buyers.
Regulatory Framework and Outlook
The European Medicines Agency coordinates scientific advice for companion diagnostics, while IVDR and CE marking requirements administered by notified bodies govern market access and performance validation standards across member states. REACH and RoHS frameworks additionally constrain chemical reagent composition and electronic instrument manufacturing specifications. Stakeholders must monitor notified body capacity constraints and IVDR transition deadlines to secure uninterrupted product certification and avoid supply discontinuities in European markets.
Market Dynamics
IVDR transition timelines are compressing conformity assessment windows, forcing European laboratories to consolidate supplier relationships and pre-emptively lock multi-year reagent contracts before notified body capacity constraints intensify certification bottlenecks.
Growth Catalysts
- Companion diagnostic mandates:EMA scientific advice pathways now require molecular profiling for oncology drug approvals, embedding testing into therapeutic development pipelines across France, Germany, and Italy.
- PCR menu expansion:Hospital networks in Germany are standardizing syndromic respiratory panels that multiplex viral and bacterial targets, reducing time-to-diagnosis in emergency departments.
- Pharmacogenomic integration:Netherlands and Nordic health systems are embedding CYP450 testing into electronic prescribing workflows, creating institutional demand for preemptive genotyping.
Market Restraints
- Notified body scarcity:IVDR designation requirements have reduced certifying entity count from over twenty to fewer than ten, extending technical documentation review timelines by twelve to eighteen months.
- Reagent import concentration:Lyophilized master mix supply chains route through single-source polymerase manufacturers in Switzerland, exposing continuity risk during customs clearance disruptions.
- NGS workflow complexity:Bioinformatics pipeline validation requires specialized computational infrastructure that community laboratories in Portugal and Greece cannot resource internally.
Strategic Opportunities
- Decentralized oncology testing:Poland and Romania present white space for community hospital molecular pathology services currently referring samples to Berlin and Paris reference centers.
- Digital PCR adoption:Absolute quantification capabilities are expanding into cell therapy manufacturing quality control, opening pharmaceutical production as a new customer vertical.
- Green reagent formulations:REACH Article 33 disclosure obligations and RoHS substance restrictions are creating competitive differentiation for reformulated amplification chemistries with reduced hazardous compound content.
Industry Challenges
- Bioinformatics workforce scarcity:Variant interpretation expertise concentrates in academic medical centers, leaving commercial laboratories dependent on outsourced clinical reporting services.
- Legacy LIS integration:Middleware connectivity between NGS platforms and hospital information systems requires custom HL7-FHIR mapping that delays go-live dates by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Molecular Diagnostics Market |
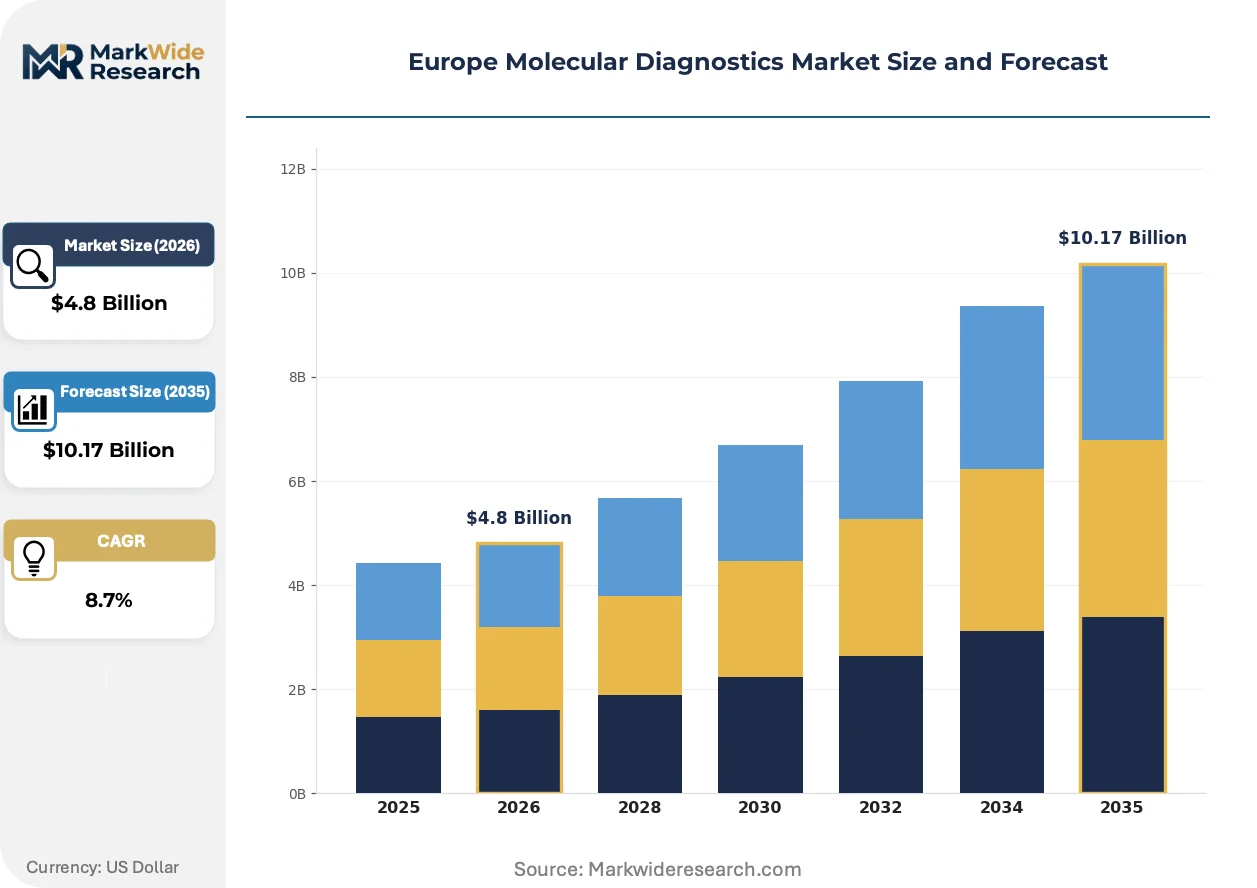
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Assays End User: Hospitals, Laboratories, Research Institutions, Clinics Technology: PCR, NGS, Microarray, Sequencing Application: Oncology, Infectious Diseases, Genetic Testing, Prenatal Testing |
| Companies Covered | Danaher, Abbott Laboratories, F. Hoffmann-La Roche Ltd., Becton Dickinson and Company, Bio-Rad Laboratories, QIAGEN, Illumina, Siemens Healthineers, bioMérieux, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Molecular Diagnostics Market Emerging Trajectories
Automation architectures and regulatory data requirements are converging to reshape how European laboratories architect testing workflows, with three developments commanding capital allocation priority.
Next-generation sequencing is expanding into routine hereditary cancer screening panels, replacing single-gene Sanger tests in Dutch and Belgian genetics services. Regional hospital consortia are pooling sequencing volume to justify platform capital expenditure, compressing per-sample costs through pooled procurement. This expansion is enabling community access to previously centralized testing capabilities.
EU In Vitro Diagnostic Regulation performance study requirements are mandating larger clinical validation cohorts than predecessor directives, elevating documentation burdens for novel assay introductions. Manufacturers are responding by prioritizing high-volume oncology and infectious disease categories where study cost amortization across kit volume proves feasible. Smaller indication panels face delayed commercialization as firms sequence regulatory submissions by revenue potential.
Laboratory procurement functions are consolidating vendor relationships to secure IVDR-compliant supply continuity, displacing opportunistic spot purchasing of research-use-only reagents. Group purchasing organizations in France and Spain are negotiating framework agreements that bundle instrumentation, consumables, and service into multi-year contracts. This concentration is most visible in German hospital networks where central procurement offices now mandate single-source molecular diagnostics agreements.
Europe Molecular Diagnostics Market Segmentation
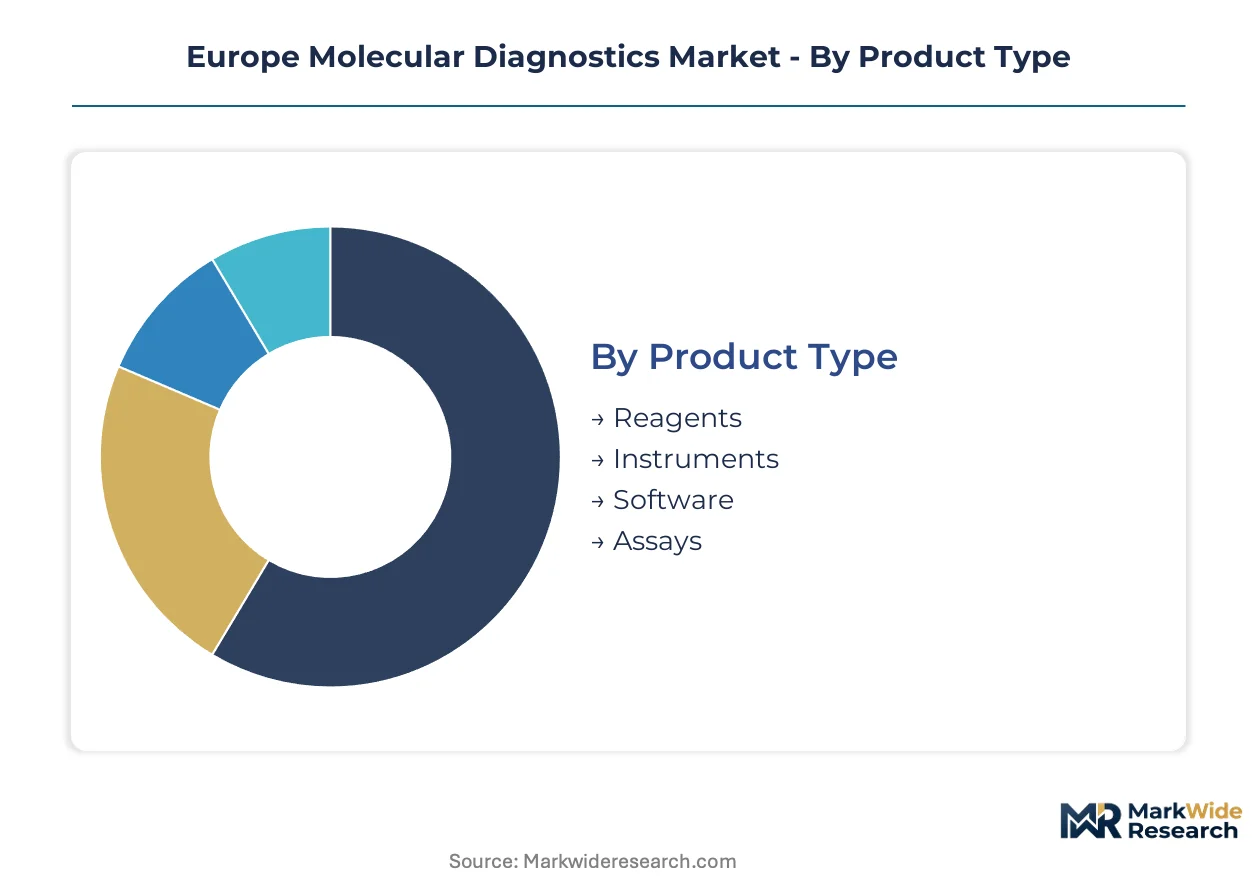
IVDR certification pathways impose divergent documentation burdens across molecular diagnostics segments, with consumable categories requiring recurring batch conformity assessments while capital equipment faces extended technical file reviews. Procurement offices in German hospital networks and French laboratory consortia are segmenting supplier selection by certification readiness and supply continuity guarantees.
Product Type:
Reagents and instruments carry distinct IVDR obligations — consumables demand ongoing notified body surveillance audits, while platforms require clinical performance studies under Annex XIII.
- Reagents:Lyophilized master mixes, primers, and nucleotide formulations constitute the recurring revenue base for European molecular diagnostics suppliers. German reference laboratories and hospital networks in the Netherlands are locking multi-year supply contracts to preempt notified body capacity constraints and customs clearance disruptions.
- Instruments:PCR thermal cyclers, NGS platforms, and automated extraction systems anchor laboratory workflow architecture. Replacement cycles in France and Belgium concentrate purchasing decisions among centralized procurement offices that mandate IVDR-compliant service bundling.
- Software:Bioinformatics pipelines and laboratory information system middleware enable variant interpretation and regulatory data management. EMA scientific advice pathways increasingly require computational validation documentation for companion diagnostic submissions.
- Assays:Kit-based test systems combine reagents with validated protocols for specific clinical indications. Oncology and infectious disease panels dominate notified body submission queues due to amortizable study costs across high kit volumes.
Leading the category by volume: Reagents. Growing fastest: Software.
End User:
Customer procurement sophistication varies sharply — hospital networks negotiate enterprise frameworks while research institutions operate under less stringent general purpose reagent exemptions.
- Hospitals:German hospital networks and French public hospital consortia anchor the largest molecular testing volumes in Europe. Syndromic respiratory panel standardization and oncology profiling mandates are embedding molecular diagnostics into emergency department and oncology service line workflows.
- Laboratories:Independent clinical laboratories and hospital-affiliated reference centers in Italy and Spain perform centralized testing for community hospitals. IVDR transition timelines are compressing supplier consolidation decisions as notified body scarcity extends certification timelines.
- Research Institutions:Academic medical centers in Belgium and the Netherlands maintain NGS infrastructure for discovery applications and clinical validation studies. REACH and RoHS compliance requirements constrain reagent formulation sourcing for non-clinical applications.
- Clinics:Community and specialty clinics in Poland and Romania currently refer molecular testing to centralized reference centers. Point-of-care molecular platform expansion is creating decentralized access opportunities in underserved Eastern European markets.
Volume concentrates in: Hospitals. Steepest expansion trajectory: Clinics.
Technology:
Platform selection determines laboratory staffing requirements, infrastructure investment, and regulatory validation scope across European markets.
- PCR:Real-time and digital PCR systems deliver quantitative nucleic acid detection with established IVDR conformity assessment pathways. German emergency departments are standardizing syndromic respiratory panels that multiplex viral and bacterial targets.
- NGS:Next-generation sequencing enables comprehensive genomic profiling for oncology and hereditary disease applications. Dutch and Belgian genetics services are replacing single-gene Sanger tests with routine hereditary cancer screening panels.
- Microarray:Solid-phase hybridization platforms support pharmacogenomic and cytogenetic testing with moderate throughput requirements. CYP450 testing integration into electronic prescribing workflows in Nordic health systems sustains institutional demand.
- Sequencing:Sanger and emerging long-read technologies retain niche applications for confirmatory testing and complex variant resolution. Sanger confirmation requirements for NGS-detected variants maintain residual demand in clinical genetics laboratories.
Installed base leader: PCR. Gaining share fastest: NGS.
Application:
Clinical indication prioritization shapes manufacturer R&D allocation and notified body submission sequencing across European regulatory pathways.
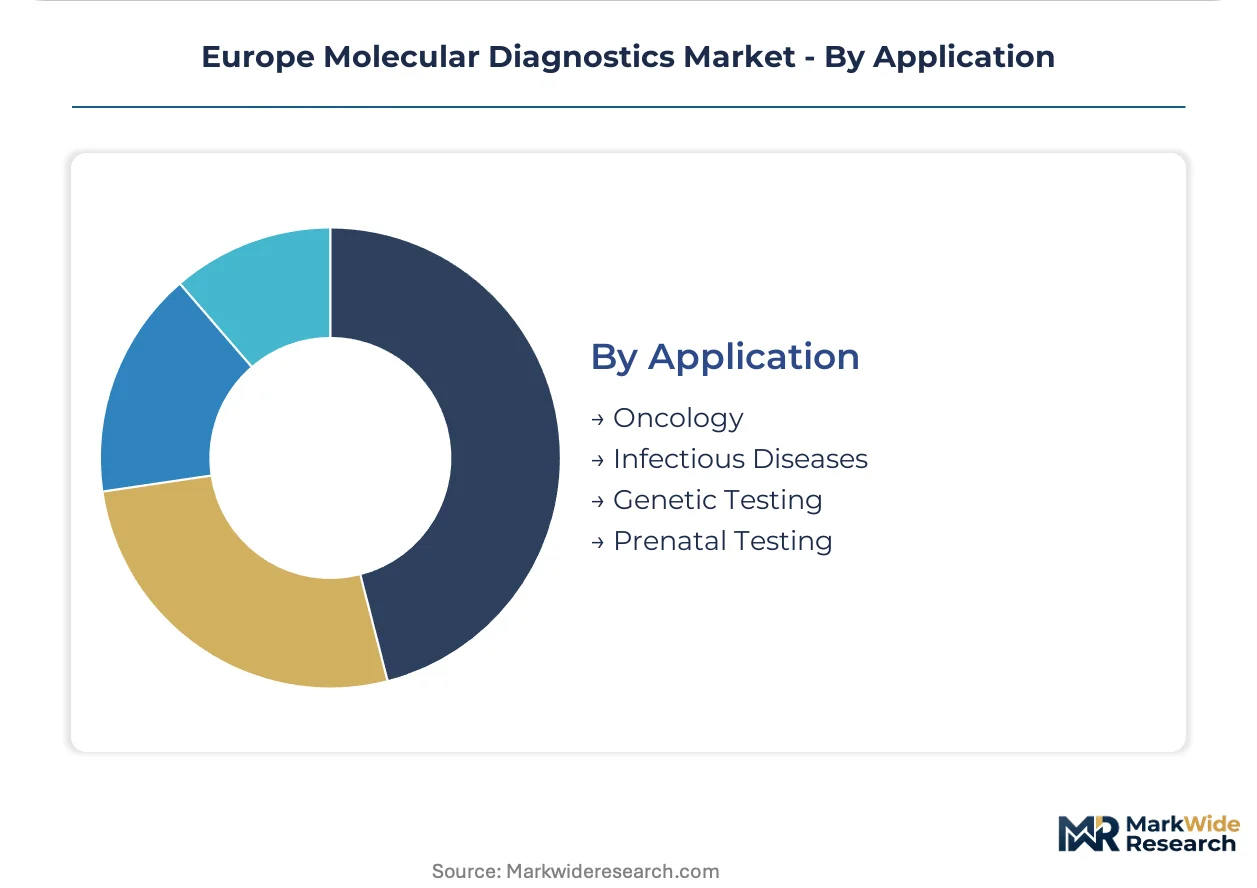
- Oncology:Companion diagnostic mandates from EMA scientific advice pathways embed molecular profiling into therapeutic development pipelines. France, Germany, and Italy anchor regional demand for comprehensive genomic profiling and circulating tumor DNA monitoring.
- Infectious Diseases:Syndromic respiratory, bloodstream infection, and antimicrobial resistance panels dominate hospital laboratory menus. German hospital network standardization of multiplex viral and bacterial detection is reducing time-to-diagnosis in emergency settings.
- Genetic Testing:Hereditary cancer, cardiomyopathy, and neurological disorder panels expand access to predictive risk assessment. Regional hospital consortia in the Netherlands and Belgium are pooling sequencing volume to justify platform capital expenditure.
- Prenatal Testing:Non-invasive prenatal screening and carrier detection applications face ethical framework variations across member states. National reimbursement policies in France and Germany determine access expansion trajectories for cell-free fetal DNA testing.
Revenue concentration: Oncology. Climbing the fastest: Genetic Testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymerase manufacturing concentrates in Swiss chemical clusters, anchoring reagent supply chains that feed German hospital networks and French laboratory consortia. IVDR transition timelines are compressing procurement decisions as notified body scarcity extends certification timelines across the continent.
Germany
Hospital networks in North Rhine-Westphalia and Bavaria anchor the continent's largest molecular testing volumes, standardizing syndromic respiratory panels across emergency departments. BfArM coordinates national reference panel distribution while enforcing post-market surveillance obligations under IVDR Article 10. Berlin-Brandenburg hosts reference laboratories that centralize oncology profiling for eastern federal states.
France
Public hospital consortia in Île-de-France are consolidating vendor relationships to secure IVDR-compliant supply continuity for high-throughput PCR platforms. ANSM oversees clinical performance study validation for companion diagnostic submissions alongside EMA scientific advice pathways. Lyon-based laboratory networks pool sequencing volume to justify NGS platform capital expenditure across Auvergne-Rhône-Alpes.
United Kingdom
NHS England genomic medicine service alliances are embedding hereditary cancer screening into regional genetics hubs, replacing single-gene Sanger tests with panel-based workflows. MHRA operates parallel recognition routes for CE-marked devices while transitioning toward UKCA marking requirements. Greater Manchester and Cambridge clusters concentrate bioinformatics workforce development for variant interpretation services.
Netherlands
Academic medical centers in Utrecht and Rotterdam are integrating pharmacogenomic testing into electronic prescribing workflows, creating institutional demand for CYP450 genotyping. Health Council guidelines mandate molecular profiling for oncology drug reimbursement decisions. Eindhoven Region instrumentation manufacturers supply automated extraction systems to Benelux hospital networks.
Italy
Hospital-affiliated reference centers in Lombardy and Lazio perform centralized molecular testing for community hospitals across central and northern regions. AIFA regulates companion diagnostic reimbursement alongside EMA marketing authorization requirements. Milan-based laboratory consortia negotiate framework agreements that bundle instrumentation, consumables, and service into multi-year contracts.
Europe Molecular Diagnostics Market Vendor Landscape
Global majors compete with regional champions across IVDR certification capabilities and supply chain resilience dimensions. Market structure tilts toward consolidated procurement relationships as German hospital networks and French laboratory consortia mandate single-source agreements. Three archetypes dominate: diversified life sciences conglomerates anchoring workflow integration, specialized diagnostic platform manufacturers, and sequencing technology specialists. Competitive moves concentrate on multi-year consumable contract lock-ins and notified body designation acquisitions.
Within the diversified conglomerate tier, Danaher and Abbott Laboratories occupy positions that exemplify platform-agnostic workflow integration strategies. F. Hoffmann-La Roche Ltd. sits within the high-throughput specialization archetype, anchoring oncology and virology applications through instrument-reagent bundling. These three entities represent contrasting responses to IVDR conformity assessment pressures: portfolio breadth, point-of-care decentralization, and centralized laboratory dominance.
| Leading Market Players |
|---|
| Danaher |
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd. |
| Becton Dickinson and Company |
| Bio-Rad Laboratories |
| QIAGEN |
| Illumina |
| Siemens Healthineers |
| bioMérieux |
| Others |
Supply Flow & Price Mechanics
Captive polymerase production in Swiss chemical clusters anchors both supply security and pricing power for European molecular diagnostics manufacturers, with IVDR certification costs embedded into multi-year consumable contracts that German hospital networks negotiate. This backward integration into enzyme manufacturing insulates dominant suppliers from customs clearance volatility while enabling service-bundled pricing premiums that community laboratories in Poland and Romania cannot match.
Pricing Analysis
Service-bundled instrumentation contracts separate premium-tier oncology platform providers from economy-tier PCR suppliers competing on reagent unit costs alone. Price differentiation rests on IVDR certification grade and after-sales bioinformatics support, with margins tightening in the standard tier as French group purchasing organizations consolidate vendor relationships. Hospital procurement offices in Germany exhibit lowest price sensitivity due to therapeutic mandate embedding, while independent clinical laboratories in Italy face acute cost compression from referral volume uncertainty.
Supply Chain Analysis
CE marking and IVDR technical documentation requirements gate market access for lyophilized master mix suppliers concentrated in Switzerland, Germany, and the Netherlands. Raw material dependencies center on thermostable polymerase enzymes, fluorophore-labeled probes, and magnetic bead formulations, with single-source vulnerability in Swiss enzyme manufacturing exposing continuity risk during customs disruptions. Distribution runs through German hospital network central procurement offices and French laboratory consortia that mandate multi-year framework agreements bundling instrumentation, consumables, and regulatory compliance services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe molecular diagnostics market functions as a cost-of-compliance arena where IVDR certification timelines and notified body scarcity erect barrier-to-entry moats favoring incumbents with established technical documentation portfolios and multi-year reagent contract lock-ins.
For Market Incumbents: Anchor market position through acquisition of notified body designation capabilities or strategic partnerships with IVDR-designated entities facing capacity constraints. Prioritize multi-year consumable contract extensions with German hospital networks before certification bottlenecks intensify, while defending against digital PCR platform entrants by embedding absolute quantification workflows into existing oncology service line agreements.
For New Entrants and Emerging Players: The premium-economy price-point gap in Eastern European community hospital molecular pathology creates white-space opportunity for decentralized NGS platform offerings. Target Poland and Romania with instrument-rental business models that circumvent capital expenditure barriers, partnering with Berlin and Paris reference centers for bioinformatics reporting services rather than building captive variant interpretation infrastructure.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified life sciences conglomerates seeking IVDR-compliant workflow integration capabilities. Five-to-ten year viability favors platform-agnostic consumable suppliers with locked hospital network contracts over pure-play instrument manufacturers facing replacement cycle compression. Monitor notified body capacity expansion announcements as the critical inflection signal for valuation re-rating of certification-constrained assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership Acquisition | Secures IVDR certification capacity for oncology panel submissions amid twelve-to-eighteen month review delays. |
| Multi-Year Reagent Contract Lock-In | Preempts supplier consolidation by German hospital network central procurement offices before IVDR deadlines. |
| Decentralized NGS Platform Deployment | Captures Eastern European community hospital volume currently referred to Berlin and Paris reference centers. |
| Bioinformatics Workforce Development | Addresses variant interpretation scarcity that forces commercial laboratory outsourcing to academic medical centers. |
| Green Reagent Formulation Investment | Differentiates amplification chemistries under REACH Article 33 disclosure obligations and RoHS substance restrictions. |
Methodological Framework
Multi-period observation of IVDR certification submission queues, notified body designation timelines, and hospital procurement contract award patterns anchored the trend analysis, supplemented by interviews with regulatory affairs directors at IVD manufacturers, laboratory medicine chiefs at German hospital networks, and procurement managers at French public hospital consortia. Secondary validation drew from EMA companion diagnostic scientific advice documentation, BfArM post-market surveillance bulletins, and ANSM clinical performance study guidance, with bottom-up reagent volume modeling triangulated against top-down hospital network expenditure disclosures.
Segment-weighting applied differential growth assumptions across PCR, NGS, microarray, and sequencing technology platforms, with end-user segmentation modeling hospitals, laboratories, research institutions, and clinics as distinct procurement sophistication tiers. CAGRs were derived from instrument replacement cycle analysis, oncology panel expansion trajectories, and pharmacogenomic workflow penetration rates across the projection horizon, incorporating IVDR transition timeline uncertainty and REACH compliance cost pass-through assumptions.
Inputs from EMA, BfArM, and ANSM regulatory documentation were available through the study window; gaps in notified body capacity expansion plans and hospital network contract renewal schedules introduce uncertainty bands around procurement consolidation timing assumptions. Forecasts reflect documented regulatory transition deadlines and laboratory infrastructure investment patterns. A model refresh is warranted upon material change in IVDR notified body designation rates or EMA companion diagnostic mandate expansion beyond oncology therapeutic areas.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Equine Diagnostic Services Market
Diagnostics
Cognitive Diagnostics Market
Diagnostics
Neuro-Auto-Immune Disease Diagnostics Market
Diagnostics
Creatinine Test Market
Diagnostics
US Prostate Cancer Nuclear Medicine Diagnostics Market
Diagnostics
GCC in-Vitro Diagnostic Devices Market
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
Fructosamine Test Market
Diagnostics
Artificial Intelligence in IVD Market
Diagnostics
Viral Molecular Diagnostics Market
Diagnostics
Blood Glucose Testing Devices Market
Diagnostics
US Influenza Diagnostics Market
Diagnostics
In Vitro Diagnostics Test Kit Market
Diagnostics
Epigenetics Diagnostics Market
Diagnostics
Viral Antigens Market
Diagnostics
At-Home Cancer Testing Market