
 Global Sepsis Diagnostics Market | 2026-2036
Global Sepsis Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sepsis Diagnostics Market Foresight
The gap between rapid molecular diagnostics and conventional microbial culture methods is repositioning competitive tiers in sepsis testing. Abbott Laboratories leverages its point-of-care footprint to sustain channel control in emergency settings. bioMérieux SA anchors its position through specialized blood culture automation systems. Thermo Fisher Scientific Inc. differentiates via broad biomarker assay portfolios spanning hospital and reference lab networks.
Sepsis diagnostics encompasses laboratory and near-patient technologies that detect bloodstream infections and host immune dysregulation through pathogen identification, biomarker quantification, or nucleic acid amplification, typically delivering results within one to eight hours to guide antibiotic therapy decisions. Molecular diagnostics platforms lead the product landscape due to their sensitivity for polymicrobial detection and declining per-test costs. Point-of-care facilities represent the fastest-growing end-user segment as health systems decentralize testing to accelerate time-to-antibiotics.
The FDA maintains stringent clinical validation requirements for sepsis assays under its in vitro diagnostics framework, while the EU MDR imposes enhanced post-market surveillance obligations on device manufacturers seeking CE marking. WHO sepsis guidelines further shape procurement criteria in emerging health systems by prioritizing diagnostics aligned with antimicrobial stewardship protocols. Stakeholders must monitor evolving reimbursement codes for rapid sepsis panels as payors recalibrate coverage around time-to-result thresholds.
Market Dynamics
The FDA's breakthrough device pathway and WHO sepsis guidelines are compressing clinical validation timelines while fragmenting reimbursement authority across hospital systems and national health programs.
Growth Catalysts
- EU MDR post-market surveillance mandates:Manufacturers investing in automated blood culture systems gain accelerated CE marking access, expanding addressable hospital networks across Germany, France, and Italy.
- Emergency department decentralization:Point-of-care molecular platforms reduce time-to-antibiotic initiation from hours to under 60 minutes in high-acuity settings.
- Antimicrobial stewardship protocols:Hospital pharmacy committees in the United States now require rapid pathogen identification to justify broad-spectrum antibiotic continuation beyond 48 hours.
Market Restraints
- Reagent supply concentration:Polymerase chain reaction master mixes and nucleic acid extraction kits depend on concentrated contract manufacturing in South Korea and Taiwan.
- Clinical labor scarcity:Certified medical laboratory scientists capable of operating multiplex molecular platforms face acute shortages in rural health systems across the United States and Australia.
- Capital intensity of automation:Continuous monitoring blood culture instruments require dedicated floor space and HVAC infrastructure that smaller community hospitals cannot accommodate.
Strategic Opportunities
- India's hospital accreditation expansion:NABH certification requirements for tertiary care centers create procurement pull for integrated sepsis diagnostic workflows.
- Host response biomarker convergence:Procalcitonin and presepsin quantification combined with pathogen detection in single-platform assays reduces test ordering complexity.
- Brazil's SUS diagnostic modernization:Federal procurement tenders for public hospital networks specify rapid molecular panels, opening volume contracts for qualified suppliers.
Industry Challenges
- Laboratory information system integration:Molecular diagnostic platforms must map to disparate electronic health record architectures, delaying deployment in multi-hospital networks.
- IVD clinical trial design complexity:FDA requires prospective studies demonstrating impact on antibiotic decision-making, extending validation timelines by 18-24 months compared to analytical performance studies alone.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sepsis Diagnostics Market |
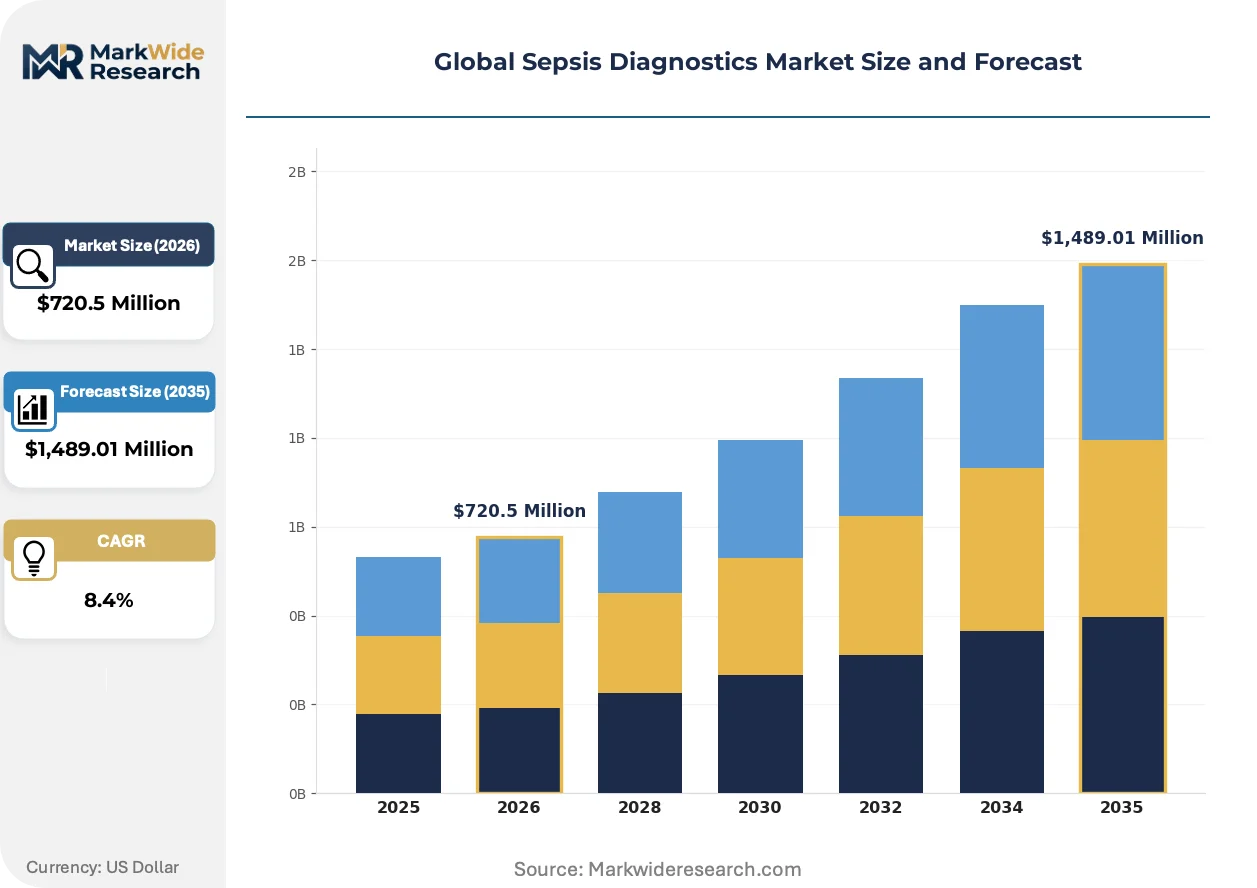
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,489.01 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biomarker Assays, Molecular Diagnostics, Immunoassays, Microbial Culture Kits Technology: Polymerase Chain Reaction, Enzyme-Linked Immunosorbent Assay, Flow Cytometry, Mass Spectrometry, Microfluidics Application: Early Detection, Prognosis Monitoring, Therapy Guidance, Risk Stratification End User: Clinical Laboratories, Diagnostic Centers, Research Institutes, Point-of-Care Facilities |
| Companies Covered | Thermo Fisher Scientific Inc., Abbott Laboratories, bioMérieux SA, QIAGEN N.V., Bruker Corporation, Becton Dickinson and Company, F. Hoffmann-La Roche Ltd, T2 Biosystems, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sepsis Diagnostics Market Shifts & Advancements
Sepsis diagnostics is consolidating around platforms that collapse pathogen identification and host immune profiling into unified workflows, while regulatory frameworks and procurement models simultaneously fragment and accelerate.
Next-generation sequencing panels for bloodstream infection detection are unifying bacterial, fungal, and antimicrobial resistance gene identification in single-sample workflows. Academic medical centers in the United States and university hospitals in Germany are piloting these platforms for immunocompromised patient populations. This unification is compressing the competitive window for standalone blood culture systems by eliminating the need for sequential testing cascades.
The EU MDR's enhanced post-market clinical follow-up requirements are forcing manufacturers to deploy real-world performance registries for CE-marked sepsis assays. Device sponsors must now submit annual safety and effectiveness updates to notified bodies, increasing compliance overhead. Blood culture instrument manufacturers serving European markets are responding by embedding remote diagnostic capabilities for predictive maintenance and performance monitoring.
Hospital pharmacy and infectious disease committees are consolidating purchasing authority for rapid sepsis panels, displacing individual department-level ordering. Integrated delivery networks in the United States now negotiate system-wide contracts with molecular diagnostic vendors, extracting volume discounts in exchange for exclusive platform commitments. This concentration is most visible in Texas and California, where multi-hospital systems command sufficient patient volume to justify dedicated laboratory automation infrastructure.
Global Sepsis Diagnostics Market Segmentation
Sepsis diagnostics segmentation reveals how regulatory pathways, testing workflows, and care settings fragment procurement authority. Product and technology categories carry distinct FDA and EU MDR validation burdens, while application and end-user dimensions determine reimbursement eligibility and capital deployment priorities.
Product Type:
FDA breakthrough device designation and EU MDR post-market surveillance obligations vary sharply across product categories, with molecular platforms facing the steepest clinical validation requirements.
- Molecular Diagnostics:Nucleic acid amplification platforms detect polymicrobial bloodstream infections through multiplexed pathogen identification. Demand concentrates in United States academic medical centers where antimicrobial stewardship committees mandate rapid pathogen identification for broad-spectrum antibiotic de-escalation. FDA breakthrough pathway compresses review timelines for assays demonstrating impact on time-to-appropriate-therapy.
- Biomarker Assays:Quantitative immunoassays measure procalcitonin, presepsin, and C-reactive protein to assess host immune dysregulation. Hospital emergency departments in Germany and France deploy these for risk stratification alongside clinical scoring systems. EU MDR requires annual safety updates for CE-marked assays, elevating compliance overhead for manufacturers.
- Immunoassays:Enzyme-linked and chemiluminescent formats support high-throughput screening in centralized laboratories.
- Microbial Culture Kits:Conventional blood culture systems remain embedded in laboratory workflows despite longer time-to-result.
Molecular diagnostics sits at the top of the volume ranking, with biomarker assays climbing the fastest as emergency departments decentralize testing.
Technology:
Capital intensity and reagent supply concentration differentiate technology tiers, with automated platforms commanding premium pricing against manual methods.
- Polymerase Chain Reaction:Real-time and digital PCR platforms achieve pathogen detection sensitivity below 10 colony-forming units per milliliter. United States integrated delivery networks in Texas and California negotiate system-wide contracts for automated PCR systems, extracting volume commitments for exclusive platform access. Reagent supply concentrates in South Korean and Taiwanese contract manufacturing facilities.
- Microfluidics:Lab-on-chip architectures integrate sample preparation, amplification, and detection in disposable cartridges. Point-of-care facilities in Australian rural health systems adopt these platforms to address clinical laboratory scientist shortages. Per-test economics improve with cartridge manufacturing scale.
- Enzyme-Linked Immunosorbent Assay:Plate-based and automated chemiluminescent formats dominate high-volume biomarker quantification.
- Flow Cytometry:Cell-based pathogen detection and immune profiling support research and specialized clinical applications.
- Mass Spectrometry:MALDI-TOF platforms accelerate microbial identification from culture isolates in reference laboratories.
PCR technology captures the largest installed base, while microfluidics gains share fastest through point-of-care expansion.
Application:
Reimbursement coding and clinical utility evidence requirements fragment application segments, with early detection commanding the strongest payor support.
- Early Detection:Rapid pathogen and biomarker identification within the first hour of emergency department presentation. United States hospital pharmacy committees require documented early detection for broad-spectrum antibiotic justification beyond 48 hours. CMS reimbursement codes increasingly tie coverage to time-to-result thresholds.
- Therapy Guidance:Antimicrobial resistance profiling and therapeutic drug monitoring inform antibiotic selection and dosing. Tertiary care centers in India's NABH-accredited hospitals procure integrated workflows combining pathogen identification with resistance gene detection. Federal procurement specifications in Brazil's SUS modernization program prioritize therapy guidance capabilities.
- Prognosis Monitoring:Serial biomarker measurement tracks treatment response and complications.
- Risk Stratification:Predictive algorithms combining clinical and laboratory data identify high-mortality-risk patients.
Early detection leads application volume, with therapy guidance expanding most quickly through antimicrobial stewardship mandates.
End User:
Facility type determines capital availability, staffing requirements, and regulatory jurisdiction, concentrating molecular platform adoption in hospital-affiliated laboratories.
- Point-of-Care Facilities:Emergency departments, intensive care units, and satellite clinics deploy compact molecular and biomarker platforms. Decentralization reduces time-to-antibiotic initiation from hours to under 60 minutes in high-acuity United States settings. FDA CLIA-waived assay designations accelerate deployment in settings lacking certified laboratory personnel.
- Clinical Laboratories:Hospital-based and reference laboratories operate high-throughput automated systems with dedicated HVAC infrastructure and continuous monitoring capabilities. Smaller community hospitals in Australia face capital constraints for blood culture instrument footprint requirements.
- Diagnostic Centers:Independent laboratories process outpatient sepsis screening and monitoring.
- Research Institutes:Academic medical centers pilot next-generation sequencing panels for immunocompromised patient populations.
Clinical laboratories maintain the largest test volume, with point-of-care facilities gaining share fastest through emergency department decentralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified medical laboratory scientists concentrate in the United States, Germany, and Japan, anchoring molecular diagnostics deployment. Regulatory frameworks in these markets compress validation timelines while procurement consolidation reshapes vendor access.
United States
Integrated delivery networks in Texas and California command system-wide contracts for automated PCR platforms, extracting exclusive platform commitments. FDA breakthrough device designation accelerates review for assays demonstrating time-to-appropriate-therapy impact. Hospital pharmacy committees in academic medical centers now mandate rapid pathogen identification for broad-spectrum antibiotic justification beyond 48 hours.
Germany
University hospitals pilot next-generation sequencing panels for immunocompromised patient populations, unifying bacterial and fungal detection workflows. EU MDR post-market surveillance mandates require annual safety and effectiveness updates to notified bodies for CE-marked assays. The Baden-Württemberg industrial cluster embeds remote diagnostic capabilities in blood culture instruments for predictive maintenance compliance.
Japan
PMDA regulatory pathways align with antimicrobial stewardship protocols prioritized in WHO sepsis guidelines, shaping procurement in tertiary care centers. Hospital emergency departments deploy procalcitonin quantification alongside clinical scoring systems for risk stratification. The Kanto region around Tokyo concentrates reference laboratory automation infrastructure serving multi-hospital networks.
India
NABH certification requirements for tertiary care centers create procurement pull for integrated sepsis diagnostic workflows combining pathogen identification with resistance gene detection. CDSCO regulatory frameworks govern in vitro diagnostic import and local manufacturing licensing. Maharashtra's hospital networks in Mumbai and Pune lead adoption of rapid molecular panels through private healthcare expansion.
Brazil
Federal procurement tenders under SUS diagnostic modernization specify rapid molecular panels, opening volume contracts for qualified suppliers. ANVISA registration requirements structure market entry for multinational device manufacturers. São Paulo's tertiary hospital concentration drives demand for therapy guidance capabilities in antimicrobial resistance profiling.
Global Sepsis Diagnostics Market Competitive Landscape
Top-tier vendors anchor hospital-affiliated laboratory networks, while mid-scale specialists occupy point-of-care and regional reference lab segments. The competitive structure stratifies across full-platform integrators, reagent-focused suppliers, and automation hardware fabricators. Dominant competitive moves include strategic partnerships for laboratory information system integration and portfolio diversification into host response biomarker convergence.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc., Abbott Laboratories, and bioMérieux SA exemplify distinct archetype positioning. Thermo Fisher Scientific Inc. represents the broad biomarker assay portfolio model spanning hospital and reference lab networks. Abbott Laboratories occupies a position emphasizing point-of-care footprint and emergency department channel control. bioMérieux SA anchors the specialized blood culture automation systems tier, reflecting European industrial concentration in clinical microbiology infrastructure.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Abbott Laboratories |
| bioMérieux SA |
| QIAGEN N.V. |
| Bruker Corporation |
| Becton Dickinson and Company |
| F. Hoffmann-La Roche Ltd |
| T2 Biosystems |
| Danaher Corporation |
| Others |
Supply & Pricing Matrix
CE-marking tier divergence between automated molecular platforms and manual microbial culture methods manifests in both procurement premiums and supply chain complexity. Premium-tier manufacturers absorb EU MDR post-market surveillance costs through bundled service contracts, while commodity-tier suppliers face margin compression from reagent sourcing volatility in South Korean and Taiwanese contract manufacturing facilities.
Pricing Analysis
Bundled reagent rental agreements dominate automated PCR platform pricing, separating capital-light subscription models from traditional instrument purchase arrangements. Price differentiation rests on FDA breakthrough designation status and integrated laboratory information system connectivity. Cost compression in point-of-care cartridge manufacturing intensifies as microfluidics suppliers achieve production scale. Academic medical centers in the United States exhibit lowest price sensitivity due to antimicrobial stewardship mandate compliance requirements, while rural Australian health systems prioritize per-test economy.
Supply Chain Analysis
Dual-sourcing qualification requirements for nucleic acid extraction kits and PCR master mixes compel manufacturers to maintain approved vendor relationships across South Korea, Taiwan, and Singapore. Raw material dependencies center on fluorophore-labeled oligonucleotides, heat-stable polymerase enzymes, and medical-grade polymer substrates. Single-source vulnerability concentrates in specialized microfluidic cartridge molding equipment. Distribution runs through integrated delivery network procurement consortia in Texas and California, with regional reference laboratories serving as secondary fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory validation cost arbitrage between FDA breakthrough pathway timelines and EU MDR post-market surveillance burdens creates geographic production incentives. Manufacturers can optimize compliance expenditure by sequencing market entry across jurisdictions with divergent clinical evidence requirements.
For Market Incumbents: To counter next-generation sequencing panel displacement of standalone blood culture systems, Abbott Laboratories and bioMérieux SA should deepen in-house production of host response biomarker assays while securing exclusive platform commitments through integrated delivery network contracts. Channel control in emergency department settings remains the priority lever against point-of-care molecular entrants. For New Entrants and Emerging Players: Capture NABH-accredited tertiary care procurement in Maharashtra and São Paulo's SUS modernization tenders through localized regulatory registration and therapy guidance capability bundling. Brazil's federal volume contracts represent the most penetrable entry vector for qualified suppliers lacking established United States academic medical center relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where laboratory information system integration capabilities fragment vendor competitiveness. Long-term viability in this market hinges on single-platform assay convergence combining pathogen identification with antimicrobial resistance profiling. Acquisition targets with embedded remote diagnostic capabilities for predictive maintenance compliance signal platform durability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR post-market surveillance mandates require annual safety updates to notified bodies. |
| Hospital System Partnership | Texas and California integrated delivery networks extract volume discounts for exclusive commitments. |
| Reimbursement Strategy | CMS coverage codes increasingly tie payment to time-to-result thresholds under 60 minutes. |
| Software Companion Development | Laboratory information system integration delays deployment in multi-hospital networks. |
| FDA Submission | Breakthrough device designation compresses review timelines for antibiotic decision-impact assays. |
Research Methodology
Direct dialogue with hospital pharmacy committee chairs, clinical laboratory directors, infectious disease specialists, and GPO contracts managers grounded this analysis in operational procurement realities. Secondary validation drew from FDA 510(k) filings, CMS reimbursement code updates, EU MDR notified body guidance documents, and hospital procurement database extracts. Bottom-up test volume modeling and top-down market sizing triangulated demand estimates across the analysis window.
Segment-level outputs reflect product type, technology platform, application purpose, and end-user facility modeling across the projection horizon. CAGRs were derived from installed base expansion rates and per-test pricing trajectories in molecular diagnostics and biomarker assay categories. Antimicrobial stewardship protocol adoption curves and point-of-care decentralization penetration served as industry-specific forecast inputs.
Regulatory pathway delays, reagent supply disruptions, and reimbursement code recalibrations are the dominant revision risks to the outlook. Deviation in FDA breakthrough designation granting velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global STD Diagnostics Market
Diagnostics
Melanoma Cancer Diagnostics Market
Diagnostics
Global Stroke Diagnostics Market
Diagnostics
IVD Antibody Market
Diagnostics
HDL Cholesterol Kits Market
Diagnostics
Global Respiratory Diagnostics Market
Diagnostics
Thrombosis and Hemostasis Biomarkers Market
Diagnostics
Shrimps Disease Diagnostics Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
RT-PCR Kits Market
Diagnostics
Respiratory Pathogen Testing Kits Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
Canada in-Vitro Diagnostics Market
Diagnostics
Viral Molecular Diagnostics Market
Diagnostics
Point of Care (Poc) Molecular Diagnostics Market