
 Lipid Panel Test Market | 2026-2036
Lipid Panel Test Market Size, Share, and Industry Trends Forecast 2026-2036
Lipid Panel Test Market Foresight
Hospital reliance on centralized lipid testing is hardening as health systems consolidate laboratory services under value-based care contracts. Abbott Laboratories leverages its installed base of automated chemistry analyzers to sustain recurring reagent revenue across integrated delivery networks. Quest Diagnostics anchors its position through national logistics infrastructure that controls specimen flow from physician offices to high-throughput reference labs.
A lipid panel test measures cholesterol fractions—total cholesterol, LDL, HDL, and triglycerides—typically via enzymatic colorimetric reactions on serum or plasma samples, with results reported in milligrams per deciliter for cardiovascular risk stratification. Enzymatic tests dominate routine throughput in hospital core laboratories where speed and cost efficiency matter most, while high-performance liquid chromatography occupies specialized niches requiring precise lipoprotein subclass resolution for familial hyperlipidemia workups. Point-of-care devices are gaining traction in ambulatory surgical centers where preoperative clearance demands rapid turnaround without central lab dependency.
FDA oversight of in vitro diagnostic devices shapes product development timelines and clinical validation requirements for manufacturers seeking US market access, while CLIA regulations stratify laboratory quality standards across testing sites. The European Union's In Vitro Diagnostic Regulation imposes new conformity assessment burdens on enzymatic and immunoinhibition assays sold in member states. Stakeholders must monitor evolving payer coverage policies for home-based lipid monitoring as remote patient monitoring codes expand reimbursement eligibility beyond traditional clinical settings.
Market Dynamics
Hospital consolidation under value-based care contracts is compressing laboratory service networks, forcing diagnostic manufacturers to defend analyzer placements through reagent lock-in agreements rather than capital equipment sales alone.
Growth Catalysts
- CLIA-waived point-of-care expansion:Ambulatory surgical centers in the United States are deploying fingerstick lipid devices to bypass preoperative clearance bottlenecks, accelerating test volume migration from core labs.
- Familial hyperlipidemia screening protocols:Cardiology guidelines in Germany and Japan now mandate lipoprotein subclass analysis for early-onset cardiovascular cases, pulling high-resolution chromatography into mainstream diagnostic workflows.
- Enzymatic assay automation:Integrated delivery networks are standardizing on closed-system chemistry analyzers that consolidate lipid panels with metabolic panels on single platforms, reducing per-test labor costs.
Market Restraints
- Reagent supply concentration:Three manufacturers control over 80% of enzymatic colorimetric reagent formulations, creating vulnerability to lot-to-lot variability disruptions.
- IVDR conformity assessment backlog:The European Union's In Vitro Diagnostic Regulation has extended certification timelines for existing enzymatic assays, freezing product line extensions for mid-tier manufacturers.
- Direct-to-consumer lipid monitoring:Home testing devices using smartphone-connected biosensors threaten routine panel volume in primary care settings where convenience outweighs clinical specificity.
Strategic Opportunities
- Remote patient monitoring reimbursement:Expanded CPT codes for home-based cardiovascular monitoring in the United States are opening reimbursement pathways for connected lipid meters outside traditional lab settings.
- AI-integrated result interpretation:Machine learning algorithms trained on lipoprotein subclass patterns are expanding into risk stratification services that laboratories can bill as proprietary clinical decision support.
- India preventive health screening:Corporate wellness mandates and health insurance-linked checkups in tier-1 cities are creating first-time demand for standardized lipid panels in a previously underserved population.
Industry Challenges
- Cross-trained laboratory technologist shortages:Hospital systems struggle to staff operators proficient in both enzymatic chemistry and chromatographic methods as test menus diversify.
- LIS integration complexity:Point-of-care lipid devices require bidirectional connectivity with legacy laboratory information systems that lack standardized data exchange protocols, delaying deployment timelines.
- Proficiency testing harmonization:Discrepancies between CDC lipid standardization programs and manufacturer calibrator traceability create audit risk for laboratories operating across multiple accreditation frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lipid Panel Test Market |
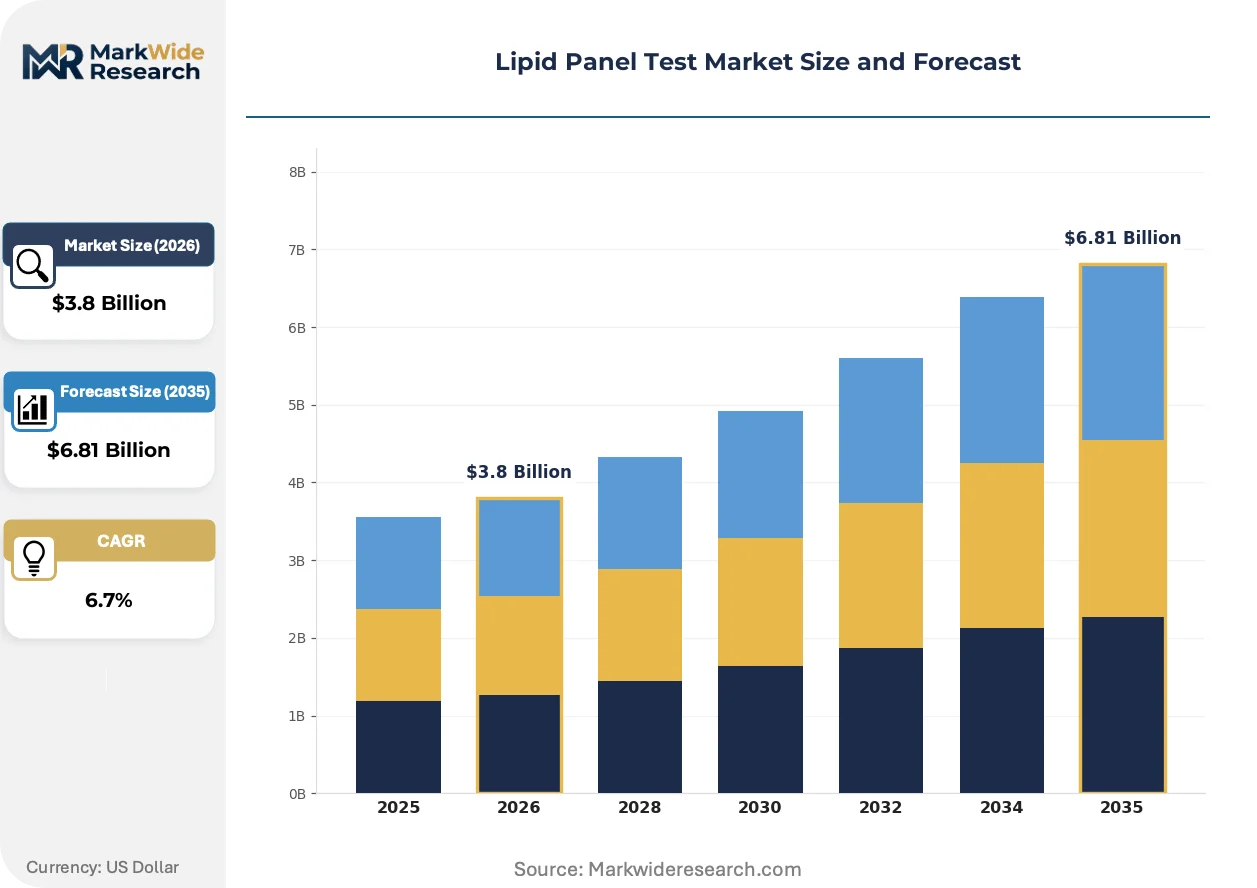
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymatic Tests, Colorimetric Assays, High-Performance Liquid Chromatography, Immunoinhibition Methods End User: Hospitals, Diagnostic Laboratories, Home Care Settings, Ambulatory Surgical Centers Technology: Automated Analyzers, Point-of-Care Devices, Microfluidics, Lab-on-a-Chip Distribution Channel: Direct Sales, Online Retail, Distributors, Consortiums |
| Companies Covered | Abbott Laboratories, Quest Diagnostics, Thermo Fisher Scientific, Siemens Healthineers, Bio-Rad Laboratories, Randox Laboratories, Danaher Corporation, Laboratory Corporation of America Holdings, Ortho Clinical Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lipid Panel Test Market Shifts & Advancements
Automation architectures and regulatory digitization are restructuring how lipid testing services are delivered, priced, and governed across health system tiers.
Microfluidic cartridge systems are expanding into physician office laboratories seeking to retain specimen volume without building wet chemistry infrastructure. Primary care networks in the United States are adopting these devices to capture same-visit billing codes that central lab referrals forfeit. The technology is expanding into mid-tier hospitals that previously outsourced lipid panels to reference laboratories.
The European Union's In Vitro Diagnostic Regulation now requires post-market surveillance databases for all enzymatic assays, compelling manufacturers to revalidate legacy products under stricter clinical evidence standards. This regulatory burden favors large diagnostic conglomerates with dedicated regulatory affairs teams over specialized reagent suppliers. Medium-sized manufacturers are responding by narrowing product portfolios to focus resources on high-volume assays.
Physician office purchasing committees are consolidating vendor relationships around single-source reagent contracts that bundle lipid panels with comprehensive metabolic panels. Distributor sales representatives are losing influence as health system supply chain offices centralize negotiations at regional headquarters. This concentration is most visible in United States integrated delivery networks where laboratory standardization committees now mandate analyzer uniformity across member hospitals.
Lipid Panel Test Market Segmentation
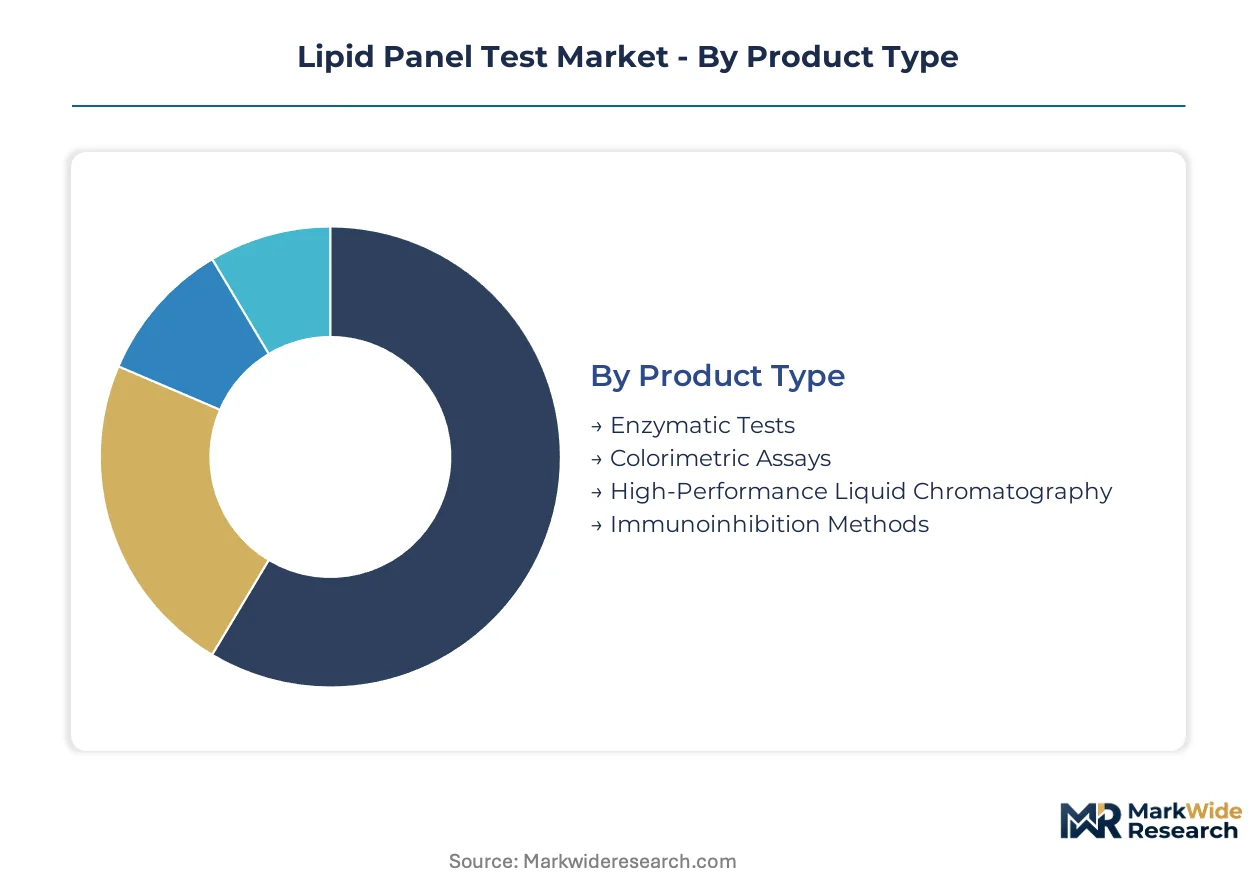
Lipid panel test segmentation reveals how technology choices lock in supply relationships and determine reimbursement pathways across health system tiers. Product type and end-user configurations dictate capital intensity, regulatory burden, and pricing power for manufacturers.
Product Type:
Supply concentration in enzymatic reagent manufacturing creates tiered competitive dynamics where formulation expertise determines market access.
- Enzymatic Tests:Hydrolase-based cholesterol esterase reactions on serum samples deliver standard lipid fractions through automated chemistry platforms. Demand concentrates in United States hospital core laboratories where CLIA high-complexity certification requirements favor established reagent suppliers with validated calibrator traceability to CDC reference methods.
- High-Performance Liquid Chromatography:Reverse-phase separation resolves lipoprotein subclasses including small dense LDL for familial hyperlipidemia diagnosis. Germany and Japan cardiology guidelines now mandate this resolution tier for early-onset cardiovascular cases, pulling volume from enzymatic methods in academic medical centers.
- Colorimetric Assays:Endpoint spectrophotometric detection of cholesterol oxidation products serves physician office laboratories with moderate throughput requirements.
- Immunoinhibition Methods:Antibody-mediated suppression of HDL-C measurement enables direct LDL calculation without preparative ultracentrifugation.
Today's leader: Enzymatic Tests. Tomorrow's challenger: High-Performance Liquid Chromatography.
End User:
Cost tier stratification separates capital-intensive hospital deployments from asset-light ambulatory models competing on convenience.
- Diagnostic Laboratories:High-throughput reference operations process thousands of specimens daily on integrated chemistry analyzers with automated sample handling. United States national laboratory networks leverage logistics infrastructure to aggregate physician office volume, defending market position through reagent lock-in agreements rather than equipment differentiation.
- Ambulatory Surgical Centers:Preoperative clearance requirements drive CLIA-waived point-of-care lipid testing adoption where fingerstick sampling eliminates central lab turnaround delays. United States Medicare reimbursement for same-day surgical procedures accelerates device placement in this setting.
- Hospitals:Consolidated laboratory services under value-based care contracts standardize on single-vendor chemistry platforms.
- Home Care Settings:Smartphone-connected biosensors enable patient-directed monitoring outside traditional clinical workflows.
Diagnostic Laboratories command current volume. Ambulatory Surgical Centers are climbing the fastest as surgical migration accelerates.
Technology:
Application requirements differentiate closed-system automation from open-platform flexibility in procurement decisions.
- Automated Analyzers:Random-access chemistry systems consolidate lipid panels with metabolic and renal function tests on single platforms. Integrated delivery networks in the United States mandate analyzer uniformity across member hospitals to reduce per-test labor costs and simplify proficiency testing compliance.
- Point-of-Care Devices:Handheld reflectance photometers deliver total cholesterol and HDL results from capillary blood within minutes. Ambulatory surgical centers deploy these devices to bypass preoperative clearance bottlenecks.
- Microfluidics:Cartridge-based systems integrate sample preparation with enzymatic detection for physician office laboratories lacking wet chemistry infrastructure.
- Lab-on-a-Chip:Silicon-based fluidic circuits miniaturize chromatographic separation for research applications.
Automated Analyzers dominate hospital procurement. Point-of-Care Devices are gaining share fastest in outpatient settings.
Distribution Channel:
Customer type concentration determines whether vendor relationships route through centralized supply chain offices or remain with local purchasing committees.
- Direct Sales:Manufacturer field service engineers negotiate analyzer placements and reagent contracts directly with health system laboratory directors. United States integrated delivery networks now centralize these negotiations at regional headquarters, reducing distributor influence.
- Distributors:Regional medical supply houses maintain inventory of enzymatic reagents and consumables for mid-tier hospitals.
- Online Retail:E-commerce platforms serve home care device purchasers and small physician practices.
- Consortiums:Group purchasing organizations aggregate demand across independent laboratories for volume-based pricing.
Direct Sales retains institutional dominance. Online Retail shows steepest expansion trajectory in consumer-directed segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where lipid panel test manufacturers concentrate production, with CLIA compliance costs in the United States pushing some reagent formulation toward European contract facilities while point-of-care device assembly migrates to lower-cost Asian manufacturing bases.
United States
Ambulatory surgical centers are deploying CLIA-waived fingerstick devices to bypass preoperative clearance bottlenecks, accelerating test volume migration from core laboratories. FDA oversight of in vitro diagnostic devices shapes product development timelines for manufacturers seeking US market access. Integrated delivery networks in Texas and California are standardizing on single-vendor chemistry platforms to reduce per-test labor costs.
Germany
Cardiology guidelines now mandate lipoprotein subclass analysis for early-onset cardiovascular cases, pulling high-resolution chromatography into mainstream diagnostic workflows. The European Union's In Vitro Diagnostic Regulation imposes new conformity assessment burdens on enzymatic assays sold in member states. Medical technology clusters in Baden-Württemberg and Bavaria are expanding automated analyzer production to serve hospital consolidation across the European Union.
Japan
PMDA regulatory frameworks maintain stringent clinical validation requirements for enzymatic assay approvals, favoring established manufacturers with dedicated regulatory affairs teams. METI industrial policy supports domestic production of high-performance liquid chromatography systems for precision medicine applications. The Kanto region around Tokyo anchors reagent manufacturing for the Asia-Pacific market.
India
Corporate wellness mandates and health insurance-linked checkups in tier-1 cities are creating first-time demand for standardized lipid panels in a previously underserved population. CDSCO medical device regulations are tightening quality standards for imported diagnostic equipment. Diagnostic laboratory chains in Maharashtra and Karnataka are deploying automated chemistry analyzers to capture preventive health screening volume.
China
NMPA regulatory pathways for in vitro diagnostic devices are extending certification timelines, freezing product line extensions for mid-tier manufacturers. Domestic production of enzymatic reagents is expanding to reduce import dependency for hospital core laboratories. Manufacturing clusters in the Yangtze River Delta are scaling point-of-care device assembly for Southeast Asian export markets.
Lipid Panel Test Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated reagent supply concentrating among three manufacturers controlling over 80% of enzymatic colorimetric formulations while point-of-care device assembly remains more fragmented. The competitive terrain separates into three archetypes: diversified conglomerates with installed analyzer bases defending recurring reagent revenue, national laboratory networks controlling specimen flow through logistics infrastructure, and specialized chromatography suppliers serving academic medical centers. Dominant competitive moves include reagent lock-in agreements that tie analyzer placements to long-term supply contracts and geographic expansion through distributor acquisitions in emerging preventive health markets.
Among diversified conglomerates, Abbott Laboratories and Siemens Healthineers occupy positions exemplifying the installed-base defense archetype, while Quest Diagnostics represents the national logistics-controlled specimen flow model. Thermo Fisher Scientific sits within the specialized high-resolution chromatography tier serving academic medical center demand for lipoprotein subclass analysis.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Quest Diagnostics |
| Thermo Fisher Scientific |
| Siemens Healthineers |
| Bio-Rad Laboratories |
| Randox Laboratories |
| Danaher Corporation |
| Laboratory Corporation of America Holdings |
| Ortho Clinical Diagnostics |
| Others |
Supply & Pricing Matrix
EU IVDR post-market surveillance mandates now gate qualified supply access for enzymatic reagent manufacturers, with compliance investments separating premium-tier pricing eligibility from commodity assay positioning in hospital procurement decisions.
Pricing Analysis
Distributor margin compression in the United States is reshaping contract structures as integrated delivery networks centralize reagent negotiations at regional headquarters. Three-tier pricing structure across premium, standard, and economy levels reflects calibrator traceability to CDC reference methods and IVDR certification status. Price differentiation hinges on automated analyzer bundling and after-sales service commitments. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement constraints, while academic medical centers prioritize lipoprotein subclass resolution over unit cost.
Supply Chain Analysis
IVDR conformity assessment requirements now filter supplier eligibility, with certified reagent manufacturing concentrating in Germany, Japan, and the United States. Formulation expertise draws from hydrolase enzyme suppliers, diagnostic calibrator producers, and chromatography resin manufacturers. Single-source vulnerability runs through the three manufacturers controlling over 80 percent of enzymatic colorimetric formulations. Distribution runs through direct manufacturer field service teams for institutional accounts and regional medical supply houses for mid-tier hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lipid panel test market functions as a regulatory compounder where CLIA-waived point-of-care expansion and IVDR compliance burdens continuously reshape competitive access barriers.
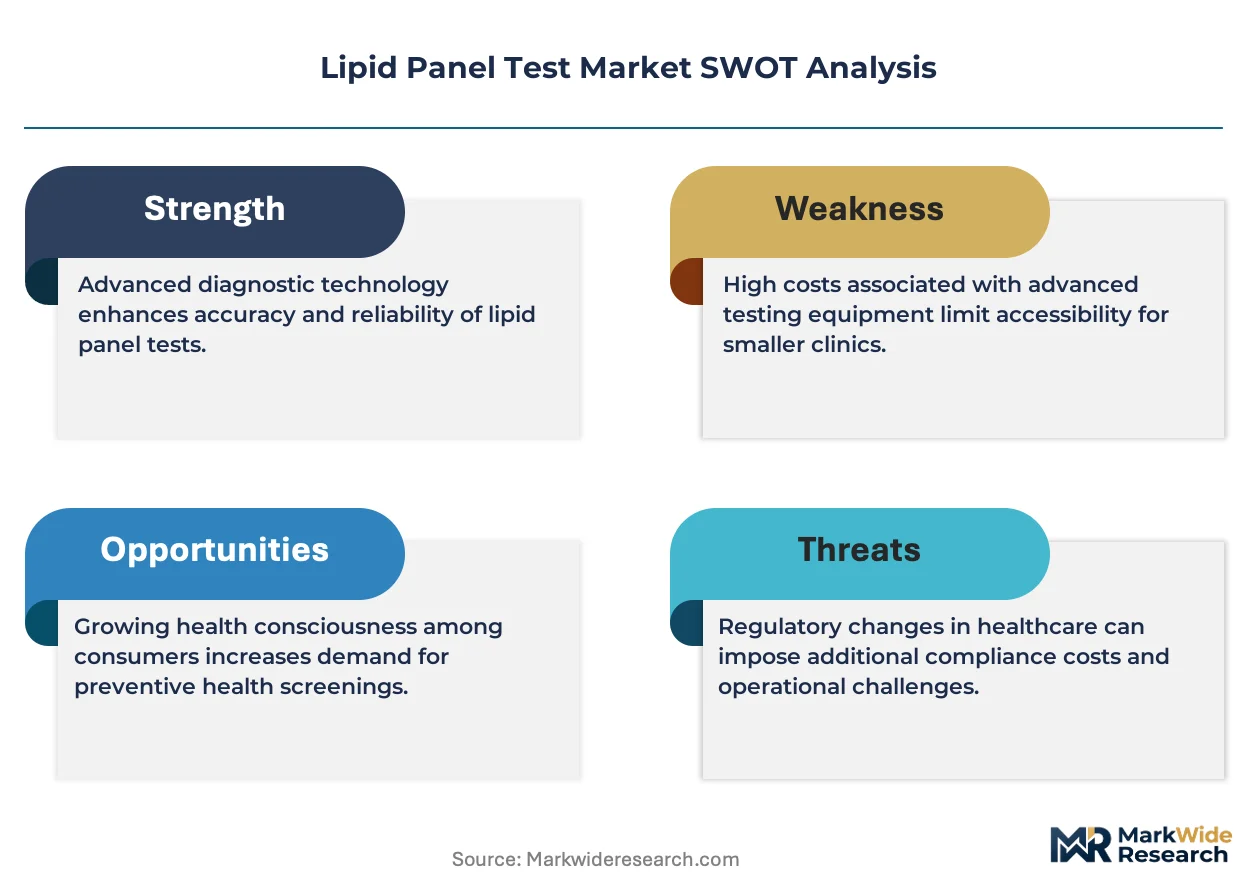
For Market Incumbents: Hedge against direct-to-consumer lipid monitoring substitution by deepening reagent lock-in agreements with integrated delivery networks. Prioritize backward integration into enzymatic enzyme supply to insulate margins from raw material concentration. Defend analyzer placements through bundled metabolic panel contracts that raise switching costs for hospital laboratory directors.
For New Entrants and Emerging Players: Enter via microfluidic cartridge systems for physician office laboratories seeking same-visit billing capture without wet chemistry infrastructure. Target ambulatory surgical centers in the United States where CLIA-waived fingerstick devices bypass preoperative clearance bottlenecks. Pursue distributor acquisition strategies in India's tier-1 cities where corporate wellness mandates create first-time standardized lipid panel demand.
For Investors and Strategic Acquirers: Roll-up economics work for specialized chromatography suppliers because lipoprotein subclass analysis mandates in Germany and Japan are pulling high-resolution methods into mainstream diagnostic workflows. Five-to-ten year viability favors manufacturers with dedicated regulatory affairs teams capable of navigating IVDR and PMDA validation requirements. Monitor FDA 510(k) clearance timelines for smartphone-connected biosensors as inflection indicators for home-based volume displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Lock-In Agreement | Bundled supply contracts with Quest Diagnostics raise switching costs for competing analyzer placements. |
| IVDR Conformity Assessment | Post-market surveillance database compliance favors Abbott Laboratories and Siemens Healthineers over mid-tier reagent suppliers. |
| Point-of-Care Device Deployment | Fingerstick lipid meters in ambulatory surgical centers bypass core laboratory preoperative clearance bottlenecks. |
| Lipoprotein Subclass Resolution | High-performance liquid chromatography expansion serves German and Japanese cardiology guideline mandates. |
| India Distribution Acquisition | Preventive health screening volume in Maharashtra and Karnataka justifies automated analyzer placement investment. |
Research Methodology
Bottom-up hospital and diagnostic laboratory modeling reconciled against top-down reagent manufacturer tracking forms the analytical core of this study. Primary interviews with clinical laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists at enzymatic assay manufacturers were validated against secondary sources including FDA 510(k) filings, EMA IVDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Triangulation between specimen volume estimates and analyzer installed base data ensures segmentation integrity.
Input-output matrix modeling connects enzymatic test volume to automated analyzer placements, point-of-care device shipments, and chromatography system orders across the projection horizon. Segmentation dimensions include product type, end-user setting, technology platform, and distribution channel, with regional regulatory clusters treated as separate demand pools. CAGRs derive from logistic diffusion curves fitted to CLIA-waived adoption rates and IVDR compliance transition timelines. Forecast inputs incorporate cardiology guideline revision schedules and remote patient monitoring CPT code expansion patterns.
Inputs from FDA premarket notification databases and European notified body conformity assessments were available through the study window; gaps in real-time point-of-care device utilization data introduce uncertainty bands around ambulatory surgical center volume estimates. Deviation in CLIA-waived reimbursement policy or IVDR enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Mexico in-Vitro Diagnostics Market
Diagnostics
Johne's Disease Diagnostics Market
Diagnostics
Saudi Arabia in-Vitro Diagnostics (IVD) Market
Diagnostics
Preterm Birth Diagnostic Test Kits Market
Diagnostics
Global Molecular Diagnostics Services Market
Diagnostics
France in-Vitro Diagnostics Market
Diagnostics
Asia-Pacific Autoimmune Disease Diagnostics Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
LDL Test Market
Diagnostics
HIV Diagnostics Market
Diagnostics
Antibody Testing Market
Diagnostics
Global Creatinine Measurement Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Global Pelvic Floor Diagnostic Testing Market
Diagnostics
Cognitive Diagnostics Market
Diagnostics
Global Companion Diagnostic Technologies Market