
 Diagnostic Reagents Market | 2026-2036
Diagnostic Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Diagnostic Reagents Market Analysis
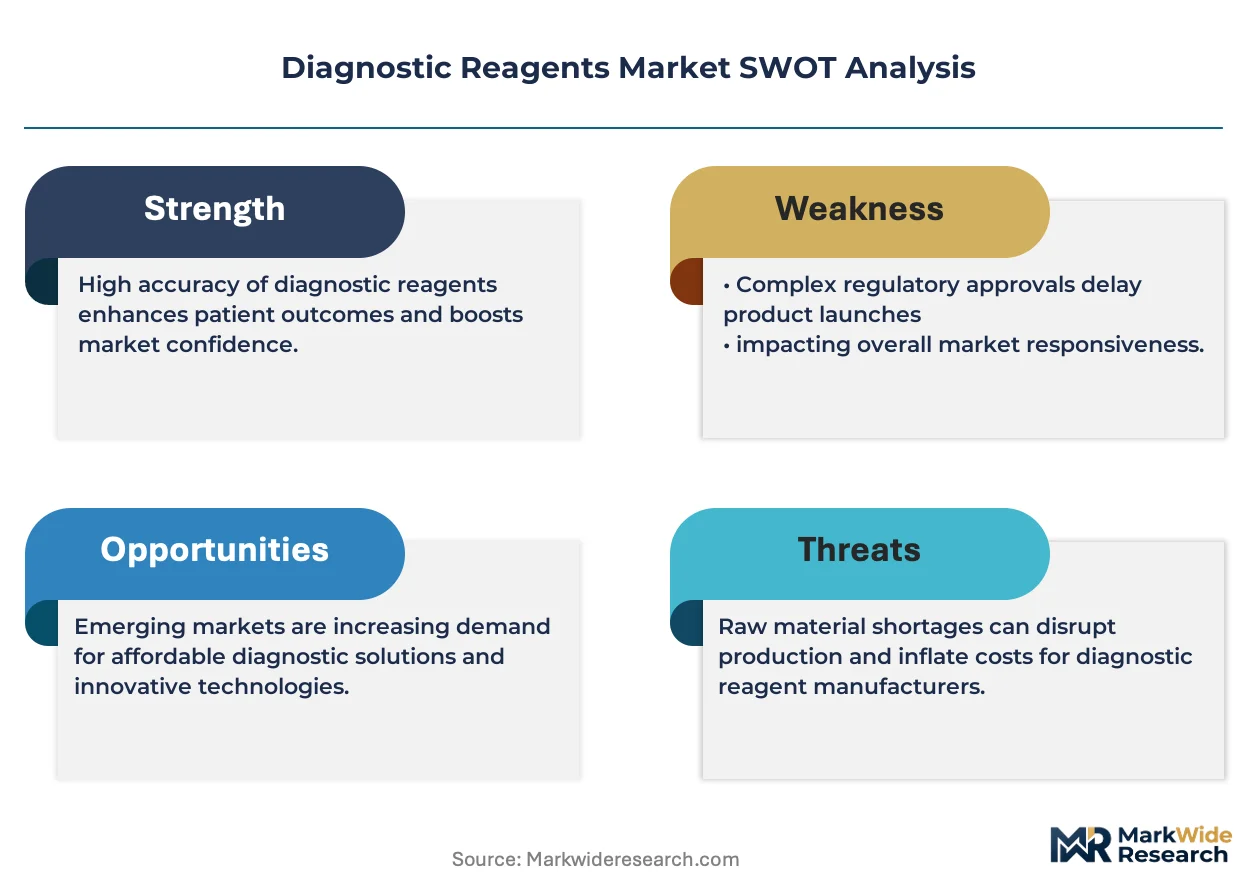
The EU Green Deal is decoupling diagnostic reagent procurement from single-source supply dependencies across European hospital networks. F. Hoffmann-La Roche Ltd leverages its captive antibody production infrastructure to sustain margin stability. Thermo Fisher Scientific Inc. anchors its position through integrated raw-material-to-kit workflows. Danaher Corporation differentiates via automated liquid-handling platforms that reduce laboratory technician labor.
Diagnostic reagents comprise purified biochemical substances—enzymes, antibodies, nucleic acid probes, and control calibrants—formulated to detect, measure, or monitor target analytes in clinical specimens with defined sensitivity and specificity thresholds. These substances enable standardized detection protocols that underpin disease screening, therapeutic monitoring, and epidemiological surveillance across healthcare systems. Assay kits command the largest revenue pool due to bundled consumable-discipline economics, while PCR-based reagents represent the fastest-expanding technology segment driven by infectious-disease panel proliferation. Clinical diagnostics absorbs the majority of end-user spending, though home-care lateral-flow applications are gaining traction through decentralized testing mandates.
EMA's In Vitro Diagnostic Regulation and FDA's quality-system requirements for IVD manufacturers impose stringent analytical-validation burdens that filter out undercapitalized entrants. China's NMPA implements tiered registration pathways that favor domestic reagent producers with localized manufacturing footprints. Stakeholders must weigh regulatory-approval timelines against regional manufacturing commitments when allocating capital across geographic portfolios.
Market Dynamics
EMA's In Vitro Diagnostic Regulation is compressing approval timelines while fragmenting manufacturing footprints across European laboratory networks. Reagent producers must simultaneously validate analytical performance and localize production to maintain market access.
Growth Catalysts
- Infectious-disease panel proliferation:PCR-based multiplex assays expand testing menus in clinical laboratories. Hospital procurement networks prioritize bundled reagent contracts covering respiratory, bloodstream, and sexually transmitted pathogen detection.
- China's NMPA tiered registration pathways:Domestic reagent producers accelerate product approvals through localized manufacturing commitments. Foreign manufacturers establish joint ventures to access hospital procurement networks.
- Decentralized testing mandates:Home-care lateral-flow applications gain reimbursement traction. Point-of-care settings absorb reagent volumes previously concentrated in centralized laboratories.
Market Restraints
- Antibody raw material concentration:Captive production infrastructure limits supplier base. F. Hoffmann-La Roche Ltd and integrated competitors control critical monoclonal antibody supply.
- EMA analytical-validation burdens:Stringent performance-documentation requirements filter undercapitalized entrants. Small reagent developers face 18-24 month approval timelines.
- Lyophilized enzyme substitution:Freeze-dried reagent formats reduce cold-chain dependency. Liquid reagent producers confront pricing pressure from shelf-stable alternatives.
Strategic Opportunities
- EU Green Deal supply decoupling:European hospital networks diversify procurement beyond single-source dependencies. Reagent producers with redundant manufacturing sites capture contract preference.
- Automated liquid-handling convergence:Integration of robotics with consumable reagent workflows reduces technician labor. Danaher Corporation's platform architecture demonstrates bundling potential.
- India's CDSCO streamlined pathways:Domestic reagent registration accelerates for manufacturers with local production. Diagnostic chains in Mumbai and Hyderabad expand molecular testing capacity.
Industry Challenges
- Analytical-validation talent scarcity:Clinical laboratories face shortages of regulatory-affairs specialists familiar with EMA's IVDR technical documentation. Training pipelines lag market expansion.
- Legacy LIS integration friction:New reagent platforms require middleware development for hospital information system connectivity. Implementation timelines extend 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diagnostic Reagents Market |
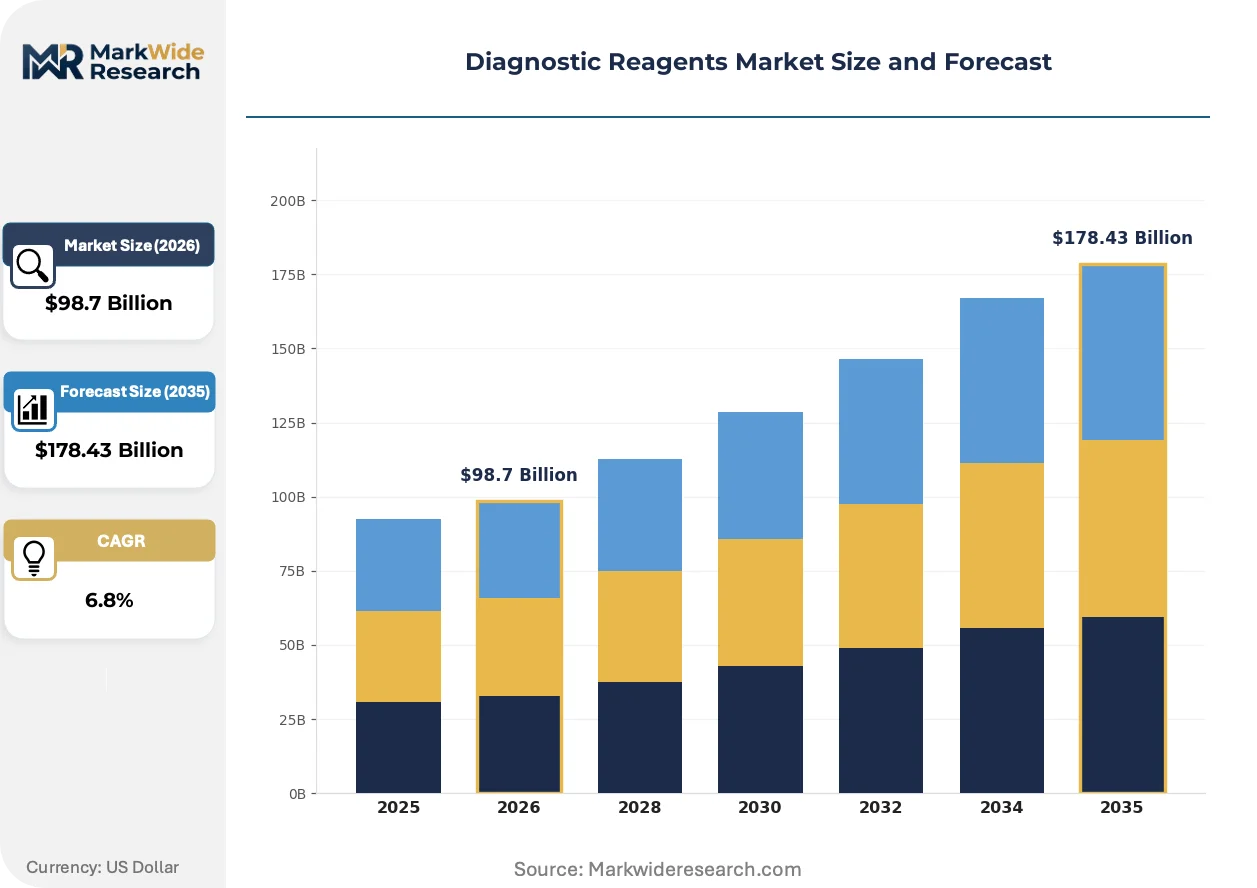
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
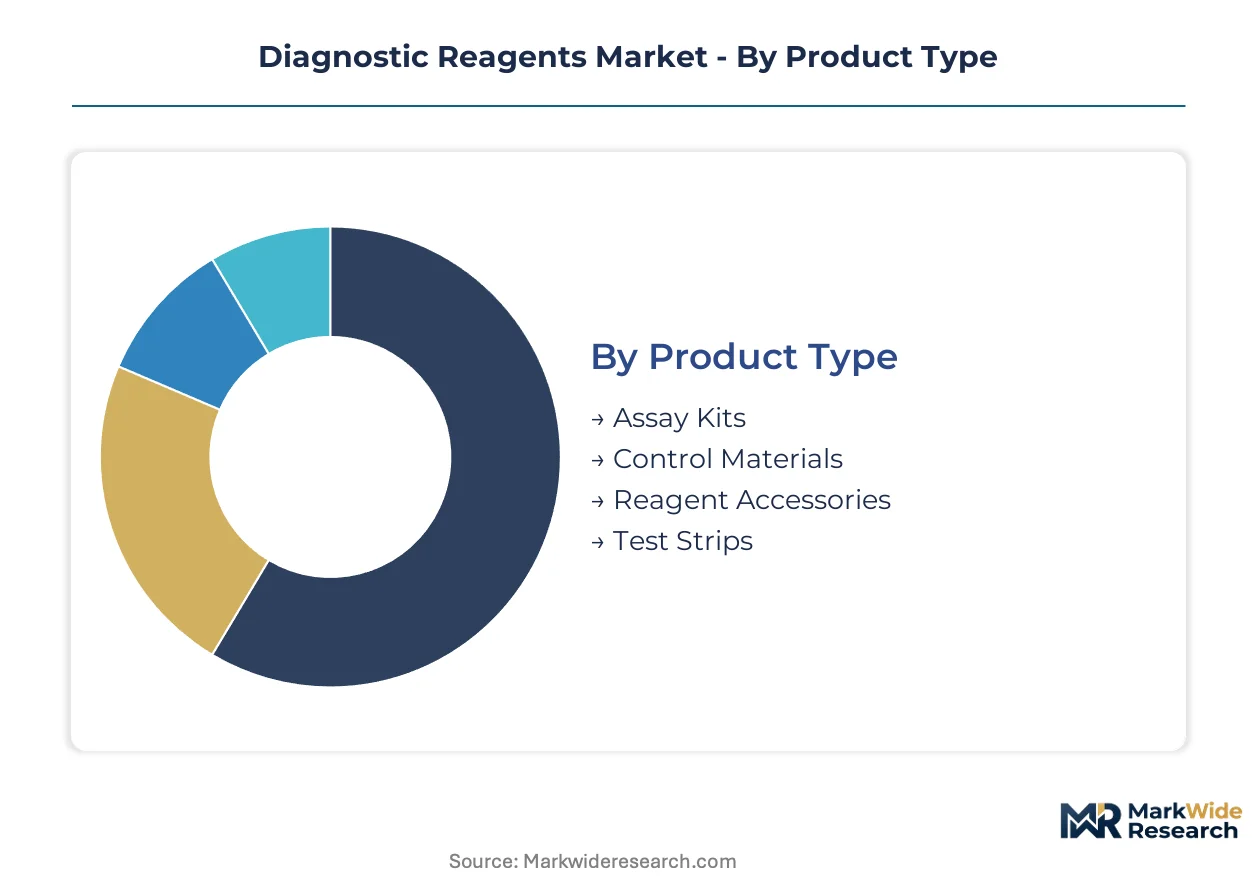
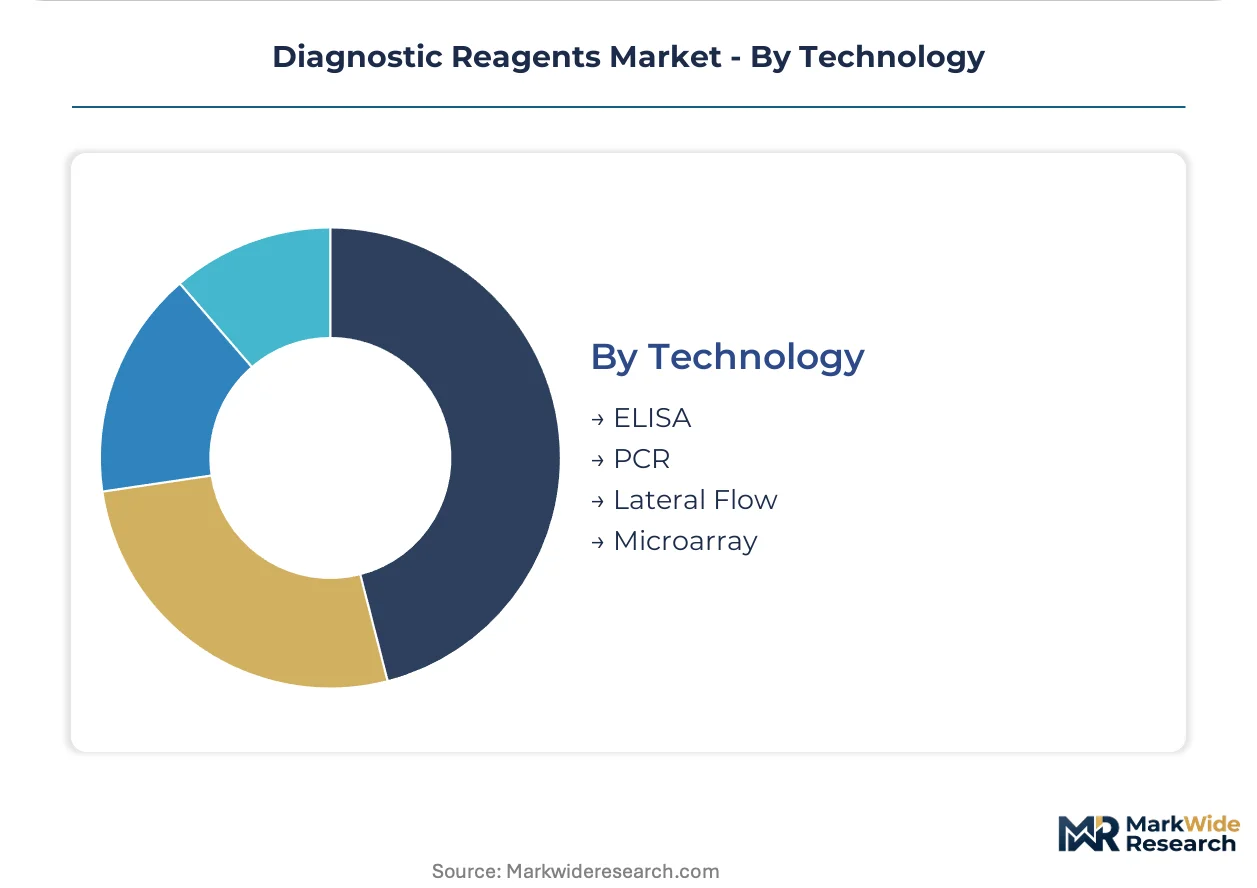
| Segmentation | Product Type: Assay Kits, Control Materials, Reagent Accessories, Test Strips Application: Clinical Diagnostics, Blood Screening, Pathogen Detection, Disease Monitoring End User: Hospitals, Diagnostic Laboratories, Research Institutions, Home Care Technology: ELISA, PCR, Lateral Flow, Microarray |
| Companies Covered | F. Hoffmann-La Roche Ltd, Abbott, Thermo Fisher Scientific Inc., Siemens Healthineers, Danaher Corporation, Becton Dickinson and Company, Hologic, Inc., Bio-Rad Laboratories, Inc., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diagnostic Reagents Market Emerging Trajectories
Reagent formulation and delivery mechanisms are fragmenting testing workflows across point-of-care, hospital laboratory, and home settings. Regulatory frameworks and procurement patterns co-evolve with these technical shifts.
Lyophilized bead-based reagent formats are decentralizing molecular testing infrastructure. Community health clinics and pharmacy chains adopt shelf-stable PCR reagents eliminating ultra-low temperature storage. This format is decentralizing testing capacity from centralized reference laboratories into retail health settings.
EU Green Deal sustainable procurement mandates reshape reagent sourcing criteria across German, French, and Dutch hospital networks. Carbon-footprint disclosure requirements now accompany tender submissions. Reagent producers with renewable-energy manufacturing certifications capture contract preference in Nordic procurement frameworks.
Hospital procurement consolidation compresses vendor panels to three preferred reagent suppliers per analyte category. Group purchasing organizations in China's tier-one cities negotiate exclusive volume commitments. This concentration is most visible in Shanghai and Beijing where municipal health bureaus centralize reagent acquisition for public hospital networks.
Diagnostic Reagents Market Segmentation
Diagnostic reagent segmentation reveals how procurement patterns split across testing workflows and regulatory environments. Product formats, application settings, and technology platforms each command distinct margin structures and replacement cycles.
Product Type:
Upgrade cycles vary sharply by product format, with bundled consumable economics driving hospital procurement decisions.
- Assay Kits:Bundled reagent-discipline combinations dominate hospital procurement networks through volume-commitment contracts. German and Chinese laboratory networks prioritize respiratory and infectious-disease panel configurations under EMA IVDR and NMPA frameworks respectively.
- Control Materials:Calibrants and quality-control reagents anchor analytical-validation protocols for regulatory compliance. Demand concentrates in centralized reference laboratories facing EMA documentation burdens.
- Reagent Accessories:Buffers, diluents, and consumable components support kit workflows.
- Test Strips:Single-use lateral-flow consumables serve decentralized testing expansion.
Volume placements concentrate in Assay Kits; the faster expansion belongs to Test Strips.
Application:
Application segmentation tracks how disease-burden shifts redirect reagent procurement across healthcare settings.
- Clinical Diagnostics:Therapeutic monitoring and routine screening absorb the majority of reagent spending through hospital laboratory networks. Chinese tier-one cities centralize procurement for public hospital systems under municipal health bureau oversight.
- Blood Screening:Transfusion safety and donor testing protocols sustain steady consumable demand.
- Pathogen Detection:PCR-based multiplex panels for respiratory, bloodstream, and sexually transmitted infections represent the technology segment climbing fastest.
- Disease Monitoring:Chronic disease surveillance reagents serve epidemiological tracking mandates.
Procurement scale favors Clinical Diagnostics; Pathogen Detection shows the steepest expansion trajectory.
End User:
End-user structure reflects the decentralization of testing capacity from centralized laboratories toward point-of-care and home settings.
- Hospitals:Acute-care networks command the largest reagent volumes through group purchasing organization negotiations. Consolidated vendor panels in Shanghai and Beijing limit supplier access to three preferred reagent sources per analyte category.
- Diagnostic Laboratories:Independent and hospital-affiliated labs face EMA IVDR analytical-validation requirements.
- Research Institutions:Academic and translational research facilities drive early-stage reagent adoption.
- Home Care:Patient-administered lateral-flow testing gains reimbursement traction under decentralized testing mandates.
Contract value pools in Hospitals; Home Care is gaining share fastest.
Technology:
Technology platforms differentiate by sensitivity thresholds, throughput economics, and regulatory-validation burdens.
- PCR:Nucleic acid amplification underpins infectious-disease panel proliferation across clinical and research settings. Lyophilized bead formats eliminate cold-chain dependency for community health clinic deployment.
- Lateral Flow:Immunochromatographic strips enable rapid point-of-care diagnostics without laboratory infrastructure.
- ELISA:Enzyme-linked immunosorbent assays serve high-throughput serological screening.
- Microarray:Multiplexed nucleic acid detection supports genomic and proteomic research applications.
Installed base concentrates in ELISA; PCR demonstrates the most rapid technology substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors procurement consolidation for diagnostic reagents across China's municipal hospital networks, while Basel and Boston concentrate captive antibody production infrastructure for multinational suppliers.
United States
FDA quality-system requirements for IVD manufacturers compress analytical-validation timelines for domestic reagent developers. Boston-Cambridge clusters anchor monoclonal antibody production for integrated diagnostic firms. Hospital procurement networks in the Northeast prioritize bundled reagent contracts covering infectious-disease panels.
Germany
EMA's In Vitro Diagnostic Regulation fragments manufacturing footprints across Bavarian and North Rhine-Westphalian laboratory networks. EU Green Deal procurement mandates now require carbon-footprint disclosure alongside tender submissions. Siemens Healthineers anchors integrated raw-material-to-kit workflows in Erlangen.
China
NMPA tiered registration pathways accelerate domestic reagent approvals for manufacturers with localized production commitments. Municipal health bureaus in Beijing and Shanghai centralize procurement for public hospital networks. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. exemplifies domestic producers capturing volume through joint ventures.
India
CDSCO streamlined pathways compress registration timelines for reagent manufacturers establishing local production. Diagnostic chains in Mumbai and Hyderabad expand molecular testing capacity for respiratory pathogen detection. Maharashtra's clinical laboratory networks prioritize lyophilized reagent formats eliminating cold-chain dependency.
Japan
PMDA regulatory frameworks sustain premium-margin positioning for domestic reagent producers. Tokyo-Osaka clinical laboratory networks absorb therapeutic monitoring reagents for aging-population disease surveillance. Kanto region hospitals consolidate vendor panels to three preferred suppliers per analyte category.
Diagnostic Reagents Market Vendor Landscape
Premium-margin players sit above commodity-margin players across regulatory-validation and captive-supply dimensions. Integrated conglomerates with antibody production infrastructure defend position against modular reagent developers dependent on external raw material sourcing. Three archetypes dominate: vertically integrated life-science conglomerates, specialized molecular diagnostics firms, and regional contract manufacturers serving procurement networks. Consolidation concentrates through automated liquid-handling platform acquisitions and lyophilized format technology licensing.
Within the integrated conglomerate tier, F. Hoffmann-La Roche Ltd and Thermo Fisher Scientific Inc. occupy positions defined by captive antibody production infrastructure and raw-material-to-kit workflow control. Danaher Corporation exemplifies the automation-convergence archetype through liquid-handling platform architecture. These three anchors represent distinct competitive vectors: biologics-captive supply, integrated manufacturing scale, and robotics-consumable bundling.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Abbott |
| Thermo Fisher Scientific Inc. |
| Siemens Healthineers |
| Danaher Corporation |
| Becton Dickinson and Company |
| Hologic, Inc. |
| Bio-Rad Laboratories, Inc. |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Hospital procurement consolidation across China's municipal health bureaus and Germany's EU Green Deal mandates forces reagent producers to reconfigure manufacturing footprints, compressing margins on liquid-format products while rewarding localized, shelf-stable alternatives with contract preference.
Pricing Analysis
Throughput-based pricing anchors reagent contracts, with hospital networks negotiating per-test economics for high-volume infectious-disease panels. Pricing stratifies across premium, standard, and economy tiers based on regulatory certification tier—EMA IVDR Class D versus Class B—and captive antibody supply control. Cost compression in standard-tier lyophilized formats is intensifying because freeze-dried reagents eliminate cold-chain logistics. Academic research institutions show highest price sensitivity; integrated diagnostic conglomerates with in-house monoclonal antibody production face lowest procurement pressure.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive reagents—expired lots, cold-chain failures, and calibration drift returns—concentrate cost recovery in centralized reference laboratories rather than point-of-care settings. Captive antibody production anchors in Switzerland, the United States, and Germany, while formulated kit assembly draws from China, India, and regional European hubs. Single-source vulnerability concentrates in monoclonal antibody supply, where F. Hoffmann-La Roche Ltd and integrated competitors control critical inputs. Distribution runs through group purchasing organizations in tier-one Chinese cities and consolidated vendor panels in Japanese Kanto region hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diagnostic reagents sector is becoming a vertical-integration race, with control over captive antibody production infrastructure and automated liquid-handling platforms serving as the decisive upstream and downstream levers for margin defense.
For Market Incumbents: Extend captive biologics supply through backward integration into hybridoma cell-line development, insulating against raw material concentration risk. Expand lyophilized format manufacturing capacity in India and Southeast Asia to capture CDSCO streamlined pathway advantages. Consolidate position against modular reagent developers dependent on external antibody sourcing by bundling robotics-consumable workflows through automated liquid-handling platform acquisitions.
For New Entrants and Emerging Players: Regional contract manufacturers serving European hospital networks offer the most penetrable channel, particularly for carbon-footprint-certified production under EU Green Deal procurement mandates. Target India's diagnostic chains in Mumbai and Hyderabad with shelf-stable PCR reagent formats eliminating cold-chain dependency. Pursue joint venture structures with domestic Chinese producers to access NMPA tiered registration pathways and municipal health bureau procurement networks.
For Investors and Strategic Acquirers: The window for entry favors specialized molecular diagnostics firms with lyophilized bead-based technology and automated platform architecture. Long-term viability over the next decade hinges on regulatory-validation talent pipelines and middleware integration capabilities for legacy laboratory information systems. Watch EMA IVDR analytical-validation backlog clearance rates as the inflection indicator for approval timeline compression and competitive entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Antibody Production Expansion | Backward integration into hybridoma infrastructure secures margin stability against raw material concentration. |
| Lyophilized Format Technology Licensing | Shelf-stable reagent formats capture decentralized testing mandates and EU Green Deal procurement preference. |
| Automated Liquid-Handling Platform Acquisition | Robotics-consumable bundling reduces laboratory technician labor and deepens hospital contract stickiness. |
| Joint Venture for NMPA Registration Access | Localized manufacturing commitments accelerate domestic reagent approvals through China's tiered pathways. |
| Carbon-Footprint Certification Program | Renewable-energy manufacturing credentials unlock Nordic and German hospital network tender preference. |
Methodological Framework
Independent corroboration across primary interviews with regulatory affairs specialists, hospital procurement managers, clinical laboratory directors, and diagnostic reagent R&D heads, combined with secondary validation of EMA IVDR technical documentation, NMPA registration filings, FDA quality-system guidance, and hospital GPO contract databases, underwrites the qualitative findings. Bottom-up reagent volume modeling by product format, application setting, technology platform, and end-user category triangulates against top-down market sizing from trade flow analysis and competitor revenue disclosure.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, application, end user, technology platform, and regional regulatory cluster. CAGRs derive from regression analysis against infectious-disease panel proliferation rates and decentralized testing mandate adoption curves. Forecast inputs incorporate lyophilized format substitution elasticity and EMA analytical-validation timeline compression scenarios.
Several conditions sit outside the modeled scope, including sudden regulatory framework revisions, monoclonal antibody supply disruptions, and pandemic-driven demand spikes. Forecasts reflect documented assumptions about procurement consolidation trajectories and technology substitution rates. Material deviation in EMA IVDR implementation timelines or NMPA domestic preference enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Europe Blood Screening Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
HDL Cholesterol Kits Market
Diagnostics
Influenza Diagnostics Market
Diagnostics
North America Ovarian Cancer Diagnostics Market
Diagnostics
Semen Analysis Market
Diagnostics
Global Alzheimers Disease Diagnostic Market
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
UAE in Vitro Diagnostics Market
Diagnostics
Argentina in Vitro Diagnostics Market
Diagnostics
Global Lateral Flow Assay Market
Diagnostics
Global Pelvic Floor Diagnostic Testing Market
Diagnostics
Global HIV/AIDS Diagnostics Market
Diagnostics
Blood Glucose Testing Devices Market
Diagnostics
Livestock Diagnostics Market
Diagnostics
United States Melanoma Diagnostics & Therapeutics Market