
 Germany in-Vitro Diagnostics Market | 2026-2036
Germany in-Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Germany in-Vitro Diagnostics Market Foresight
A shortage of trained laboratory technicians is collapsing throughput capacity at mid-sized German hospitals, forcing automation investments and consolidated outsourcing contracts. Siemens Healthineers anchors the high-end imaging-integrated diagnostics segment with captive manufacturing in Erlangen. Roche Diagnostics dominates decentralized testing through its cobas platform installed base across German clinics. Abbott differentiates via point-of-care connectivity solutions that feed directly into hospital information systems.
In-vitro diagnostics encompasses analytical testing performed on biological specimens outside the living organism, typically requiring sample volumes between 10 microliters and 10 milliliters processed through automated liquid-handling systems with throughput rates exceeding 1,000 tests per hour. Reagents constitute the largest recurring revenue pool, while molecular diagnostics represents the fastest-expanding technology segment as PCR and NGS-based oncology panels displace traditional histopathology in German cancer centers. Diagnostic laboratories command the dominant end-user channel, though blood banks are emerging as a specialized growth vertical for transfusion-transmitted infection screening.
CE marking under the EU In Vitro Diagnostic Regulation (IVDR) now requires notified body involvement for the majority of test classes, extending market access timelines and elevating documentation burdens for manufacturers serving Germany. Germany's Federal Institute for Drugs and Medical Devices (BfArM) coordinates national implementation while referencing EMA guidance on companion diagnostics. The EU AI Act introduces additional conformity requirements for algorithm-enabled diagnostic interpretation tools. Stakeholders must monitor IVDR transition deadlines and pre-emptively restructure quality management systems to avoid supply disruptions.
Market Dynamics
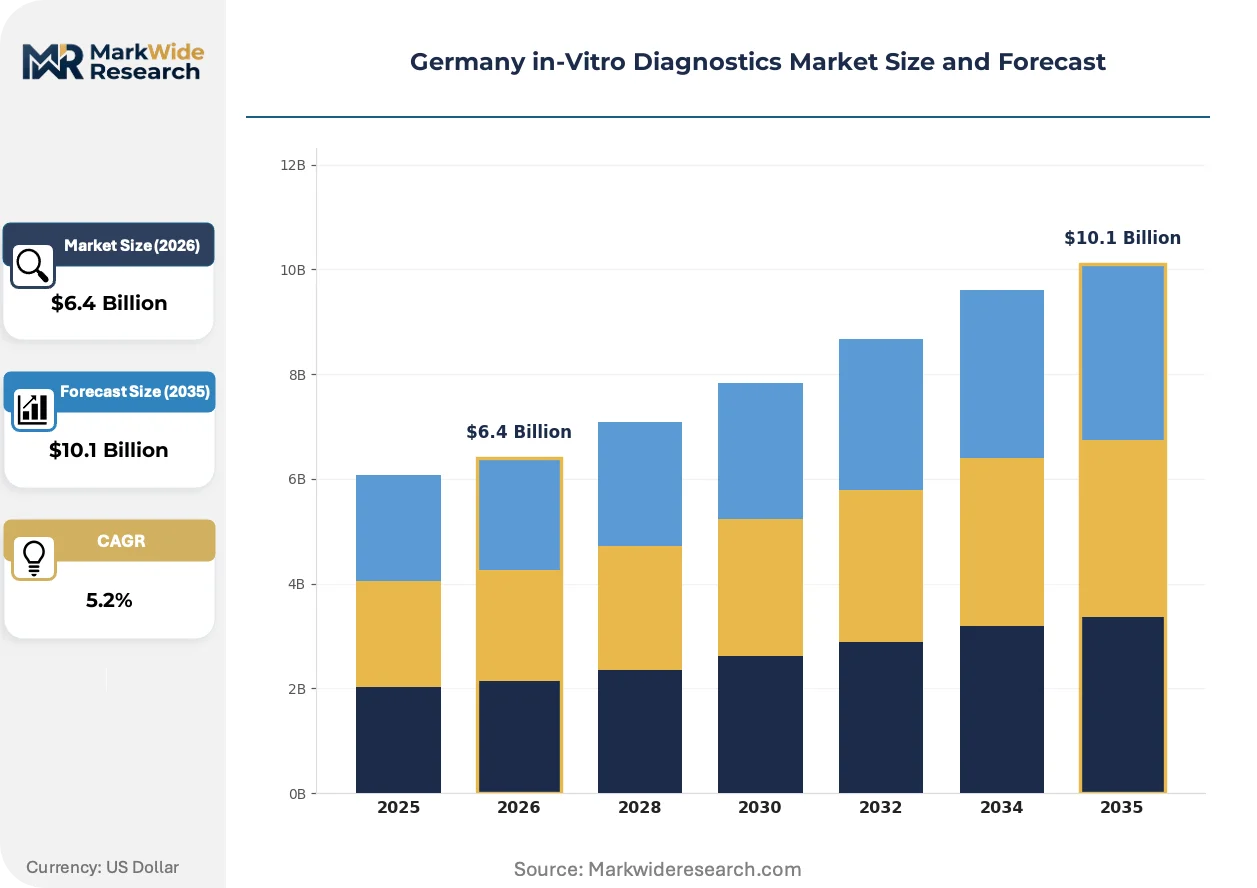
The EU In Vitro Diagnostic Regulation (IVDR) is compressing product registration timelines while German hospital laboratories accelerate automation investments to offset collapsing technician capacity.
Growth Catalysts
- IVDR Compliance Mandate:The EU In Vitro Diagnostic Regulation requires notified body involvement for Class B-D devices, forcing German manufacturers to upgrade quality management systems and expand regulatory affairs teams.
- Molecular Diagnostics Expansion:PCR and NGS-based oncology panels are displacing traditional histopathology workflows in German cancer centers, creating sustained reagent demand.
- Hospital Consolidation:Mid-sized German hospitals are merging laboratory operations into centralized hubs, driving high-throughput analyzer procurement.
Market Restraints
- Reagent Cost Volatility:Specialized enzymes and fluorescent probes face supply concentration among single-source suppliers, squeezing gross margins for German test manufacturers.
- IVDR Documentation Burden:The EU In Vitro Diagnostic Regulation's performance evaluation requirements extend technical file preparation timelines by eighteen to twenty-four months.
- Histopathology Substitution Limits:Tissue morphology assessment retains diagnostic authority in lymphoma classification, capping molecular test penetration in specific oncology subtypes.
Strategic Opportunities
- Decentralized Testing Networks:German clinics are deploying connected point-of-care devices that feed directly into hospital information systems, bypassing centralized laboratory bottlenecks.
- Blood Bank Screening Expansion:Transfusion-transmitted infection panels represent an underpenetrated vertical with mandated screening protocols driving reagent volume.
- EU AI Act Alignment:Algorithm-enabled diagnostic interpretation tools face new conformity requirements, creating first-mover advantage for German manufacturers with pre-certified software modules.
Industry Challenges
- Technician Training Deficit:German vocational programs produce insufficient medical laboratory assistants, forcing hospitals to automate or outsource routine workflows.
- Legacy Analyzer Integration:Hospital IT departments struggle to interface new molecular diagnostic platforms with existing laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany in-Vitro Diagnostics Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.1 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Kits, Software Technology: Immunoassay, Molecular Diagnostics, Clinical Chemistry, Hematology, Microbiology Application: Infectious Diseases, Oncology, Cardiovascular Diseases, Diabetes, Neurological Disorders End User: Diagnostic Laboratories, Research Institutes, Blood Banks, Academic Centers |
| Companies Covered | Siemens Healthineers, Roche Diagnostics, Abbott Diagnostics, Danaher Corporation, Thermo Fisher Scientific, Sysmex Corporation, Analytik Jena, Sartorius, Bio-Rad Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany in-Vitro Diagnostics Market Shifts & Advancements
Microfluidic architectures and AI-augmented interpretation are compressing test turnaround times while regulatory frameworks force systematic quality system overhauls across German manufacturing.
Digital PCR platforms are miniaturizing absolute quantification capabilities for circulating tumor DNA monitoring. German oncology centers are adopting these systems for minimal residual disease tracking. The technology is miniaturizing laboratory footprints while preserving analytical sensitivity previously requiring centralized reference labs.
The EU AI Act introduces risk-classification requirements for algorithm-enabled diagnostic software. German notified bodies must develop specialized competence for evaluating machine-learning-based interpretation tools. Companion diagnostic manufacturers serving German cancer centers face dual conformity assessment under both IVDR and AI Act frameworks.
Consolidated procurement consortia now dominate analyzer acquisition decisions for German hospital networks. Single-source tenders covering ten-year reagent supply commitments are displacing equipment-only purchases. This concentration is most visible in Bavaria and North Rhine-Westphalia where regional purchasing alliances command volume discounts exceeding fifteen percent.
Germany in-Vitro Diagnostics Market Segmentation
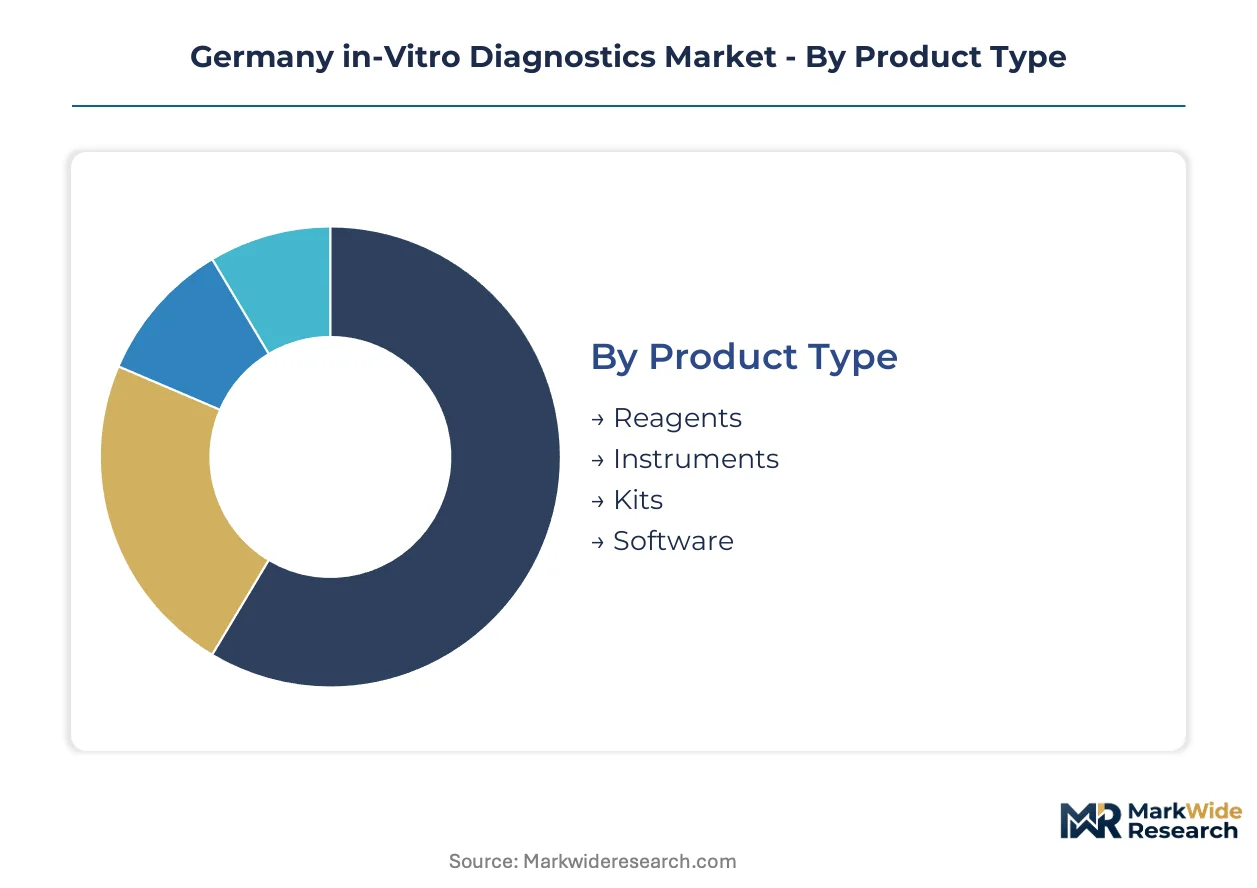
IVD segmentation in Germany reflects divergent procurement patterns between hospital networks and independent laboratories. Product mix varies sharply across federal states based on regional purchasing alliance structures and IVDR compliance timelines.
Product Type:
Domestic manufacturing concentrates in reagents and instruments, while software modules increasingly source from specialized developers in Berlin and Munich.
- Reagents:Enzyme formulations and fluorescent probes constitute the recurring revenue base for German manufacturers. Bavarian hospital networks consume the highest per-capita volumes through consolidated ten-year supply contracts with single-source commitments.
- Instruments:Automated liquid-handling platforms with throughput exceeding 1,000 tests per hour anchor laboratory investments. North Rhine-Westphalia's regional purchasing alliances command volume discounts exceeding fifteen percent on analyzer acquisitions.
- Kits:Pre-configured assay panels streamline IVDR compliance documentation for mid-sized German manufacturers.
- Software:Laboratory information management modules from German developers interface directly with hospital IT systems in Baden-Württemberg.
Reagents command the established base. The steepest expansion runs through software.
Technology:
Technology adoption splits between mature platforms serving routine screening and emerging molecular methods displacing traditional workflows in specialized centers.
- Molecular Diagnostics:PCR and NGS-based platforms enable circulating tumor DNA monitoring with absolute quantification sensitivity. German oncology centers in Heidelberg and Berlin deploy these systems for minimal residual disease tracking, displacing histopathology in solid tumor profiling.
- Immunoassay:Chemiluminescence analyzers process cardiac troponin and thyroid panels at throughput rates matching emergency department demand curves. Rhineland-Palatinate hospitals prioritize these platforms for STAT testing workflows.
- Clinical Chemistry:Integrated metabolic panels remain the workhorse for German hospital laboratory automation.
- Hematology:Cell counter installations concentrate in Saxony's consolidated diagnostic hubs.
- Microbiology:Automated culture systems face extended IVDR recertification timelines for mass spectrometry identification modules.
Molecular diagnostics is gaining share fastest. Immunoassay retains the volume base.
Application:
Application demand concentrates in acute care settings and cancer centers, with infectious disease screening mandated across blood bank networks.
- Oncology:Companion diagnostic requirements under BfArM guidance drive molecular panel adoption. German cancer centers in Munich and Hamburg deploy NGS-based profiling to guide targeted therapy selection, creating sustained reagent demand for BRCA and EGFR mutation detection.
- Infectious Diseases:Multiplex respiratory panels and transfusion-transmitted infection screening anchor procurement volumes. Blood banks in Hesse and Lower Saxony operate under mandated screening protocols driving reagent volume commitments.
- Cardiovascular Diseases:High-sensitivity troponin assays dominate emergency department testing in urban German hospitals.
- Diabetes:HbA1c testing consolidates into automated chemistry platforms in primary care networks.
- Neurological Disorders:Cerebrospinal fluid biomarker panels face limited reimbursement coverage in German statutory health insurance.
Oncology commands the premium tier. Infectious diseases anchors the volume base.
End User:
End-user structure reflects Germany's dual hospital and outpatient laboratory system, with blood banks emerging as a specialized procurement channel.
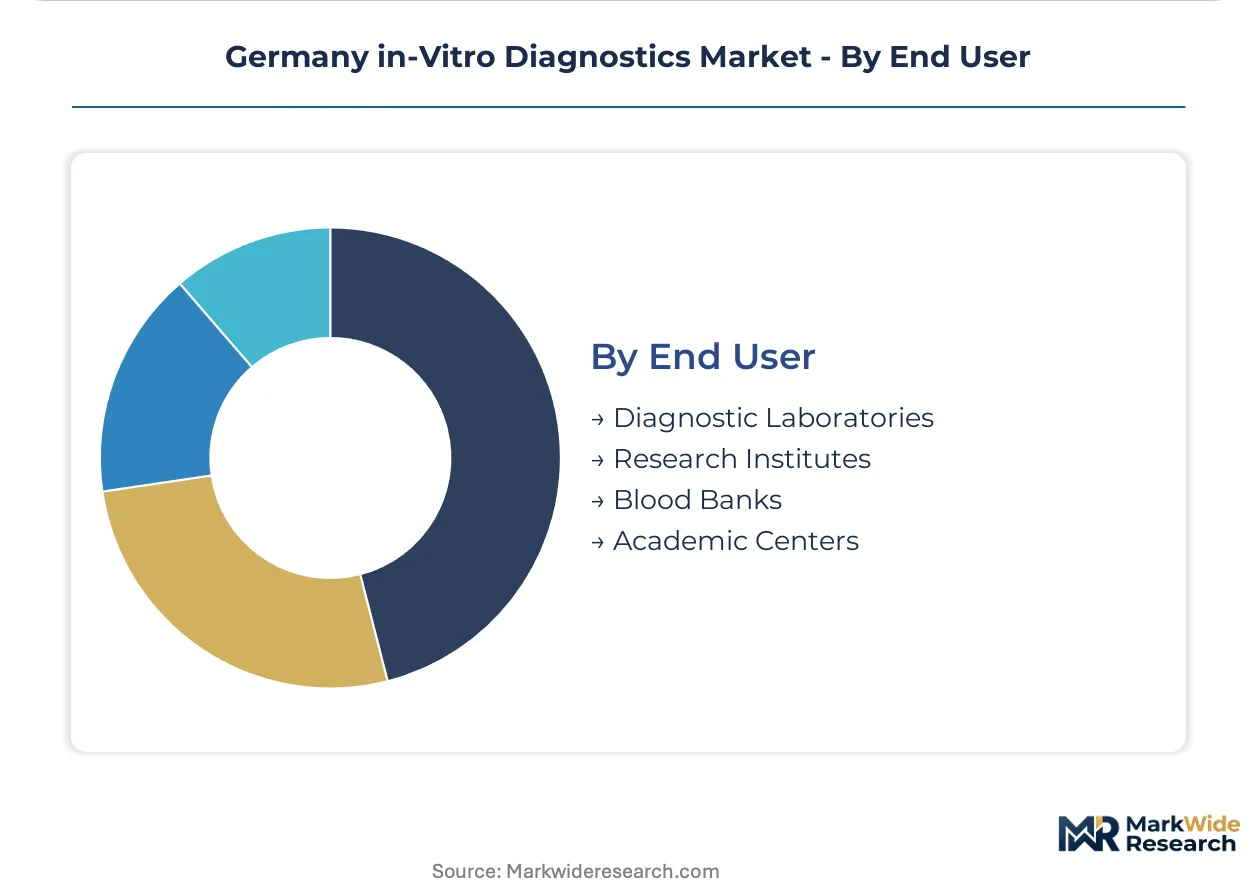
- Diagnostic Laboratories:Hospital-based and independent labs process the majority of German IVD test volumes. Mid-sized hospitals in Thuringia and Brandenburg are merging operations into centralized hubs, driving high-throughput analyzer procurement with ten-year reagent lock-in.
- Blood Banks:Transfusion services represent an underpenetrated vertical with mandated nucleic acid testing protocols. German Red Cross facilities in Bavaria and North Rhine-Westphalia operate dedicated screening laboratories with specialized procurement requirements.
- Research Institutes:Academic medical centers in Freiburg and Tübingen pilot novel assay formats ahead of clinical translation.
- Academic Centers:University hospital laboratories balance research flexibility with diagnostic accreditation under IVDR.
Diagnostic laboratories command the established base. The steepest expansion runs through blood banks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German IVD consumption patterns diverge sharply from neighboring markets through heavier reliance on hospital-integrated laboratory networks rather than independent commercial labs. Regional purchasing alliances in Bavaria and North Rhine-Westphalia consolidate procurement power, while eastern states lag in molecular diagnostics adoption.
Bavaria
Munich and Erlangen anchor Germany's highest-density IVD manufacturing corridor, with university hospitals driving companion diagnostic panel adoption. BfArM coordinates national IVDR implementation from Bonn, but Bavarian notified bodies handle disproportionate certification volumes. Siemens Healthineers maintains captive production in Erlangen, supplying analyzer hardware to regional purchasing alliances commanding fifteen percent volume discounts.
North Rhine-Westphalia
The Ruhr-Rhine metropolitan belt operates Germany's largest consolidated laboratory hub structure, merging mid-sized hospital operations into centralized high-throughput facilities. IVDR transition deadlines pressure regional manufacturers to restructure quality management systems. Cologne-Düsseldorf purchasing consortia negotiate decade-long reagent supply contracts locking in analyzer procurement decisions across twenty-plus hospital networks.
Baden-Württemberg
Heidelberg and Tübingen university medical centers pilot NGS-based minimal residual disease tracking ahead of clinical translation. The state's statutory health insurance reimbursement frameworks favor automated chemistry platforms over emerging molecular methods. Freiburg's diagnostic software developers supply laboratory information management modules interfacing directly with hospital IT systems.
Berlin-Brandenburg
The capital region exhibits Germany's steepest technician training deficit, collapsing throughput capacity at mid-sized hospitals and accelerating automation investments. Charité university hospital operates reference laboratories serving eastern federal states with delayed IVDR compliance timelines. Potsdam-area blood banks expand nucleic acid testing capacity for transfusion-transmitted infection screening under mandated protocols.
Hamburg
Germany's second-largest city concentrates private diagnostic laboratory chains serving outpatient clinics across northern federal states. The port city's logistics infrastructure supports reagent import distribution to Scandinavian markets. Hamburg's hospital networks lag Bavaria and North Rhine-Westphalia in molecular diagnostics adoption, maintaining higher histopathology dependency for oncology classification.
Germany in-Vitro Diagnostics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with Siemens Healthineers and Roche Diagnostics commanding installed base advantages through differentiated channel strategies. The upper tier anchors high-throughput hospital automation and decentralized clinic testing respectively. Mid-sized specialists compete on IVDR compliance speed and software connectivity. Competitive moves concentrate on ten-year reagent lock-in contracts and AI-augmented interpretation modules.
Among Germany-based manufacturers, Siemens Healthineers exemplifies the imaging-integrated diagnostics archetype through its Erlangen manufacturing concentration. Roche Diagnostics occupies the decentralized platform position with clinic-installed cobas infrastructure. Abbott represents the point-of-care connectivity specialist tier, feeding devices directly into hospital information systems.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Roche Diagnostics |
| Abbott Diagnostics |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Sysmex Corporation |
| Analytik Jena |
| Sartorius |
| Bio-Rad Laboratories |
| Others |
Supply & Pricing Matrix
EU IVDR certification tiers gate both supplier qualification and price differentiation simultaneously, forcing German manufacturers to stratify offerings across CE-marked premium assays, self-certified standard panels, and economy reagent lines while hospital procurement consortia exploit compliance documentation burdens to extract volume concessions.
Pricing Analysis
Long-term offtake contracts dominate analyzer-reagent bundling, with Bavarian and North Rhine-Westphalian purchasing alliances locking in decade-long commitments exceeding fifteen percent discounts. Price differentiation hinges on IVDR certification grade and analyzer throughput capacity, with high-complexity molecular diagnostics commanding premiums over automated chemistry workhorses. Cost compression in economy reagent tiers is intensifying because single-source enzyme suppliers squeeze contract manufacturers. Mid-sized hospital networks exhibit highest price sensitivity, while university cancer centers prioritize companion diagnostic accuracy over procurement cost.
Supply Chain Analysis
Inventory buffers for fluorescent probes and PCR enzymes extend lead times eighteen to twenty-four months as manufacturers pre-position inputs ahead of IVDR documentation deadlines. German reagent formulation draws from specialty chemical suppliers in Switzerland and the Netherlands, while precision optics and microfluidic components source from Japanese and US fabricators. Single-source vulnerability concentrates in thermostable polymerase enzymes, with distribution running through regional logistics hubs in Hamburg and Frankfurt serving hospital networks and independent laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IVDR transition timelines fragment competitive positioning, creating specialist niches for rapid-compliance reagent manufacturers and AI-augmented interpretation software developers as hospital laboratories face simultaneous automation mandates and technician shortages.
For Market Incumbents: Secure ten-year reagent lock-in contracts with merged hospital laboratory hubs before IVDR recertification waves disrupt supplier switching. Backward integration into captive enzyme production hedges against single-source raw material concentration, while preemptive AI Act software certification builds switching costs against emerging algorithm developers. For New Entrants and Emerging Players: Differentiate on IVDR compliance velocity by pre-configuring assay kits with technical file documentation packages that collapse hospital procurement evaluation timelines. Blood bank nucleic acid testing represents the most penetrable vertical, with mandated screening protocols and specialized procurement requirements bypassing consolidated hospital purchasing alliances. Target direct sales to German Red Cross regional facilities with transfusion-transmitted infection panel offerings. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across molecular diagnostics manufacturing as cleanroom capacity and notified body consulting costs escalate. Five-to-ten year viability favors mid-scale reagent specialists with established IVDR technical files over capital-heavy instrument platform challengers. Watch BfArM guidance updates on companion diagnostic reimbursement as the signal for oncology panel demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical File Pre-Configuration | Accelerates hospital procurement decisions by collapsing documentation evaluation timelines. |
| AI-Augmented Interpretation Certification | Builds first-mover advantage under EU AI Act risk-classification requirements for algorithm-enabled diagnostics. |
| Blood Bank Screening Partnership | Accesses mandated nucleic acid testing volumes through German Red Cross regional laboratory contracts. |
| Reagent Manufacturing Scale-Up | Captures recurring revenue from ten-year supply commitments in consolidated Bavarian hospital networks. |
| Software-Hardware Integration Development | Feeds point-of-care devices directly into hospital information systems, bypassing centralized laboratory bottlenecks. |
Research Methodology
A spread of perspectives from hospital laboratory directors, IVD regulatory affairs managers, biomedical procurement officers, and notified body auditors converged on the working assumptions, validated against BfArM guidance documents, EU MDR/IVDR implementation reports, hospital GPO contract databases, and manufacturer quality system disclosures. Bottom-up test volume modeling triangulated with top-down healthcare expenditure allocation analysis.
Segmentation dimensions modeled span product type, technology platform, clinical application, and end-user channel across the projection horizon. CAGRs derive from installed base expansion rates, reagent consumption per analyzer, and IVDR transition impact on pricing power. Forecast inputs incorporate technician training pipeline data and regional hospital consolidation announcements.
The analysis sits within stated boundaries; outcomes outside sustained IVDR implementation timelines or accelerated AI Act enforcement would require recalibration. Forecasts reflect documented assumptions regarding reimbursement stability and raw material supply continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Johne's Disease Diagnostics Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
Blood Glucose Testing Devices Market
Diagnostics
US Tissue Diagnostics Market
Diagnostics
Livestock Diagnostics Market
Diagnostics
Melioidosis Diagnostic Market
Diagnostics
Diabetic Assays Market
Diagnostics
Middle East and Africa Liver Cancer Diagnostics Market
Diagnostics
Artificial Intelligence in IVD Market
Diagnostics
Global STD Diagnostics Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market
Diagnostics
Global HIV Diagnosis Market
Diagnostics
Hypopituitarism Diagnostics Market
Diagnostics
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market
Diagnostics
North America Thyroid Cancer Diagnostics Market